
 Digital Body Thermometer Market | 2026-2036
Digital Body Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Body Thermometer Market Intelligence
The bundling of digital thermometers with smartphone applications for health tracking is rebalancing buyer choice toward connected ecosystems over standalone devices. This shift favors companies with strong software and hardware integration capabilities. Omron Healthcare leverages its brand in home health monitoring to offer integrated solutions. Philips extends its consumer electronics expertise into personal health devices, creating a seamless user experience. Meanwhile, Braun GmbH differentiates its products through design and perceived accuracy in the premium consumer segment.
A digital body thermometer is an electronic instrument used to measure human body temperature. These devices typically utilize a thermistor, which changes its electrical resistance with temperature, or an infrared sensor to detect thermal radiation and convert it into a readable value on an LCD screen. Their primary purpose is the rapid and non-invasive detection of fever for clinical diagnosis and personal health monitoring. While oral and axillary product types constitute a mature market segment, infrared-based temporal and ear thermometers are showing higher growth. Demand from the home care sector is expanding more rapidly than procurement for traditional hospitals.
Regulatory frameworks are critical in shaping product standards and market access. In the United States, the FDA's 510(k) clearance process is required for new devices. Across Europe, manufacturers must comply with CE marking requirements under the Medical Device Regulation (MDR). In China, the NMPA sets the standards for medical device approval and quality control. Future competitive advantage will depend on integrating reliable connectivity for telehealth applications without compromising clinical accuracy or affordability.
Market Dynamics
The convergence of medical device functionality with consumer electronics is the central force shaping the digital body thermometer market. This trend is driven by consumer demand for integrated health tracking and telehealth capabilities, compelling manufacturers to build software ecosystems around their hardware, a significant shift from producing standalone measurement devices.
Growth Catalysts
- Infrared Technology Adoption:The wider use of infrared sensors for non-contact temporal and ear measurements accelerates adoption in both home care and clinical settings due to speed and hygiene benefits.
- Expanding Home Care Segment:A rising emphasis on preventative health and self-monitoring, particularly for pediatric and geriatric care, is expanding the household penetration of digital thermometers.
- Healthcare Infrastructure Development:National health policies in countries like China, focused on modernizing and expanding healthcare services, create sustained demand from hospitals and public health programs.
Market Restraints
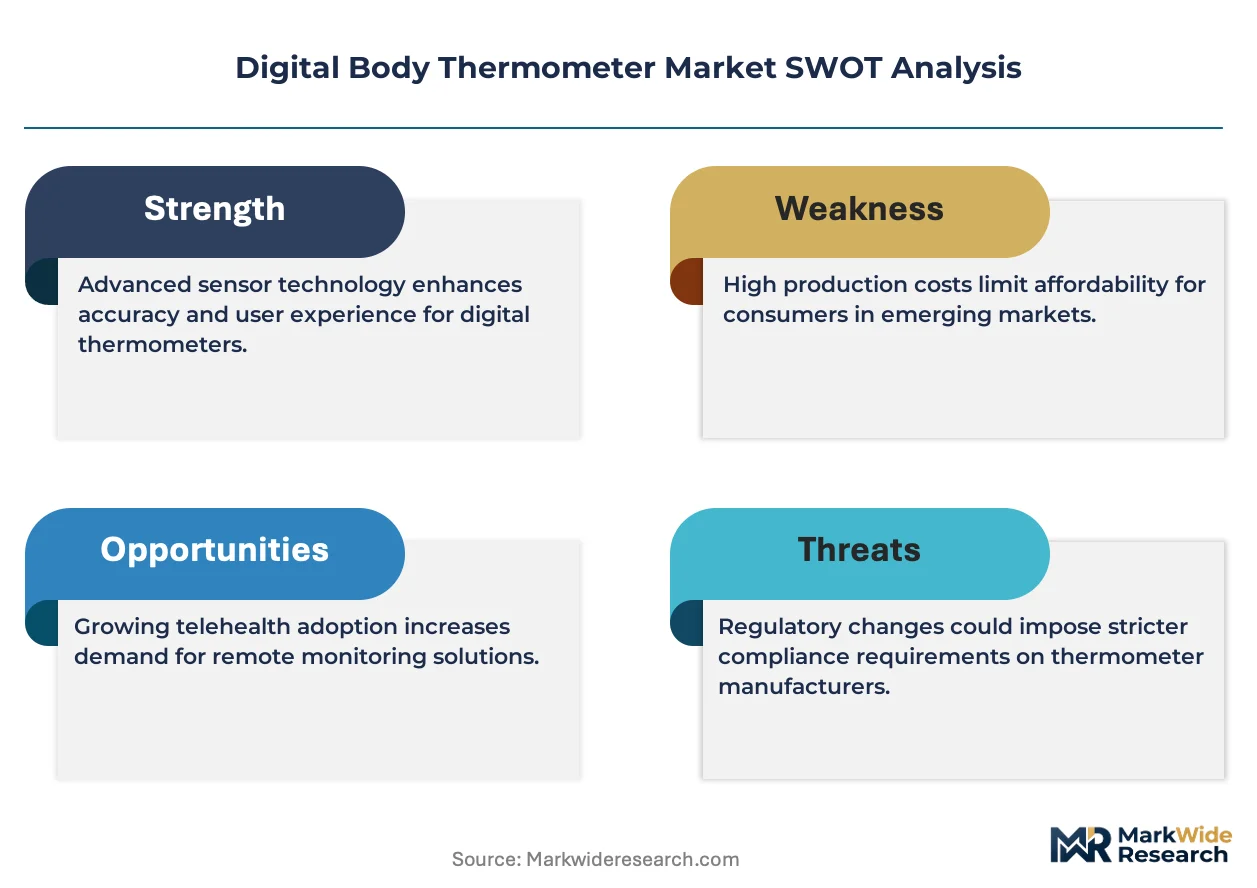
- Stringent Regulatory Hurdles:Complex and lengthy device approval pathways, such as the FDA's 510(k) process and the EU's MDR, increase development costs and extend time-to-market.
- Component Cost Pressure:The price of high-precision thermistors and clinical-grade infrared sensors constitutes a significant portion of the bill of materials, limiting affordability in developing economies.
- Threat from Low-Cost Alternatives:Basic, low-cost digital stick thermometers represent a persistent substitute, capping the price premium achievable for more advanced models in price-sensitive consumer segments.
Strategic Opportunities
- Telehealth Integration:Developing devices with built-in connectivity to automatically sync data with telehealth platforms and electronic health records opens new service-based revenue models.
- Wearable Form Factors:Innovation in continuous temperature monitoring through wearable patches or smart fabrics creates a new product category for post-operative, chronic illness, and infant care.
- Penetration in Emerging Markets:Growing healthcare expenditure and consumer purchasing power in regions like Southeast Asia and Latin America present untapped geographic expansion opportunities.
Industry Challenges
- Cybersecurity and Data Privacy:For connected thermometers, ensuring compliance with data protection regulations like GDPR and HIPAA represents a significant and continuous operational challenge.
- Maintaining Clinical Accuracy:Ensuring consistent accuracy and reliability outside of controlled clinical environments is a persistent technical challenge for devices used by laypersons at home.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Body Thermometer Market |
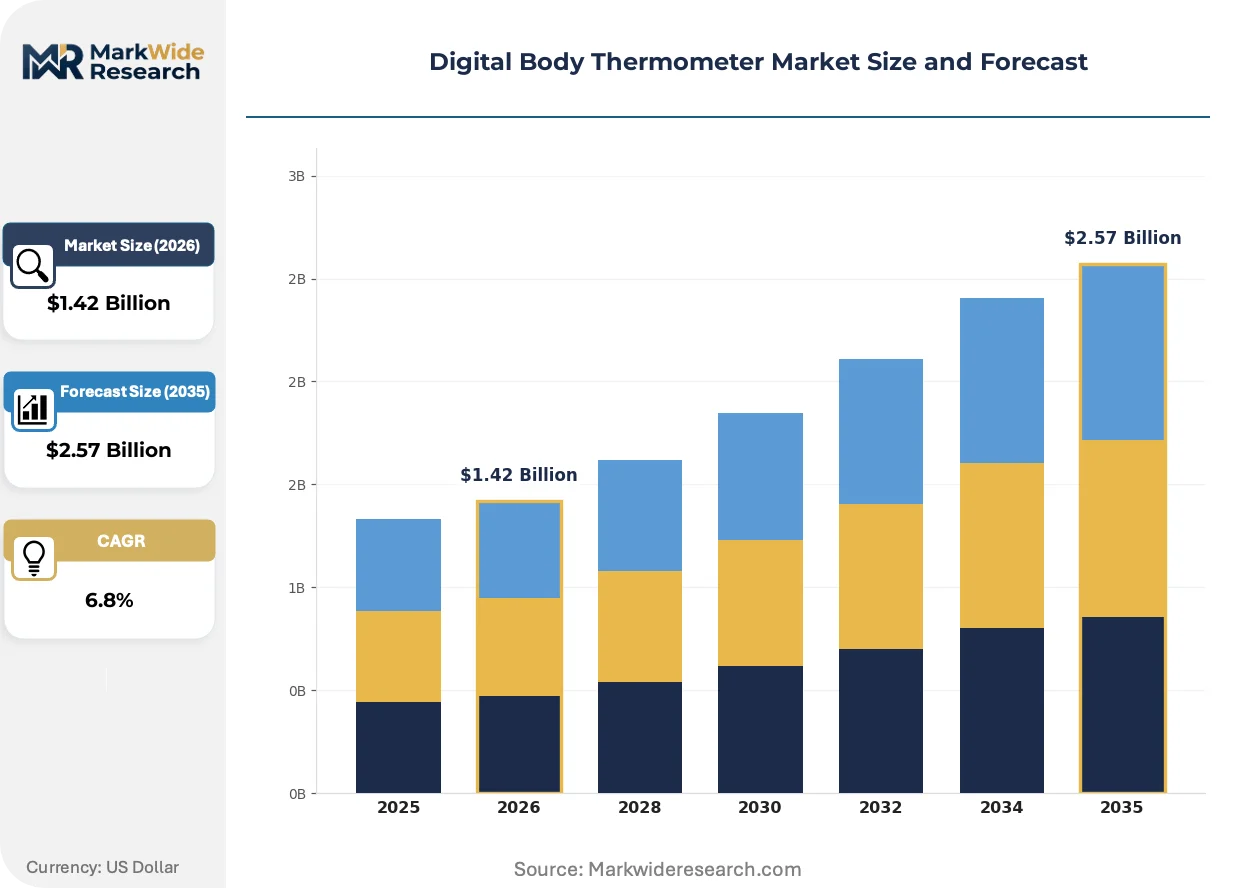
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral, Rectal, Axillary, Ear, Temporal, Forehead Technology: Infrared, Thermistor, Thermocouple, Liquid Crystal, Electronic, Ultrasonic End User: Hospitals, Diagnostic Centers, Home Care, Clinics, Nursing Homes, Pediatric Facilities Distribution Channel: Pharmacies, Online Retailers, Medical Distributors, Supermarkets, Direct Sales, Specialized Dealers |
| Companies Covered | Omron Healthcare Inc., Terumo Corporation, Exergen Corporation, Microlife Corporation, Braun GmbH, Philips, Geratherm Medical AG, A&D Medical, Fairhaven Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Body Thermometer Market Strategic Shifts & Innovations
The market's evolution is defined by the integration of hardware with sophisticated software ecosystems. This shift places a premium on user experience and data utility, moving the competitive focus from pure measurement accuracy to the value of connected health insights.
Infrared sensor technology detects thermal radiation, enabling rapid and non-contact temperature measurement. The home care end-user segment is rapidly adopting this for its convenience and hygienic advantages over traditional contact thermometers. This technology is expanding into new applications like continuous monitoring patches and integrated screening systems for public spaces.
Europe's Medical Device Regulation (MDR) imposes significantly stricter requirements for clinical evidence, post-market surveillance, and software validation. This directive increases compliance burdens and development timelines for manufacturers aiming to access the European market. The connected device category is most affected, as cybersecurity and data integrity documentation face heightened regulatory scrutiny.
A preference for bundled solutions is altering consumer purchasing behavior, with device choice often dictated by compatibility with a preferred health tracking application. This pattern disrupts the traditional sales model of one-off purchases in pharmacies, favoring electronics retailers and direct-to-consumer online channels. The shift is most pronounced in North America and Western Europe, where smartphone and health app usage is widespread.
Digital Body Thermometer Market Segmentation
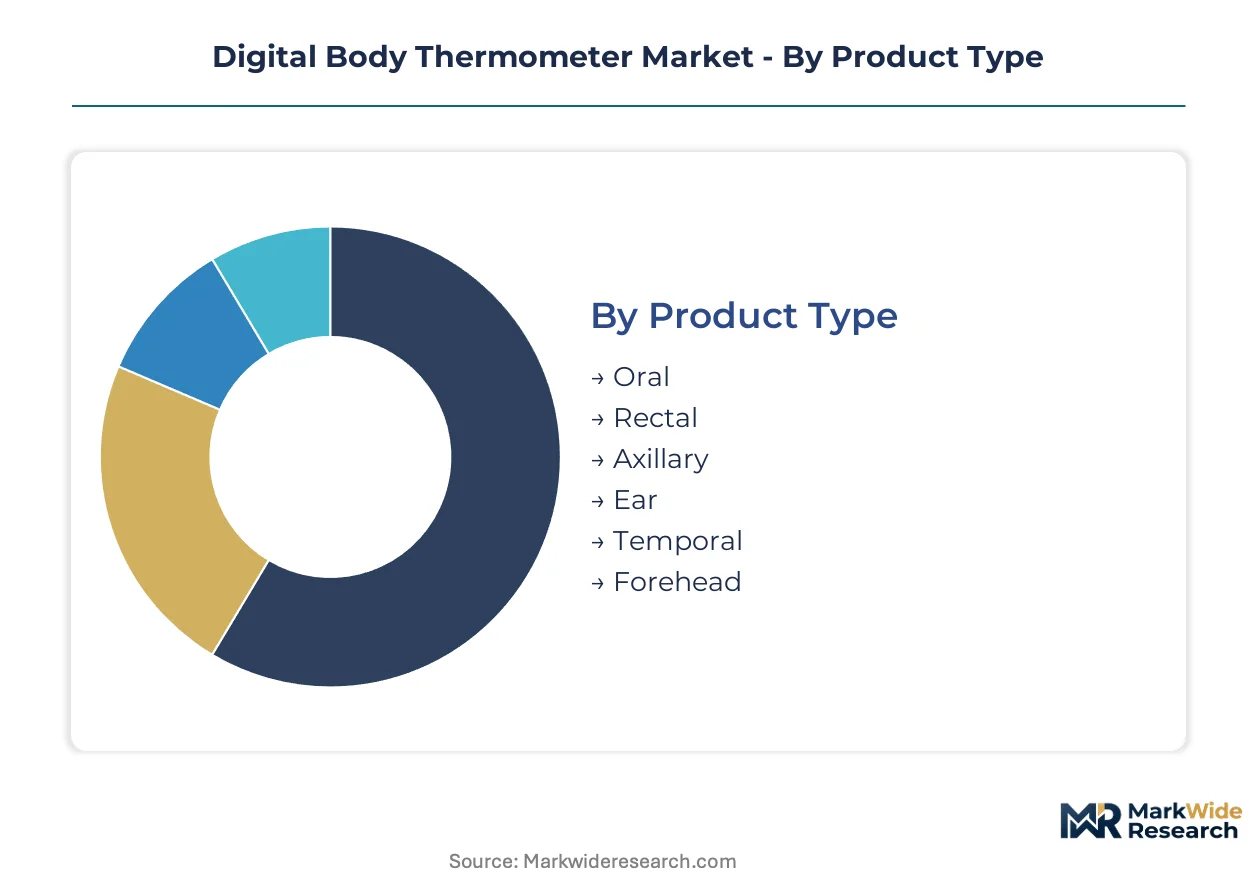
Understanding the varied segments within the digital body thermometer market reveals distinct demand patterns and technological preferences. This granular view highlights where innovation is concentrated and how different user needs shape product development. Analyzing these segments helps manufacturers tailor offerings and optimize market entry strategies.
Product Type:
Product types are differentiated by their measurement methodology and target application, influencing user convenience and accuracy expectations.
- Temporal:These infrared-based devices offer non-contact measurement by scanning the forehead, providing rapid and hygienic temperature readings. Demand is strong in home care settings and public health screening due to speed and ease of use.
- Ear:Utilizing infrared technology, ear thermometers accurately measure temperature from the tympanic membrane, making them suitable for pediatric use and clinical environments. Their precision in detecting core body temperature drives adoption in hospitals and home monitoring.
- Oral:Traditional stick thermometers measure temperature inside the mouth, offering a widely accepted and cost-effective method for general fever detection.
- Axillary:These devices measure temperature from the armpit, commonly used for infants and children where non-invasive methods are preferred.
- Rectal:Considered highly accurate for infants and young children, rectal thermometers are primarily used in clinical and specific home care situations.
- Forehead:Similar to temporal thermometers, these devices provide quick, non-contact readings, often favored for screening purposes in various settings.
Oral products maintain significant market scale; temporal and ear thermometers exhibit the steepest expansion trajectory.
Technology:
The underlying technology determines the accuracy, speed, and form factor of digital thermometers, directly impacting their suitability for diverse applications.
- Infrared:This technology detects thermal radiation for non-contact measurements, enabling rapid and hygienic temperature acquisition. Infrared sensors are crucial for temporal and ear thermometers, driving adoption in home and clinical environments.
- Thermistor:Thermistors change electrical resistance with temperature, providing highly accurate and stable readings in contact-based digital thermometers. Their reliability underpins many oral, rectal, and axillary devices.
- Electronic:This broad category encompasses devices that convert thermal input into digital output, often leveraging thermistors or infrared sensors for measurement. Electronic thermometers offer user-friendly displays and data processing capabilities.
- Thermocouple:Thermocouples generate a voltage proportional to temperature differences, used in some industrial and specialized medical applications requiring robust temperature sensing.
- Liquid Crystal:These thermometers utilize temperature-sensitive liquid crystals that change color to indicate temperature, offering a simple, disposable, and low-cost solution for basic screening.
- Ultrasonic:Ultrasonic technology is less common for body temperature measurement but can be explored for non-invasive internal temperature sensing in advanced research applications.
Infrared technology commands substantial innovation, while thermistor-based solutions offer foundational reliability.
End User:
End-user segments define the specific requirements for device features, accuracy, and connectivity, reflecting distinct purchasing priorities.
- Home Care:This segment comprises individual consumers and families using thermometers for personal health monitoring, particularly for pediatric and geriatric care. Demand from this sector is expanding more rapidly than traditional hospital procurement.
- Hospitals:Large healthcare facilities require durable, accurate, and often connected thermometers for clinical diagnosis and patient monitoring across various departments. National health policies in countries like China drive sustained demand from hospitals.
- Clinics:Smaller medical practices and outpatient facilities use digital thermometers for routine patient examinations and initial fever detection.
- Diagnostic Centers:These centers utilize thermometers as part of broader diagnostic procedures, requiring reliable and efficient measurement tools.
- Nursing Homes:Long-term care facilities need easy-to-use and hygienic thermometers for monitoring the health of elderly residents.
- Pediatric Facilities:Specialized children's hospitals and clinics require thermometers designed for infant and child comfort and accuracy, often favoring non-invasive methods.
Home Care represents the largest volume segment; Hospitals maintain high-value procurement.
Distribution Channel:
The distribution channels dictate how digital thermometers reach end-users, influencing market access and brand visibility.
- Online Retailers:E-commerce platforms provide extensive product choices, competitive pricing, and convenience for consumers, particularly for connected devices bundled with health applications. This channel shows significant growth in North America and Western Europe.
- Pharmacies:Traditional brick-and-mortar pharmacies serve as a primary point of sale for medical devices, offering accessibility and professional advice to consumers. They remain a trusted source for over-the-counter health products.
- Medical Distributors:These specialized channels supply hospitals, clinics, and other healthcare institutions with bulk orders and specialized medical equipment.
- Supermarkets:Mass-market retailers offer basic digital thermometers alongside other consumer goods, appealing to price-sensitive buyers seeking convenience.
- Direct Sales:Some manufacturers engage in direct-to-consumer sales, particularly for premium or technologically advanced products, often leveraging online platforms.
- Specialized Dealers:These outlets cater to niche markets or offer a curated selection of high-end or specific-use medical devices.
Online Retailers offer unparalleled reach; Pharmacies provide localized access and trust.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The digital body thermometer market initially scaled in developed economies, driven by early medical device advancements and widespread healthcare access. Innovation in temperature measurement technology originated in countries with strong scientific research capabilities. These regions established foundational regulatory frameworks for medical diagnostics.
United States
Demand for connected health devices and home monitoring drives market expansion. The FDA's 510(k) clearance process shapes product development and market entry for manufacturers. Silicon Valley companies and Boston's medical device hub concentrate on integrating AI and telehealth into new diagnostic tools.
Germany
European demand for high-precision medical instruments supports the digital thermometer sector. CE marking requirements under the Medical Device Regulation (MDR) influence product design and approval timelines. Stuttgart's medical technology cluster focuses on engineering robust and reliable diagnostic solutions.
China
Expanding healthcare infrastructure and a vast population base create substantial demand for digital thermometers. The NMPA sets stringent standards for medical device approval and quality control within the country. Shenzhen's electronics manufacturing prowess facilitates the mass production of advanced temperature measurement devices.
Japan
An aging population and a strong emphasis on preventative health drive demand for personal health monitoring devices. Japan's PMDA ensures medical device quality and safety through rigorous approval processes. Osaka's medical equipment industry specializes in developing compact and highly accurate thermometry solutions.
India
Increased healthcare expenditure and a growing middle class are boosting consumer purchasing power for health devices. The PLI scheme encourages domestic manufacturing of medical electronics, including digital thermometers. Bengaluru's tech ecosystem supports the development of integrated health tracking applications for these devices.
Digital Body Thermometer Market Key Industry Players
Premium-margin players sit above commodity-margin players across product innovation and brand perception. The market exhibits a tiered structure, with established medical device manufacturers coexisting with consumer electronics brands and agile tech startups. Two strategic archetypes include specialized medical device companies focusing on clinical accuracy and diversified consumer health technology firms emphasizing user experience. Companies frequently engage in strategic partnerships for software integration and pursue geographic expansion into emerging markets.
Among established medical device manufacturers, Omron Healthcare Inc. exemplifies a strong brand presence in home health monitoring solutions, often integrating its devices with broader health ecosystems. Braun GmbH occupies a position in the premium consumer segment, differentiating its products through design and perceived accuracy, catering to discerning buyers. Philips, a diversified consumer electronics company, extends its expertise into personal health devices, creating a seamless user experience across its portfolio. These companies anchor the market through their focus on reliability, user trust, and continuous product refinement.
| Leading Market Players |
|---|
| Omron Healthcare Inc. |
| Terumo Corporation |
| Exergen Corporation |
| Microlife Corporation |
| Braun GmbH |
| Philips |
| Geratherm Medical AG |
| A&D Medical |
| Fairhaven Health |
| Others |
Cost & Logistics Intelligence
Consumer demand for integrated health tracking is compelling manufacturers to invest heavily in software ecosystems, which in turn influences component sourcing and pricing for advanced digital thermometers. This shift impacts the entire value chain, from raw material procurement to end-user cost.
Pricing Analysis
Premium-mid-economy pricing differentiation characterizes the digital body thermometer market. Brand perception and clinical accuracy drive premium pricing, while volume scale influences standard and economy tiers. Pricing softness runs through the basic stick thermometer segment due to intense competition from low-cost alternatives. Home care consumers in developing economies exhibit high price sensitivity, whereas hospitals prioritize accuracy and durability over absolute cost.
Supply Chain Analysis
Infrared sensor supply largely rests on specialized manufacturers in Japan, Germany, and China. The supply chain relies on these regions for critical inputs like microcontrollers, LCD screens, and advanced sensor technologies. Component cost volatility, especially for high-precision sensors, represents a structural risk for device manufacturers. Downstream distribution runs through a mix of online retailers for direct-to-consumer sales and medical distributors for institutional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital body thermometer market offers geographic-arbitrage opportunities, leveraging lower manufacturing costs in Asia against premium market access and regulatory compliance in Europe.
For Market Incumbents: Deepen software and hardware integration capabilities to counter the threat from agile tech startups specializing in connected health. Consolidate market share through strategic acquisitions of software platforms and invest heavily in R&D for advanced sensor technology. The rise of integrated telehealth solutions threatens standalone device relevance. Investing in robust clinical validation and achieving stringent regulatory certifications like MDR will reinforce market leadership.
For New Entrants and Emerging Players: Launch via direct-to-consumer online channels, targeting the rapidly expanding home care segment with user-friendly, connected devices. Focus on white-space opportunities in continuous temperature monitoring through wearable form factors or specialized pediatric solutions. Emerging markets in Southeast Asia and Latin America represent a penetrable segment for affordable, smart thermometers. A go-to-market angle emphasizing seamless data integration with popular health apps offers differentiation.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized medical device companies demonstrating strong regulatory compliance and innovative software integration. Long-term viability over a five-to-ten-year window favors firms that can consistently deliver clinical accuracy within connected ecosystems. Acquisition targets should be mid-sized firms with proprietary sensor technology or established telehealth platform partnerships. A signal to watch is successful 510(k) or CE marking approval for a novel, connected temperature monitoring device.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI-driven diagnostic algorithms | Enhances clinical accuracy and predictive capabilities for digital body thermometers used in personal health monitoring. |
| Pursue CE marking under MDR for connected devices | Secures market access and establishes regulatory credibility for digital thermometers across the European market. |
| Form partnerships with telehealth platform providers | Integrates digital thermometer data directly into patient health records, enhancing remote care services. |
| Develop wearable temperature monitoring solutions | Creates new product categories for continuous temperature tracking in infant care and post-operative recovery. |
| Expand manufacturing capacity in Southeast Asia | Optimizes production costs and diversifies the supply chain for digital body thermometers in emerging markets. |
Research Approach
Bottom-up end-user segment modeling reconciled against top-down component supply tracking forms the analytical core for this digital body thermometer market study. This approach combines insights from primary interviews with industry stakeholders and rigorous secondary validation. Interviews included R&D leads, regulatory affairs specialists, hospital procurement managers, and online retail category managers. Secondary data sources involved FDA 510(k) clearance databases, NMPA approval lists, EU MDR guidance documents, and medical device trade publications. Data triangulation ensures the robustness of market size estimations and trend analyses.
Historical trendline analysis and regression modeling informed the quantitative forecast for the digital body thermometer market. This analytical framework projects market trajectories across the analysis window. Key segmentation dimensions modeled include product type, technology, end-user, distribution channel, and regional adoption patterns. Compound annual growth rates were derived from projected market values, reflecting expected shifts in demand and technology. Healthcare expenditure trends and technology adoption rates served as critical forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of rapid regulatory shifts or significant component supply disruptions. Forecasts reflect assumptions regarding technological advancements and market dynamics. Evolving data privacy regulations and competitive pricing pressures represent specific risk factors. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Bathroom and Toilet Assist Devices Market
Medical Devices
Cervical Retractors Market
Medical Devices
Wireless Neurofeedback Device Market
Medical Devices
North America Advanced Drug Delivery Systems Market
Medical Devices
Global Hyperbaric Oxygen Therapy (HBOT) Devices Market
Medical Devices
Electrocautery Devices Market
Medical Devices
United States Contraceptive Devices Market
Medical Devices
Intra-Abdominal Pressure Measurement Devices (IPMD) Market
Medical Devices
Global Mobile C-Arm Market
Medical Devices
Global Implantable Drug Delivery Market
Medical Devices
Global Trauma Devices Market
Medical Devices
Global Gynecology Robotic Surgery Market
Medical Devices
Middle Ear Implants Market
Medical Devices
Global Surgical Drills Market
Medical Devices
Electrocardiograph (ECG) Market
Medical Devices
Bone Growth Stimulators Market