
 Radiofrequency-Based Aesthetic Devices Market | 2026-2036
Radiofrequency-Based Aesthetic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Radiofrequency-Based Aesthetic Devices Market Insights
Modular platform bundling is hardening as the dominant procurement pattern among mid-sized aesthetic clinics. InMode leverages interchangeable applicator ecosystems to sustain premium positioning across body contouring and skin tightening workflows. Alma Lasers competes through flexible leasing structures that reduce capital barriers for dermatology centers entering RF microneedling. Venus Concept anchors its presence in the home care segment with simplified user interfaces that lower operator training requirements.
Radiofrequency-based aesthetic devices generate controlled dermal heating through electromagnetic energy delivery at frequencies typically spanning 0.3 to 10 MHz, with tissue impedance and penetration depth determined by electrode configuration and cooling mechanism integration. These systems serve commercial purposes across wrinkle reduction, body contouring, and cellulite treatment by inducing collagen remodeling and adipose tissue disruption without ablative surface damage. Multipolar devices occupy the largest installed base due to balanced efficacy profiles and reduced procedural downtime, while RF microneedling technology captures the fastest expansion as practitioners seek combined dermal penetration with thermal energy delivery. Bipolar devices concentrate margin pools in established dermatology chains that prioritize predictable outcomes over treatment speed.
FDA 510(k) clearance requirements and the EU Medical Device Regulation shape product development timelines and clinical evidence burdens for manufacturers seeking market access. The Federal Trade Commission monitors advertising claims for at-home RF devices, creating compliance costs that favor established players with legal infrastructure. ISO 13485 quality management certification functions as a baseline qualification for contract manufacturing relationships across the supply chain. Stakeholders must monitor evolving state-level scope-of-practice regulations that determine whether nurse practitioners and physician assistants can independently operate RF devices.
Market Dynamics
Modular platform architectures are compressing equipment refresh cycles as aesthetic clinics prioritize interchangeable applicator ecosystems over single-purpose devices. This procurement pattern is redistributing margin pools toward consumables and software subscriptions while eroding capital equipment premiums.
Growth Catalysts
- EU Medical Device Regulation (MDR) harmonization:The 2017/745 framework is consolidating quality benchmarks across European aesthetic device distribution, accelerating replacement demand for legacy systems lacking updated technical documentation.
- Fractional RF microneedling penetration:Combined dermal penetration with thermal energy delivery is displacing standalone microneedling in premium dermatology workflows.
- South Korean medical tourism infrastructure:Concentrated procurement volumes from international patient flows are sustaining domestic manufacturing scale for multipolar and fractional RF platforms.
Market Restraints
- Clinical efficacy documentation burdens:FDA 510(k) clearance pathways have tightened evidentiary requirements for RF microneedling systems, extending pre-market timelines and legal infrastructure costs.
- Copper coil and electrode supply concentration:Precision RF applicator manufacturing depends on specialized electromagnetic component suppliers concentrated in East Asian electronics clusters.
- Intense pulsed light substitution:IPL platforms compete for non-ablative skin tightening budgets with lower per-procedure operating costs and reduced operator training requirements.
Strategic Opportunities
- Home-use RF device channels:Simplified user interfaces and consumer-directed marketing are opening aesthetic maintenance revenues outside clinical settings.
- Combination therapy protocols:Integration of RF energy with cryolipolysis or laser platforms is creating premium service tiers in body contouring workflows.
- US state-level scope-of-practice expansion:Regulatory shifts permitting nurse practitioners and physician assistants to operate RF devices independently are expanding addressable provider bases.
Industry Challenges
- ISO 13485 certification timelines:Quality management system audits for contract manufacturing relationships are creating supply chain onboarding friction for emerging device developers.
- RF engineering talent scarcity:Electromagnetic tissue interaction modeling and thermal dose optimization require specialized biomedical engineering expertise that concentrates in established device manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiofrequency-Based Aesthetic Devices Market |
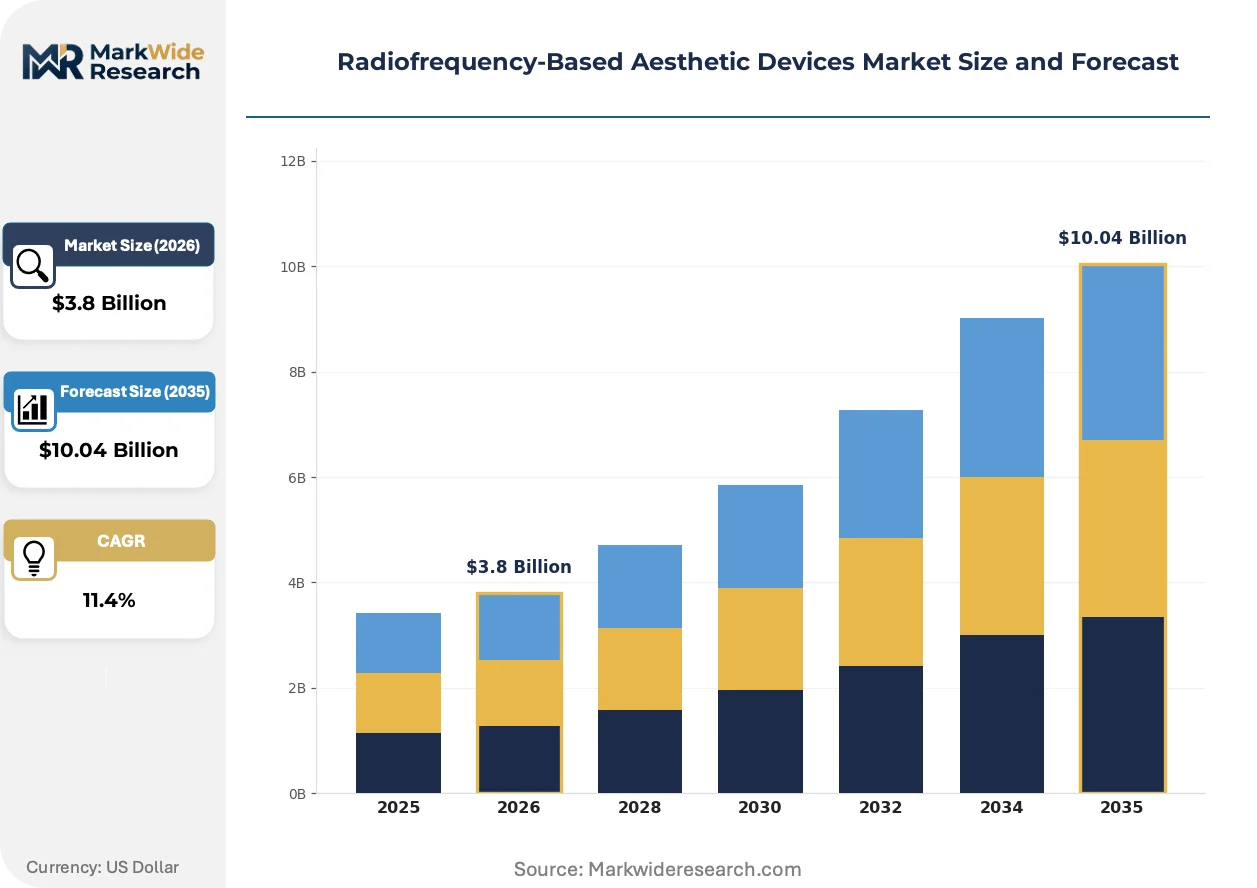
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monopolar Devices, Bipolar Devices, Multipolar Devices, Ultrasound-Combined Devices Technology: RF Microneedling, Fractional RF, Non-Invasive RF, Skin Tightening Devices End User: Aesthetic Clinics, Dermatology Centers, Hospitals, Home Care Users Application: Wrinkle Reduction, Body Contouring, Skin Resurfacing, Cellulite Treatment |
| Companies Covered | InMode, Cutera, Alma Lasers, Lutronic, Cynosure, Lumenis, Syneron Candela, Venus Concept, EndyMed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiofrequency-Based Aesthetic Devices Market Trends and Innovations
Real-time impedance feedback systems are reshaping treatment precision by enabling dynamic energy delivery adjustment based on tissue resistance variations. This capability is compressing operator skill requirements while standardizing outcomes across experience levels.
AI-guided treatment planning is electrifying procedural standardization in high-volume aesthetic chains. Machine learning algorithms trained on dermal imaging datasets are automating energy parameter selection for RF microneedling protocols. Large dermatology groups in the United States are deploying these systems to reduce inter-practitioner outcome variance and accelerate staff onboarding.
FDA and FTC coordinated enforcement is tightening advertising substantiation for at-home RF devices. The Federal Trade Commission's monitoring of efficacy claims is elevating compliance infrastructure costs that favor established players with dedicated legal teams. Consumer-directed RF device marketing in North America is pivoting toward clinical study citations and before-and-after documentation protocols.
Subscription-based equipment access is disrupting traditional capital purchase models in mid-sized aesthetic practices. Leasing structures bundled with consumable supply agreements are replacing outright ownership for fractional RF platforms. This shift is most visible in United States metropolitan markets where clinic operators prioritize cash flow flexibility over balance sheet asset accumulation.
Radiofrequency-Based Aesthetic Devices Market Segmentation
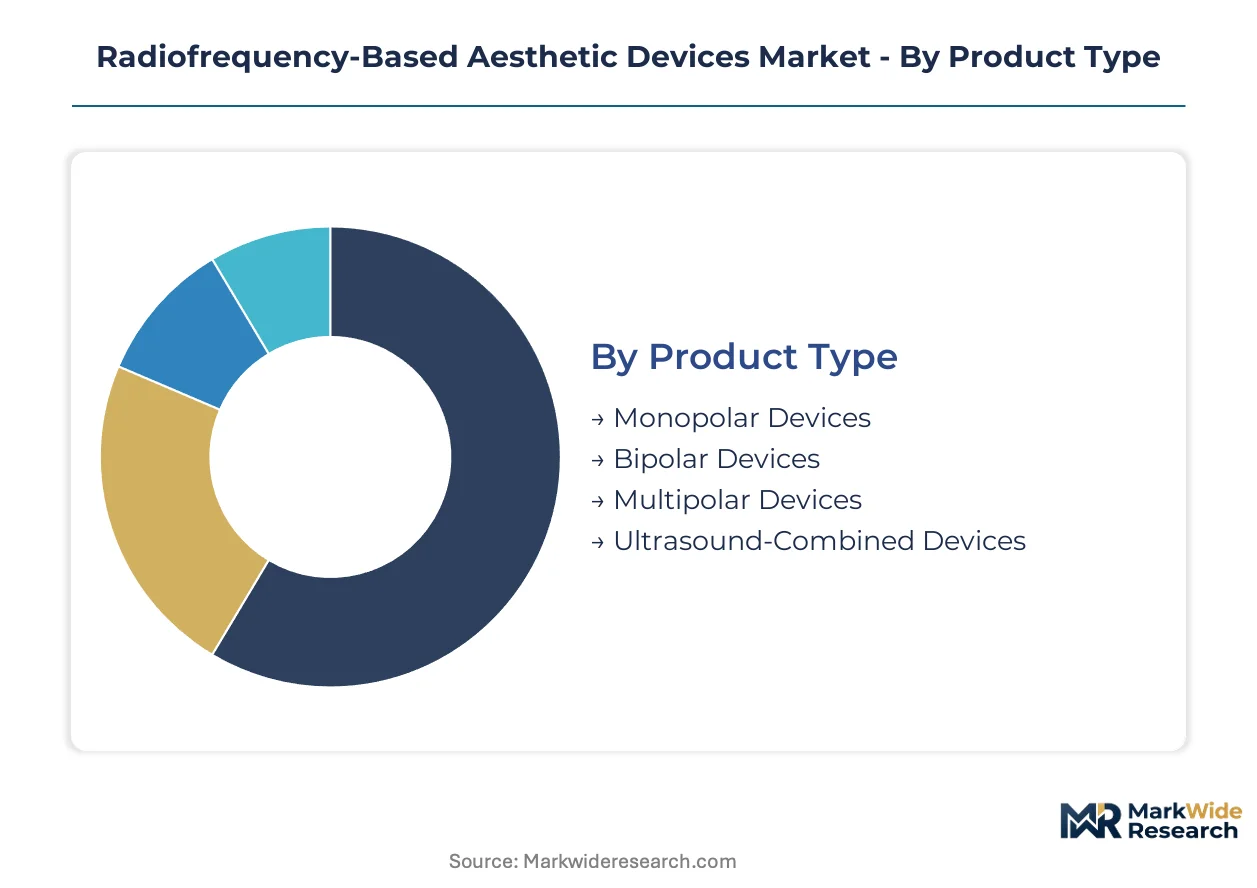
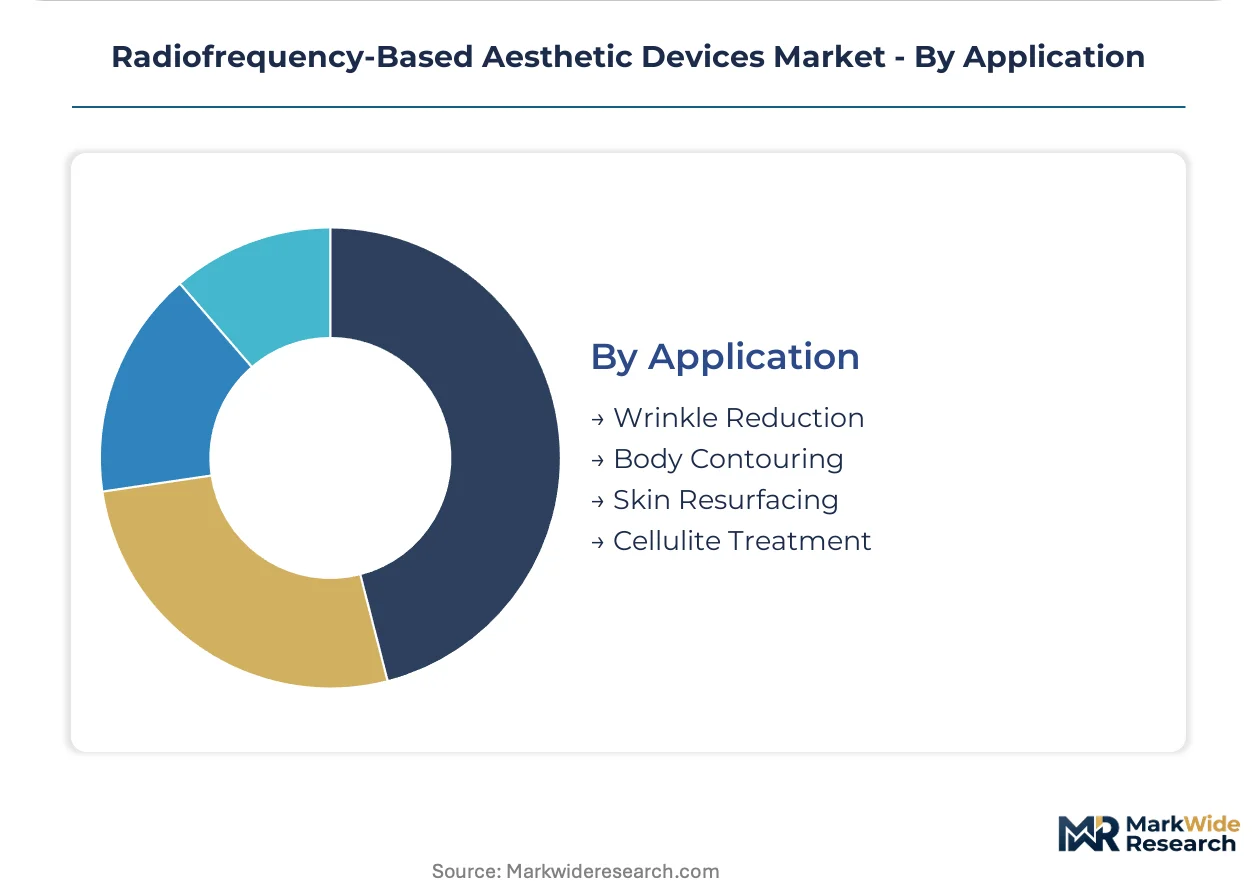
RF aesthetic device procurement patterns diverge sharply across clinical settings and consumer channels, with upgrade cycles compressing as modular platforms displace single-purpose systems. Segmentation clarity enables suppliers to align development roadmaps with distinct technical requirements and purchasing authority structures.
Product Type:
Equipment refresh cycles vary dramatically by electrode configuration, with multipolar systems dominating replacement demand due to workflow flexibility and reduced downtime profiles.
- Multipolar Devices:Three or more active electrodes create controlled thermal zones through phased energy delivery, enabling simultaneous treatment of larger surface areas. Demand concentrates in South Korean dermatology chains and medical tourism facilities where throughput efficiency determines equipment selection.
- Bipolar Devices:Paired electrodes confine current flow to superficial dermal layers, producing predictable heating patterns with minimal operator calibration. Established United States dermatology groups prioritize these systems for standardized staff training and liability risk reduction.
- Monopolar Devices:Single active electrode with large return pad enables deepest tissue penetration for subcutaneous fat disruption.
- Ultrasound-Combined Devices:Hybrid platforms integrate RF thermal delivery with acoustic cavitation for enhanced adipose tissue targeting.
Multipolar devices sit at the top of the volume ranking, with ultrasound-combined platforms climbing the fastest as combination therapy protocols gain traction.
Technology:
Capital allocation across RF technology categories tracks procedure reimbursement rates and consumable attachment economics, with microneedling variants commanding premium positioning.
- RF Microneedling:Insulated needles deliver thermal energy at precise dermal depths while sparing epidermal trauma. FDA 510(k) documentation requirements for these systems have extended pre-market timelines, concentrating procurement among well-capitalized United States dermatology groups.
- Fractional RF:Micro-needle arrays create fractional thermal injury patterns that accelerate collagen remodeling with reduced recovery periods. South Korean manufacturers dominate installed base expansion in Asia-Pacific medical tourism corridors.
- Non-Invasive RF:Surface electrode systems deliver energy without skin penetration, appealing to home care channels and entry-level clinical settings.
- Skin Tightening Devices:Purpose-built platforms optimize electrode geometry for laxity correction in facial and neck applications.
RF Microneedling captures the steepest expansion trajectory, while non-invasive RF maintains the broadest geographic penetration.
End User:
Purchasing authority structures determine equipment specification complexity, with institutional buyers prioritizing interoperability and individual practitioners emphasizing portability.
- Aesthetic Clinics:Mid-sized independent practices drive modular platform adoption through leasing structures that bundle consumables with equipment access. These buyers prioritize interchangeable applicator ecosystems over single-modality capital investments.
- Dermatology Centers:Physician-owned groups and hospital-affiliated practices demand comprehensive clinical evidence packages and training infrastructure. United States metropolitan markets show concentrated procurement of AI-guided treatment planning systems.
- Hospitals:Integrated health systems apply centralized procurement standards that favor established manufacturers with ISO 13485 certification.
- Home Care Users:Consumer-directed channels require simplified interfaces and reduced energy outputs that comply with FTC advertising substantiation requirements.
Dermatology centers anchor the revenue base, with home care users gaining share fastest as simplified devices enter direct-to-consumer distribution.
Application:
Procedure volume distribution reflects demographic aging patterns and body image concern prevalence, with facial applications sustaining premium pricing power.
- Wrinkle Reduction:Periorbital and perioral treatments utilize fractional RF and microneedling platforms to induce neocollagenesis without ablative surface damage. United States aesthetic clinics report strongest demand among patients aged 45-65 seeking maintenance procedures.
- Body Contouring:Subcutaneous fat disruption and skin tightening combinations target abdomen, flank, and thigh applications. South Korean medical tourism infrastructure channels international patients toward multipolar and ultrasound-combined platforms.
- Skin Resurfacing:Texture improvement and scar revision applications favor fractional delivery modes with controlled thermal injury depth.
- Cellulite Treatment:Connective tissue remodeling protocols address dermal-dermal interface irregularities through targeted heating.
Wrinkle reduction leads in procedure volume, with body contouring expanding most quickly as combination therapy protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radiofrequency aesthetic technology achieved commercial scale in South Korean dermatology chains during the early 2000s, with Seoul-based manufacturers establishing the template for multipolar and fractional platforms that now define global equipment standards.
United States
FDA 510(k) clearance pathways tightened evidentiary requirements for RF microneedling systems, extending pre-market timelines for manufacturers seeking entry. The FTC coordinates enforcement on at-home device advertising claims, elevating compliance infrastructure costs. Metropolitan dermatology groups in Los Angeles and New York deploy AI-guided treatment planning systems to standardize outcomes across high-volume practices.
South Korea
Medical tourism infrastructure channels concentrated procurement volumes from international patient flows toward domestic manufacturers. MFDS regulates device safety through pre-market notification requirements that align with export market standards. Seoul Capital Area hosts the densest cluster of fractional RF platform developers, with Gangnam district aesthetic clinics serving as demonstration sites for equipment exports.
Germany
EU MDR harmonization accelerates replacement demand for legacy systems lacking updated technical documentation. CE marking requirements under 2017/745 consolidate quality benchmarks across European distribution channels. Baden-Württemberg precision engineering clusters supply specialized electromagnetic components for RF applicator manufacturing.
Japan
PMDA regulatory frameworks emphasize clinical evidence standards that favor established manufacturers with dedicated quality management systems. METI industrial policy supports domestic device development through targeted R&D subsidies. Osaka-based aesthetic chains drive adoption of combination therapy protocols integrating RF with cryolipolysis platforms.
Brazil
ANVISA medical device registration creates market access barriers that concentrate procurement among multinational manufacturers with established regulatory infrastructure. São Paulo dermatology centers anchor demand for non-invasive RF systems targeting cellulite treatment applications. Local distributors in Rio de Janeiro manage service networks for imported equipment platforms.
Radiofrequency-Based Aesthetic Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and clinical evidence depth, with FDA-cleared RF microneedling systems commanding equipment premiums that erode under IPL substitution pressure. The vendor base stratifies into three tiers: multinational platform specialists with interchangeable applicator ecosystems, regional manufacturers serving medical tourism corridors, and emerging developers targeting home-use channels. Consolidation pressure intensifies as leasing structures and subscription-based equipment access redistribute margin pools toward consumables and software. Dominant competitive moves include strategic partnerships for AI-guided treatment planning integration and backward integration into precision electromagnetic component supply.
Within the premium-platform tier, InMode and Alma Lasers occupy positions that exemplify divergent go-to-market strategies, with the former anchoring modular ecosystem approaches and the latter representing flexible capital structure solutions. Cutera sits within the specialty-device archetype, its positioning reflecting concentrated investment in fractional RF microneedling protocols. These three entities collectively illustrate how regulatory infrastructure scale and clinical evidence depth determine tier placement across North American and Asia-Pacific markets.
| Leading Market Players |
|---|
| InMode |
| Cutera |
| Alma Lasers |
| Lutronic |
| Cynosure |
| Lumenis |
| Syneron Candela |
| Venus Concept |
| EndyMed |
| Others |
Pricing and Supply Chain Analysis
Modular platform bundling from mid-sized aesthetic clinics is forcing precision electromagnetic component suppliers to consolidate production in East Asian electronics clusters, compressing margins for RF applicator manufacturers while elevating pricing power for specialized copper coil vendors.
Pricing Analysis
Subscription-based equipment access bundled with consumable supply agreements dominates procurement, with three-tier pricing structure across premium, standard, and economy levels separating AI-guided treatment planning systems from basic fractional RF platforms. FDA 510(k) certification tier and ISO 13485 quality management status drive price differentiation between established manufacturers and emerging developers. Pricing pressure stems from IPL substitution in non-ablative skin tightening budgets. Home care channels exhibit highest price sensitivity; dermatology centers anchored by hospital systems show lowest.
Supply Chain Analysis
Single-source vulnerability sits with precision copper coil and electrode manufacturers concentrated in South Korea, Taiwan, and Japan. RF applicator production draws from specialized electromagnetic component feedstock, precision-machined needle arrays, and thermal management substrates. Tariff exposure on East Asian electronics imports threatens cost stability for North American device assemblers. Distribution runs through regional distributors managing service networks for imported equipment platforms, with direct manufacturer relationships reserved for high-volume dermatology chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play between South Korean manufacturing scale and United States regulatory compliance infrastructure, where domestic production avoids FDA import documentation burdens while Seoul-based R&D subsidies lower development cost bases.
For Market Incumbents: Deepen backward integration into precision electromagnetic component supply to defend against copper coil price volatility and East Asian supply concentration. Expand captive production of RF applicator subassemblies in Baden-Württemberg precision engineering clusters to reduce tariff exposure. Prioritize ISO 13485 certification investment for contract manufacturing relationships to maintain hospital system procurement eligibility. For New Entrants and Emerging Players: Launch via direct-to-consumer channels targeting home care users with simplified non-invasive RF devices, exploiting FTC advertising substantiation gaps that burden established players with compliance infrastructure costs. White-space opportunity concentrates in AI-guided treatment planning software subscriptions for mid-sized aesthetic clinics seeking outcome standardization. Penetrate Brazilian metropolitan markets through Rio de Janeiro distributor partnerships, leveraging ANVISA registration barriers that slow multinational expansion. For Investors and Strategic Acquirers: Asymmetric upside sits with regional manufacturers serving medical tourism corridors, where Seoul Capital Area density and Gangnam district demonstration sites create captive export demand. Long-term viability hinges on regulatory infrastructure scale across multiple jurisdictions. Signal to watch: FDA 510(k) clearance timeline compression for RF microneedling systems indicating reduced evidentiary burden for well-capitalized entrants.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market access for RF microneedling platforms in United States dermatology chains. |
| CE Marking Pathway | Unlocks EU MDR-harmonized distribution across German and broader European aesthetic clinic networks. |
| Hospital System Partnership | Secures centralized procurement contracts with integrated health systems prioritizing ISO 13485 certification. |
| Software Companion Development | Enables AI-guided treatment planning integration for high-volume United States metropolitan practices. |
| Reimbursement Strategy | Positions combination therapy protocols for coverage expansion as scope-of-practice regulations evolve. |
Research Methodology
Direct dialogue with aesthetic clinic operators, dermatology center procurement managers, biomedical engineers at device manufacturers, and GPO contracts specialists anchored primary insights, cross-referenced against FDA 510(k) filings, MFDS pre-market notifications, EU MDR technical documentation databases, and hospital procurement contract records. Bottom-up and top-down triangulation validated segment-level assumptions across the analysis window.
Bottom-up modeling aggregated equipment shipment data, consumable attachment rates, and service revenue streams by electrode configuration and technology category, while top-down analysis calibrated aggregate market scale against regulatory filing volumes and trade flow patterns. CAGRs derived from procedure volume growth trajectories, reimbursement rate evolution, and technology substitution curves across the projection horizon. Forecast inputs included AI-guided treatment planning adoption rates and state-level scope-of-practice regulatory shifts.
Several conditions sit outside the modeled scope, including macroeconomic recession impacts on discretionary aesthetic procedure demand, sudden FDA enforcement action on at-home device advertising claims, and copper commodity price spikes beyond historical volatility bands. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US C-Arms Market
Medical Devices
Global Medical Injection Molding Market
Medical Devices
Joint Reconstruction Devices Market
Medical Devices
Global Biopsy Punch Market
Medical Devices
Global Antimicrobial Coatings for Medical Devices Market
Medical Devices
Electrocardiograph (ECG) Market
Medical Devices
Breast Pump Flange Market
Medical Devices
Europe Sperm Separation Devices Market
Medical Devices
Intravenous Stopcock Market
Medical Devices
Medical Coatings Market
Medical Devices
3D Printing Medical Devices Market
Medical Devices
Global Canes and Crutches Market
Medical Devices
Absorbable PGLA Surgical Sutures Market
Medical Devices
Wearable Bioelectronic Skin Patches Market
Medical Devices
Infrared Heating Pad Market
Medical Devices
Argentina Respiratory Devices Market