
 Disposable Contact Lenses Market | 2026-2036
Disposable Contact Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Contact Lenses Market Intelligence
The widespread substitution of traditional hydrogel with advanced silicone hydrogel materials is restructuring product economics and patient outcomes. Johnson & Johnson Vision Care Inc. leverages its significant R&D investment in material science to lead in this space. Alcon Inc. competes through a diversified portfolio spanning daily to extended wear options. Bausch + Lomb Incorporated sustains its position by focusing on solutions for digital eye strain and moisture retention technologies.
Disposable contact lenses are Class II or Class III medical devices, typically made from polymers like polymacon or silicone hydrogel, designed for short-term vision correction. Their primary function is to correct refractive errors such as myopia and hyperopia. The daily wear duration segment shows the highest growth, valued for its convenience and hygiene benefits. Lenses for astigmatism and presbyopia applications command premium pricing compared to standard spherical lenses.
Product approval and market access are governed by stringent regulatory frameworks for medical devices. Key authorities include the FDA in the United States, the EMA in Europe enforcing the Medical Device Regulation (MDR), and Japan's PMDA. These bodies enforce standards for material biocompatibility and clinical performance. Success for manufacturers depends on navigating these distinct regional approval pathways while innovating for niche applications.
Market Dynamics
The evolution of polymer science, particularly the transition from hydrogel to silicone hydrogel materials, is the central force shaping product capabilities and market economics. This shift directly addresses consumer demand for improved comfort and ocular health, driving R&D and competitive positioning.
Growth Catalysts
- Silicone Hydrogel Adoption:This material's superior oxygen permeability enhances corneal health and comfort, expanding the market to users requiring longer wear-times or those with higher sensitivity.
- Presbyopia Demographics:An aging global population increases presbyopia prevalence, creating a dedicated and expanding consumer base for specialized multifocal disposable lenses.
- Economic Growth:Rising healthcare spending and urbanization in countries like China and Brazil unlock new demand for convenient vision correction, supporting shifts from eyeglasses.
Market Restraints
- Raw Material Costs:The synthesis of silicone hydrogel monomers is more complex and costly than traditional polymacon, translating to higher end-product prices for consumers.
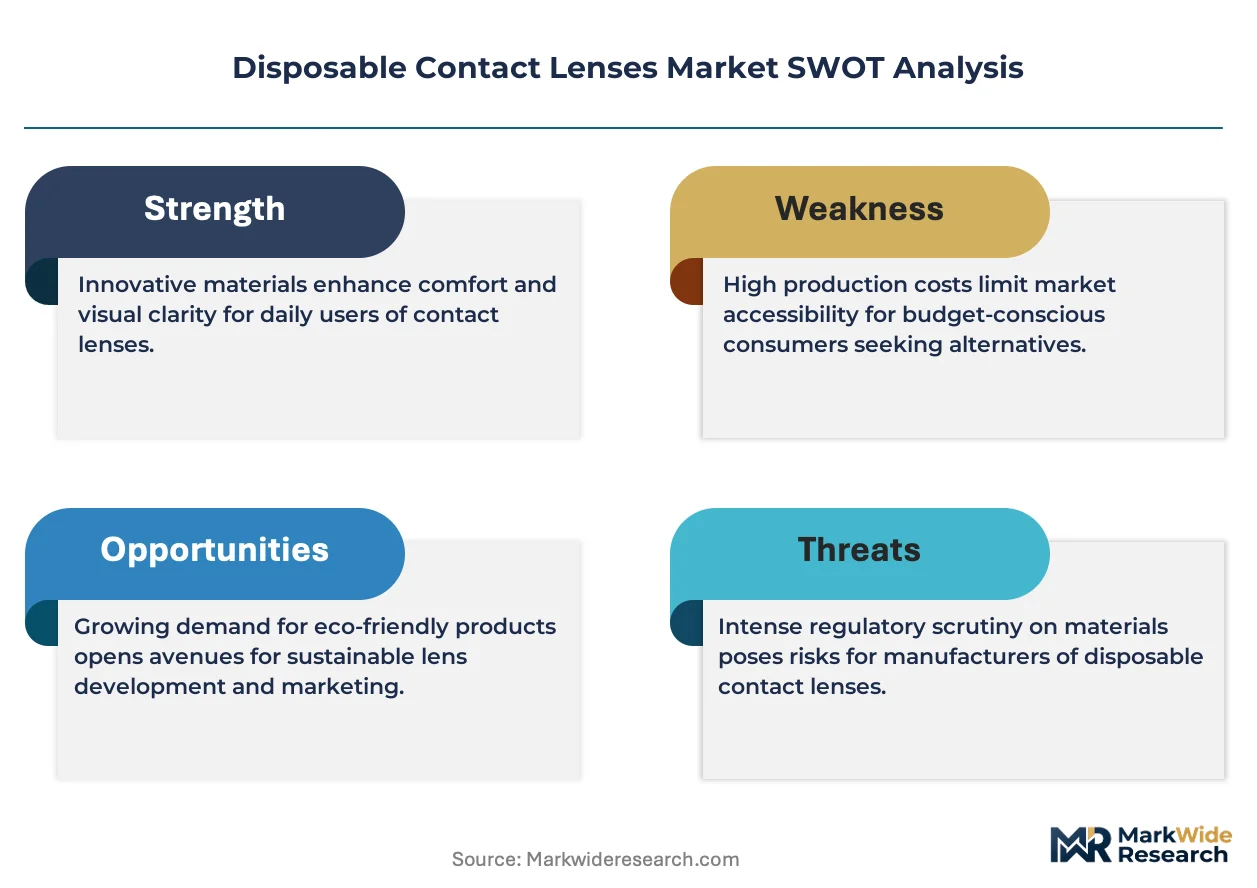
- Regulatory Hurdles:Stringent clinical data requirements from the FDA and EMA create long, expensive pathways for new product approvals, which can limit market entry for smaller innovators.
- Substitution Risk:Alternative vision correction methods, including LASIK surgery and advanced spectacle lenses, present a persistent threat to the contact lens user base.
Strategic Opportunities
- Smart Lenses:The integration of biosensors into contact lenses for non-invasive health monitoring, such as glucose levels for diabetic patients, represents a new high-value frontier.
- Digital Eye Strain Solutions:Developing lenses with specific blue-light filtering or unique optical designs addresses a growing need from consumers with high daily screen-time exposure.
- Underpenetrated Markets:Low current adoption rates in Latin American and Southeast Asian countries present significant geographic expansion opportunities for established manufacturers.
Industry Challenges
- Regulatory Divergence:Navigating disparate and evolving medical device regulations, such as the EU's MDR and Japan's PMDA rules, complicates global product launches and increases compliance overhead.
- Counterfeit Products:The proliferation of unauthorized online sellers distributing non-compliant or counterfeit lenses threatens patient safety and erodes brand trust in the market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Contact Lenses Market |
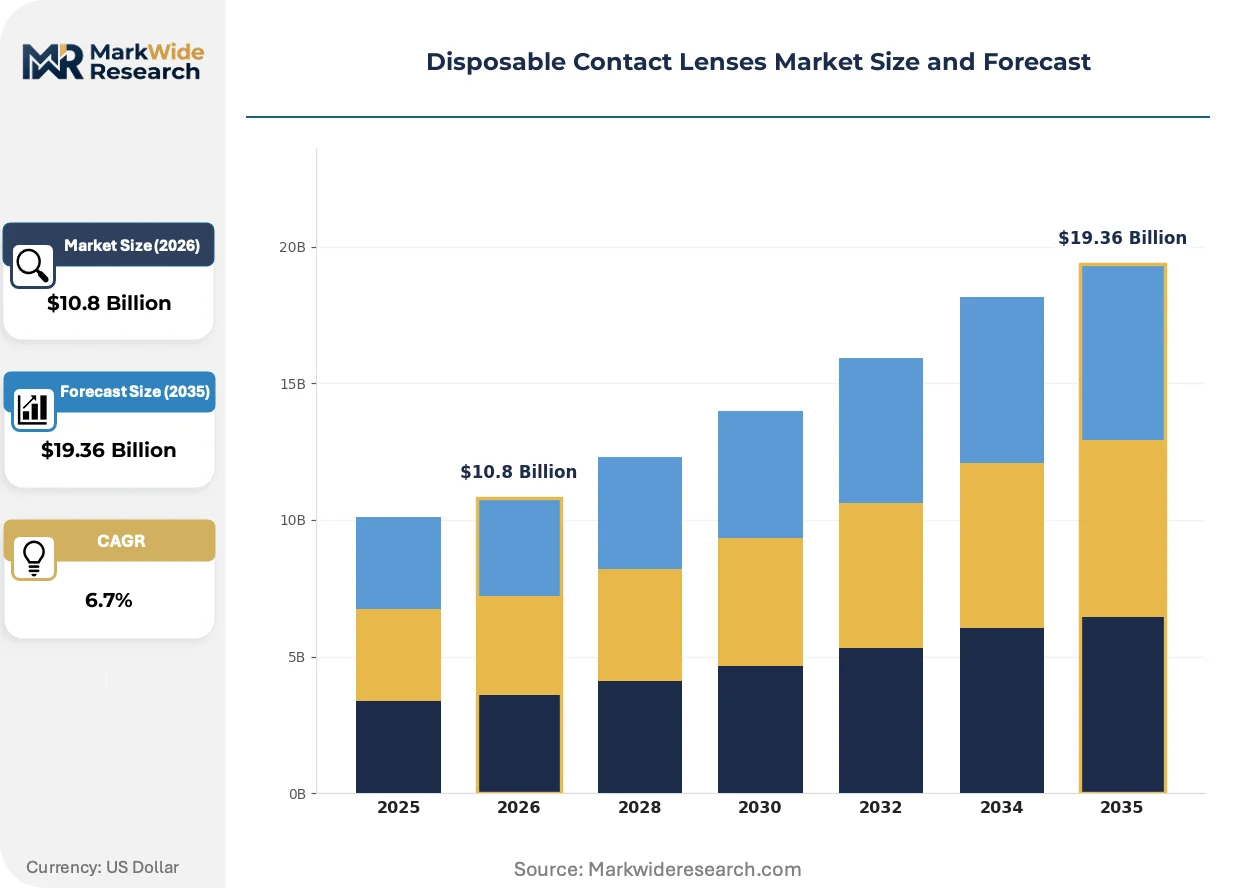
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $19.36 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Hydrogel, Silicone Hydrogel, Polymacon, Methafilcon, Omafilcon Wear Duration: Daily, Bi-weekly, Monthly, Quarterly, Extended Wear Application: Myopia, Hyperopia, Astigmatism, Presbyopia, Cosmetic Correction End User: Optometrists, Ophthalmologists, Optical Retailers, Eye Care Clinics, Online Retailers |
| Companies Covered | Johnson & Johnson Vision Care Inc., Alcon Inc., Bausch + Lomb Incorporated, CooperVision Inc., Carl Zeiss AG, HOYA Corporation, Menicon Co. Ltd., SEED Co. Ltd., Interojo Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Contact Lenses Market Strategic Shifts & Innovations
Material science advancements are converging with digital consumer behaviors to redefine product value and delivery. This interaction is pushing innovation beyond simple vision correction toward integrated lifestyle and wellness solutions, impacting both product design and distribution channels.
Advanced moisture-embedding technologies integrate wetting agents directly into the silicone hydrogel matrix for sustained hydration. This is rapidly being adopted by consumers experiencing dry eye symptoms, often linked to digital screen use. This material science innovation is converging with the demand for all-day comfort, making daily disposables a viable option for a wider patient population.
The European Union's Medical Device Regulation (MDR) mandates more stringent clinical evidence and post-market surveillance for all devices. This increases the compliance burden, requiring manufacturers to invest heavily in data collection and lifecycle management systems. The daily disposable segment is particularly impacted, as high sales volumes now necessitate more rigorous and continuous performance monitoring to maintain CE marking.
A clear behavioral shift toward subscription-based purchasing models is gaining momentum among consumers. This direct-to-consumer (DTC) trend disrupts reliance on traditional optical retailers and empowers users with greater convenience and brand choice. The transition is most visible in North America and Western Europe, where e-commerce infrastructure supports recurring delivery services for vision care products.
Disposable Contact Lenses Market Segmentation
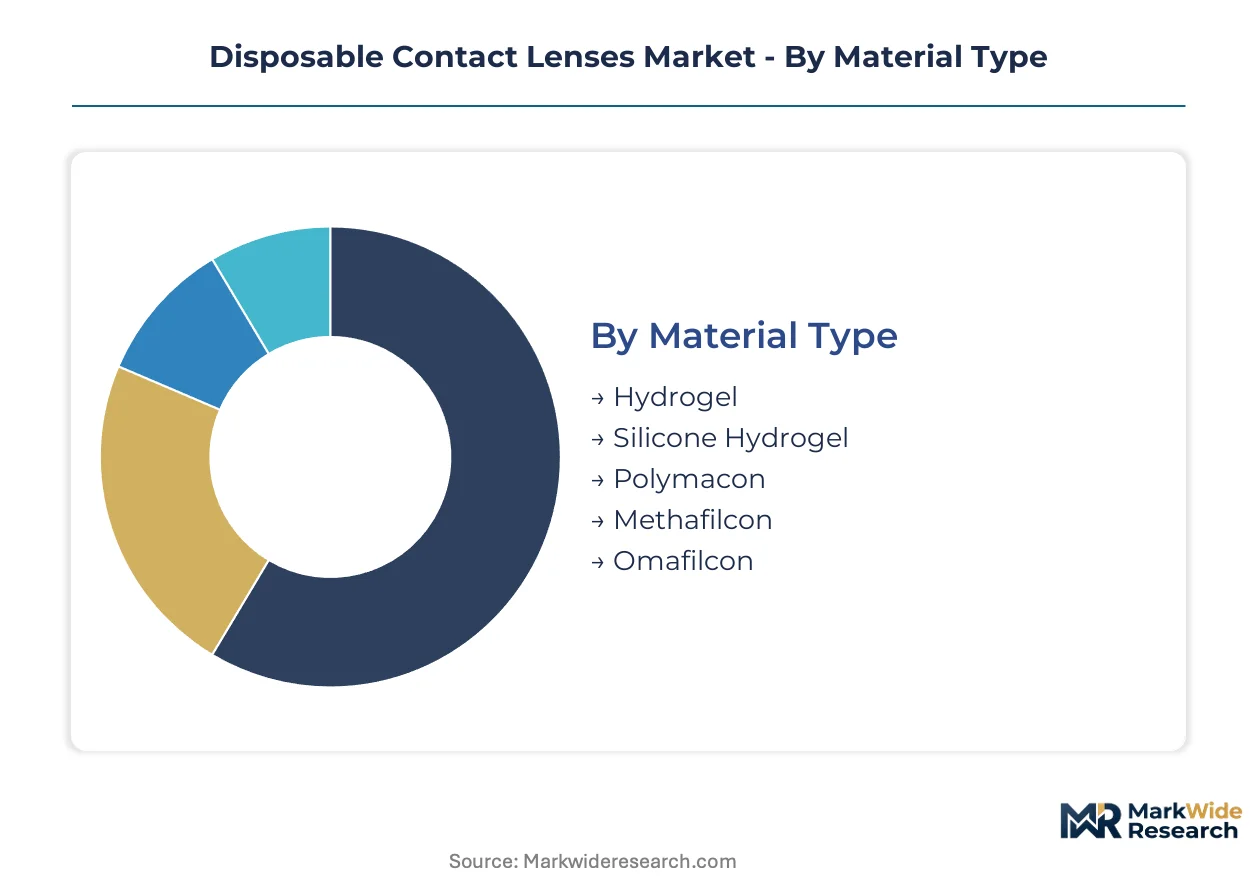
Understanding the distinct segments within the disposable contact lenses market is critical for manufacturers to align product development with specific consumer needs and channel dynamics. This detailed segmentation reveals the varied demand drivers across material science, wear patterns, vision correction requirements, and distribution pathways.
Material Type:
Supply concentration in material science largely dictates product performance and cost structures for disposable contact lenses.
- Silicone Hydrogel:This advanced polymer offers superior oxygen permeability, enhancing corneal health and extended wear comfort. Demand concentrates in developed markets and for users requiring longer wear times due to its physiological benefits.
- Hydrogel:Traditional water-based polymers provide basic vision correction and established comfort. Demand is often concentrated in cost-sensitive segments and for new users seeking entry-level options.
- Polymacon:A conventional hydrogel polymer, widely used in many standard contact lens formulations.
- Methafilcon:This hydrophilic hydrogel material contributes to lens wettability and comfort.
- Omafilcon:A non-ionic hydrogel designed to resist protein and lipid deposits, promoting cleaner lens surfaces.
Today's leader: Silicone Hydrogel. Tomorrow's challenger: Omafilcon.
Wear Duration:
Volume distribution across wear duration types reveals distinct consumer preferences driven by convenience, hygiene, and cost considerations.
- Daily:Single-use lenses offer maximum hygiene and convenience, eliminating the need for cleaning solutions. Demand is concentrating among busy professionals and consumers prioritizing eye health in urban environments.
- Monthly:These lenses provide a cost-effective solution for regular wearers, requiring daily cleaning and disinfection. Demand is strong in established markets where users balance cost and convenience.
- Bi-weekly:Replaced every two weeks, these lenses offer a balance between daily disposables and monthly options.
- Quarterly:Less common, these lenses are designed for extended use over three months with diligent care.
- Extended Wear:Approved for continuous wear overnight for specified periods, emphasizing high oxygen transmission.
The daily wear duration segment is expanding most quickly due to hygiene benefits.
Application:
Customer demographics significantly influence application demand, with specialized lenses addressing a spectrum of vision correction needs.
- Presbyopia:Multifocal lenses correct age-related near vision loss, providing clear vision at multiple distances. Demand is surging due to the aging global population and increased awareness of specialized options.
- Astigmatism:Toric lenses feature a specific design to correct vision blurred by an irregularly shaped cornea. Demand is concentrated among patients with complex refractive errors seeking precise visual acuity.
- Myopia:Corrects nearsightedness, representing the largest volume of refractive error corrections globally.
- Hyperopia:Addresses farsightedness, often corrected with standard spherical lens designs.
- Cosmetic Correction:Lenses designed to change or enhance eye color, driven by aesthetic consumer preferences.
The market for presbyopia correction is gaining share fastest due to demographic shifts.
End User:
Margin structures vary considerably across different end-user distribution channels, reflecting service levels and consumer purchasing habits.
- Optical Retailers:Traditional brick-and-mortar stores offer professional fitting services and immediate product availability. Demand is strong from consumers who prefer in-person consultation and expert guidance.
- Online Retailers:E-commerce platforms provide convenience, competitive pricing, and direct-to-consumer delivery models. Demand is concentrating among tech-savvy and price-conscious consumers.
- Optometrists:Primary eye care professionals who prescribe and fit contact lenses, providing essential patient education.
- Ophthalmologists:Medical doctors specializing in eye health, often referring patients for contact lens options after medical assessment.
- Eye Care Clinics:Integrated facilities offering comprehensive eye examinations, prescriptions, and product sales.
Online channels are climbing the fastest, disrupting traditional distribution models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Massachusetts medical device corridor, a hub for ophthalmic innovation, underpins significant market activity for disposable contact lenses. This region benefits from high consumer awareness and strong regulatory oversight by the FDA. Demand for daily disposables and specialized lenses continues to expand here.
United States
US consumers prioritize convenience and eye health, driving strong demand for daily disposable lenses. The FDA's stringent approval processes ensure product safety and clinical efficacy for new entrants. California's ophthalmic research centers actively develop advanced materials and smart lens technologies.
China
China's expanding middle class and increasing urbanization fuel substantial growth in disposable contact lens adoption. The NMPA regulates market entry and product standards, influencing manufacturing practices. The Yangtze River Delta region sees significant investment in domestic production and distribution networks.
Germany
German consumers seek high-comfort, specialized lenses, particularly for presbyopia correction. The European Medical Device Regulation (MDR) sets rigorous standards for product quality and post-market surveillance. Bavaria's precision optics industry contributes to advanced lens design and manufacturing expertise.
Japan
Japanese consumers value hygiene and aesthetic options, driving sales of daily disposables and cosmetic lenses. Japan's PMDA ensures strict quality control and clinical performance for all ophthalmic devices. The Kanto region, including Tokyo, serves as a major distribution and innovation hub for contact lens manufacturers.
Brazil
Brazilian consumers in urban centers increasingly adopt disposable contact lenses for convenience and lifestyle benefits. ANVISA oversees product registration and quality control for medical devices across the country. São Paulo's metropolitan area acts as a primary market and distribution gateway for Latin American expansion.
Disposable Contact Lenses Market Key Industry Players
Global majors compete with regional champions across material science and distribution channels within the disposable contact lenses market. The industry structure exhibits a tiered consolidation, with a few large multinational corporations dominating premium segments. Innovators and specialized players occupy niche segments, focusing on advanced materials or specific vision correction needs. Companies primarily engage in strategic R&D investments and portfolio diversification to maintain market share.
Within the multinational archetype, Johnson & Johnson Vision Care Inc. represents a leader in material science, particularly silicone hydrogel advancements. This company leverages its significant R&D investments to drive product development and market penetration. Alcon Inc. exemplifies a diversified portfolio approach, spanning various wear durations and application types, catering to a broad customer base. Bausch + Lomb Incorporated occupies a position focused on addressing specific consumer needs, such as digital eye strain and enhanced moisture retention technologies. These entities collectively anchor significant market share through extensive global distribution networks and continuous product innovation.
| Leading Market Players |
|---|
| Johnson & Johnson Vision Care Inc. |
| Alcon Inc. |
| Bausch + Lomb Incorporated |
| CooperVision Inc. |
| Carl Zeiss AG |
| HOYA Corporation |
| Menicon Co. Ltd. |
| SEED Co. Ltd. |
| Interojo Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps and publicly traded corporations influence disposable contact lens supply behavior and pricing discipline. Their investment in advanced materials like silicone hydrogel directly impacts end-user costs and market accessibility.
Pricing Analysis
Raw material costs for silicone hydrogel directly pass through to disposable contact lens pricing. The market primarily uses a three-tier pricing structure across premium, standard, and economy levels. Price differentiation stems from material innovation, such as silicone hydrogel, and specialized applications like presbyopia correction. Pricing softness reflects intense competition from alternative vision correction methods. Cost-sensitive segments, often new users, contrast with those seeking advanced comfort and specialized correction.
Supply Chain Analysis
Online retail platforms and traditional optical retailers form the primary distribution models for disposable contact lenses. Supply concentrates in countries with advanced manufacturing capabilities, including the United States, Japan, and Germany. The industry relies on specialized silicone monomers and hydrogel polymers for lens production. Regulatory restrictions, particularly varying medical device approvals across regions, pose a significant structural supply chain risk. Distribution runs through both direct-to-consumer channels and professional eye care networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The disposable contact lenses market acts as a stable compounder, driven by continuous material science advancements. This steady growth reflects ongoing consumer demand for enhanced comfort and improved ocular health solutions.
For Market Incumbents:Deploy R&D investment into next-generation silicone hydrogel materials to maintain product differentiation. Pursue strategic partnerships with digital health platforms to integrate smart lens technologies, countering substitution risk from LASIK surgery. Strengthen global regulatory compliance efforts, especially with the EU's MDR, to mitigate market access hurdles. Expand manufacturing capacity in key regional hubs to optimize cost structures.
For New Entrants and Emerging Players:Capture market share in underpenetrated Latin American and Southeast Asian geographies. Focus on developing cost-effective daily disposable lenses for these regions, leveraging the hygiene benefits. The presbyopia application segment presents a highly penetrable opportunity due to demographic shifts. A direct-to-consumer e-commerce model, emphasizing convenience and subscription services, can accelerate market entry.
For Investors and Strategic Acquirers:Valuations sit cheapest among specialized material science innovators and regional manufacturers with strong distribution networks. The long-term viability of this market remains robust over a 5-10 year window, driven by an aging population and increasing screen time. Target mid-sized companies possessing unique intellectual property in advanced polymer development. The signal to watch is the successful commercialization of non-invasive health monitoring smart lenses.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Material R&D | Drives superior oxygen permeability, enhancing wearer comfort and corneal health. |
| Digital Health Integration | Positions lenses as lifestyle solutions, attracting tech-savvy consumers. |
| Targeted Geographic Expansion | Unlocks new demand in emerging economies like China and Brazil. |
| Regulatory Pathway Optimization | Accelerates market entry for innovative products under FDA and EMA standards. |
| Subscription Model Deployment | Boosts customer loyalty and recurring revenue for manufacturers. |
Research Approach
Bottom-up patient demographic modeling reconciled against top-down manufacturer supply tracking forms the analytical core for this study. This approach integrates primary interviews with optometrists, R&D directors, and procurement managers, validated through extensive secondary research. Secondary data sources include FDA filings, EMA submissions, NMPA reports, and company financial disclosures. This triangulation ensures robust data accuracy across both demand and supply sides.
Historical trendline analysis informs the projection of market growth across the analysis window. The analytical framework models segmentation by material type, wear duration, application, end-user, and geographic region. Compound annual growth rates are derived from weighted averages of these segments. Key forecast inputs include global demographic shifts impacting presbyopia prevalence and advancements in silicone hydrogel materials.
Underlying measurement precision varies by segment; established hydrogel and daily wear segments carry tighter precision than emerging smart lens applications. Forecasts reflect assumptions regarding regulatory stability and raw material availability. Periodic stress-testing of base assumptions is recommended due to potential shifts in medical device regulations or competitive landscape.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Disposable Needle Guides Market
Medical Devices
Neurothrombectomy Devices Market
Medical Devices
Global Refractive Surgery Devices Market
Medical Devices
Cervical Retractors Market
Medical Devices
Global Foot Orthotic Insoles Market
Medical Devices
Medical Manifolds Market
Medical Devices
Manual Wheelchair Market
Medical Devices
Injection Practice Pad Market
Medical Devices
Asia-Pacific Ultrasound Probe Disinfection Market
Medical Devices
Medication Dispensing and Packaging Systems Market
Medical Devices
Ultrasonic Nebulizers Market
Medical Devices
India Anesthesia Devices Market
Medical Devices
North America General Surgical Devices Market
Medical Devices
Bathroom and Toilet Assist Devices Market
Medical Devices
Global Closed System Transfer Devices Market
Medical Devices
MRI Coils Market