
 Global Surgical Visualization Products Market | 2026-2036
Global Surgical Visualization Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surgical Visualization Products Market Foresight
Surgeon training capacity is bifurcating the competitive landscape between established academic centers and community hospitals struggling with visualization competency gaps. Olympus Corporation leverages its Institute of Training and Education to lock in long-term institutional relationships. Stryker Corporation sustains R&D intensity across its 1588 camera platform to defend premium positioning. Karl Storz GmbH & Co. KG dominates rigid endoscope craftsmanship through German manufacturing heritage that anchors European procurement preferences.
Surgical visualization products comprise optical and electronic systems engineered to magnify, illuminate, and digitally capture anatomical structures during operative procedures, with 4K resolution sensors and CMOS chip architectures now standard in flagship camera heads. These systems enable real-time tissue differentiation that reduces iatrogenic injury rates in laparoscopic and open interventions. Fluorescence technology leads technology segment margins because indocyanine green integration commands premium pricing in oncologic resections. Augmented Reality occupies the fastest-expanding niche as headset overlays merge preoperative imaging with live endoscopic feeds. Endoscopes remain the largest product type by installed base, though surgical microscopes generate higher per-unit profitability in neurosurgery and ophthalmology applications.
FDA 510(k) clearance timelines shape American market entry velocity for novel visualization modalities, while EU MDR technical documentation requirements extend certification cycles for European launches. Japan's PMDA enforces JIS standards for electromagnetic compatibility that filter out lower-tier Asian manufacturers. Stakeholders must monitor how FDA's evolving software-as-medical-device guidance treats AI-powered image enhancement algorithms embedded in next-generation camera processors.
Market Dynamics
CMOS sensor miniaturization is compressing camera head form factors while EU MDR sterilization protocols force redesign cycles across reusable endoscope portfolios. This dual pressure concentrates R&D budgets among manufacturers with captive semiconductor supply chains and German-certified sterilization infrastructure.
Growth Catalysts
- Fluorescence-guided oncology protocols:Indocyanine green integration in hepatobiliary resections drives replacement demand for 4K-fluorescence hybrid systems in Heidelberg and Berlin university hospital clusters.
- EU MDR clinical evidence mandates:Stricter sterilization documentation requirements for reusable endoscopic devices accelerate validation spending that locks out subscale competitors.
- Japan's PMDA electromagnetic compatibility standards:JIS certification filters lower-tier Asian manufacturers, concentrating procurement among METI-compliant domestic and European suppliers.
Market Restraints
- German manufacturing concentration:Rigid endoscope optical craftsmanship clusters around Tuttlingen, creating single-source vulnerability for European procurement chains.
- CMOS wafer input volatility:Semiconductor foundry capacity constraints in Taiwan and South Korea transmit pricing instability to camera head production schedules.
- FDA 510(k) timeline compression:Software-as-medical-device guidance uncertainty for AI-powered image enhancement algorithms extends American market entry cycles.
Strategic Opportunities
- Augmented Reality headset overlays:Preoperative imaging fusion with live endoscopic feeds opens neurosurgery and spinal navigation applications underserved by conventional monitors.
- Community hospital competency gaps:Surgeon training capacity bifurcation creates service contract opportunities for visualization system vendors with captive education infrastructure.
- India's PLI scheme for medical devices:Domestic manufacturing incentives attract component assembly investment targeting price-sensitive South Asian procurement budgets.
Industry Challenges
- EU MDR technical documentation cycles:Extended certification timelines for European launches compress revenue recognition windows and strain working capital.
- Legacy 1080p system integration:Hospital IT infrastructure heterogeneity complicates 4K camera head deployment without parallel network backbone upgrades.
- Sterilization protocol revalidation:Reusable endoscope redesign requirements demand parallel clinical evidence generation that diverts engineering resources from next-generation development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surgical Visualization Products Market |
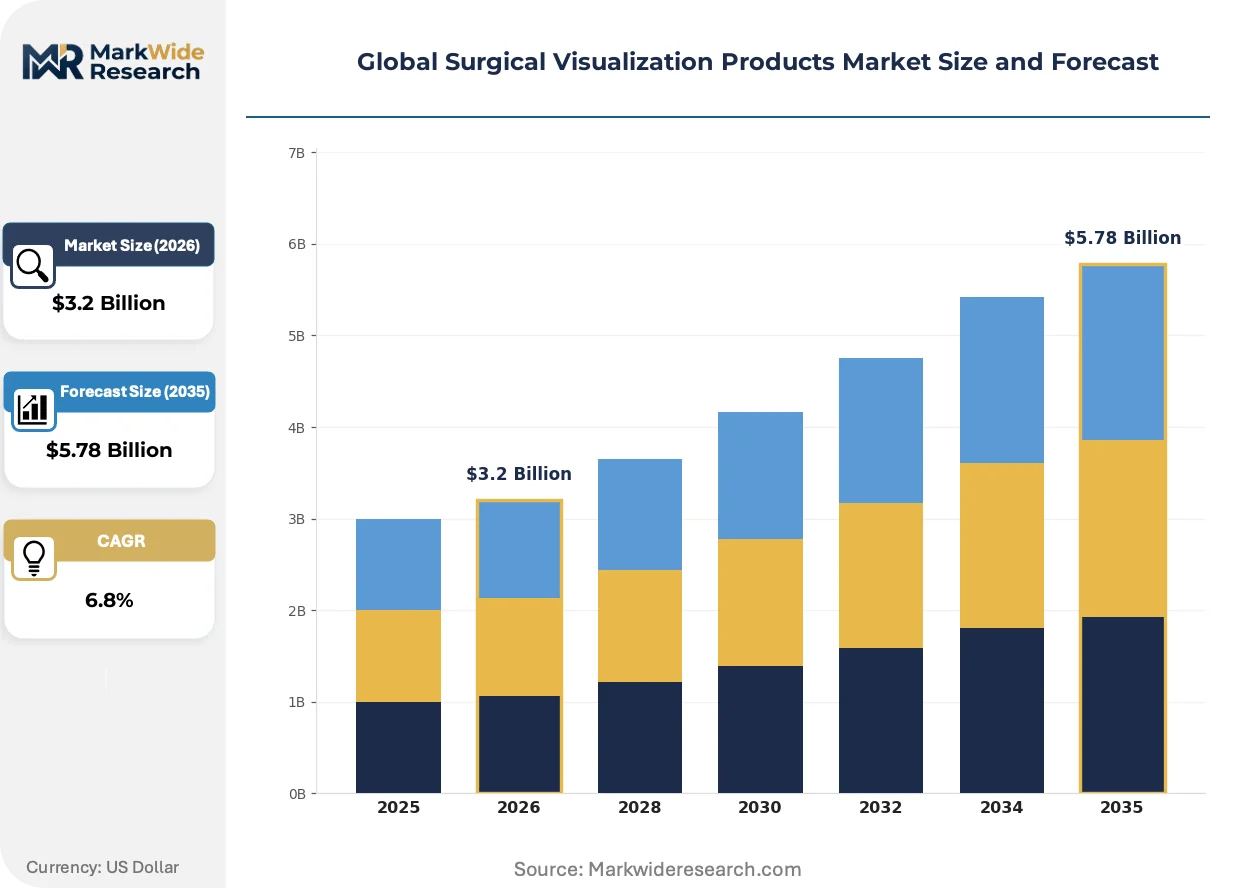
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopes, Surgical Microscopes, Cameras, Display Monitors, Light Sources Technology: 3D Imaging, Fluorescence, High-Definition, Augmented Reality, Narrow Band Imaging Application: Neurosurgery, Cardiothoracic Procedures, Orthopedic Surgery, Gastroenterology, Urology End User: Ambulatory Surgery Centers, Diagnostic Laboratories, Specialty Clinics, Academic Medical Centers, Research Institutes |
| Companies Covered | Olympus Corporation, Stryker Corporation, Medtronic, Karl Storz GmbH & Co. KG, Fujifilm Holdings Corporation, Smith & Nephew, Conmed Corporation, Richard Wolf GmbH, Arthrex, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surgical Visualization Products Market Shifts & Advancements
Visualization hardware is flattening while software layers accumulate value. Three concurrent developments—component miniaturization, regulatory software classification, and procurement unbundling—are restructuring how surgical imaging systems are specified, priced, and maintained across hospital capital budgets.
Chip-on-tip CMOS architectures are miniaturizing distal sensor placement in flexible endoscopes. Gastroenterology suites in Tokyo university hospitals adopt sub-3mm outer diameter scopes for transnasal procedures. This form factor compression enables same-day surgery workflows that displace traditional inpatient admission patterns.
EU MDR software-as-medical-device classification captures AI-powered image enhancement algorithms embedded in camera processors. Manufacturers must submit technical documentation for algorithm updates that previously shipped as firmware patches. This regulatory capture most affects oncology applications where real-time tissue characterization drives purchasing decisions.
Hospital procurement departments unbundle visualization hardware from multi-year service contracts. German university hospitals now source camera heads through competitive tender while negotiating training and maintenance separately. This disaggregation concentrates price pressure on equipment margins while elevating service revenue as a defendable profit pool.
Global Surgical Visualization Products Market Segmentation
Surgical visualization procurement fragments across hardware categories, imaging modalities, and care settings with divergent substitution pressures. Each segment exhibits distinct vulnerability to adjacent technologies and alternative clinical workflows.
Product Type:
Substitution pressure intensifies where single-use alternatives and software-defined imaging erode capital equipment value.
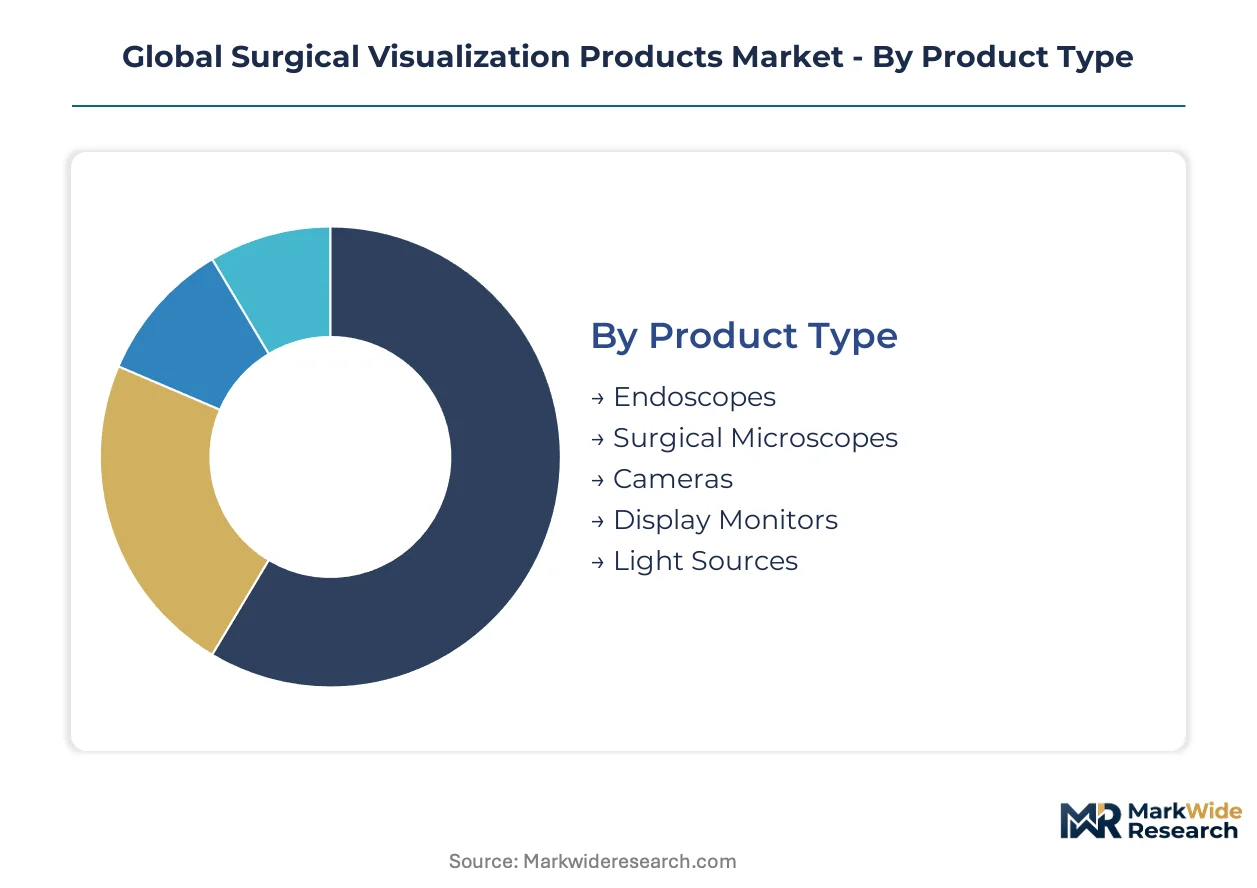
- Endoscopes:Rigid and flexible fiber-optic or video systems deliver direct anatomical visualization through natural orifices or surgical ports. Demand clusters in German university hospitals in Heidelberg and Berlin where 4K-fluorescence hybrid procurement anchors European replacement cycles. EU MDR sterilization revalidation requirements accelerate validation spending that locks out subscale reusable endoscope competitors.
- Surgical Microscopes:Optical-mechanical systems with motorized positioning and integrated imaging for microsurgical fields command premium per-unit profitability in neurosurgery and ophthalmology suites. CMOS sensor miniaturization compresses camera head form factors while maintaining optical performance thresholds.
- Cameras:CMOS-chip-based camera heads convert optical signals to digital streams for processing and display.
- Display Monitors:Medical-grade screens calibrated for color accuracy and luminance consistency in surgical environments.
- Light Sources:LED and xenon illumination systems coupled to endoscopes through fiber-optic light guides.
Endoscopes retain volume leadership; Augmented Reality headset overlays hold the steepest expansion curve as preoperative imaging fusion displaces conventional monitor dependency.
Technology:
Cost tier stratification separates premium fluorescence and AR systems from commoditized HD infrastructure in hospital capital budgets.
- 3D Imaging:Stereoscopic visualization systems render depth perception for laparoscopic suturing and robotic-assisted procedures. Demand concentrates in Japanese academic medical centers where METI-compliant domestic suppliers dominate procurement.
- Fluorescence:Indocyanine green integration enables real-time perfusion assessment and tumor margin delineation in oncologic resections. Heidelberg and Berlin university hospital clusters drive replacement demand for 4K-fluorescence hybrid systems in hepatobiliary protocols.
- High-Definition:1080p resolution systems face displacement pressure as 4K infrastructure becomes standard in flagship installations.
- Augmented Reality:Headset overlays merge preoperative CT/MRI with live endoscopic feeds for neurosurgery navigation.
- Narrow Band Imaging:Spectral-filtered light enhancement improves mucosal surface visualization in gastroenterology screening.
High-Definition retains installed base dominance; Augmented Reality gains share fastest as spinal navigation applications expand beyond conventional monitor limitations.
Application:
Volume concentration in high-acuity settings creates margin dispersion across procedure complexity tiers.
- Neurosurgery:Microscopic and endoscopic visualization for intracranial and spinal procedures demands sub-millimeter resolution and fluorescence capability. German Tuttlingen manufacturing clusters anchor rigid endoscope optical craftsmanship for European procurement preferences.
- Cardiothoracic Procedures:Visualization for minimally invasive valve repair and coronary bypass requires 3D imaging integration with perfusion assessment. Demand concentrates in North American hospital systems expanding minimally invasive surgery suites faster than other buyer segments.
- Orthopedic Surgery:Arthroscopic visualization for joint repair and reconstruction.
- Gastroenterology:Flexible endoscopy for diagnostic and therapeutic procedures.
- Urology:Endoscopic visualization for renal and prostatic interventions.
Neurosurgery retains premium pricing leadership; Orthopedic Surgery climbs fastest as ambulatory surgery center volume shifts drive capital equipment standardization.
End User:
Customer type determines procurement authority consolidation versus fragmented purchasing across integrated delivery networks.
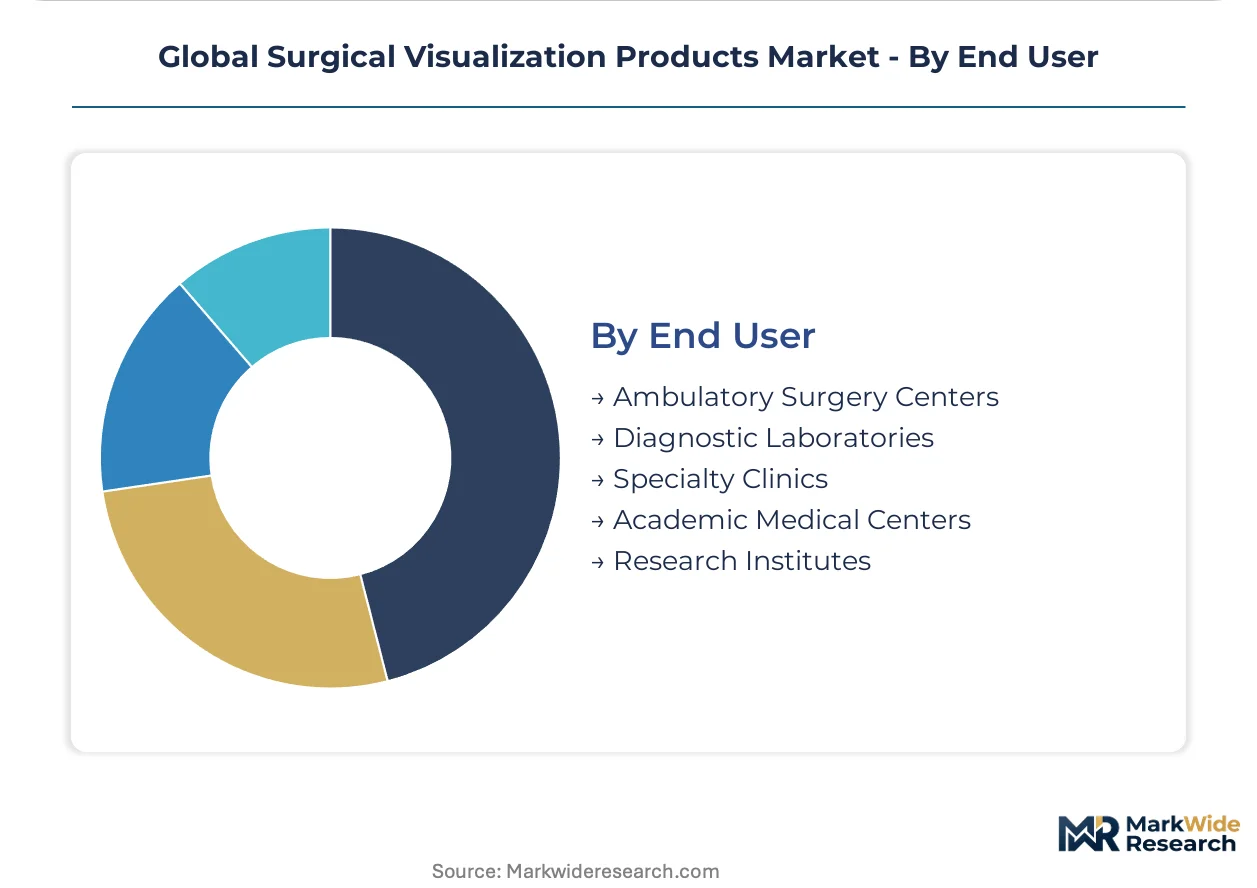
- Ambulatory Surgery Centers:Outpatient facilities performing same-day procedures prioritize compact, multi-specialty visualization platforms. India's PLI scheme for medical devices attracts component assembly investment targeting price-sensitive South Asian procurement budgets.
- Diagnostic Laboratories:Pathology and cytology visualization for specimen examination and telepathology consultation.
- Specialty Clinics:Single-discipline practices with focused procedure volumes and limited capital budgets.
- Academic Medical Centers:Teaching hospitals with research mandates and fellowship training programs anchor 4K-fluorescence hybrid system demand in Heidelberg and Berlin clusters where procurement unbundling separates hardware from service contracts.
- Research Institutes:Preclinical and translational visualization for device development and surgical technique innovation.
Academic Medical Centers retain technology leadership in premium system adoption; Ambulatory Surgery Centers expand most quickly as same-day surgery workflows displace traditional inpatient admission patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance timelines shape American market entry velocity while EU MDR technical documentation requirements extend certification cycles for European launches. Japan's PMDA enforces JIS standards for electromagnetic compatibility that filter out lower-tier Asian manufacturers.
United States
North American hospitals are expanding minimally invasive surgery suites faster than any other buyer segment. FDA 510(k) clearance timelines compress revenue recognition windows for novel visualization modalities. Boston and Cleveland academic medical centers anchor procurement clusters for 4K-fluorescence hybrid systems.
Germany
University hospitals in Heidelberg and Berlin anchor the largest procurement clusters for 4K-fluorescence hybrid systems in Europe. EU MDR's stricter clinical evidence requirements for reusable endoscopic devices force manufacturers to redesign sterilization protocols. Tuttlingen manufacturing clusters concentrate rigid endoscope optical craftsmanship for European procurement preferences.
Japan
Tokyo university hospitals adopt sub-3mm outer diameter scopes for transnasal gastroenterology procedures. METI enforces JIS standards for electromagnetic compatibility that filter lower-tier Asian manufacturers. Osaka and Nagoya academic medical centers concentrate 3D imaging demand for laparoscopic suturing applications.
India
Domestic manufacturing incentives under the PLI scheme attract component assembly investment targeting price-sensitive South Asian procurement budgets. CDSCO regulates medical device imports while BIS standards govern electromagnetic compatibility certification. Maharashtra and Karnataka host emerging assembly operations for visualization system components.
South Korea
CMOS wafer input volatility from semiconductor foundry capacity constraints in Taiwan and South Korea transmits pricing instability to camera head production schedules. MFDS regulates medical device safety while domestic manufacturers supply components to global visualization system vendors. Seoul anchors procurement demand for premium surgical microscopy in neurosurgery applications.
Global Surgical Visualization Products Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in surgical visualization systems. The upper tier combines captive semiconductor supply chains with German-certified sterilization infrastructure. Three archetypes dominate: diversified medical technology conglomerates with visualization divisions, German precision optics specialists with manufacturing heritage, and Asian electronics manufacturers leveraging component cost positions. Competitive moves concentrate on M&A for fluorescence technology capabilities and strategic partnerships for AI-powered image enhancement algorithms.
Within the diversified conglomerate tier, Olympus Corporation and Stryker Corporation exemplify integrated players with training infrastructure and R&D intensity across camera platforms. Karl Storz GmbH & Co. KG occupies a position among German precision optics specialists with manufacturing heritage that anchors European procurement preferences. These three represent distinct competitive vectors: education-locked institutional relationships, sustained premium positioning through platform development, and craftsmanship-based regional supply security.
| Leading Market Players |
|---|
| Olympus Corporation |
| Stryker Corporation |
| Medtronic |
| Karl Storz GmbH & Co. KG |
| Fujifilm Holdings Corporation |
| Smith & Nephew |
| Conmed Corporation |
| Richard Wolf GmbH |
| Arthrex, Inc. |
| Others |
Supply & Pricing Matrix
CMOS sensor displacement of legacy CCD architectures is redrawing procurement geography while compressing camera head margins across tiered equipment categories. Taiwan and South Korean foundry concentration now governs cost structures for visualization system vendors locked into semiconductor supply commitments.
Pricing Analysis
German university hospital clusters in Heidelberg and Berlin pay premiums exceeding standard European procurement levels for 4K-fluorescence hybrid systems with indocyanine green integration. Three-tier pricing structure across premium, standard, and economy levels separates fluorescence-enabled oncology platforms from basic HD infrastructure and entry-level 1080p replacements. Cost compression in mid-tier camera heads is intensifying because CMOS wafer input volatility transmits foundry pricing instability downstream. Ambulatory surgery centers in India exhibit highest price sensitivity due to PLI scheme-driven domestic assembly alternatives, while Japanese academic medical centers show lowest sensitivity given METI compliance requirements that filter lower-tier suppliers.
Supply Chain Analysis
Taiwan Strait logistics exposure concentrates single-source vulnerability for CMOS wafer inputs that feed camera head production schedules. Semiconductor fabrication rests on Taiwan, South Korea, and Japan for advanced node CMOS sensors, while German Tuttlingen clusters anchor rigid endoscope optical craftsmanship. Xenon lamp filaments and LED phosphor substrates draw from Chinese and Japanese specialty chemical suppliers. Tariff exposure on Chinese-manufactured optical components threatens margin stability for vendors without captive German sterilization infrastructure. Distribution runs through hospital GPO contracts in North America, direct tender processes in European university clusters, and government procurement channels in Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The surgical visualization market is recovering from EU MDR certification cycle compression that delayed European revenue recognition. Hospital capital budget restocking after sterilization protocol revalidation drives replacement demand for 4K-fluorescence hybrid platforms.
For Market Incumbents: Fortify captive semiconductor supply chains through backward integration into CMOS sensor sourcing or long-term foundry offtake agreements with Taiwan and South Korean partners. Lock in German sterilization infrastructure certification ahead of EU MDR technical documentation deadlines to exclude subscale competitors from reusable endoscope tenders. Prioritize fluorescence technology R&D to defend premium positioning against single-use endoscope substitution threats. For New Entrants and Emerging Players: FDA 510(k) pre-submission pathways offer fastest regulatory clearance for AI-powered image enhancement algorithms embedded in camera processors. Target ambulatory surgery center procurement in India where PLI scheme incentives create price-sensitive demand for compact visualization platforms. Pursue software-as-medical-device classification to bypass capital equipment margin compression through recurring algorithm licensing revenue. For Investors and Strategic Acquirers: EU MDR's stricter clinical evidence requirements reshape the acquisition landscape toward targets with validated sterilization documentation and German manufacturing heritage. Five-to-ten year viability favors visualization system vendors combining captive semiconductor supply chains with education-locked institutional relationships. Monitor FDA software-as-medical-device guidance evolution as inflection indicator for AI-powered image enhancement algorithm valuations.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation compliance unlocks Heidelberg and Berlin university hospital procurement clusters. |
| Hospital System Partnership | Olympus Institute of Training and Education model locks in long-term institutional relationships beyond equipment sales. |
| Software Companion Development | AI-powered image enhancement algorithms embedded in camera processors command premium positioning in oncology applications. |
| FDA Submission | 510(k) clearance timelines determine American market entry velocity for novel fluorescence and AR visualization modalities. |
| Reimbursement Strategy | Fluorescence-guided surgery protocol adoption in hepatobiliary resections drives hospital capital budget allocation priority. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and visualization system vendor sales executives. Secondary validation drew from FDA 510(k) clearance databases, EU MDR technical documentation filings, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up installed base analysis triangulated against top-down capital expenditure forecasts across the projection horizon.
Across the modeling period, volume and value outputs integrated product type segmentation by endoscope, surgical microscope, and camera head categories alongside technology tier stratification across HD, 4K, fluorescence, and augmented reality modalities. CAGRs derived from replacement cycle analysis for legacy 1080p systems and fluorescence protocol adoption curves in oncologic surgery. Industry-specific inputs included CMOS sensor foundry capacity utilization rates and EU MDR certification timeline distributions.
Decision-makers should treat outputs as directional under assumptions of continued hospital minimally invasive surgery suite expansion and stable semiconductor foundry pricing; material deviation in Taiwan Strait logistics or FDA software guidance would warrant model refresh. Practitioners should keep alternative scenarios live as EU MDR enforcement intensity and single-use endoscope substitution rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
IVF Time-Lapse Imaging Devices Market
Medical Devices
Human Enhancement Market
Medical Devices
North America Surgical Microscopes Market
Medical Devices
GCC Organ Preservation Market
Medical Devices
Patellar Implant Market
Medical Devices
Global Nasal Spray Market
Medical Devices
Oxygen Delivery Units Market
Medical Devices
Speech Generating Devices Market
Medical Devices
Wearable Defibrillators Market
Medical Devices
Sinus Implants Market
Medical Devices
Global Large Volume Wearable Injectors Market
Medical Devices
Dialysis Device and Concentrates Market
Medical Devices
Global Laparoscopic and Open Hernia Mesh Repair Surgery Market
Medical Devices
Global Hydrocephalus Shunts Market
Medical Devices
United States Implantable Medical Devices Market
Medical Devices
Global Pacemakers Market