
 Intraoral Scanners Market | 2026-2036
Intraoral Scanners Market Size, Share, and Industry Trends Forecast 2026-2036
Intraoral Scanners Market Intelligence
Dental distributor networks is reconfiguring how intraoral scanners reach chairside clinicians and laboratory technicians. Align Technology leverages direct-to-practice digital workflows to sustain brand loyalty among orthodontists. Dentsply Sirona anchors its position through integrated CAD/CAM ecosystems that lock in consumables revenue. 3Shape competes on open-architecture software that interoperates with third-party milling centers.
An intraoral scanner is a handheld or desktop electro-optical device that captures three-dimensional surface geometry of dentition and soft tissues using structured light, laser triangulation, or confocal microscopy, typically achieving accuracy of 10–50 microns for clinical acceptance in crown and bridge fabrication. Its primary purpose is to replace physical elastomeric impressions with digital files compatible with restorative design software and additive manufacturing. Handheld scanners dominate unit volume due to ergonomic portability for operatory use, while desktop scanners retain margin concentration in dental laboratories processing high-throughput restorative cases. Optical scanning technology leads installed base, though structured light scanning captures fastest expansion in orthodontics applications requiring full-arch capture speed.
FDA 510(k) clearance and CE marking under EU MDR govern commercialization pathways, with FDA scrutiny intensifying for software-as-medical-device updates that alter diagnostic algorithms. ISO 13485 quality management and IEC 60601 electrical safety standards further constrain design validation cycles for manufacturers targeting multiple jurisdictions. Stakeholders must monitor evolving reimbursement codes for digital impressions across public and private dental payers, as coverage determination will shape clinician upgrade cycles and laboratory outsourcing decisions.
Market Dynamics
Digital workflow integration is compressing the traditional boundary between chairside capture and laboratory production, forcing manufacturers to choose between closed ecosystems and interoperable platforms. Scanner vendors now compete on software architecture rather than hardware specifications alone.
Growth Catalysts
- FDA 510(k) pathway streamlining:Expedited clearance for iterative software updates accelerates product lifecycle velocity and reduces validation overhead for manufacturers targeting the United States.
- Orthodontic aligner fabrication:Clear aligner therapy requires full-arch digital models, pulling scanner adoption into general dentistry practices previously served by physical impressions.
- Laser triangulation advances:Improved emitter-detector configurations reduce capture time per arch from minutes to seconds, addressing throughput bottlenecks in high-volume clinics.
Market Restraints
- Consumables lock-in economics:Closed-architecture systems tether users to proprietary milling materials and design software, raising lifetime cost uncertainty for purchasers.
- Optical component supply concentration:Precision CMOS sensors and specialized lens assemblies concentrate among East Asian component suppliers, creating exposure to trade policy volatility.
- EU MDR technical documentation burden:Expanded clinical evidence requirements for Class IIa medical devices extend CE marking timelines and inflate regulatory compliance costs.
Strategic Opportunities
- Teledentistry-enabled remote consultations:Cloud-linked scanners allow asynchronous specialist review, opening rural and underserved markets to prosthodontic and orthodontic expertise.
- South Korean aesthetic dentistry expansion:High private dental expenditure and cultural emphasis on cosmetic procedures create concentrated demand for premium scanning workflows.
- AI-assisted margin detection convergence:Machine learning algorithms layered onto scan data promise automated preparation assessment, reducing technician intervention time.
Industry Challenges
- Cross-functional digital dentistry training:Clinicians and laboratory technicians require simultaneous upskilling on CAD software, milling protocols, and scan validation to realize productivity gains.
- Legacy practice management system integration:Proprietary scanner file formats conflict with established dental record architectures, forcing middleware investments or workflow fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intraoral Scanners Market |
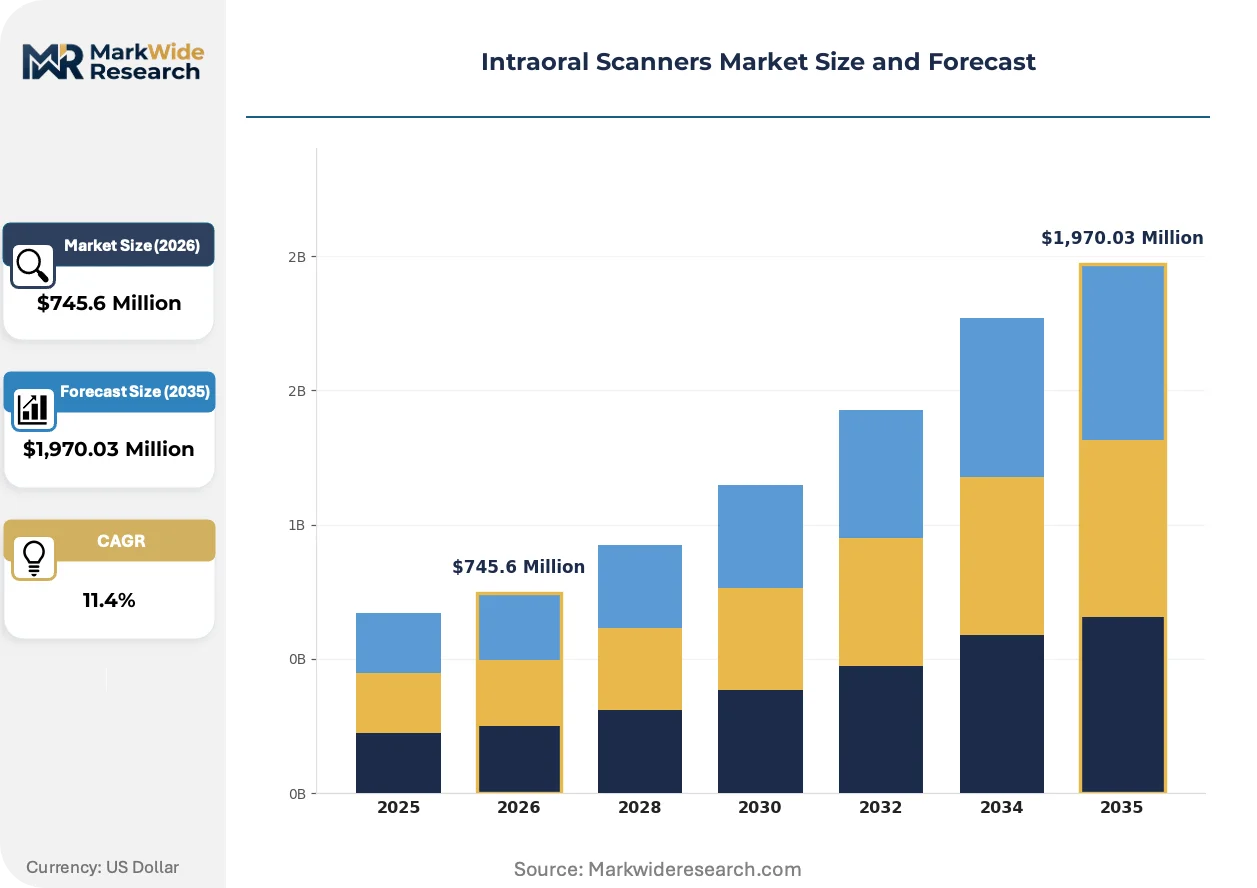
| Market Size in 2026 | $745.6 Million |
| Market Size in 2035 | $1,970.03 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Scanners, Desktop Scanners, 3D Scanners, Pen-Style Scanners End User: Dentists, Dental Laboratories, Orthodontists, Oral Surgeons Technology: Optical Scanning, Laser Scanning, Structured Light Scanning, Triangulation Application: Restorative Dentistry, Orthodontics, Implants, Periodontics |
| Companies Covered | Align Technology, Dentsply Sirona, 3Shape, Medit, Planmeca Oy, Carestream Dental, Dental Wings, Straumann Group, Shining 3D Tech Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intraoral Scanners Market Strategic Shifts & Innovations
Convergence between optical hardware and computational imaging is redefining performance benchmarks. Vendors now differentiate through real-time processing capabilities rather than raw scanning speed, shifting competitive emphasis toward software-defined workflows.
Structured light projection is hybridizing with confocal microscopy in next-generation handheld units. High-volume prosthodontic clinics in Germany are piloting these dual-modality devices for subgingival margin capture. The technology is hybridizing previously separate use cases—restorative and periodontal—into single hardware investments, compressing addressable market segmentation.
CE marking under EU MDR is mandating post-market clinical follow-up for software-as-medical-device updates. Manufacturers must now maintain surveillance registries tracking diagnostic algorithm modifications across installed bases. Dental laboratories in France and Italy face the steepest compliance adaptation, as many lack quality management infrastructure for ongoing performance monitoring.
Subscription-based access models are displacing capital purchase arrangements among mid-sized dental groups. Third-party financing entities now bundle scanner hardware with design software licenses and maintenance, transferring obsolescence risk from practice to vendor. This shift concentrates most visibly in United States multi-location dental service organizations seeking predictable technology expenditure profiles.
Intraoral Scanners Market Segmentation
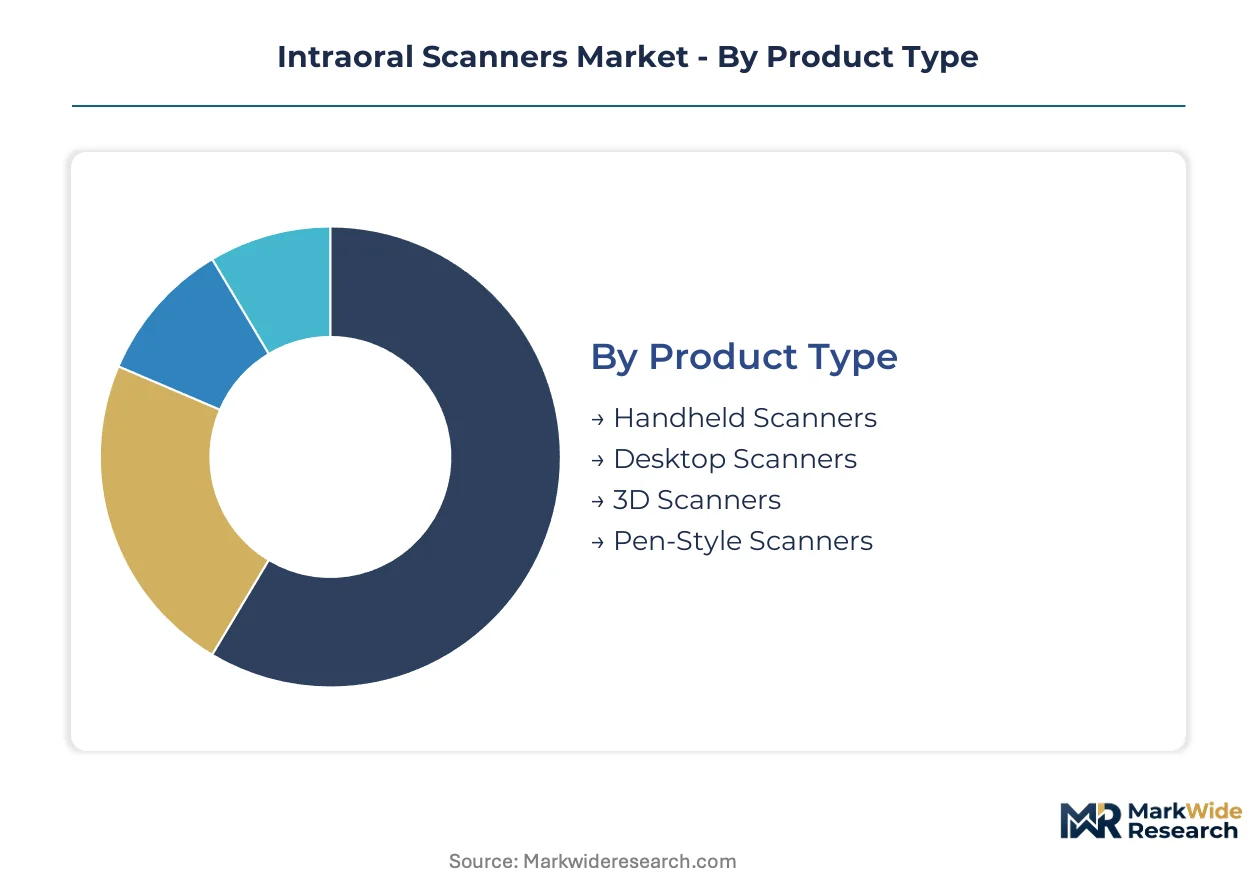
Intraoral scanner purchasing decisions hinge on workflow integration requirements, clinical throughput demands, and regulatory compliance burdens. Each segmentation dimension reveals distinct margin profiles and vendor competitive strategies that shape procurement patterns across dental settings.
Product Type:
Mature handheld form factors coexist with emerging desktop configurations as laboratories digitize high-volume restorative workflows.
- Handheld Scanners:Ergonomic pistol-grip or wand-shaped devices employ active triangulation or confocal microscopy for chairside capture, achieving clinical accuracy within 20 microns. General dentistry practices in the United States and Germany concentrate procurement here, driven by single-visit crown workflows and patient comfort demands. These units handle the majority of throughput; 3D Scanners are the fastest mover on share.
- Desktop Scanners:Fixed-position systems process stone models or impression scans for laboratory-based restorative design, prioritizing batch throughput over operatory portability. Dental laboratories in South Korea and Italy anchor demand, reflecting outsourcing trends from smaller practices.
- 3D Scanners:Hybrid devices merge intraoral capture with extraoral model scanning capabilities, serving multi-site dental service organizations seeking hardware consolidation.
- Pen-Style Scanners:Compact cylindrical form factors target pediatric and orthodontic applications requiring maneuverability in limited oral volumes.
Handheld Scanners handle the majority of throughput; 3D Scanners are the fastest mover on share.
End User:
Customer type stratification follows the division between chairside clinical capture and laboratory-based production workflows.
- Dentists:General practitioners and prosthodontists in private practice settings drive unit volume, with purchasing decisions tied to CAD/CAM milling system compatibility and software subscription economics.
- Dental Laboratories:Centralized production facilities in Germany and the United States concentrate demand for high-throughput desktop units, with ISO 13485 quality management infrastructure enabling CE marking compliance.
- Orthodontists:Clear aligner therapy expansion pulls scanner adoption into specialty practices previously reliant on physical impressions, with full-arch capture speed determining vendor selection.
- Oral Surgeons:Implant planning workflows require subgingival margin accuracy, favoring structured light configurations with enhanced depth-of-field performance.
Dentists command the largest installed base; Orthodontists are expanding most quickly as aligner therapy penetrates general dentistry referral networks.
Technology:
Optical maturity contrasts with structured light acceleration as computational imaging reduces hardware cost barriers.
- Optical Scanning:Confocal microscopy and white-light interferometry dominate current installed bases, delivering proven accuracy for crown-and-bridge applications across European and North American markets.
- Laser Scanning:Triangulation-based systems using red or blue wavelength emitters capture fastest expansion in high-volume orthodontic practices, with reduced capture time per arch improving clinic throughput.
- Structured Light Scanning:Pattern projection techniques enable full-arch capture without powder application, gaining traction in pediatric and geriatric populations with reduced cooperation tolerance.
- Triangulation:Active stereo vision configurations persist in entry-level devices, with Asian manufacturing clusters driving cost compression for emerging market penetration.
Optical Scanning retains the deepest installed base; Structured Light Scanning is climbing the fastest on new unit shipments.
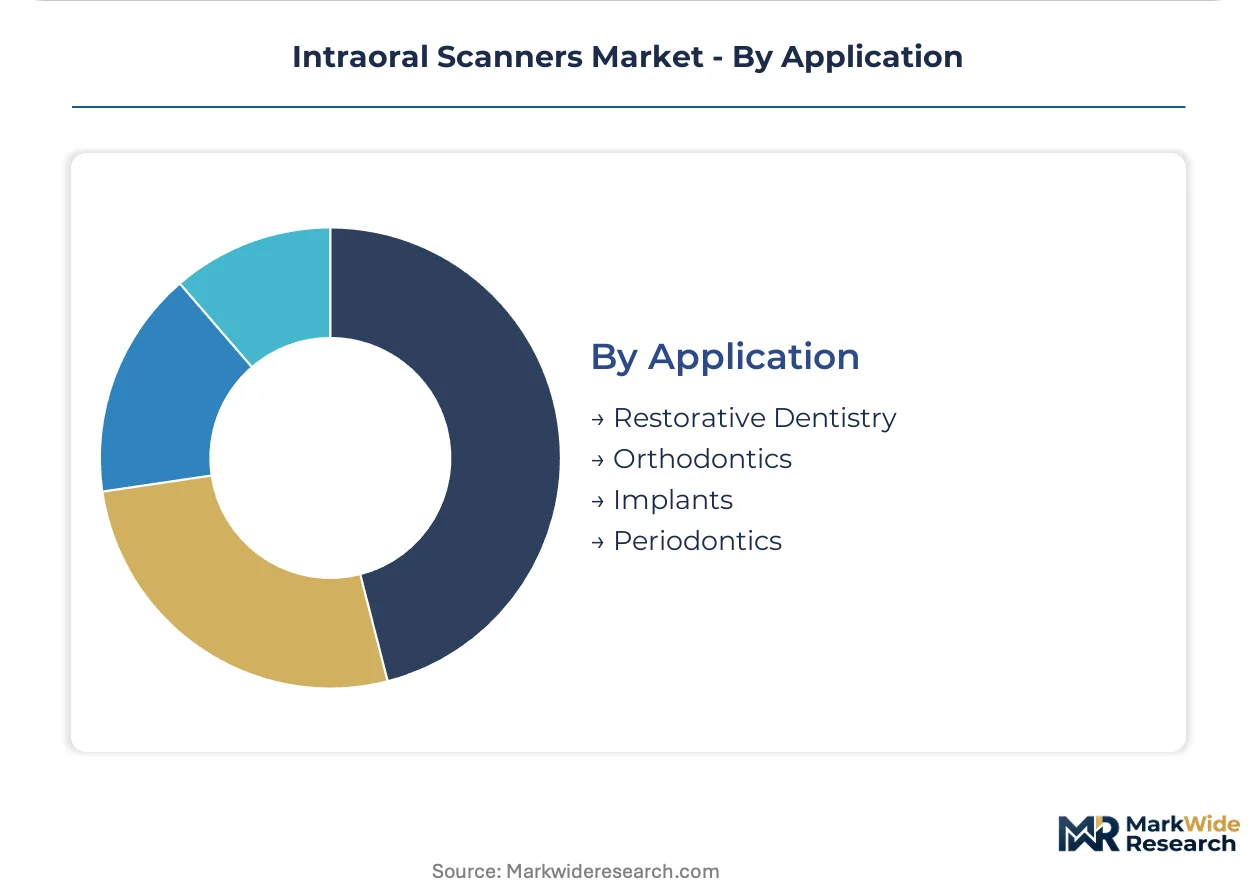
Application:
Restorative volume anchors revenue while orthodontic workflows reshape growth trajectories through aligner ecosystem integration.
- Restorative Dentistry:Single-unit crowns and fixed partial dentures constitute the historical core application, with scanner accuracy thresholds defined by marginal fit requirements for permanent cementation.
- Orthodontics:Clear aligner fabrication demands full-arch digital models with gingival tissue capture, pulling scanner specifications toward faster scan times and automated occlusion analysis.
- Implants:Surgical guide fabrication requires integration with CBCT datasets, favoring scanners with open STL export and third-party implant planning software compatibility.
- Periodontics:Emerging applications in soft tissue monitoring and regenerative outcome documentation drive pilot adoption in academic medical centers.
Restorative Dentistry generates the dominant procedure volume; Orthodontics is gaining share fastest as aligner therapy expands beyond traditional specialty boundaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium scanner pricing in South Korea runs 15–20% above German equivalents, reflecting concentrated private dental expenditure and limited reimbursement pressure. This asymmetry channels vendor R&D investment toward Seoul-based aesthetic dentistry clusters while compressing margins in European markets with tighter public payer oversight.
United States
Dental service organizations in Texas and Florida drive multi-unit scanner procurement through subscription financing models. FDA 510(k) clearance timelines for software-as-medical-device updates compress product refresh cycles. The Pacific Northwest hosts pilot deployments of teledentistry-linked scanners for rural specialist access.
Germany
High-volume prosthodontic clinics in Bavaria and North Rhine-Westphalia anchor demand for dual-modality structured light devices. CE marking under EU MDR mandates post-market surveillance registries that laboratories in Stuttgart industrial zones struggle to implement. Baden-Württemberg dental technology parks concentrate milling center outsourcing relationships.
South Korea
Seoul Capital Area aesthetic dentistry chains specify premium scanning workflows for cosmetic veneer and aligner cases. MFDS regulatory pathways for AI-assisted margin detection software accelerate faster than FDA equivalents. Busan-Ulsan manufacturing clusters supply precision optical components to domestic scanner assemblers.
China
Private dental chains in Shanghai and Shenzhen deploy entry-level triangulation scanners for crown-and-bridge volume workflows. NMPA Class II medical device registration requirements intensify for software updates altering diagnostic algorithms. Yangtze River Delta electronics manufacturing bases produce CMOS sensors and lens assemblies for regional vendors.
Japan
Tokyo and Osaka orthodontic practices adopt structured light systems for pediatric full-arch capture without powder application. PMDA quality management audits extend validation timelines for foreign manufacturers. METI dental technology standardization initiatives promote interoperability between scanner file formats and legacy practice management systems.
Intraoral Scanners Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying precision optics and embedded processing modules. The vendor base stratifies into three tiers: closed-ecosystem incumbents with captive consumables revenue, open-architecture challengers interoperating with third-party milling centers, and Asian cost-optimized entrants penetrating emerging markets. Consolidation pressure concentrates among mid-scale European manufacturers lacking software differentiation. Dominant competitive moves include strategic partnerships between scanner vendors and aligner fabricators, plus geographic expansion through distributor acquisition in Southeast Asian markets.
Among United States-based platform integrators, Align Technology exemplifies the closed-ecosystem archetype through direct-to-practice digital workflow penetration. Dentsply Sirona anchors the integrated CAD/CAM tier with German manufacturing heritage and consumables lock-in economics. Copenhagen-based 3Shape occupies the open-architecture position, interoperating with third-party design software and milling center networks. Medit represents the Korean challenger model, leveraging East Asian component supply chains for cost-positioned handheld units targeting price-sensitive dental groups.
| Leading Market Players |
|---|
| Align Technology |
| Dentsply Sirona |
| 3Shape |
| Medit |
| Planmeca Oy |
| Carestream Dental |
| Dental Wings |
| Straumann Group |
| Shining 3D Tech Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Incheon-to-Rotterdam container freight corridors transmit East Asian component cost volatility into European scanner pricing, amplifying the spread between premium configured-to-order systems and standard handheld units while compressing margins for distributors caught between concentrated CMOS sensor supply and price-sensitive dental service organizations.
Pricing Analysis
The customization-premium spread separates standard handheld units from laboratory-grade desktop configurations bundled with design software licenses. Subscription-based SaaS-tiered pricing dominates United States multi-location dental groups, while per-unit transactional sales persist in European private practices. Price differentiation hinges on ISO 13485 certification tier and after-sales service bundling. Pricing pressure stems from Asian cost-optimized entrants flooding entry-level triangulation segments. Dental laboratories exhibit highest price sensitivity due to batch-processing economics; aesthetic dentistry chains in Seoul show lowest sensitivity.
Supply Chain Analysis
Extended payment terms from Yangtze River Delta CMOS foundries and supply-chain finance facilities anchored in Busan-Ulsan electronics clusters shape working capital requirements for scanner assemblers. Precision lens assemblies concentrate in South Korea, Japan, and Germany. Manufacturing draws from specialized CMOS sensors, optical-grade polymers, and embedded processing modules. Single-source vulnerability around East Asian emitter-detector configurations creates tariff exposure. Distribution runs through dental distributor networks reconfiguring toward direct-to-practice digital workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Intraoral scanner penetration sits at early-cycle expansion, with clear aligner therapy pulling hardware adoption into general dentistry practices previously served by physical impressions alone.
For Market Incumbents: Insulate consumables revenue streams by deepening software lock-in through AI-assisted margin detection modules. Defend against open-architecture challengers by acquiring third-party design software specialists. Prioritize CE marking compliance investment to maintain European laboratory relationships amid EU MDR surveillance registry requirements.
For New Entrants and Emerging Players: Build out teledentistry-enabled scanner deployments targeting rural United States markets underserved by prosthodontic specialists. Penetrate South Korean aesthetic dentistry chains through premium workflow bundling. Pursue distributor acquisition in Southeast Asian expansion corridors as the primary go-to-market angle.
For Investors and Strategic Acquirers: Mid-scale European manufacturers lacking software differentiation represent prime acquisition targets for platform consolidation plays. Long-term viability favors vendors with captive cloud infrastructure for asynchronous specialist consultation. Watch FDA software-as-medical-device clearance velocity as the inflection indicator for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-as-Medical-Device FDA Submission | Expedited 510(k) pathways compress product refresh cycles for iterative algorithm updates. |
| CE Marking Pathway Under EU MDR | Post-market surveillance registries force quality management investment among French and Italian laboratories. |
| Hospital System Partnership | Academic medical centers pilot periodontal applications in soft tissue monitoring workflows. |
| Software Companion Development | AI-assisted margin detection modules reduce technician intervention time in crown fabrication. |
| Reimbursement Strategy | Coverage determination for digital impressions shapes clinician upgrade cycles across public and private payers. |
Research Approach
A spread of perspectives from prosthodontic clinic directors, dental laboratory quality managers, biomedical engineers at scanner manufacturers, and GPO contracts managers converged on the working assumptions. Primary interviews combined with secondary validation against FDA 510(k) filings, MFDS registration databases, hospital procurement records, and customs trade data. Bottom-up unit shipment estimates triangulated against top-down expenditure flows across the analysis window.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product form factor, end-user clinical setting, optical technology type, and application workflow. CAGRs derived from fitted growth curves applied to validated base-year estimates. Industry-specific forecast inputs incorporated aligner therapy penetration rates and regulatory clearance timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Asian cost-optimized entrants or rapid FDA pathway acceleration would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pet Mobility Aids Market
Medical Devices
UAE Respiratory Devices Market
Medical Devices
Global Medical Devices Market
Medical Devices
Global Electrophysiology Devices Market
Medical Devices
United States Insulin Pumps Market
Medical Devices
Saliva Collection Devices Market
Medical Devices
North America Advanced Drug Delivery Systems Market
Medical Devices
Global Neurovascular Guidewires Market
Medical Devices
Wearable Artificial Kidney Market
Medical Devices
Acne Treatment Devices Market
Medical Devices
Neurotechnology Market
Medical Devices
Ultrasonic Skin Care Devices Market
Medical Devices
Veterinary Respiratory Ventilators Market
Medical Devices
Asia-Pacific Ultrasound Probe Disinfection Market
Medical Devices
Wearable Insulin Pump Market
Medical Devices
Leadless Pacemakers Market