
 Global Medical Laser Systems Market | 2026-2036
Global Medical Laser Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Laser Systems Market Outlook
The capital-intensity divergence between integrated manufacturers and assembly-dependent competitors is unwinding competitive hierarchies across the sector. Boston Scientific Corporation leverages captive semiconductor fabrication to control diode laser supply chains for surgical applications. Candela Corporation sustains premium positioning through in-house resonator design and proprietary cooling architectures. Koninklijke Philips N.V. anchors its ophthalmology franchise via integrated diagnostic-to-treatment platforms spanning femtosecond and excimer modalities.
Medical laser systems generate coherent, monochromatic light through stimulated emission in solid-state crystals, gas discharge tubes, or doped fiber gain media, with output parameters precisely tuned to tissue absorption spectra for incision, coagulation, or photothermal ablation. Solid-state lasers dominate ophthalmology capital equipment budgets due to reliability and wavelength stability, while fiber lasers capture share in minimally invasive surgery through flexible delivery and thermal precision. Diode-pumped platforms now lead technology roadmaps across aesthetic and surgical segments, displacing lamp-pumped architectures with superior wall-plug efficiency and maintenance intervals.
FDA 510(k) premarket notifications govern Class II laser device clearance in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for high-risk surgical lasers sold in Europe. ISO 13485 quality management certification and IEC 60825 laser safety standards shape manufacturing protocols and market access prerequisites across all major jurisdictions. Stakeholders must monitor reimbursement coding dynamics for laser-assisted procedures and evolving MDR technical documentation demands to calibrate portfolio investments and geographic prioritization.
Market Dynamics
The transition from lamp-pumped to diode-pumped architectures is redistributing manufacturing advantage toward semiconductor-literate suppliers and away from legacy optical assembly houses.
Growth Catalysts
- EU MDR clinical evidence pathways:Stricter documentation requirements for Class III surgical lasers are consolidating competitive field toward well-capitalized incumbents with established quality management systems.
- Dermatology clinic expansion:Aesthetic treatment portfolios now standardize fractional CO₂ and picosecond platforms as core revenue generators across United States, Germany, and Japan.
- Fiber laser thermal precision:Flexible delivery systems enable single-port laparoscopic procedures previously requiring open surgical access.
Market Restraints
- III-V semiconductor supply concentration:Gallium arsenide and indium phosphide substrate fabrication clusters in East Asia create diode laser sourcing vulnerability for Western OEMs.
- Technical wavelength limitations:Mid-infrared surgical applications remain underserved due to atmospheric absorption and fiber transmission losses above 3 μm.
- FDA 510(k) predicate device dependence:Substantial equivalence requirements constrain novel therapeutic indications without predicate laser systems.
Strategic Opportunities
- India's underserved ophthalmology infrastructure:Cataract surgery backlogs in tier-2 and tier-3 cities create installation base for portable femtosecond platforms.
- Photobiomodulation therapy expansion:Low-level laser applications in pain management and tissue repair extend addressable market beyond traditional surgical and aesthetic segments.
- Japan METI carbon neutrality incentives:Energy-efficient solid-state replacements for gas discharge lasers qualify for green technology procurement preferences.
Industry Challenges
- Laser safety officer certification scarcity:IEC 60825 compliance training programs fail to match installation growth in outpatient surgical centers.
- Multi-wavelength platform integration complexity:Combining diode, solid-state, and fiber sources within unified control architectures strains embedded software validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Laser Systems Market |
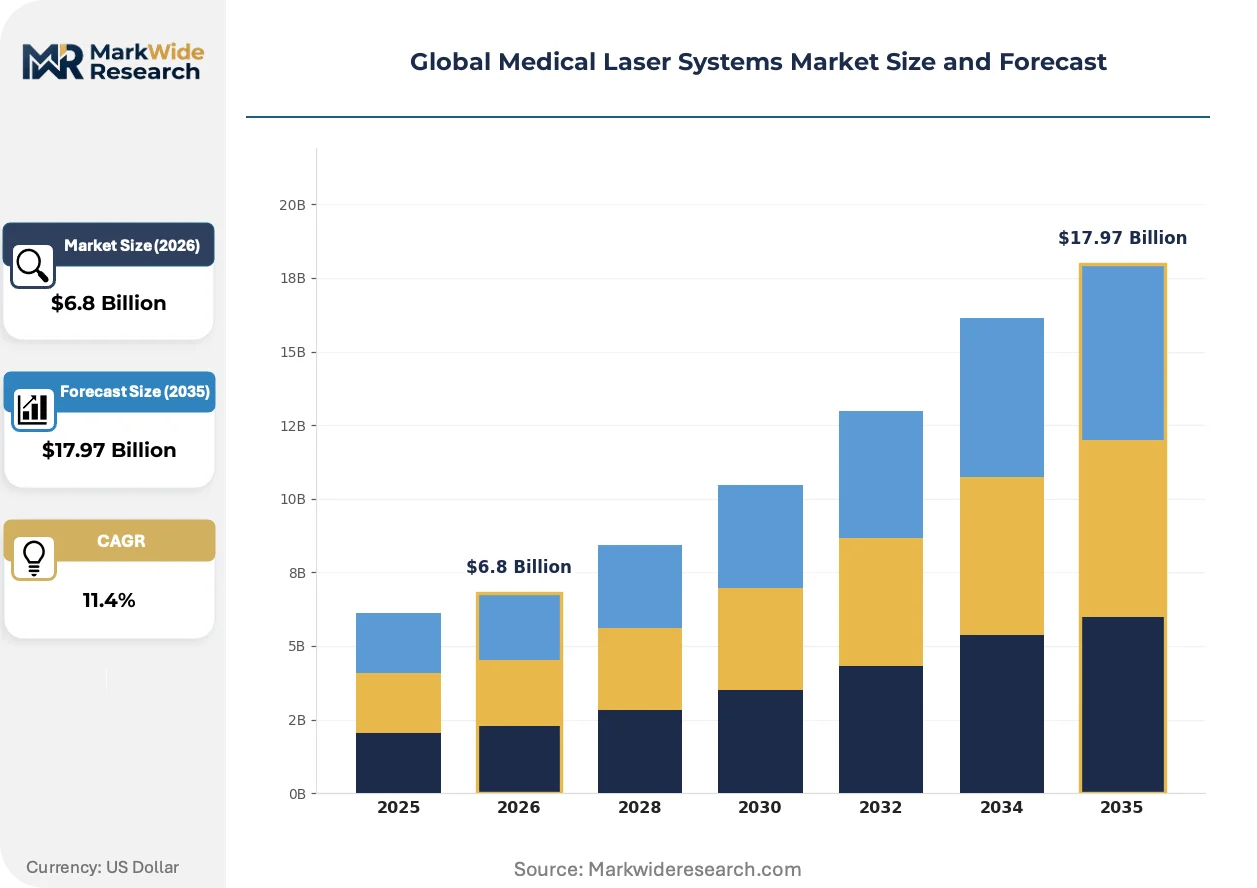
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid-State Lasers, Gas Lasers, Fiber Lasers, Dye Lasers Application: Ophthalmology, Dermatology, Surgery, Aesthetic Procedures End User: Hospitals, Clinics, Research Laboratories, Ambulatory Surgical Centers Technology: Diode Laser, Q-Switched Laser, Pulsed Laser, Continuous Wave Laser |
| Companies Covered | Boston Scientific Corporation, Candela Corporation, Koninklijke Philips N.V., BIOLASE MG LLC., IRIDEX Corporation, El.En. S.p.A., Alcon, Carl Zeiss Meditec AG, Cutera, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Laser Systems Market Strategic Shifts
Platform convergence between diagnostic imaging and therapeutic delivery is collapsing the traditional separation between capital equipment categories in ophthalmology and dermatology.
Diode-pumped solid-state lasers are decomposing the lamp-pumped installed base across aesthetic and surgical segments. Dermatology clinics in Germany and Japan now specify diode architectures as default procurement for hair removal and vascular lesion treatment. The technology is decomposing maintenance revenue streams previously captured by flashlamp replacement schedules.
MDR technical documentation requirements are extending clinical evidence obligations to medium-risk surgical lasers previously cleared through self-certification. European notified bodies now demand prospective clinical data for ablative resurfacing platforms. Aesthetic device manufacturers with limited European regulatory experience face portfolio rationalization or partnership requirements.
After-sales service unbundling is fragmenting historical OEM-captive revenue in United States hospital systems. Third-party laser service organizations now hold ISO 13485 certification for resonator alignment and fiber delivery replacement. Independent service contracts now capture 15-20% of maintenance spend in high-volume ophthalmology practices.
Global Medical Laser Systems Market Segmentation
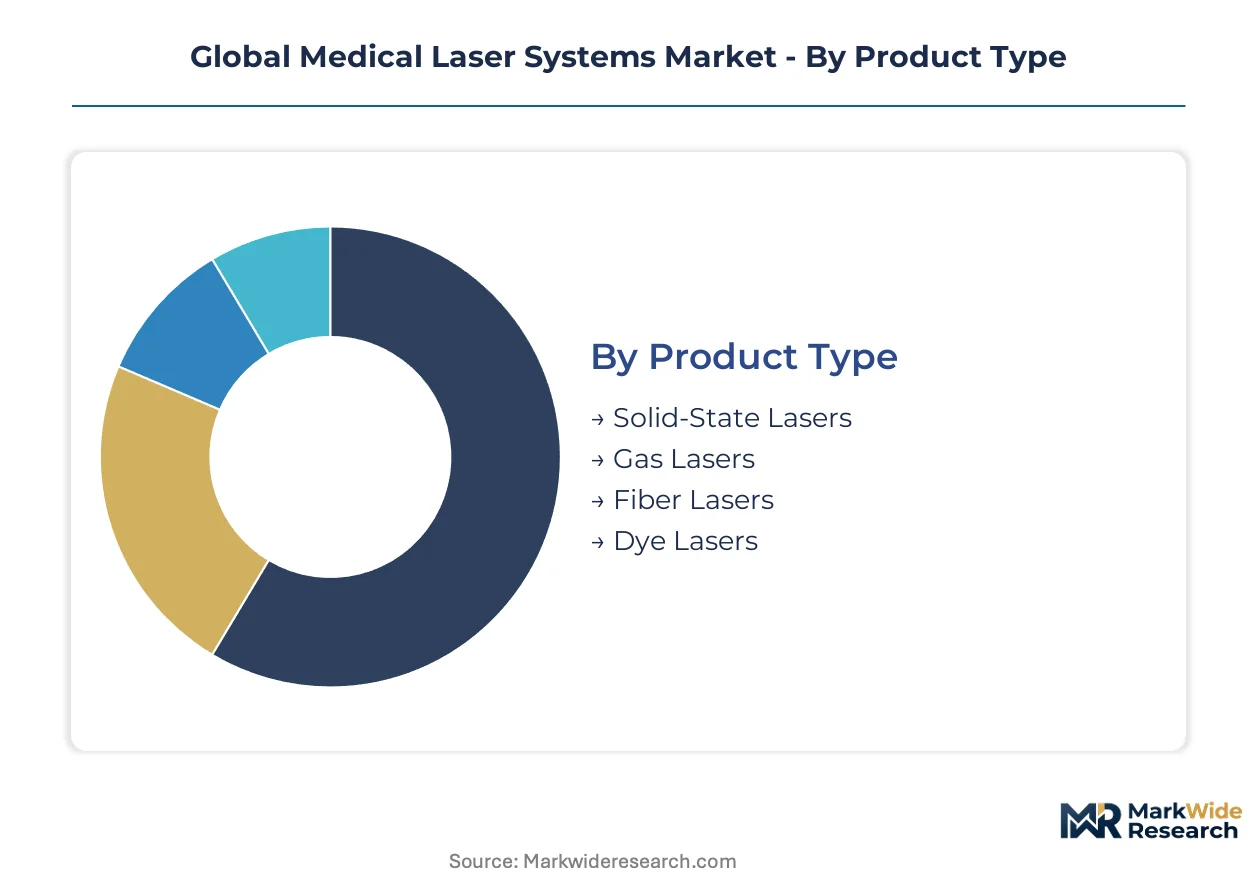
Medical laser procurement decisions split across four distinct dimensions: underlying gain medium, clinical indication, facility type, and temporal emission profile. Each axis carries different substitution vulnerabilities and margin structures that reshape competitive positioning across the sector.
Product Type:
Substitution pressure from diode-pumped architectures weighs most heavily on legacy lamp-pumped platforms, with efficiency differentials now compelling facility-level equipment refresh cycles.
- Solid-State Lasers:Nd:YAG and Er:YAG crystals pumped by diode arrays deliver wavelength stability critical for ophthalmic capsulotomy and dermatological resurfacing. Demand concentrates in German and Japanese university hospitals where maintenance contracts favor reliability over acquisition cost.
- Gas Lasers:CO₂ discharge tubes and excimer gas mixtures still dominate deep tissue ablation and corneal sculpting despite wall-plug efficiency penalties. United States ambulatory surgery centers retain installed base for tissue interaction predictability in open surgical access.
- Fiber Lasers:Ytterbium-doped silica gain media enable flexible beam delivery through endoscopic channels for single-port laparoscopy.
- Dye Lasers:Organic rhodamine and coumarin solutions tune across visible spectra for vascular lesion treatment in pediatric dermatology.
Solid-state lasers anchor the volume base while fiber lasers gain share at the steepest rate.
Application:
Reimbursement coding density varies sharply across clinical domains, concentrating vendor R&D toward procedure categories with established CPT or DRG coverage.
- Ophthalmology:Femtosecond platforms for cataract fragmentation and excimer systems for refractive correction command capital equipment budgets through diagnostic-therapeutic integration. Japanese clinics prioritize compact footprints for high-throughput screening programs.
- Dermatology:Fractional CO₂ and picosecond Nd:YAG devices drive aesthetic clinic revenue through repeat treatment protocols. German private dermatology groups specify multi-wavelength platforms to consolidate vendor relationships.
- Surgery:Holmium and thulium fiber lasers enable enucleation and lithotripsy through flexible ureteroscope delivery.
- Aesthetic Procedures:Hair removal and tattoo clearance applications standardize 755 nm alexandrite and 1064 nm Nd:YAG specifications across United States medspa chains.
Ophthalmology anchors the volume base while dermatology gains share at the steepest rate.
End User:
Capital deployment cycles diverge sharply between integrated health systems and independent outpatient facilities, fragmenting pricing power across customer tiers.
- Hospitals:Centralized procurement committees negotiate multi-year service bundles covering solid-state surgical suites and ophthalmology capital equipment. United States IDN consolidation shifts volume toward standardized diode-pumped platforms.
- Clinics:Dermatology and ophthalmology specialty practices prioritize lease-to-own structures and third-party service contracts over OEM captive maintenance. German clinic chains now specify ISO 13485-certified independent service providers.
- Research Laboratories:Academic medical centers acquire tunable dye and optical parametric oscillator systems for preclinical tissue interaction studies.
- Ambulatory Surgical Centers:Medicare reimbursement incentives drive laser lithotripsy and ophthalmic procedure migration to outpatient settings.
Hospitals anchor the volume base while ambulatory surgical centers gain share at the steepest rate.
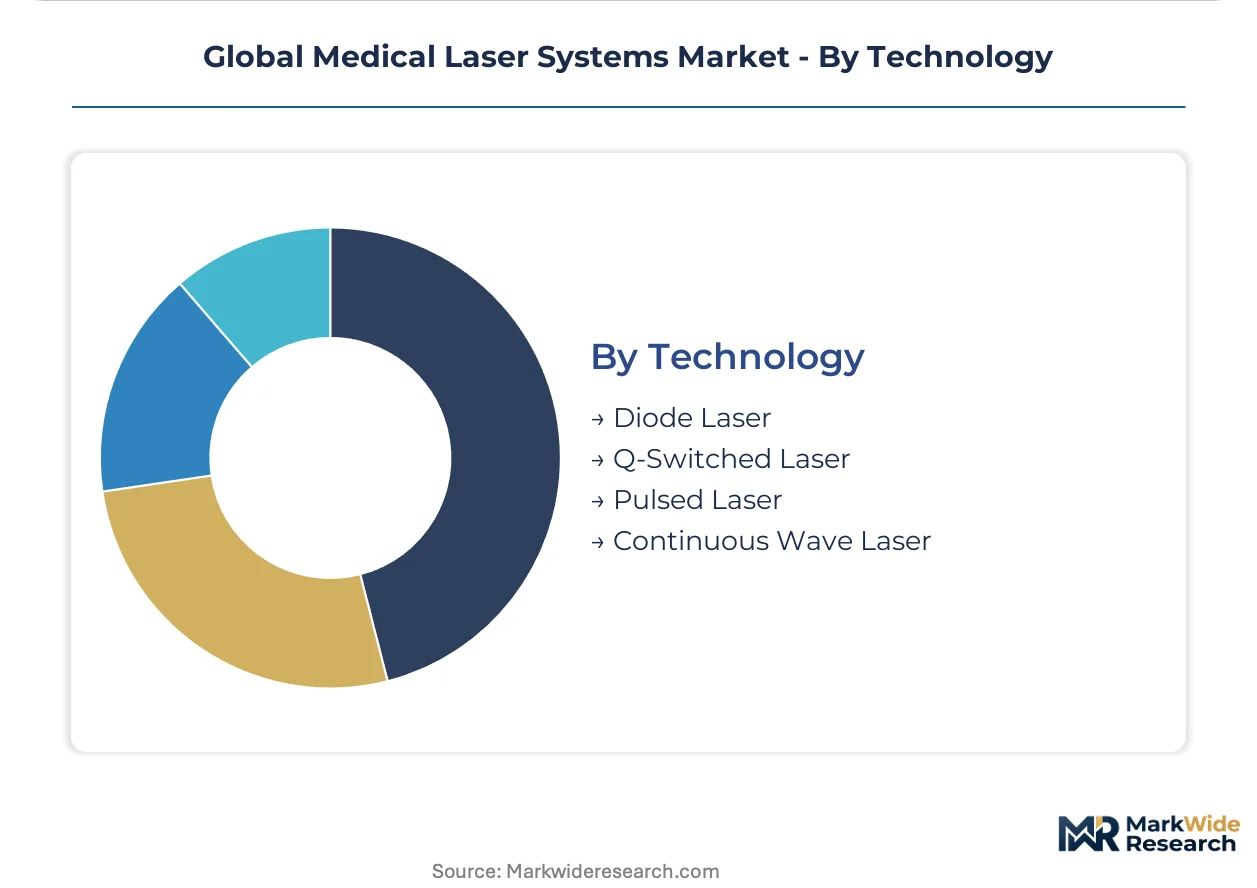
Technology:
Thermal damage zone control and tissue interaction specificity separate clinical adoption curves across emission modalities.
- Diode Laser:Gallium arsenide and indium phosphide edge-emitting arrays deliver 800-980 nm output for hair follicle photothermolysis and soft tissue cutting. Japanese manufacturers specify these for low-power photobiomodulation accessories.
- Q-Switched Laser:Nanosecond pulse compression via electro-optic modulators enables selective photothermolysis of tattoo pigments and melanosomes without collateral thermal injury. United States dermatology clinics specify these for picosecond platform retrofits.
- Pulsed Laser:Millisecond-duration emission from flashlamp-pumped or diode-pumped solid-state sources controls thermal diffusion for vascular lesion coagulation.
- Continuous Wave Laser:Uninterrupted emission from CO₂ or Nd:YAG sources enables rapid incision with simultaneous hemostasis in open surgical fields.
Continuous wave lasers anchor the volume base while Q-switched lasers gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate low price elasticity, prioritizing reliability and integrated service contracts, while United States ambulatory surgery centers and Indian tier-2 cities exhibit high sensitivity to acquisition cost and third-party maintenance alternatives.
United States
Medicare reimbursement migration drives laser lithotripsy and ophthalmic procedures toward outpatient settings, compressing capital deployment cycles. FDA 510(k) premarket notifications govern Class II laser device clearance, accelerating commercialization timelines relative to European pathways. Boston and Minneapolis medical device clusters concentrate surgical laser R&D and semiconductor-literate supplier networks.
Germany
University hospitals in Baden-Württemberg and Bavaria specify solid-state surgical suites with multi-year service bundles over lowest acquisition cost. EU MDR technical documentation requirements now demand prospective clinical data for ablative resurfacing platforms previously cleared through self-certification. Berlin-Brandenburg and Munich host notified bodies and quality management consultancies serving pan-European compliance.
Japan
Compact femtosecond platforms for high-throughput ophthalmic screening programs dominate procurement specifications in Tokyo and Osaka metropolitan areas. METI carbon neutrality incentives qualify energy-efficient solid-state replacements for gas discharge lasers under green technology procurement preferences. Nagoya precision optics manufacturers supply resonator components to domestic and export OEMs.
India
Cataract surgery backlogs in tier-2 and tier-3 cities create installation demand for portable femtosecond platforms with lease-to-own structures. CDSCO medical device regulations impose import licensing and quality standards that favor established multinational suppliers over unorganized local assemblers. Hyderabad and Bengaluru medical technology clusters concentrate diagnostic imaging integration capabilities.
China
Domestic diode laser fabrication capacity in Shenzhen and Shanghai reduces import dependency for aesthetic and surgical system manufacturers. NMPA medical device registration pathways now align with international standards, accelerating market access for multinational OEMs with established quality systems. Wuhan and Xi'an university hospitals drive adoption of fiber laser platforms for minimally invasive urological procedures.
Global Medical Laser Systems Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with semiconductor fabrication control and captive resonator design separating premium positioning from assembly-dependent competitors. The upper tier commands pricing power through in-house supply chain management and proprietary cooling architectures. Three archetypes dominate: integrated device manufacturers with captive semiconductor fabrication, optical specialists with resonator design expertise, and diversified health technology conglomerates with diagnostic-to-treatment platform integration. Competitive moves concentrate on backward integration into III-V semiconductor supply and strategic partnerships for MDR compliance infrastructure.
Among United States-based diversified manufacturers, Boston Scientific Corporation exemplifies the integrated device archetype through semiconductor-literate supply chain management. Dutch health technology conglomerate Koninklijke Philips N.V. occupies a position representing diagnostic-therapeutic platform convergence. Italian laser specialist El.En. S.p.A. sits within the optical fabrication tier, anchoring European resonator design capabilities. These three represent distinct strategic postures: captive supply control, integrated platform breadth, and specialized optical engineering.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Candela Corporation |
| Koninklijke Philips N.V. |
| BIOLASE MG LLC. |
| IRIDEX Corporation |
| El.En. S.p.A. |
| Alcon |
| Carl Zeiss Meditec AG |
| Cutera |
| Others |
Value Chain & Pricing Dynamics
Long-term service bundling contracts lock in diode laser supply access for United States hospital systems while freezing maintenance pricing visibility across multi-year ophthalmology equipment deployments. These arrangements tie OEMs to III-V semiconductor foundry capacity reservations in East Asia, embedding gallium arsenide sourcing costs into capital equipment margins.
Pricing Analysis
After-sales service contracts now drive lifetime value capture, with resonator alignment and fiber delivery replacement generating recurring revenue streams independent of initial system sales. Pricing stratifies across premium, standard, and economy tiers based on ISO 13485 certification grade and after-sales bundling intensity. Cost compression in the independent service tier is intensifying because third-party laser service organizations now hold quality management certification previously reserved for OEMs. Ambulatory surgical centers in the United States exhibit highest price sensitivity, while German university hospitals prioritize reliability over acquisition cost.
Supply Chain Analysis
Container availability constraints on the Shanghai–Los Angeles trade lane elevate inbound logistics costs for gallium arsenide substrate shipments destined for Western diode laser fabricators. Supply concentrates in Japan, Germany, and the United States for precision resonator components, while East Asian foundries dominate III-V semiconductor wafer production. Raw material dependencies center on indium phosphide substrates, ytterbium-doped silica fiber, and rare-earth doping elements. Single-source vulnerability in gallium arsenide epitaxy creates structural risk for OEMs without captive fabrication. Distribution runs through authorized dealer networks for capital equipment and third-party ISO 13485-certified service providers for maintenance parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical laser systems market functions as a defensive-moat arena where FDA 510(k) regulatory entrenchment and embedded switching costs protect incumbent positions against new entrant disruption.
For Market Incumbents: Shield installed base revenue by deepening backward integration into III-V semiconductor supply chains, countering East Asian foundry concentration risk. Capture maintenance spend from third-party service encroachment through predictive resonator health monitoring subscriptions. Prioritize MDR technical documentation infrastructure investment to consolidate competitive field as EU clinical evidence requirements tighten. For New Entrants and Emerging Players: Differentiate on portable femtosecond platform form factors targeting India's tier-2 and tier-3 ophthalmology infrastructure gaps. Penetrate the photobiomodulation therapy extension segment where low-level laser applications lack established incumbent footprints. Deploy lease-to-own structures with independent service provider partnerships to bypass OEM-captive maintenance networks. For Investors and Strategic Acquirers: Capital is best deployed toward integrated device manufacturers with captive semiconductor fabrication and established quality management systems, positioned for MDR consolidation tailwinds. Long-term viability rests on backward integration depth and diagnostic-to-treatment platform convergence capabilities. Watch for III-V semiconductor supply disruption signals as inflection indicators for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Accelerates Class II laser commercialization timelines relative to European MDR routes. |
| CE Marking Pathway under MDR | Consolidates competitive field toward well-capitalized incumbents with clinical evidence infrastructure. |
| Hospital System Partnership | Locks in multi-year service bundling contracts and blocks third-party service penetration. |
| Software Companion Development | Enables predictive maintenance subscriptions and embedded switching cost creation. |
| Reimbursement Strategy | Secures CPT code coverage for laser-assisted procedures in Medicare outpatient settings. |
Study Parameters
Desk research of FDA 510(k) premarket notification databases, EU MDR technical documentation filings, and hospital procurement contract registries preceded structured interviews with biomedical engineers, GPO contracts managers, ophthalmology clinic administrators, and laser safety officers. Primary fieldwork across United States, German, and Japanese medical device clusters validated secondary data on installation base migration and service contract structures. Bottom-up equipment shipment tracking and top-down healthcare capital expenditure analysis provided triangulation across the analysis window.
Variance decomposition across product type, application, end user, and technology dimensions shaped the analytical framework throughout the projection horizon. Modeled segments spanned gain medium categories, clinical indications from ophthalmology to aesthetic procedures, facility types from integrated health systems to ambulatory surgical centers, and emission modalities from continuous wave to Q-switched architectures. CAGRs were derived from procedure volume elasticity to capital equipment replacement cycles and reimbursement coding density shifts. Forecast inputs incorporated diode-pumped architecture adoption curves and MDR compliance cost pass-through assumptions.
The analysis sits within stated boundaries; outcomes outside sustained FDA 510(k) pathway efficiency, stable III-V semiconductor supply availability, and maintained Medicare reimbursement incentives would require recalibration. Forecasts reflect documented assumptions regarding technology substitution rates and regulatory enforcement intensity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Intraocular Lens (IOL) Market
Medical Devices
Medical Face Shield Market
Medical Devices
Global Cranial Fixation and Stabilization Systems Market
Medical Devices
Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
Controlled-Release Drug Delivery Technology Market
Medical Devices
Global Intraosseous Devices Market
Medical Devices
Medical Polyetheretherketone Market
Medical Devices
Subcutaneous Injection Ports Market
Medical Devices
Hemorrhage Control System Market
Medical Devices
Australia Artificial Organs and Bionic Implants Market
Medical Devices
Global Continuous Peripheral Nerve Block Catheter Market
Medical Devices
Canada Aesthetic Devices Market
Medical Devices
US Intrauterine Devices Market
Medical Devices
Ablation Devices Market
Medical Devices
Global Vascular Access Devices Market
Medical Devices
Peritoneal Dialysis Solutions Market