
 UK Logistics Market | 2026-2036
UK Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
UK Logistics Market Intelligence
Real-time warehouse orchestration software is tilting fulfillment economics toward predictive inventory placement. GXO Logistics leverages automated storage and retrieval systems across its UK distribution network. DHL Supply Chain anchors pharmaceutical cold-chain compliance through temperature-validated facilities. Wincanton competes in defence and bulk commodities with specialized fleet configurations.
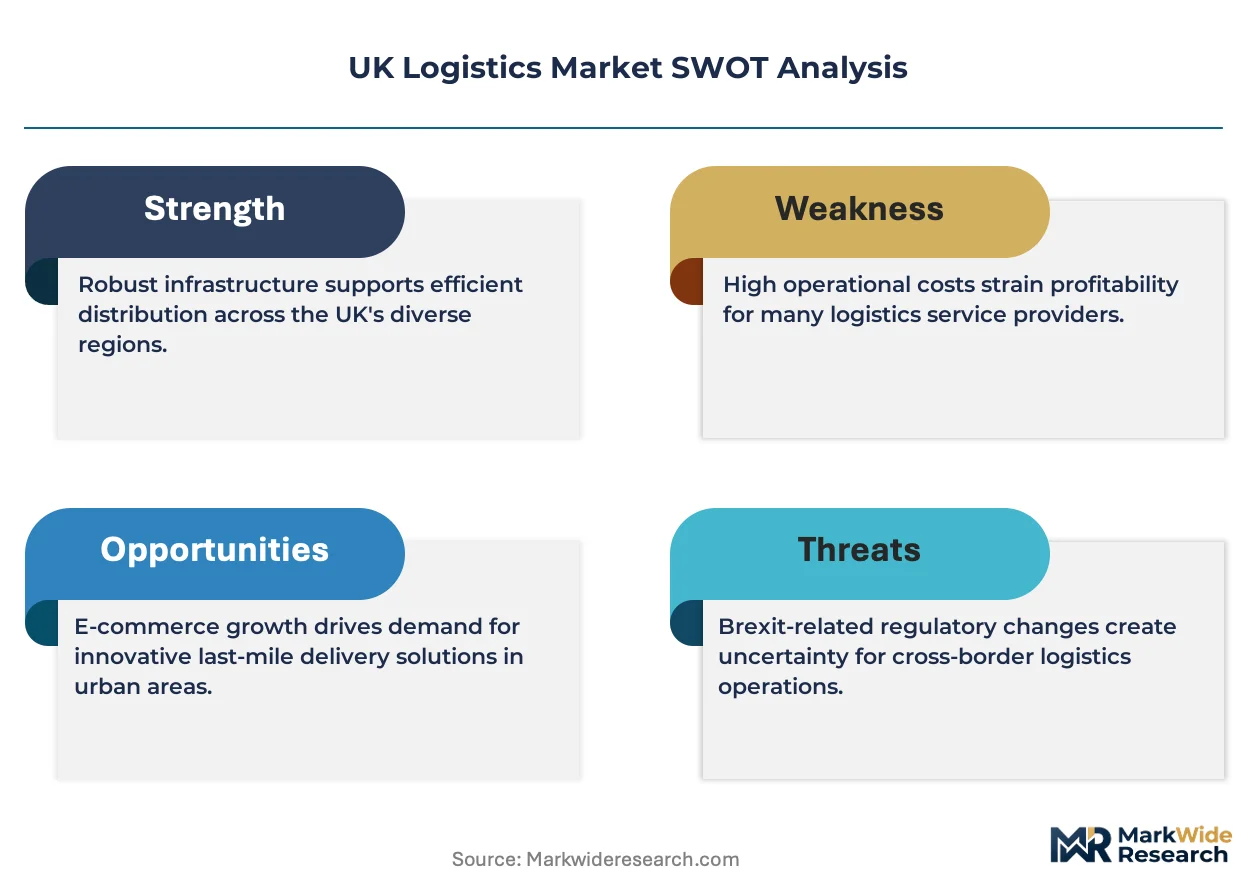
UK logistics encompasses the planning, execution, and control of goods movement across road, rail, air, and sea modalities, typically measured by tonne-kilometres and inventory turns. The sector orchestrates supply chain synchronization for manufacturers, retailers, and healthcare providers through multimodal coordination, customs brokerage, and demand-responsive warehousing. Last-mile delivery commands premium pricing as urban congestion charges and emission zones tighten operational windows. Freight forwarding benefits from post-Brexit customs complexity, with specialist brokers capturing margin from rules-of-origin documentation. Warehousing in the Midlands and South East faces land scarcity, pushing developers toward vertical construction and mezzanine automation.
The UK's Department for Transport enforces HGV operator licensing and driver hours regulations through Traffic Commissioners. HMRC administers post-Brexit customs declarations and duties, reshaping cross-border logistics costs and documentation burdens. The Health and Safety Executive mandates warehouse safety standards, influencing automation investment decisions. Stakeholders must monitor how the proposed emissions trading scheme for road freight alters total cost of ownership calculations against battery-electric and hydrogen alternatives.
Market Dynamics
Fleet electrification mandates under the UK's net-zero transport strategy are compressing diesel asset lifecycles and forcing wholesale infrastructure reinvestment across road freight operators.
Growth Catalysts
- Clean Air Zone expansion:Birmingham, Bristol, and Sheffield enforcement zones are accelerating commercial vehicle turnover toward zero-emission alternatives. Logistics operators face compliance deadlines that compress replacement cycles.
- Automated storage and retrieval systems:E-commerce fulfillment density requirements are driving ASRS deployment in the Midlands logistics corridor. Warehouse developers report automation penetration rising fastest in ambient grocery and fashion verticals.
- Pharmaceutical cold-chain growth:Temperature-validated storage demand from NHS procurement and private healthcare distributors is expanding specialized facility construction around Coventry and Leicester.
Market Restraints
- Driver qualification barriers:HGV operator licensing through Traffic Commissioners maintains strict driver hours and medical certification standards. New entrant capacity remains constrained by training pipeline bottlenecks.
- Land scarcity in South East England:Greenbelt restrictions and competing residential development priorities limit greenfield warehouse availability. Developers report land costs absorbing disproportionate capital allocation.
- Battery-electric range limitations:Current commercial EV technology imposes payload-distance trade-offs on long-haul routes. Hydrogen fuel cell alternatives remain pre-commercial for heavy freight applications.
Strategic Opportunities
- Northern Powerhouse corridor development:Manchester-Liverpool logistics clustering offers underdeveloped warehousing stock relative to Midlands saturation. Infrastructure investment is concentrating rail freight intermodal capacity.
- Post-Brexit customs specialization:Rules-of-origin documentation complexity creates margin capture potential for specialist freight forwarders. SME exporters demonstrate willingness to pay premium brokerage fees.
- Vertical construction and mezzanine automation:Land-constrained South East sites favor multi-level facilities with robotic goods-to-person systems. Planning permissions increasingly require density-maximizing designs.
Industry Challenges
- Warehouse automation integration:Legacy WMS platforms require expensive middleware development to orchestrate robotic systems. Operators report 18-24 month implementation timelines for brownfield retrofits.
- Emissions trading scheme preparation:Proposed road freight carbon pricing lacks clarity on scope and timing. Fleet managers face asset-stranding risk from premature diesel retirement or delayed electric deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Logistics Market |
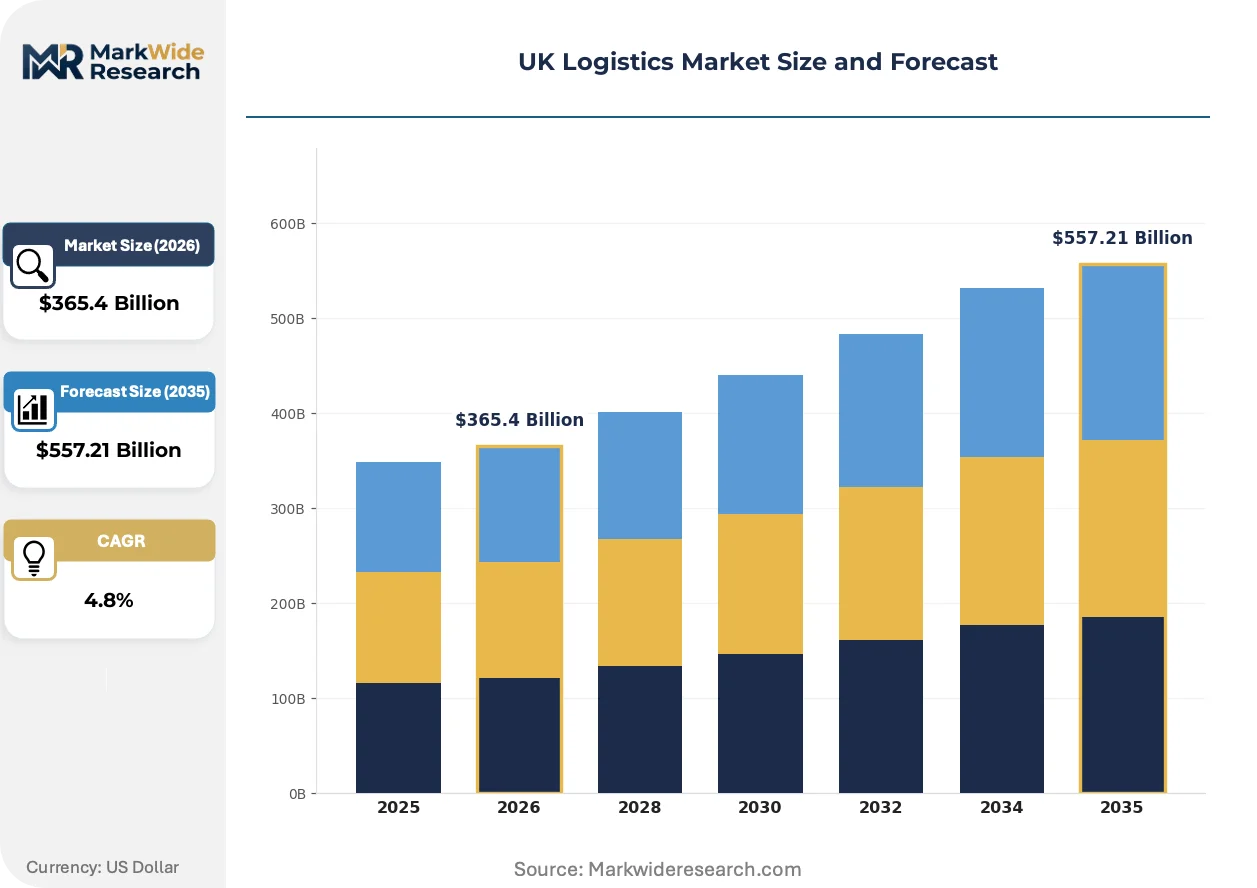
| Market Size in 2026 | $365.4 Billion |
| Market Size in 2035 | $557.21 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Last-Mile Delivery, Freight Forwarding Client Type: B2B, B2C, E-commerce, Manufacturing Technology: Blockchain, IoT, AI, Robotics Distribution Channel: Direct, Third-Party Logistics, Omnichannel, Cross-Docking |
| Companies Covered | DHL Supply Chain, GXO Logistics, XPO Logistics, Kuehne+Nagel, CEVA Logistics, Wincanton, DB Schenker, UPS Supply Chain Solutions, FedEx Supply Chain, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Logistics Market Strategic Shifts & Innovations
Real-time visibility infrastructure is compressing inventory buffers across UK supply chains. Three developments are restructuring operational economics and competitive positioning.
Autonomous mobile robots are collapsing picking labor requirements in high-SKU environments. Grocery and fashion e-commerce operators are deploying AMR fleets at scale in the Midlands corridor. The technology is collapsing unit fulfillment costs below manual operations at volumes exceeding 50,000 orders daily.
The UK Department for Transport's zero-emission HGV roadmap mandates phase-out dates for diesel tractor units. Fleet operators face compressed asset depreciation schedules and charging infrastructure capital demands. Refrigerated transport and construction logistics segments report greatest uncertainty on alternative fuel technology selection.
Consolidation of buying power among grocery multiples is forcing third-party logistics providers toward gainshare pricing structures. Traditional rate-per-pallet contracts are losing share to performance-linked arrangements with inventory accuracy and OTIF penalties. The shift is most advanced in ambient food distribution serving the big four supermarket chains.
UK Logistics Market Segmentation
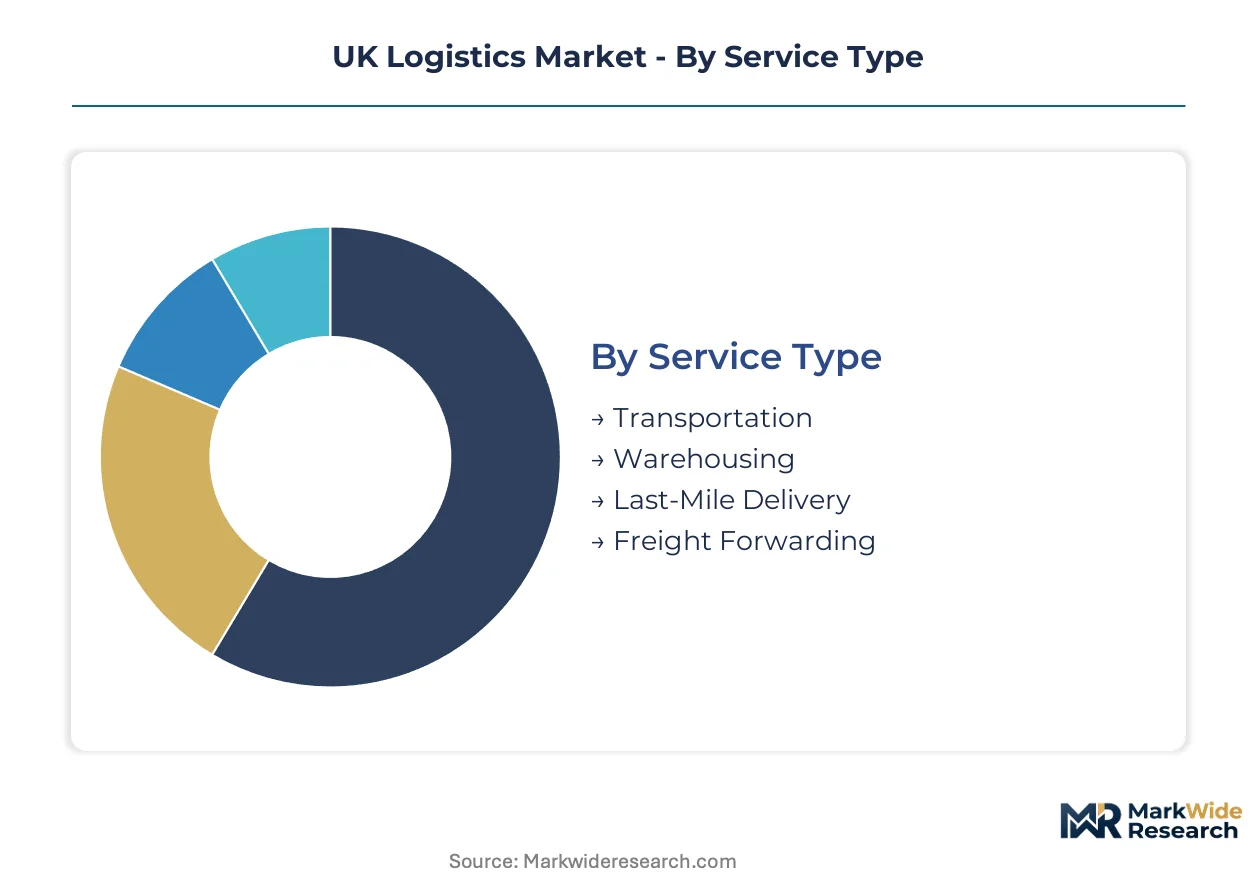
Segmentation in UK logistics reveals how service specialization, client requirements, and technology deployment create distinct competitive arenas. Each dimension carries different margin profiles and capital intensity, shaping where operators concentrate investment and where new entrants find openings.
Service Type:
Mature segments dominate revenue concentration while emerging service lines capture technology-driven efficiency gains.
- Transportation:Road freight operations spanning full-truckload, part-load, and dedicated contract carriage constitute the foundational revenue layer. Fleet electrification mandates from the Department for Transport are compressing diesel asset lifecycles and forcing infrastructure reinvestment across haulage operators serving the Midlands corridor.
- Warehousing:Multi-user and dedicated facilities provide inventory storage, value-added services, and fulfillment operations. Automated storage and retrieval systems are penetrating fastest in the South East where land scarcity pushes developers toward vertical construction with mezzanine robotics.
- Last-Mile Delivery:Urban parcel distribution faces tightening emission zone enforcement and congestion charging windows. Clean Air Zone expansion in Birmingham, Bristol, and Sheffield is accelerating commercial vehicle turnover toward zero-emission alternatives.
- Freight Forwarding:Customs brokerage and international shipment coordination capture margin from post-Brexit documentation complexity. Specialist brokers extract premium fees from SME exporters navigating rules-of-origin requirements.
Transportation handles the majority of throughput; freight forwarding is expanding most quickly on regulatory-driven demand.
Client Type:
Customer concentration patterns split between volume-scaled retail procurement and specialized industrial requirements.
- B2B:Industrial and wholesale supply chain contracts emphasize reliability metrics and dedicated capacity allocation. Manufacturing clients in automotive and aerospace verticals demand synchronized inbound logistics to support just-in-time production schedules.
- B2C:Direct-to-consumer fulfillment requires flexible capacity scaling around promotional peaks and seasonal demand surges. Home delivery networks face pressure from residential time-window expectations and failed-delivery cost absorption.
- E-commerce:Pure-play online retailers and omnichannel operations drive ASRS and AMR adoption in the Midlands logistics corridor. Grocery and fashion verticals report automation penetration rising fastest where order volumes exceed 50,000 daily.
- Manufacturing:Component inbound and finished goods outbound coordination demands specialized fleet configurations and temperature-controlled capabilities. Pharmaceutical cold-chain growth around Coventry and Leicester is expanding temperature-validated facility construction.
B2B commands the deepest contract tenure; e-commerce is gaining share fastest on fulfillment density requirements.
Technology:
Adoption maturity varies from established tracking infrastructure to pre-commercial autonomous systems.
- Blockchain:Distributed ledger applications focus on supply chain provenance and customs documentation integrity. Pilot deployments target pharmaceutical serialization and high-value goods authentication where audit trails reduce counterparty risk.
- IoT:Sensor networks for real-time location, temperature monitoring, and asset condition tracking are now baseline infrastructure. Cold-chain compliance for NHS procurement relies on continuous data logging through validated IoT devices.
- AI:Predictive demand forecasting and dynamic route optimization are compressing inventory buffers and empty-running miles. Machine learning applications in warehouse orchestration software are tilting fulfillment economics toward predictive inventory placement.
- Robotics:Autonomous mobile robots are collapsing picking labor requirements in high-SKU environments. Grocery and fashion operators deploying AMR fleets at scale report unit fulfillment costs below manual operations at sufficient volume thresholds.
IoT handles the majority of deployed endpoints; robotics is climbing the fastest on labor cost arbitrage.
Distribution Channel:
Channel structure reflects control preferences and asset ownership trade-offs across client risk profiles.
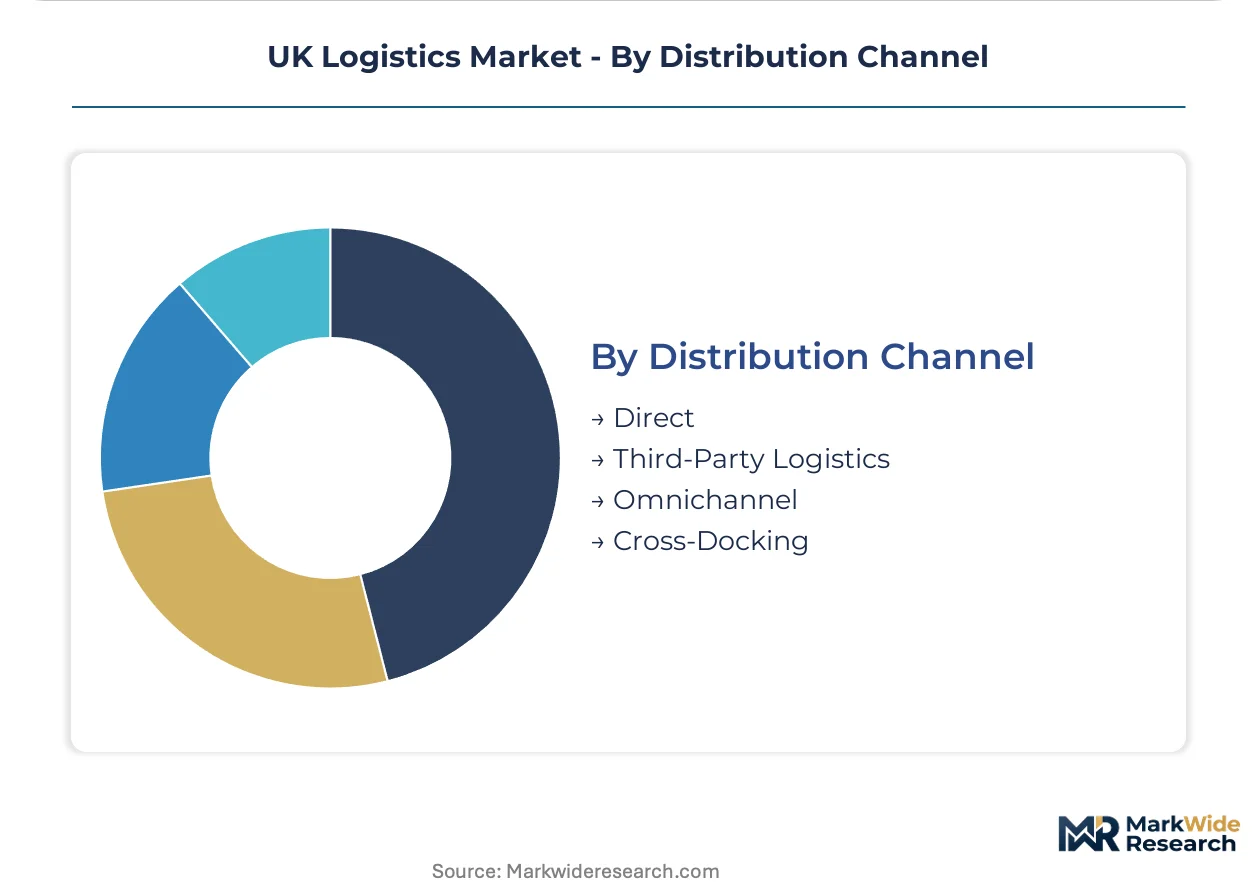
- Direct:Shipper-operated logistics networks retain control over customer experience and capacity prioritization. Capital intensity limits direct operation to large-scale retailers and manufacturers with sufficient volume density.
- Third-Party Logistics:Outsourced operators provide variable-cost access to specialized capabilities and geographic coverage. Consolidation of buying power among grocery multiples is forcing 3PL providers toward gainshare pricing with OTIF penalties.
- Omnichannel:Integrated inventory pools serving store replenishment, online fulfillment, and click-and-collect from shared stock. Real-time visibility infrastructure enables order routing optimization across fulfillment nodes.
- Cross-Docking:Flow-through facilities minimizing inventory holding through rapid sortation and onward dispatch. Time-definite networks for fashion and perishables rely on cross-dock velocity to maintain product freshness and markdown avoidance.
Third-party logistics handles the majority of outsourced volume; omnichannel is gaining share fastest on inventory unification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UK-EU trade corridor dominates cross-border freight flows, with Irish Sea routes and Channel tunnel movements handling the majority of goods volume. Post-Brexit customs complexity has reshaped distribution patterns across British sub-regions.
London and South East
Last-mile density and premium warehousing costs drive automation investment in Greater London and Thames Valley distribution zones. Clean Air Zone enforcement in London tightens delivery windows for commercial vehicles. Slough and Dartford logistics parks attract vertical construction with mezzanine robotics to overcome land scarcity.
Midlands Logistics Corridor
E-commerce fulfillment concentration and automotive supply chain synchronization elevate Birmingham, Coventry, and Leicester as the primary warehousing demand cluster. The Department for Transport's Midlands Engine investment program expands rail freight intermodal capacity. East Midlands Gateway and Magna Park developments concentrate automated storage and retrieval systems deployment.
North England
Manchester-Liverpool port connectivity and underdeveloped warehousing stock relative to Midlands saturation attract speculative development. Northern Powerhouse rail freight investment targets container traffic diversion from road haulage. Trafford Park and Liverpool2 deep-water terminal expansion anchor manufacturing and retail distribution clustering.
Scotland
Aberdeen energy logistics and Edinburgh-Grangemouth petrochemical flows sustain specialized fleet demand. Transport Scotland's freight mode shift grant program subsidizes rail and waterborne alternatives to trunk road movements. Glasgow and central belt distribution zones serve whisky export consolidation and retail replenishment north of the border.
Wales
Port of Holyhead Irish Sea connectivity and South Wales manufacturing supply chains generate cross-border freight intensity. Welsh Government transport decarbonization targets accelerate commercial vehicle electrification timelines. Cardiff and Newport logistics zones handle steel, automotive components, and FMCG distribution to western England markets.
UK Logistics Market Key Industry Players
On the supply side, the industry is consolidating around integrated operators with scale advantages in automation deployment and fleet electrification. Tiered competition separates global network players from domestic specialists and technology-forward disruptors. Strategic archetypes include asset-heavy contract logistics providers, customs-specialized freight forwarders, and last-mile platform operators. Capacity expansion through speculative warehousing development and strategic partnerships for charging infrastructure dominate competitive moves.
Among asset-heavy contract logistics providers, GXO Logistics and DHL Supply Chain represent the automation-forward tier, while Wincanton occupies a position within domestic specialist operators serving defence and bulk commodity verticals. These companies exemplify divergent capital allocation strategies across the competitive spectrum.
| Leading Market Players |
|---|
| DHL Supply Chain |
| GXO Logistics |
| XPO Logistics |
| Kuehne+Nagel |
| CEVA Logistics |
| Wincanton |
| DB Schenker |
| UPS Supply Chain Solutions |
| FedEx Supply Chain |
| Others |
Cost & Logistics Intelligence
Midlands logistics corridor capacity saturation around Birmingham and Leicester is compressing warehousing margins while amplifying pricing power for automated facilities with immediate availability. Fleet electrification mandates from the Department for Transport are forcing asset reinvestment that operators attempt to recover through contract renegotiation with grocery multiples and pharmaceutical distributors.
Pricing Analysis
Prior-generation diesel fleet contracts trade at a discount to battery-electric alternatives, while next-generation hydrogen fuel cell pricing remains pre-commercial and unquoted. Three-tier pricing structure across premium automation-enabled, standard conventional warehousing, and economy spot-market trucking dominates contract structures. Price differentiation rests on Clean Air Zone compliance certification and volume scale commitments above fifty thousand pallet positions annually. Cost compression in long-haul road freight is intensifying because payload-distance trade-offs erode electric vehicle utilization rates. SME exporters demonstrate highest price sensitivity, while NHS procurement and automotive just-in-time operations accept premium pricing for reliability guarantees.
Supply Chain Analysis
Specialist contract logistics providers including GXO Logistics and DHL Supply Chain hold automated capacity concentration in the South East and Midlands corridors. Geographic supply concentration centers on the UK domestic market with critical dependencies on Dutch and French port infrastructure for EU-UK freight flows. Raw material inputs for fleet electrification draw from lithium cell manufacturing in China, South Korea, and Japan, while warehouse automation components source from German and Italian engineering clusters. Single-source vulnerability runs through Channel tunnel capacity and Irish Sea ro-ro routes. Distribution runs through third-party logistics networks with omnichannel inventory pooling gaining share fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UK logistics is approaching a platform-economics inflection where real-time visibility infrastructure enables interoperability between shipper ERP systems and operator WMS platforms, collapsing information asymmetries that historically sustained margin capture.
For Market Incumbents: Build switching-cost moats through embedded warehouse orchestration software that raises retrofit expenses for competitor migration. Consolidate speculative automation deployment in the Northern Powerhouse corridor ahead of infrastructure investment announcements. Defend against technology-forward disruptors by securing exclusive charging infrastructure partnerships with electricity network operators. Deepen vertical integration into temperature-validated construction for pharmaceutical verticals where compliance barriers protect pricing. For New Entrants and Emerging Players: Pursue white-space opportunities in post-Brexit customs brokerage specialization where rules-of-origin complexity outpaces incumbent capacity expansion. Target Manchester-Liverpool logistics clustering with underdeveloped warehousing stock relative to Midlands saturation. Enter through vertical construction and mezzanine automation expertise for land-constrained South East sites where planning permissions increasingly mandate density-maximizing designs. Lead with gainshare pricing models that align operator incentives with supermarket OTIF performance metrics. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because automation capital intensity and fleet electrification mandates favor scaled operators with balance sheet capacity for infrastructure reinvestment. Acquisition targets should emphasize domestic specialists with defence or bulk commodity contracts providing revenue stability through cyclical downturns. Monitor Clean Air Zone enforcement expansion schedules as the critical signal for asset-stranding risk and replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Storage and Retrieval System Deployment | ASRS penetration in Midlands grocery and fashion verticals collapses unit fulfillment costs below manual operations at sufficient scale. |
| Fleet Electrification Partnership | Charging infrastructure agreements with National Grid and regional DNOs secure operational capacity ahead of competitor rollout. |
| Post-Brexit Customs Specialization | Rules-of-origin documentation expertise captures premium brokerage fees from SME exporters navigating HMRC complexity. |
| Vertical Construction Development | Multi-level facilities with robotic goods-to-person systems overcome greenbelt land scarcity in South East England. |
| Gainshare Contract Structuring | Performance-linked arrangements with inventory accuracy and OTIF penalties align 3PL incentives with grocery multiple procurement demands. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet managers at road freight operators, warehouse development directors, pharmaceutical procurement leads at NHS trusts, and customs brokerage specialists. Secondary validation drew from Department for Transport operator licensing statistics, HMRC customs declaration data, Health and Safety Executive enforcement notices, and Traffic Commissioners regulatory publications. Bottom-up capacity modeling across the Midlands logistics corridor was triangulated against top-down market value estimates.
Calibration against historical automation deployment timelines and fleet turnover patterns informed projection methodology across the analysis window. Segmentation dimensions modeled include service type, client vertical, technology adoption tier, and geographic cluster. CAGRs were derived from logistic curve fitting to electrification mandate compliance schedules and e-commerce fulfillment density trajectories. Forecast inputs incorporated Clean Air Zone expansion announcements and Midlands Engine infrastructure investment commitments.
Macroeconomic conditions sit as an overlay; deviation in consumer spending velocity, commercial real estate yields, or EU-UK trade friction would shift the trajectory. Forecasts reflect documented assumptions regarding technology cost decline curves and regulatory enforcement timing. Quarterly review of HGV operator licensing applications, warehouse planning permission grants, and battery-electric vehicle registration data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
United States Apparel Logistics Market
Logistics and Shipping
Contract Logistics Market
Logistics and Shipping
Central and Eastern Europe Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
GCC Dangerous Goods Logistics Market
Logistics and Shipping
Global 3PL Market
Logistics and Shipping
Romania Freight and Logistics Market
Logistics and Shipping
United Arab Emirates (UAE) Third-Party Logistics (3PL) Market
Logistics and Shipping
Big Data in Logistics Market
Logistics and Shipping
North America Refrigerated Container Shipping Market
Logistics and Shipping
Smart Shipping Containers Market
Logistics and Shipping
Egypt Third Party Logistics (3PL) Market
Logistics and Shipping
New York Freight and Logistics Market
Logistics and Shipping
Asia Pacific International Express Service Market
Logistics and Shipping
North America Logistics Market
Logistics and Shipping
Total Logistics Market
Logistics and Shipping
Kazakhstan Freight and Logistics Market