
 Total Logistics Market | 2026-2036
Total Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Total Logistics Market Analysis
E-commerce fulfillment networks is reorganizing procurement patterns away from traditional retail buyers toward direct-to-consumer operators. DHL Supply Chain & Global Forwarding leverages its pharmaceutical cold-chain infrastructure to anchor premium-margin segments. Amazon dominates last-mile technology investment, while Maersk Logistics controls intermodal ocean-rail connectivity across Asia-Europe corridors.
Total logistics encompasses the integrated planning, execution, and control of freight movement, inventory storage, and information flows across supply chains, typically measured by ton-kilometers, warehouse throughput, and order-cycle time. Its primary purpose is reducing landed cost while meeting service-level agreements for time-definite delivery. Transportation services lead revenue contribution due to fuel and labor intensity, though third-party logistics is growing fastest as manufacturers outsource fleet and warehouse ownership. Warehousing retains concentrated margin pools in temperature-controlled and bonded facilities serving pharmaceutical and automotive end users.
The EU Green Deal and its F-Gas Regulation are reshaping refrigerant standards in European cold-chain warehousing, while India's CEA mandates energy-efficiency audits for large logistics parks. The US EPA and DOT jointly enforce heavy-duty truck emissions standards under the Clean Truck Plan, raising compliance costs for fleet operators. Stakeholders must monitor how carbon-border adjustments and battery-electric truck total-cost-of-ownership curves reshape network design decisions before the next equipment replacement cycle.
Market Dynamics
E-commerce fulfillment networks are reorganizing procurement patterns for pharmaceutical cold-chain logistics while the EU Green Deal's emissions trading scheme tightens fuel-efficiency mandates for freight carriers. The interaction between direct-to-consumer delivery density and carbon-border compliance costs is compressing traditional hub-and-spoke network economics.
Growth Catalysts
- EU Green Deal emissions trading:The tightening cap-and-trade mechanism for heavy-duty freight creates compliance-driven fleet renewal cycles that favor logistics providers with capital reserves for electric and hydrogen truck deployment.
- Pharmaceutical cold-chain infrastructure:Temperature-sensitive biologics distribution demands are pulling investment into validated packaging and real-time monitoring systems across last-mile networks.
- India warehousing corridor concentration:Demand clustering around Mumbai and Delhi-NCR is generating economies of scale in automated storage and retrieval systems for third-party logistics operators.
Market Restraints
- Diesel price volatility:Fuel represents 25-35% of road freight operating costs, and geopolitical supply disruptions transmit directly to carrier margin pressure without contract pass-through clauses.
- Chassis and container equipment concentration:Asian manufacturing dominance for intermodal equipment creates lead-time vulnerability and pricing power asymmetry for North American and European asset owners.
- Battery-electric truck range limitations:Current lithium-ion energy density constrains long-haul routes beyond 300 miles without mid-journey charging infrastructure that remains sparse on transcontinental corridors.
Strategic Opportunities
- CEA energy-efficiency mandates:India's mandated audits for large logistics parks create service revenue streams for engineering consultancies and equipment retrofit specialists.
- Reverse logistics for electronics:E-waste collection and refurbishment networks remain underdeveloped relative to forward distribution, offering first-mover positioning for circular-economy compliance.
- Autonomous yard tractors:Convergence of lidar perception systems and terminal operating software enables driverless container repositioning in high-throughput port environments.
Industry Challenges
- Commercial driver shortage:Demographic shifts and lifestyle preferences are constraining recruitment for long-haul trucking across North America and Western Europe.
- Warehouse automation integration:Legacy warehouse management systems require expensive middleware development to coordinate with robotic picking and autonomous mobile robot fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Total Logistics Market |
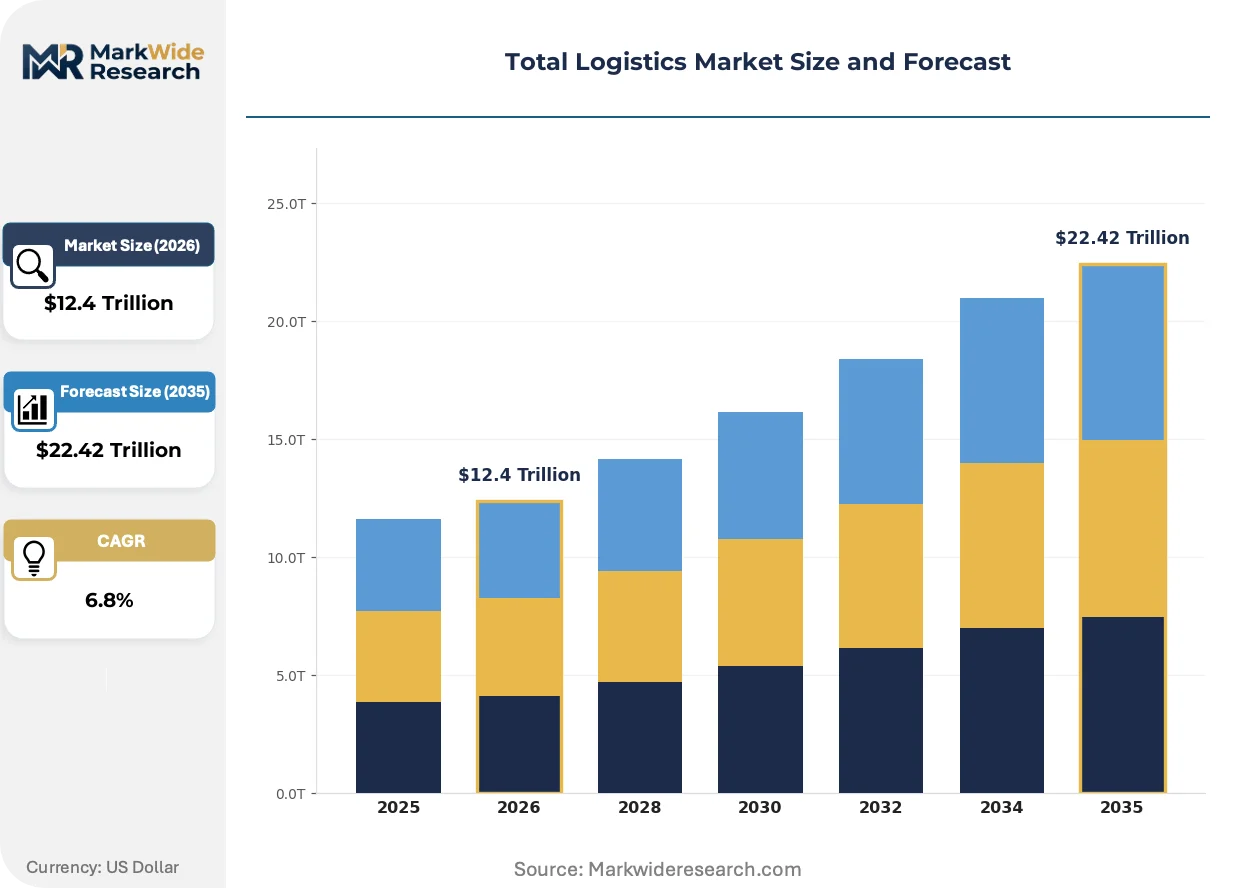
| Market Size in 2026 | $12.4 Trillion |
| Market Size in 2035 | $22.42 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Third-Party Logistics End User: Manufacturing, Retail, E-Commerce, Automotive Technology: Blockchain, IoT, AI, Automation Distribution Channel: Direct, Online, Third-Party, Specialty |
| Companies Covered | DSV, CEVA Logistics, Amazon, C.H. Robinson, Nippon Express, DHL Supply Chain & Global Forwarding, DB Schenker, Maersk Logistics, Kuehne + Nagel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Total Logistics Market Emerging Trajectories
Digital freight matching platforms and predictive analytics are compressing procurement cycles while autonomous vehicle testing accelerates on designated freight corridors. The competitive frontier has shifted from asset ownership to algorithmic network optimization.
Blockchain-enabled documentation is fragmenting traditional freight forwarding value capture. The technology creates immutable records of cargo condition and custody transfer for pharmaceutical and high-value shipments. Large shippers in the automotive and electronics sectors are piloting direct carrier contracting that bypasses intermediary document-processing fees. The structural consequence is margin compression for traditional forwarders who cannot embed compliance automation into their service layers.
The EU F-Gas Regulation is reshaping refrigerant standards in European cold-chain warehousing by mandating phasedown of hydrofluorocarbon-based systems. Operators face retrofit capital requirements or penalties for non-compliance with global warming potential thresholds. Temperature-controlled facilities serving pharmaceutical distribution in Germany and the Netherlands are accelerating adoption of CO2 transcritical refrigeration to meet 2030 reduction targets.
Direct-to-consumer order patterns are compressing batch sizes and delivery windows in urban fulfillment networks. Retailers are unbundling inventory pools between forward distribution centers and micro-fulfillment nodes positioned within 10 miles of dense population centers. This shift is most visible in grocery and fast-fashion verticals across metropolitan China and Southeast Asian megacities where same-day delivery has become a baseline expectation.
Total Logistics Market Segmentation
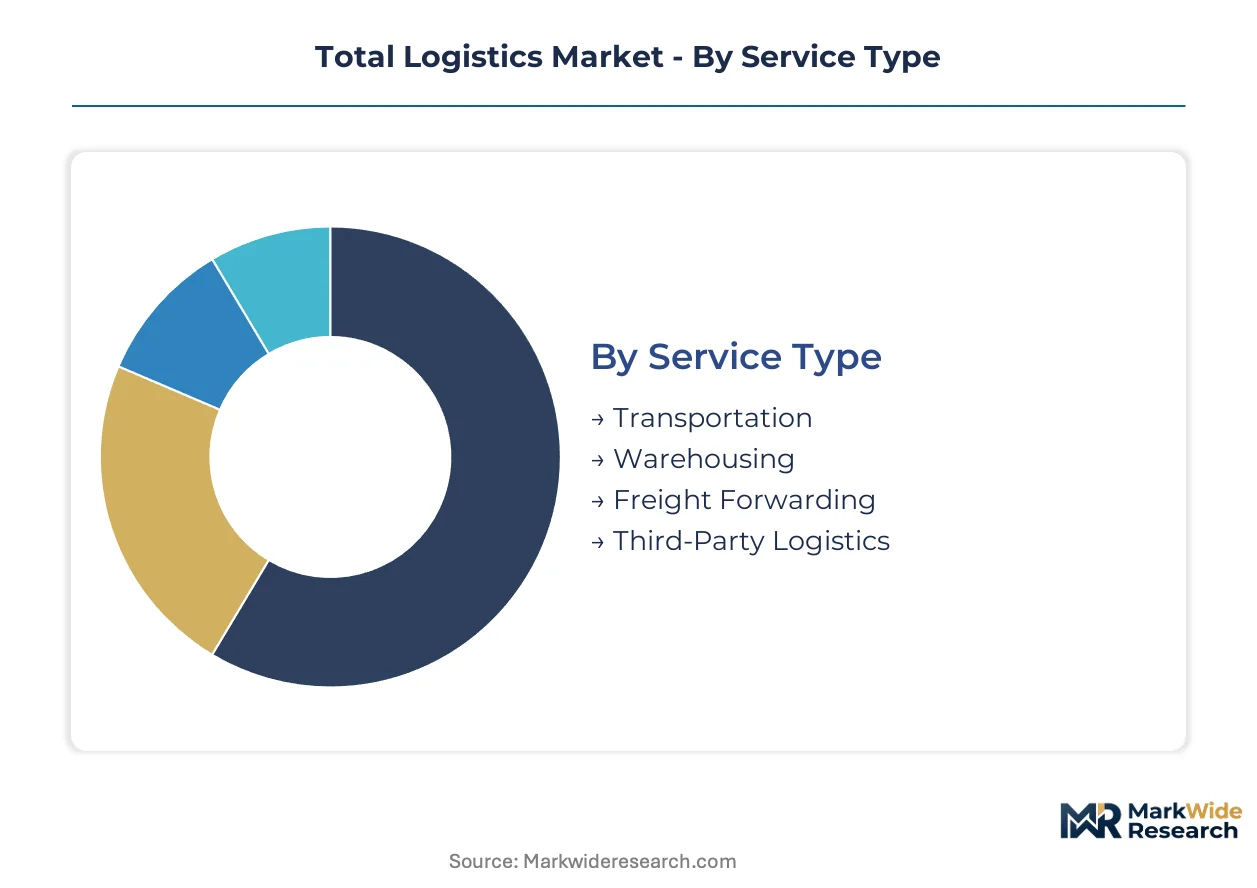
Logistics providers configure service portfolios around distinct operational capabilities and customer risk profiles. Each segmentation axis reveals where capital deployment concentrates and which technology investments reshape competitive boundaries.
Service Type:
Third-party logistics operators face the most acute substitution pressure as manufacturers weigh in-house fleet control against outsourcing economics.
- Transportation:Asset-heavy road, rail, air, and ocean freight carriage governed by fuel-cost exposure and driver availability constraints. Demand clusters around pharmaceutical cold-chain corridors linking Mumbai to European distribution hubs, pressured by EU Green Deal emissions compliance deadlines.
- Warehousing:Temperature-controlled and ambient storage facilities with bonded-status specialization for customs-deferred inventory. Investment concentrates in Delhi-NCR automated parks serving e-commerce fulfillment networks, driven by India's CEA energy-efficiency audit mandates.
- Freight Forwarding:Intermodal coordination and customs documentation services. Blockchain-enabled documentation is fragmenting traditional value capture as automotive shippers pilot direct carrier contracting.
- Third-Party Logistics:Integrated outsourcing of transportation, warehousing, and inventory management. Retailers unbundle inventory pools between forward distribution centers and micro-fulfillment nodes within 10 miles of dense population centers.
Transportation anchors the volume base while third-party logistics gains share at the steepest rate.
End User:
Cost-tier stratification separates capital-intensive manufacturers from margin-compressed retail operators with diverging service-level requirements.
- Manufacturing:Just-in-time component delivery and finished-goods distribution for automotive and electronics assembly. German automotive OEMs drive demand for validated packaging systems across Asia-Europe intermodal corridors.
- Retail:Store replenishment and seasonal surge capacity for brick-and-mortar networks. Same-day delivery baselines in Chinese and Southeast Asian megacities compress batch sizes and delivery windows.
- E-Commerce:Direct-to-consumer order fulfillment with returns processing. Procurement patterns shift away from traditional retail buyers toward direct-to-consumer operators reorganizing pharmaceutical cold-chain logistics.
- Automotive:Sequenced parts delivery to assembly lines and finished-vehicle distribution. Battery-electric vehicle supply chains require specialized handling for lithium-ion cell transport under UN dangerous goods regulations.
Manufacturing retains the largest contract value per engagement while e-commerce expands most quickly.
Technology:
Application maturity separates pilot-phase deployments from scaled operational integration with measurable ROI thresholds.
- Blockchain:Immutable cargo-condition records and custody-transfer documentation. Pharmaceutical and high-value shipments pilot direct carrier contracting that bypasses intermediary document-processing fees.
- IoT:Real-time location tracking and environmental monitoring for temperature-sensitive biologics. Validated packaging systems with sensor integration anchor premium-margin segments in European cold-chain networks.
- AI:Predictive demand forecasting and dynamic route optimization. Algorithmic network optimization displaces asset ownership as the primary competitive frontier.
- Automation:Robotic picking, autonomous mobile robots, and driverless yard tractors. Legacy warehouse management systems require expensive middleware development to coordinate with robotic fleets.
IoT commands the largest installed base while AI demonstrates the steepest adoption trajectory.
Distribution Channel:
Customer-type concentration shapes whether procurement runs through centralized supply chain functions or decentralized business-unit authority.
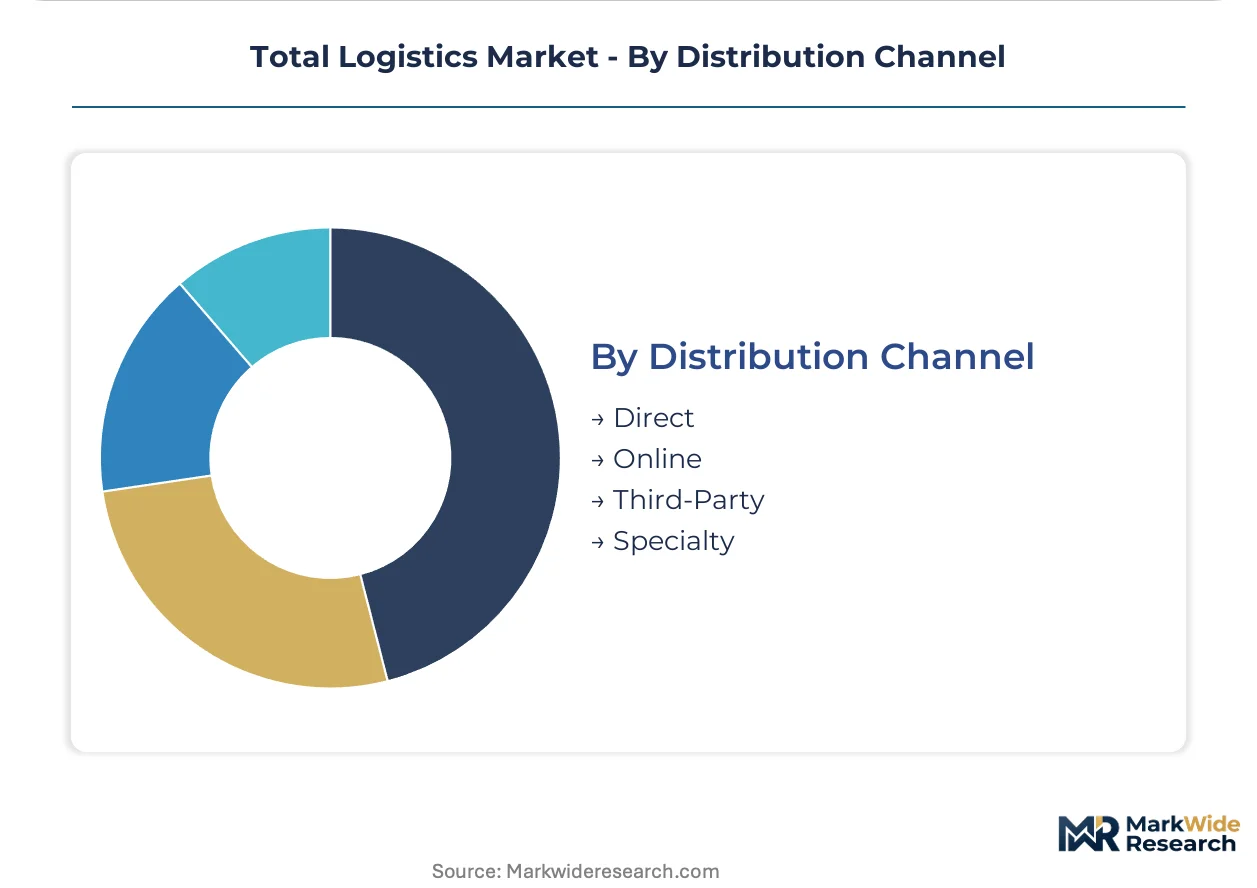
- Direct:Long-term contracted relationships between shippers and asset-owning carriers. Large automotive and electronics shippers consolidate volume to secure capacity guarantees.
- Online:Digital freight-matching platforms compressing procurement cycles for spot-market capacity. Algorithmic pricing transparency erodes traditional broker margins.
- Third-Party:Intermediary forwarders and non-asset-based logistics providers. Margin compression accelerates for traditional forwarders who cannot embed compliance automation into service layers.
- Specialty:Niche providers serving pharmaceutical cold-chain, hazardous materials, or oversized cargo. CO2 transcritical refrigeration retrofits accelerate in German and Dutch temperature-controlled facilities.
Direct contracting anchors relationship value while online platforms climb the fastest in transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jebel Ali Port in Dubai anchors Middle Eastern transshipment capacity for Asia-Europe corridors. Rotterdam's Maasvlakte terminals underwrite Northwest European gateway functions for containerized pharmaceuticals. Singapore's Tuas megaport consolidates Southeast Asian hub operations for temperature-sensitive biologics.
United States
E-commerce fulfillment density and pharmaceutical cold-chain expansion drive warehouse automation investment. The EPA and DOT jointly enforce heavy-duty truck emissions standards under the Clean Truck Plan, elevating electric fleet procurement costs. The Inland Empire corridor east of Los Angeles concentrates automated storage facilities serving direct-to-consumer distribution networks.
Germany
Automotive sequenced parts delivery and pharmaceutical biologics distribution anchor premium logistics demand. The EU Green Deal's emissions trading scheme tightens fuel-efficiency mandates for freight carriers operating across the Rhine-Alpine corridor. The Ruhr industrial zone accelerates CO2 transcritical refrigeration retrofits in temperature-controlled warehousing to meet 2030 F-Gas Regulation targets.
India
Third-party logistics outsourcing and e-commerce fulfillment network expansion concentrate capital deployment. The CEA mandates energy-efficiency audits for large logistics parks exceeding specified consumption thresholds. Mumbai and Delhi-NCR warehousing corridors generate economies of scale in automated storage and retrieval systems for pharmaceutical and retail distribution.
China
Cross-border e-commerce logistics and battery-electric vehicle supply chain handling reshape network requirements. NMPA and MIIT coordinate dangerous goods regulations for lithium-ion cell transport under UN standards. The Yangtze River Delta cluster around Shanghai integrates ocean-rail intermodal connectivity for automotive and electronics exports to European markets.
Netherlands
Pharmaceutical cold-chain gateway functions and perishable food distribution sustain temperature-controlled facility demand. The EU F-Gas Regulation mandates hydrofluorocarbon phasedown in European warehousing, accelerating refrigerant system replacement. The Port of Rotterdam's hinterland rail connections enable bonded customs-deferred inventory positioning for German and Belgian manufacturing supply chains.
Total Logistics Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and geographic coverage dimensions. The market structure tiers between asset-heavy ocean-rail integrators, technology-forward last-mile platforms, and non-asset freight forwarders. Three archetypes dominate: integrated carriers controlling intermodal infrastructure, e-commerce-native operators algorithmically optimizing delivery density, and specialist forwarders embedding compliance automation. Competitive moves concentrate on electric fleet deployment partnerships and warehouse automation system integration.
Among integrated logistics providers, DHL Supply Chain & Global Forwarding and Maersk Logistics occupy positions spanning pharmaceutical cold-chain infrastructure and ocean-rail corridor control. C.H. Robinson represents the non-asset freight matching archetype, anchoring digital procurement platform development without fixed equipment ownership. These three exemplify divergent capital deployment strategies—integrated asset bases versus technology-enabled network coordination—reshaping margin capture across temperature-sensitive and time-definite delivery segments.
| Leading Market Players |
|---|
| DSV |
| CEVA Logistics |
| Amazon |
| C.H. Robinson |
| Nippon Express |
| DHL Supply Chain & Global Forwarding |
| DB Schenker |
| Maersk Logistics |
| Kuehne + Nagel |
| Others |
Supply Flow & Price Mechanics
EU Green Deal emissions trading schemes gate both fleet qualification and freight rate differentiation simultaneously, compressing margin pools for carriers without capital reserves while rewarding early electric truck adopters with premium contract access.
Pricing Analysis
Volume-discount tiering structures dominate contract logistics, with pharmaceutical cold-chain commanding premium rates against standard ambient freight. Price differentiation rests on EU F-Gas Regulation compliance certification and real-time IoT monitoring integration. Cost compression in standard road freight is intensifying because diesel price volatility transmits directly to operating margins without pass-through clauses. E-commerce retailers exhibit highest price sensitivity, while pharmaceutical manufacturers accept premium positioning for validated temperature assurance.
Supply Chain Analysis
Just-in-time preferences dominate automotive and electronics assembly, while strategic stockpiling characterizes pharmaceutical buffer inventory for pandemic readiness. Supply concentrates in China for intermodal equipment manufacturing, Germany for automotive sequencing parts, and India for third-party logistics outsourcing growth. Raw material dependencies include lithium-ion cells for electric fleet transition, specialized refrigerants for cold-chain retrofit, and chassis components for container production. Single-source vulnerability in Asian equipment manufacturing creates lead-time risk. Distribution runs through bonded warehousing corridors in Rotterdam, Dubai, and Singapore for customs-deferred inventory positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Total logistics market fragmentation creates opportunity as direct-to-consumer delivery density splits procurement authority between centralized supply chain functions and decentralized e-commerce operators, opening niches for specialized last-mile and cold-chain providers.
For Market Incumbents: Fortify pharmaceutical cold-chain infrastructure against DHL Supply Chain's anchored position by accelerating CO2 transcritical refrigeration retrofits ahead of 2030 F-Gas deadlines. Consolidate control over Mumbai and Delhi-NCR warehousing corridors through automated storage capacity additions that exploit CEA audit mandates as competitive moats. For New Entrants and Emerging Players: Lead with reverse logistics for electronics refurbishment as circular-economy compliance creates first-mover positioning where forward distribution networks remain overdeveloped. Target India's energy-efficiency audit services for large logistics parks, deploying engineering consultancy capabilities as a wedge into facility management contracts. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across battery-electric truck deployment as total-cost-of-ownership curves reshape fleet replacement economics. Acquisition candidates include autonomous yard tractor software developers and CO2 refrigeration retrofit specialists with proven European pharmaceutical facility deployments. Watch electric truck range extension beyond 300 miles as the inflection signal for long-haul carrier viability.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Deployment Partnership | Battery-electric truck procurement with charging infrastructure secures EU Green Deal compliance premiums for freight contracts. |
| Cold-Chain Refrigerant Retrofit | CO2 transcritical system installation meets F-Gas Regulation thresholds for pharmaceutical warehousing in Germany and Netherlands. |
| Autonomous Yard Tractor Integration | Driverless container repositioning at Jebel Ali and Rotterdam terminals reduces labor dependency in high-throughput port environments. |
| Micro-Fulfillment Node Expansion | Urban inventory positioning within 10 miles of dense population centers captures same-day delivery baselines in Chinese megacities. |
| Blockchain Documentation Platform | Immutable cargo-condition records fragment traditional freight forwarder margins by enabling direct shipper-carrier contracting. |
Methodological Framework
Initial hypotheses were tested against primary input from fleet operations directors, pharmaceutical supply chain managers, warehouse automation engineers, and customs brokerage heads and refined through secondary validation against EPA heavy-duty truck emissions filings, EU ETS transaction registries, India CEA energy audit disclosures, and ocean-rail intermodal trade data. Bottom-up carrier capacity assessments and top-down logistics spend estimates were triangulated to anchor market sizing.
Variance-decomposition framing isolates growth contributions from e-commerce fulfillment expansion, pharmaceutical cold-chain infrastructure investment, and regulatory compliance cost pass-through across the projection horizon. Segmentation dimensions modeled include service type, end-user industry, technology adoption tier, and distribution channel structure. CAGRs were derived from equipment replacement cycle analysis and fleet electrification penetration curves, with battery-electric truck total-cost-of-ownership trajectories and carbon-border adjustment implementation timelines as key inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement intensity or accelerated India warehousing corridor development would require recalibration. Forecasts reflect assumptions regarding lithium-ion energy density improvement and charging infrastructure buildout pace. Revision becomes warranted when battery-electric truck range thresholds cross 500-mile corridors or when carbon-border adjustment mechanisms expand beyond pilot phases.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Singapore 3PL Market
Logistics and Shipping
North America Freight and Logistics Market
Logistics and Shipping
Automotive Logistics Market
Logistics and Shipping
Russia Freight and Logistics Market
Logistics and Shipping
Global Courier Market
Logistics and Shipping
Italy Apparel Logistics Market
Logistics and Shipping
Nigeria Air Freight Market
Logistics and Shipping
GCC Air Freight and Logistics Market
Logistics and Shipping
France Freight and Logistics Market
Logistics and Shipping
United Kingdom Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
United States Chartered Air Freight Transport Market
Logistics and Shipping
ASEAN Chemical Logistics Market
Logistics and Shipping
Ocean Freight Software Market
Logistics and Shipping
Government and Education Logistics Market
Logistics and Shipping
Germany Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Global Dry Bulk Shipping Market