
 Contract Logistics Market | 2026-2036
Contract Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Contract Logistics Market Analysis
China's warehouse construction boom is reshaping contract logistics capacity globally. DHL Supply Chain leverages its Asia-Pacific footprint to anchor automotive and consumer electronics fulfillment networks. Kuehne + Nagel specializes in pharmaceutical cold chain compliance, differentiating through temperature-controlled infrastructure. GXO Logistics dominates e-commerce warehousing automation, competing on robotic throughput density.
Contract logistics encompasses outsourced management of transportation, warehousing, inventory control, and distribution operations performed under multi-year agreements with defined service levels and key performance indicators. Providers integrate warehouse management systems with client enterprise resource planning platforms to synchronize stock positioning with production schedules and order cycles. Warehousing services capture the largest margin pools due to long-term lease structures and automation capex barriers, while transportation segments face more fragmented competition. Pharmaceutical verticals command premium pricing through GDP-compliant infrastructure, whereas retail and consumer goods volumes drive scale economics in shared distribution networks.
FDA enforcement of the Drug Supply Chain Security Act elevates track-and-trace requirements for pharmaceutical logistics providers, mandating serialized packaging verification at every distribution node. EPA emissions standards under the Clean Air Act accelerate fleet electrification investments, reshaping capital deployment for last-mile operators. OSHA warehouse safety regulations influence automation adoption thresholds, particularly for material handling equipment. Stakeholders must evaluate whether dedicated or shared delivery models align with regulatory compliance costs and customer concentration risk.
Market Dynamics
Automotive electrification in Germany is collapsing traditional inbound logistics models as battery supply chains demand entirely different handling protocols, temperature controls, and reverse logistics infrastructure than combustion-era component flows.
Growth Catalysts
- E-commerce fulfillment density:China's urban warehouse construction is absorbing unprecedented capital as platform operators demand dedicated facilities within two-hour delivery radii of Tier-1 city centers.
- EU Green Deal fleet mandates:The EU Green Deal is compelling logistics providers to electrify last-mile vehicle fleets and retrofit warehouse energy systems to meet emissions reporting thresholds.
- Pharmaceutical serialization infrastructure:The FDA's Drug Supply Chain Security Act enforcement is mandating track-and-trace verification systems at every distribution node, creating specialized service demand.
Market Restraints
- Automation capex barriers:Warehouse robotics deployment requires capital commitments that fragment competitive tiers between automated and manual operators.
- Lithium-ion handling regulations:UN 38.3 testing requirements and IATA dangerous goods classifications impose specialized infrastructure costs on battery logistics corridors.
- Real estate concentration risk:Prime logistics land scarcity in the Netherlands' Randstad and Germany's Rhine-Ruhr corridor is inflaming lease rate volatility.
Strategic Opportunities
- India's contract logistics penetration gap:India's manufacturing-led growth is outpacing organized logistics capacity, creating first-mover advantages for temperature-controlled and automotive specialists.
- CSRD reporting services:The EU's Corporate Sustainability Reporting Directive is generating demand for Scope 3 emissions tracking and supply chain transparency as billable consulting layers.
- Autonomous mobile robot convergence:Integration of AMR fleets with warehouse management systems is collapsing labor cost structures in high-throughput e-commerce operations.
Industry Challenges
- WMS-ERP integration complexity:Synchronizing warehouse management platforms with client enterprise resource planning systems demands specialized IT talent that commands premium compensation.
- GDP certification timelines:Pharmaceutical Good Distribution Practice compliance requires 12-18 month facility validation periods that delay revenue recognition on new cold chain contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contract Logistics Market |
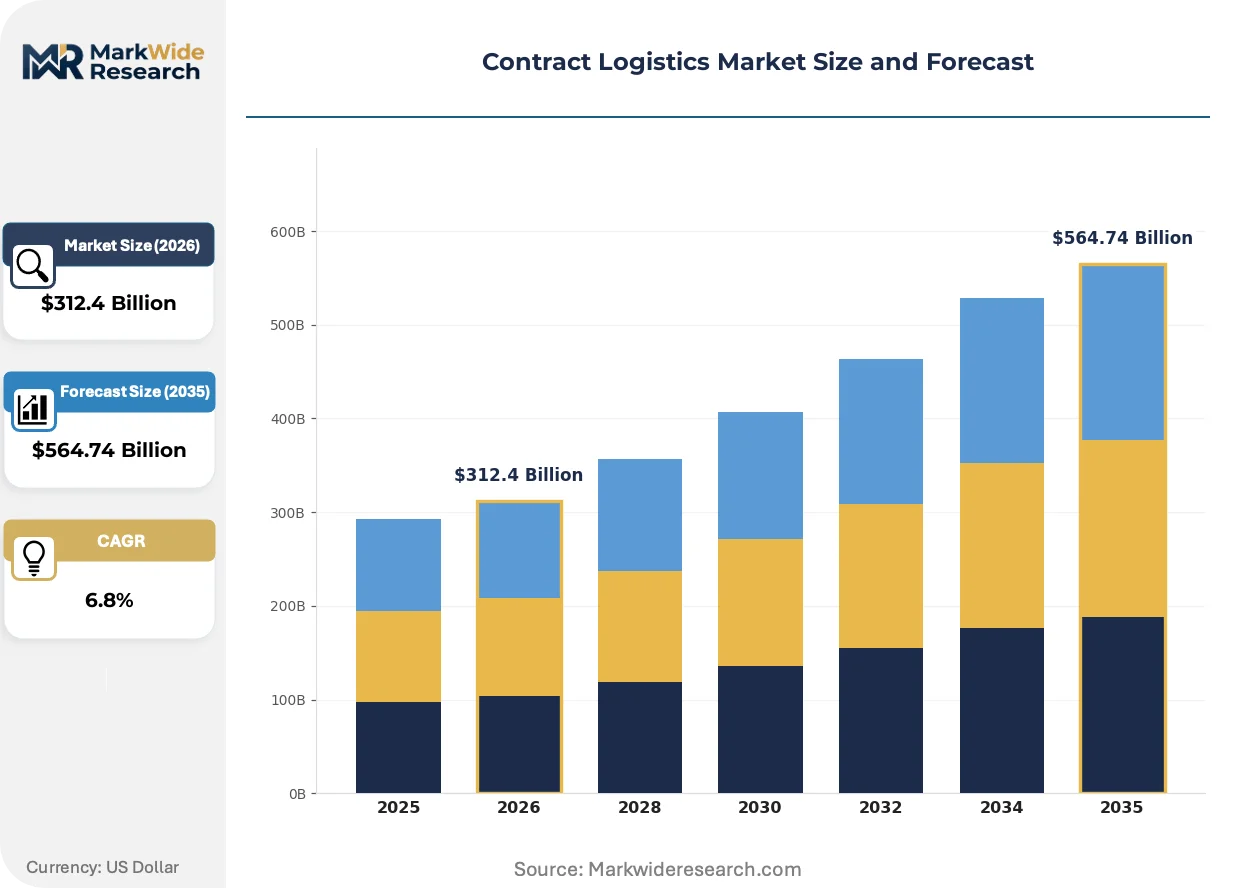
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $564.74 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Distribution, Freight Forwarding Industry Vertical: Retail, Automotive, Pharmaceuticals, Consumer Goods Delivery Model: Dedicated, Shared, Integrated, Global End User: Manufacturers, E-commerce, Wholesalers, Third-party Providers |
| Companies Covered | DHL Supply Chain, GXO Logistics, Kuehne + Nagel, DB Schenker, CEVA Logistics, United Parcel Service, DSV, Nippon Express, GEODIS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contract Logistics Market Emerging Trajectories
Digital twin technology is collapsing the information lag between physical inventory positions and planning systems, enabling real-time reconfiguration of fulfillment networks as demand signals shift.
Autonomous mobile robots are collapsing labor cost differentials between high-wage and low-wage logistics markets. E-commerce operators in Germany and Japan are deploying AMR fleets at accelerating velocity as unit economics converge with manual picking. This compression is enabling near-shoring of fulfillment capacity without sacrificing throughput efficiency.
The EU's Corporate Sustainability Reporting Directive is mandating granular Scope 3 emissions disclosure across supply chains. Logistics providers must now deploy carbon accounting infrastructure that tracks every transport leg and warehouse energy input. Pharmaceutical and automotive verticals face the steepest compliance curves as their customers face downstream reporting obligations.
Direct-to-consumer order patterns are fragmenting batch sizes and compressing delivery windows. Retailers are unbundling regional distribution center networks into smaller urban fulfillment nodes positioned for same-day service. This restructuring is most visible in China's Yangtze River Delta, where platform operators are securing dedicated warehouse capacity ahead of competitors.
Contract Logistics Market Segmentation
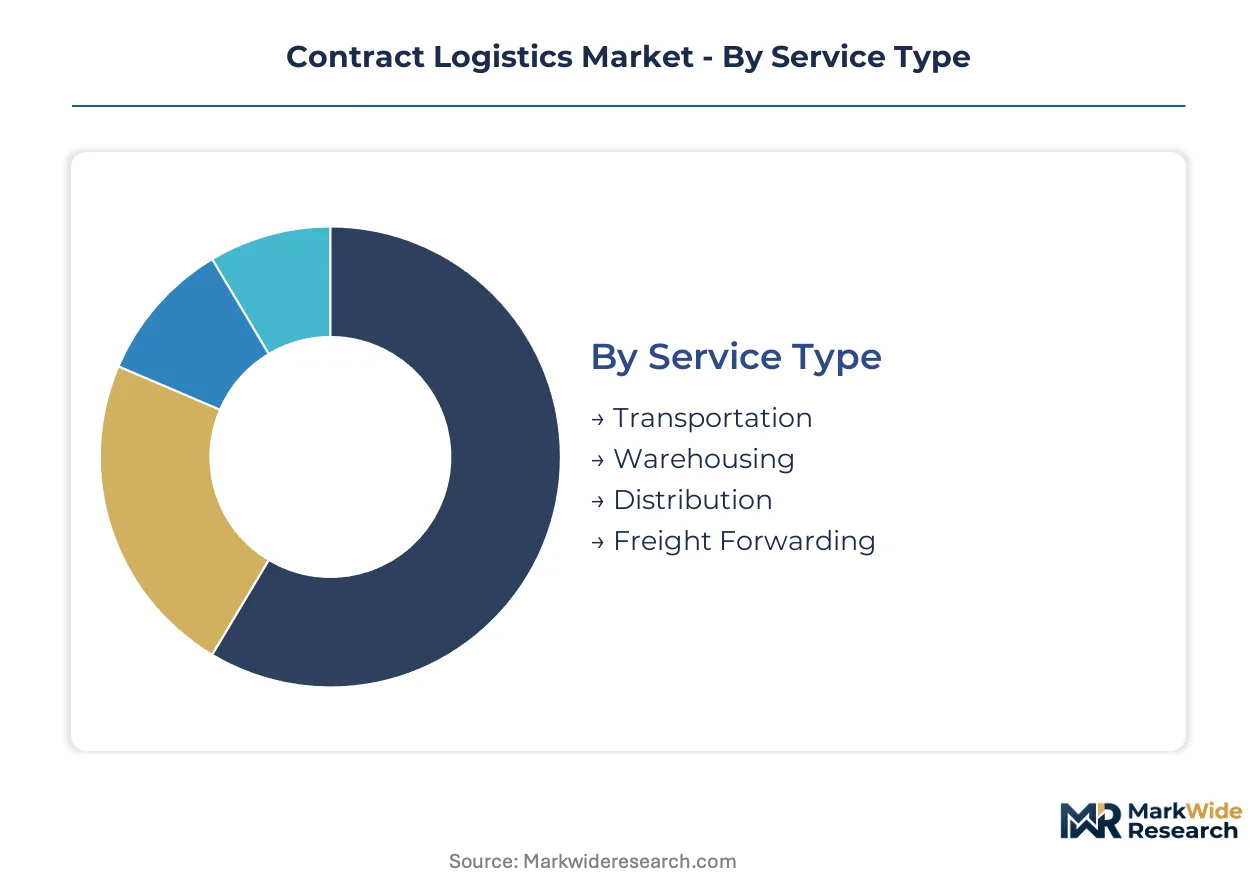
Contract logistics segmentation reveals divergent capital intensity and margin profiles across service types and delivery models. Cycle time differentials between inventory-heavy warehousing and transaction-focused freight forwarding dictate distinct pricing architectures and contract structures.
Service Type:
Transportation cycles inventory through networks within hours to days, while warehousing locks capital into multi-year lease commitments and automation infrastructure.
- Transportation:Fleet-based movement of goods across road, rail, air, and ocean modes with asset-light brokerage models competing against owned-asset operators. Automotive manufacturers in Germany are outsourcing inbound battery supply chains to specialized providers capable of handling UN 38.3 dangerous goods protocols.
- Warehousing:Long-term facility leases with automated storage and retrieval systems capturing margin premiums through throughput density. China's e-commerce fulfillment networks are absorbing dedicated warehouse capacity within two-hour delivery radii of Tier-1 city centers.
- Distribution:Consolidated last-mile delivery networks serving multiple clients through shared sorting infrastructure.
- Freight Forwarding:Cross-border documentation and carrier procurement with minimal fixed asset requirements.
Warehousing anchors the volume base while freight forwarding gains share at the steepest rate as near-shoring fragments traditional ocean freight corridors.
Industry Vertical:
Vertical specialization separates premium-priced compliance-heavy segments from scale-driven commodity services.
- Retail:High-velocity fulfillment networks demanding same-day delivery capability with seasonal volume spikes. Platform operators in China's Yangtze River Delta are securing dedicated urban warehouse capacity ahead of competitors.
- Automotive:Inbound supply chain synchronization with just-in-sequence delivery to assembly lines. German manufacturers are collapsing traditional logistics models as battery supply chains require temperature-controlled handling and reverse logistics infrastructure distinct from combustion-era component flows.
- Pharmaceuticals:GDP-compliant cold chain infrastructure with serialized track-and-trace verification.
- Consumer Goods:Shared distribution networks capturing scale economics through consolidated delivery routes.
Retail commands the largest revenue pool while pharmaceuticals expands most quickly on FDA Drug Supply Chain Security Act enforcement.
Delivery Model:
Asset dedication levels determine contract duration, pricing flexibility, and customer concentration risk exposure.
- Dedicated:Exclusive facility and fleet allocation with multi-year contractual minimums. Automotive OEMs in Germany are mandating dedicated battery logistics corridors to isolate supply chain risk from competitor access.
- Shared:Multi-client consolidation with variable throughput pricing and lower switching costs. China's e-commerce platforms are rejecting shared models for high-value electronics categories demanding inventory segregation.
- Integrated:End-to-end control tower services spanning planning, execution, and visibility layers.
- Global:Network coverage across three or more continents with standardized service level agreements.
Dedicated contracts lock in the highest margin contribution while integrated models climb the fastest as shapers seek single-accountability structures.
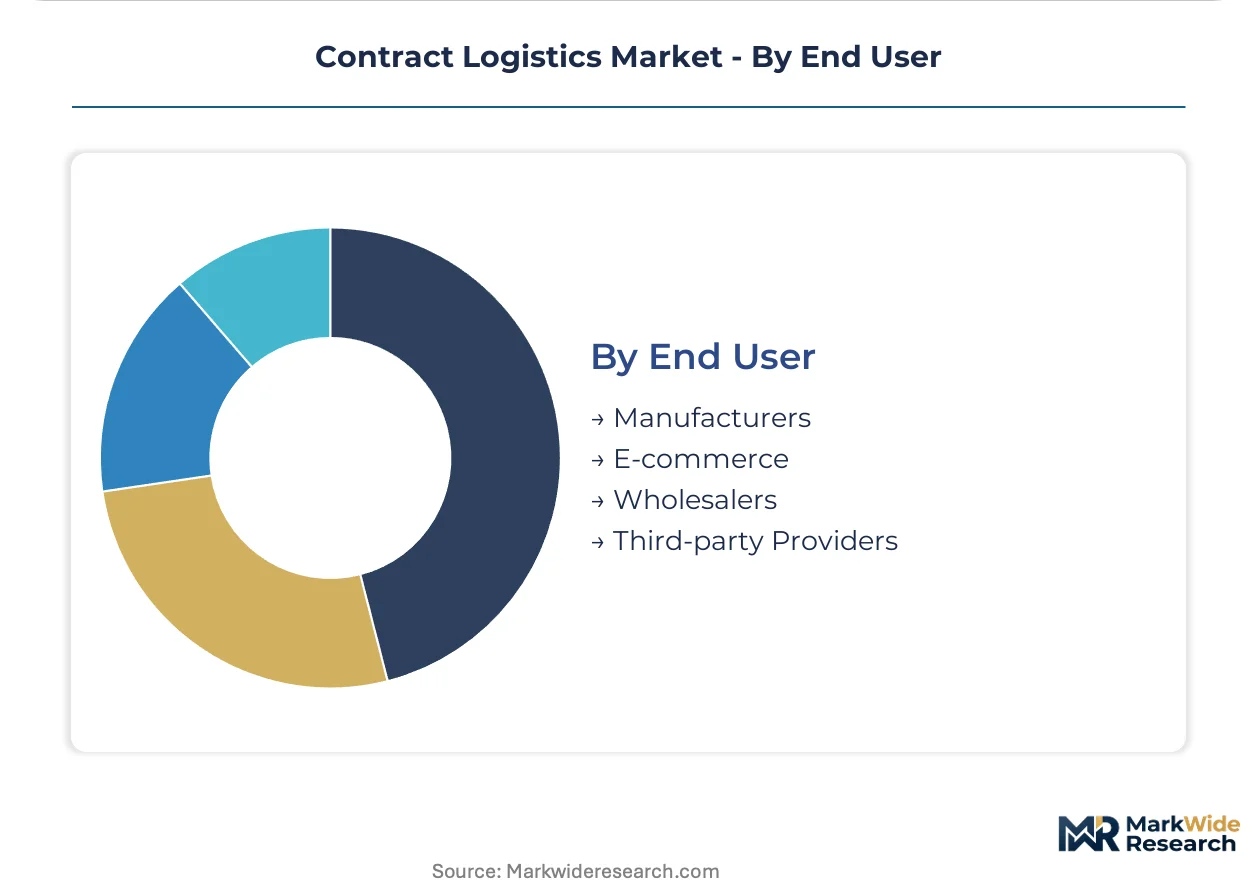
End User:
Procurement sophistication and volume scale separate enterprise-grade requirements from fragmented mid-market demand.
- Manufacturers:Production-integrated logistics with warehouse management systems synchronized to enterprise resource planning platforms. German automotive producers are requiring real-time inventory visibility as electrification collapses traditional component flow patterns.
- E-commerce:Direct-to-consumer fulfillment with compressed delivery windows and high return volumes. Chinese platform operators are absorbing unprecedented capital into urban warehouse construction within two-hour delivery radii.
- Wholesalers:Pallet-in-case-out distribution with batch-oriented replenishment cycles.
- Third-party Providers:Subcontracted capacity layers with price-taker positioning in oversupplied corridors.
Manufacturers anchor contract duration while e-commerce drives the steepest capacity expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR's dual carbon goals are accelerating warehouse electrification mandates across China's logistics corridors. Contract logistics capacity is concentrating in manufacturing clusters where automotive and e-commerce demand intersect with regulatory compliance deadlines.
China
E-commerce fulfillment density is absorbing unprecedented warehouse construction capital in the Yangtze River Delta. MEE emissions tracking requirements are forcing platform operators to retrofit existing facilities with renewable energy systems. Shanghai and Hangzhou are anchoring dedicated two-hour delivery radius networks for consumer electronics.
Germany
Automotive electrification is collapsing traditional inbound logistics models as battery supply chains demand temperature-controlled handling. KBA fleet certification standards under the EU Green Deal are accelerating last-mile vehicle electrification investments. The Rhine-Ruhr corridor is experiencing acute prime logistics land scarcity, inflaming lease rate volatility.
United States
Pharmaceutical serialization infrastructure is expanding under FDA Drug Supply Chain Security Act enforcement. EPA Clean Air Act emissions standards are reshaping capital deployment for last-mile fleet operators. The Midwest automotive belt is requiring real-time inventory visibility as electrification disrupts component flow patterns.
India
Manufacturing-led growth is outpacing organized logistics capacity, creating first-mover advantages for temperature-controlled specialists. BIS warehouse safety standards are influencing automation adoption thresholds for material handling equipment. Gujarat and Maharashtra are absorbing dedicated automotive and pharmaceutical distribution investments.
Netherlands
CSRD reporting services are generating billable demand for Scope 3 emissions tracking and supply chain transparency. REACH chemical handling protocols are elevating infrastructure requirements for hazardous goods corridors. The Randstad logistics cluster is facing prime land scarcity that is compressing facility development timelines.
Contract Logistics Market Vendor Landscape
Integrated control tower providers and specialized vertical operators split the market into distinct competitive arenas. Consolidation pressure is intensifying as scale economics favor operators with multi-continent network coverage. Three archetypes dominate: pan-regional integrators with standardized service level agreements, vertical specialists commanding premium pricing through compliance-heavy infrastructure, and automation-first operators competing on robotic throughput density. M&A activity targets last-mile capacity in urban corridors, while strategic partnerships secure scarce real estate positions ahead of competitors.
Within the integrated tier, DHL Supply Chain and Kuehne + Nagel occupy positions as archetype anchors for automotive and pharmaceutical verticals respectively. GXO Logistics exemplifies the automation-first vector, competing on warehouse robotics deployment density. These three entities represent the strategic positioning spectrum: geographic breadth, compliance depth, and operational velocity.
| Leading Market Players |
|---|
| DHL Supply Chain |
| GXO Logistics |
| Kuehne + Nagel |
| DB Schenker |
| CEVA Logistics |
| United Parcel Service |
| DSV |
| Nippon Express |
| GEODIS |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on China's Yangtze River Delta warehouse corridor determines both tiered pricing spreads across dedicated versus shared facility models and supply chain shape as operators cluster automation capex in this zone. Lease rate volatility in Germany's Rhine-Ruhr corridor and the Netherlands' Randstad feeds back into contract duration decisions, with automotive OEMs accepting premium dedicated pricing to isolate supply chain risk.
Pricing Analysis
China commands 15-25% facility cost premiums over India's emerging logistics clusters. Three-tier pricing structure across premium GDP-certified cold chain, standard automated warehousing, and economy manual operations differentiates the market. Cost compression in economy tiers is intensifying because e-commerce platforms demand same-day delivery infrastructure without corresponding rate increases. Mid-market manufacturers exhibit highest price sensitivity, while pharmaceutical multinationals prioritize compliance over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with DHL Supply Chain, GXO Logistics, and Kuehne + Nagel anchoring capacity across China, Germany, and the United States. Warehouse robotics, lithium-ion battery handling infrastructure, and carbon accounting software draw from specialized vendor ecosystems. Single-source vulnerability concentrates in China's Tier-1 city land positions where platform operators have secured multi-year exclusives. Distribution runs through hub-and-spoke networks with urban micro-fulfillment nodes multiplying last-mile density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The contract logistics market tracks automotive production cycles, with electrification capital expenditure waves now driving recovery momentum after inventory destocking troughs.
For Market Incumbents: Build compliance infrastructure moats through GDP certification and CSRD reporting capability stacks. Integrate carbon accounting software layers to capture Scope 3 consulting revenue as EU mandates deepen. Automate warehouse management system deployments to defend against robotics-native challengers eroding labor cost advantages. For New Entrants and Emerging Players: India's temperature-controlled pharmaceutical corridors represent the most penetrable entry point given organized capacity shortages against manufacturing growth. Target automotive battery logistics specialists in Gujarat and Maharashtra where UN 38.3 handling expertise remains scarce. Lead with AMR-integrated facility designs to bypass legacy labor cost structures. For Investors and Strategic Acquirers: EU Green Deal fleet mandates reshape the acquisition landscape toward electrified last-mile operators with validated KBA certifications. Five-to-ten-year viability favors automation-first warehouse platforms with scalable robotics architectures. Monitor SAMR dual carbon enforcement timelines as inflection signal for Chinese asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| AMR Fleet Deployment | GXO Logistics demonstrates robotic throughput density collapsing labor cost differentials across high-wage markets. |
| Cold Chain Certification | Kuehne + Nagel's GDP infrastructure captures pharmaceutical serialization premiums under FDA enforcement. |
| Carbon Accounting Integration | CSRD reporting services generate billable Scope 3 transparency layers for EU automotive clients. |
| Urban Micro-Fulfillment | DHL Supply Chain anchors two-hour delivery radius networks in China's Yangtze River Delta corridor. |
| Battery Logistics Specialization | UN 38.3 handling protocols isolate automotive electrification revenue from commoditized transport segments. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K logistics segment disclosures, EU emissions registry filings, and automotive production databases. Interviews with warehouse operations directors, pharmaceutical supply chain managers, e-commerce fulfillment planners, and fleet electrification specialists informed demand-side validation. Bottom-up facility capacity modeling and top-down macroeconomic triangulation anchored market sizing across the analysis window.
Forecast inputs include service type segmentation, industry vertical specialization tiers, delivery model dedication levels, and end-user procurement sophistication gradients. Modeled dimensions span transportation, warehousing, distribution, and freight forwarding with geographic production cluster overlays. CAGRs derive from regression analysis against automotive output, e-commerce penetration curves, and pharmaceutical serialization compliance deadlines.
Stress conditions across lithium-ion handling regulation timelines, prime logistics land availability, and AMR deployment cost curves were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on electrification capex cycles and warehouse automation adoption thresholds. Quarterly review of EU Green Deal enforcement velocity and SAMR dual carbon mandate progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Netherlands Cold Chain Logistics Market
Logistics and Shipping
Russia 3PL Market
Logistics and Shipping
Germany Dangerous Goods Logistics Market
Logistics and Shipping
Europe less-Than Container Load Market
Logistics and Shipping
Latin America Contract Logistics Market
Logistics and Shipping
California Freight and Logistics Market
Logistics and Shipping
Global Connected Logistics Market
Logistics and Shipping
Europe Third Party Logistics Market
Logistics and Shipping
Colombia Freight and Logistics Market
Logistics and Shipping
Airfreight Forwarding Market
Logistics and Shipping
North America Logistics Automation Market
Logistics and Shipping
Egypt 3PL Market
Logistics and Shipping
Asia Pacific (APAC) Contract Logistics Market
Logistics and Shipping
Chile Air Freight Transport Market
Logistics and Shipping
Fleet of Containers Market
Logistics and Shipping
Multicarrier Shipping Software Market