
 North America Refrigerated Container Shipping Market | 2026-2036
North America Refrigerated Container Shipping Market Size, Share, and Industry Trends Forecast 2026-2036
North America Refrigerated Container Shipping Market Insights
The EPA's AIM Act refrigerant phasedown is expanding compliance obligations across North American reefer fleets. A.P. Moller – Maersk leverages its integrated cold-chain infrastructure to sustain trans-Pacific pharmaceutical lanes. CMA-CGM anchors capacity deployment through dedicated reefer services on Latin America–U.S. routes. Hapag-Lloyd differentiates via real-time cargo monitoring systems that compete on traceability.
Refrigerated container shipping denotes the maritime transport of temperature-sensitive cargo in insulated, mechanically cooled intermodal boxes typically maintaining ranges from minus thirty degrees Celsius to plus thirty degrees Celsius through integrated compressor-evaporator units. Reefer containers dominate installed base volumes while advanced refrigeration units command premium positioning amid pharmaceutical sector compliance requirements. The food industry end-user segment absorbs the largest throughput share, though pharmaceutical sector demand accelerates fastest on biologics cold-chain expansion. Third-party logistics channels intermediate the majority of contracted reefer movements, with direct shipping relationships consolidating among multinational agricultural exporters.
The U.S. Coast Guard enforces container safety regulations under the International Convention for Safe Containers, while Transport Canada administers equivalent standards through its marine safety directorate. The FDA's Food Safety Modernization Act and the Sanitary Food Transportation Act jointly mandate temperature documentation across domestic and import reefer movements. Stakeholders must monitor refrigerant technology transitions, port cold-storage congestion, and evolving pharmaceutical validation protocols to secure positioning.
Market Dynamics
The EPA's phasedown of hydrofluorocarbon refrigerants under the AIM Act is forcing fleet-wide retrofits across North American reefer operations, compressing capital deployment timelines while elevating compliance costs for container lessors and vessel operators.
Growth Catalysts
- Pharmaceutical cold-chain expansion:Biologics manufacturers are widening adoption of temperature-controlled maritime transport for high-value injectables requiring strict thermal validation from manufacturing sites to distribution hubs.
- Texas-Louisiana petrochemical corridor concentration:Specialty chemical exporters along the U.S. Gulf Coast are expanding refrigerated container bookings for temperature-sensitive polymer intermediates and catalyst precursors.
- FDA Food Safety Modernization Act enforcement:Temperature documentation mandates for import and domestic reefer movements are tightening carrier liability standards and driving demand for certified cold-chain infrastructure.
Market Restraints
- Refrigerant input cost volatility:Transition to lower-global-warming-potential cooling systems is elevating unit retrofit expenses and compressing lessor margins on aging container fleets.
- Port cold-storage congestion:Limited refrigerated yard capacity at major North American gateways is extending dwell times and degrading cargo integrity for time-sensitive perishables.
- Technical limitation in battery-backed reefers:Current energy storage density constraints restrict autonomous operation duration, constraining deployment on routes with unreliable shore power infrastructure.
Strategic Opportunities
- Mexican produce export growth:Avocado and berry shippers in Michoacán and Jalisco are expanding refrigerated container contracting for direct U.S. Midwest distribution, bypassing traditional transshipment points.
- Real-time cargo monitoring convergence:Integration of IoT sensors with blockchain verification protocols is creating premium service tiers for pharmaceutical validation requirements.
- Canadian federal carbon pricing trajectory:Escalating carbon cost obligations on marine fuel are incentivizing shore-power-equipped reefer investments at Vancouver and Prince Rupert terminals.
Industry Challenges
- Refrigeration technician scarcity:Specialized marine HVAC certification programs are failing to match fleet expansion rates, extending maintenance backlogs during peak shipping seasons.
- Legacy fleet integration complexity:Retrofit of next-generation cooling units onto twenty-foot equivalent units with aged electrical architectures is requiring custom engineering and elongating deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Refrigerated Container Shipping Market |
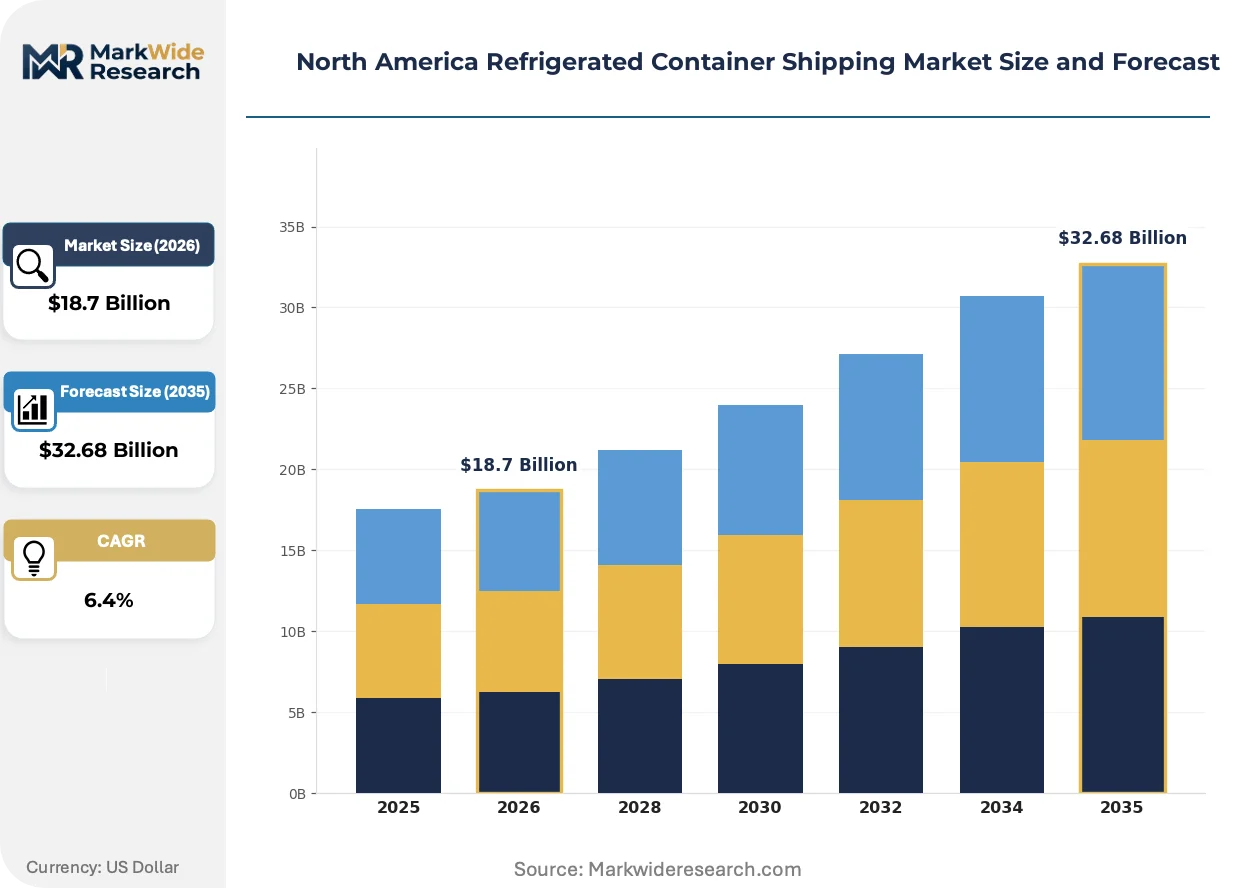
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Container Type: Reefer Containers, Insulated Containers, Thermo-Controlled Containers, Advanced Refrigeration Units End User: Food Industry, Pharmaceutical Sector, Agriculture Products, Chemical Manufacturers Temperature Control: Chilled, Frozen, Ambient, Deep Frozen Distribution Channel: Direct Shipping, Third-party Logistics, Freight Forwarders, Others |
| Companies Covered | Mediterranean Shipping Company (MSC), A.P. Moller – Maersk, CMA-CGM, Hapag-Lloyd, Mulder Brothers, SeaCube Container Leasing Ltd., Ocean Network Express Pte. Ltd., Seaco Srl, Almar Container Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Refrigerated Container Shipping Market Trends and Innovations
Refrigerated container operations are undergoing hardware and software transformation simultaneously, with regulatory pressure on refrigerants intersecting with pharmaceutical-grade traceability demands.
Advanced compressor-evaporator units utilizing CO2 transcritical cycles are penetrating North American reefer fleets. Pharmaceutical logistics providers are adopting these systems fastest to preempt EU F-Gas Regulation alignment pressures. The technology is converging with blockchain-based temperature logging to create auditable custody chains for biologics shipments.
Transport Canada's marine safety directorate is tightening enforcement of refrigerated container inspection protocols under updated International Convention for Safe Containers implementation guidelines. Carrier compliance costs are rising for pre-trip inspection documentation and refrigerant leak detection certification. The Port of Vancouver's perishables gateway is responding with dedicated reefer maintenance facilities to reduce inspection failure rates.
Direct contracting between multinational agricultural exporters and vessel operators is displacing traditional third-party logistics intermediation for high-volume refrigerated lanes. Berry and stone-fruit shippers in California's Central Valley are negotiating multi-year slot charters with dedicated reefer services. This pattern is most visible on Latin America–U.S. routes where cargo owners seek volume certainty over spot-market flexibility.
North America Refrigerated Container Shipping Market Segmentation
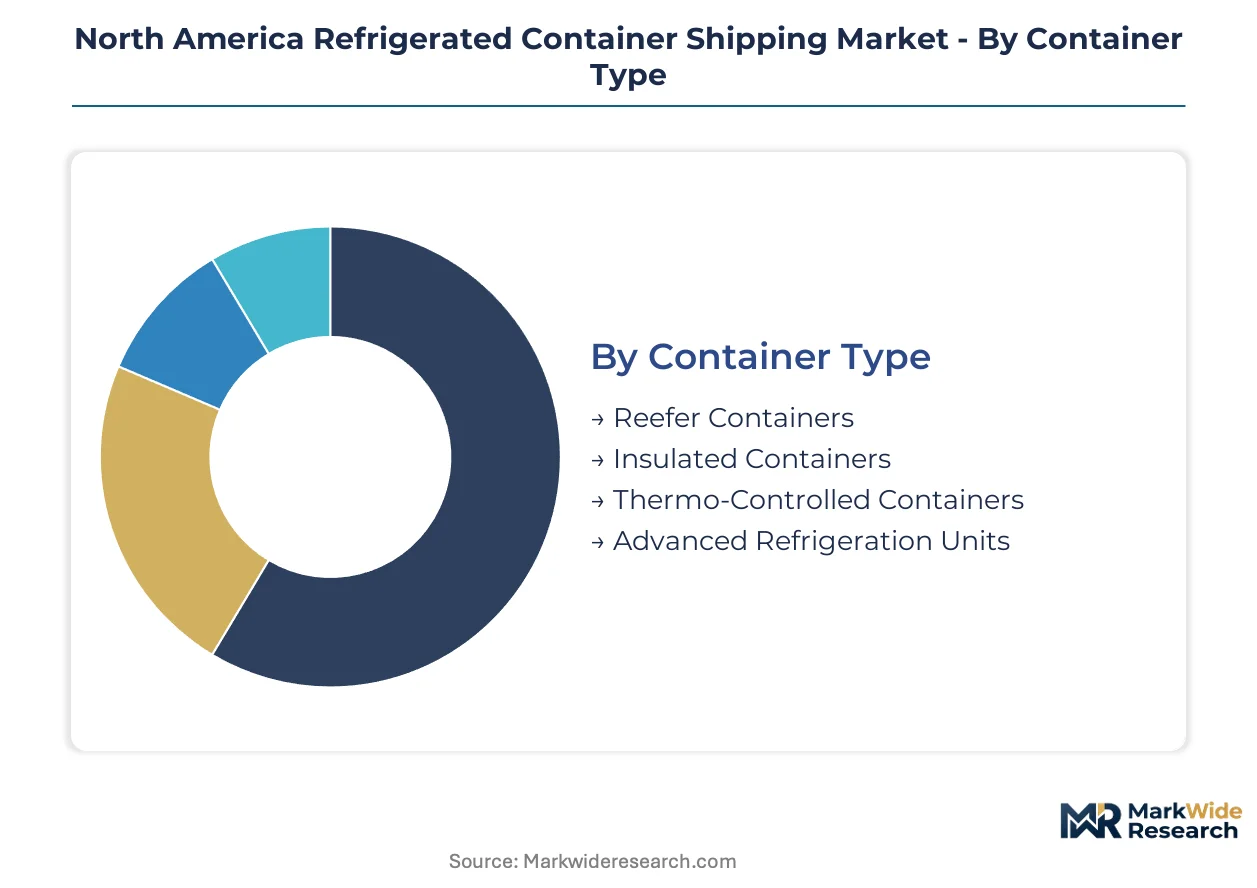
Refrigerated container shipping segmentation reveals how cargo characteristics dictate equipment specifications, regulatory compliance burdens, and channel economics across North American trade lanes. Understanding these divisions exposes where capital deployment concentrates and where margin compression threatens.
Container Type:
Supply concentration in mechanical reefer units shapes fleet investment patterns, with specialized cooling technologies commanding premium positioning amid EPA refrigerant phasedown timelines.
- Reefer Containers:Mechanically cooled intermodal boxes with integrated compressor-evaporator systems maintaining minus thirty to plus thirty degrees Celsius. Demand concentrates along the Texas-Louisiana petrochemical corridor for temperature-sensitive polymer intermediates, with Gulf Coast exporters booking dedicated reefer slots to bypass transshipment delays.
- Advanced Refrigeration Units:Next-generation systems utilizing CO2 transcritical cycles and lower-global-warming-potential refrigerants. Pharmaceutical logistics providers in California and New Jersey are adopting these fastest to preempt EU F-Gas Regulation alignment pressures and secure FDA validation documentation.
- Insulated Containers:Passive thermal protection without active mechanical cooling, suitable for short-haul ambient cargo movements.
- Thermo-Controlled Containers:Hybrid systems combining insulation with limited active temperature management for moderate-duration voyages.
Today's leader: Reefer Containers. Tomorrow's challenger: Advanced Refrigeration Units.
End User:
Cost tier stratification separates commodity perishables from high-value pharmaceutical cargo, with validation requirements driving equipment specification divergence.
- Food Industry:The largest throughput segment spanning fresh produce, meat, seafood, and dairy products requiring continuous cold-chain integrity. Berry and stone-fruit shippers in California's Central Valley are negotiating multi-year slot charters with dedicated reefer services to secure volume certainty over spot-market flexibility.
- Pharmaceutical Sector:Biologics manufacturers requiring strict thermal validation from manufacturing sites to distribution hubs, with blockchain-based temperature logging creating auditable custody chains. This segment climbs the fastest on injectables cold-chain expansion and FDA enforcement tightening.
- Agriculture Products:Grain, seeds, and nursery stock requiring humidity-controlled environments distinct from food-grade specifications.
- Chemical Manufacturers:Specialty chemical exporters along the U.S. Gulf Coast expanding refrigerated container bookings for catalyst precursors and polymer intermediates.
Food Industry absorbs current volume. Pharmaceutical Sector captures expanding margin.
Temperature Control:
Application-specific thermal bands determine compressor sizing, energy consumption profiles, and shore power infrastructure requirements at North American gateways.
- Frozen:Minus eighteen degrees Celsius standard for meat, seafood, and prepared foods, commanding the largest installed base of mechanical reefer units.
- Chilled:Zero to four degrees Celsius for fresh produce and dairy, with the Port of Vancouver's perishables gateway investing in dedicated reefer maintenance facilities to reduce inspection failure rates.
- Deep Frozen:Below minus thirty degrees Celsius for pharmaceutical cold-chain and specialty chemicals, requiring enhanced insulation and compressor capacity.
- Ambient:Controlled temperature above fifteen degrees Celsius for sensitive non-refrigerated cargo, primarily utilizing insulated containers.
Frozen dominates fleet deployment. Deep Frozen commands steepest expansion trajectory.
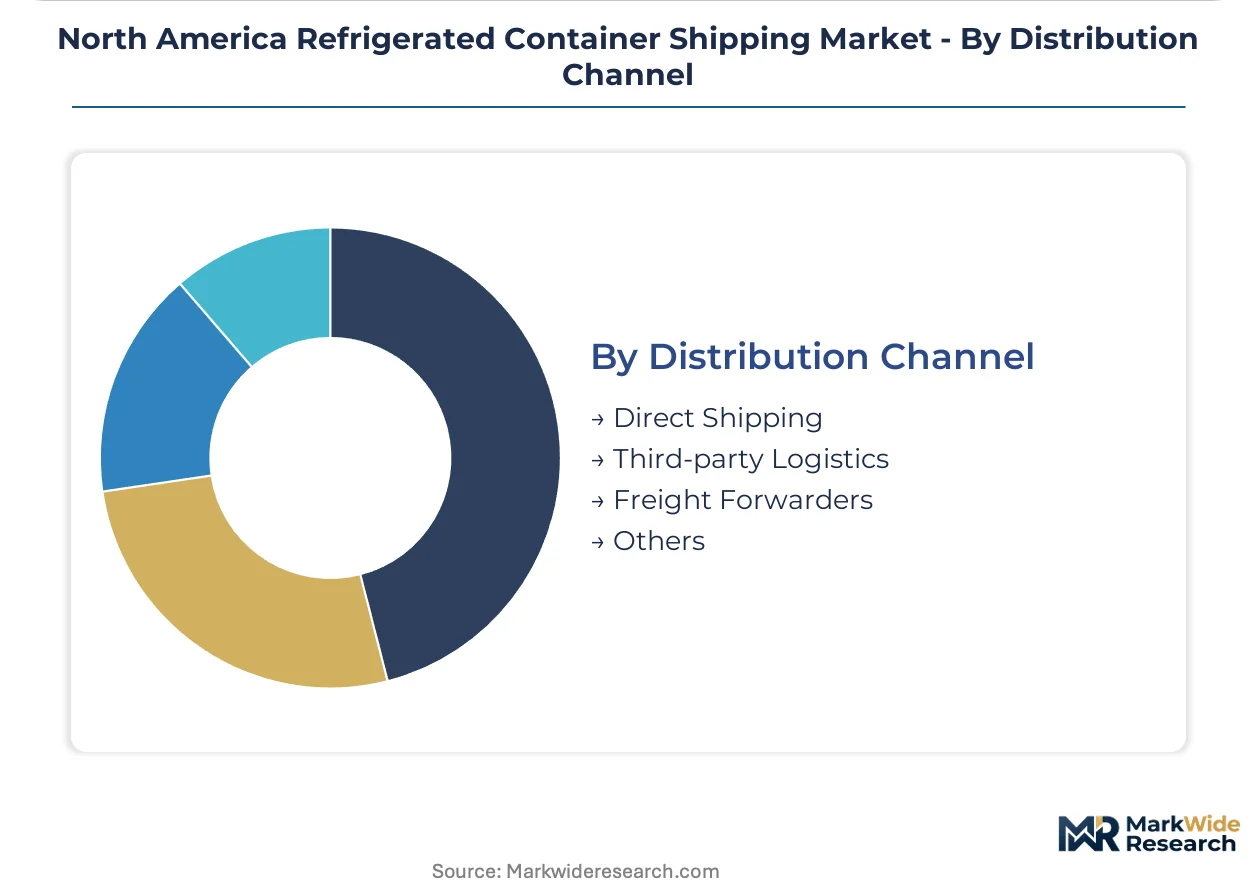
Distribution Channel:
Customer type evolution is displacing traditional intermediation, with direct contracting consolidating among multinational agricultural exporters seeking supply chain control.
- Third-party Logistics:Cold-chain specialists intermediate the majority of contracted reefer movements, offering consolidated booking power and regulatory compliance management. Mexican produce exporters in Michoacán and Jalisco leverage 3PL networks for direct U.S. Midwest distribution.
- Direct Shipping:Multinational agricultural exporters negotiate vessel-operator relationships directly, bypassing intermediary margins on high-volume lanes.
- Freight Forwarders:Transactional booking agents aggregating smaller shipper volumes into consolidated reefer slots.
- Others:Niche channels including cooperative shipping arrangements and captive logistics operations.
Third-party Logistics holds current share. Direct Shipping gains fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refrigerated container shipping scaled from post-war California produce exports and Texas petrochemical corridors, with regulatory frameworks evolving from voluntary industry standards to EPA and FDA mandates governing transcontinental cold-chain integrity.
United States
California's Central Valley berry shippers and Texas-Louisiana petrochemical exporters drive refrigerated container demand through dedicated reefer slot charters. The FDA's Food Safety Modernization Act enforces temperature documentation across import and domestic movements. The Port of Long Beach maintains specialized reefer maintenance facilities to reduce inspection failure rates during peak produce seasons.
Canada
British Columbia's seafood processors and Alberta's meat exporters anchor Pacific reefer throughput through Vancouver's perishables gateway. Transport Canada's marine safety directorate tightens refrigerated container inspection protocols under updated International Convention for Safe Containers guidelines. Prince Rupert terminals invest in shore-power infrastructure to meet federal carbon pricing obligations on marine fuel consumption.
Mexico
Michoacán avocado growers and Jalisco berry producers expand direct U.S. Midwest distribution through refrigerated container contracting. Mexican federal environmental standards align with EPA refrigerant phasedown timelines under USMCA harmonization pressures. Lázaro Cárdenas port authorities develop dedicated cold-storage yards to bypass traditional Los Angeles-Long Beach transshipment congestion.
Guatemala
Escuintla department banana and sugar exporters generate seasonal reefer demand through Puerto Quetzal's expanding perishables terminal. The country's national agricultural export regulator mandates cold-chain certification for EU-bound shipments under evolving sanitary protocols. Santo Tomás de Castilla port operators retrofit reefer plugging stations to accommodate pharmaceutical validation requirements for regional distribution.
North America Refrigerated Container Shipping Market Competitive Landscape
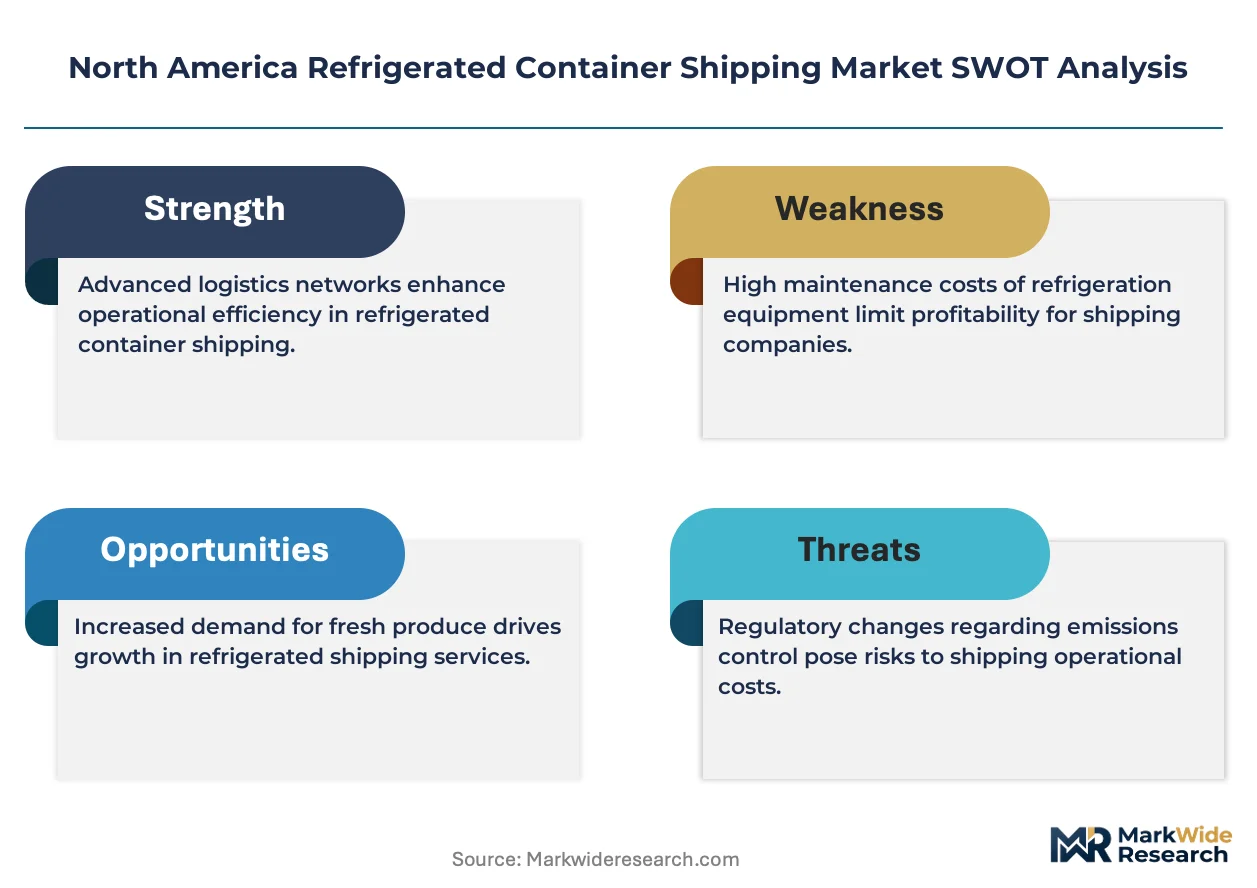
Capital-heavy vessel operators compete with asset-light container lessors across North American reefer markets, creating a tiered structure where integrated carriers control trans-Pacific lanes while specialized lessors dominate equipment financing. The market consolidates around three strategic archetypes: global liner conglomerates with dedicated cold-chain divisions, regional container leasing specialists, and integrated logistics providers offering end-to-end temperature validation. Dominant competitive moves include fleet-wide refrigerant retrofit programs and multi-year slot charter negotiations with agricultural exporters.
Among European-based integrated carriers, Mediterranean Shipping Company and A.P. Moller – Maersk occupy positions anchoring premium pharmaceutical lanes through controlled cold-chain infrastructure. German liner Hapag-Lloyd exemplifies the technology-differentiation archetype, with its positioning tied to real-time cargo monitoring capabilities. These three entities represent distinct competitive vectors: scale-driven network coverage, integrated logistics control, and digital traceability specialization.
| Leading Market Players |
|---|
| Mediterranean Shipping Company (MSC) |
| A.P. Moller – Maersk |
| CMA-CGM |
| Hapag-Lloyd |
| Mulder Brothers |
| SeaCube Container Leasing Ltd. |
| Ocean Network Express Pte. Ltd. |
| Seaco Srl |
| Almar Container Group |
| Others |
Pricing and Supply Chain Analysis
Multinational agricultural exporters in California's Central Valley and Michoacán are consolidating direct vessel-operator relationships, compressing intermediary margins and shifting pricing power toward volume-guaranteed contract structures over spot-market volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade validation services from commodity perishables and basic reefer slots. Price differentiation rests on FDA certification tier and real-time cargo monitoring integration, with pharmaceutical logistics providers showing least price sensitivity. Cost compression in standard-tier reefer slots is intensifying because EPA refrigerant retrofit obligations are elevating lessor operating expenses.
Supply Chain Analysis
USMCA domestic-content harmonization pressures are reshaping sourcing patterns for compressor-evaporator units and refrigeration components. Manufacturing concentrates in China, South Korea, and Mexico for cooling systems, while aluminum chassis and insulation materials draw from Canadian and U.S. Gulf Coast suppliers. Single-source vulnerability in semiconductor-dependent control modules threatens fleet retrofit timelines. Distribution runs through dedicated reefer maintenance facilities at Port of Vancouver and Port of Long Beach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refrigerated container shipping offers margin-expansion pathways through premium-tier pharmaceutical validation services and CO2 transcritical cooling system adoption, with fleet-wide refrigerant retrofits creating equipment refresh cycles that favor technology-differentiated lessors.
For Market Incumbents: Deepen integration with biologics manufacturers by securing FDA validation documentation capabilities and blockchain-based temperature logging infrastructure. Threats from specialized pharmaceutical cold-chain entrants require preemptive certification investments. Backward integration into shore-power infrastructure at Vancouver and Prince Rupert terminals captures federal carbon pricing advantages.
For New Entrants and Emerging Players: Third-party logistics intermediaries in Mexican produce corridors represent the most penetrable channel partner type for bypassing established carrier-direct relationships. White-space targets include Michoacán avocado shippers seeking dedicated Midwest distribution slots and Jalisco berry exporters requiring cold-chain certification for EU-bound shipments. Go-to-market positioning should emphasize real-time monitoring integration over commodity reefer slot pricing.
For Investors and Strategic Acquirers: Integrated logistics providers with pharmaceutical cold-chain capabilities are the most active acquirer in this space, consolidating equipment lessors and validation service specialists. Long-term viability favors asset-light technology platforms over capital-heavy vessel operations. Acquisition target archetypes include regional container lessors with EPA-compliant cooling unit inventories. The signal to watch is pharmaceutical sector slot charter contract duration extension above multi-year baselines.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Fleet Retrofit Program | EPA AIM Act compliance secures operating licenses across California and Gulf Coast corridors. |
| Pharmaceutical Validation Partnership | FDA documentation capabilities unlock biologics cold-chain premiums on trans-Pacific lanes. |
| Shore-Power Infrastructure Investment | Canadian federal carbon pricing obligations incentivize electrified reefer plugging at Vancouver terminals. |
| Direct Slot Charter Negotiation | Multinational agricultural exporters in Central Valley secure volume certainty over spot-market volatility. |
| IoT-Blockchain Integration Launch | Real-time temperature logging creates auditable custody chains for EU F-Gas Regulation alignment. |
Research Methodology
Multiple input streams — carrier fleet managers, pharmaceutical logistics executives, container lessor procurement leads, and port authority operations directors — were reconciled against customs trade data, EPA refrigerant phasedown filings, FDA Food Safety Modernization Act enforcement records, and Transport Canada marine safety directives. Secondary validation drew from vessel operator annual disclosures and refrigerated container equipment manufacturer technical specifications. Bottom-up equipment deployment estimates and top-down trade lane volume analysis were triangulated to establish market sizing.
Historical reefer slot pricing trends were cross-referenced against panel input from agricultural exporter procurement committees and 3PL contract negotiators. Segmentation modeling spanned container type, end-user industry, temperature control band, and distribution channel complexity across the projection horizon. CAGRs were derived from equipment refresh cycle analysis and pharmaceutical cold-chain throughput acceleration patterns. Forecast inputs incorporated EPA refrigerant phasedown compliance timelines and USMCA trade corridor expansion assumptions.
Revisions become necessary when EPA enforcement intensity exceeds modeled baselines, pharmaceutical validation protocol requirements shift, or port cold-storage congestion triggers dwell time degradation beyond cargo integrity thresholds. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Australia Freight and Logistics Market
Logistics and Shipping
Saudi Arabia Secure Logistics Market
Logistics and Shipping
United States 3PL Market
Logistics and Shipping
Refurbishment and Repair Logistics Orchestration Platforms Market
Logistics and Shipping
Poland Third Party Logistics (3PL) Market
Logistics and Shipping
High-Tech Logistics Market
Logistics and Shipping
Global Drone Logistics and Transportation Market
Logistics and Shipping
Canada Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Brazil Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Logistics Data Quality and Normalization Services Market
Logistics and Shipping
Inbound Logistics Market
Logistics and Shipping
United States Courier, Express and Parcel (CEP) Market
Logistics and Shipping
Central and Eastern Europe Freight and Logistics Market
Logistics and Shipping
Contract Logistics Market
Logistics and Shipping
South Korea Third-Party Logistics (3PL) Market
Logistics and Shipping
Saudi Arabia Integrated Cold Chain Logistics Market