
 Nigeria Third-Party Logistics (3PL) Market | 2026-2036
Nigeria Third-Party Logistics (3PL) Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Third-Party Logistics (3PL) Market Foresight
The National Agency for Food and Drug Administration and Control (NAFDAC) enforcement of cold-chain compliance for pharmaceuticals is recalibrating 3PL investment priorities across Nigeria. GIG Logistics leverages its nationwide hub network to dominate temperature-sensitive distribution corridors. SIFAX Logistics anchors its position through integrated port-to-warehouse operations at Lagos and Onne terminals. DHL International GmbH differentiates via customs brokerage depth and cross-border African lane specialization.
Third-party logistics encompasses the outsourcing of supply chain execution—encompassing freight movement, inventory storage, order fulfillment, and distribution coordination—to specialized providers operating under service-level agreements with defined key performance indicators. Nigeria's 3PL sector functions as critical commercial infrastructure, bridging fragmented domestic manufacturing with import-dependent consumption through multi-modal coordination. Warehousing services capture premium margins as bonded terminal scarcity and Lagos industrial land constraints elevate facility economics. E-commerce end users represent the fastest-expanding demand pool, with same-day and next-day fulfillment expectations forcing automation adoption across provider networks. Road delivery mode maintains volume leadership despite infrastructure degradation, while air freight commands outsized yields for high-value pharmaceuticals and electronics.
The Standards Organisation of Nigeria (SON) mandates product certification and quality verification for imported goods, directly shaping customs clearance timelines and bonded warehousing demand. The Federal Road Safety Corps (FRSC) axle-load regulations and driver certification requirements influence fleet composition and route economics for road-dominant operators. Stakeholders must weigh regulatory compliance costs against automation dividends as digital freight matching and warehouse management systems redefine competitive thresholds in Africa's largest consumer market.
Market Dynamics
The Central Bank of Nigeria's cashless policy and digital payment infrastructure push are fundamentally restructuring last-mile delivery requirements across the 3PL sector. E-commerce fulfillment complexity is accelerating outsourced logistics adoption as platforms demand same-day and next-day capabilities.
Growth Catalysts
- Lagos State industrial clustering:Port access and concentrated manufacturing create disproportionate logistics pull, generating economies of scale for providers operating within the corridor.
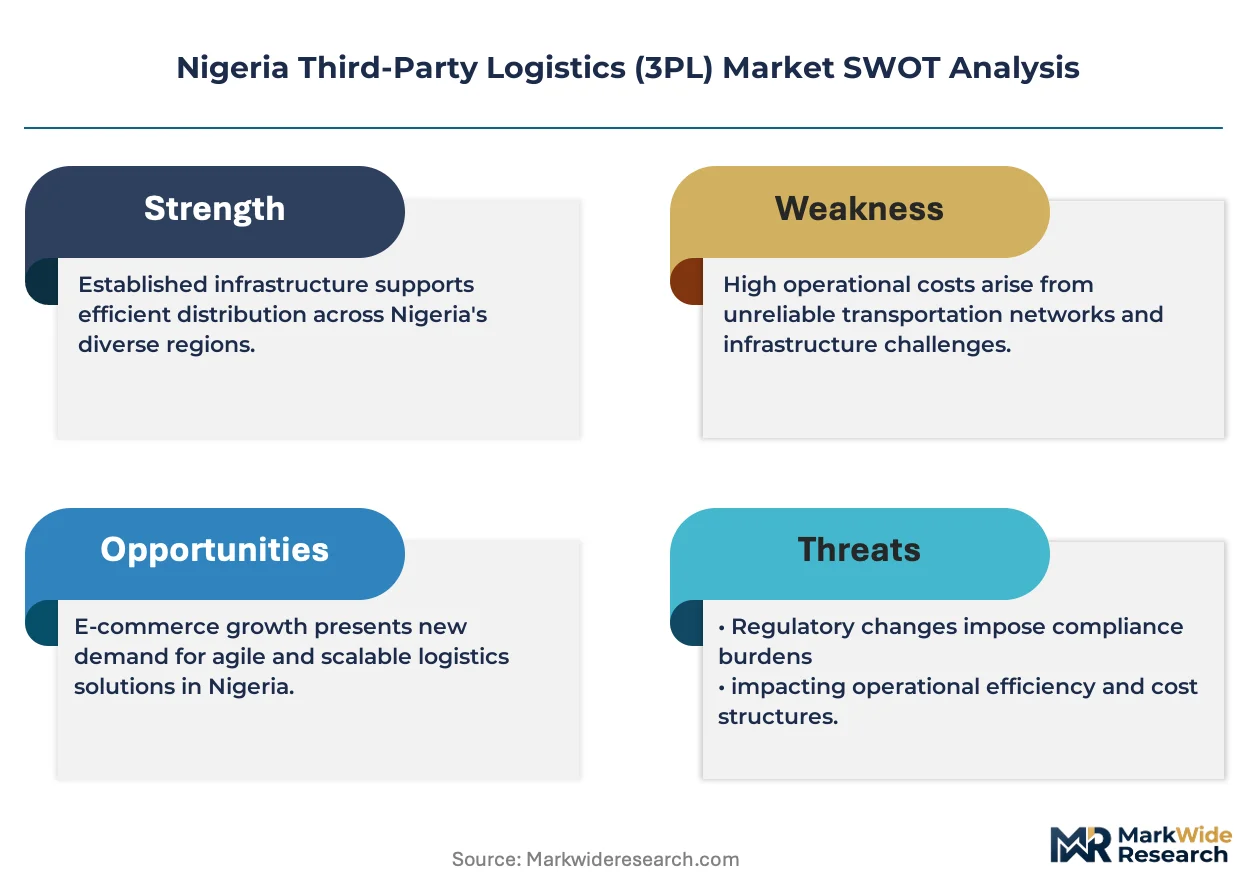
- NAFDAC cold-chain mandates:Enforcement of pharmaceutical temperature compliance is recalibrating investment priorities toward specialized warehousing and refrigerated fleet expansion.
- Digital freight matching platforms:Real-time load-board technologies are reducing empty backhaul miles and improving asset utilization rates across road-dominant operators.
Market Restraints
- Fuel price volatility:Diesel cost fluctuations directly compress margins for road-based operators who lack fuel surcharge pass-through mechanisms in contract structures.
- Bonded terminal scarcity:Limited availability of customs-bonded facilities at Lagos and Onne ports creates warehousing bottlenecks and extends clearance timelines.
- Axle-load enforcement variance:Inconsistent FRSC implementation across state boundaries forces fleet operators to maintain multiple vehicle configurations.
Strategic Opportunities
- Kano and northern corridor expansion:Underpenetrated inland markets offer first-mover advantages for providers establishing hub-and-spoke networks beyond Lagos concentration.
- Cross-border African lanes:ECOWAS trade facilitation protocols are opening land-bridge routes to Benin, Togo, and Ghana for integrated logistics operators.
- Automation convergence:Warehouse management systems paired with IoT-enabled inventory tracking are enabling real-time visibility that commands premium pricing from enterprise clients.
Industry Challenges
- Certified cold-chain technician scarcity:NAFDAC-compliant pharmaceutical handling requires specialized training that outpaces current vocational pipeline output.
- Legacy system integration friction:Enterprise shippers with SAP or Oracle environments demand API connectivity that smaller 3PLs struggle to provision.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Third-Party Logistics (3PL) Market |
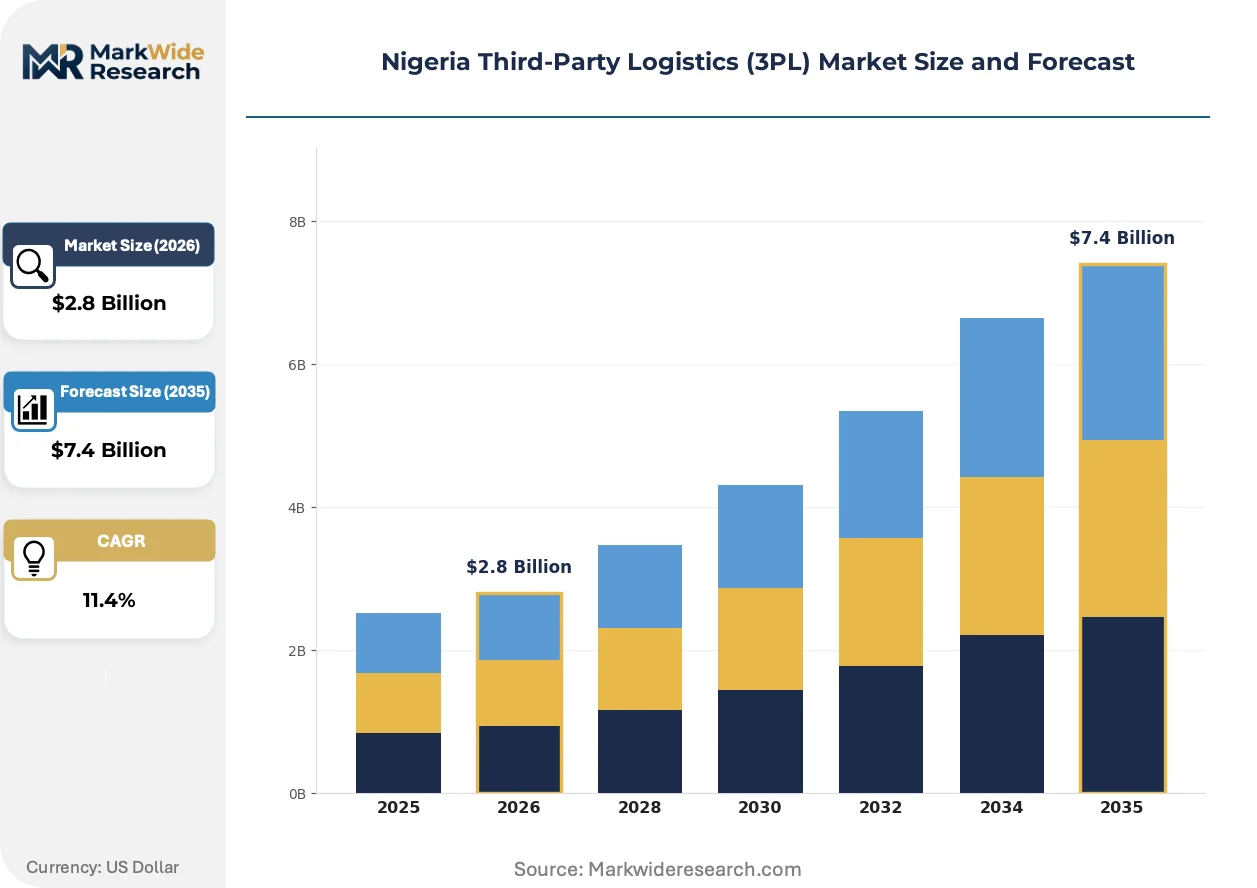
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Distribution End User: Retail, Manufacturing, Pharmaceuticals, E-commerce Technology: Software Solutions, Automation, Tracking Systems, Data Analytics Delivery Mode: Road, Rail, Air, Sea |
| Companies Covered | Creseada International Limited, SIFAX Logistics, DHL International GmbH, Redline Logistics, Aramex Nigeria, GIG Logistics, MDS Logistics, UPS Nigeria, Bollore Transport and Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Third-Party Logistics (3PL) Market Shifts & Advancements
Digital infrastructure investments are compressing fulfillment timelines while regulatory pressure on product integrity is elevating compliance technology spending. Three convergent developments are redefining competitive thresholds.
Telematics-enabled fleet management is unifying route optimization, driver behavior monitoring, and predictive maintenance into single-platform operations. E-commerce platforms with high shipment volumes are deploying these systems fastest, consolidating previously fragmented dispatch functions and reducing per-delivery costs through algorithmic load consolidation.
SON product certification mandates are extending customs clearance timelines and elevating demand for pre-inspection warehousing. Importers of electronics and consumer goods are responding by shifting toward bonded terminal operators with integrated inspection facilities, compressing the port-to-warehouse transfer window.
Same-day fulfillment expectations among Lagos-based e-commerce end users are compressing order-to-delivery cycles from 48-72 hours toward 4-8 hour windows. Fashion and electronics verticals are driving this most aggressively, forcing 3PLs to deploy micro-fulfillment nodes in urban districts rather than centralized suburban warehouses.
Nigeria Third-Party Logistics (3PL) Market Segmentation
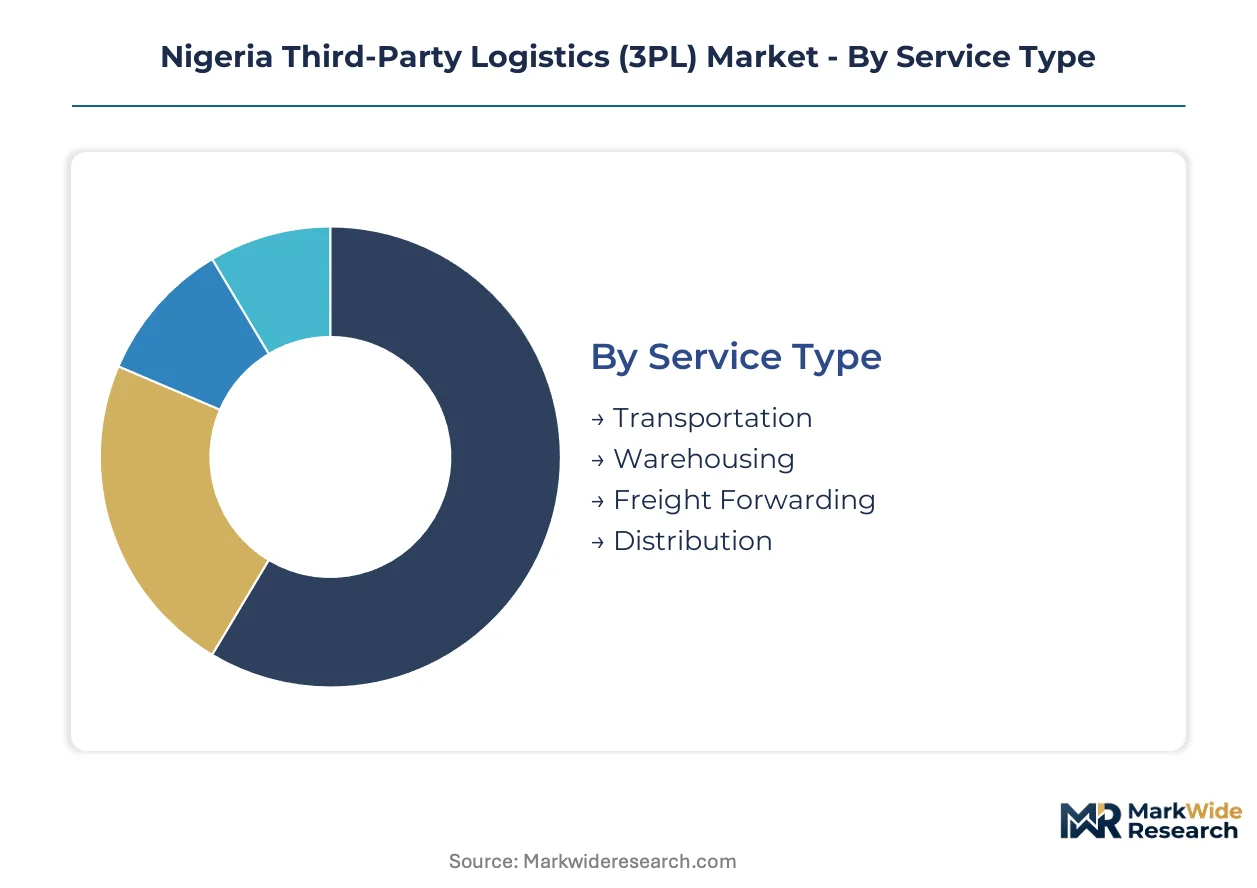
Service configuration determines margin structure and capital intensity across Nigeria's 3PL landscape. Technology deployment separates premium providers from commodity operators. Delivery mode selection reflects infrastructure constraints and cargo value density trade-offs.
Service Type:
Technology integration depth distinguishes competitive tiers, with digital capabilities reshaping contract economics.
- Transportation:Asset-light fleet management dominates Lagos-Abuja corridors, where fuel surcharge mechanisms and telematics-enabled route optimization compress per-kilometer costs. Road haulage captures volume leadership despite diesel price volatility eroding margins for operators lacking long-term fuel hedging.
- Warehousing:Bonded terminal scarcity at Lagos and Onne ports elevates facility economics, with temperature-controlled space commanding premium rates under NAFDAC pharmaceutical mandates. Industrial land constraints in Lagos State force vertical stacking and automated retrieval systems.
- Freight Forwarding:Customs brokerage depth differentiates providers navigating SON certification requirements and extended clearance timelines.
- Distribution:Last-mile fragmentation across Nigeria's 36 states demands hub-and-spoke network density that only national-scale operators maintain profitably.
Mature deployment sits with Transportation. Newer deployment is concentrated in Warehousing.
End User:
Customer sophistication dictates service-level agreement complexity and technology integration requirements.
- Retail:Inventory velocity pressures force just-in-time replenishment contracts with penalty clauses for stockout events. Fashion and electronics verticals drive same-day fulfillment investments in Lagos urban micro-fulfillment nodes.
- E-commerce:Platform consolidation around Jumia and Konga concentrates shipment volumes, enabling algorithmic load consolidation and predictive dispatch that compresses order-to-delivery cycles toward 4-8 hour windows.
- Manufacturing:Import-dependent production lines require bonded warehousing for raw materials staging ahead of customs clearance.
- Pharmaceuticals:NAFDAC cold-chain compliance mandates specialized handling certifications that limit qualified provider pools.
Volume concentration favors Retail. Margin expansion is steepest in Pharmaceuticals.
Technology:
Digital infrastructure investment separates enterprise-grade providers from fragmented local competitors.
- Software Solutions:Warehouse management systems with API connectivity to SAP and Oracle environments command premium pricing from multinational shippers. Cloud-based platforms reduce upfront capital barriers for mid-tier 3PLs seeking automation.
- Automation:Robotic picking and automated sortation systems deploy fastest in Lagos e-commerce fulfillment centers facing labor cost inflation and same-day delivery SLAs.
- Tracking Systems:IoT-enabled inventory visibility satisfies enterprise client demands for real-time shipment status.
- Data Analytics:Predictive demand forecasting reduces safety stock requirements for retail clients with seasonal volatility.
Enterprise adoption centers on Software Solutions. Automation deployment is expanding most quickly in high-volume fulfillment operations.
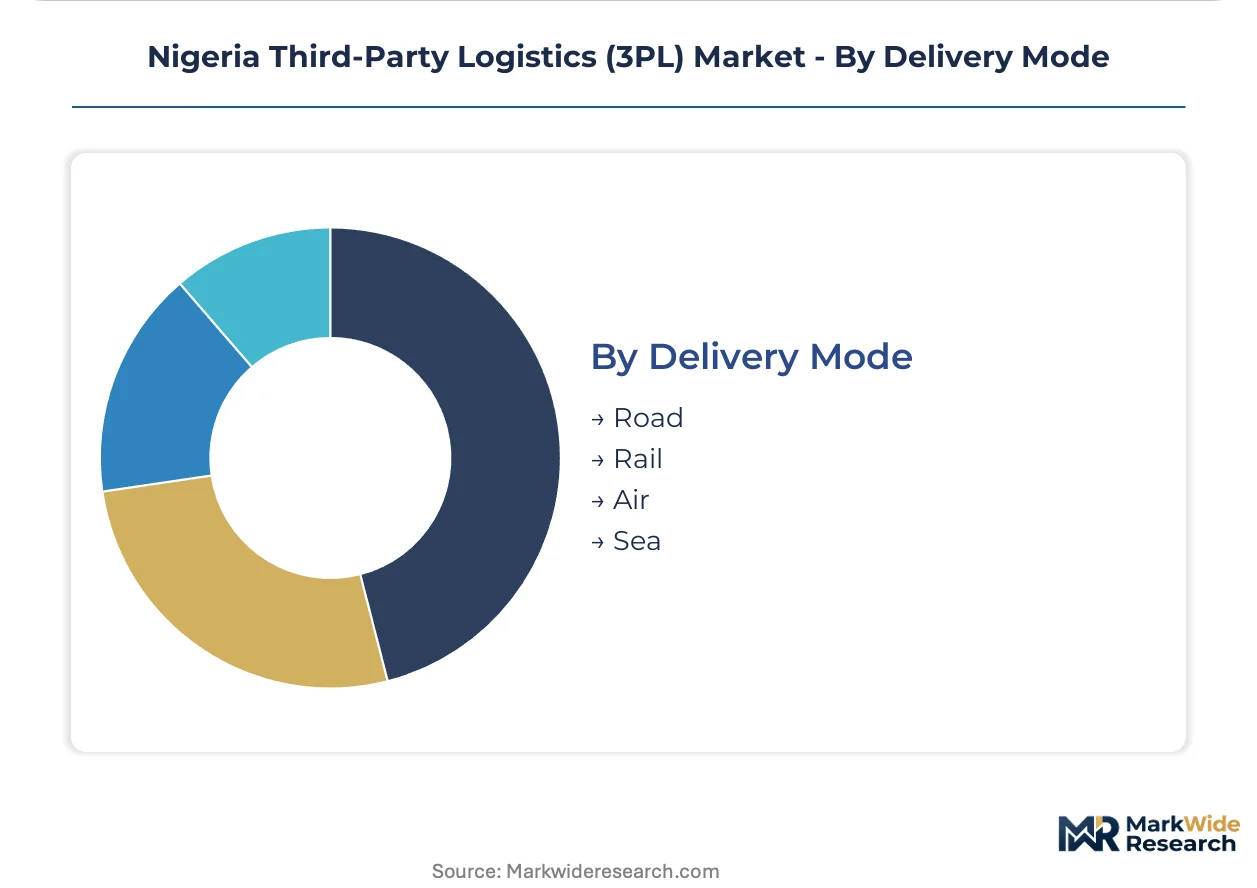
Delivery Mode:
Infrastructure quality and cargo value density determine modal selection across Nigeria's logistics corridors.
- Road:Volume dominance persists despite Federal Road Safety Corps axle-load enforcement variance forcing multi-configuration fleet maintenance. Diesel cost pass-through limitations in contract structures compress operator margins during price spikes.
- Air:High-value pharmaceuticals and electronics command outsized yields on Lagos-Abuja and international lanes, with Murtala Muhammed International Airport anchoring temperature-sensitive cargo flows.
- Sea:Containerized imports through Lagos and Onne terminals feed bonded warehousing demand ahead of SON inspection requirements.
- Rail:Limited track rehabilitation between Lagos and Kano offers long-haul bulk cargo alternatives, though last-mile connectivity gaps constrain adoption.
Established infrastructure favors Road. Network investment is concentrating in Air freight for premium cargo segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters concentrate in Lagos State while consumption spreads across Nigeria's 36 states. This geographic mismatch creates logistics corridors that favor hub-and-spoke network operators. The Central Bank of Nigeria's cashless policy accelerates e-commerce penetration in secondary cities.
Lagos State
Port access at Apapa and Lekki anchors import-dependent supply chains for consumer goods and pharmaceuticals. The Standards Organisation of Nigeria operates inspection protocols that extend customs clearance timelines. Industrial clustering around Ikeja and Ogba districts concentrates warehousing demand and elevates land costs.
Kano State
Northern Nigeria's commercial hub generates agricultural commodity flows and manufactured goods distribution. The country's national food and drug regulator enforces cold-chain compliance for pharmaceutical shipments entering the Sahel corridor. Dawanau grain market and Bompai industrial zone create multimodal logistics demand.
Rivers State
Onne Port and Port Harcourt refineries anchor hydrocarbon and petrochemical logistics. The Federal Road Safety Corps enforces axle-load regulations on East-West Road corridors. Trans-Amadi industrial layout attracts bonded warehousing investment for import staging.
Federal Capital Territory
Abuja's administrative concentration generates high-value document and parcel flows. Government procurement regulations shape contract logistics requirements for public sector suppliers. Central Business District and Garki industrial zones concentrate same-day delivery demand from e-commerce platforms.
Ogun State
Agbara and Otta industrial corridors absorb Lagos manufacturing overflow. The country's central bank monetary policy influences working capital cycles for just-in-time inventory systems. Sagamu interchange serves as a road freight consolidation point for southwest distribution.
Nigeria Third-Party Logistics (3PL) Market Competitive Landscape
The competitive structure tilts toward nationally-scaled integrated operators with port-to-warehouse capabilities. Domestic providers with hub networks command premium positioning in temperature-sensitive corridors. Three archetypes dominate: international express specialists, Nigerian-owned integrated logistics platforms, and port-centric terminal operators. Capacity expansion and customs brokerage depth represent the primary competitive moves.
Among internationally-rooted specialists, DHL International GmbH and Aramex Nigeria exemplify cross-border lane expertise. SIFAX Logistics anchors the port-centric tier through integrated terminal operations. GIG Logistics represents the domestic integrated archetype with nationwide hub density.
| Leading Market Players |
|---|
| Creseada International Limited |
| SIFAX Logistics |
| DHL International GmbH |
| Redline Logistics |
| Aramex Nigeria |
| GIG Logistics |
| MDS Logistics |
| UPS Nigeria |
| Bollore Transport and Logistics |
| Others |
Supply & Pricing Matrix
Family-owned logistics operators with multi-generational port relationships anchor supply-side discipline across Nigeria's 3PL corridors, translating bonded terminal scarcity into sustained pricing power for warehousing while diesel cost pass-through limitations compress road haulage margins.
Pricing Analysis
Margin tightening in road transportation reflects diesel price volatility eroding operator returns where fuel surcharge mechanisms remain absent from contract structures. Three-tier pricing structure across premium, standard, and economy levels stratifies by technology integration depth and customs brokerage capability. E-commerce platforms exhibit acute price sensitivity, demanding algorithmic load consolidation at compressed rates, while pharmaceutical shippers accept premium positioning for NAFDAC-certified cold-chain handling.
Supply Chain Analysis
Direct-to-manufacturer channels handle just-in-time raw material flows for import-dependent production lines across Lagos and Ogun industrial zones. Supply concentration rests on China for containerized consumer goods, India for pharmaceutical APIs, and regional West African sources for agricultural commodities. Single-source vulnerability pervades bonded terminal capacity at Apapa and Onne ports, where limited customs-bonded facilities create staging bottlenecks. Distribution runs through hub-and-spoke networks radiating from Lagos State toward 36 state-level last-mile nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nigeria's 3PL sector constitutes a consolidation play as diesel cost volatility and automation investment thresholds force sub-scale operators toward exit or acquisition.
For Market Incumbents: To counter margin compression from fuel price volatility, deepen backward integration into captive fleet maintenance facilities and expand temperature-controlled warehouse capacity in Kano and Rivers States ahead of NAFDAC enforcement tightening. For New Entrants and Emerging Players: E-commerce platform partnerships offer the most penetrable entry vector, with micro-fulfillment nodes in Abuja and Port Harcourt presenting white-space opportunities for providers deploying cloud-based warehouse management systems with rapid API connectivity. For Investors and Strategic Acquirers: Accelerated automation capex announcements from GIG Logistics and SIFAX Logistics are the leading indicator that scale thresholds are rising, suggesting five-to-ten year viability favors nationally-scaled operators with integrated port-to-warehouse capabilities and customs brokerage depth.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | NAFDAC pharmaceutical mandates elevate certified facility scarcity into durable competitive positioning. |
| Digital Freight Platform Integration | Real-time load-board technologies reduce empty backhaul miles for Lagos-Abuja corridor operators. |
| Cross-Border ECOWAS Lane Development | Land-bridge routes to Benin and Ghana unlock revenue diversification beyond Nigeria domestic concentration. |
| Micro-Fulfillment Node Deployment | Urban district warehouses compress order-to-delivery cycles for fashion and electronics e-commerce verticals. |
| Customs Brokerage Capability Buildout | SON certification expertise shortens clearance timelines at bonded terminals with integrated inspection facilities. |
Research Methodology
Trade databases, Central Bank of Nigeria monetary policy releases, and NAFDAC regulatory filings formed the secondary backbone, combined with primary interviews spanning 3PL operations directors, e-commerce supply chain managers, pharmaceutical distribution heads, and bonded terminal operators. Bottom-up and top-down triangulation validated volume estimates across service type, end user, and delivery mode segments.
Bottom-up modeling aggregated individual operator capacity and utilization rates, while top-down analysis cross-referenced against national trade flow data and e-commerce transaction growth across the projection horizon. Segmentation dimensions included service configuration, technology deployment tier, customer sophistication level, and regional logistics corridor density. CAGRs derived from trend extrapolation of diesel cost pass-through elasticity and automation adoption curves.
Caveats apply where diesel subsidy removal timing, FRSC axle-load enforcement consistency, or ECOWAS trade protocol implementation could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
UAE Logistics Market
Logistics and Shipping
Australia 3PL Market
Logistics and Shipping
Global Automated Container Terminal Market
Logistics and Shipping
South Africa Freight and Logistics Market
Logistics and Shipping
Netherlands Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
China Shipping Agency Services Market
Logistics and Shipping
Cross-Border Logistics Services Market
Logistics and Shipping
Multi-Enterprise Logistics Contract and SLA Performance Management Platforms Market
Logistics and Shipping
US Hazardous Goods Logistics Market
Logistics and Shipping
Australia Freight Forwarding Market
Logistics and Shipping
Japan E-Commerce Logistics Market
Logistics and Shipping
France Cold Chain Logistics Market
Logistics and Shipping
Nordics Freight and Logistics Market
Logistics and Shipping
Freight Management System Market
Logistics and Shipping
China less than Truckload Road Freight Transport Market
Logistics and Shipping
Retail Logistics Market