
 Poland Road Freight Transport Market | 2026-2036
Poland Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Road Freight Transport Market Insights
Low-emission drivetrain technologies are repositioning total cost of ownership calculations for Polish fleet operators. Girteka sustains one of Europe's largest truck fleets and anchors capacity along the east-west corridor through Poland. Raben Group differentiates through contract logistics integration, while Waberer's International dominates domestic full-truckload movements with extensive terminal infrastructure.
Poland road freight transport encompasses the commercial movement of goods by motorized road vehicles operating on public highway networks, typically involving articulated trucks with gross combination weights up to 40 tonnes and cargo volumes measured in pallet positions or cubic meters. The sector functions as the dominant mode for domestic goods distribution and international trade linkage, with trucks handling approximately three-quarters of Poland's total freight tonne-kilometers. Full truckload delivery mode leads volume throughput due to Poland's manufacturing density and cross-border export flows, while less than truckload services capture expanding margin pools from fragmented e-commerce consignments. Contract logistics services exhibit the fastest structural growth as shporters outsource fleet ownership and warehouse coordination to specialized providers.
The European Union's Mobility Package regulations reshape driver working conditions and cabotage access for Polish carriers operating across member states, while Poland's General Inspectorate of Road Transport enforces tachograph compliance and vehicle weight limits on national routes. The EU Green Deal's CO2 emission performance standards for heavy-duty vehicles mandate progressive fleet decarbonization, pressuring operators to evaluate alternative fuel investments against residual diesel asset values. Stakeholders must monitor how EU ETS carbon pricing expansion to road transport alters route economics and whether Polish government subsidy programs for electric truck procurement accelerate fleet turnover timelines.
Market Dynamics
The EU Green Deal's CO2 emission performance standards for heavy-duty vehicles are forcing Polish carriers to accelerate fleet turnover timelines and reassess residual diesel asset values against alternative fuel investments. This regulatory pressure intersects with expanding e-commerce fulfillment networks to reshape capacity deployment across Poland's logistics corridors.
Growth Catalysts
- E-commerce fulfillment expansion:Dedicated transport services are scaling across Poland's major logistics corridors as distribution networks densify their last-mile coverage. Fragmented consignment volumes from online retail are converting to less-than-truckload margin pools.
- EU Green Deal mandates:CO2 emission performance standards for heavy-duty vehicles are pressuring operators to evaluate electric and hydrogen drivetrain investments. Fleet modernization decisions are accelerating as residual diesel asset values compress.
- Manufacturing cluster concentration:Silesian and Greater Poland voivodeships generate sustained full-truckload demand through dense automotive and electronics production facilities. Cross-border export flows anchor capacity utilization on east-west corridors.
Market Restraints
- Driver availability constraints:Poland's General Inspectorate of Road Transport enforces strict tachograph compliance and working hour limits that tighten labor supply. The EU Mobility Package's revised driver posting rules add administrative friction to international operations.
- Alternative fuel infrastructure gaps:Electric truck charging networks and hydrogen refueling stations remain sparse along Poland's east-west transit routes. Range anxiety limits early adopters to fixed-radius urban distribution circuits.
- Residual value risk on diesel assets:Accelerated decarbonization timelines threaten secondary market liquidity for conventional tractor units. Fleet operators face stranded asset exposure on vehicles with remaining depreciation schedules.
Strategic Opportunities
- Contract logistics outsourcing:Shippers are divesting fleet ownership and warehouse coordination to specialized providers, creating structural growth in integrated service contracts. Raben Group's model demonstrates margin capture from bundling transport with value-added warehousing.
- Intermodal corridor development:Rail-road terminals at Łódź and Poznań offer modal shift potential for long-haul container movements. Polish government infrastructure subsidies for terminal expansion are reducing transfer cost penalties.
- Battery-electric urban delivery:Subnational air quality zones in Kraków and Warsaw are restricting diesel access to city centers. Municipal procurement programs for zero-emission last-mile fleets are creating protected demand pockets.
Industry Challenges
- Telematics integration complexity:Legacy fleet management systems require costly retrofitting to interface with EU-mandated smart tachograph units and carbon reporting platforms. Polish mid-size carriers lack in-house IT capabilities for seamless data harmonization.
- Certification timeline compression:EU ETS carbon pricing expansion to road transport demands accelerated emissions verification protocols. Operators must implement monitoring systems ahead of enforcement deadlines to avoid penalty exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Road Freight Transport Market |
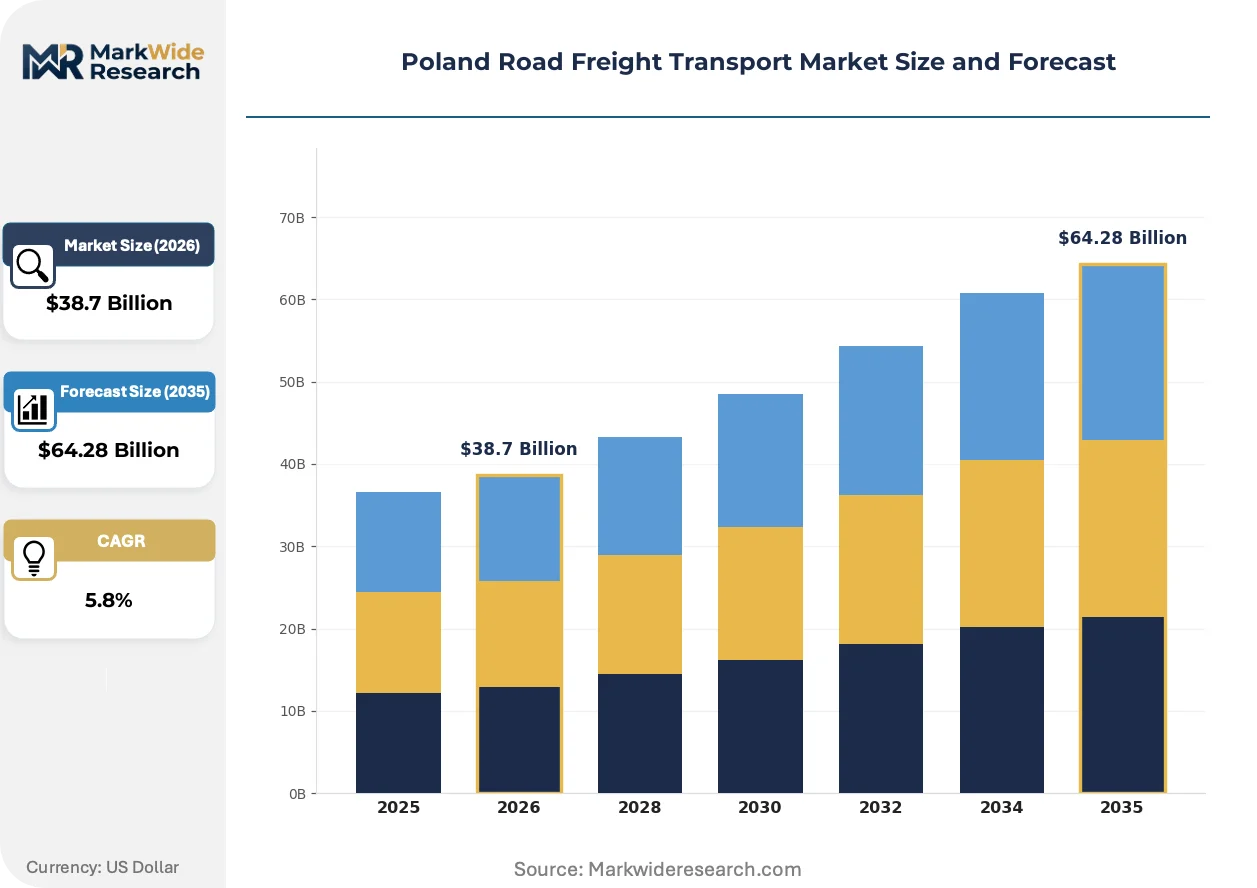
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Trucks, Vans, Trailers, Buses Delivery Mode: Intermodal, Full Truckload, Less than Truckload, Expedited End User: Retail, Manufacturing, E-commerce, Agriculture Service Type: Contract Logistics, Freight Brokerage, Third-party Logistics, Dedicated Transport |
| Companies Covered | DB Schenker, Girteka, Raben Group, Rhenus Group, ROHLIG SUUS Logistics, Vos Logistics, Waberer’s International, DHL Poland, Kuetka Transport, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Road Freight Transport Market Trends and Innovations
Digital freight platforms and drivetrain electrification are converging to reshape asset utilization models and cost structures across Polish road freight. These shifts are compressing traditional brokerage margins while elevating data-centric fleet management capabilities.
Trailer telematics integrating cargo sensors, door monitoring, and geofencing is modularizing fleet oversight for Polish carriers managing high-value automotive and electronics shipments. Third-party logistics providers are deploying these systems fastest, using real-time visibility to justify premium service tiers. The technology is modularizing how shippers purchase transport, unbundling tracking from haulage to create standalone data service revenue streams.
REACH chemical safety regulations and the EU Green Deal's F-Gas restrictions are tightening refrigerant compliance requirements for temperature-controlled transport across Poland's food and pharmaceutical corridors. Carriers operating reefer units must retrofit or replace equipment using prohibited hydrofluorocarbons. The dairy and fresh produce distribution segment is responding fastest, consolidating procurement to access compliant fleet pools.
Shippers are unbundling transport procurement from warehousing contracts, fragmenting vendor relationships across specialized providers. Food manufacturers and automotive suppliers are leading this disintermediation, separating line-haul from last-mile to optimize each leg independently. The Silesian industrial basin exhibits this pattern most visibly, with producers maintaining multiple carrier relationships for different corridor densities.
Poland Road Freight Transport Market Segmentation
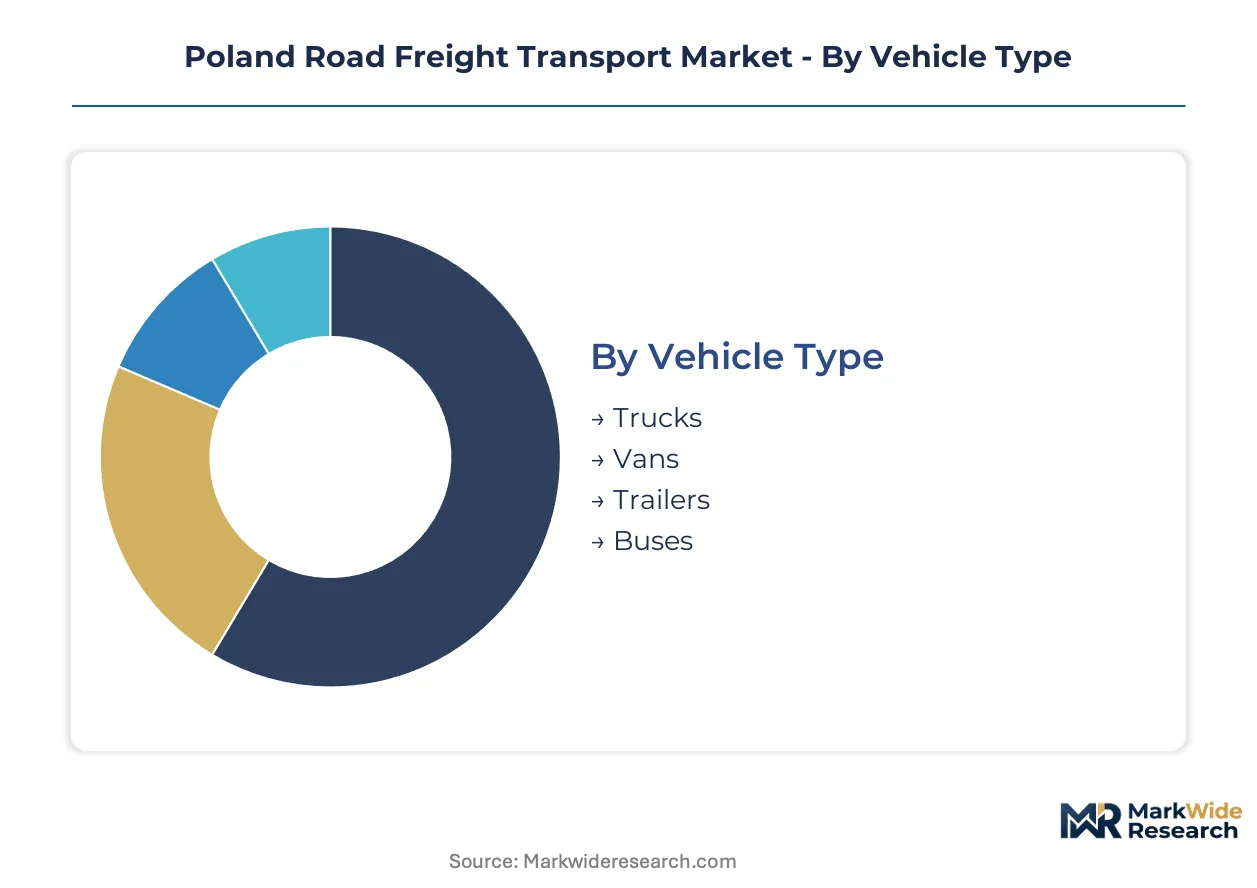
Polish carriers configure asset deployment differently across vehicle classes, delivery modes, and service tiers to match cargo density with route economics. Each segmentation dimension reveals distinct margin structures and capital intensity requirements that shape competitive positioning in the Silesian manufacturing belt and Greater Poland distribution corridors.
Vehicle Type:
Standardization dominates heavy-duty segments while light commercial vehicles accommodate customization for last-mile density.
- Trucks:Articulated tractor units with gross combination weights up to 40 tonnes form the backbone of cross-border east-west corridors. Silesian automotive suppliers and Greater Poland electronics manufacturers generate sustained full-truckload demand that anchors capacity utilization on routes to Germany and the Netherlands.
- Vans:Light commercial vehicles with cargo volumes below 15 cubic meters serve urban last-mile circuits. E-commerce fulfillment networks in Warsaw and Kraków deploy these for fragmented consignment delivery where truck access faces municipal restrictions.
- Trailers:Modular cargo units enable flexible loading configurations for temperature-controlled and dry goods. Food manufacturers across the Masovian Voivodeship lease trailer pools to match seasonal harvest volumes without fleet ownership.
- Buses:Converted passenger coaches handle express parcel and employee shuttle cargo for regional distribution networks. Postal operators in rural Podlaskie Voivodeship utilize these for low-density route coverage.
Leading the category by volume: Trucks. Growing fastest: Vans.
Delivery Mode:
Cost tier differentiation separates consolidated network services from premium expedited offerings.
- Full Truckload:Dedicated vehicle capacity for single-shipper cargo dominates manufacturing corridors. Automotive component flows from the Silesian Industrial Basin to assembly plants in Germany sustain the highest revenue per kilometer in this segment.
- Less than Truckload:Consolidated multi-shipper cargo enables margin capture from fragmented e-commerce volumes. Distribution centers around Łódź and Poznań utilize these services for inventory replenishment across retail networks.
- Intermodal:Rail-road terminal transfers reduce long-haul fuel exposure for container movements. The Łódź Fabryczna terminal and Poznań Franowo facility anchor this mode for Baltic-Adriatic corridor traffic.
- Expedited:Time-definite delivery with dedicated driver teams commands premium pricing. Pharmaceutical distributors in Warsaw deploy these for temperature-sensitive vaccine shipments requiring continuous cold chain verification.
Full Truckload commands the greatest tonnage. Less than Truckload is expanding most quickly.
End User:
Application-specific requirements drive equipment specification and service level differentiation.
- Manufacturing:Just-in-time delivery schedules for automotive and electronics producers demand high reliability. Katowice-based suppliers enforce strict delivery windows that favor dedicated contract arrangements over spot market procurement.
- E-commerce:Reverse logistics and returns handling capabilities separate qualified providers from commodity haulers. Fulfillment centers near Warsaw and Wrocław require weekend and evening delivery flexibility that strains conventional fleet scheduling.
- Retail:Seasonal volume spikes from fashion and consumer goods necessitate surge capacity access. Distribution networks serving Poznań and Gdańsk consolidate procurement to secure guaranteed peak season slots.
- Agriculture:Harvest-time bulk movements of grain and dairy products require specialized tipping trailers and temperature control. The Greater Poland Voivodeship generates concentrated seasonal demand during autumn procurement cycles.
Manufacturing anchors the largest freight volumes. E-commerce shows the steepest expansion trajectory.
Service Type:
Customer type stratification separates integrated supply chain managers from transactional capacity brokers.
- Contract Logistics:Bundled transport, warehousing, and inventory management services capture multi-year outsourcing relationships. Food manufacturers in the Masovian region favor these arrangements to divest fixed asset ownership.
- Third-party Logistics:Asset-light coordination of carrier networks enables flexibility without fleet investment. Mid-size Polish shippers utilize these providers to access EU-wide coverage without direct cabotage compliance burden.
- Dedicated Transport:Exclusive vehicle allocation for single-shipper operations guarantees capacity availability. Major retailers operating national distribution networks from central Poland prefer this model for predictable cost structures.
- Freight Brokerage:Spot market matching of shipper demand with available carrier capacity extracts margin from price volatility. Digital platforms are compressing traditional brokerage spreads in cross-border east-west lanes.
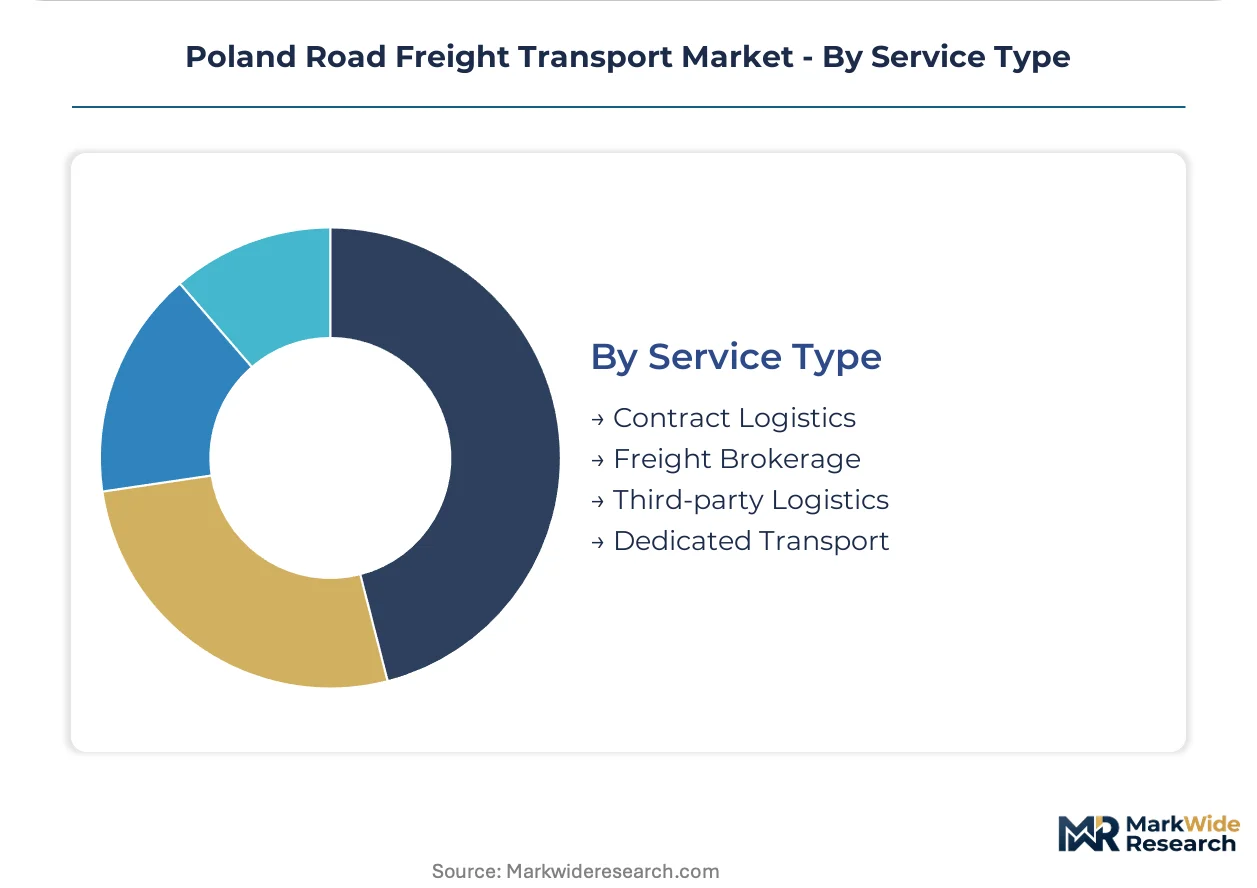
Contract Logistics leads by revenue concentration. Third-party Logistics is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Poland's central manufacturing belt and western border corridors where automotive and electronics production clusters generate sustained freight volumes. The Silesian and Greater Poland voivodeships anchor domestic tonnage, while cross-border flows to Germany and the Netherlands drive international capacity utilization.
Silesian Voivodeship
Automotive component suppliers and steel producers generate the highest full-truckload volumes in this southern industrial basin. The EU Green Deal's CO2 emission standards pressure Katowice-based carriers to accelerate fleet turnover. Dense manufacturing around Gliwice and Bielsko-Biała sustains dedicated contract logistics arrangements for just-in-time delivery to German assembly plants.
Greater Poland Voivodeship
Electronics manufacturing and food processing create diversified freight demand across Poznań and surrounding production zones. Poland's General Inspectorate of Road Transport enforces strict tachograph compliance on national routes serving this region. The Łódź-Poznań corridor functions as a critical east-west logistics artery connecting Baltic ports to German industrial centers.
Masovian Voivodeship
Warsaw's e-commerce fulfillment networks and pharmaceutical distribution drive premium expedited services and last-mile van deployments. Municipal air quality regulations in the capital restrict diesel access to urban centers, accelerating battery-electric procurement. The Warsaw-Łódź logistics triangle hosts major contract logistics providers bundling transport with value-added warehousing.
Lower Silesian Voivodeship
Wrocław's technology manufacturing campuses and automotive suppliers generate high-value cargo requiring real-time tracking capabilities. The EU Mobility Package's revised driver posting rules add administrative complexity to international operations originating here. Cross-border flows to Czech and German markets utilize the A4 motorway corridor as the primary transit route.
Pomeranian Voivodeship
Gdańsk's port-centric logistics and shipbuilding supply chains create specialized heavy-haul and project cargo demand. Government infrastructure subsidies support intermodal terminal expansion at the Baltic-Adriatic corridor junction. Food manufacturers across the region leverage seasonal trailer pools to manage harvest-time volume spikes without fixed fleet investment.
Poland Road Freight Transport Market Competitive Landscape
Capacity expansion dominates the current landscape as established carriers modernize fleets to meet EU Green Deal decarbonization timelines. The market exhibits a tiered structure with integrated contract logistics providers occupying premium positions, mid-size domestic operators serving regional corridors, and digital freight platforms compressing spot brokerage margins. Two strategic archetypes define competitive positioning: asset-heavy fleet operators with terminal infrastructure and asset-light coordinators leveraging third-party carrier networks. M&A activity and alternative fuel investments constitute the dominant competitive moves reshaping market structure.
Within the integrated contract logistics tier, Raben Group exemplifies bundled service models combining transport with warehouse coordination, while Girteka anchors capacity deployment across east-west European corridors through extensive fleet scale. Among domestic full-truckload specialists, Waberer's International occupies a position representing terminal-network density for domestic movements. These three players collectively illustrate how Polish carriers are repositioning around decarbonization mandates and e-commerce fulfillment expansion.
| Leading Market Players |
|---|
| DB Schenker |
| Girteka |
| Raben Group |
| Rhenus Group |
| ROHLIG SUUS Logistics |
| Vos Logistics |
| Waberer's International |
| DHL Poland |
| Kuetka Transport |
| Others |
Pricing and Supply Chain Analysis
Diesel fuel and driver labor costs cascade through contract tiers from Silesian manufacturing clusters to last-mile van operators in Warsaw, compressing margins for spot-market carriers while insulating integrated providers with long-term offtake agreements.
Pricing Analysis
Full-truckload volume anchors revenue concentration, but less-than-truckload services capture expanding margin pools from fragmented e-commerce consignments. Pricing stratifies across premium expedited, standard scheduled, and economy deferred tiers, with differentiation driven by delivery speed guarantees and cargo tracking certification levels. Cost compression in the spot brokerage tier is intensifying because digital freight platforms disintermediate traditional intermediaries. Small and mid-size domestic operators exhibit highest price sensitivity, while multinational contract logistics buyers prioritize service reliability over rate negotiation.
Supply Chain Analysis
Logistics costs concentrate in east-west corridor movements linking German industrial centers to Polish manufacturing clusters, with fuel and toll exposure dominating line-haul economics. Vehicle manufacturing draws from German, Czech, and domestic Polish component suppliers for tractor units and trailer assemblies. Supply chain risk centers on single-source vulnerability for electric drivetrain components as EU Green Deal deadlines accelerate fleet turnover. Distribution runs through hub-and-spoke terminal networks anchored at Łódź and Poznań, with rail-road intermodal transfers gaining share on long-haul Baltic-Adriatic routes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Poland road freight transport market reads as a cost-of-compliance story where EU Green Deal CO2 emission performance standards for heavy-duty vehicles create a barrier-to-entry moat for carriers with capital to fund alternative fuel fleet transitions.
For Market Incumbents: To counter margin compression from digital freight platforms, deepen captive maintenance capabilities and secure exclusive terminal access in the Silesian Industrial Basin. Prioritize backward integration into electric truck charging infrastructure along the A4 motorway corridor to lock in route economics before subsidy windows close.
For New Entrants and Emerging Players: Enter via battery-electric urban delivery services in Kraków and Warsaw, where municipal diesel restrictions create protected demand pockets with limited incumbent presence. Target pharmaceutical and fresh food verticals requiring temperature-controlled compliance that commoditized haulers underserve.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-size carriers with dense terminal networks in Greater Poland and Lower Silesia, where stranded diesel asset risk pressures seller valuations. Watch EU ETS carbon pricing expansion to road transport as the inflection signal for accelerated fleet turnover timelines and consolidation pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Procurement | EU Green Deal compliance deadlines force residual diesel value risk management. |
| Terminal Infrastructure Expansion | Łódź and Poznań hub density secures intermodal transfer cost advantages. |
| Contract Logistics Integration | Bundled warehousing and transport captures multi-year outsourcing relationships. |
| Digital Platform Partnership | Real-time visibility justifies premium tiers for automotive and electronics cargo. |
| Driver Training Certification | EU Mobility Package compliance reduces administrative friction on international routes. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by structured interviews with fleet operations directors, logistics procurement managers at manufacturing shippers, intermodal terminal operators, and compliance officers at the General Inspectorate of Road Transport. Primary fieldwork combined with secondary validation from EU transport statistics, Polish Central Statistical Office freight reports, and carrier financial disclosures. Bottom-up vehicle deployment modeling and top-down corridor flow analysis were triangulated against macroeconomic indicators.
Data-stream reconciliation across vehicle type, delivery mode, end-use industry, and service tier segmentation dimensions generated volume and value outputs over the projection horizon. CAGRs were derived from trend extrapolation of fleet turnover rates, e-commerce penetration curves, and regulatory compliance cost trajectories. Industry-specific forecast inputs included EU ETS carbon price scenarios and Polish government subsidy program allocations for zero-emission commercial vehicles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU decarbonization timelines or prolonged alternative fuel infrastructure gaps. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Traction Equipment Market
Transportation & Logistics
Refrigerated Road Transportation Market
Transportation & Logistics
Road Haulage Market
Transportation & Logistics
Netherlands Road Freight Transport Market
Transportation & Logistics
Transport Refrigeration Unit (TRU) Market
Transportation & Logistics
Chile Road Freight Transport Market
Transportation & Logistics
Saudi Arabia Road Freight Transport Market
Transportation & Logistics
Parking Meter Market
Transportation & Logistics
Global Fourth Party Logistics Market
Transportation & Logistics
Italy Road Freight Transport Market
Transportation & Logistics
Ride-Hailing and Taxi Market
Transportation & Logistics
Refrigerated Trailer Market
Transportation & Logistics
US Reverse Logistics Market
Transportation & Logistics
North America Road Freight Transport Market
Transportation & Logistics
Canada Customs Brokerage Market
Transportation & Logistics
Slovakia Road Freight Transport Market