
 Central and Eastern Europe Courier, Express, and Parcel (CEP) Market | 2026-2036
Central and Eastern Europe Courier, Express, and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
Central and Eastern Europe Courier, Express, and Parcel (CEP) Market Insights
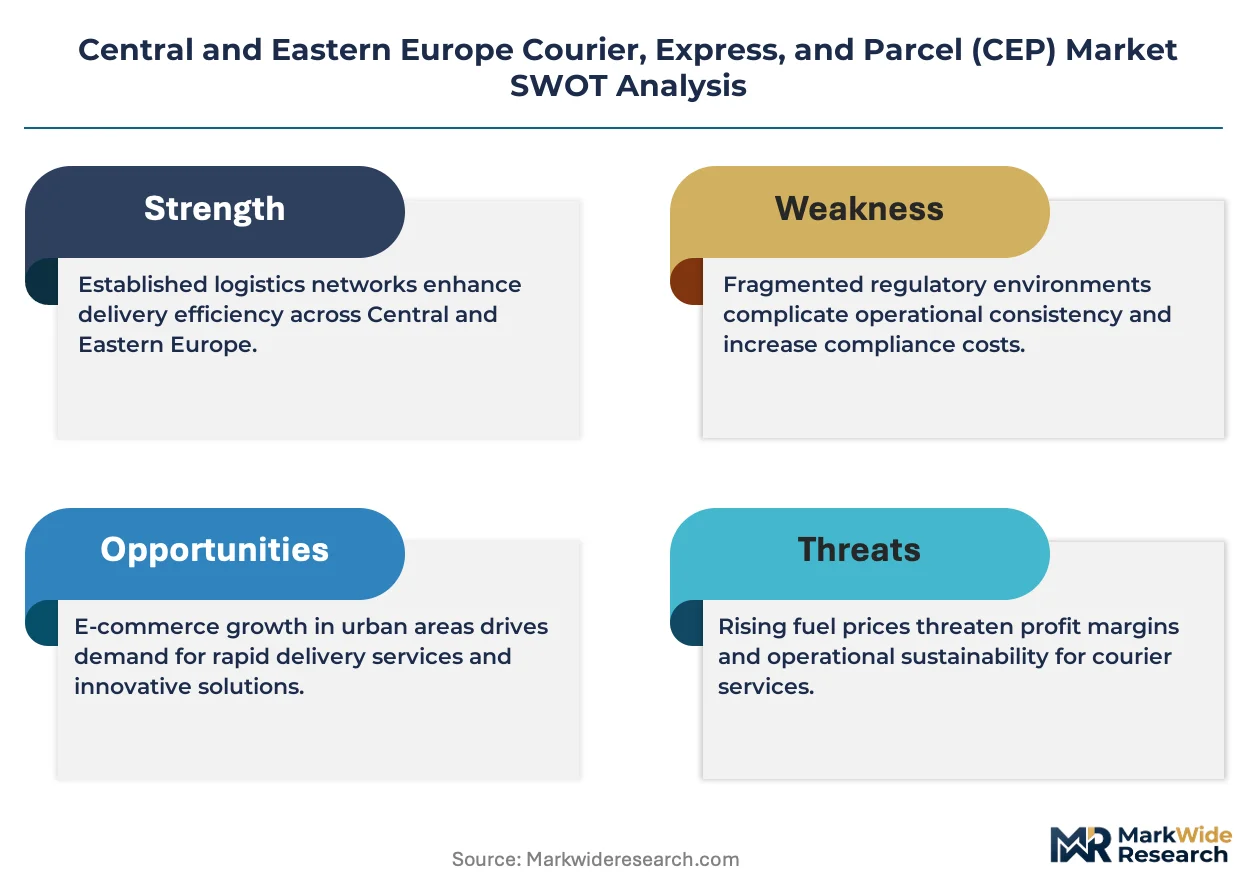
EU Green Deal compliance is recalibrating the cost-of-entry calculus for new fleet operators across Central and Eastern Europe. DHL Group leverages its integrated air-and-ground network to sustain premium express margins in Polish and Czech corridors. InPost anchors its competitive position through dense automated parcel locker infrastructure in Polish cities. Poczta Polska SA dominates rural last-mile coverage where private carriers struggle to achieve unit economics.
Courier, Express, and Parcel (CEP) services encompass time-definite logistics solutions spanning same-day through international delivery, utilizing integrated hub-and-spoke networks, automated sortation, and multi-modal transport to move documents and goods under contractual service level agreements. Same-day delivery commands premium pricing but remains operationally constrained by driver availability and urban congestion, while next-day delivery occupies the volume-maturity sweet spot where scale economies are most pronounced. Standard delivery segments compete primarily on cost efficiency, whereas international shipping extracts margin from customs brokerage complexity and cross-border regulatory navigation.
Poland's General Inspectorate of Road Transport, Czechia's Ministry of Transport, and Romania's National Authority for Consumer Protection collectively enforce driver hours regulations, emissions standards, and consumer protection frameworks that elevate compliance costs for non-compliant operators. ECHA's REACH chemical documentation requirements and EU packaging waste directives further shape material choices for protective shipping containers. Stakeholders must monitor how forthcoming EU digital customs initiatives reshape cross-border clearance speed and which carriers secure pre-certified status.
Market Dynamics
The EU Green Deal's emissions targets are recalibrating fleet investment decisions across Polish, Czech, and Romanian logistics corridors, forcing carriers to accelerate electric vehicle deployment and carbon accounting systems ahead of 2030 compliance deadlines.
Growth Catalysts
- E-commerce merchant density:Online retail fulfillment volumes in Warsaw, Krakow, and the Silesian triangle are compressing delivery windows and expanding same-day service coverage. Automated sortation hubs capture scale economies from parcel density.
- EU Green Deal mandates:Emissions targets are unlocking green financing instruments for fleet electrification. Carriers securing pre-certified low-emission vehicle status gain preferential urban access permits in Polish and Czech city centers.
- Parcel locker infrastructure:Dense automated locker networks in Polish urban cores reduce failed delivery rates and driver time-per-stop. Last-mile cost structures improve as consumer pickup behavior normalizes.
Market Restraints
- Driver availability constraints:Poland's General Inspectorate of Road Transport enforces strict hours regulations that limit fleet utilization rates. Recruitment costs for qualified commercial drivers are escalating across Czechia and Romania.
- Cross-border customs friction:Non-harmonized documentation requirements between EU member states and neighboring markets create clearance delays. Small carriers lacking integrated brokerage capabilities face margin compression on international lanes.
- Last-mile rural economics:Poczta Polska SA's universal service obligation coverage in remote Polish regions sets uneconomic benchmarks. Private carriers struggle to match unit costs where parcel density falls below threshold levels.
Strategic Opportunities
- Romanian secondary city penetration:Bucharest-anchored networks remain underdeveloped in Cluj-Napoca, Timisoara, and Iasi corridors. First-mover parcel locker deployment captures emerging e-commerce fulfillment demand.
- EU digital customs pre-certification:forthcoming EU digital customs initiatives reward carriers with advance clearance status. Cross-border express margins expand for operators integrating real-time documentation systems.
- Electric van + cargo bike convergence:Urban congestion charges and low-emission zones are forcing modal shift combinations. Micro-fulfillment depots at city edges enable zero-emission final-kilometer completion.
Industry Challenges
- Telematics integration complexity:Legacy fleet management systems resist seamless connection with real-time route optimization platforms. IT upgrade cycles strain mid-size carrier capital allocation.
- REACH-compliant packaging material sourcing:ECHA documentation requirements for protective shipping containers extend procurement timelines. Alternative cushioning materials face performance validation gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Central and Eastern Europe Courier, Express, and Parcel (CEP) Market |
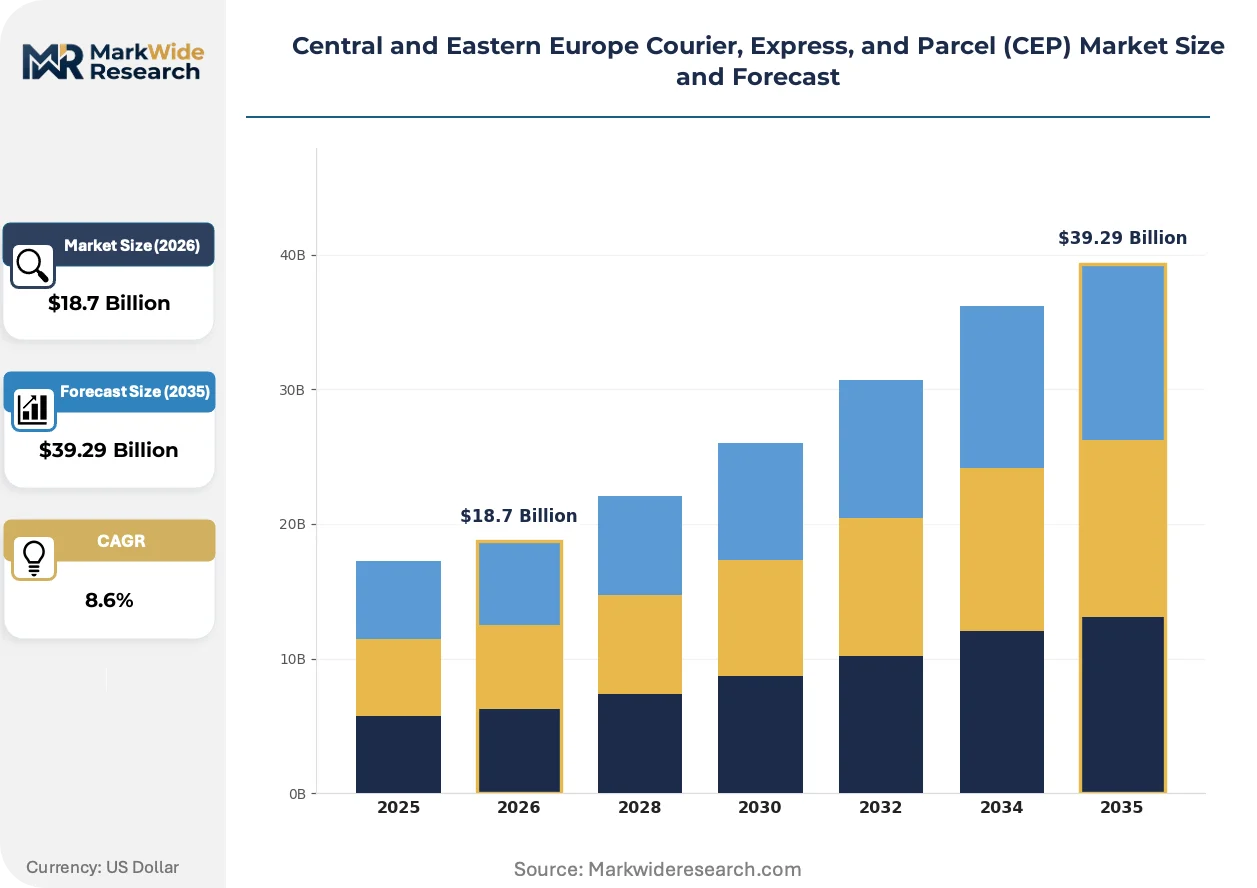
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same-Day Delivery, Next-Day Delivery, Standard Delivery, International Shipping Distribution Channel: Online Retail, Brick-and-Mortar, Wholesalers, Direct Sales End User: E-Commerce, Retail, Manufacturing, Healthcare Package Type: Envelope, Box, Pallet, Bulk |
| Companies Covered | DHL Group, InPost, FedEx, La Poste Group, Poczta Polska SA, International Distribution Services, Fan Courier, Sameday, GLS, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Central and Eastern Europe Courier, Express, and Parcel (CEP) Market Trends and Innovations
Automation and emissions compliance are compressing operational timelines across Central and Eastern European CEP networks, forcing carriers to reconfigure sortation, fleet, and last-mile systems simultaneously.
Autonomous mobile robots are expanding into hub sortation operations across Polish distribution centers. DHL Group and InPost are deploying robotic pick-and-place systems at Warsaw and Krakow facilities to compress overnight processing windows. Labor cost arbitrage is diminishing as robotic throughput guarantees reshape night-shift economics.
EU packaging waste directives are mandating recycled content thresholds for protective shipping materials. ECHA's REACH documentation requirements extend compliance timelines for alternative cushioning substrates. E-commerce merchants sourcing from Asia-Pacific suppliers face the steepest material requalification burdens.
Urban consumers are consolidating purchase timing around predictable delivery windows rather than demanding instantaneous fulfillment. Next-day delivery slots with precise two-hour windows are displacing same-day premiums in Prague and Bratislava corridors. Polish retail banking and electronics verticals show the strongest preference compression toward scheduled precision over speed.
Central and Eastern Europe Courier, Express, and Parcel (CEP) Market Segmentation
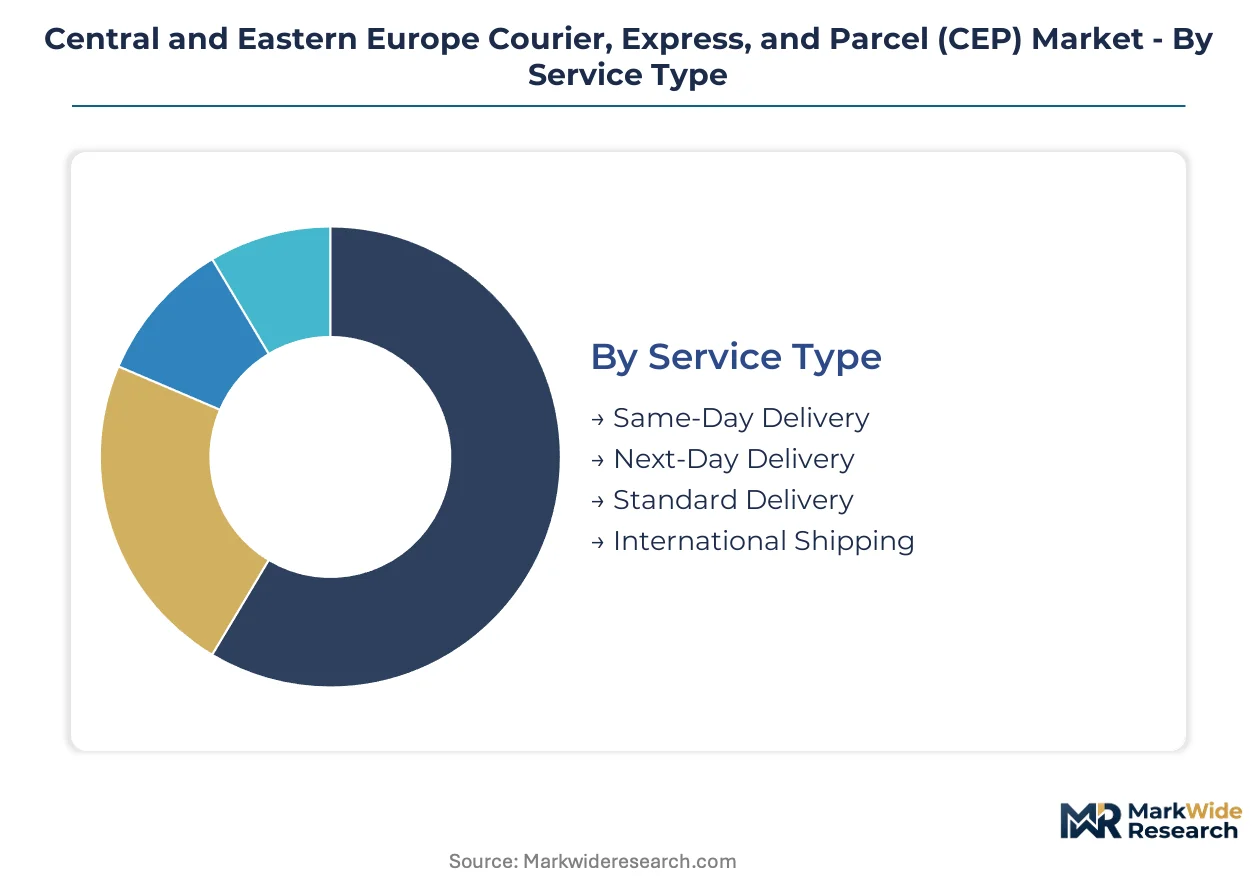
CEP market segmentation reveals how service economics diverge across speed tiers, channel structures, and package characteristics. Understanding these divisions exposes where margin compression occurs and where scale economies accumulate in Polish, Czech, and Romanian corridors.
Service Type:
Speed premiums separate buyers by urgency tolerance and inventory carrying cost trade-offs.
- Same-Day Delivery:Time-critical fulfillment utilizing dedicated courier networks and micro-fulfillment depots. Warsaw and Krakow e-commerce merchants absorb premium pricing for electronics and banking documents where stock-out costs exceed delivery fees.
- Next-Day Delivery:Hub-and-spoke sortation with overnight line-haul positioning. Volume concentrates in Silesian triangle industrial zones where manufacturing replenishment cycles align with 24-hour windows.
- Standard Delivery:Deferred ground transport optimizing load consolidation over speed. Rural Polish corridors and cross-border Romanian lanes favor this tier where parcel density justifies slower transit.
- International Shipping:Customs brokerage-integrated express with documentation pre-clearance. Czechia's automotive suppliers leverage this for just-in-sequence deliveries to German assembly plants.
Volume sits with Next-Day Delivery; growth tilts toward Same-Day Delivery.
Distribution Channel:
Channel selection determines last-mile cost allocation between carrier and recipient.
- Online Retail:Direct-to-consumer fulfillment generating parcel locker utilization and failed delivery cost exposure. Polish urban corridors show highest locker density adoption.
- Brick-and-Mortar:Store-based pickup and ship-from-store configurations. Czech electronics retailers use this to offset last-mile delivery cost inflation.
- Wholesalers:B2B palletized consolidation with scheduled delivery windows. Romanian construction materials distributors dominate this channel.
- Direct Sales:Manufacturer-controlled logistics bypassing retail intermediaries. Healthcare equipment suppliers in Warsaw utilize this for installation-integrated delivery.
Shipment value concentrates in Online Retail; margin expansion favors Direct Sales.
End User:
End-use verticals impose divergent service level requirements and packaging specifications.
- E-Commerce:High-volume, low-margin fulfillment with extreme seasonality. Polish fashion and electronics merchants drive locker network expansion and returns processing infrastructure.
- Retail:Omnichannel replenishment and promotional event surge capacity. Czech grocery chains utilize this for dark store-to-home delivery corridors.
- Manufacturing:Production-critical inbound logistics with penalty clauses for delay. Automotive suppliers in Czechia and Slovakia depend on this for assembly line feeding.
- Healthcare:Temperature-controlled transport with chain-of-custody documentation. Romanian pharmaceutical distributors require this for clinical trial materials and hospital supplies.
Parcel count accumulates in E-Commerce; value per shipment peaks in Healthcare.
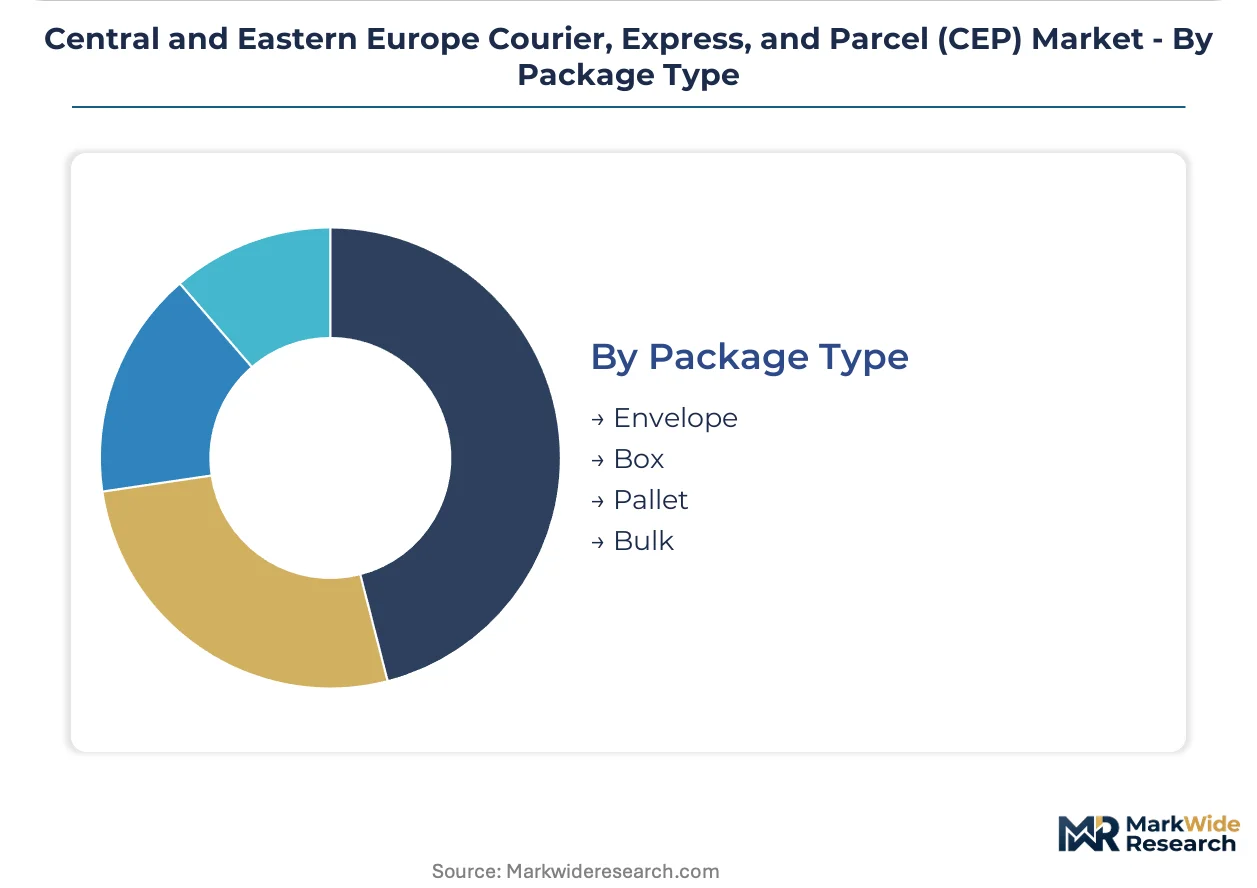
Package Type:
Physical form factor dictates handling equipment, vehicle configuration, and damage liability exposure.
- Envelope:Document and small-item flat packaging with automated sortation compatibility. Banking and legal sectors in Warsaw generate concentrated demand for tamper-evident variants.
- Box:Cubic parcel standard for e-commerce general merchandise. Polish automated hubs optimize for this form factor in dimension-based pricing models.
- Pallet:Unitized freight requiring liftgate equipment and dock-level loading. Manufacturing corridors between Czechia and Germany move significant palletized volume.
- Bulk:Unpackaged or loose-loaded shipments for industrial commodities. Construction materials and agricultural inputs in rural Romania utilize this for cost-minimized transport.
Automated processing capacity centers on Box; manual handling cost burden concentrates in Bulk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Katowice Special Economic Zone and adjacent Silesian logistics triangle concentrate automated sortation infrastructure serving cross-border manufacturing corridors. Polish urban agglomerations anchor parcel volume generation. EU Green Deal implementation timelines vary across member states, reshaping fleet investment priorities.
Poland
Warsaw and Krakow e-commerce merchants compress delivery windows toward same-day fulfillment. The General Inspectorate of Road Transport enforces strict commercial driver hours regulations that constrain fleet utilization. Automated parcel locker networks in the Silesian triangle capture scale economies from manufacturing replenishment cycles.
Czechia
Prague corridor automotive suppliers demand just-in-sequence express delivery to German assembly plants. The Ministry of Transport administers low-emission zone permits that favor pre-certified electric fleet operators. Brno and Ostrava industrial zones generate B2B palletized volume crossing the German border.
Romania
Bucharest-anchored e-commerce fulfillment remains underdeveloped in Cluj-Napoca and Timisoara secondary corridors. The National Authority for Consumer Protection enforces delivery transparency mandates that elevate compliance costs for cross-border operators. Emerging parcel locker deployment in Iasi captures pharmaceutical distribution demand.
Hungary
Budapest logistics parks serve as transshipment nodes for Asia-Europe rail corridors terminating in Western Europe. National emissions standards align with EU Green Deal timelines but lag Polish enforcement stringency. Miskolc and Debrecen manufacturing zones generate automotive component express volume.
Slovakia
Bratislava's proximity to Vienna creates cross-border commuter delivery demand with Austrian service expectations. The national transport authority coordinates with Czech and Polish regulators on driver qualification reciprocity. Zilina automotive clusters depend on overnight express for production-critical inbound parts.
Central and Eastern Europe Courier, Express, and Parcel (CEP) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Central and Eastern European CEP corridors. Tiered market structure separates integrated global networks from regional last-mile specialists and national postal incumbents. Three archetypes dominate: multinational integrators with air-ground networks, automated locker specialists with urban density, and universal service obligation carriers with rural coverage. Competitive moves concentrate on fleet electrification partnerships and parcel locker network densification.
Within the integrated multinational tier, DHL Group and FedEx exemplify hub-and-spoke network operators leveraging air freight connectivity. InPost represents the automated infrastructure archetype with dense Polish urban locker deployment. Poczta Polska SA anchors the universal service segment with rural last-mile coverage obligations that private competitors struggle to match economically.
| Leading Market Players |
|---|
| DHL Group |
| InPost |
| FedEx |
| La Poste Group |
| Poczta Polska SA |
| International Distribution Services |
| Fan Courier |
| Sameday |
| GLS |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up locker network specialists in Polish urban corridors are consolidating last-mile infrastructure while enforcing pricing discipline through automated pickup density. This ownership pattern concentrates supply-side leverage among carriers with pre-certified EU Green Deal fleet status, compressing margins for asset-light brokers dependent on third-party capacity.
Pricing Analysis
Lead-time-driven pricing angles dominate Central and Eastern European CEP corridors, with same-day delivery commanding substantial premiums over deferred standard service. Three-tier pricing structure across premium express, standard deferred, and economy bulk separates urgent manufacturing replenishment from routine e-commerce fulfillment. Cost compression in standard delivery tiers is intensifying because automated sortation hubs capture scale economies that manual operations cannot match. E-commerce merchants show highest price sensitivity, while healthcare and automotive suppliers absorb premium rates for time-critical shipments.
Supply Chain Analysis
Dual-sourcing requirements for electric vehicle fleets are forcing carriers to qualify battery suppliers across Poland, Czechia, and Hungary simultaneously. Vehicle chassis production concentrates in Czechia and Slovakia, while battery pack assembly localizes in Polish industrial zones. Supply chain risk centers on single-source vulnerability for specialized telematics hardware from German Tier 1 suppliers. Distribution runs through hub-and-spoke networks anchored at Warsaw, Prague, and Budapest sortation facilities with overnight line-haul positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Central and Eastern European CEP operations are transitioning from diesel-dependent line-haul to electric van and cargo bike convergence, with EU Green Deal compliance deadlines forcing fleet replacement cycles that favor capital-rich incumbents.
For Market Incumbents: Deploy parcel locker network densification as the primary defensive lever. Expand automated pickup infrastructure in Romanian secondary cities before first-mover windows close. Integrate real-time customs documentation systems to capture EU digital customs pre-certification advantages. Counter emerging pure-play locker specialists by securing exclusive real estate partnerships in Polish urban cores.
For New Entrants and Emerging Players: EU Green Deal low-emission zone permits in Czechia open a window for electric fleet operators to secure preferential urban access. Target Cluj-Napoca and Timisoara corridors where parcel locker penetration remains underdeveloped. Pursue pharmaceutical distribution partnerships in Romanian regional markets as the anchor go-to-market angle.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-size carriers with stranded diesel fleet assets in Poland and Czechia. Long-term viability hinges on conversion cost recovery timelines and residual value realization for legacy vehicles. Monitor EU digital customs implementation velocity as the inflection signal for cross-border express margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Partnership | EU Green Deal pre-certification unlocks preferential urban access permits in Polish and Czech city centers. |
| Parcel Locker Network Densification | Automated pickup infrastructure in Romanian secondary cities captures emerging e-commerce fulfillment demand. |
| Real-Time Customs Integration | Digital documentation systems secure advance clearance status for cross-border express lanes. |
| Micro-Fulfillment Depot Deployment | City-edge facilities enable zero-emission final-kilometer completion via cargo bike convergence. |
| Robotic Sortation Upgrade | Autonomous mobile robots compress overnight processing windows at Warsaw and Krakow distribution hubs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Central and Eastern European CEP market assessment. Primary interviews with fleet operations directors, e-commerce logistics managers, parcel locker network planners, and customs brokerage specialists combined with bottom-up volume modeling and top-down macroeconomic validation. Secondary sources encompassed EU transport statistics, national road transport inspectorate filings, ECHA chemical documentation registers, and carrier sustainability disclosures.
Data-stream reconciliation across shipment volume databases, fleet registration records, and infrastructure investment trackers informed the analytical framework. Segmentation dimensions modeled included service type, distribution channel, end-use vertical, and package characteristics across the projection horizon. CAGRs derived from trend extrapolation of e-commerce penetration rates, emissions compliance cost trajectories, and automated infrastructure deployment schedules.
The model assumes a particular technology adoption path for electric van and cargo bike convergence; alternative pathways for hydrogen fuel cell last-mile fleets would alter the outlook. Forecasts reflect assumptions regarding EU Green Deal enforcement stringency and digital customs implementation timelines. Deviation in emissions compliance deadlines or cross-border regulatory harmonization velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
France Freight and Logistics Market
Logistics and Shipping
United Arab Emirates Freight and Logistics Market
Logistics and Shipping
North America FMCG Logistics Market
Logistics and Shipping
South Africa Freight and Logistics Market
Logistics and Shipping
Switzerland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Armenia Freight and Logistics Market
Logistics and Shipping
Global Dry Bulk Shipping Market
Logistics and Shipping
North America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Peru Logistics Market
Logistics and Shipping
United States 3PL Market
Logistics and Shipping
Air Cargo Container Market
Logistics and Shipping
North America Cargo Inspection Market
Logistics and Shipping
Qatar Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
South Korea Third-Party Logistics (3PL) Market
Logistics and Shipping
North America Last Mile Delivery Market
Logistics and Shipping
Shipping Container Modification Market