
 North America Logistics Market | 2026-2036
North America Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Logistics Market Intelligence
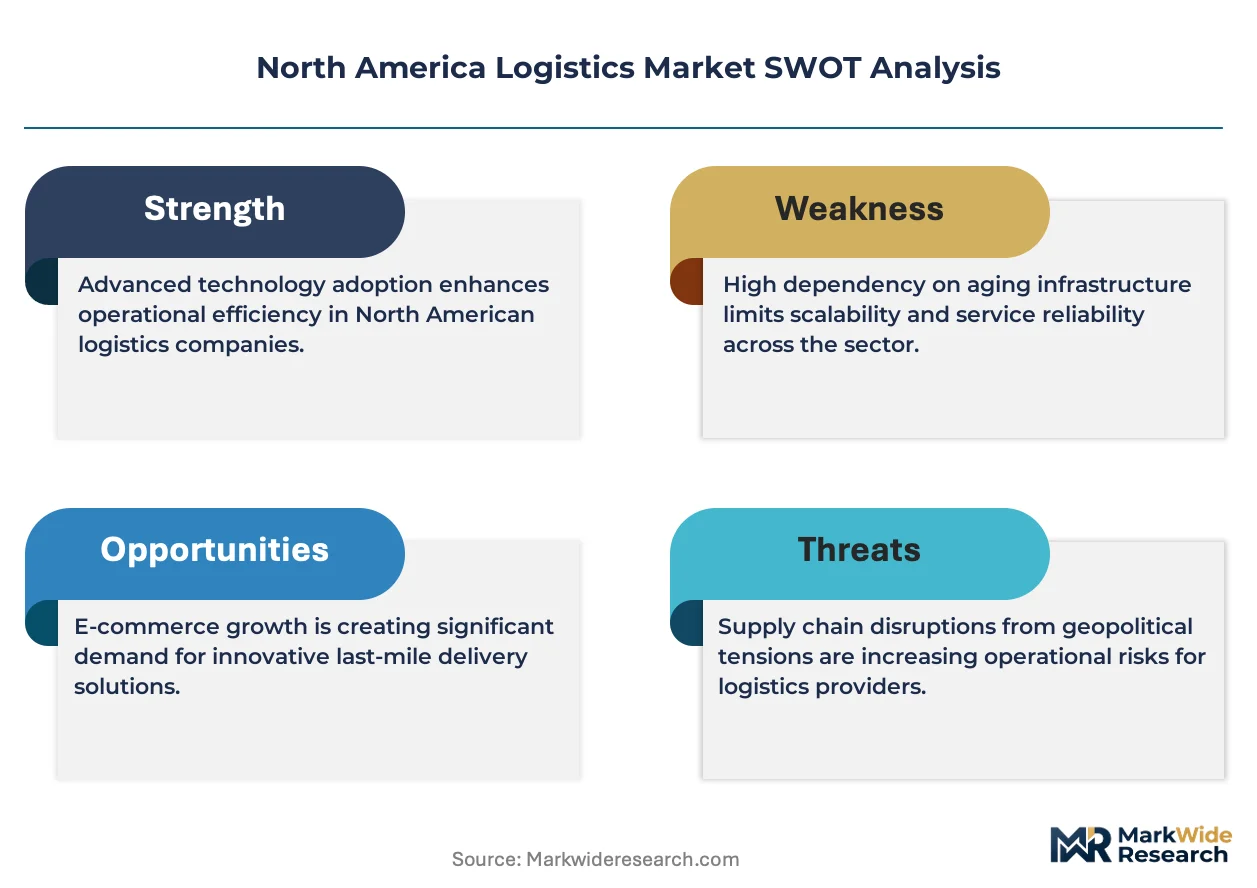
The gap between premium white-glove logistics and commodity freight brokerage is broadening as shippers demand real-time visibility and carbon accounting. C.H. Robinson leverages its digital freight platform to capture mid-market shippers seeking hybrid service tiers. FedEx sustains premium positioning through integrated express and customs brokerage capabilities. XPO specializes in less-than-truckload density economics that commodity players struggle to replicate.
Logistics encompasses the planning, execution, and control of goods movement across multimodal networks, with performance measured by dwell time, cost per hundredweight, and order cycle time. Its primary commercial purpose is synchronizing inventory flows with consumption patterns while minimizing working capital lockup. Transportation services anchor revenue pools across North America, though AI Analytics within the technology segment represents the fastest-expanding margin opportunity as predictive routing reduces empty miles. Warehousing competes on cubic velocity and automation density, while Third-party Providers face consolidation pressure from asset-light digital entrants.
The US EPA, Transport Canada, and FMCSA collectively enforce emissions thresholds, hours-of-service limits, and cross-border credentialing that dictate fleet investment cycles and driver availability. Mexico's Secretariat of Infrastructure, Communications and Transportation coordinates port and rail interoperability standards affecting US-Mexico freight corridors. Stakeholders must weigh electrification capex against regulatory credit values while monitoring autonomous trucking pilot expansions that could reset labor cost structures.
Market Dynamics
The US-Mexico cross-border freight corridor is compressing dwell times through unified customs pre-clearance systems, forcing asset-heavy carriers to rebalance fleet positioning around Laredo-Nuevo Laredo throughput velocity rather than traditional hub-and-spoke density.
Growth Catalysts
- E-commerce fulfillment density:Micro-fulfillment centers within 50 miles of metropolitan cores are pulling refrigerated and last-mile capacity into suburban industrial zones. The Texas manufacturing belt around Austin and San Antonio anchors regional warehouse absorption.
- EPA Phase 3 greenhouse gas standards:Fleet operators face 2027 model-year compliance deadlines that accelerate tractor replacement cycles. Electrified terminal tractors and depot charging infrastructure qualify for IRA commercial clean vehicle credits.
- Nearshoring manufacturing flows:Electronics and automotive suppliers are relocating final assembly to Mexico's Bajío region. This generates dedicated contract logistics demand for just-in-sequence parts delivery to Monterrey and Querétaro plants.
Market Restraints
- Driver availability compression:FMCSA Drug and Alcohol Clearinghouse disqualifications have removed over 100,000 licensed operators from eligibility pools since 2020. Entry-level driver training mandates extend onboarding timelines.
- Cross-border credentialing friction:Mexico's SICT and US CBP operate non-harmonized security certification programs for bonded carriers. Dual compliance adds administrative overhead to US-Mexico lane economics.
- Chassis pool concentration:Ocean carrier-controlled equipment pools dominate intermodal container availability at Los Angeles-Long Beach and Savannah. Equipment imbalance surcharges spike during peak agricultural export windows.
Strategic Opportunities
- Autonomous trucking pilots:Texas Department of Transportation permits allow driver-out operations on I-45 freight corridors between Dallas and Houston. First-motor carriers are securing dedicated lane access agreements with shippers.
- Canada Clean Fuel Regulations credit markets:Biodiesel and renewable natural gas pathway certifications create tradable compliance credits for fleet operators. Transport Canada verification protocols reward early renewable diesel adopters.
- Cold chain pharmaceutical distribution:Temperature-controlled GDP compliance for biologics and cell therapies remains underpenetrated in secondary US markets. Specialized 2-8°C last-mile networks in Phoenix and Denver lack sufficient qualified capacity.
Industry Challenges
- TMS-ELD integration complexity:Legacy transportation management systems require middleware development to ingest real-time hours-of-service data from FMCSA-registered electronic logging devices. Custom API builds strain mid-market IT budgets.
- Carbon accounting verification:Shipper Scope 3 reporting demands conflict with inconsistent fuel consumption measurement methodologies across carrier fleets. Third-party audit standards from Smart Freight Centre remain unevenly adopted.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Logistics Market |
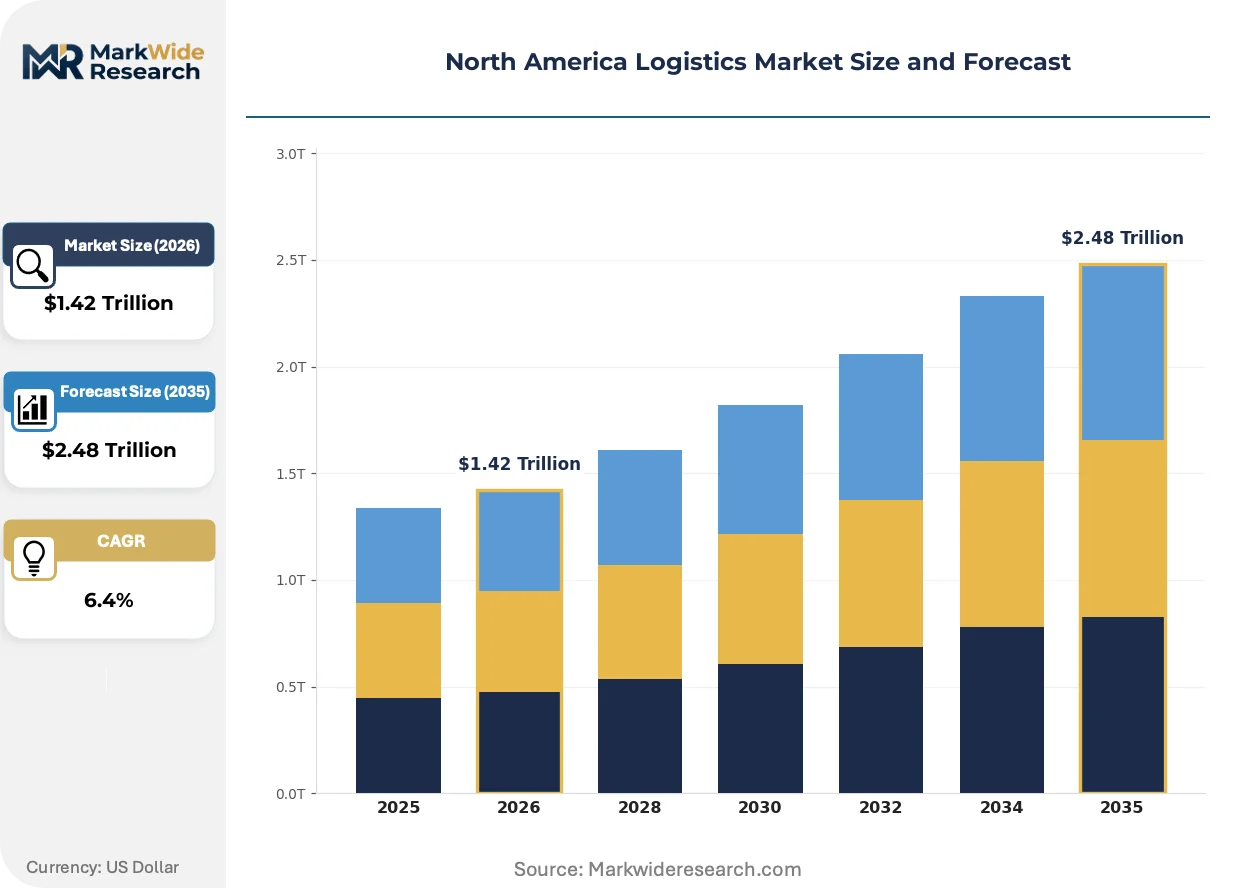
| Market Size in 2026 | $1.42 Trillion |
| Market Size in 2035 | $2.48 Trillion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Distribution Technology: Cloud Computing, IoT Solutions, AI Analytics, Blockchain Customer Type: E-commerce, Retail, Manufacturing, Third-party Providers Delivery Model: Direct Delivery, Same-day Service, Scheduled Delivery, Standard Shipping |
| Companies Covered | C.H. Robinson, DHL Supply Chain & Global Forwarding, FedEx, Ryder Supply Chain Solutions, GXO Logistics, United Parcel Service of America, Inc., XPO, Inc., GEODIS, J.B. Hunt Transport, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Logistics Market Strategic Shifts & Innovations
Artificial intelligence is compressing planning cycles across North American freight networks, replacing static routing tables with dynamic optimization engines that ingest port congestion, weather, and dwell-time signals in real time.
Machine learning freight-matching platforms are consolidating spot market liquidity by algorithmically pairing shipper load tenders with carrier capacity based on predicted empty-mile probabilities. Mid-sized brokerages and asset-light 3PLs are adopting these tools fastest, compressing traditional phone-and-email dispatch workflows into sub-minute matching intervals. The structural consequence is margin compression for commodity freight brokers lacking proprietary data network effects.
Transport Canada's forthcoming Clean Fuel Regulations amendment tightens carbon intensity benchmarks for transportation fuels sold in Canadian provinces. Diesel importers and blenders must secure progressively lower-carbon feedstocks or purchase compliance credits, accelerating renewable diesel refinery investments in Alberta and British Columbia. Cross-border fleets operating Canada-US lanes face bifurcated fuel procurement strategies.
Shippers are unbundling long-term dedicated contract rates from transactional spot exposure, splitting freight portfolios into core volume commitments and surge capacity pools. Food and beverage manufacturers with seasonal harvest windows pioneered this bifurcated procurement model, and automotive suppliers with volatile production schedules are now adopting similar structures. The practice concentrates negotiating leverage with large asset-based carriers for baseline volume while preserving auction-based flexibility for demand spikes.
North America Logistics Market Segmentation
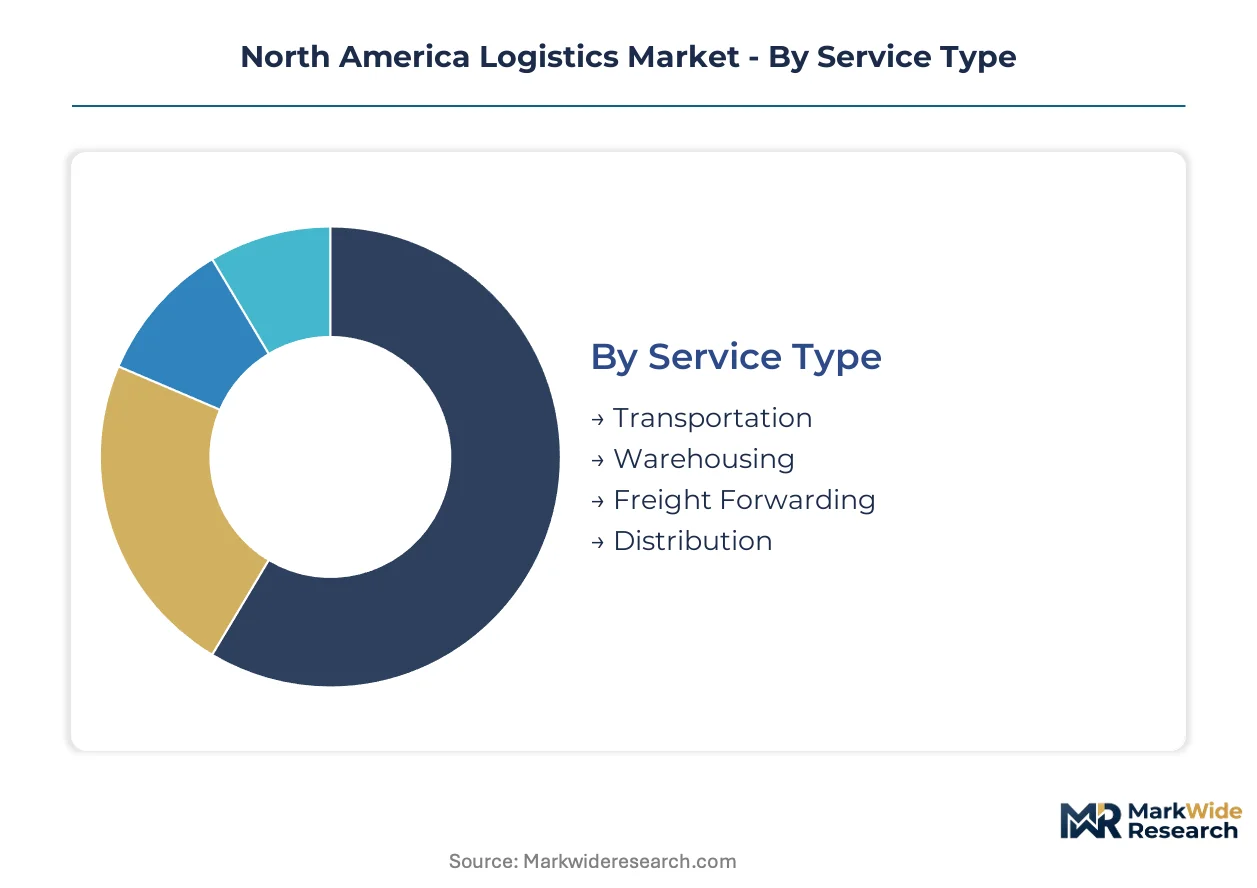
Logistics providers structure operations around service capabilities, technology stacks, and customer procurement patterns. Segmentation reveals where capital concentrates and which delivery models capture premium pricing.
Service Type:
Transportation assets cluster along high-volume corridors where density economics justify dedicated fleet investment.
- Transportation:Truckload and less-than-truckload operations move bulk freight across the US-Mexico corridor. Demand concentrates around Laredo-Nuevo Laredo throughput and the Texas manufacturing belt, driven by nearshoring flows and EPA Phase 3 compliance deadlines accelerating fleet turnover.
- Warehousing:Cubic velocity and automation density determine competitiveness. Micro-fulfillment centers within 50 miles of metropolitan cores anchor regional absorption, particularly in Austin and San Antonio, as e-commerce fulfillment density reshapes suburban industrial zones.
- Freight Forwarding:Customs brokerage and cross-border credentialing expertise differentiate providers. Dual compliance with US CBP and Mexico's SICT programs adds administrative overhead to lane economics.
- Distribution:Last-mile networks synchronize inventory flows with consumption patterns. Temperature-controlled GDP compliance for biologics remains underpenetrated in secondary markets like Phoenix and Denver.
Transportation absorbs the bulk of installed capacity; Warehousing is expanding most quickly.
Technology:
Technology investments track margin pressure points where automation replaces labor-intensive planning workflows.
- Cloud Computing:Scalable infrastructure supports real-time visibility platforms and carrier-shipper data exchange. Mid-market brokerages adopt cloud-based TMS fastest to avoid middleware development costs for ELD integration.
- IoT Solutions:Sensor networks monitor cargo condition, location, and dwell time across multimodal handoffs. Cold chain pharmaceutical distribution relies on continuous 2-8°C monitoring for cell therapy integrity.
- AI Analytics:Predictive routing engines ingest port congestion, weather, and dwell-time signals to reduce empty miles. This segment captures the fastest-expanding margin opportunity as machine learning freight-matching consolidates spot market liquidity.
- Blockchain:Distributed ledger applications focus on document verification and customs credentialing. Cross-border bonded carrier certification programs create audit trail requirements that blockchain architectures address.
Cloud Computing anchors current IT spending; AI Analytics is climbing the fastest as shippers demand predictive capability.
Customer Type:
Customer procurement patterns split between contract volume commitments and surge capacity auctions.
- E-commerce:Fulfillment networks require sub-50-mile last-mile radius and returns processing infrastructure. Micro-fulfillment density in suburban zones pulls refrigerated capacity away from traditional distribution centers.
- Retail:Seasonal demand volatility drives bifurcated procurement models separating baseline volume from surge pools. Food and beverage manufacturers with harvest windows pioneered this structure.
- Manufacturing:Just-in-sequence parts delivery dominates automotive and electronics supply chains. Relocation of final assembly to Mexico's Bajío region generates dedicated contract logistics demand for Monterrey and Querétaro plants.
- Third-party Providers:Asset-light digital entrants consolidate brokerages while specialized 3PLs defend through vertical expertise. Carbon accounting verification capabilities increasingly determine shipper selection.
Manufacturing holds the largest contract logistics footprint; E-commerce is gaining share fastest through fulfillment network expansion.
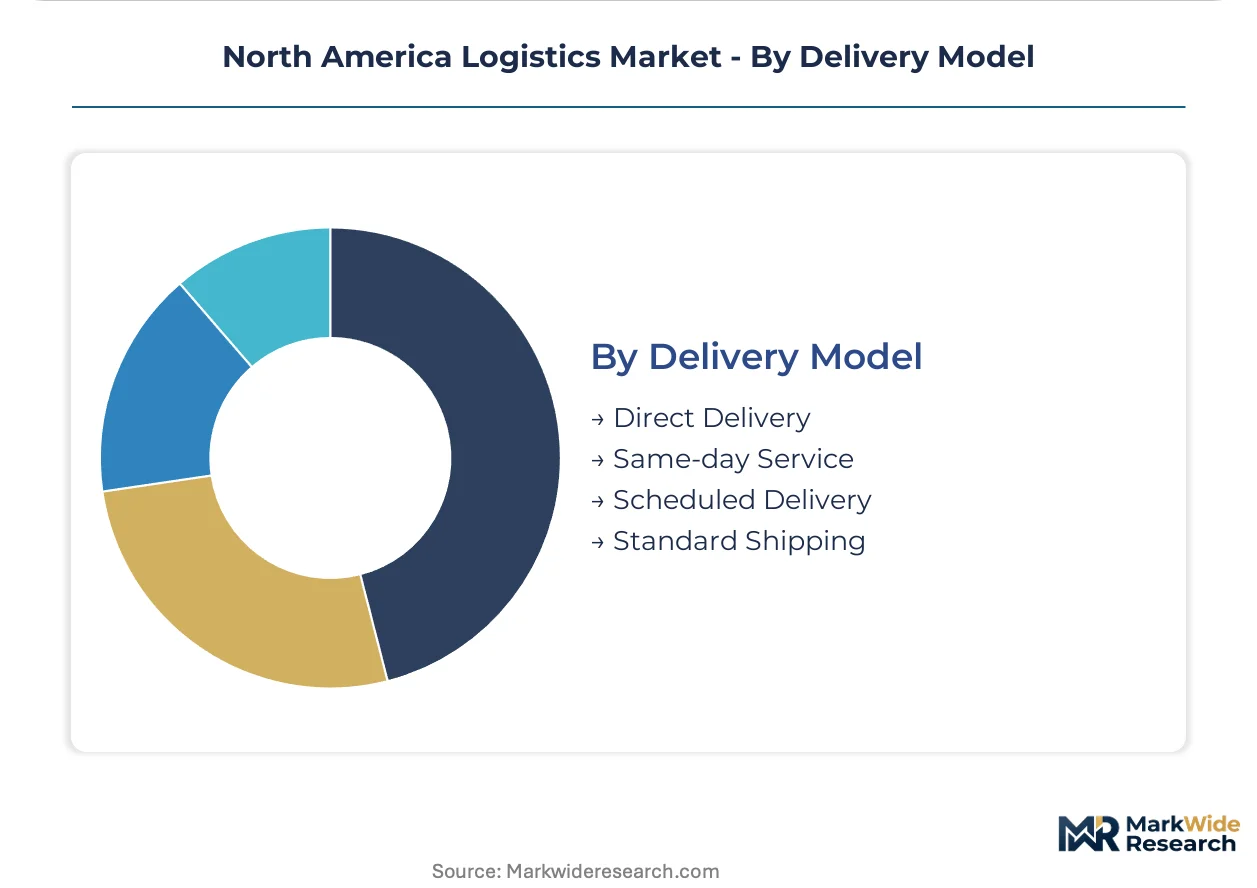
Delivery Model:
Speed tiers stratify pricing and capacity allocation across customer willingness-to-pay gradients.
- Direct Delivery:Point-to-point routing bypasses hub infrastructure for high-value or time-critical shipments. FedEx sustains premium positioning through integrated express and customs brokerage capabilities in this tier.
- Same-day Service:Urban micro-fulfillment networks enable sub-four-hour delivery windows. Grocery and pharmacy categories anchor demand in metropolitan cores with sufficient order density.
- Scheduled Delivery:Appointment-based windows reduce redelivery costs for bulky or installation-required goods. White-glove logistics providers differentiate through real-time visibility and carbon accounting in this segment.
- Standard Shipping:Consolidated line-haul and deferred last-mile minimize unit costs. C.H. Robinson captures mid-market shippers through digital freight platform efficiency in this commoditized tier.
Standard Shipping carries the highest shipment volume; Same-day Service is expanding most quickly as urban fulfillment density increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Laredo-Nuevo Laredo anchors cross-border freight throughput across the North America Logistics Market, processing the densest concentration of US-Mexico truck movements and driving carrier fleet positioning throughout the Texas manufacturing belt.
United States
E-commerce fulfillment density and EPA Phase 3 compliance deadlines dominate logistics investment decisions. The US EPA enforces greenhouse gas standards that accelerate tractor replacement cycles through 2027. The Texas manufacturing belt around Austin and San Antonio absorbs regional warehouse capacity as micro-fulfillment networks expand.
Canada
Cross-border fleet operators face bifurcated fuel procurement under Transport Canada's Clean Fuel Regulations. The regulation mandates progressively lower-carbon transportation fuels and creates tradable compliance credits for early renewable diesel adopters. Alberta and British Columbia anchor renewable diesel refinery investments serving Canada-US lane operators.
Mexico
Nearshoring manufacturing flows from electronics and automotive suppliers concentrate final assembly in the Bajío region. Mexico's Secretariat of Infrastructure, Communications and Transportation coordinates port and rail interoperability standards. Monterrey and Querétaro plants generate dedicated contract logistics demand for just-in-sequence parts delivery.
North America Logistics Market Key Industry Players
Capital-heavy asset-based carriers compete with asset-light digital platforms for shipper wallet share across North America. The market structures around three tiers: integrated express networks, specialized less-than-truckload operators, and technology-enabled brokerages. Strategic moves concentrate on fleet electrification capex deployment and autonomous trucking pilot partnerships that could reset lane economics.
Within the integrated logistics tier, FedEx and United Parcel Service of America, Inc. anchor premium service positioning through customs brokerage and express capabilities. C.H. Robinson occupies the asset-light brokerage archetype, capturing mid-market shippers through digital freight platform efficiency. These three represent contrasting capital intensity models that define competitive boundaries across transportation, warehousing, and forwarding segments.
| Leading Market Players |
|---|
| C.H. Robinson |
| DHL Supply Chain & Global Forwarding |
| FedEx |
| Ryder Supply Chain Solutions |
| GXO Logistics |
| United Parcel Service of America, Inc. |
| XPO, Inc. |
| GEODIS |
| J.B. Hunt Transport, Inc. |
| Others |
Cost & Logistics Intelligence
Premium white-glove logistics and commodity freight brokerage operate as divergent profit pools, with the former commanding rates tied to carbon accounting transparency and real-time visibility while the latter faces algorithmic compression from machine-learning freight-matching platforms. This bifurcation manifests in carrier fleet procurement strategies that prioritize EPA Phase 3 compliance investments for premium tiers versus asset-light digital brokerage models for standard segments.
Pricing Analysis
Value-based pricing anchors on throughput velocity and customs pre-clearance reliability across the US-Mexico corridor. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by carbon certification grade, automation density, and cross-border credentialing completeness. Cost compression in the standard tier intensifies because machine-learning freight-matching consolidates spot market liquidity into sub-minute intervals. Mid-market shippers exhibit highest price sensitivity, while pharmaceutical and automotive manufacturers demonstrate lowest sensitivity due to GDP compliance and just-in-sequence delivery requirements.
Supply Chain Analysis
Direct-to-shipper channels handle contract logistics demand from nearshoring manufacturers, while digital freight platforms aggregate spot capacity for transactional shippers. Geographic supply concentration centers on Mexico's Bajío region for final assembly, the Texas manufacturing belt for warehouse absorption, and the Laredo-Nuevo Laredo corridor for cross-border throughput. Raw material flows draw from Canadian renewable diesel refineries, US EPA-certified tractor manufacturing, and Mexican electronics component suppliers. Single-source vulnerability in ocean carrier-controlled chassis pools at Los Angeles-Long Beach and Savannah creates equipment imbalance surcharges during peak agricultural export windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Logistics Market functions as a cost-of-compliance arena where EPA Phase 3 greenhouse gas standards and Transport Canada Clean Fuel Regulations erect barrier-to-entry moats favoring fleet operators with capital deployment capacity for electrification and renewable diesel infrastructure.
For Market Incumbents: Acquire autonomous trucking lane access agreements with Texas Department of Transportation permits on I-45 freight corridors between Dallas and Houston. Secure dedicated contract logistics relationships with electronics and automotive suppliers relocating final assembly to Monterrey and Querétaro plants. Defensive positioning requires backward integration into depot charging infrastructure qualifying for IRA commercial clean vehicle credits, countering asset-light digital entrants consolidating mid-market brokerages.
For New Entrants and Emerging Players: Launch via cold chain pharmaceutical distribution networks targeting underpenetrated secondary markets in Phoenix and Denver with specialized 2-8°C GDP-compliant last-mile capacity. White-space concentration exists in temperature-controlled cell therapy logistics where qualified capacity scarcity meets biologics demand growth. Go-to-market execution should emphasize carbon accounting verification capabilities aligned with Smart Freight Centre audit standards to differentiate from commodity temperature-controlled carriers.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized less-than-truckload operators with density economics defensible against digital freight-matching compression. Long-term viability over the next decade favors asset-based carriers with integrated customs brokerage and express capabilities serving nearshoring manufacturing flows. Monitor autonomous trucking pilot expansions beyond Texas I-45 corridors as the signal indicating potential labor cost structure resets across lane economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Deployment | IRA commercial clean vehicle credits offset EPA Phase 3 compliance capex for tractor replacement cycles. |
| Autonomous Trucking Lane Access | Texas DOT permits on I-45 corridors enable driver-out operations resetting Dallas-Houston lane economics. |
| Renewable Diesel Refinery Investment | Alberta and British Columbia facilities supply Canada-US lane operators with Transport Canada-verified compliance credits. |
| Micro-Fulfillment Network Expansion | Sub-50-mile last-mile radius infrastructure captures e-commerce fulfillment density in Austin and San Antonio suburban zones. |
| Cross-Border Credentialing Harmonization | Unified customs pre-clearance systems compress dwell times at Laredo-Nuevo Laredo throughput points. |
Research Approach
Multi-period observation of fleet electrification capex flows, cross-border throughput velocity, and carbon credit market development anchored the trend analysis, supplemented by interviews with fleet operations directors, customs brokerage managers, warehouse automation engineers, and shipper procurement leads. Secondary validation drew from FMCSA hours-of-service data, US EPA emissions compliance filings, Transport Canada Clean Fuel Regulations credit registries, and CBP trade statistics. Bottom-up carrier capacity modeling and top-down regional GDP correlation established triangulation boundaries.
Segment-weighting across service type, technology stack, customer procurement pattern, and delivery model tiers shaped the analytical framework over the projection horizon. Transportation, warehousing, freight forwarding, and distribution service categories combined with cloud computing, IoT solutions, AI analytics, and blockchain technology investments formed the segmentation architecture. CAGRs derived from logistic curve adoption modeling for electrified fleet penetration and linear regression for e-commerce fulfillment density expansion, with freight-matching platform transaction velocity and renewable diesel refinery capacity serving as industry-specific forecast inputs.
Regulatory enforcement delays, autonomous trucking permit scope restrictions, and chassis pool concentration shocks are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding EPA Phase 3 compliance timelines and nearshoring manufacturing relocation velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Japan Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Australia Last Mile Delivery Market
Logistics and Shipping
Retail Logistics Market
Logistics and Shipping
Latin America Logistics Market
Logistics and Shipping
Asia-Pacific Shipping Agency Services Market
Logistics and Shipping
Turkey Freight and Logistics Market
Logistics and Shipping
GCC Contract Logistics Market
Logistics and Shipping
Chile Cold Chain Logistics Market
Logistics and Shipping
Bangladesh Freight and Logistics Market
Logistics and Shipping
Ukraine Freight and Logistics Market
Logistics and Shipping
Bangladesh Contract Logistics Market
Logistics and Shipping
First and Last Mile Delivery Market
Logistics and Shipping
Cargo Transportation Market
Logistics and Shipping
Military Logistics Market
Logistics and Shipping
Czech Republic Freight and Logistics Market
Logistics and Shipping
Central and Eastern Europe Freight and Logistics Market