
 Asia Pacific International Express Service Market | 2026-2036
Asia Pacific International Express Service Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific International Express Service Market Insights
Air cargo capacity across Southeast Asian hubs is consolidating as freighter deployments shift toward express-compatible narrow-body conversions. DHL Group leverages its intra-Asia network density to capture pharmaceutical and electronics flows between Singapore, Vietnam, and South Korea. FedEx sustains competitive position through Memphis-Anchorage-Pacific routing architecture that minimizes transit variance for B2B shippers. SF Express anchors its growth on captive e-commerce volume from parent ecosystem affiliates while extending ground-linehaul integration into ASEAN markets.
Asia Pacific international express service encompasses time-definite cross-border parcel and document delivery operating under standardized transit commitments, typically leveraging air freight for intercontinental legs and bonded ground networks for final-mile clearance. The service integrates customs pre-declaration systems, thermal-controlled handling protocols, and real-time track-and-trace infrastructure to serve trade lanes where inventory velocity determines working capital efficiency. Next-day and on-demand service types command premium positioning as electronics and perishable shippers absorb higher unit costs to compress cash conversion cycles. Multimodal delivery modes are gaining structural share where maritime-air combinations balance speed against fuel surcharge exposure on pure aerial lanes. B2B customer segments dominate absolute volume while B2C channels exhibit faster trajectory as marketplace sellers internationalize their fulfillment footprints.
China's MIIT enforces data localization requirements on cross-border logistics platforms, conditioning market access on domestic server architecture and audit transparency. Japan's METI coordinates mutual recognition agreements with ASEAN customs authorities to expediate express clearance for qualified operators under AEO frameworks. India's DGFT maintains export documentation standards that express carriers must embed into pre-shipment data feeds to avoid terminal delays. Stakeholders must weigh regulatory compliance investment against network autonomy as digital trade governance fragments across jurisdictions.
Market Dynamics
Cross-border e-commerce velocity is compressing clearance timelines across Southeast Asian corridors, forcing express operators to pre-position inventory closer to consumption nodes before final-mile dispatch.
Growth Catalysts
- Customs digitization:ASEAN Single Window protocols slash documentary inspection hours at Malaysian and Thai border posts, accelerating pharmaceutical and electronics flows.
- Thermal-controlled narrow-body conversions:Refrigerated express compartments on converted 737-800 freighters enable ambient-sensitive cargo lanes previously restricted to wide-body schedules.
- India's pharmaceutical export density:DGFT documentation automation embeds pre-shipment data feeds directly into carrier systems, eliminating terminal queuing for temperature-validated shipments.
Market Restraints
- Aviation fuel surcharge volatility:Jet kerosene price swings transmit directly to unit economics on aerial legs, squeezing margin on economy-tier shipments.
- Hub concentration risk:Singapore Changi and Hong Kong International Airport handle disproportionate intra-Asia transshipment volumes, creating systemic exposure to weather or labor disruptions.
- Data localization compliance costs:China's MIIT mandates domestic server architecture for cross-border logistics platforms, fragmenting IT infrastructure across jurisdictional boundaries.
Strategic Opportunities
- Vietnam-Indonesia corridor expansion:Underpenetrated manufacturing zones in Ho Chi Minh City and Jakarta offer first-mover positioning for bonded ground-linehaul networks.
- Maritime-air multimodal combinations:Sea freight from Shanghai to Singapore followed by express aerial dispatch cuts fuel exposure versus pure air routing for non-urgent electronics.
- Japan-ASEAN AEO mutual recognition:METI-coordinated qualified operator frameworks expedite customs clearance for pre-certified express carriers, creating regulatory preference moats.
Industry Challenges
- Customs-brokerage talent scarcity:Shortage of personnel fluent in both ASEAN tariff schedules and Chinese GB standards delays clearance optimization.
- Legacy WMS integration friction:Bonded warehouse management systems at older facilities resist real-time data handoffs to carrier track-and-trace platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific International Express Service Market |
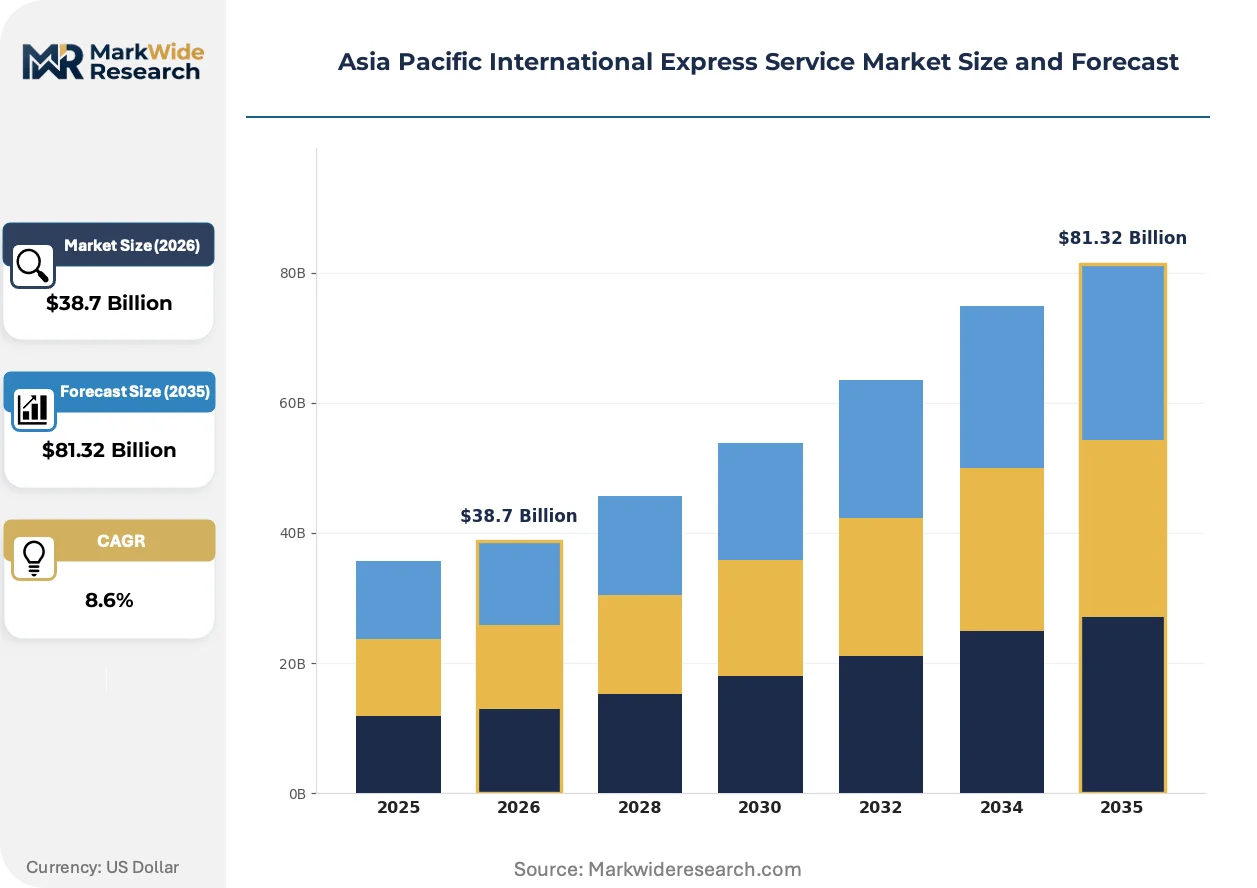
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $81.32 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same Day, Next Day, On-Demand, Scheduled Delivery Mode: Aerial, Ground, Maritime, Multimodal End User: Retailers, E-Commerce, Manufacturers, Event Organizers Customer Type: B2B, B2C, Small Enterprises, Corporates |
| Companies Covered | China Post, DHL Group, FedEx, United Parcel Service, SF Express, CJ Logistics, Yamato Holdings, Blue Dart Express, Aramex, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific International Express Service Market Trends and Innovations
Express operators are absorbing predictive analytics into pre-clearance workflows, compressing the interval between cargo arrival and customs release. This shift reconfigures competitive advantage around data latency rather than pure aerial speed.
Machine-learning cargo screening is absorbing pattern-recognition duties from manual document review at Singapore and Incheon hubs. Pharmaceutical shippers with temperature-validated supply chains are adopting these lanes fastest. The technology is absorbing compliance labor costs while shrinking inspection variance for high-value electronics flows.
Japan's METI is expanding AEO mutual recognition to cover Vietnam and the Philippines, conditioning expedited clearance on real-time data transparency. Electronics manufacturers with just-in-time inventory models are restructuring supplier contracts around these qualified operator lanes. South Korean semiconductor exporters are migrating volume toward METI-preferred routing to lock in transit-time certainty.
Shippers are unbundling after-sales logistics from product purchase contracts, treating express delivery as a separately procured working-capital service. Electronics marketplace sellers in Shenzhen and Guangzhou are piloting this model most aggressively. The shift is most visible in cross-border B2C channels where inventory velocity directly determines seller cash conversion cycles on platform settlement timelines.
Asia Pacific International Express Service Market Segmentation
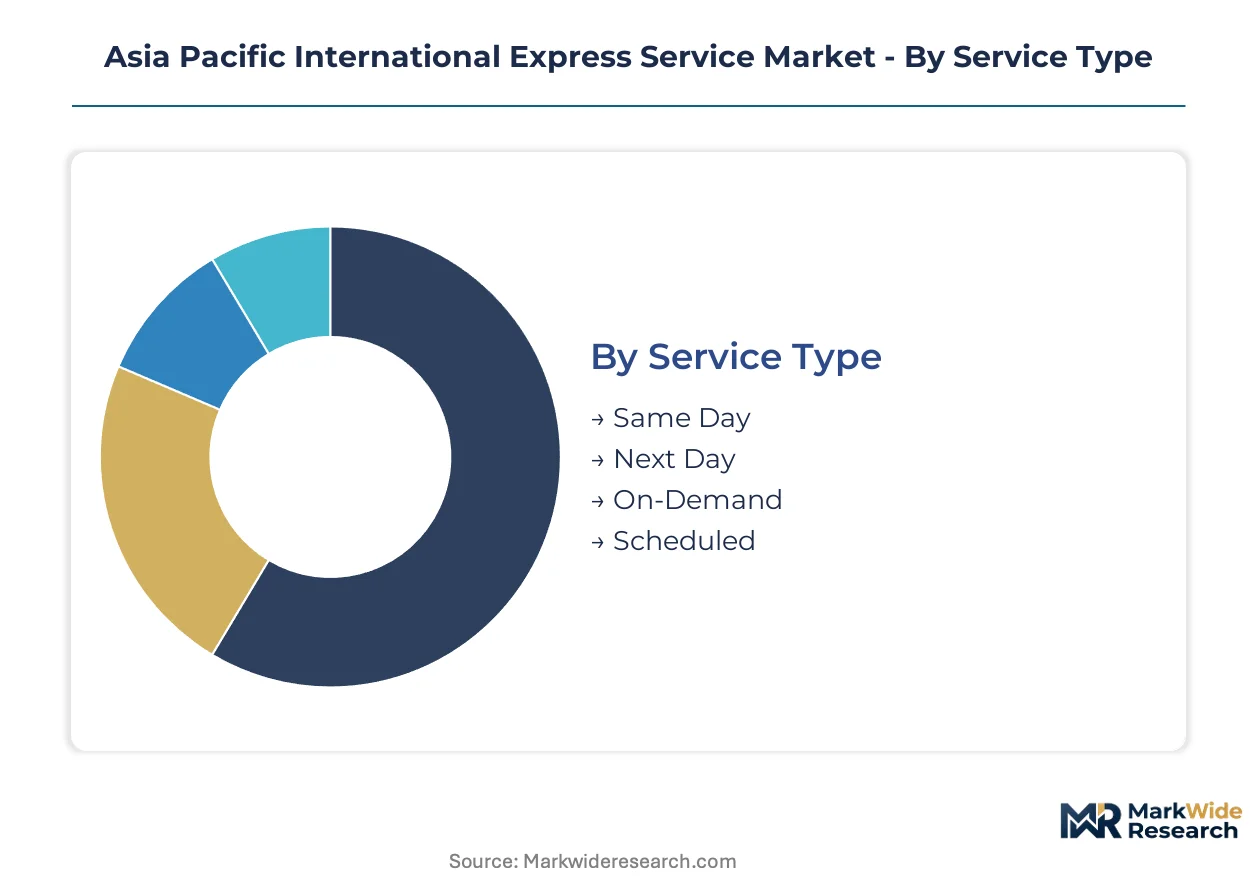
Segmentation in Asia Pacific international express services reveals how capital deployment, operational complexity, and customer economics diverge across service tiers. Express operators allocate fleet and customs infrastructure based on these divisions, with premium segments commanding dedicated freighter capacity while economy tiers absorb network slack.
Service Type:
Capital intensity peaks with same-day networks requiring owned aircraft and bonded warehouse pre-positioning, while scheduled services leverage third-party capacity with minimal fixed asset exposure.
- Same Day:Dedicated narrow-body freighters and helicopter transfers serve financial document and emergency pharmaceutical flows between Singapore, Hong Kong, and Shanghai. Singapore's sovereign wealth-backed logistics funds anchor the densest same-day infrastructure in Southeast Asia.
- Next Day:Standardized cut-off times and consolidated air cargo bookings balance speed against unit economics for electronics manufacturers with just-in-time inventory models. Vietnam's export manufacturing zones generate the steepest volume climb for next-day lanes into European and North American markets.
- On-Demand:API-triggered dispatch through gig-economy ground fleets supplements core aerial networks for intra-city urgent delivery.
- Scheduled:Fixed-frequency consolidation services absorb excess postal and non-urgent B2B volume through deferred routing.
Next Day absorbs the bulk of installed capacity; On-Demand is expanding most quickly.
Delivery Mode:
Operating cost structures fragment sharply across modes, with fuel surcharge exposure driving shippers toward maritime-air combinations on non-urgent lanes.
- Aerial:Pure air freight dominates time-definite commitments above 48 hours, with narrow-body conversions replacing aging wide-body freighters on intra-Asia lanes. India's DGFT documentation automation embeds directly into carrier pre-clearance systems, accelerating pharmaceutical flows through Mumbai and Delhi.
- Multimodal:Sea freight from Shanghai to Singapore followed by express aerial dispatch cuts fuel exposure by 30-40% versus pure air routing for electronics with flexible delivery windows. South Korean semiconductor exporters are restructuring supplier contracts around these hybrid lanes to lock in transit-time certainty.
- Ground:Bonded truck networks connect manufacturing clusters across the Mekong sub-region, with customs pre-clearance at Thai border posts.
- Maritime:Containerized express services capture non-urgent document and low-value parcel flows between secondary Chinese ports and ASEAN manufacturing zones.
Aerial commands the highest revenue per kilogram; Multimodal is gaining share fastest as fuel volatility reshapes shipper preferences.
End User:
Inventory velocity requirements and documentation complexity vary dramatically across end-user categories, conditioning carrier service design and pricing architecture.
- Manufacturers:Electronics and automotive component shippers dominate absolute tonnage, with just-in-time models demanding customs pre-clearance and thermal-validated handling. China's MIIT data localization mandates force these shippers to maintain duplicate IT infrastructure for cross-border logistics visibility.
- E-Commerce:Marketplace sellers in Shenzhen and Guangzhou are unbundling after-sales logistics from product purchase contracts, treating express delivery as separately procured working-capital services. Indonesia's cross-border marketplace regulations are compressing clearance timelines, forcing pre-positioned inventory models.
- Retailers:Department store chains and luxury brands utilize express for seasonal replenishment and reverse logistics.
- Event Organizers:Time-critical exhibition and conference materials require specialized handling protocols and dedicated customer service lanes.
Manufacturers anchor absolute volume; E-Commerce is climbing the fastest as marketplace sellers internationalize fulfillment footprints.
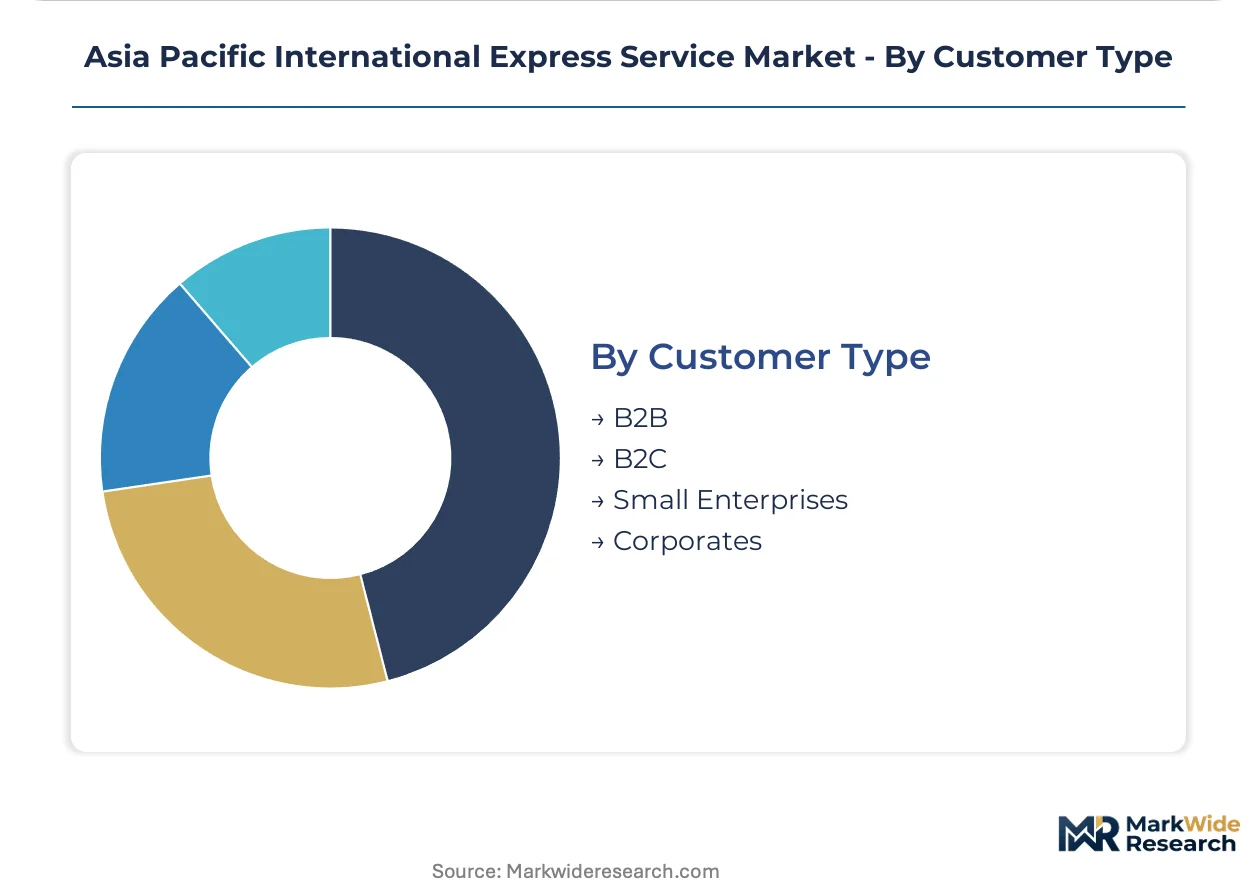
Customer Type:
Contract structures and margin profiles diverge between enterprise accounts with dedicated service teams and transactional small-enterprise volume.
- B2B:Long-term contracts with electronics and pharmaceutical shippers provide revenue predictability and drive network density investments. Japan's METI AEO mutual recognition frameworks create regulatory preference moats for qualified operators serving these accounts.
- Corporates:Large enterprises with centralized procurement negotiate volume-based pricing and service level agreements spanning multiple trade lanes.
- B2C:Individual marketplace buyers absorb higher per-unit costs for delivery certainty, with cash conversion cycle pressure driving premium service selection.
- Small Enterprises:Aggregated through platform APIs and postal partnerships, this segment generates fill capacity on existing networks with minimal incremental cost.
B2B locks in the majority of contracted revenue; B2C is expanding most quickly as cross-border marketplace penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jet fuel refining capacity concentrated in Singapore and South Korea anchors the Asia Pacific express service infrastructure, conditioning network economics across manufacturing corridors from Ho Chi Minh City to Mumbai.
China
Electronics manufacturing clusters in Shenzhen and Dongguan generate dense time-definite shipment demand to European and North American markets. MIIT data localization mandates force express operators to maintain domestic server architecture for cross-border logistics visibility. The Yangtze River Delta around Shanghai anchors pharmaceutical and semiconductor export flows through Pudong International Airport.
India
Pharmaceutical exporters in Hyderabad and Ahmedabad drive temperature-validated express volume to regulated markets in Europe and the United States. DGFT documentation automation embeds pre-shipment data feeds directly into carrier systems, eliminating terminal queuing. Mumbai's Chhatrapati Shivaji International Airport handles the densest pharmaceutical express traffic in South Asia.
Vietnam
Electronics contract manufacturers in Bac Ninh and Hai Phong provinces generate next-day shipment demand to South Korean and Japanese assembly facilities. ASEAN Single Window protocols slash documentary inspection hours at border posts with Cambodia and Laos. Ho Chi Minh City anchors bonded ground-linehaul networks extending into the Mekong Delta manufacturing zones.
South Korea
Semiconductor exporters in Pyeongtaek and Icheon demand transit-time certainty for just-in-time inventory models serving Chinese electronics assemblers. Incheon International Airport deploys machine-learning cargo screening to absorb pattern-recognition duties from manual document review. The Seoul Capital Area concentrates the highest express revenue per kilogram in Northeast Asia.
Indonesia
Cross-border marketplace sellers in Jakarta and Surabaya compress clearance timelines through pre-positioned inventory models serving ASEAN consumer markets. Customs digitization accelerates clearance speeds at Tanjung Priok port for maritime-air multimodal combinations. The Jakarta-Bandung corridor anchors bonded truck networks connecting manufacturing clusters to Soekarno-Hatta International Airport.
Asia Pacific International Express Service Market Competitive Landscape
Global majors compete with regional champions across network density and customs integration capabilities. The market structures around three tiers: integrated global networks with owned freighter capacity, Asia-centric specialists leveraging intra-regional ground-linehaul density, and postal operators with last-mile reach into secondary cities. Strategic moves concentrate on bonded warehouse pre-positioning and AEO qualification to secure customs preference moats.
Within the integrated global tier, DHL Group, FedEx, and United Parcel Service occupy positions defined by intercontinental routing architecture and customs pre-clearance capabilities. These operators exemplify the network-scale archetype where Memphis-Anchorage-Pacific routing minimizes transit variance. Among Asia-centric specialists, SF Express and CJ Logistics represent regional champions extending ground-linehaul integration into ASEAN markets. China Post anchors the postal operator archetype with captive last-mile density into tier-three Chinese cities.
| Leading Market Players |
|---|
| China Post |
| DHL Group |
| FedEx |
| United Parcel Service |
| SF Express |
| CJ Logistics |
| Yamato Holdings |
| Blue Dart Express |
| Aramex |
| Others |
Pricing and Supply Chain Analysis
Same-day premium tiers and deferred scheduled services diverge sharply across the Asia Pacific international express market, with the former embedding dedicated freighter capacity and bonded pre-positioning while the latter absorbs network slack through third-party aerial bookings. This bifurcation concentrates pricing power with operators controlling narrow-body conversions and thermal-validated handling protocols, particularly on pharmaceutical corridors from India and electronics lanes from Vietnam.
Pricing Analysis
Warranty and service bundling separates premium express tiers from economy positioning, with same-day and next-day commitments embedding customs pre-clearance and thermal validation while scheduled services strip these to bare transit. Three-tier pricing structure across premium, standard, and economy levels reflects fuel surcharge exposure, with aerial legs commanding premium positioning against maritime-air multimodal alternatives. Cost compression in economy tiers intensifies as jet kerosene volatility transmits directly to unit economics, squeezing margin on deferred routing. Small enterprise marketplace sellers exhibit highest price sensitivity, absorbing higher per-unit costs only when cash conversion cycle pressure demands delivery certainty.
Supply Chain Analysis
Workforce availability constraints in Vietnam's Bac Ninh province and Indonesia's Jakarta-Bandung corridor are reshaping bonded ground-linehaul network deployment decisions. Manufacturing concentration centers on China, Vietnam, and India, with electronics clusters in Shenzhen and Dongguan and pharmaceutical exporters in Hyderabad anchoring densest demand corridors. Freighter conversions and thermal-controlled narrow-body retrofits draw from aviation MRO capacity concentrated in Singapore and South Korea. Single-source vulnerability runs through hub concentration at Singapore Changi and Hong Kong International Airport, creating systemic exposure to weather or labor disruptions. Distribution runs through integrated carrier networks with owned aerial capacity, postal partnerships for last-mile reach, and emerging gig-economy ground fleets for on-demand dispatch.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
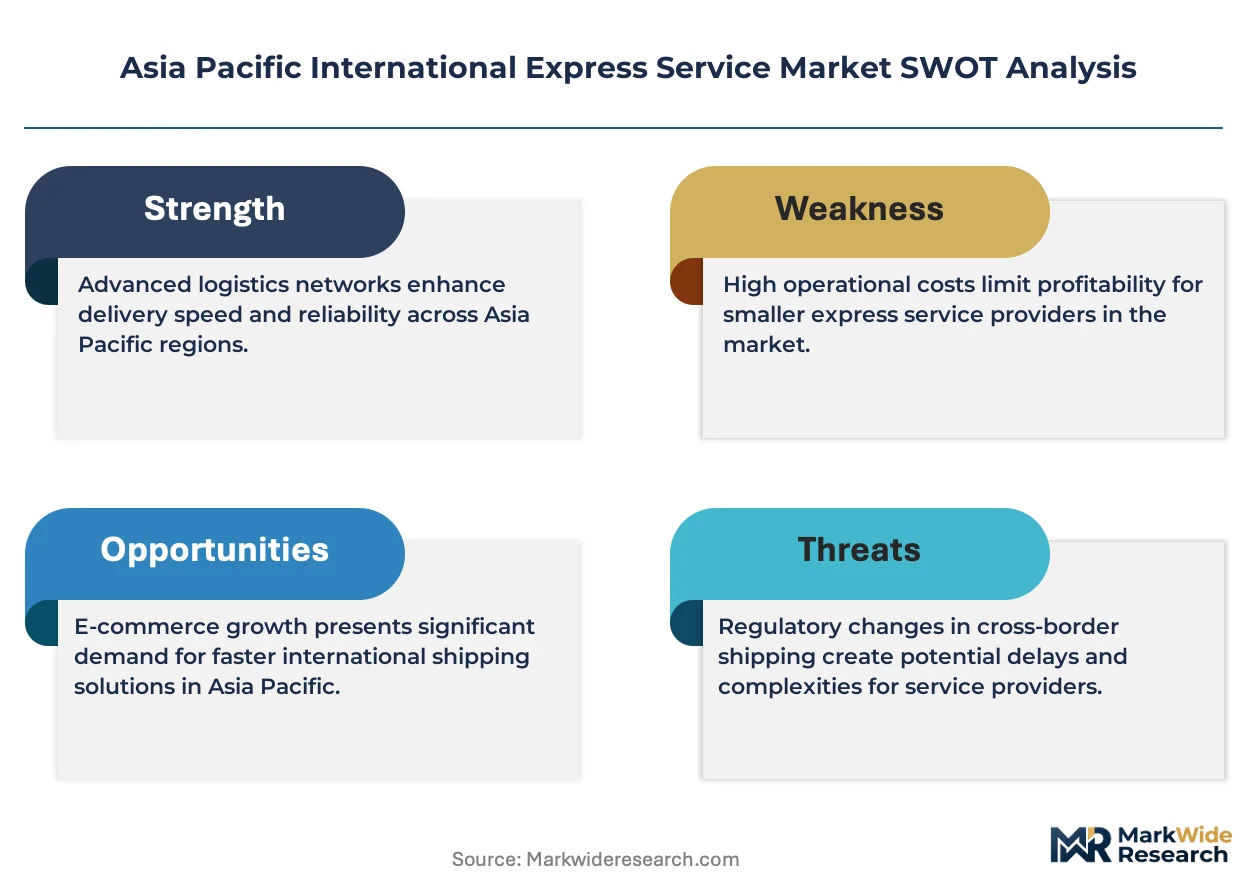
Consolidation pressure is intensifying across the Asia Pacific international express market as aviation fuel surcharge volatility and data localization compliance costs force sub-scale operators toward exit or acquisition. This structural pressure favors network-dense incumbents with captive freighter capacity and AEO-qualified customs integration.
For Market Incumbents: Deploy AEO mutual recognition frameworks as defensive moats, particularly leveraging Japan's METI-coordinated qualified operator status to lock in pharmaceutical and electronics flows. Add narrow-body freighter capacity at Vietnamese and Indonesian hubs before competitor pre-positioning solidifies. Threat from SF Express's ground-linehaul integration into ASEAN markets demands accelerated bonded warehouse investment in Ho Chi Minh City and Jakarta.
For New Entrants and Emerging Players: Capture underpenetrated maritime-air multimodal lanes connecting Shanghai to Singapore for non-urgent electronics flows, where fuel exposure concerns have reshaped shipper preferences toward hybrid routing. Target Vietnam-Indonesia corridor expansion with bonded truck networks and customs pre-clearance capabilities at Thai border posts. Go-to-market angle should emphasize API-triggered dispatch integration with cross-border marketplace platforms serving Jakarta and Surabaya sellers.
For Investors and Strategic Acquirers: Re-rating potential sits with Asia-centric specialists possessing dense intra-regional ground-linehaul networks given accelerating customs digitization and ASEAN Single Window protocol expansion. Long-term viability over the next decade hinges on regulatory compliance infrastructure rather than pure aerial speed. Acquisition target archetype: regional operators with AEO-qualified status and captive narrow-body freighter capacity. Signal to watch: METI expansion of mutual recognition to Vietnam and the Philippines as inflection indicator for qualified operator lane restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| AEO Qualification Investment | Japan's METI frameworks create customs preference moats for pre-certified operators serving pharmaceutical corridors. |
| Narrow-Body Freighter Conversion | Thermal-controlled 737-800 retrofits enable ambient-sensitive cargo lanes previously restricted to wide-body schedules. |
| Bonded Warehouse Pre-Positioning | Ho Chi Minh City and Jakarta facilities compress final-mile dispatch intervals for cross-border e-commerce velocity. |
| Maritime-Air Multimodal Expansion | Shanghai-Singapore sea freight followed by express aerial dispatch cuts fuel exposure versus pure air routing. |
| API Integration with Marketplace Platforms | Shenzhen and Guangzhou sellers unbundle after-sales logistics as separately procured working-capital services. |
Research Methodology
Independent corroboration across customs authority documentation, carrier network disclosures, and cross-border e-commerce platform data underwrites the qualitative findings in this study. Primary interviews with express carrier network planners, pharmaceutical supply chain directors, electronics manufacturing logistics leads, and ASEAN customs administration officials combined with secondary validation from DGFT automation protocols, METI mutual recognition frameworks, and MIIT data localization mandates. Bottom-up volume modeling across service type, delivery mode, and end-user segments triangulated against top-down macro trade flow analysis.
Rate-of-change decomposition anchored the analytical framework across the projection horizon, segmenting by service tier commitment, modal configuration, and customer contract structure. Modeling incorporated aerial capacity deployment patterns, fuel surcharge pass-through mechanisms, and customs digitization adoption curves as industry-specific forecast inputs. CAGRs derived from installed base expansion, network density investments, and trade lane velocity requirements rather than extrapolated historical trends.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to aviation fuel price volatility, regulatory fragmentation across MIIT and DGFT jurisdictions, and hub concentration risk at Singapore Changi and Hong Kong International Airport. Forecasts reflect documented assumptions regarding customs digitization timelines and AEO mutual recognition expansion. Material deviation in jet kerosene pricing regimes or ASEAN Single Window implementation pace warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Asean Freight Forwarding Market
Logistics and Shipping
North America Refrigerated Container Shipping Market
Logistics and Shipping
Global Load Planning Services and Solutions Market
Logistics and Shipping
Nigeria Third-Party Logistics (3PL) Market
Logistics and Shipping
Egypt Freight and Logistics Market
Logistics and Shipping
Event Logistics Market
Logistics and Shipping
Illinois Freight and Logistics Market
Logistics and Shipping
Global Courier Market
Logistics and Shipping
Australia 3PL Market
Logistics and Shipping
Saudi Arabia Freight and Logistics Market
Logistics and Shipping
New Zealand Freight and Logistics Market
Logistics and Shipping
Spare Part Logistics Market
Logistics and Shipping
Courier, Express and Parcel Services Market
Logistics and Shipping
US Courier, Express, and Parcel Market
Logistics and Shipping
GCC Contract Logistics Market
Logistics and Shipping
Global Air Cargo and Freight Logistics Market