
 United States Apparel Logistics Market | 2026-2036
United States Apparel Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
United States Apparel Logistics Market Insights
ISO 9001 certification for quality management systems is unwinding competitive access in apparel logistics, favoring operators with documented process controls. Deutsche Post DHL Group leverages its domestic ground network to anchor next-day delivery commitments for fashion brands. XPO Logistics competes through specialized final-mile solutions for high-velocity e-commerce apparel. FedEx sustains advantage via integrated air-ground infrastructure that supports seasonal surge capacity.
United States apparel logistics encompasses the planning, execution, and control of garment movement from manufacturing origins through wholesale and retail channels, typically requiring temperature-controlled storage for sensitive textiles and real-time shipment visibility across multi-node networks. RFID tagging and automated sorting systems enable piece-level tracking through distribution centers, reducing mis-shipment rates for SKU-intensive fashion inventories. Warehousing services capture the largest service type segment as brands maintain safety stock to buffer against demand volatility. Third-party logistics delivery modes are expanding fastest among client types, as mid-size apparel brands outsource fulfillment rather than build captive networks.
The Federal Motor Carrier Safety Administration shapes carrier availability through hours-of-service enforcement, while OSHA warehouse safety standards influence automation investment decisions. EPA emissions regulations for heavy-duty trucks push fleet operators toward alternative fuel vehicles in California corridor routes. Stakeholders must weigh compliance costs against service-level commitments as regulatory density intensifies in high-volume freight lanes.
Market Dynamics
The Federal Motor Carrier Safety Administration's tightened hours-of-service enforcement is compressing driver availability across long-haul freight lanes serving Southeast distribution clusters. This regulatory pressure is forcing apparel logistics operators to reconfigure network topology and accelerate automation investments.
Growth Catalysts
- Savannah-Charleston port expansion:Container terminal capacity additions at these Georgia and South Carolina gateways are drawing e-commerce fulfillment center investment from omnichannel retailers seeking reduced inland drayage distances.
- ISO 9001 certification requirements:Quality management system documentation is becoming a gatekeeping standard for vendor qualification by major fashion brands, favoring established third-party logistics operators with process audit trails.
- RFID-enabled piece-level tracking:Automated sorting systems with radio-frequency identification tagging are reducing mis-shipment rates for SKU-intensive inventories across multi-node distribution networks.
Market Restraints
- Driver labor scarcity:FMCSA hours-of-service rules are constraining effective capacity per tractor, while wage inflation in the Southeast trucking corridor erodes operating margins for asset-based carriers.
- California emissions mandates:EPA heavy-duty truck standards combined with state-level zero-emission requirements are forcing premature fleet turnover on West Coast lanes serving trans-Pacific apparel imports.
- Real estate cost concentration:Industrial warehouse rents in the I-85/I-95 corridor near Atlanta and Greenville-Spartanburg are appreciating faster than national averages, squeezing network expansion economics.
Strategic Opportunities
- Mid-market brand outsourcing:Apparel companies with $50-200 million annual revenue are abandoning captive fulfillment to access specialized final-mile capabilities without capital deployment.
- OSHA automation incentives:Warehouse safety standards are accelerating robot deployment for pallet handling and sortation, creating first-mover advantages for operators with installed collaborative robotics.
- Nearshoring freight pivot:Manufacturing relocation from Asia to Mexico and Central America is rerouting container flows through Gulf Coast ports, opening new intermodal hub opportunities in Texas and Louisiana.
Industry Challenges
- Automation integration complexity:Legacy warehouse management systems require costly middleware development to interface with autonomous mobile robots and AI-driven demand forecasting platforms.
- Seasonal surge staffing:Peak holiday volume spikes demand temporary workforce scaling that conflicts with FMCSA driver qualification timelines and OSHA training mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Apparel Logistics Market |
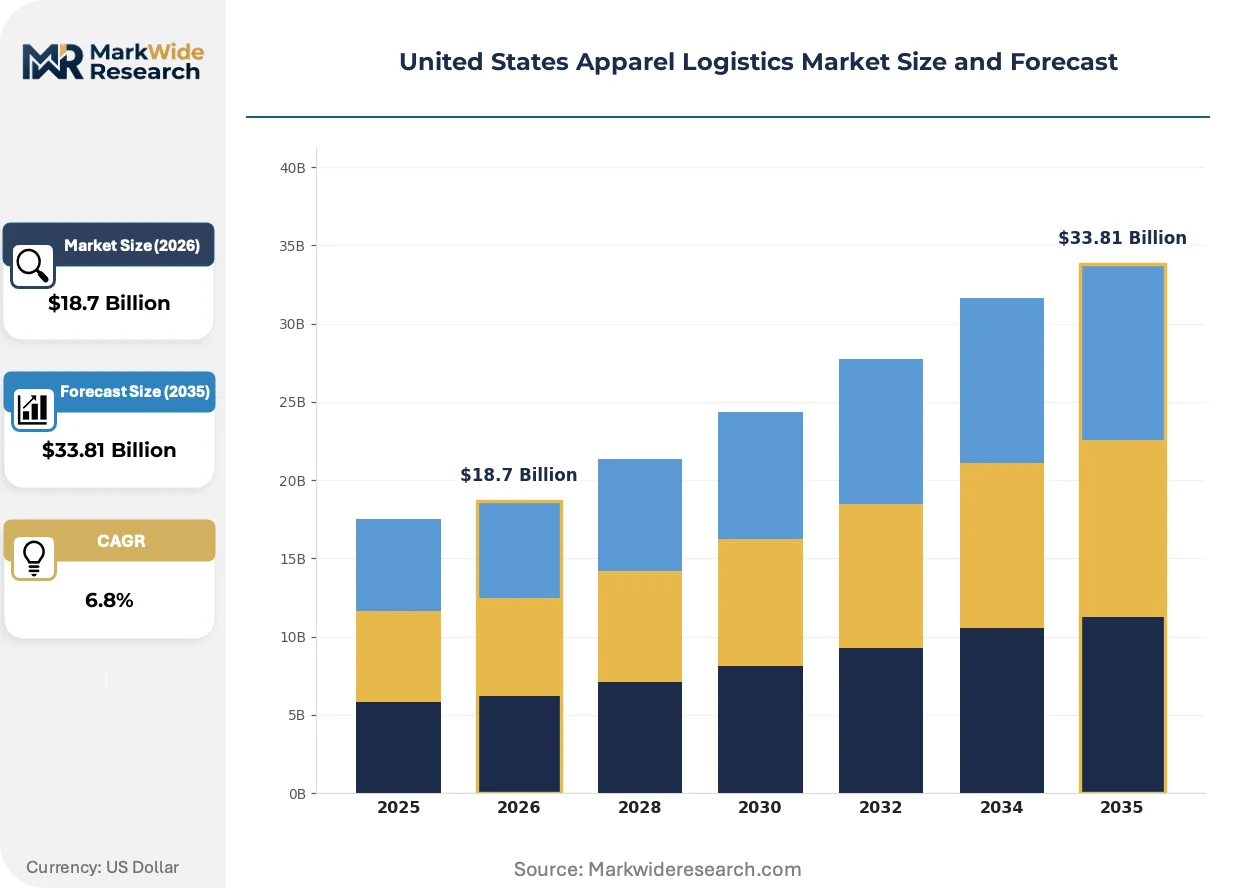
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Distribution, Inventory Management Client Type: Retailers, Manufacturers, E-commerce, Wholesalers Delivery Mode: Direct Shipping, Cross-Dock, Drop Shipping, Third-Party Logistics Technology: RFID, Barcode Scanning, Automated Sorting, Inventory Software |
| Companies Covered | CEVA Logistics, DB Schenker, Deutsche Post DHL Group, DSV, Hellmann Worldwide Logistics, Kuehne + Nagel, XPO Logistics, FedEx, UPS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Apparel Logistics Market Trends and Innovations
Apparel logistics is undergoing operational recalibration as regulatory density intersects with automation maturation and demand signal fragmentation. Three developments are restructuring competitive capabilities across the sector.
Autonomous mobile robots with vision-guided picking capabilities are supplanting conventional conveyor-and-sorter configurations in high-velocity e-commerce fulfillment centers. Fashion brands with direct-to-consumer channels exceeding 30% of revenue are deploying these systems at pace, compressing order cycle times from four hours to 90 minutes while reducing labor dependency in the Southeast distribution corridor.
The EPA's Phase 3 greenhouse gas standards for heavy-duty vehicles are mandating alternative fuel adoption across California freight corridors serving Los Angeles-Long Beach apparel imports. Fleet operators face 2027 compliance deadlines requiring electric or hydrogen tractor deployment, with drayage carriers bearing disproportionate capital burden due to short-haul duty cycles that favor battery-electric technology.
Buy-side consolidation among specialty apparel retailers is compressing vendor qualification timelines while elevating service-level requirements. Regional boutique chains are consolidating procurement through cooperative buying groups, replacing fragmented direct relationships with centralized third-party logistics contracts that demand ISO-certified quality documentation and real-time inventory visibility across the Southeast distribution network.
United States Apparel Logistics Market Segmentation
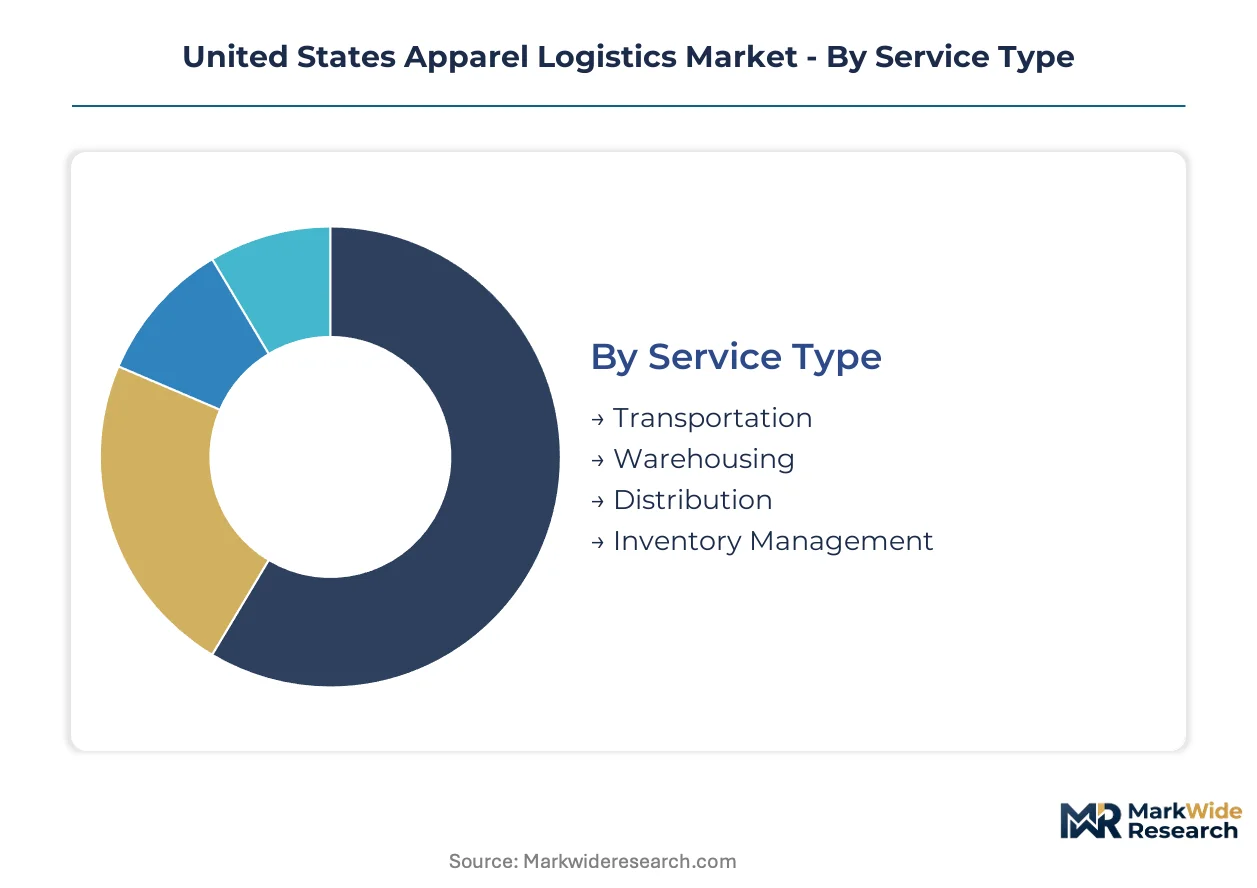
Segmentation in United States apparel logistics reveals how service specialization and technology deployment create divergent margin profiles across customer tiers. Understanding these splits helps operators prioritize capital allocation between asset-heavy warehousing and technology-enabled visibility platforms.
Service Type:
Substitution pressure runs strongest against pure-play transportation providers as integrated operators bundle warehousing with freight management, eroding standalone trucking margins.
- Transportation:Full-truckload and less-than-truckload movements connect port gateways to distribution clusters, with drayage from Savannah and Charleston commanding premium rates amid chassis shortages. FMCSA hours-of-service enforcement compresses driver availability on Southeast corridors serving fast-fashion replenishment cycles.
- Warehousing:Multi-client facilities with temperature-controlled zones store seasonal inventory buffers for omnichannel retailers, commanding higher per-pallet rates than ambient storage through value-added services like garment-on-hanger processing. Demand concentrates near the I-85 corridor where Atlanta and Greenville-Spartanburg industrial rents appreciate fastest.
- Distribution:Cross-dock operations consolidate inbound container freight for outbound parcel injection, reducing dwell time for time-sensitive fashion SKUs.
- Inventory Management:Vendor-managed inventory programs shift working capital burden from apparel brands to logistics operators with balance sheet capacity.
Warehousing retains volume leadership; inventory management holds the steepest expansion curve.
Client Type:
Cost tier stratification separates enterprise accounts with dedicated facility contracts from mid-market brands purchasing shared-space services.
- Retailers:Department stores and specialty chains require seasonal surge capacity with guaranteed space commitments, paying premium rates for peak-season flexibility. Omnichannel operators in the Southeast cluster demand same-day fulfillment capabilities.
- E-commerce:Direct-to-consumer pure-plays drive fastest adoption of automated sortation and final-mile optimization, with piece-level tracking mandatory for returns processing. Growth concentrates among digitally native brands outsourcing fulfillment entirely.
- Manufacturers:Brand-owning producers seek inbound material coordination and finished goods distribution to wholesale accounts.
- Wholesalers:Independent distributors serving boutique accounts prioritize cross-dock velocity over long-term storage.
Retailers dominate contract value; e-commerce gains share fastest.
Delivery Mode:
Volume concentration favors third-party logistics as captive fleet economics deteriorate under driver scarcity and emissions compliance costs.
- Third-Party Logistics:Asset-light network orchestration allows mid-size apparel brands to access specialized capabilities without capital deployment, with 3PLs absorbing FMCSA compliance burden and fleet turnover costs. Demand expansion concentrates among brands with $50-200 million annual revenue abandoning captive fulfillment.
- Cross-Dock:Minimal-inventory flow-through models support fast-fashion replenishment with 24-48 hour turnaround from port to store.
- Direct Shipping:Point-to-point movements serve large-format retail distribution centers with predictable volume profiles.
- Drop Shipping:Supplier-direct fulfillment eliminates retailer inventory holding but requires real-time visibility integration.
Third-party logistics commands volume leadership; cross-dock shows steepest growth trajectory.
Technology:
Margin compression on basic barcode infrastructure pushes investment toward RFID and automation systems that justify premium pricing.
- RFID:Item-level tagging enables 99.9% inventory accuracy and automated sortation for SKU-intensive fashion assortments, with deployment concentrated in Southeast e-commerce fulfillment centers processing high-velocity direct-to-consumer orders. ISO 9001-certified operators leverage RFID data for process audit trails.
- Automated Sorting:Vision-guided robotic systems compress order cycle times from hours to minutes while reducing OSHA-reportable injuries in warehouse environments.
- Barcode Scanning:Legacy infrastructure persists in cost-sensitive wholesale operations with lower velocity requirements.
- Inventory Software:Cloud-based warehouse management systems provide real-time visibility but require middleware investment for legacy integration.
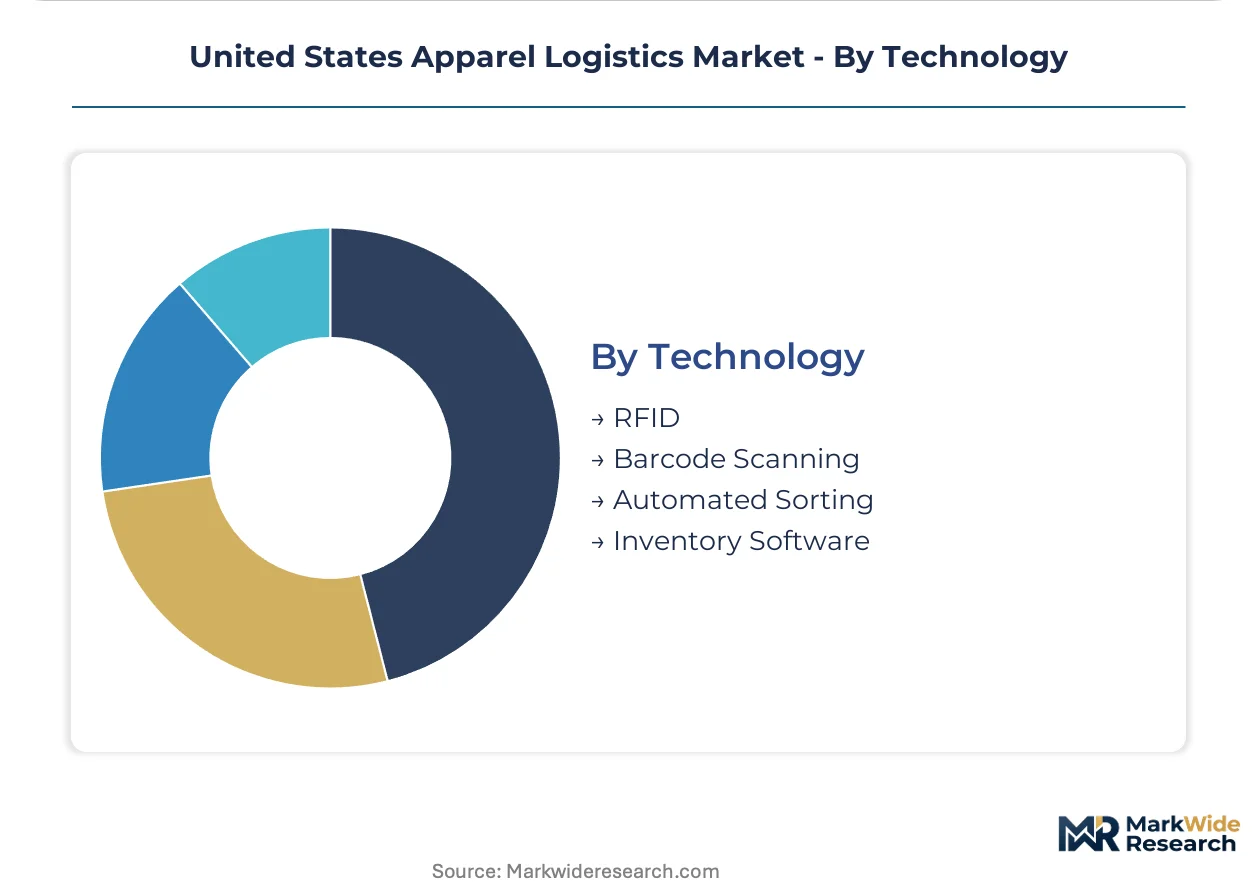
RFID leads adoption momentum; automated sorting climbs fastest among greenfield facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Savannah's Garden City Terminal expansion underwrites Georgia's dominance in apparel import processing, with rail connectivity to Atlanta distribution clusters reducing inland transit times for containerized garments.
Southeast (Georgia/South Carolina)
Savannah and Charleston port capacity additions draw e-commerce fulfillment investment from omnichannel retailers seeking reduced drayage distances. The Federal Motor Carrier Safety Administration tightens hours-of-service enforcement across I-95 and I-85 corridors, compressing driver availability for fast-fashion replenishment cycles. The Greenville-Spartanburg industrial market commands premium warehouse rents as brands cluster safety stock near Charleston's expanding container terminals.
California
Los Angeles-Long Beach port complexes handle trans-Pacific apparel volumes despite chassis shortages elevating drayage rates. The Environmental Protection Agency's Phase 3 greenhouse gas standards force fleet turnover toward electric tractors by 2027, with drayage carriers bearing disproportionate capital burden. The Inland Empire warehouse market saturates as operators seek lower-cost alternatives in Phoenix and Las Vegas corridors.
Texas
Houston and Laredo gateways capture nearshoring freight pivots as manufacturing relocates from Asia to Mexico. Gulf Coast port expansion opens intermodal hub opportunities for apparel flows rerouted through Texas rather than West Coast terminals. Dallas-Fort Worth distribution clusters absorb overflow demand from constrained California warehouse markets.
Northeast Corridor
New York-New Jersey port facilities serve European fashion imports with expedited customs processing for high-value seasonal collections. The Port Authority of New York and New Jersey invests in berth deepening to accommodate larger vessel calls. Pennsylvania's Lehigh Valley warehouse market supports last-mile fulfillment for Manhattan and Philadelphia retail concentrations.
Midwest (Illinois/Ohio)
Chicago's intermodal rail hub positions apparel distributors for Midwest market access without coastal port dependency. Columbus and Indianapolis fulfillment centers leverage central geography for two-day delivery coverage to coastal population centers. Ohio's warehouse development accelerates as brands diversify beyond Southeast concentration risk.
United States Apparel Logistics Market Competitive Landscape
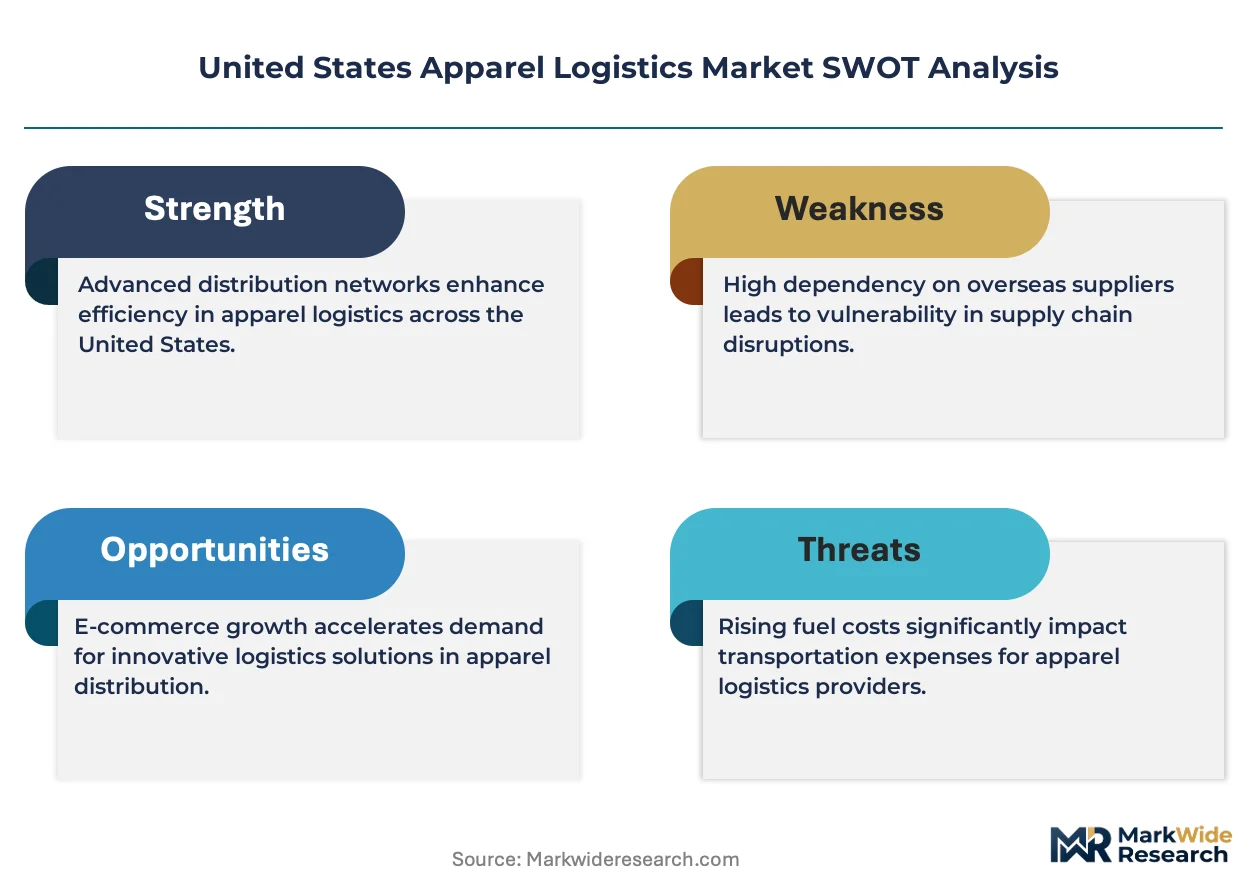
Listed logistics conglomerates compete with private specialists across asset ownership models, with scale advantages in integrated air-ground networks clashing against nimble final-mile operators. Market structure tilts toward consolidation among top-tier integrators while mid-market fragmentation persists in specialized warehousing. Three archetypes dominate: global integrators with captive air fleets, asset-light fourth-party logistics orchestrators, and regional final-mile specialists. Competitive moves center on automation partnerships for warehouse robotics deployment and strategic port-adjacent real estate acquisition.
Within the global integrator tier, Deutsche Post DHL Group and FedEx exemplify scale-driven positioning through domestic ground network density and seasonal surge capacity. XPO Logistics occupies a specialist position in high-velocity e-commerce final-mile solutions. These three entities anchor competitive dynamics as mid-market apparel brands abandon captive fulfillment for outsourced access to ISO-certified quality documentation and real-time inventory visibility platforms.
| Leading Market Players |
|---|
| CEVA Logistics |
| DB Schenker |
| Deutsche Post DHL Group |
| DSV |
| Hellmann Worldwide Logistics |
| Kuehne + Nagel |
| XPO Logistics |
| FedEx |
| UPS |
| Others |
Pricing and Supply Chain Analysis
Forty-five to sixty days of safety stock concentration near Savannah and Charleston ports directly shapes carrier pricing power, as FMCSA hours-of-service constraints tighten effective capacity on Southeast drayage corridors serving fast-fashion replenishment cycles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates contract negotiations, with ISO 9001 certification and real-time visibility integration serving as the primary price differentiation drivers. Cost compression in the standard tier is intensifying because mid-market apparel brands with $50-200 million revenue are consolidating procurement through cooperative buying groups. E-commerce pure-plays with direct-to-consumer volumes exceeding thirty percent of sales exhibit the lowest price sensitivity, while wholesale distributors serving fragmented boutique accounts face the highest.
Supply Chain Analysis
Safety stock positioning at forty-five to sixty days near Southeast port gateways reflects inventory strategy calibrated to trans-Pacific lead-time volatility. Manufacturing concentration draws from Bangladesh, Vietnam, and China, with cotton fiber and synthetic textile inputs resting on commodity price swings and tariff exposure. Single-source vulnerability runs through Los Angeles-Long Beach chassis shortages and Savannah container terminal congestion. Distribution runs through multi-node networks anchored by Atlanta and Greenville-Spartanburg fulfillment clusters with final-mile injection into parcel carrier hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
United States apparel logistics functions as a service-attach opportunity where value-added capabilities—garment-on-hanger processing, returns management, and vendor-managed inventory programs—expand faster than pure transportation and warehousing revenue.
For Market Incumbents: Shield market position by deepening automation partnerships for autonomous mobile robot deployment in Southeast fulfillment centers, countering the threat of asset-light fourth-party logistics orchestrators capturing mid-market brand outsourcing. Prioritize ISO 9001 certification investment to maintain vendor qualification access as buy-side consolidation elevates documentation requirements. For New Entrants and Emerging Players: Final-mile optimization for high-velocity e-commerce apparel represents the most penetrable service-layer gap, as incumbents under-serve digitally native brands requiring ninety-minute order cycle times. Target the $50-200 million revenue brand segment with specialized returns processing capabilities and RFID-enabled piece-level tracking as the primary go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because automation capital requirements and regulatory compliance burdens are forcing fragmentation among regional specialists without balance sheet capacity for fleet turnover. Acquire operators with installed collaborative robotics in the I-85 corridor and ISO-certified quality documentation. Watch FMCSA enforcement intensity and EPA Phase 3 compliance timelines as inflection indicators for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Automation Partnership | Deploys autonomous mobile robots in Atlanta fulfillment centers to compress order cycle times under OSHA safety standards. |
| Port-Adjacent Real Estate Acquisition | Secures warehouse capacity near Savannah Garden City Terminal expansion before industrial rent appreciation accelerates. |
| ISO 9001 Certification Investment | Documents process audit trails for vendor qualification by consolidating omnichannel retailers and cooperative buying groups. |
| Alternative Fuel Fleet Transition | Positions drayage operations for EPA Phase 3 compliance on California corridors serving Los Angeles-Long Beach imports. |
| Returns Processing Capability Buildout | Captures e-commerce apparel brands outsourcing reverse logistics with specialized garment inspection and reconditioning services. |
Research Methodology
A spread of perspectives from supply chain directors at omnichannel retailers, fleet operations managers at asset-based carriers, warehouse automation engineers, and procurement leads at mid-market apparel brands converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through FMCSA regulatory filings, EPA emissions standards documentation, port authority container volume reports, and industrial real estate transaction databases. Bottom-up service-type demand modeling and top-down macroeconomic triangulation anchored value estimates.
Segmentation dimensions modeled include service type, client type, delivery mode, and technology deployment across the analysis window. CAGRs derived from historical volume trajectories, regulatory implementation timelines, and automation adoption curves. Forecast inputs incorporated FMCSA hours-of-service enforcement intensity, Southeast port capacity expansion schedules, and nearshoring freight pivot velocity from Asia to Mexico and Central America.
Forecasts assume regulatory continuity in FMCSA hours-of-service rules and EPA Phase 3 greenhouse gas standards; material policy shifts would require re-modeling driver availability and fleet turnover economics. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
United States Chemical Logistics Market
Logistics and Shipping
Express Delivery Market
Logistics and Shipping
Brazil Freight and Logistics Market
Logistics and Shipping
Japan E-Commerce Logistics Market
Logistics and Shipping
Poland Cold Chain Logistics Market
Logistics and Shipping
Government and Education Logistics Market
Logistics and Shipping
Air Cargo Capacity and Allotment Marketplace Platforms Market
Logistics and Shipping
US Retail Logistics Market
Logistics and Shipping
Asean Freight and Logistics Market
Logistics and Shipping
United Kingdom Contract Logistics Market
Logistics and Shipping
New York Freight and Logistics Market
Logistics and Shipping
China International Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
North America Freight and Logistics Market
Logistics and Shipping
Saudi Arabia Integrated Cold Chain Logistics Market
Logistics and Shipping
Thailand Courier Express Parcel (CEP) Market
Logistics and Shipping
Sweden Cold Chain Logistics Market