
 United Arab Emirates (UAE) Third-Party Logistics (3PL) Market | 2026-2036
United Arab Emirates (UAE) Third-Party Logistics (3PL) Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates (UAE) Third-Party Logistics (3PL) Market Analytics
Modular service bundling is decoupling as buyers unbundle transportation from warehousing and instead procure standalone last-mile delivery or IoT-enabled inventory management. CEVA Logistics leverages its European network architecture to anchor cross-border freight forwarding into the UAE. Aramex specializes in last-mile density across Gulf Cooperation Council corridors, while DP World dominates port-centric logistics through its control of Jebel Ali terminal operations and adjacent free-zone real estate.
Third-party logistics in the UAE encompasses outsourced supply-chain execution where providers manage transportation, warehousing, and freight forwarding under service-level agreements typically measured by inventory accuracy, order-cycle time, and customs-clearance velocity. The primary commercial purpose is to replace fixed asset ownership with variable-cost distribution networks that flex with import-export volume volatility. Transportation and freight forwarding command the largest revenue pools given the UAE's transshipment-hub function between Asia, Europe, and Africa. Warehousing is maturing as developers add automated storage and retrieval systems to capture premium rates from pharmaceutical and electronics clients.
The UAE's General Civil Aviation Authority and the Federal Transport Authority jointly regulate cross-border freight licensing, while Dubai Customs enforces bonded-warehouse standards that determine which 3PL operators qualify for duty-deferment privileges. MOHAP pharmaceutical storage guidelines and the UAE's emerging digital trade-documentation framework are tightening facility-certification requirements and pushing providers toward blockchain-integrated track-and-trace systems. Stakeholders must weigh whether to build in-house customs-brokerage capabilities or partner with established free-zone operators as regulatory fragmentation between emirates intensifies.
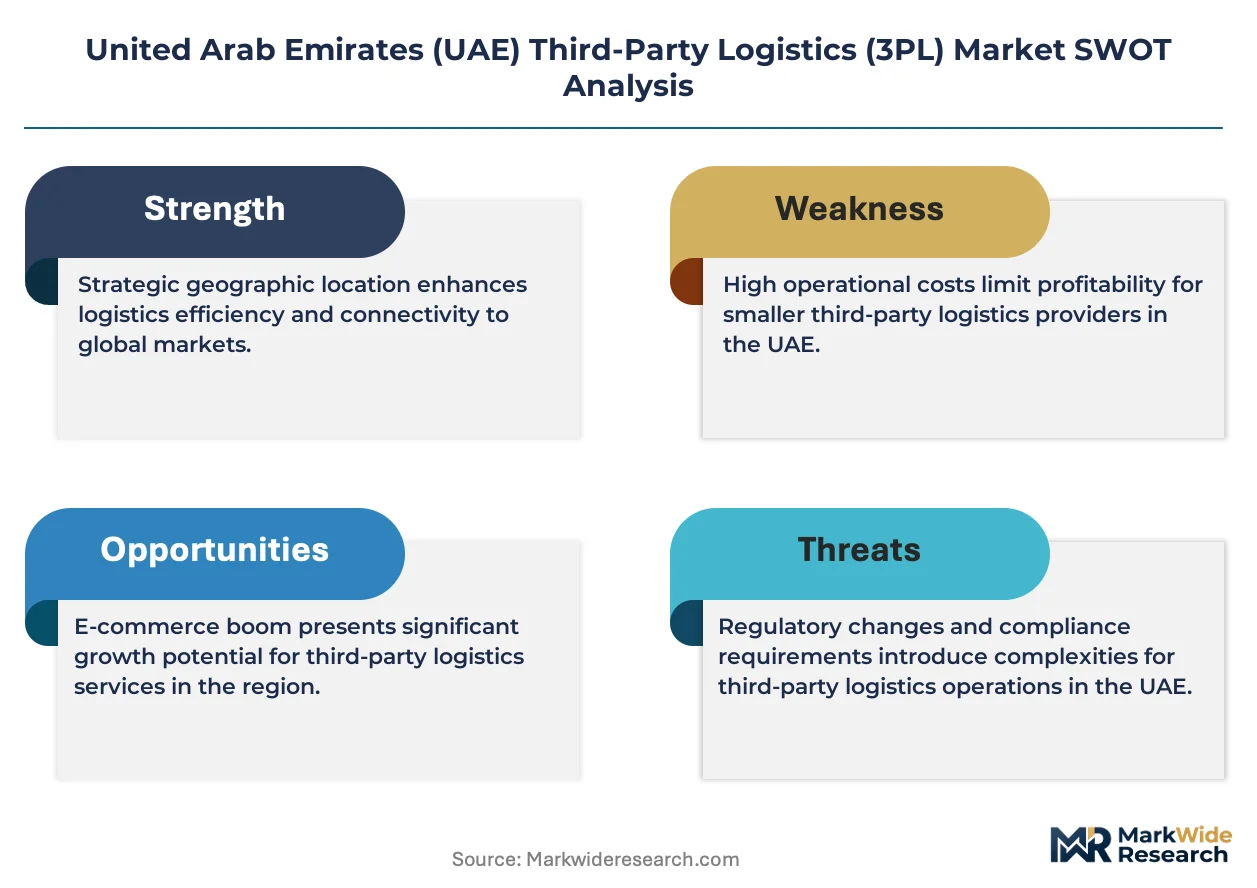
Market Dynamics
Freight digitization mandates from the UAE's Federal Transport Authority are forcing 3PL operators to reconfigure legacy customs-brokerage workflows around real-time data exchange, compressing the competitive window for paper-based clearance specialists.
Growth Catalysts
- E-commerce fulfillment surge:Dubai-based retailers are outsourcing inventory management to bonded warehouses in Jebel Ali Free Zone, creating pull for temperature-controlled storage and same-day delivery infrastructure.
- MOHAP pharmaceutical guidelines:Cold-chain certification requirements for vaccine distribution are expanding demand for IoT-enabled warehouse monitoring systems across Abu Dhabi and Dubai.
- Port automation investments:Khalifa Industrial Zone's automated container handling is reducing dwell times and attracting transshipment volume from Asia-Europe trade lanes.
Market Restraints
- Labor cost inflation:Warehouse operator wages in Dubai have risen sharply, squeezing margins for providers dependent on manual picking and packing operations.
- Free-zone concentration risk:Over 60 percent of bonded warehousing capacity sits within Jebel Ali and Khalifa zones, creating vulnerability to single-point disruptions.
- Customs system fragmentation:Divergent digital platforms between Dubai Customs and Abu Dhabi Customs increase compliance overhead for multi-emirate operators.
Strategic Opportunities
- Sharjah underpenetration:Industrial zones in Sharjah and Ras Al Khaimah offer lower land costs for 3PLs seeking to diversify beyond saturated Dubai facilities.
- Blockchain trade documentation:The UAE's emerging digital trade framework creates first-mover advantage for providers integrating distributed-ledger track-and-trace systems.
- Cross-border GCC corridors:Saudi Arabia's logistics privatization opens adjacent markets for UAE-based operators with established Saudi customs relationships.
Industry Challenges
- Scarce customs-brokerage talent:Licensed clearance specialists with dual Dubai-Abu Dhabi certification command premium compensation, constraining expansion timelines.
- ASRS capex intensity:Automated storage and retrieval systems for pharmaceutical clients require substantial upfront investment with 5-7 year payback horizons.
- Legacy WMS integration:Older warehouse management systems lack API connectivity to new government freight platforms, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates (UAE) Third-Party Logistics (3PL) Market |
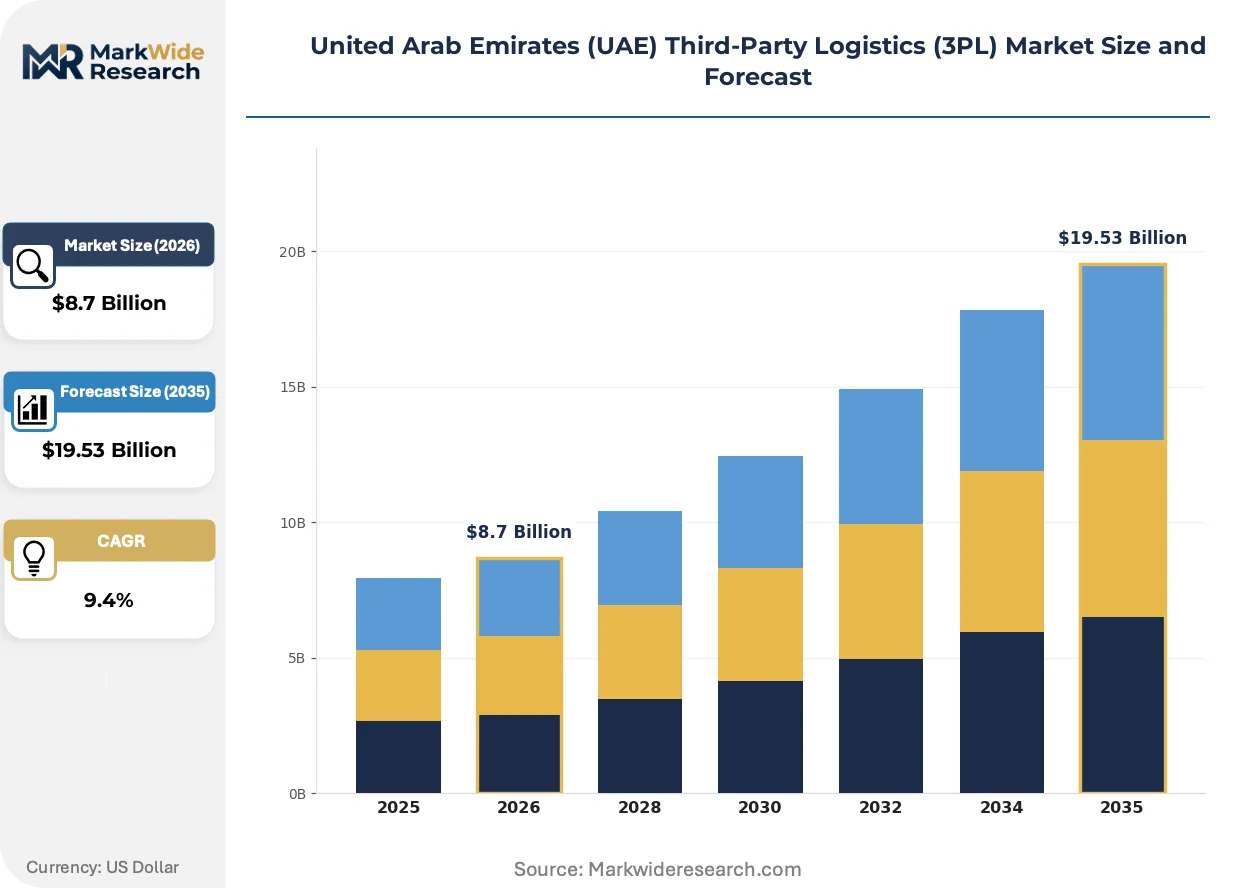
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Last Mile Delivery End User: E-Commerce, Retail, Automotive, Healthcare Technology: IoT Solutions, Warehouse Management Systems, Robotics, Blockchain Distribution Channel: Direct Sales, Online Platforms, Partnerships, Distributors |
| Companies Covered | CEVA Logistics, Kuehne + Nagel, Aramex, Agility Logistics, DP World, DHL Global Forwarding, FedEx Logistics, The Kanoo Group, GAC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates (UAE) Third-Party Logistics (3PL) Market Evolving Landscape
Digital freight platforms and warehouse robotics are compressing the traditional 3PL value chain, replacing asset-heavy models with variable-cost networks that scale with import-export volatility.
Autonomous mobile robots for inventory transport are consolidating warehouse labor models in Dubai's pharmaceutical and electronics facilities. CEVA Logistics and DP World subsidiaries have deployed AMR fleets across Jebel Ali Free Zone operations, reducing picker travel time by half. This consolidation is compressing the wage-cost advantage of manual operations and raising the entry threshold for new warehouse competitors.
MOHAP's cold-chain certification mandates are tightening facility standards for vaccine and biologics storage. Operators must now maintain continuous temperature logging with 15-minute interval reporting to retain pharmaceutical distribution licenses. The Dubai Healthcare City cluster is most affected, with 3PLs retrofitting existing warehouses with redundant cooling and backup power systems to maintain compliance.
Retailers are unbundling transportation from warehousing contracts, procuring standalone last-mile delivery or inventory-management services through separate agreements. This fragmentation is displacing the traditional bundled 3PL model in Abu Dhabi's e-commerce sector. Fashion and electronics verticals show the strongest unbundling momentum, with merchants preferring specialized last-mile density providers over integrated operators.
United Arab Emirates (UAE) Third-Party Logistics (3PL) Market Segmentation
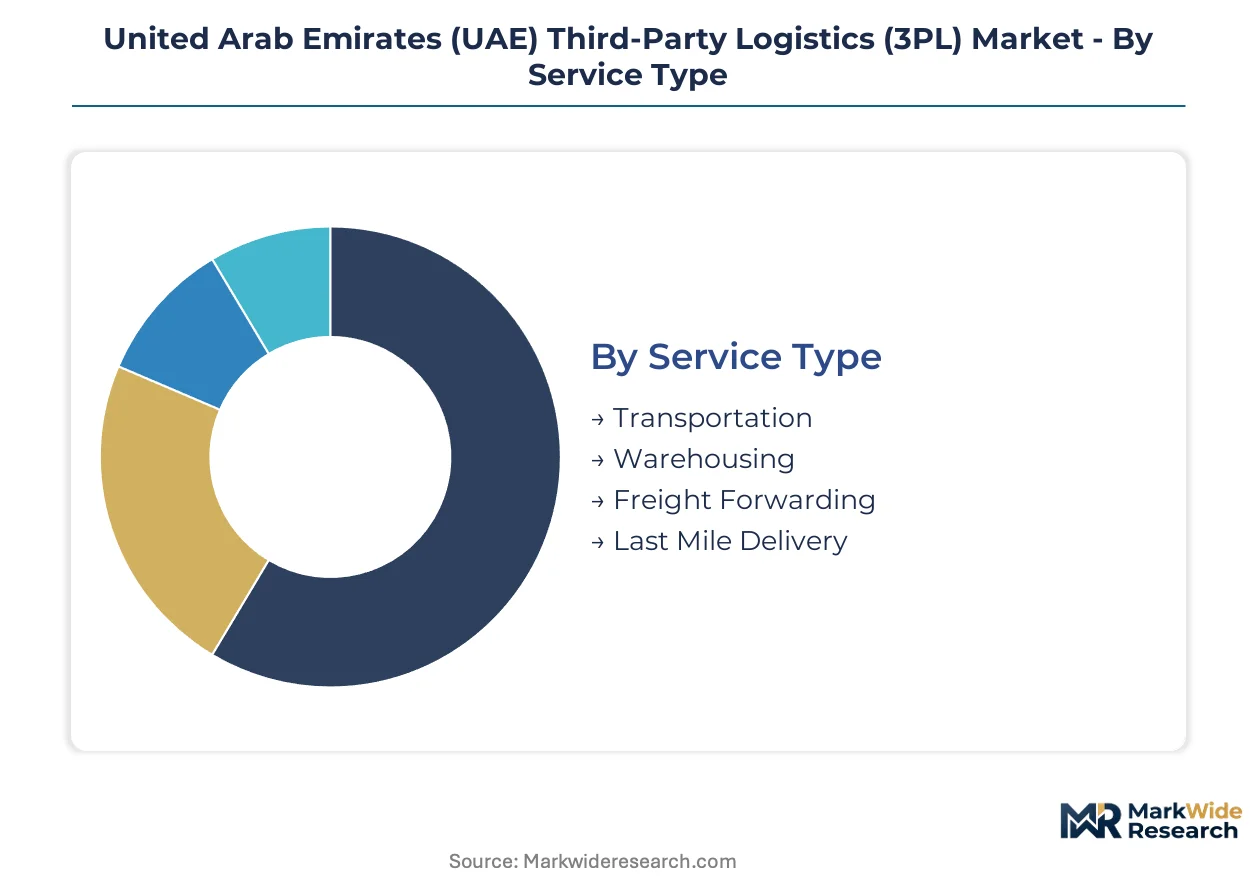
Service unbundling across the UAE logistics sector demands granular segmentation to capture where value migrates. Buyers now procure transportation, warehousing, and last-mile capabilities through separate contracts rather than bundled agreements.
Service Type:
Transportation and freight forwarding anchor revenue volume, while warehousing commands premium pricing through automation.
- Transportation:Road and air cargo movements connecting Jebel Ali Port to GCC corridors dominate tonnage. Fleet operators in Dubai face margin compression from fuel cost volatility and driver wage inflation.
- Warehousing:Bonded storage facilities in Khalifa Industrial Zone attract pharmaceutical and electronics clients seeking MOHAP-certified cold-chain infrastructure. Automated storage and retrieval systems differentiate premium providers from manual operations.
- Freight Forwarding:Customs-brokerage integration determines competitiveness as Dubai Customs mandates real-time data exchange.
- Last Mile Delivery:Same-day fulfillment networks in Abu Dhabi and Dubai concentrate demand from fashion and electronics retailers outsourcing final-leg execution.
Today's leader: Transportation. Tomorrow's challenger: Warehousing.
End User:
E-commerce verticals drive volume expansion, while healthcare generates margin premiums through regulatory certification.
- E-Commerce:Dubai-based retailers outsource inventory management to bonded warehouses, pulling temperature-controlled storage and rapid fulfillment infrastructure. Unbundling trends separate warehousing from last-mile contracts.
- Healthcare:MOHAP pharmaceutical guidelines mandate continuous temperature logging with 15-minute interval reporting. Vaccine distribution requirements expand demand for redundant cooling and backup power systems.
- Retail:Traditional merchants consolidate supplier networks through shared warehousing in Jebel Ali Free Zone.
- Automotive:Spare parts distributors require specialized racking and sequencing capabilities for just-in-time delivery to service centers.
E-commerce captures current volume growth. Healthcare offers the steepest expansion trajectory through regulatory-driven service premiums.
Technology:
Deployment maturity splits between proven warehouse systems and emerging freight digitization platforms.
- Warehouse Management Systems:Legacy platforms lack API connectivity to government freight platforms, forcing expensive middleware development for compliance.
- IoT Solutions:Sensor networks enable 15-minute temperature reporting for pharmaceutical clients and real-time inventory visibility across multi-emirate operations.
- Robotics:Autonomous mobile robots consolidate labor models in Dubai's pharmaceutical facilities, compressing wage-cost advantages of manual operations.
- Blockchain:Distributed-ledger track-and-trace systems align with the UAE's emerging digital trade-documentation framework, creating first-mover positioning.
WMS dominates current deployment. Blockchain represents the capability gap that separates compliant operators from laggards.
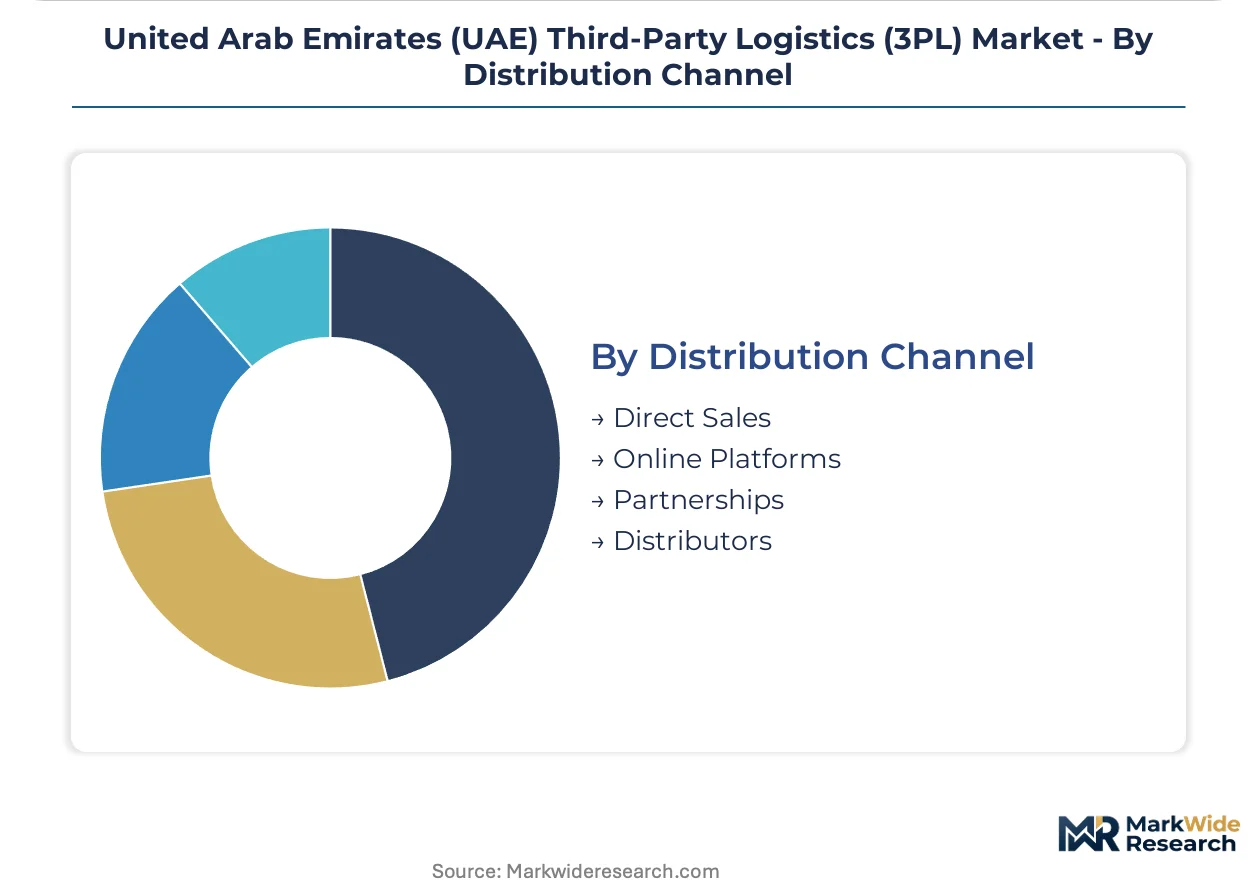
Distribution Channel:
Direct relationships anchor enterprise contracts, while platform intermediation grows among mid-market shippers.
- Direct Sales:Enterprise manufacturers and retailers negotiate long-term service-level agreements with integrated 3PL operators, specifying inventory accuracy and customs-clearance velocity metrics.
- Partnerships:Free-zone operators bundle logistics with real estate leases, capturing multinational distributors seeking duty-deferment privileges.
- Online Platforms:Digital freight marketplaces aggregate spot demand from small and mid-sized importers, compressing margins through price transparency.
- Distributors:Local agents resell international 3PL capabilities to UAE-based clients lacking direct provider relationships.
Direct sales secure margin. Platform intermediation gains share fastest among price-sensitive mid-market segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UAE's logistics infrastructure originated from Jebel Ali Port's 1979 inauguration, which established Dubai as a transshipment hub between Asia and Europe. This maritime foundation expanded through free-zone development and bonded warehousing across multiple emirates.
Dubai
E-commerce fulfillment demand from fashion and electronics retailers concentrates in Jebel Ali Free Zone, where bonded warehousing enables duty-deferred inventory storage. Dubai Customs mandates real-time data exchange for customs-brokerage operators, compressing clearance timelines. The Jebel Ali Port cluster anchors automated container handling and adjacent logistics real estate.
Abu Dhabi
Pharmaceutical distribution requirements under MOHAP guidelines drive cold-chain infrastructure investment for vaccine and biologics storage. Khalifa Industrial Zone's automated port operations reduce container dwell times for Asia-Europe transshipment. The zone's integrated customs-clearance facilities attract multinational distributors seeking Gulf Cooperation Council market access.
Sharjah
Industrial land costs run substantially below Dubai levels, drawing 3PL operators seeking warehouse diversification outside saturated emirates. The emirate's logistics parks target mid-market manufacturers with standard-grade warehousing rather than premium automation. Sharjah's port facilities handle regional trade flows to Iran and East Africa.
Northern Emirates
Ras Al Khaimah's developing industrial zones offer greenfield development opportunities for temperature-controlled storage facilities. The emirate's cement and ceramics export base generates bulk freight forwarding demand. Ajman and Fujairah concentrate last-mile delivery networks serving northern population corridors.
United Arab Emirates (UAE) Third-Party Logistics (3PL) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across automation intensity and regulatory certification depth. The vendor base splits between integrated port-free-zone operators and specialized last-mile or customs-brokerage providers. Three archetypes dominate: European network anchors with cross-border freight forwarding capabilities, regional last-mile density specialists, and port-centric real estate controllers. Competitive moves concentrate on automation capex deployment and customs-brokerage talent acquisition.
Within the European network tier, CEVA Logistics and Kuehne + Nagel occupy positions leveraging continental infrastructure for Middle East freight forwarding. Aramex represents the regional specialist archetype with Gulf Cooperation Council corridor density. DP World anchors the port-centric category through Jebel Ali terminal control and adjacent free-zone logistics real estate. These three exemplify divergent strategic positions without direct overlap in core service configuration.
| Leading Market Players |
|---|
| CEVA Logistics |
| Kuehne + Nagel |
| Aramex |
| Agility Logistics |
| DP World |
| DHL Global Forwarding |
| FedEx Logistics |
| The Kanoo Group |
| GAC |
| Others |
Value Network & Pricing Analysis
E-commerce retailers' unbundling of warehousing from last-mile contracts is forcing 3PL operators to restructure service offerings and compress margins on standalone transportation bids. This procurement shift concentrates pricing power with buyers who can pit specialized providers against integrated operators.
Pricing Analysis
Three-tier pricing structure across premium automation, standard bonded warehousing, and economy manual operations dominates the UAE 3PL landscape. Price differentiation centers on MOHAP cold-chain certification grade and ASRS deployment intensity, with pharmaceutical clients paying substantial premiums for redundant cooling systems. Cost compression in economy warehousing is intensifying because Sharjah-based competitors undercut Dubai rates with lower land costs. Small and mid-sized importers using digital freight platforms exhibit highest price sensitivity, while multinational distributors with free-zone real estate bundles show lowest.
Supply Chain Analysis
Regional distribution centers concentrate in Jebel Ali Free Zone and Khalifa Industrial Zone, forming a hub-and-spoke pattern radiating toward GCC corridors. Supply draws from German automation equipment providers, Chinese warehouse robotics manufacturers, and Indian customs-brokerage talent pools. Single-source vulnerability sits with licensed clearance specialists holding dual Dubai-Abu Dhabi certification. Distribution runs through bonded warehouse networks with integrated customs facilities before final-mile handoff to specialized delivery operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE 3PL market functions as a geographic-arbitrage play where operators exploit land-cost differentials between Dubai's saturated free zones and Sharjah's underdeveloped industrial parks to capture margin expansion.
For Market Incumbents: Anticipate margin erosion from digital freight platforms aggregating spot demand by consolidating customs-brokerage talent pools through selective acquisition of licensed specialists. Vertical integration into Sharjah warehouse development secures lower-cost capacity buffers against Dubai land inflation. For New Entrants and Emerging Players: Capture white-space opportunity in Ras Al Khaimah temperature-controlled storage facilities where pharmaceutical demand outpaces certified supply. The most penetrable segment sits with mid-market manufacturers lacking direct relationships with established free-zone operators; a Sharjah-based facility with MOHAP certification and competitive land rates provides the strongest go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale operators holding dual-emirate customs licenses and underutilized warehouse automation capacity. Long-term viability hinges on regulatory compliance depth rather than asset scale alone. The signal to watch is MOHAP's expansion of mandatory temperature-logging intervals beyond current 15-minute standards.| Strategic Initiative | Industry Significance |
|---|---|
| ASRS Deployment | Automated storage systems in Jebel Ali reduce picker travel time by half for pharmaceutical clients. |
| Customs-Brokerage Acquisition | Licensed specialists with dual Dubai-Abu Dhabi certification command premium compensation and constrain expansion timelines. |
| Sharjah Warehouse Development | Lower land costs outside saturated Dubai facilities enable margin expansion for temperature-controlled operations. |
| Blockchain Track-and-Trace Integration | Distributed-ledger systems align with the UAE's emerging digital trade-documentation framework. |
| GCC Corridor Expansion | Saudi Arabia's logistics privatization opens adjacent markets for operators with established customs relationships. |
Research Methodology
Multiple input streams — primary interviews with logistics operations directors, customs-brokerage license holders, and free-zone facility managers; secondary validation through Federal Transport Authority filings, Dubai Customs trade documentation, and MOHAP facility certification records; plus bottom-up and top-down triangulation — were reconciled to construct market estimates.
Data-stream reconciliation across service type, end-user vertical, technology deployment, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from trend extrapolation of bonded warehouse capacity expansion, e-commerce fulfillment volume growth, and pharmaceutical cold-chain infrastructure investment.
Underlying measurement precision varies by segment; transportation and freight forwarding carry tighter precision than emerging blockchain-integrated track-and-trace services. Forecasts reflect assumptions around regulatory implementation timelines and free-zone development schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
China less than Truckload Road Freight Transport Market
Logistics and Shipping
United States Chartered Air Freight Transport Market
Logistics and Shipping
North America Last Mile Delivery Market
Logistics and Shipping
Tank Container Shipping Market
Logistics and Shipping
Control Towers Market
Logistics and Shipping
Singapore Freight and Logistics Market
Logistics and Shipping
Poland Cold Chain Logistics Market
Logistics and Shipping
North America Sea Freight Forwarding Market
Logistics and Shipping
Latin America Freight Forwarding Market
Logistics and Shipping
Vietnam Express Delivery Services Market
Logistics and Shipping
Last-Mile Delivery Market
Logistics and Shipping
Logistics Data Quality and Normalization Services Market
Logistics and Shipping
GCC Warehousing and Distribution Logistics Market
Logistics and Shipping
Europe Refrigerated Container Shipping Market
Logistics and Shipping
Asia-Pacific Shipping Agency Services Market
Logistics and Shipping
Hong Kong Freight and Logistics Market