
 Europe Sea Freight Forwarding Market | 2026-2036
Europe Sea Freight Forwarding Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sea Freight Forwarding Market Insights
Real-time container tracking and predictive ETA algorithms is rewriting operational expectations for European shippers. Kuehne + Nagel International AG leverages proprietary visibility platforms to sustain control over high-value automotive cargo flows. DSV anchors its competitive stance through integrated air-sea booking systems that dominate Scandinavian trade lanes. DB Schenker competes aggressively on rail-sea intermodal pricing across German hinterland corridors.
Sea freight forwarding encompasses the coordination of ocean cargo movement through carrier negotiation, documentation management, customs clearance, and multimodal handoff, typically operating with container specifications ranging from twenty-foot equivalent units to forty-foot high-cube refrigerated boxes for temperature-sensitive goods. The primary commercial purpose centers on consolidating fragmented shipper demand into economically viable vessel space allocations while managing port-to-door liability transitions. Full Container Load services occupy the mature revenue core as Less than Container Load segments attract margin-focused investment from digital freight platforms. Breakbulk forwarding sustains niche profitability across oversized industrial machinery movements through the Baltic and Mediterranean. Roll-on/Roll-off capacity is concentrating around automotive sector contracts linking Bremerhaven with southern European assembly plants.
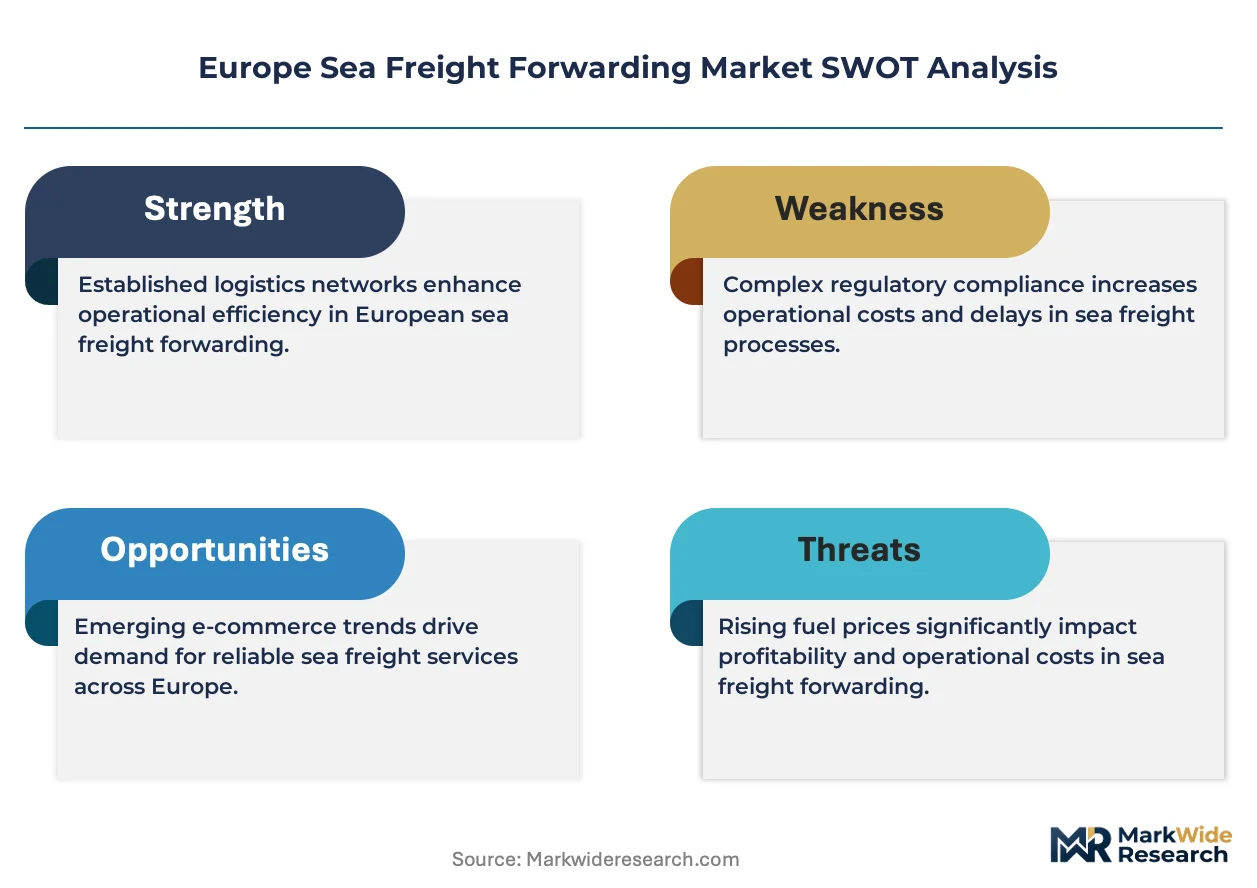
The EU Green Deal and F-Gas Regulation are reshaping vessel fuel compliance timelines across European ports, while ECHA oversight of hazardous cargo documentation tightens market access for non-compliant operators. CE marking requirements for handling equipment and the CSRD disclosure mandates are forcing forwarders to restructure emissions reporting across subcontractor networks. Stakeholders must monitor how the EU AI Act classification of autonomous routing software affects liability frameworks before committing to platform investments.
Market Dynamics
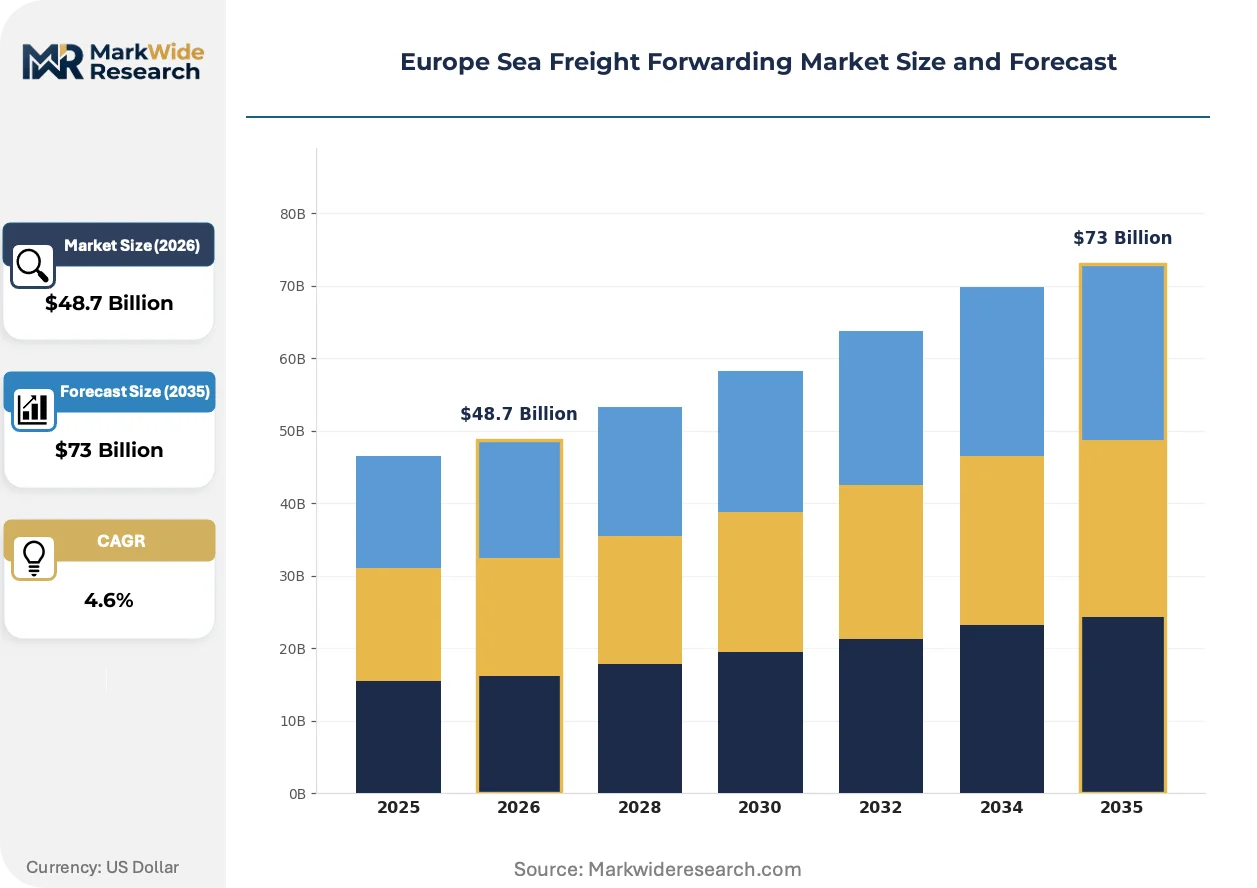
EU Green Deal emission mandates are compressing vessel fuel transition timelines while Rotterdam-Hamburg-Antwerp corridor investments concentrate intermodal capacity, forcing forwarders to restructure subcontractor networks around electrified port infrastructure and carbon disclosure requirements.
Growth Catalysts
- EU Green Deal fuel compliance:Mandates for alternative marine fuels are accelerating vessel retrofits across North Sea ports, creating demand for specialized reefer handling and emission-verified carrier contracts.
- E-commerce fulfillment networks:German and Dutch online retailers are expanding ocean freight volumes for transatlantic inventory positioning, requiring faster port-to-warehouse handoffs and predictive ETA capabilities.
- Intermodal rail-sea integration:German hinterland corridors are absorbing container overflow from congested terminals through synchronized rail schedules and shared track access agreements.
Market Restraints
- Baltic carrier concentration:Breakbulk and Ro-Ro capacity remains controlled by a narrow set of Scandinavian operators, limiting price negotiation leverage for oversized machinery shippers.
- ECHA hazardous documentation:Tightened oversight of chemical cargo manifests is extending clearance timelines at Rotterdam and Hamburg, penalizing operators with incomplete subcontractor audit trails.
- Green methanol supply scarcity:Alternative fuel availability at European bunkering hubs trails vessel retrofit schedules, forcing dual-fuel ships to rely on conventional marine diesel for extended routes.
Strategic Opportunities
- Polish port expansion:Gdansk and Gdynia container terminals are adding deep-water berths and rail connections, opening Baltic access for Central European manufacturers bypassing North Sea congestion.
- CSRD emissions disclosure:Mandatory Scope 3 reporting is creating paid advisory services around carbon accounting software and verified carrier emission databases for mid-sized forwarders.
- AI Act autonomous routing:Classification of self-optimizing cargo allocation algorithms is clarifying liability frameworks, enabling platform investments in predictive disruption management.
Industry Challenges
- Maritime data science talent:Shortages of professionals combining port operations expertise with machine learning implementation are delaying predictive analytics deployments at mid-tier forwarders.
- Refrigerated container fleet renewal:F-Gas Regulation phase-down schedules are forcing accelerated replacement of cooling units, straining capex budgets for temperature-controlled cargo specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sea Freight Forwarding Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $73 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Container Load, Less than Container Load, Breakbulk, Roll-on/Roll-off End User: Manufacturers, Retailers, E-commerce, Logistics Providers Transport Mode: Direct Shipping, Transshipment, Intermodal, Inland Transport Sector: Consumer Goods, Industrial Products, Electronics, Automotive |
| Companies Covered | Kuehne + Nagel International AG, DHL Global Forwarding, DSV, DB Schenker, Bollore Logistics, CEVA Logistics, Geodis, Hellmann Worldwide Logistics, Fr. Meyer's Sohn, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sea Freight Forwarding Market Trends and Innovations
Digital freight platforms are compressing carrier-shipper matching cycles while EU regulatory frameworks harden emission accountability requirements, reshaping how forwarders construct subcontractor networks and price risk.
Blockchain-enabled bill-of-lading systems are digitizing document transfer between Rotterdam terminals and German inland depots, cutting release cycle times for automotive parts importers from days to hours. Large German manufacturers are mandating these platforms for supplier compliance. The technology is digitizing custody handoff verification and reducing fraud exposure across multimodal chains.
F-Gas Regulation refrigerant phase-down mandates are forcing reefer container fleet replacements across Mediterranean and North Sea operators, accelerating capital deployment into electric cooling units. Spanish and Italian fruit exporters face compressed equipment availability during peak harvest windows. Temperature-sensitive pharmaceutical flows through Swissmedic-regulated corridors are prioritizing compliant cold chain certification.
Shippers are unbundling port-to-door liability coverage from carrier contracts, purchasing standalone cargo insurance through digital broker platforms that price risk by individual voyage conditions. German automotive suppliers lead this shift, replacing annual all-risk policies with per-shipment coverage. The practice is most visible along Bremerhaven-southern Europe assembly plant routes where disruption frequency justifies dynamic pricing.
Europe Sea Freight Forwarding Market Segmentation
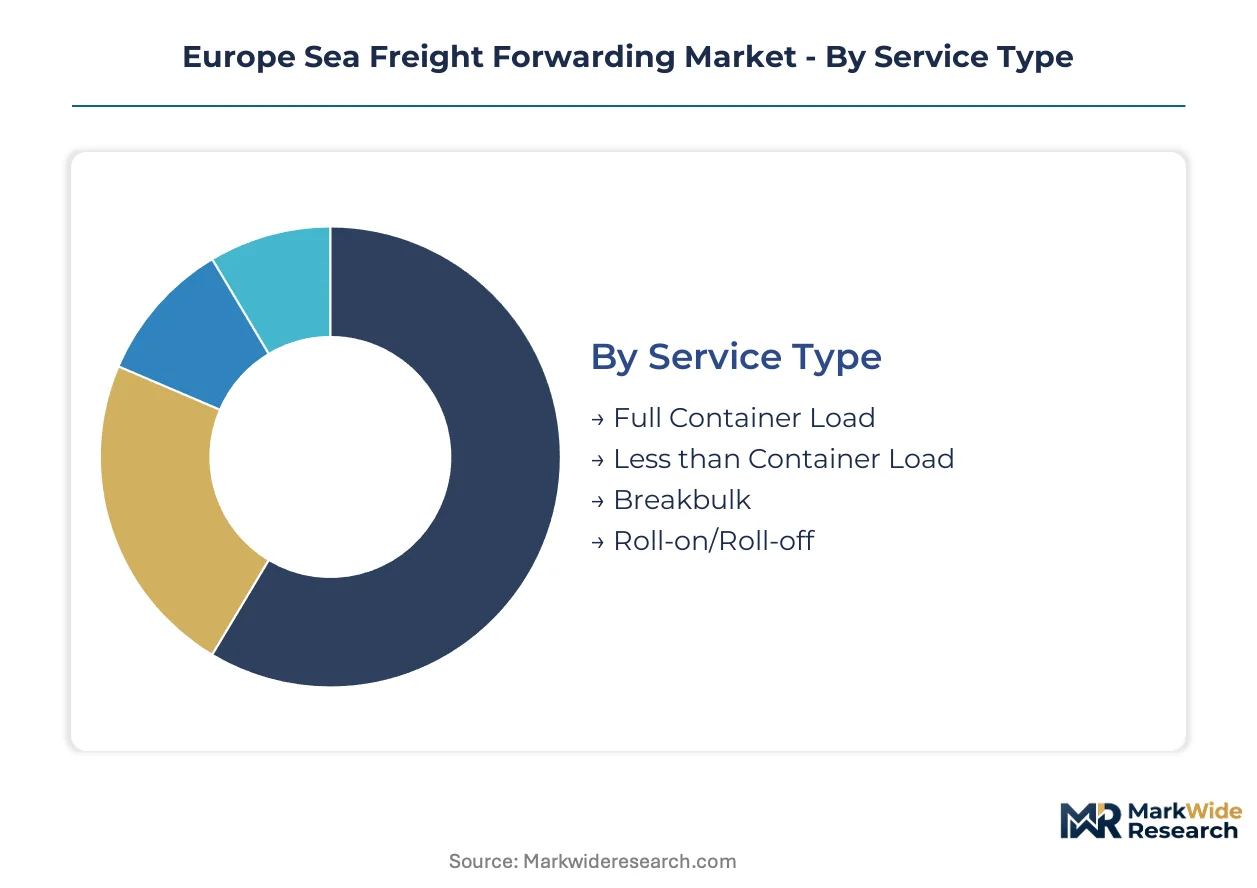
Service differentiation determines margin capture and client retention across European sea freight forwarding. Forwarders structure pricing and operational investments around cargo consolidation economics, equipment specialization, and port-to-door liability complexity.
Service Type:
After-sales service intensity varies sharply across service categories, with temperature-controlled and oversized cargo demanding dedicated account management and 24/7 exception handling.
- Full Container Load:Dedicated container allocation for single-shipper volumes dominates automotive and industrial flows through Rotterdam and Hamburg. German manufacturers anchor demand with contracted annual slot commitments and penalty clauses for vessel delays.
- Less than Container Load:Consolidation of fragmented shipper demand into shared container space attracts digital platform investment and dynamic pricing algorithms. Dutch and German e-commerce retailers drive fastest adoption for transatlantic inventory positioning with unpredictable volume spikes.
- Breakbulk:Non-containerized cargo handling for oversized machinery concentrates around Baltic project logistics with specialized heavy-lift equipment.
- Roll-on/Roll-off:Wheeled cargo services link Bremerhaven with southern European assembly plants under long-term automotive contracts.
By volume, Full Container Load leads. By growth pace, Less than Container Load is ahead.
End User:
Cost tier segmentation separates enterprise clients with integrated supply chain control from price-sensitive mid-market shippers purchasing transactional forwarding.
- Manufacturers:Industrial producers with captive logistics functions demand carrier direct contracts and emission-verified reporting for EU Green Deal compliance. German automotive and machinery exporters dominate contract value with multi-year agreements.
- Retailers:Omnichannel distributors require predictive ETA visibility and rapid customs clearance for seasonal inventory surges. Dutch fashion and home goods importers prioritize speed-to-shelf over pure freight cost minimization.
- E-commerce:Online merchants with fragmented supplier bases purchase consolidated forwarding through digital platforms with instant quoting.
- Logistics Providers:Third-party operators subcontract ocean capacity for client-forwarded cargo with white-label documentation.
Manufacturers generate the highest contract values. E-commerce is climbing the fastest.
Transport Mode:
Application-driven mode selection balances speed, cost, and carbon disclosure requirements across European corridors.
- Direct Shipping:Point-to-point vessel routing without intermediate port calls serves time-sensitive automotive parts from Bremerhaven to Mediterranean assembly plants.
- Transshipment:Hub-and-spoke container relay through Rotterdam and Antwerp consolidates feeder traffic from smaller Baltic and Mediterranean ports.
- Intermodal:Synchronized rail-sea coordination absorbs German hinterland overflow from congested North Sea terminals with scheduled block train departures.
- Inland Transport:Barge and truck feeder connections complete port-to-door delivery with liability handoff at container yard gates.
Transshipment handles the greatest container volumes. Intermodal is expanding most quickly.
Sector:
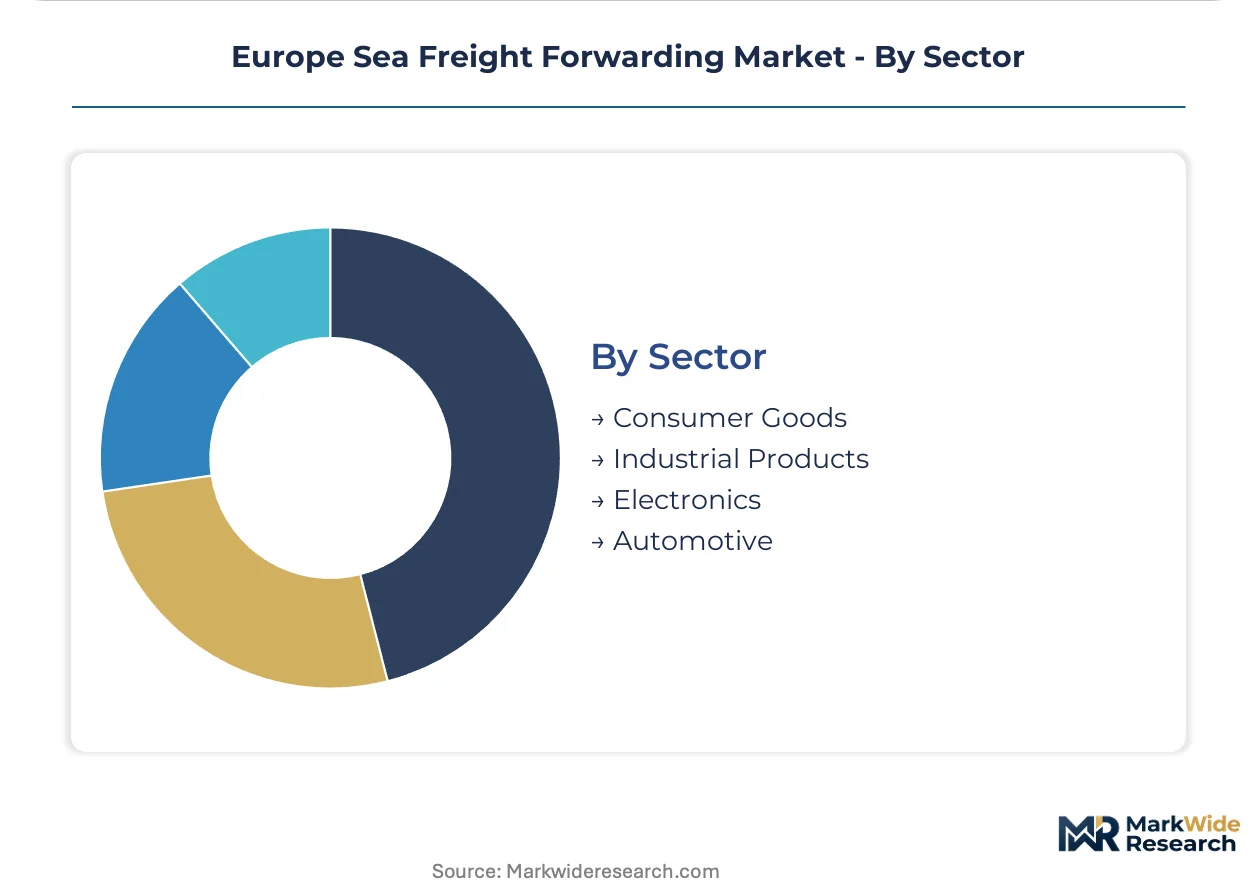
Margin profiles diverge by cargo sensitivity, with temperature-controlled pharmaceuticals and just-in-time automotive commanding premium pricing over commoditized consumer goods.
- Consumer Goods:High-volume, low-margin shipments of packaged products flow through standardized dry containers with minimal value-added services.
- Industrial Products:Project cargo and machinery movements require specialized handling equipment and charter party negotiations for oversized loads.
- Electronics:High-value, theft-sensitive devices demand sealed container protocols and expedited customs clearance through AEO-certified forwarders.
- Automotive:Finished vehicles and components move under strict sequencing requirements with real-time tracking and damage liability protocols.
Consumer Goods moves the most container volume. Electronics is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam-Hamburg-Antwerp corridor volumes dominate European ocean freight flows, with German automotive exports feeding Mediterranean assembly plants and Dutch distribution hubs handling transatlantic e-commerce inventory positioning.
Germany
Bremerhaven automotive terminals and Hamburg container traffic anchor North Sea throughput. KBA enforces emission-verified carrier certification under EU Green Deal timelines. Bavarian machinery exporters are contracting dedicated reefer capacity for temperature-sensitive components to Asian markets.
Netherlands
Rotterdam transshipment consolidation serves fragmented Benelux shipper demand through predictive ETA platforms. CSRD disclosure mandates force mid-sized forwarders to restructure subcontractor emissions reporting. Eindhoven-region electronics manufacturers mandate blockchain-enabled documentation for supplier compliance.
Belgium
Antwerp chemical cargo flows concentrate breakbulk and hazardous documentation expertise. ECHA oversight of chemical manifests extends clearance timelines, penalizing operators with incomplete audit trails. Flemish port authorities are electrifying terminal equipment ahead of EU Green Deal bunkering requirements.
Poland
Gdansk and Gdynia deep-water expansion absorbs Central European container overflow from congested North Sea hubs. National rail infrastructure investments synchronize block train departures with vessel schedules. Silesian manufacturing clusters are bypassing Hamburg through direct Baltic feeder connections.
France
Marseille-Fos Mediterranean transshipment handles North African and Middle Eastern trade lanes with specialized Ro-Ro capacity. ANSM pharmaceutical cargo regulations tighten cold chain certification for temperature-sensitive exports. Auvergne-Rhône-Alpes industrial shippers are unbundling port-to-door liability coverage into per-voyage policies.
Europe Sea Freight Forwarding Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered service categories. The vendor base concentrates around integrated logistics conglomerates with captive vessel space allocations and digital freight platforms compressing spot-rate discovery cycles. Three archetypes dominate: asset-heavy ocean carriers with forwarding arms, technology-enabled intermediaries, and regional specialists in temperature-controlled or project cargo. Competitive moves center on rail-sea intermodal capacity lock-ups and emissions-verified carrier network restructuring.
Among Swiss-anchored integrated players, Kuehne + Nagel International AG exemplifies the visibility-platform archetype, while Danish-based DSV occupies a position within the consolidation-driven tier. German-structured DB Schenker represents the rail-sea intermodal specialist category. These three entities anchor the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| Kuehne + Nagel International AG |
| DHL Global Forwarding |
| DSV |
| DB Schenker |
| Bollore Logistics |
| CEVA Logistics |
| Geodis |
| Hellmann Worldwide Logistics |
| Fr. Meyer's Sohn |
| Others |
Pricing and Supply Chain Analysis
Rotterdam-Hamburg-Antwerp terminal concentration anchors vessel slot allocation power, compressing margin pools for mid-sized forwarders while amplifying pricing leverage for integrated players with captive berthing agreements and emission-verified carrier networks.
Pricing Analysis
Legacy diesel-fuel contracts, dual-fuel retrofits, and green methanol-ready slots stratify across premium, standard, and economy tiers. Kuehne + Nagel and DSV command premium positioning through real-time visibility platforms, while digital freight platforms erode standard-tier margins with instant spot-rate matching. Cost compression in economy-tier LCL consolidation intensifies as Alibaba and Amazon inject direct booking tools. E-commerce retailers exhibit highest price sensitivity; automotive manufacturers with JIT sequencing requirements show lowest.
Supply Chain Analysis
EU dual-use export controls on autonomous routing software and encryption-capable tracking devices limit technology transfer to non-EU forwarder networks. Manufacturing concentration clusters in Germany, the Netherlands, and Belgium. Container manufacturing draws from Chinese steel and South Korean reefer compressors. Single-source vulnerability concentrates in Scandinavian Ro-Ro operators controlling Baltic project cargo. Distribution runs through Rotterdam-Antwerp hub-and-spoke relay with German hinterland rail feeders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe sea freight forwarding market sits at a high-growth inflection as EU Green Deal emission mandates force $15 billion in vessel retrofit and port electrification investment, compressing incumbent adaptation windows while opening white-space for compliant challengers.
For Market Incumbents: Entrench rail-sea intermodal capacity through exclusive track access agreements along German hinterland corridors. Lock in green methanol supply contracts ahead of bunkering infrastructure buildout. DSV's Scandinavian lane dominance and DB Schenker's synchronized block train networks demonstrate defensible moats against digital platform disintermediation. For New Entrants and Emerging Players: Establish a beachhead in Polish port expansion corridors where Gdansk and Gdynia deep-water berths bypass Rotterdam congestion. Target Central European manufacturers with CSRD-compliant emissions reporting bundled into forwarding contracts. Lead with AI Act-certified autonomous routing to clarify liability frameworks that incumbents delay. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed temperature-controlled specialists facing F-Gas Regulation fleet replacement deadlines. Five-to-ten-year viability hinges on reefer container ownership and verified cold chain certification. Watch for EU AI Act liability rulings on autonomous cargo allocation as the signal for platform investment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Green Methanol Supply Agreement | Secures alternative fuel access for dual-fuel retrofits ahead of Rotterdam bunkering infrastructure completion. |
| Rail-Sea Intermodal Integration | Locks synchronized block train capacity along Hamburg-Munich corridor for automotive JIT sequencing. |
| CSRD Emissions Disclosure Platform | Captures paid advisory revenue from mid-sized forwarders restructuring subcontractor carbon accounting. |
| Blockchain-Enabled Documentation | Meets Eindhoven electronics manufacturer mandates for supplier compliance and custody verification. |
| Polish Port Capacity Investment | Opens Baltic access for Silesian manufacturing clusters bypassing North Sea terminal congestion. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU customs data, port authority throughput statistics, and carrier emission disclosure filings. Interviews with freight forwarding operations directors, terminal equipment procurement managers, and ECHA regulatory compliance officers were triangulated with KBA carrier certification records and CSRD implementation guidance. Bottom-up vessel slot allocation models were cross-checked against top-down EU maritime trade flow estimates.
Forecast inputs span service type segmentation, end-user cost tier stratification, and transport mode adoption curves across the projection horizon. Modeled dimensions include FCL versus LCL consolidation economics, reefer versus dry container equipment specialization, and intermodal rail-sea penetration rates. CAGRs were derived from elasticity-adjusted volume projections incorporating EU Green Deal compliance timelines and E-commerce fulfillment network expansion.
Stress conditions across green methanol supply scarcity, Baltic carrier consolidation, and AI Act liability reclassification were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions around emission-verified carrier network restructuring and port electrification capex cycles. Material shifts in EU alternative fuel bunkering infrastructure rollout or ECHA hazardous documentation enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Europe Refrigerated Container Shipping Market
Logistics and Shipping
Singapore 3PL Market
Logistics and Shipping
Turkey Freight and Logistics Market
Logistics and Shipping
Latin America Stevedoring and Marine Cargo Handling Market
Logistics and Shipping
Hong Kong Freight and Logistics Market
Logistics and Shipping
United Arab Emirates Freight and Logistics Market
Logistics and Shipping
North America Cargo Handling Equipment Market
Logistics and Shipping
North America Cargo Inspection Market
Logistics and Shipping
Air Freight Software Market
Logistics and Shipping
US Hazardous Goods Logistics Market
Logistics and Shipping
Japan Freight Forwarding Market
Logistics and Shipping
Car Carrier Market
Logistics and Shipping
WAN Connected Returnable Transport Asset Tracking Market
Logistics and Shipping
Cloud Logistics Market
Logistics and Shipping
United States 3PL Market
Logistics and Shipping
Global Dry Bulk Shipping Market