
 Global 3PL Market | 2026-2036
Global 3PL Market Size, Share, and Industry Trends Forecast 2026-2036
Global 3PL Market Analysis
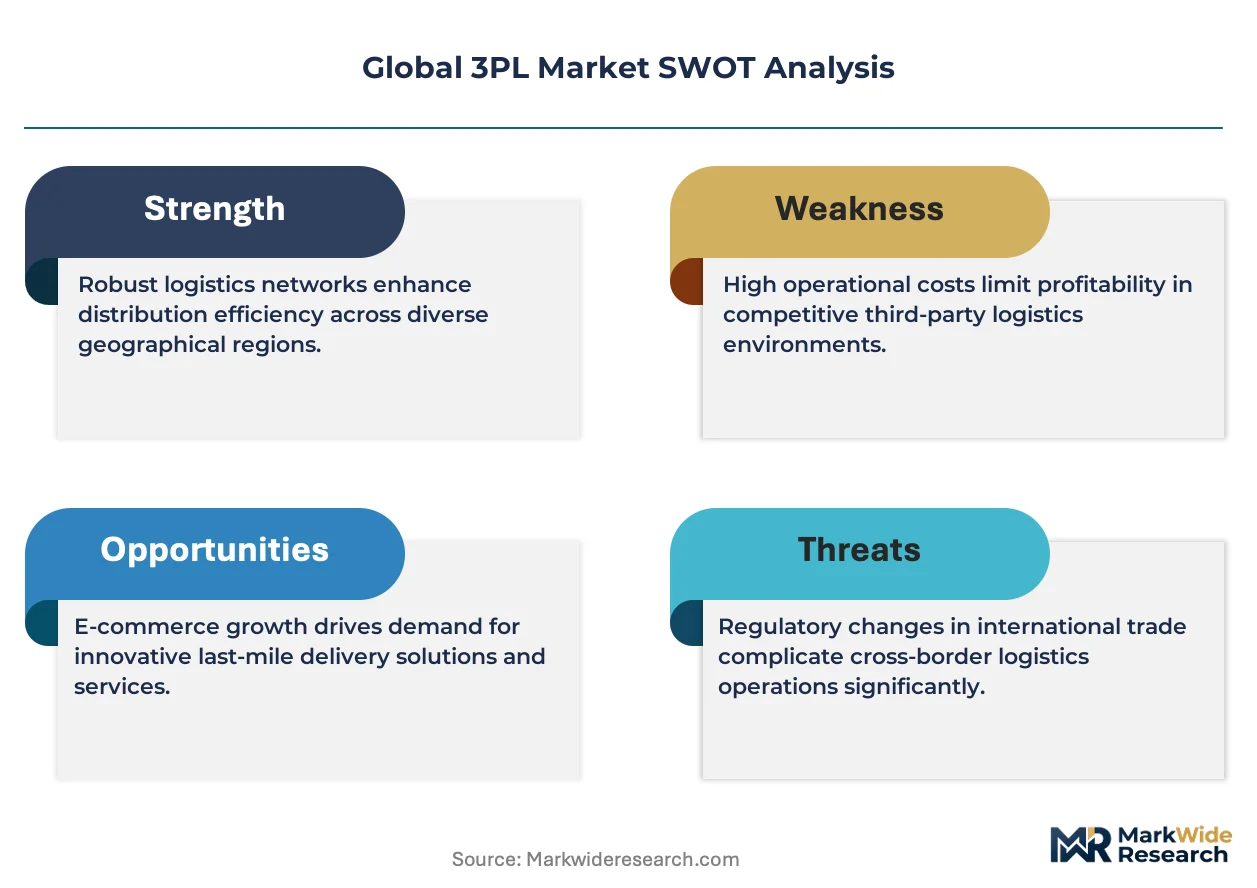
The EU Green Deal is shifting procurement priorities across contract logistics networks, compelling shippers to verify carrier emissions profiles before awarding freight contracts. DHL Supply Chain leverages its GoGreen Plus service to anchor long-term pharmaceutical and automotive accounts. Kuehne + Nagel competes through its integrated sea-air solutions linking Asian manufacturing hubs with European distribution centers. C.H. Robinson dominates North American over-the-road brokerage through its digital freight-matching platform and carrier density.
Third-party logistics (3PL) encompasses outsourced supply chain management functions including transportation procurement, inventory storage, order fulfillment, and freight forwarding coordination, typically governed by multi-year contracts with defined service-level agreements specifying on-time delivery thresholds and inventory accuracy rates. The primary commercial purpose centers on converting fixed logistics infrastructure costs into variable operating expenses while accessing specialized carrier networks and warehouse management systems. Transportation services lead the service type category in revenue contribution, reflecting persistent shipper preference for outsourced freight procurement and route optimization. E-commerce retailers within the customer type dimension represent the fastest-growing demand pool, driven by direct-to-consumer delivery expectations and returns processing complexity. Contract logistics commands the deepest margin pools due to long-term facility commitments and value-added services such as kitting, labeling, and quality inspection.
The US EPA and DOT jointly enforce emissions standards for heavy-duty trucking fleets, directly affecting 3PL provider equipment investment cycles and carrier qualification protocols. China's MIIT implements GB standards for intelligent logistics systems, mandating data interoperability between warehouse management platforms and transport tracking networks. The EU AI Act introduces risk-classification requirements for automated routing and demand-forecasting algorithms deployed by logistics operators. Stakeholders must monitor regulatory divergence between emissions accounting frameworks and digital platform compliance obligations as they evaluate network design and technology partnerships.
Market Dynamics
E-commerce fulfillment velocity requirements are compressing warehouse lease durations and forcing 3PL providers to deploy modular automation systems that can relocate across facilities within contract cycles.
Growth Catalysts
- EU Green Deal emissions mandates:Shippers now require verified carrier emissions data before contract award, creating demand for certified low-carbon logistics networks across European distribution corridors.
- Cross-border e-commerce expansion:Direct-to-consumer brands in China and Southeast Asia require bonded warehousing and last-mile partnerships in destination markets to manage customs complexity and returns processing.
- Real-time visibility platforms:IoT-enabled cargo monitoring systems allow pharmaceutical and automotive manufacturers to track temperature-sensitive shipments across multimodal handoffs.
Market Restraints
- Diesel price volatility:Fuel represents 25-35% of linehaul costs for road freight operators, compressing margins when hedging strategies fail during supply shocks.
- Port capacity concentration:Container throughput bottlenecks at Shanghai, Rotterdam, and Los Angeles-Long Beach create systemic delays that cascade through contract logistics schedules.
- Driver availability constraints:Aging workforce demographics and licensing barriers limit qualified operator pools in the United States and Western Europe.
Strategic Opportunities
- India's manufacturing corridor expansion:PLI scheme incentives for electronics and automotive production are generating demand for integrated contract logistics near Gujarat and Tamil Nadu industrial zones.
- Autonomous yard management:Convergence of computer vision and electric terminal tractors offers labor arbitrage in high-wage distribution markets.
- CSRD supply chain disclosure requirements:Mandatory Scope 3 emissions reporting for EU-listed companies creates advisory revenue streams for 3PL providers with carbon accounting capabilities.
Industry Challenges
- Warehouse management system interoperability:Legacy ERP integrations consume 12-18 month implementation timelines, delaying automation ROI realization for mid-market shippers.
- Cold chain qualification protocols:GDP certification for pharmaceutical distribution requires specialized facility audits and temperature mapping documentation that extend onboarding cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 3PL Market |
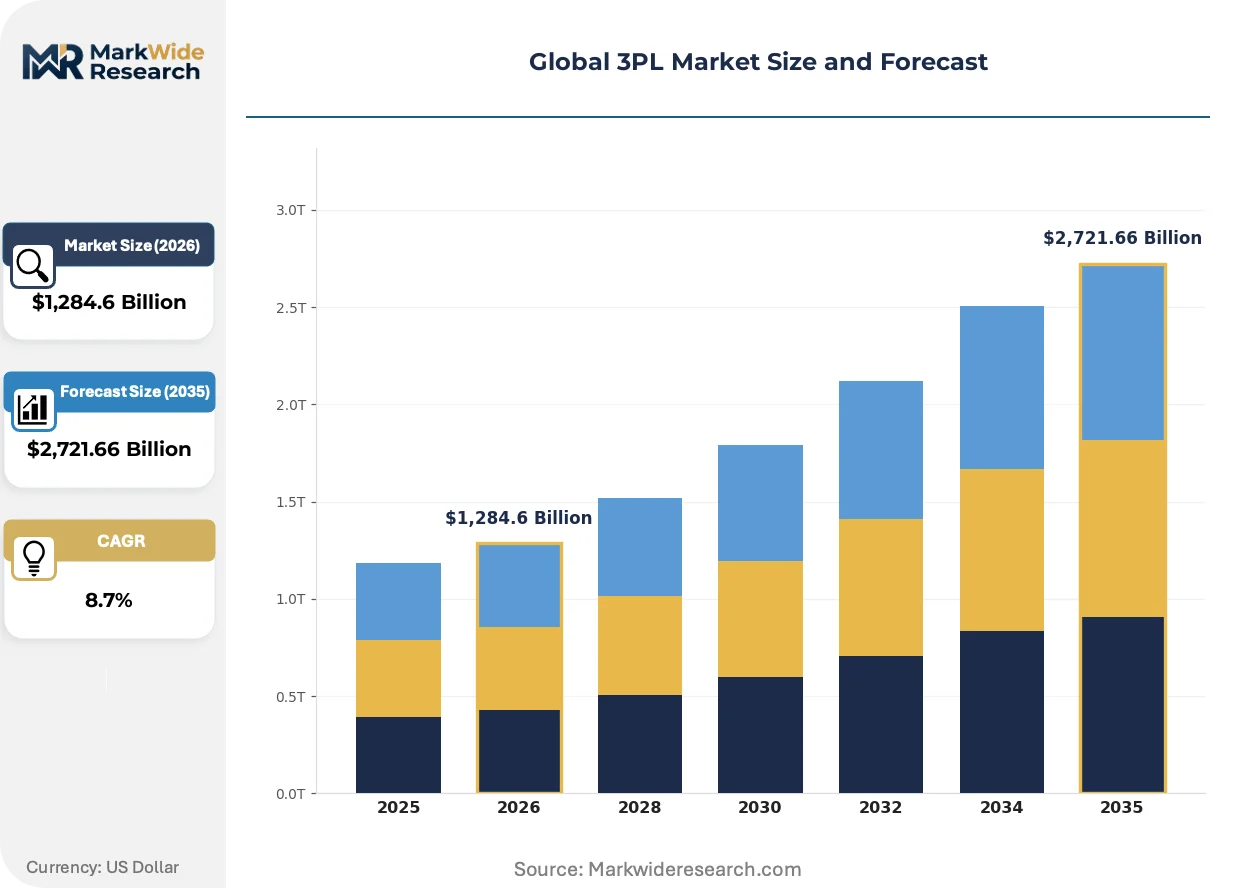
| Market Size in 2026 | $1,284.6 Billion |
| Market Size in 2035 | $2,721.66 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Contract Logistics Customer Type: Retailers, Manufacturers, E-commerce, Wholesalers Delivery Model: Just-in-Time, Dedicated Fleet, On-Demand, Multi-Modal Industry Vertical: Automotive, Consumer Goods, Healthcare, Technology |
| Companies Covered | Amazon, DHL Supply Chain & Global Forwarding, Kuehne + Nagel, DSV, CEVA Logistics, Nippon Express, C.H. Robinson, GXO Logistics, Sinotrans, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 3PL Market Emerging Trajectories
Digital freight platforms and warehouse robotics are merging into unified control towers that orchestrate inventory positioning and transportation procurement through single interfaces rather than siloed systems.
Autonomous mobile robots are converging with warehouse management systems to enable dynamic slotting algorithms that reposition fast-moving SKUs based on real-time order patterns. Grocery and apparel retailers with high SKU variability are deploying these systems at 50,000+ square meter facilities. This convergence is compressing labor cost differentials between developed and emerging market warehousing operations.
The EU AI Act risk-classification framework is mandating human oversight protocols for automated routing algorithms that optimize multimodal freight movements. Logistics operators must document decision audit trails and maintain fallback manual procedures for high-risk AI deployments. Pharmaceutical cold chain networks face the steepest compliance burden due to patient safety implications of temperature excursion errors.
Shippers are unbundling long-term contract logistics agreements into shorter-term, scope-specific arrangements that separate warehousing from transportation procurement. Automotive and industrial manufacturers in Germany and the United States are leading this fragmentation, awarding 2-3 year facility contracts while retaining direct carrier relationships for primary freight lanes. This pattern is eroding the integrated margin pools that historically anchored 3PL profitability.
Global 3PL Market Segmentation
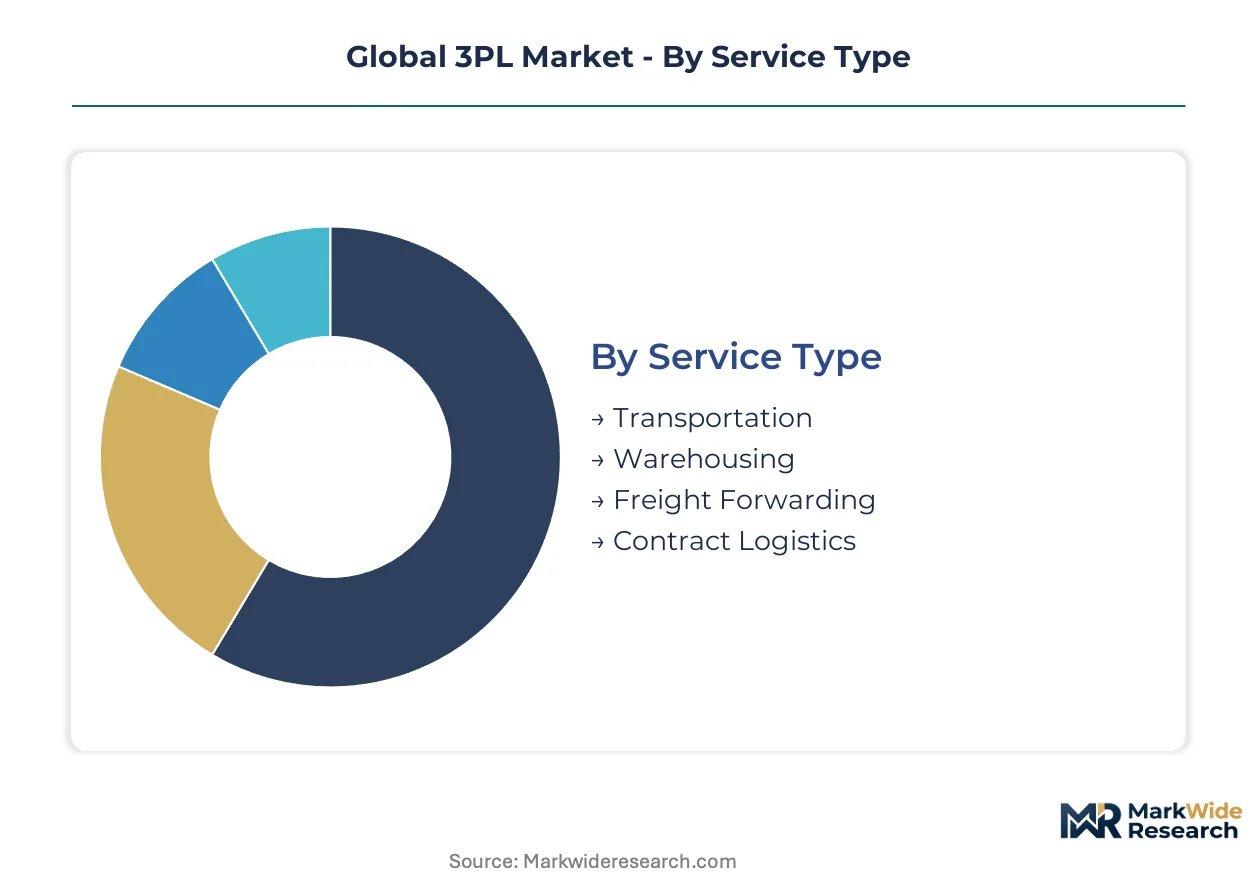
Third-party logistics providers structure service portfolios around operational depth and customer integration levels. Segment boundaries determine capital intensity, contract duration, and margin architecture across provider networks.
Service Type:
Standalone transportation procurement dominates shallow integration relationships, while embedded contract logistics anchors deep operational partnerships with multi-year facility commitments.
- Transportation:Linehaul and last-mile freight procurement governed by lane-specific rate contracts and carrier scorecards. Demand concentrates among automotive manufacturers in Germany and the United States seeking dedicated fleet capacity for inbound parts sequencing. Diesel price hedging failures during supply shocks compress margins unpredictably.
- Contract Logistics:Integrated facility operations combining warehousing, inventory management, and value-added services under single accountability structures. Pharmaceutical distributors in Switzerland and consumer electronics brands in China award 5-7 year agreements to secure GDP-certified cold chain infrastructure and bonded customs facilities. Long-term lease commitments lock in margin pools but limit geographic flexibility.
- Warehousing:Standalone storage services with variable commitment periods and modular automation deployment. E-commerce fulfillment centers in India and Southeast Asia drive specifications for 50,000+ square meter facilities with robotic goods-to-person systems.
- Freight Forwarding:Intermodal coordination across ocean, air, and land networks with customs brokerage and documentation management. Cross-border e-commerce expansion from China into European markets generates demand for sea-air consolidation and deconsolidation services.
Volume placements concentrate in Transportation; the faster expansion belongs to Contract Logistics.
Customer Type:
Shipper scale and channel complexity determine outsourcing depth, with direct-to-consumer operations demanding the most sophisticated fulfillment architectures.
- E-commerce:Direct-to-consumer retailers requiring same-day or next-day delivery promises, returns processing infrastructure, and dynamic inventory positioning across multiple nodes. Chinese marketplace sellers expanding into European markets drive cross-border bonded warehousing demand. Velocity requirements compress warehouse lease durations and force modular automation investments.
- Manufacturers:Industrial producers outsourcing inbound materials management and finished goods distribution to convert fixed logistics costs into variable operating expenses. Automotive OEMs in Germany and the United States unbundle warehousing from transportation procurement, awarding shorter facility contracts while retaining direct carrier relationships.
- Retailers:Brick-and-mortar and omnichannel operators balancing store replenishment with e-commerce fulfillment from shared inventory pools. Grocery and apparel segments deploy autonomous mobile robots for dynamic slotting in high-SKU-variability facilities.
- Wholesalers:Distribution intermediaries consolidating fragmented supplier bases and managing bulk break-bulk operations for downstream customers. Pharmaceutical wholesalers in Europe face EU Green Deal emissions verification requirements for carrier selection.
Shipper concentration sits with Manufacturers; E-commerce climbs the fastest in contract value growth.
Delivery Model:
Reliability requirements and asset ownership structures differentiate service tiers, from dedicated capacity commitments to spot-market flexibility.
- Just-in-Time:Synchronized production logistics with narrow delivery windows and severe penalty structures for deviation. Automotive assembly plants in Germany and the United States specify 15-minute tolerance windows for sequenced parts delivery.
- Dedicated Fleet:Captive vehicle and driver resources assigned exclusively to single shipper accounts. Pharmaceutical cold chain networks in Switzerland and France require temperature-validated equipment with continuous monitoring documentation.
- On-Demand:Spot-market capacity procurement through digital freight-matching platforms with dynamic pricing. Small and mid-market shippers in India leverage these services to avoid fixed fleet commitments during demand volatility.
- Multi-Modal:Orchestrated handoffs across road, rail, ocean, and air modes with single accountability for end-to-end performance. Electronics manufacturers in China utilize integrated sea-air solutions to balance speed and cost for European distribution.
Contract value aggregates in Dedicated Fleet; Multi-Modal solutions gain share fastest among international shippers.
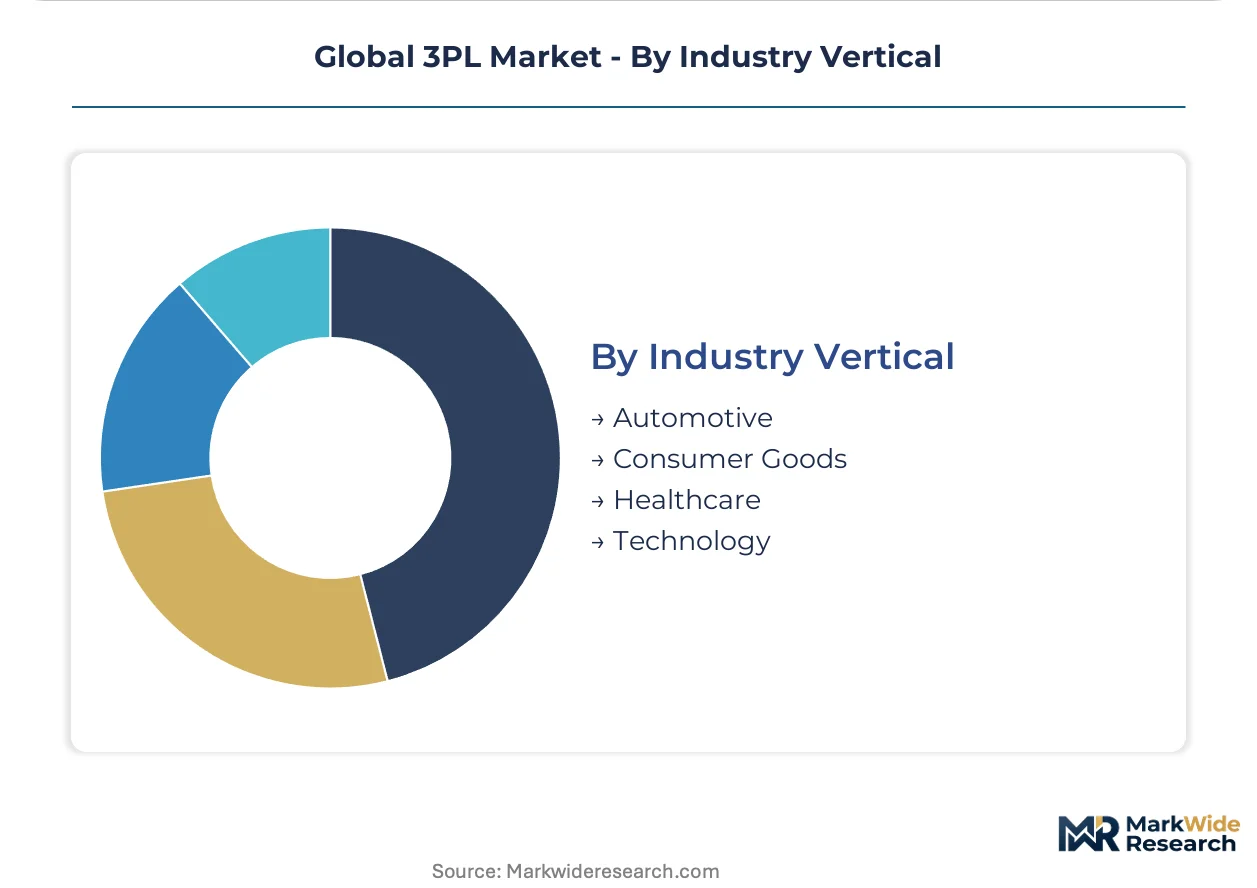
Industry Vertical:
Regulatory intensity and product characteristics shape compliance burdens and facility specifications across end-use markets.
- Healthcare:Pharmaceutical, biologic, and medical device distribution requiring GDP certification, temperature mapping, and serialization compliance. EU AI Act risk-classification mandates human oversight protocols for automated routing algorithms in patient-facing cold chain networks.
- Automotive:Inbound production logistics, aftermarket parts distribution, and finished vehicle transport with just-in-time sequencing requirements. Battery electric vehicle supply chains in China and Germany drive demand for hazardous materials handling certification and thermal runaway containment protocols.
- Consumer Goods:High-velocity replenishment of fast-moving packaged goods with seasonal demand spikes and promotional volatility. Apparel retailers deploy dynamic slotting algorithms repositioning SKUs based on real-time order patterns.
- Technology:Electronics, semiconductor, and hardware distribution with high value density and rapid obsolescence cycles. India's PLI scheme incentives for electronics manufacturing generate integrated contract logistics demand near Gujarat and Tamil Nadu industrial zones.
Revenue concentration rests with Consumer Goods; Healthcare shows the steepest expansion trajectory driven by cold chain compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Yangshan Deep Water Port anchors the densest concentration of integrated contract logistics infrastructure worldwide, processing container volumes that cascade through bonded warehousing networks across the Yangtze River Delta manufacturing corridor.
China
Electronics manufacturers in Shenzhen and Dongguan drive demand for sea-air consolidation services linking Pearl River Delta factories with European distribution nodes. MIIT's GB standards for intelligent logistics systems mandate data interoperability between warehouse management platforms and transport tracking networks. The Yangtze River Delta cluster around Shanghai and Suzhou supports the highest density of automated fulfillment centers serving cross-border e-commerce exporters.
United States
Automotive OEMs in Michigan and Tennessee unbundle warehousing contracts from transportation procurement, compressing 3PL margin pools through shorter facility agreements. EPA and DOT jointly enforce emissions standards for heavy-duty trucking fleets, accelerating carrier qualification protocols and equipment investment cycles. The Chicago-Detroit corridor concentrates pharmaceutical cold chain infrastructure serving Midwest distribution networks.
Germany
Automotive assembly plants in Stuttgart and Wolfsburg specify 15-minute tolerance windows for sequenced parts delivery, demanding synchronized just-in-time logistics architectures. EU Green Deal emissions mandates compel shippers to verify carrier emissions profiles before awarding freight contracts. The Rhine-Ruhr industrial zone anchors contract logistics networks serving chemical and pharmaceutical manufacturers with GDP-certified cold chain facilities.
India
Electronics and automotive production incentives under the PLI scheme generate integrated contract logistics demand near Gujarat and Tamil Nadu industrial zones. BIS standards govern warehouse construction and fire safety protocols for large-format fulfillment facilities. The Delhi-Mumbai Industrial Corridor concentrates new logistics park development serving manufacturing investments in Haryana and Maharashtra.
Switzerland
Pharmaceutical distributors in Basel and Geneva award 5-7 year contract logistics agreements to secure temperature-validated cold chain infrastructure with continuous monitoring documentation. Swissmedic regulates GDP certification requirements that extend facility onboarding cycles through specialized audits and temperature mapping protocols. The Zurich-Geneva logistics axis serves as the primary European hub for high-value biologic shipments requiring validated thermal packaging.
Global 3PL Market Vendor Landscape
Premium-margin players sit above commodity-margin players across service integration depth, with contract logistics specialists commanding multi-year facility commitments while transportation brokers compete on digital matching efficiency. The vendor base stratifies into three tiers: integrated global networks with owned air and ocean assets, regional contract logistics operators with captive warehouse portfolios, and digital freight platforms aggregating spot-market capacity. Consolidation pressure intensifies as shippers fragment long-term agreements into scope-specific arrangements. Strategic moves center on autonomous yard technology partnerships and carbon accounting capability acquisitions.
Within the integrated global network tier, DHL Supply Chain and Kuehne + Nagel occupy positions exemplifying divergent specialization strategies. DHL Supply Chain leverages its GoGreen Plus service to anchor pharmaceutical and automotive accounts requiring verified low-carbon logistics networks. Kuehne + Nagel competes through integrated sea-air solutions linking Asian manufacturing hubs with European distribution centers. Among North American digital freight specialists, C.H. Robinson represents the platform-archetype dominance in over-the-road brokerage through carrier density and dynamic pricing algorithms.
| Leading Market Players |
|---|
| Amazon |
| DHL Supply Chain & Global Forwarding |
| Kuehne + Nagel |
| DSV |
| CEVA Logistics |
| Nippon Express |
| C.H. Robinson |
| GXO Logistics |
| Sinotrans |
| Others |
Supply Flow & Price Mechanics
Modular automation systems that relocate across facilities within contract cycles simultaneously compress capital recovery timelines and concentrate bargaining power with equipment lessors in China and Germany. This technological shift forces 3PL providers to accept shorter payback periods while carrier networks in these manufacturing hubs capture premium lease rates for redeployable robotic infrastructure.
Pricing Analysis
Outcome-based pricing tied to on-time delivery thresholds anchors pharmaceutical and automotive contracts in Switzerland and Germany. Three-tier pricing structure across premium, standard, and economy levels separates GDP-certified cold chain services from general warehousing and spot-market brokerage. Cost compression in standard-tier transportation procurement is intensifying because diesel price volatility erodes hedging effectiveness. Small and mid-market e-commerce retailers in India exhibit the highest price sensitivity, while pharmaceutical distributors in Basel demonstrate the lowest due to patient safety compliance requirements.
Supply Chain Analysis
Freight cost volatility in containerized ocean lanes and European road networks shapes carrier qualification protocols and contract duration decisions. Supply concentration rests on China for automated fulfillment equipment, Germany for precision manufacturing components, and the United States for digital freight-matching platforms. Raw material dependencies include lithium-ion battery systems for electric terminal tractors, steel for warehouse racking infrastructure, and semiconductors for IoT cargo monitoring devices. Single-source vulnerability in Shanghai port capacity creates systemic delay cascades. Distribution runs through bonded warehousing networks in the Yangtze River Delta before final-mile handoffs to European distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing backward integration into autonomous yard technology to capture labor arbitrage in high-wage distribution markets.
For Market Incumbents: Cement multi-year facility commitments with pharmaceutical and automotive accounts by embedding carbon accounting capabilities that satisfy EU Green Deal emissions verification requirements. Acquire specialized cold chain operators in Switzerland to secure GDP-certified infrastructure. Defend against digital freight platforms by anchoring integrated sea-air solutions linking Asian manufacturing hubs with European distribution nodes. For New Entrants and Emerging Players: Launch via on-demand digital freight-matching platforms targeting small and mid-market shippers in India's manufacturing corridor expansion around Gujarat and Tamil Nadu. White-space opportunities concentrate in autonomous yard management for high-wage markets and CSRD advisory services for EU-listed companies requiring Scope 3 emissions reporting. Penetrate through partnerships with electronics manufacturers seeking bonded warehousing for cross-border e-commerce expansion. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated global networks seeking regional contract logistics capabilities. Long-term viability favors providers with captive warehouse portfolios in pharmaceutical cold chain and automotive just-in-time corridors. Target mid-cap operators with GDP certification and automated facility infrastructure. Watch for inflection in EU AI Act enforcement timelines affecting routing algorithm compliance costs.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Yard Technology Partnership | Computer vision and electric terminal tractors enable labor arbitrage in Germany and United States distribution markets. |
| Carbon Accounting Capability Acquisition | CSRD supply chain disclosure requirements create advisory revenue streams for EU-listed company relationships. |
| Modular Automation Deployment | Robotic goods-to-person systems compress lease durations and enable facility relocation across contract cycles. |
| Sea-Air Consolidation Service Expansion | Integrated solutions linking Pearl River Delta factories with European nodes balance speed and cost for electronics manufacturers. |
| GDP-Certified Cold Chain Infrastructure Investment | Pharmaceutical distributors in Switzerland award 5-7 year agreements for temperature-validated facilities with continuous monitoring. |
Methodological Framework
Multi-period observation of carrier emissions profiles, warehouse automation deployment rates, and contract duration patterns anchored the trend analysis, supplemented by interviews with logistics procurement directors, pharmaceutical supply chain managers, automotive platform engineers, and e-commerce fulfillment operators. Secondary validation drew from EPA emissions filings, EU Green Deal regulatory texts, MIIT GB standard publications, and customs trade data for containerized freight flows. Bottom-up facility-level capacity assessments and top-down market sizing triangulated volume estimates.
Input-output matrices modeled service type, customer segment, delivery model, and industry vertical dimensions across the projection horizon. CAGRs were derived from segment-level growth trajectories weighted by revenue concentration. Forecast inputs incorporated diesel price volatility indices, port throughput capacity utilization at Shanghai and Rotterdam, and driver availability demographic projections for United States and Western Europe markets.
Regulatory enforcement timelines, fuel supply shocks, and automation technology adoption curves are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about emissions mandate implementation pacing and carrier qualification protocol evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
North America Cross Border Road Freight Transport Market
Logistics and Shipping
ASEAN Chemical Logistics Market
Logistics and Shipping
Air Cargo Container Market
Logistics and Shipping
Qatar Third-Party Logistics (3PL) Market
Logistics and Shipping
Singapore Shipping Agency Services Market
Logistics and Shipping
Hungary Freight and Logistics Market
Logistics and Shipping
India Freight and Logistics Market
Logistics and Shipping
GCC Air Freight Transport Market
Logistics and Shipping
Iraq Logistics Market
Logistics and Shipping
Czech Republic Third-Party Logistics Market
Logistics and Shipping
Australia Cold Chain Logistics Market
Logistics and Shipping
Tanker Cargo Ship Market
Logistics and Shipping
United Arab Emirates Freight and Logistics Market
Logistics and Shipping
Water Hauling Services Market
Logistics and Shipping
China Shipping Agency Services Market
Logistics and Shipping
Russia 3PL Market