
 Third Party Logistics Services Market | 2026-2036
Third Party Logistics Services Market Size, Share, and Industry Trends Forecast 2026-2036
Third Party Logistics Services Market Analytics
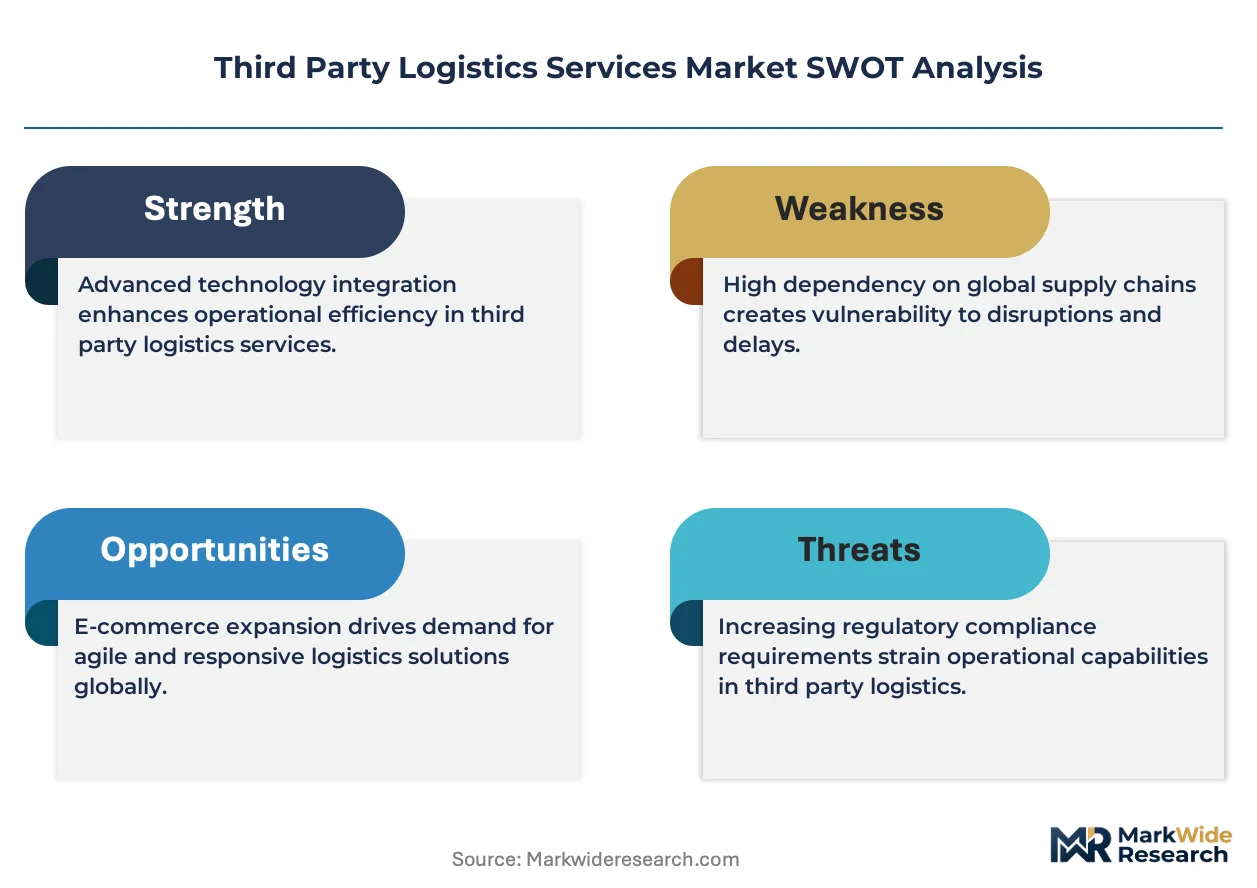
The gap between premium integrated logistics and commodity freight brokerage is expanding as shippers demand real-time visibility and carbon accountability. DHL Supply Chain & Global Forwarding leverages its air-ocean intermodal network to anchor high-margin pharmaceutical lanes. Kuehne + Nagel sustains competitive position through specialized perishables expertise and digital booking platforms. C.H. Robinson dominates North American truckload brokerage through proprietary freight-matching algorithms.
Third party logistics services encompass outsourced transportation, warehousing, inventory management, and freight forwarding executed under contract by external providers, typically governed by service-level agreements specifying on-time delivery thresholds and inventory accuracy rates above 99.5 percent. These services enable manufacturers and retailers to convert fixed distribution costs into variable operating expenses while accessing specialized infrastructure. Transportation and warehousing together form the revenue core, though inventory management segments attract disproportionate margin expansion as clients pay premiums for predictive stock positioning. E-commerce client types represent the fastest-growing demand pool, with dedicated delivery models commanding higher contract values than shared networks due to capacity guarantees.
The EU Green Deal and CSRD reporting requirements are forcing logistics providers to document scope-three emissions across subcontractor fleets, reshaping vendor qualification criteria. FDA food safety modernization rules and REACH chemical handling standards in Europe impose parallel compliance burdens on cross-border operators. Stakeholders must monitor how carbon border adjustment mechanisms and digital customs platforms will restructure lane economics and asset deployment decisions.
Market Dynamics
Real-time visibility mandates from pharmaceutical and automotive OEMs are compressing carrier selection cycles and forcing asset-heavy investments in telematics infrastructure across contract logistics networks.
Growth Catalysts
- EU Green Deal scope-three reporting:Shippers now require documented emissions data from subcontractor fleets, creating premium pricing power for providers with certified carbon accounting systems.
- Cross-border e-commerce corridors:Dedicated fulfillment networks in Vietnam and Indonesia are absorbing manufacturing relocation from China, driving demand for bonded warehousing and last-mile density.
- Automotive EV battery logistics:UN 38.3 dangerous goods certification requirements for lithium-ion transport are filtering out generalist carriers and concentrating volume with hazmat-qualified specialists.
Market Restraints
- Diesel price volatility:Fuel represents 25-35% of linehaul costs for road freight operators, with European carriers exposed to EU ETS carbon pricing passthrough from 2024.
- Port concentration risk:Shanghai-Ningbo and Rotterdam-Antwerp corridor dependencies create systemic vulnerability from labor actions or customs system failures.
- Driver shortage demographics:Aging workforces in Germany and the United States face recruitment gaps that constrain capacity expansion regardless of equipment availability.
Strategic Opportunities
- India's pharmaceutical cold chain:CDSCO temperature compliance mandates for biologics distribution remain underpenetrated by organized 3PLs outside Mumbai and Hyderabad clusters.
- Blockchain-IoT convergence:Immutable custody records for high-value electronics are enabling insurance premium reductions that offset platform deployment costs.
- Direct-to-manufacturer spare parts:Industrial OEMs are bypassing distributor networks for critical components, opening dedicated inventory positioning contracts with specialized forwarders.
Industry Challenges
- Warehouse automation integration:Retrofitting AS/RS and AMR systems into existing brownfield facilities requires 18-24 month timelines that conflict with contract renewal cycles.
- REACH chemical handling certification:European operators face 12-18 month qualification periods for new substance categories, delaying revenue recognition on specialty chemical contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Third Party Logistics Services Market |
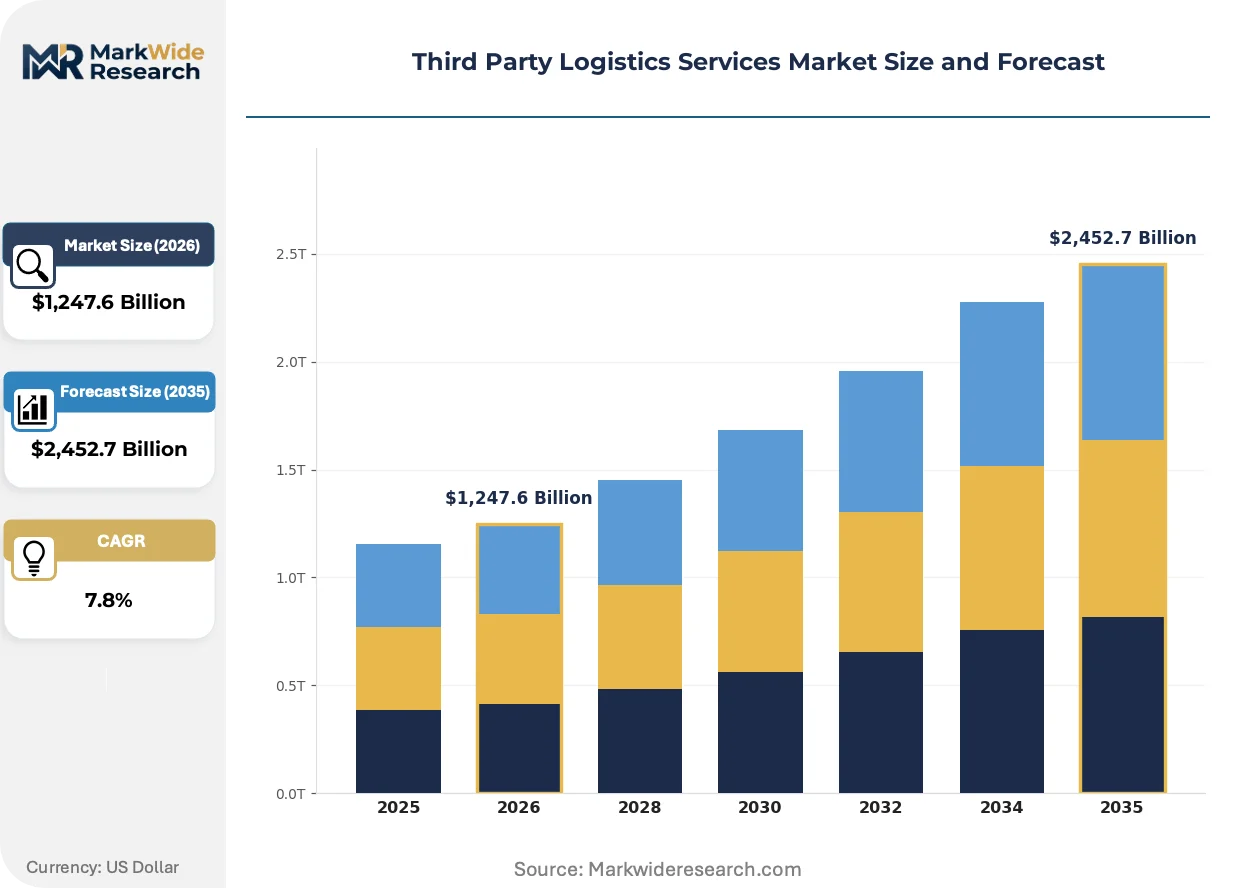
| Market Size in 2026 | $1,247.6 Billion |
| Market Size in 2035 | $2,452.7 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Inventory Management, Freight Forwarding Client Type: Manufacturers, Retailers, E-commerce, Wholesalers Technology: TMS, WMS, RFID, IoT Delivery Model: On-Demand, Subscription, Dedicated, Shared |
| Companies Covered | Amazon, DHL Supply Chain & Global Forwarding, Kuehne + Nagel, DSV, DB Schenker, CEVA Logistics, Nippon Express, C.H. Robinson, Maersk Logistics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Third Party Logistics Services Market Evolving Landscape
Digital freight platforms and autonomous yard operations are converging to compress dwell times and eliminate manual dispatch decisions in high-throughput distribution centers.
Autonomous mobile robots are expanding into case-picking and pallet transport functions within e-commerce fulfillment centers. Grocery and apparel retailers with SKU proliferation above 50,000 units are deploying these systems at 40% faster payback periods than traditional conveyor investments. The technology is expanding into mid-market 3PL contracts previously reserved for manual operations, compressing labor cost differentials between tier-one and regional providers.
CSRD sustainability reporting requirements now mandate scope-three emissions disclosure across European value chains. Logistics providers must audit subcontractor fuel consumption and asset utilization rates to maintain shipper qualification status. Pharmaceutical and automotive verticals in Germany and the Netherlands are demanding quarterly carbon performance reviews that influence contract renewal terms and volume allocation decisions.
Shippers are consolidating carrier relationships from 15-20 providers per lane to 3-5 strategic partnerships with guaranteed capacity commitments. Consumer electronics manufacturers with China-to-Europe volumes are trading rate competitiveness for allocation certainty during peak seasons. This concentration is most visible in Dutch and Belgian port hinterland corridors where dedicated fleet arrangements now command 12-18% contract premiums over spot-market alternatives.
Third Party Logistics Services Market Segmentation
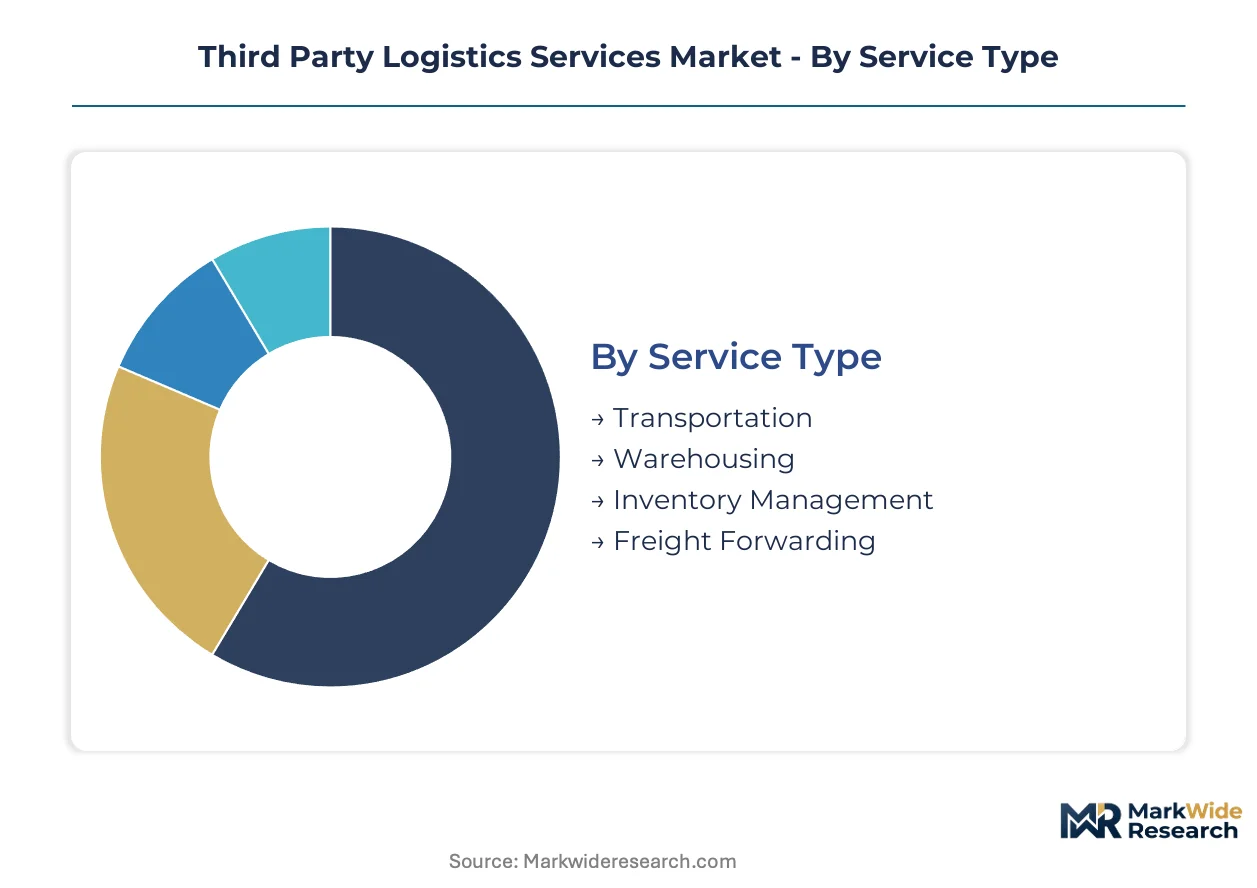
Third party logistics services fragment across operational capabilities, client sophistication, and technology intensity. Segment selection determines capital requirements, margin profiles, and regulatory exposure for providers competing across contract tiers.
Service Type:
Volume-heavy segments dominate revenue concentration while premium services capture disproportionate margin expansion.
- Transportation:Road, air, ocean, and rail freight execution under contract terms governing on-time performance thresholds. Pharmaceutical and automotive OEMs in Germany and the United States compress carrier selection cycles through real-time visibility mandates. Fuel represents 25-35% of linehaul costs, with European operators absorbing EU ETS carbon pricing passthrough.
- Warehousing:Facility operations spanning receiving, storage, order fulfillment, and cross-docking functions governed by inventory accuracy rates above 99.5%. E-commerce fulfillment networks in Vietnam and Indonesia absorb manufacturing relocation from China, driving bonded warehousing demand. Retrofitting AS/RS and AMR systems into brownfield facilities requires 18-24 month timelines.
- Inventory Management:Predictive stock positioning, demand forecasting, and safety buffer optimization converting fixed distribution costs into variable operating expenses. Clients pay premiums for predictive capabilities that reduce carrying costs while maintaining service levels. This segment captures the steepest expansion trajectory as manufacturers prioritize working capital efficiency.
- Freight Forwarding:Intermodal coordination, customs brokerage, and documentation management for cross-border movements. UN 38.3 dangerous goods certification requirements for lithium-ion transport filter out generalist carriers. Port concentration risk in Shanghai-Ningbo and Rotterdam-Antwerp corridors creates systemic vulnerability.
Mature deployment sits with Transportation. Newer deployment is concentrated in Inventory Management.
Client Type:
Application intensity varies by sector compliance burdens and inventory velocity requirements.
- E-commerce:Direct-to-consumer fulfillment with SKU proliferation above 50,000 units demanding dedicated delivery models. Autonomous mobile robots deploy at 40% faster payback periods than traditional conveyor investments in grocery and apparel segments. Dedicated capacity guarantees command higher contract values than shared networks.
- Manufacturers:Industrial OEMs bypassing distributor networks for critical spare parts, opening dedicated inventory positioning contracts. CDSCO temperature compliance mandates for Indian biologics distribution remain underpenetrated by organized 3PLs outside Mumbai and Hyderabad clusters.
- Retailers:Omnichannel distribution combining store replenishment with direct fulfillment from regional DCs. CSRD scope-three reporting requirements force documentation of subcontractor emissions across European value chains.
- Wholesalers:Consolidated procurement and break-bulk distribution serving fragmented downstream channels. Shared warehouse networks match cost structures to volume variability in non-durable goods categories.
Established relationships anchor Manufacturers. Emerging opportunity clusters around E-commerce.
Technology:
Margin capture depends on integration depth and data architecture sophistication.
- WMS:Warehouse management systems orchestrating inventory location, labor allocation, and order wave planning. Brownfield retrofit timelines conflict with contract renewal cycles, delaying technology refresh decisions.
- TMS:Transportation management platforms optimizing carrier selection, route planning, and freight audit processes. Proprietary freight-matching algorithms differentiate brokerage performance in North American truckload markets.
- IoT:Sensor networks enabling real-time asset tracking, condition monitoring, and predictive maintenance across distributed fleets. Pharmaceutical lanes demand telematics infrastructure investments that compress carrier selection cycles.
- RFID:Radio-frequency identification for automated inventory counts, shipment verification, and yard management. Immutable custody records for high-value electronics enable insurance premium reductions.
RFID deployment lags in mid-market contracts. IoT adoption accelerates fastest among temperature-sensitive verticals.
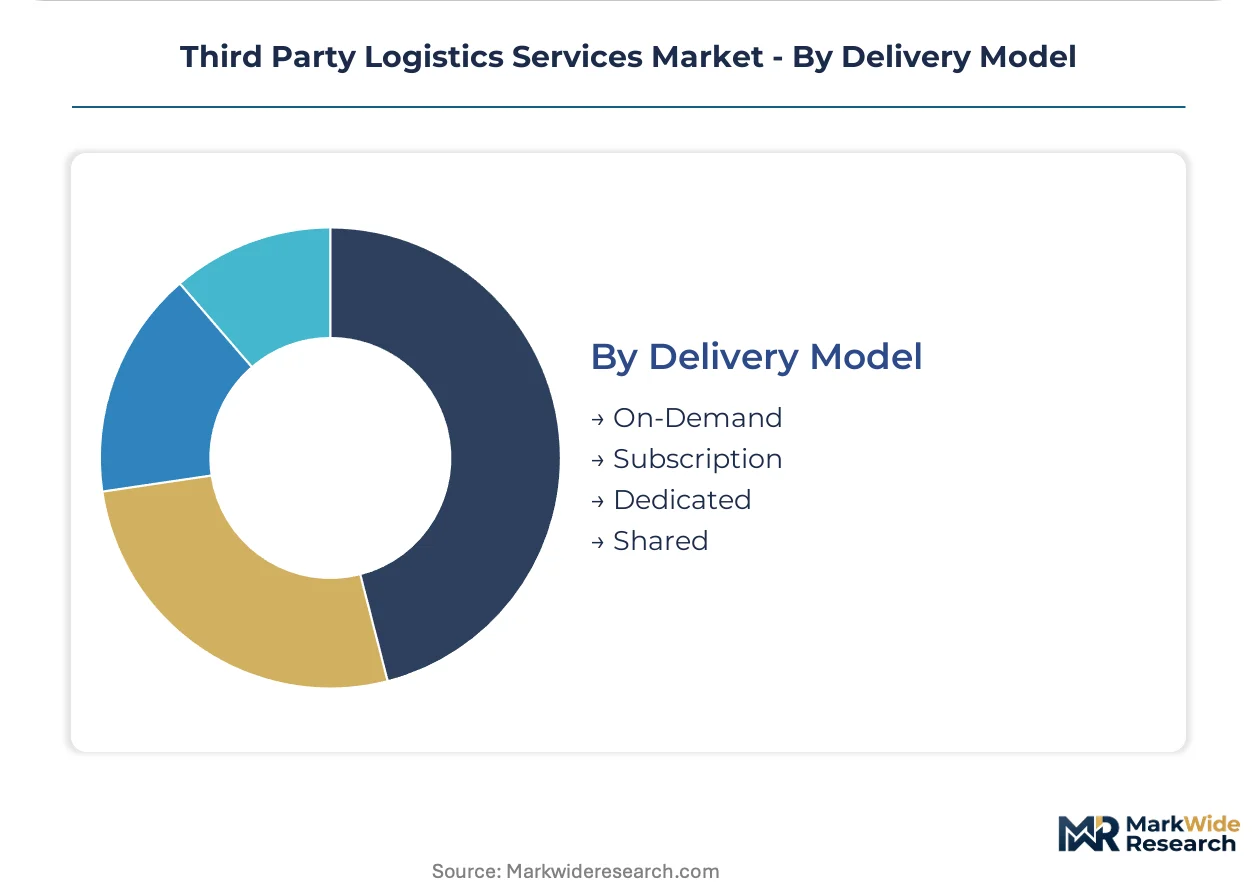
Delivery Model:
Contract structure determines capital commitment duration and revenue predictability.
- Dedicated:Exclusive capacity arrangements with guaranteed throughput commitments and customized operating procedures. Consumer electronics manufacturers with China-to-Europe volumes trade rate competitiveness for allocation certainty during peak seasons. Dutch and Belgian port hinterland corridors command 12-18% contract premiums over spot-market alternatives.
- Shared:Multi-client facilities and transportation networks matching variable demand to pooled capacity. Cost efficiency appeals to mid-market shippers with inconsistent volume profiles and limited forecast accuracy.
- Subscription:Fixed-fee arrangements covering defined service levels with predictable monthly billing. Simplifies procurement for finance teams prioritizing budget certainty over optimization flexibility.
- On-Demand:Transactional access to capacity without contractual minimums, priced at spot-market rates. Digital booking platforms reduce friction for expedited shipments and overflow handling.
Shared networks dominate mid-market penetration. Dedicated arrangements expand fastest among automotive and pharmaceutical verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai-Ningbo corridor dominance shapes global 3PL deployment patterns. Port concentration and manufacturing relocation dynamics create divergent growth trajectories across major logistics markets.
United States
E-commerce fulfillment networks and automotive EV battery logistics drive carrier selection cycles. FDA food safety modernization rules impose compliance burdens on cross-border cold chain operators. Chicago and Dallas-Fort Worth distribution clusters absorb dedicated capacity commitments from pharmaceutical and retail shippers.
Germany
Automotive OEM real-time visibility mandates compress contract renewal timelines for logistics providers. EU Green Deal scope-three reporting requirements force documentation of subcontractor emissions across value chains. Rhine-Ruhr and Stuttgart industrial corridors concentrate pharmaceutical and automotive 3PL contracts with certified carbon accounting systems.
China
Manufacturing relocation to Vietnam and Indonesia sustains bonded warehousing demand in coastal export zones. SAMR and MEE regulations on chemical handling and dual carbon goals reshape vendor qualification criteria. Yangtze River Delta and Pearl River Delta clusters maintain dominance in consumer electronics and automotive component logistics.
India
Pharmaceutical cold chain expansion and export processing zone growth attract organized 3PL investment. CDSCO temperature compliance mandates for biologics distribution remain underpenetrated outside established clusters. Mumbai and Hyderabad pharmaceutical corridors command premium pricing for hazmat-qualified specialists.
Netherlands
Rotterdam-Antwerp hinterland concentration creates systemic vulnerability but sustains dedicated fleet premiums. EU CSRD sustainability reporting requirements mandate quarterly carbon performance reviews from logistics subcontractors. Dutch port logistics zones command 12-18% contract premiums over spot-market alternatives for guaranteed capacity arrangements.
Third Party Logistics Services Market Competitive Landscape
Capital-heavy asset owners compete with asset-light platform orchestrators for shipper relationships. The market structures around three tiers: integrated global networks with owned infrastructure, regional specialists with vertical expertise, and digital freight platforms with algorithmic matching capabilities. Strategic moves concentrate on M&A-driven network consolidation and technology licensing partnerships that compress carrier selection cycles.
Among integrated global networks, DHL Supply Chain & Global Forwarding and Kuehne + Nagel occupy positions exemplifying the premium-tier archetype with specialized pharmaceutical and perishables capabilities. C.H. Robinson represents the asset-light brokerage model with proprietary freight-matching algorithms dominating North American truckload markets.
| Leading Market Players |
|---|
| Amazon |
| DHL Supply Chain & Global Forwarding |
| Kuehne + Nagel |
| DSV |
| DB Schenker |
| CEVA Logistics |
| Nippon Express |
| C.H. Robinson |
| Maersk Logistics |
| Others |
Value Network & Pricing Analysis
Diesel benchmark indices in Rotterdam and Singapore cascade through road freight linehaul economics, compressing margins for carriers without fuel surcharge mechanisms while concentrating pricing power with asset-heavy operators holding dedicated fleet contracts.
Pricing Analysis
Throughput-based pricing anchors premium contracts in pharmaceutical and automotive verticals, where shippers pay for guaranteed capacity rather than spot-market variability. Three-tier pricing structure across dedicated, shared, and on-demand service levels separates providers by certification depth and carbon accounting sophistication. Cost compression in commodity brokerage segments is intensifying because digital freight platforms erode traditional markup structures. Mid-market manufacturers with inconsistent volume profiles exhibit highest price sensitivity, while pharmaceutical shippers prioritize compliance documentation over rate competitiveness.
Supply Chain Analysis
Domestic-content mandates in India's pharmaceutical corridors and Vietnam's export processing zones are reshaping warehouse sourcing toward local facility development. Supply concentrates in China's Yangtze River Delta, Germany's Rhine-Ruhr corridor, and the Netherlands' Rotterdam-Antwerp hinterland for bonded warehousing and cross-docking infrastructure. Asset deployment hinges on lithium-ion battery handling certification, cold chain equipment availability, and last-mile density in urban clusters. Single-source vulnerability in Shanghai-Ningbo port dependencies creates systemic exposure to labor actions and customs system failures. Distribution runs through hub-and-spoke networks anchored by regional distribution centers serving e-commerce fulfillment and automotive spare parts positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Driver shortage demographics across Germany and the United States constrain capacity expansion regardless of equipment availability, propping contract premiums for qualified operators. Fleet owners and logistics providers must navigate this supply-constrained environment through differentiated positioning.
For Market Incumbents: Hedge against digital freight platform disruption by deepening proprietary freight-matching algorithm investments and securing long-term dedicated capacity commitments from pharmaceutical and automotive OEMs. Acquire hazmat-qualified specialists in lithium-ion transport to capture EV battery logistics volume filtering out generalist carriers. Carbon accounting certification represents the priority lever for maintaining shipper qualification status under EU CSRD requirements.
For New Entrants and Emerging Players: The 12-18% contract premium gap between dedicated fleet arrangements and spot-market alternatives in Dutch and Belgian port hinterlands offers white-space entry for regional specialists with guaranteed capacity models. Target India's pharmaceutical cold chain outside Mumbai and Hyderabad clusters, where CDSCO temperature compliance mandates remain underpenetrated by organized 3PLs. Lead with blockchain-IoT custody platforms enabling insurance premium reductions for high-value electronics shippers.
For Investors and Strategic Acquirers: The window for entry favors asset-light platform orchestrators with vertical specialization in perishables or hazardous materials handling. Long-term viability centers on providers integrating warehouse automation with predictive inventory positioning capabilities. Monitor quarterly carbon performance review adoption among German and Dutch pharmaceutical shippers as the inflection signal for contract renewal term renegotiation.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Accounting Certification | EU Green Deal scope-three reporting mandates documentation across subcontractor fleets for shipper qualification. |
| Autonomous Mobile Robot Deployment | Grocery and apparel retailers with SKU proliferation above 50,000 units achieve 40% faster payback than conveyor investments. |
| Hazmat Qualification Investment | UN 38.3 dangerous goods certification filters generalist carriers from lithium-ion battery transport volume. |
| Dedicated Fleet Arrangements | Consumer electronics manufacturers trade rate competitiveness for allocation certainty during peak seasons. |
| Blockchain-IoT Platform Integration | Immutable custody records for high-value electronics enable insurance premium reductions offsetting deployment costs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with logistics procurement directors, warehouse operations managers, fleet dispatch coordinators, and pharmaceutical supply chain leads. EIA fuel price benchmarks, EU ETS carbon market data, and FDA food safety modernization filings provided demand-side validation. Bottom-up facility capacity assessments and top-down trade flow analysis were triangulated against carrier financial disclosures.
Data-stream reconciliation across transportation management system deployments, warehouse automation investments, and contract renewal timelines informed the analytical framework. Segmentation dimensions modeled include service type, client vertical, technology integration depth, and delivery model commitment structure. CAGRs were derived from volume throughput projections and value-based pricing evolution across the projection horizon. Forecast inputs incorporated EU CSRD implementation timelines and pharmaceutical cold chain regulatory expansion patterns.
Inputs from carrier financial disclosures and trade association surveys were available through the study window; gaps in real-time telematics penetration data introduce uncertainty bands around visibility-driven pricing premium estimates. Forecasts reflect documented assumptions regarding diesel price volatility and port labor action frequency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Bird Carriers Market
Transportation Services
Ride-Hailing Service Market
Transportation Services
On Street Vehicle Parking Meter Market
Transportation Services
Indonesia Car Rental Market
Transportation Services
Germany Car Rental Market
Transportation Services
Airport Handling Service Market
Transportation Services
Taxi and Ride-Hailing Services Market
Transportation Services
Driving Vacation Market
Transportation Services
Cross Docking Services Market
Transportation Services
Global Garbage Truck Market
Transportation Services
Peer-To-Peer (P2P) Car-Sharing Market
Transportation Services
India Two-Wheelers Rental Market
Transportation Services
Bulk Transportation Services Market
Transportation Services
Waste Collection Vehicle Market
Transportation Services
Vietnam Taxi Market
Transportation Services
Global White Glove Service in Delivery Market