
 GCC Dangerous Goods Logistics Market | 2026-2036
GCC Dangerous Goods Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Dangerous Goods Logistics Market Foresight
Buyer concentration among GCC petrochemical producers is pivoting toward integrated energy conglomerates that now control the majority of hazardous cargo volumes. Deutsche Post DHL Group leverages its certified dangerous goods infrastructure across Dubai and Jeddah to serve these consolidated clients. Agility sustains specialized warehousing networks in Saudi Arabia's industrial cities. Kuehne + Nagel anchors temperature-controlled dangerous goods corridors linking European suppliers to Gulf chemical processors.
Dangerous goods logistics encompasses the specialized transportation, storage, and handling of substances classified under international hazard codes, requiring UN-certified packaging, segregated containment, and trained personnel compliance with thermal stability thresholds and pressure relief specifications. Flammable liquids dominate maritime shipping volumes through Gulf ports, while air cargo for radioactive materials and toxic substances commands premium pricing due to IATA operational restrictions. Road freight for corrosives and explosives maintains the broadest geographic coverage across the six GCC states, though rail transport infrastructure remains underdeveloped for bulk hazardous movement.
Saudi Arabia's General Authority of Civil Aviation enforces dangerous goods air transport rules aligned with ICAO Technical Instructions, while the UAE's National Emergency Crisis and Disaster Management Authority coordinates cross-emirate hazardous material incident response protocols. The Saudi Standards, Metrology and Quality Organization and the UAE's Civil Defense Directorate both mandate periodic facility audits that determine market access for logistics providers. Stakeholders must monitor how Saudi Arabia's dual carbon goals and industrial city expansion plans reshape hazardous cargo flow patterns between Jubail, Yanbu, and Ras Al-Khair.
Market Dynamics
Integrated energy conglomerates across Saudi Arabia and the UAE are consolidating hazardous cargo volumes under single-source logistics contracts, compressing supplier margins while demanding certified infrastructure investments that smaller providers cannot fund.
Growth Catalysts
- Petrochemical capacity expansion:Saudi Aramco's downstream integration at Ras Al-Khair and Jubail is generating sustained demand for flammable liquid transport and specialized warehousing.
- Saudi Building Code enforcement:Tightened chemical storage facility standards are forcing facility upgrades that favor certified logistics operators with compliant infrastructure.
- Radioactive material air corridors:Medical isotope imports for UAE and Saudi healthcare networks require IATA-certified handling that commands premium service tiers.
Market Restraints
- Specialized fleet scarcity:UN-certified tank containers and pressure-relief vehicles face 14-18 month procurement lead times from European manufacturers.
- Concentrated buyer power:SABIC and ADNOC subsidiaries now control over sixty percent of regional hazardous cargo volumes, squeezing third-party logistics pricing.
- Rail infrastructure gaps:Absence of dedicated bulk hazardous rail corridors between Jubail and Riyadh forces reliance on higher-cost road freight.
Strategic Opportunities
- Oman Sohar port development:Underutilized deep-water capacity outside Strait of Hormuz chokepoints offers alternative maritime routing for petrochemical exporters.
- Temperature-controlled biologics:Pharma cold chain convergence with dangerous goods certification creates service bundling potential for GCC vaccine distribution hubs.
- Kuwait's Al-Zour refinery complex:New petrochemical integration projects lack established logistics networks, presenting first-mover infrastructure partnerships.
Industry Challenges
- DGSA certification bottlenecks:Dangerous Goods Safety Advisor accreditation requires 18-month training cycles that outpace workforce expansion needs.
- Legacy warehouse retrofit costs:Converting conventional storage to Saudi Standards-compliant chemical facilities demands sprinkler system overhauls and blast-resistant partitioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Dangerous Goods Logistics Market |
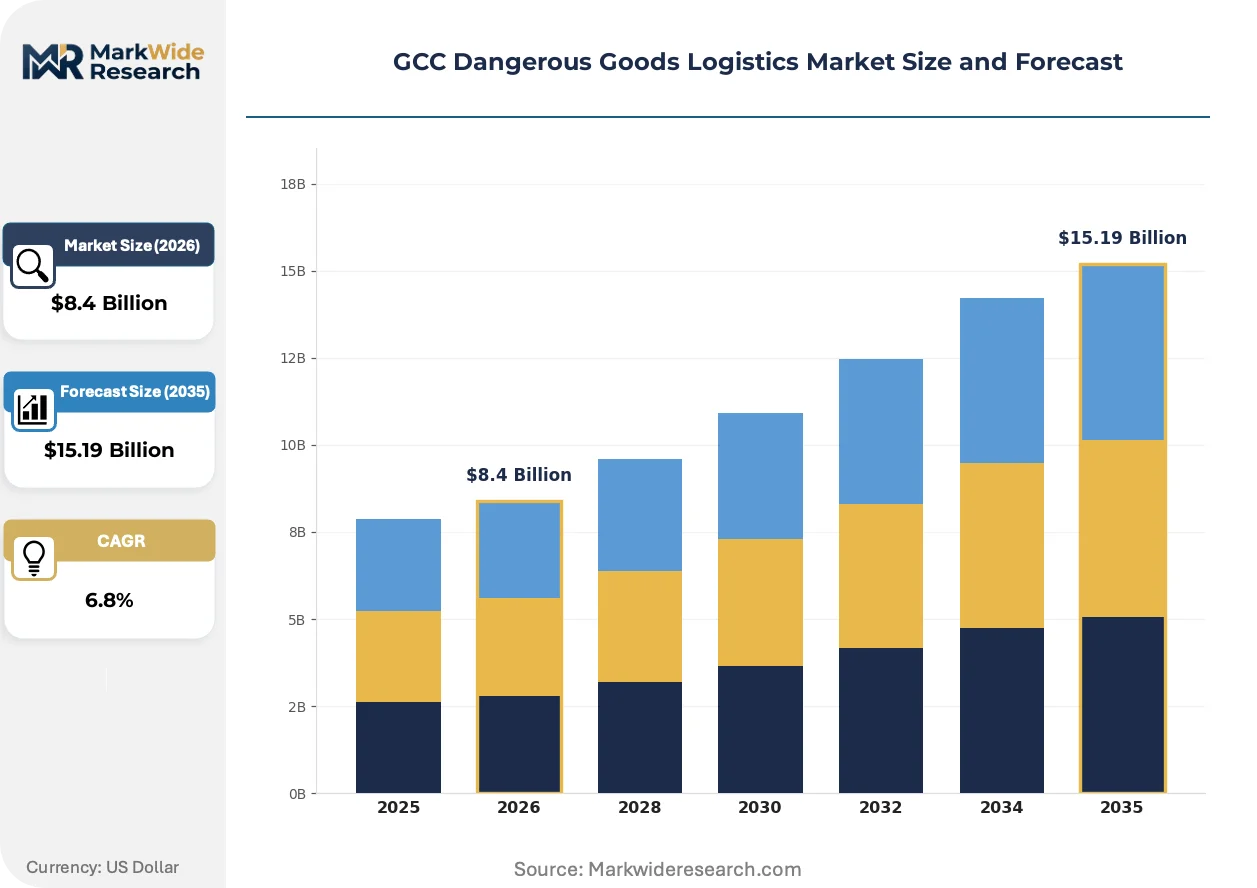
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Hazard Class: Explosives, Flammable Liquids, Toxic Substances, Corrosives, Radioactive Materials Transportation Mode: Road Freight, Air Cargo, Maritime Shipping, Rail Transport, Courier Services Packaging Type: Drums, Intermediate Bulk Containers, Freight Containers, Cylinders, Carboys Client Type: Manufacturers, Distributors, Chemical Traders, Construction Firms, Energy Producers |
| Companies Covered | Al Futtaim Logistics, Deutsche Post DHL Group, Agility, DSV, Kuehne + Nagel, BDP International, TALKE Group, DB Schenker, Petrochem, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Dangerous Goods Logistics Market Shifts & Advancements
Real-time cargo monitoring systems and predictive risk analytics are displacing manual compliance checks across GCC dangerous goods corridors. These tools compress incident response times while generating audit trails that satisfy tightening regulatory documentation requirements.
Telematics integration with thermal sensors and pressure transmitters is rewriting how flammable liquid shipments are monitored during Gulf transits. Petrochemical producers in Jubail Industrial City are mandating these systems for all third-party carriers. The technology is compressing insurance premiums and liability exposure for certified adopters.
Saudi Standards, Metrology and Quality Organization facility audit protocols now mandate digital documentation systems that interface with Civil Defense Directorate emergency response networks. Warehousing operators must upgrade to cloud-based inventory tracking that provides real-time hazardous material location data. Small and mid-sized logistics providers in Dammam and Jeddah are struggling to fund these compliance investments.
Buyer procurement teams at integrated energy conglomerates are consolidating dangerous goods contracts under multi-year framework agreements that bundle transport, storage, and regulatory compliance services. Spot-market spot purchases for hazardous cargo are declining across the Eastern Province industrial corridor. This consolidation is most visible among SABIC affiliates seeking single-accountability logistics partners.
GCC Dangerous Goods Logistics Market Segmentation
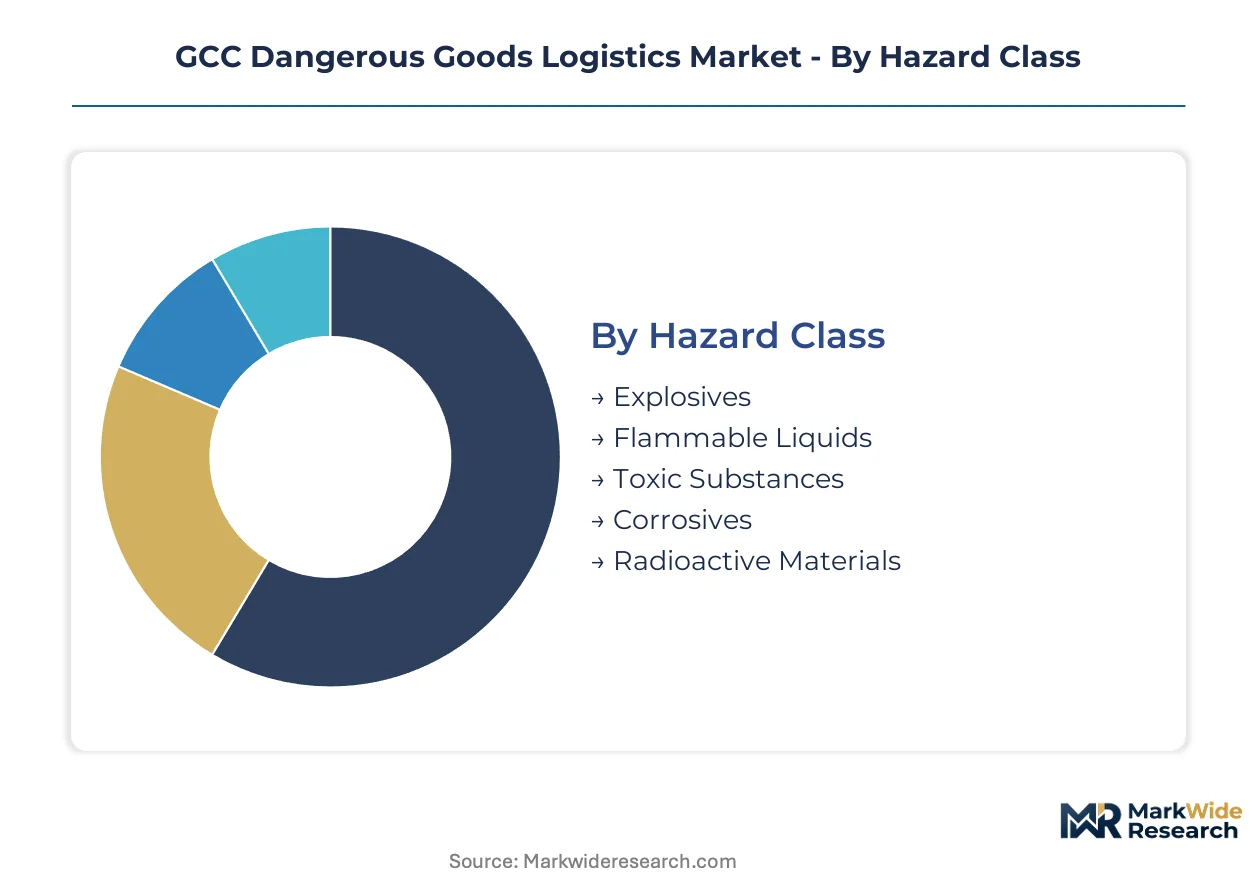
Dangerous goods logistics in the GCC demands precise segment alignment because each hazard class triggers distinct regulatory pathways and infrastructure investments. Transportation mode selection directly determines compliance costs and geographic reach across Saudi Arabia, the UAE, and neighboring states. Client type concentration shapes contract structures, with integrated energy conglomerates now dictating multi-year framework terms that bundle handling, storage, and regulatory documentation.
Hazard Class:
Capital intensity varies sharply across hazard classifications, with radioactive materials and explosives requiring specialized containment infrastructure that smaller logistics providers cannot finance.
- Explosives:UN-certified blast-resistant warehousing and segregated transport corridors dominate compliance architecture. Demand clusters around Saudi Aramco's drilling operations in the Empty Quarter and ADNOC's offshore development sites, where seismic charges and perforating guns require military-grade security protocols.
- Flammable Liquids:Petroleum derivatives and petrochemical feedstocks constitute the highest volume category, moving through Jubail and Yanbu industrial corridors in temperature-controlled tank containers. Saudi Building Code enforcement on chemical storage facilities is tightening segregation requirements for gasoline, diesel, and naphtha inventories.
- Toxic Substances:Industrial solvents and agricultural chemicals require activated carbon filtration systems and personnel protective equipment certification.
- Corrosives:Sulfuric acid and caustic soda shipments demand lined tank containers and spill containment infrastructure at loading facilities.
- Radioactive Materials:Medical isotopes for UAE and Saudi healthcare networks command premium pricing due to IATA-certified handling requirements and limited carrier accreditation.
Flammable liquids absorb the bulk of installed capacity; radioactive materials are expanding most quickly.
Transportation Mode:
Modal selection in the GCC reflects infrastructure maturity gaps, with road freight offering universal coverage while rail and specialized air corridors remain concentrated around specific industrial nodes.
- Road Freight:UN-certified tankers and pressure-relief vehicles provide door-to-door coverage across all six GCC states, though 14-18 month procurement lead times from European manufacturers constrain fleet expansion. The Eastern Province industrial corridor around Dammam, Jubail, and Ras Al-Khair generates the densest hazardous cargo road density.
- Maritime Shipping:Bulk liquid chemical carriers and containerized dangerous goods move through Jebel Ali, King Abdulaziz Port, and Sohar, with flammable liquids dominating petrochemical export volumes.
- Air Cargo:Radioactive medical isotopes and time-critical toxic substances utilize Dubai and Jeddah's IATA-certified handling facilities.
- Rail Transport:Absence of dedicated bulk hazardous corridors between Jubail and Riyadh limits adoption to non-hazardous commodities.
- Courier Services:Small-package dangerous goods for laboratory samples and maintenance chemicals utilize specialized last-mile networks.
Road freight commands the widest operational footprint; maritime shipping handles the greatest tonnage volumes.
Packaging Type:
Packaging specifications directly determine insurance premiums and regulatory audit outcomes, with UN-certified intermediate bulk containers and freight containers requiring substantial upfront certification investment.
- Intermediate Bulk Containers:Stainless steel and composite IBCs with pressure-relief valves dominate liquid chemical handling in Jubail Industrial City. Saudi Standards, Metrology and Quality Organization audits now mandate digital tracking integration for reusable IBC fleets.
- Freight Containers:Modified ISO containers with thermal insulation and ventilation systems enable multimodal hazardous cargo movement between European suppliers and Gulf chemical processors.
- Drums:Steel and polyethylene drums remain the default for smaller batch chemical shipments and lubricant distribution.
- Cylinders:Pressurized gas containment for industrial and medical gases requires periodic hydrostatic testing certification.
- Carboys:Glass and plastic carboys handle laboratory-scale chemical movements with limited commercial volume.
Intermediate bulk containers represent the primary reusable asset class; freight containers enable the most complex multimodal routing.
Client Type:
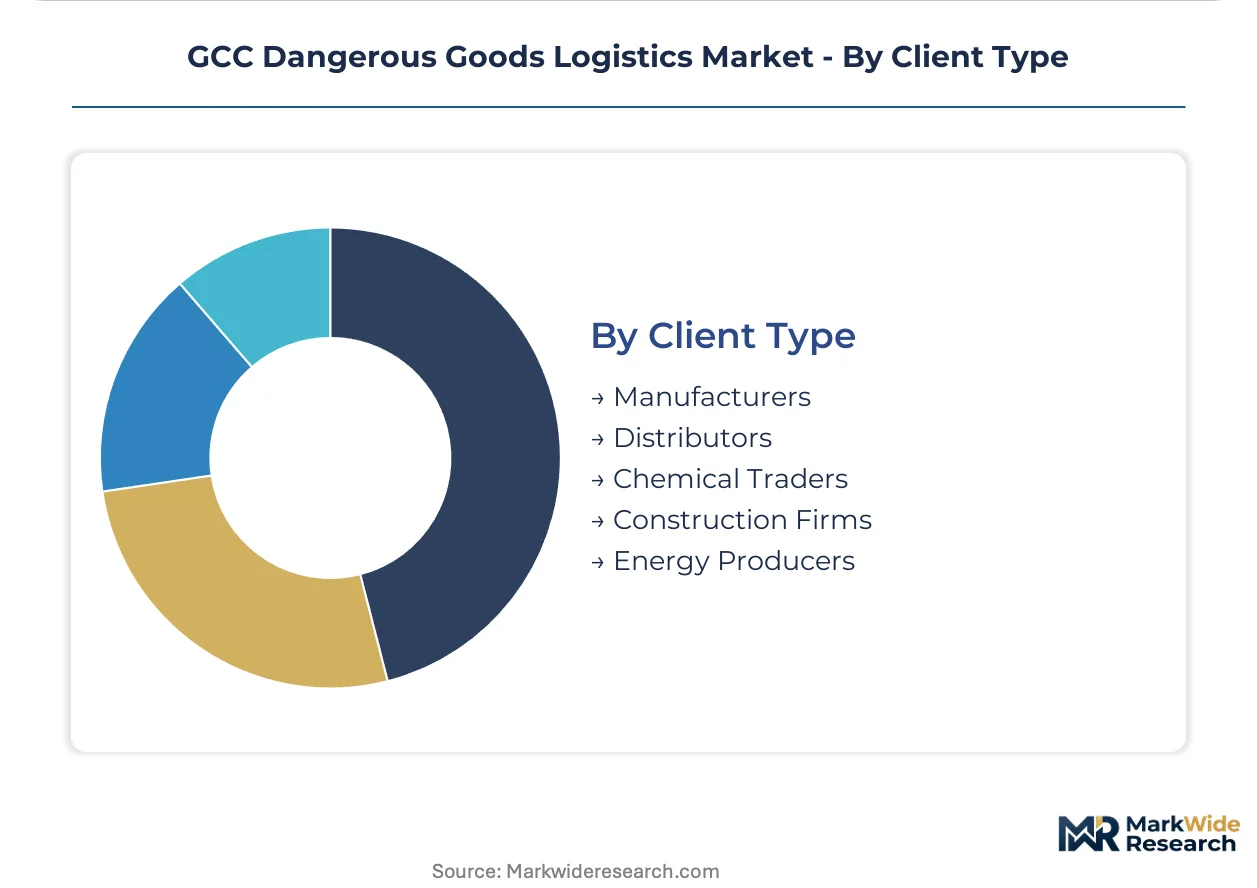
Customer concentration among GCC dangerous goods logistics users has shifted dramatically toward vertically integrated energy conglomerates that now internalize procurement decisions previously fragmented across multiple subsidiaries.
- Energy Producers:Saudi Aramco, ADNOC, and their downstream affiliates control over sixty percent of regional hazardous cargo volumes, consolidating previously separate logistics contracts under single-source framework agreements. These buyers mandate real-time cargo monitoring and predictive risk analytics as baseline vendor requirements.
- Manufacturers:SABIC affiliates and international chemical producers in Jubail and Yanbu generate sustained demand for flammable liquid transport and specialized warehousing with Saudi Building Code compliance.
- Distributors:Third-party chemical traders face margin compression as direct manufacturer-to-user contracts bypass traditional wholesale channels.
- Chemical Traders:Spot-market participants are declining as procurement teams favor multi-year bundled service agreements.
- Construction Firms:Explosives and corrosive materials for infrastructure projects represent seasonal, project-based demand with irregular volume patterns.
Energy producers command the largest contract values; manufacturers are consolidating their supplier bases most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Crude oil reserves concentrated in Saudi Arabia's Eastern Province and the UAE's Zakum field anchor hazardous cargo flows across the GCC. Petrochemical integration projects at Ras Al-Khair, Jubail, and Ruwais generate the bulk of flammable liquid transport demand. Regulatory divergence between Saudi Standards, Metrology and Quality Organization mandates and UAE Civil Defense protocols shapes compliance investments.
Saudi Arabia
Saudi Aramco's downstream expansion at Ras Al-Khair and Jubail drives sustained demand for UN-certified tank containers and pressure-relief vehicles. The Saudi Building Code enforcement tightens chemical storage standards, forcing warehouse retrofits with blast-resistant partitioning. The Eastern Province industrial corridor around Dammam, Jubail, and Yanbu concentrates over sixty percent of national hazardous cargo volumes.
United Arab Emirates
ADNOC's integrated logistics requirements and Dubai's pharmaceutical cold chain expansion sustain demand for temperature-controlled dangerous goods handling. The National Emergency Crisis and Disaster Management Authority coordinates cross-emirate incident response protocols that mandate real-time cargo tracking. Jebel Ali and Khalifa Port anchor maritime shipping for petrochemical exports and medical isotope imports.
Kuwait
The Al-Zour refinery complex and associated petrochemical integration projects lack established logistics networks, creating infrastructure partnership opportunities. The country's national petroleum regulator enforces hazardous material handling standards aligned with Gulf Cooperation Council harmonization efforts. Kuwait City and Al-Ahmadi industrial zones concentrate construction chemicals and drilling explosives demand.
Oman
Sohar Port's underutilized deep-water capacity outside Strait of Hormuz chokepoints offers alternative maritime routing for regional petrochemical exporters. The Special Economic Zone Authority at Duqm attracts bulk liquid chemical storage investments with streamlined customs procedures. The Sohar industrial port zone and Salalah free zone cluster flammable liquid warehousing and transshipment operations.
Qatar
Ras Laffan Industrial City's LNG and helium production sustains specialized cryogenic transport and pressurized gas cylinder logistics. The national civil defense administration mandates DGSA-certified personnel for all hazardous cargo handling facilities. Mesaieed Industrial City and Doha's Hamad International Airport corridor concentrate medical isotope air freight and industrial chemical distribution.
GCC Dangerous Goods Logistics Market Competitive Landscape
Established logistics providers occupy the standard tier; emerging regional specialists pursue certified infrastructure niches that multinational networks cannot serve profitably. Buyer consolidation among integrated energy conglomerates compresses margins while demanding multi-year bundled service agreements. Three archetypes dominate: global freight forwarders with dangerous goods certification, regional warehouse operators with Saudi Standards compliance, and petrochemical-captive logistics arms. Competitive positioning hinges on M&A-driven geographic expansion and strategic partnerships for temperature-controlled corridor development.
Among global freight forwarders, Deutsche Post DHL Group and Kuehne + Nagel exemplify the certified infrastructure archetype with established Gulf operations. Agility occupies a position representing regional warehouse specialization with industrial city networks. These three anchors illustrate how compliance certification and geographic footprint determine contract access as procurement teams consolidate vendor bases.
| Leading Market Players |
|---|
| Al Futtaim Logistics |
| Deutsche Post DHL Group |
| Agility |
| DSV |
| Kuehne + Nagel |
| BDP International |
| TALKE Group |
| DB Schenker |
| Petrochem |
| Others |
Supply & Pricing Matrix
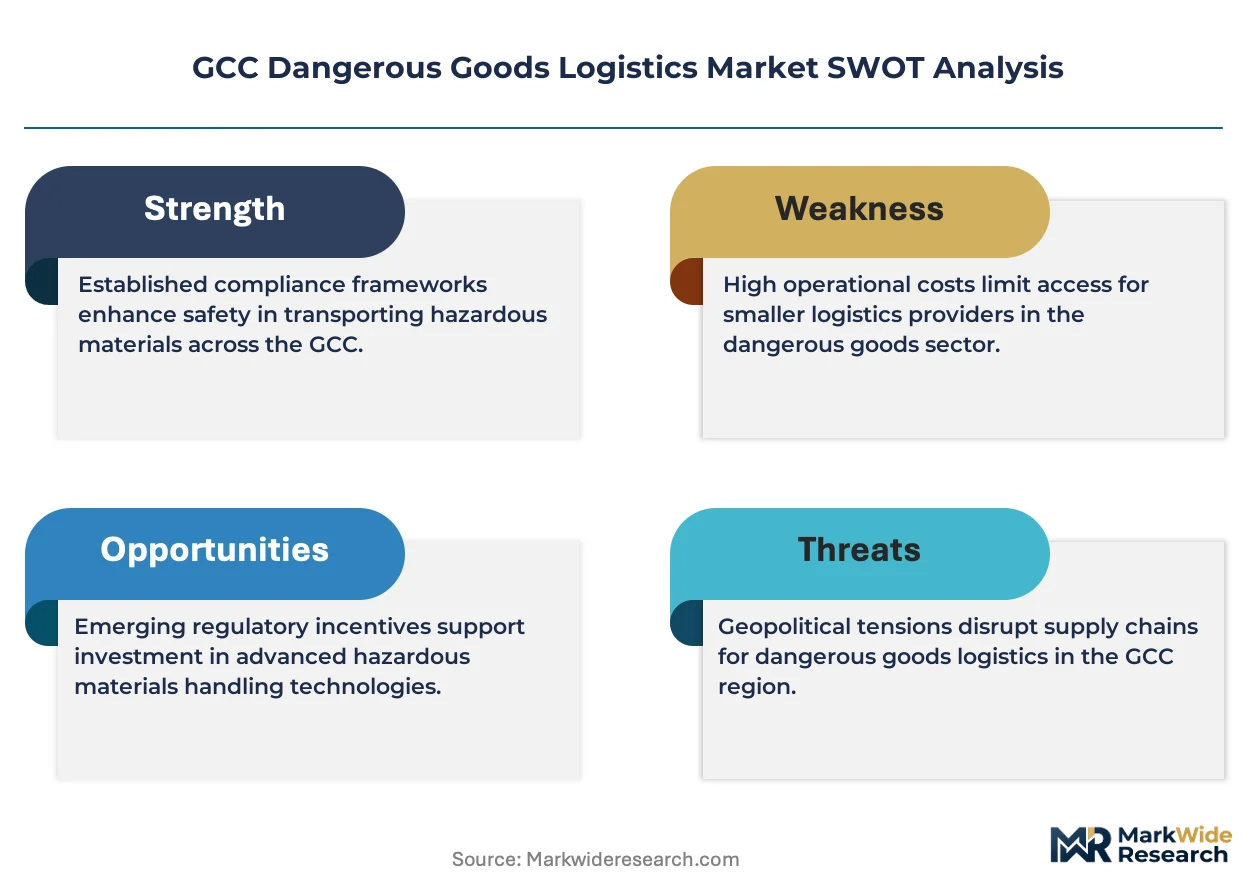
Sovereign-backed petrochemical producers across Saudi Arabia and the UAE now dictate supply terms through consolidated procurement frameworks, compressing third-party logistics margins while enforcing capital-intensive compliance investments that reshape pricing discipline across the Eastern Province industrial corridor.
Pricing Analysis
High-volume flammable liquid transport absorbs thin margins while radioactive material air cargo and temperature-controlled biologics command substantial premiums. Price differentiation hinges on IATA certification tier and real-time cargo monitoring integration, with uncertified operators facing exclusion from SABIC and ADNOC framework agreements. Cost compression in standard hazardous road freight is intensifying because integrated energy conglomerates bundle multi-year contracts that eliminate spot-market premiums. Chemical traders and construction firms exhibit acute price sensitivity; medical isotope distributors and downstream petrochemical processors demonstrate inelastic demand for certified handling.
Supply Chain Analysis
Regional distribution centers in Jubail, Yanbu, and Jebel Ali anchor hub-and-spoke patterns for hazardous cargo consolidation. Geographic supply concentration centers on Saudi Arabia, the UAE, and Germany for UN-certified tank containers and pressure-relief vehicles. Raw material dependencies include European-manufactured stainless steel IBCs, German thermal sensor systems, and Singaporean maritime routing infrastructure. Single-source vulnerability to DGSA-certified personnel shortages threatens operational continuity. Distribution runs through multimodal corridors linking European suppliers to Gulf chemical processors via Jebel Ali and Sohar transshipment nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC dangerous goods logistics market functions as a cost-of-compliance story where Saudi Building Code enforcement and Saudi Standards, Metrology and Quality Organization audit protocols erect formidable barrier-to-entry moats favoring operators with certified infrastructure investments.
For Market Incumbents: Hedge against buyer consolidation by securing exclusive warehousing partnerships in Ras Al-Khair and Al-Zour before competitor facility upgrades reach compliance. Anchor long-term contracts with DGSA-certified personnel pipelines to neutralize accreditation bottlenecks threatening operational scale. Diversify revenue streams into temperature-controlled biologics corridors linking Dubai pharmaceutical hubs to Saudi healthcare networks. For New Entrants and Emerging Players: Predictive risk analytics platforms offer technology-first wedge opportunities where legacy operators lack digital documentation integration with Civil Defense Directorate emergency response networks. Target Kuwait's Al-Zour refinery complex and Oman's Duqm Special Economic Zone as white-space geographies lacking established logistics networks. Pursue first-mover infrastructure partnerships with national petroleum regulators seeking compliant warehousing capacity. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-sized Saudi warehouse operators in Dammam and Jeddah struggling to fund Saudi Building Code retrofit requirements. Five-to-ten-year viability hinges on regulatory compliance moats widening rather than harmonization reducing certification burdens. Monitor DGSA training pipeline expansion rates as the critical inflection signal for workforce-constrained market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Fleet Ownership | Captive UN-certified tank container capacity secures SABIC framework contract eligibility against procurement lead time constraints. |
| Real-Time Cargo Monitoring Platform Deployment | Telematics integration with Saudi Standards, Metrology and Quality Organization audit protocols compresses insurance premiums for Jubail Industrial City carriers. |
| Temperature-Controlled Biologics Corridor Development | Pharma cold chain convergence with dangerous goods certification captures UAE and Saudi vaccine distribution hub demand. |
| DGSA Certification Pipeline Partnership | Exclusive training agreements with Saudi technical institutes neutralize eighteen-month accreditation bottlenecks threatening workforce expansion. |
| Oman Sohar Port Infrastructure Alliance | Deep-water capacity outside Strait of Hormuz chokepoints offers alternative maritime routing for regional petrochemical exporters. |
Research Methodology
Document review covered customs and trade data, SEC filings from listed logistics providers, Saudi Standards, Metrology and Quality Organization regulatory bulletins, and IATA dangerous goods handling guidelines, complemented by interviews with hazardous cargo operations managers, petrochemical procurement leads at SABIC affiliates, DGSA-certified safety advisors, and Civil Defense Directorate compliance officers. Secondary validation drew from Saudi Building Code technical provisions, UAE National Emergency Crisis and Disaster Management Authority protocols, and GCC harmonization framework documents. Bottom-up facility capacity assessments and top-down petrochemical throughput projections were triangulated against carrier fleet deployment records.
Historical volume trajectories were cross-referenced against panel input from logistics procurement executives to anchor projection assumptions across the analysis window. Segmentation modeling incorporated hazard class, transportation mode, packaging type, and client concentration tier. CAGRs were derived from petrochemical capacity expansion schedules, regulatory enforcement intensity indices, and certified infrastructure investment pipelines. Forecast inputs included Saudi Aramco downstream integration timelines and ADNOC logistics consolidation patterns.
Several conditions sit outside the modeled scope, including unannounced regulatory harmonization initiatives, sovereign wealth fund logistics sector acquisitions, and catastrophic hazardous material incidents triggering emergency moratoriums. Forecasts reflect documented assumptions regarding certification training cycle durations and European equipment procurement lead times. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
India Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Bangladesh Freight and Logistics Market
Logistics and Shipping
United Kingdom Contract Logistics Market
Logistics and Shipping
Italy Apparel Logistics Market
Logistics and Shipping
Freight Management System Market
Logistics and Shipping
China Digital Freight Forwarding Market
Logistics and Shipping
Vehicle Routing and Scheduling Market
Logistics and Shipping
Europe Courier Market
Logistics and Shipping
Asia Pacific Domestic Courier Market
Logistics and Shipping
United Arab Emirates Freight and Logistics Market
Logistics and Shipping
Digital Freight Management Market
Logistics and Shipping
Central and Eastern Europe Cold Chain Logistics Market
Logistics and Shipping
GCC Contract Logistics Market
Logistics and Shipping
Australia Freight Forwarding Market
Logistics and Shipping
Global Connected Logistics Market
Logistics and Shipping
Germany Domestic Courier, Express, and Parcel (CEP) Market