
 Egypt Third Party Logistics (3PL) Market | 2026-2036
Egypt Third Party Logistics (3PL) Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Third Party Logistics (3PL) Market Insights
Last-mile delivery networks in the Nile Delta corridor is narrowing as e-commerce penetration forces consolidation among fulfillment operators. DHL Group leverages its bonded warehouse infrastructure around Cairo International Airport to capture pharmaceutical and electronics flows. Aramex sustains competitive density through dedicated cross-border parcel lanes into Upper Egypt and Sinai. DB Schenker anchors industrial project logistics tied to Suez Canal Economic Zone manufacturing clusters.
Third Party Logistics denotes outsourced supply chain management where providers assume transportation, warehousing, inventory management, and freight forwarding functions under contractual arrangements, typically measured by cost-per-unit-shipped and order-cycle-time performance metrics. The primary commercial purpose centers on converting fixed logistics assets into variable costs while injecting specialized technology and network scale unavailable to individual shippers. Warehousing commands the dominant margin pool as ambient and cold-storage facilities around Alexandria and Damietta ports reach utilization thresholds, while automated warehousing and IoT tracking represent the fastest-expanding technology segments as real-time visibility becomes a non-negotiable buyer requirement. Road freight retains volume leadership across domestic distribution, though sea-air multimodal combinations gain share for consumer electronics imports routed through East Port Said.
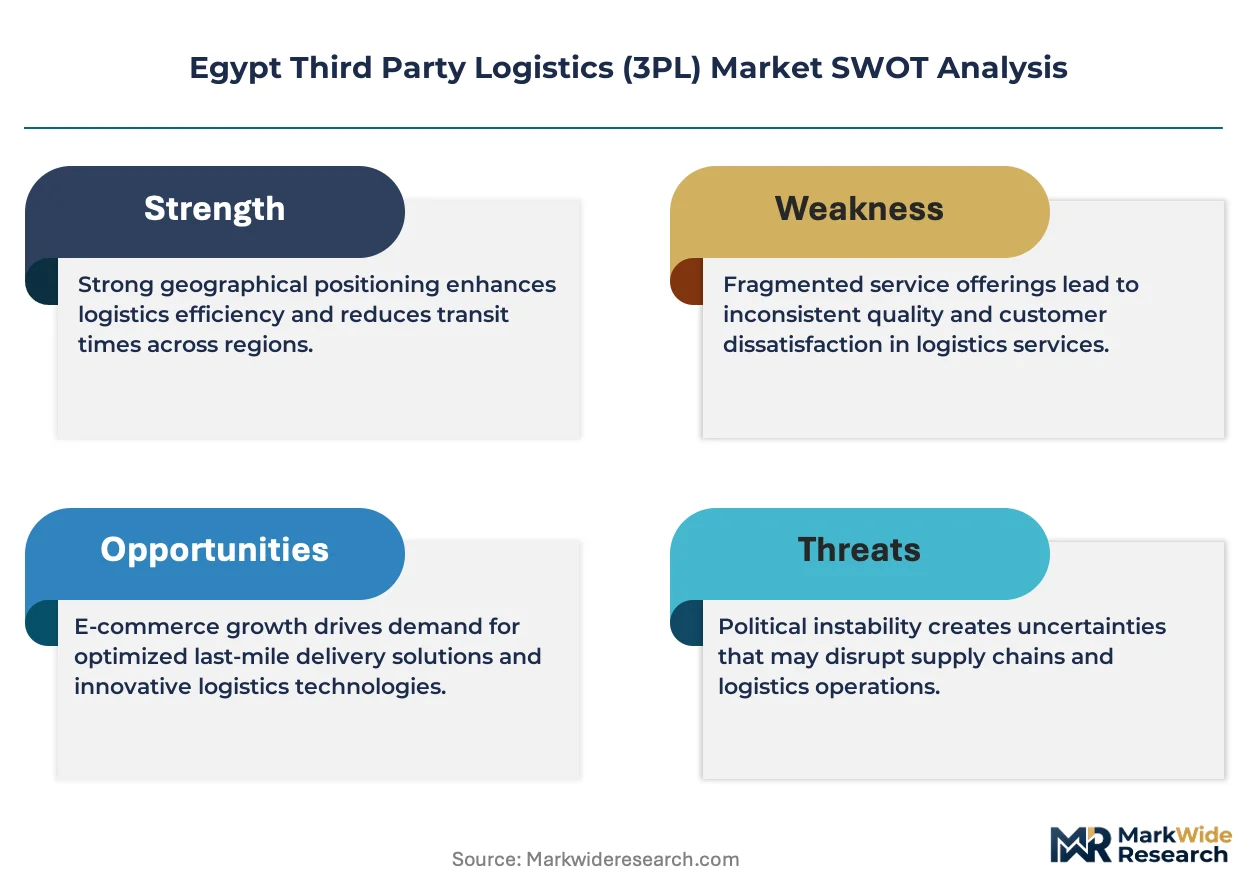
Egypt's General Authority for Investment and Free Zones governs bonded warehouse licensing and special economic zone logistics incentives, while the Ministry of Transportation oversees commercial vehicle weight limits and intermodal terminal standards that directly shape fleet investment cycles. The Egyptian Customs Authority implements the national single-window platform, forcing 3PL operators to integrate declaration automation or lose port clearance contracts. Stakeholders must monitor how Suez Canal tariff adjustments and domestic fuel subsidy rationalization reshape route economics between Red Sea and Mediterranean corridors.
Market Dynamics
Customs modernization protocols from Egypt's General Authority for Investment and Free Zones are compressing clearance timelines and forcing 3PL operators to automate declaration workflows or surrender port contracts to bonded warehouse specialists.
Growth Catalysts
- Pharmaceutical cold chain expansion:Temperature-sensitive biologics distribution is pulling specialized warehousing investment toward Cairo-Alexandria corridors where port-linked cold storage clusters are forming.
- Egypt Customs Authority single-window mandate:Digital declaration integration requirements are filtering out non-technical operators and concentrating contract awards among platform-capable providers.
- Dry port development at 6th of October City:Inland container depot expansion is shifting freight consolidation patterns away from congested Mediterranean port gates toward desert logistics parks.
Market Restraints
- Diesel price subsidy volatility:Fleet operators face margin compression from unpredictable fuel cost adjustments that the Ministry of Petroleum implements without forward notice periods.
- Chassis pool concentration at Alexandria:Container equipment shortages at Egypt's primary import gateway create bottlenecks during peak agricultural export windows.
- Weight limit enforcement variance:Inconsistent axle load policing across governorates forces fleet spec diversity that raises capital intensity per tractor unit.
Strategic Opportunities
- Upper Egypt cross-border corridors:Underdeveloped logistics infrastructure in Sohag-Aswan axis offers first-mover positioning for providers establishing Sudan and Libya transit lanes.
- Suez Canal Economic Zone manufacturing:Industrial project logistics contracts tied to Chinese and European anchor tenants are expanding specialized heavy-lift and oversized cargo capabilities.
- Warehouse Management System convergence:Integration of IoT sensor networks with Egyptian Customs Authority data feeds is creating predictive clearance services that command premium pricing.
Industry Challenges
- Licensed customs broker scarcity:Egypt Customs Authority certification requirements are outpacing training program throughput, constraining operator scaling.
- Intermodal terminal standardization gaps:Incompatible container handling specifications between Nile barge feeders and Mediterranean port cranes force manual transloading.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Third Party Logistics (3PL) Market |
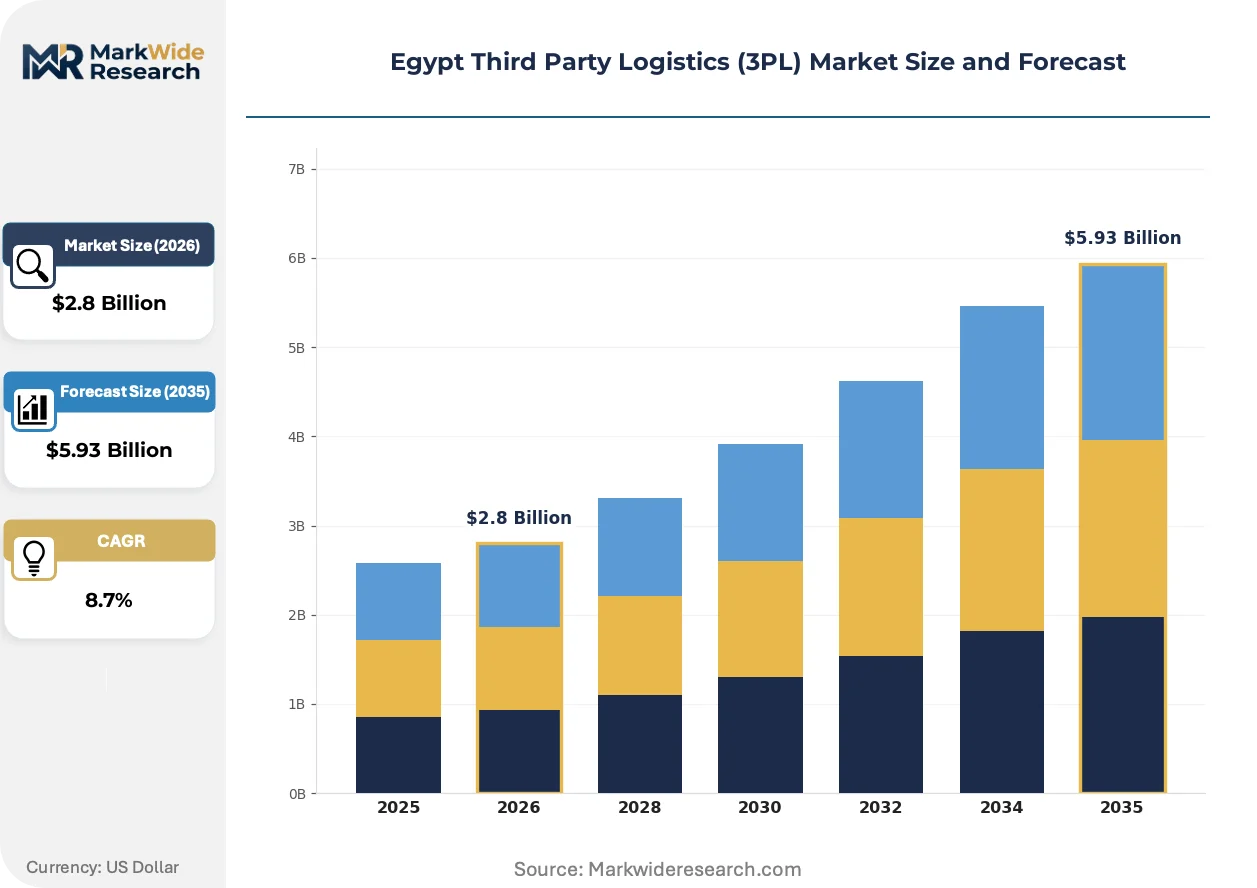
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Warehousing, Transportation, Freight Forwarding, Distribution End User: Retail, E-Commerce, Automotive, Consumer Electronics Technology: Automated Warehousing, IoT Tracking, Blockchain, TMS Delivery Mode: Road, Rail, Air, Sea |
| Companies Covered | Kuehne + Nagel, DHL Group, DSV, FedEx, Aramex, DB Schenker, DP World, Expeditors International, UPS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Third Party Logistics (3PL) Market Trends and Innovations
Real-time visibility infrastructure is becoming the baseline competitive threshold as pharmaceutical and electronics shippers reject providers lacking IoT-enabled inventory tracking across bonded and ambient storage networks.
Automated guided vehicle systems deployed in Cairo International Airport free zones are collapsing labor cost structures for high-velocity pharmaceutical handling. Egyptian pharmaceutical distributors are adopting these systems within eighteen-month replacement cycles. The technology is collapsing the traditional three-shift staffing model into single-shift supervision with machine tending.
Egypt's General Authority for Investment and Free Zones revised bonded warehouse licensing rules now mandate electronic inventory reconciliation with customs databases. Operators without API connectivity face license non-renewal. Pharmaceutical and electronics verticals are responding by consolidating contracts among providers with pre-integrated compliance architectures.
Shippers are unbundling transportation from warehousing contracts and awarding these functions to separate specialists. Pharmaceutical manufacturers are leading this disaggregation, retaining direct relationships with cold storage operators while sourcing line-haul from dedicated fleet providers. The Nile Delta corridor exhibits the most advanced contract fragmentation, with some shippers managing four distinct logistics service relationships.
Egypt Third Party Logistics (3PL) Market Segmentation
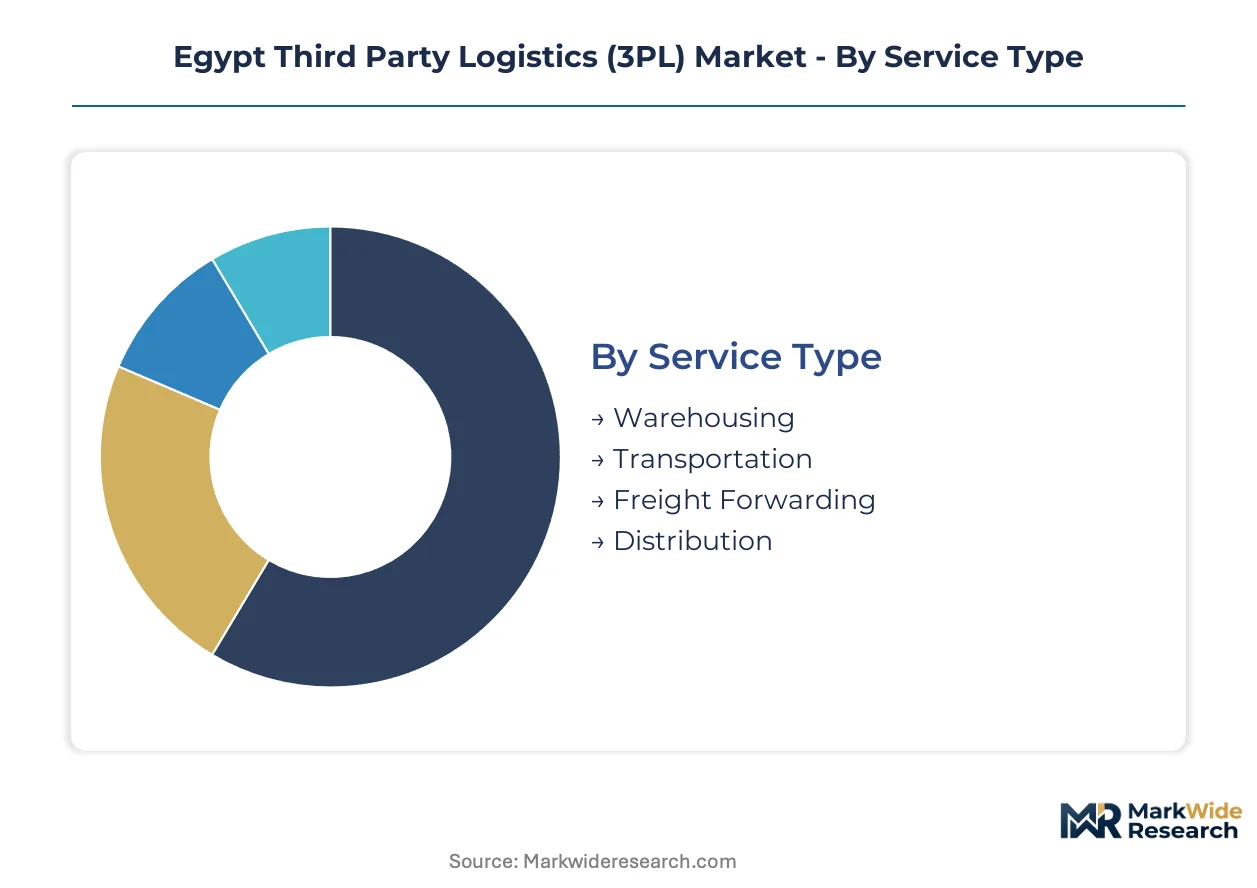
Service configuration across Egypt's 3PL landscape reflects divergent margin profiles and capital intensity requirements. Shippers segment providers based on bonded warehouse licensing, cold chain certification, and customs integration capabilities rather than generic transportation assets.
Service Type:
Shippers select service bundles based on inventory velocity requirements and regulatory complexity, with bonded storage and temperature control commanding premium positioning.
- Warehousing:Ambient and cold-storage facilities around Alexandria and Damietta ports operate at utilization thresholds. Pharmaceutical distributors consolidate contracts with providers holding Egyptian Customs Authority API integration for electronic inventory reconciliation.
- Transportation:Road freight dominates domestic distribution volumes while diesel subsidy volatility from the Ministry of Petroleum compresses fleet operator margins. Line-haul specialists face unpredictable fuel cost adjustments without forward notice periods.
- Freight Forwarding:Sea-air multimodal combinations gain share for consumer electronics imports routed through East Port Said.
- Distribution:Last-mile networks in the Nile Delta corridor narrow as e-commerce penetration forces fulfillment operator consolidation.
Established volume favors warehousing; emerging adoption favors freight forwarding multimodal solutions.
End User:
Vertical specialization determines provider selection criteria, with temperature sensitivity and customs complexity creating divergent service requirements.
- Retail:Cairo-Alexandria corridor concentration drives demand for high-velocity ambient storage with rapid inventory turnover capabilities.
- E-Commerce:Last-mile density requirements in the Nile Delta reshape fulfillment operator competitive dynamics.
- Automotive:Industrial project logistics tied to Suez Canal Economic Zone manufacturing clusters expand specialized heavy-lift and oversized cargo capabilities.
- Consumer Electronics:Real-time visibility infrastructure serves as baseline competitive threshold as shippers reject providers lacking IoT-enabled inventory tracking across bonded networks.
Contract concentration clusters around consumer electronics; margin expansion favors automotive project logistics.
Technology:
Technology adoption separates platform-capable providers from operators facing license non-renewal under revised bonded warehouse rules.
- Automated Warehousing:Automated guided vehicle systems deployed in Cairo International Airport free zones collapse labor cost structures for high-velocity pharmaceutical handling. Egyptian distributors adopt these systems within compressed replacement cycles.
- IoT Tracking:Real-time visibility infrastructure becomes non-negotiable buyer requirement across pharmaceutical and electronics verticals. Sensor network integration with Egyptian Customs Authority data feeds creates predictive clearance services commanding premium pricing.
- Blockchain:Supply chain transparency applications remain exploratory with limited commercial deployment.
- TMS:Transportation management systems optimize fleet routing amid weight limit enforcement variance across governorates.
IoT tracking anchors current investment; automated warehousing delivers the steepest expansion trajectory.
Delivery Mode:
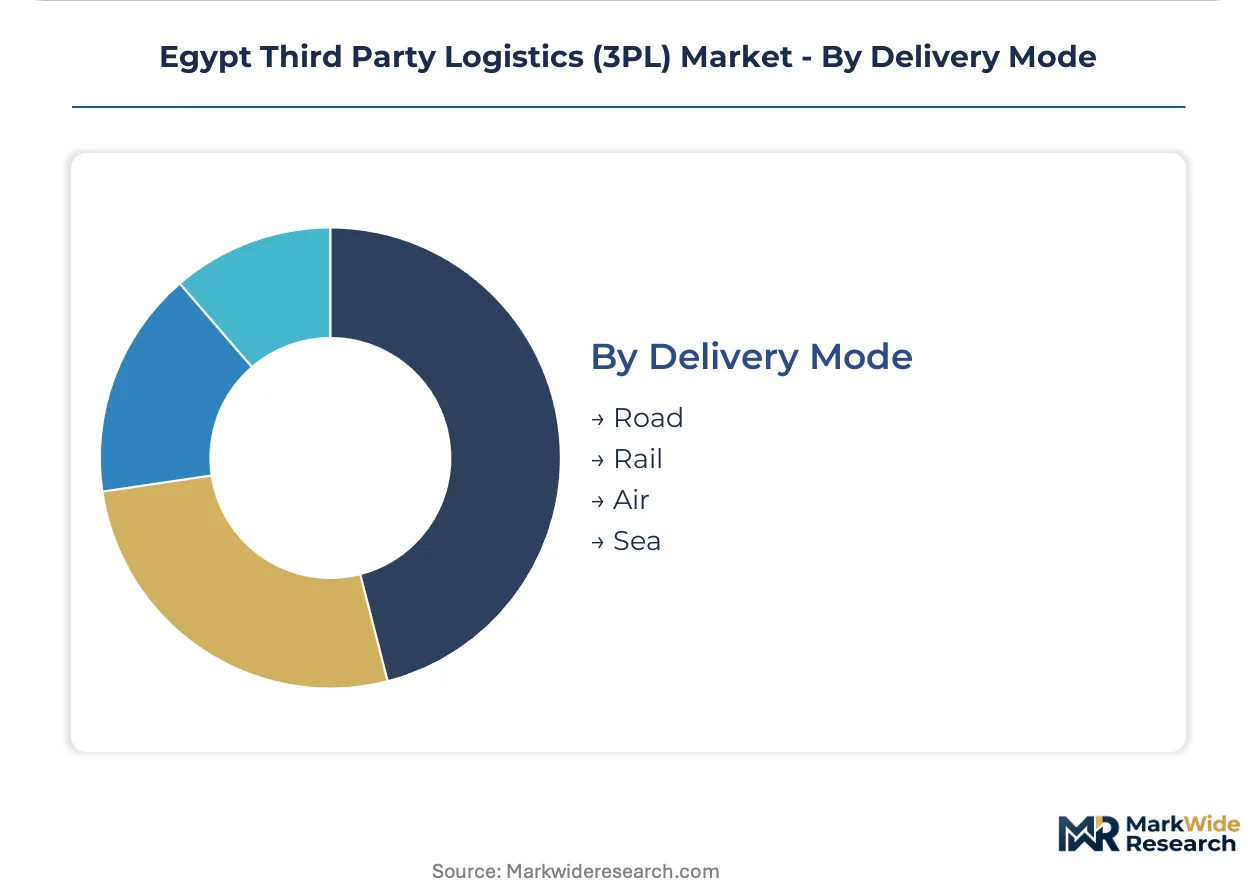
Modal selection reflects route economics between Red Sea and Mediterranean corridors shaped by Suez Canal tariff adjustments.
- Road:Volume leadership across domestic distribution persists despite chassis pool concentration at Alexandria creating bottlenecks during peak agricultural export windows.
- Rail:Intermodal terminal standardization gaps between Nile barge feeders and Mediterranean port cranes force manual transloading constraints.
- Air:Cairo International Airport bonded warehouse infrastructure captures pharmaceutical and electronics flows with expedited clearance protocols.
- Sea:Port modernization at Damietta and East Port Said reshapes freight consolidation patterns for import-heavy verticals.
Road retains volume dominance; air freight captures premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Cairo commands premium logistics pricing that Alexandria and Damietta corridors cannot replicate, creating a two-tier rate structure across Egypt's 3PL landscape. This asymmetry concentrates high-value pharmaceutical and electronics flows around Cairo International Airport while bulk freight accepts lower margins at Mediterranean port gateways.
Greater Cairo
Pharmaceutical cold chain demand and e-commerce fulfillment density drive warehousing investment toward 6th of October City dry port developments. Egypt's General Authority for Investment and Free Zones mandates electronic inventory reconciliation for bonded warehouse licensing. Cairo International Airport free zones host automated guided vehicle deployments that collapse labor costs for high-velocity handling.
Alexandria Governorate
Chassis pool concentration at Egypt's primary import gateway creates peak-season bottlenecks during agricultural export windows. The Egyptian Customs Authority single-window platform forces 3PL operators to integrate declaration automation or surrender port clearance contracts. Port-linked cold storage clusters around Damietta and Alexandria reach utilization thresholds as temperature-sensitive biologics distribution expands.
Suez Canal Economic Zone
Industrial project logistics contracts tied to Chinese and European manufacturing anchor tenants expand specialized heavy-lift capabilities. The Suez Canal Authority tariff adjustments reshape route economics between Red Sea and Mediterranean corridors. Manufacturing clusters at Ain Sokhna and East Port Said attract sea-air multimodal combinations for consumer electronics imports.
Nile Delta Corridor
Last-mile delivery networks narrow as e-commerce penetration forces consolidation among fulfillment operators. Ministry of Transportation weight limit enforcement variance across governorates raises fleet capital intensity. Mansoura and Tanta logistics parks emerge as secondary consolidation points for retail distribution.
Upper Egypt
Underdeveloped logistics infrastructure in the Sohag-Aswan axis offers first-mover positioning for Sudan and Libya transit lanes. Diesel price subsidy volatility from the Ministry of Petroleum compresses fleet operator margins without forward notice periods. Aswan dry port development remains stalled pending customs modernization protocol extensions.
Egypt Third Party Logistics (3PL) Market Competitive Landscape
Global integrators and regional specialists split the market along service complexity lines, with bonded warehouse licensing and customs integration capabilities determining contract awards. Three strategic archetypes dominate: international freight forwarders with Egyptian customs API integration, regional parcel specialists with cross-border density, and port-centric operators with bonded infrastructure. Competitive moves concentrate on customs technology partnerships and dry port capacity expansion rather than pure transportation asset accumulation.
Among global forwarders with Egyptian regulatory integration, Kuehne + Nagel and DHL Group exemplify the platform-capable tier that captures pharmaceutical and electronics flows through Cairo International Airport bonded warehouse infrastructure. DSV represents the consolidation-oriented archetype positioned to absorb customs-automated operators as the Egyptian Customs Authority single-window mandate filters out non-technical providers. Regional specialists including Aramex occupy positions in cross-border parcel density through dedicated lanes into Upper Egypt and Sinai.
| Leading Market Players |
|---|
| Kuehne + Nagel |
| DHL Group |
| DSV |
| FedEx |
| Aramex |
| DB Schenker |
| DP World |
| Expeditors International |
| UPS |
| Others |
Pricing and Supply Chain Analysis
Cairo-Alexandria logistics corridors concentrate bonded warehouse capacity and cold storage infrastructure, creating cost asymmetries that feed into three-tier pricing stratification across pharmaceutical, electronics, and retail verticals. Diesel subsidy volatility from Egypt's Ministry of Petroleum compresses fleet margins unpredictably, while customs integration capabilities determine which providers capture premium-configured contracts versus commodity line-haul rates.
Pricing Analysis
The customization-premium spread separates API-integrated bonded warehouse operators from standard transportation providers, with pharmaceutical cold chain contracts commanding substantial premiums over ambient retail distribution. Price differentiation hinges on Egyptian Customs Authority certification tier and real-time visibility infrastructure, with IoT-enabled inventory tracking becoming a threshold requirement for premium positioning. Cost compression in standard road freight intensifies as diesel price adjustments from the Ministry of Petroleum arrive without forward notice, eroding fleet operator margins. E-commerce fulfillment operators in the Nile Delta corridor exhibit highest price sensitivity, while pharmaceutical distributors prioritize compliance architecture over rate negotiation.
Supply Chain Analysis
Export-control regimes on semiconductor manufacturing equipment and pharmaceutical cold chain technology limit flows into Egyptian free zones, constraining automation deployment timelines. Supply concentration centers on China for consumer electronics components, Germany for automated material handling systems, and India for pharmaceutical APIs. Raw material dependencies span lithium-ion battery cells, temperature-controlled packaging materials, and chassis equipment for container handling. Single-source vulnerability runs through Alexandria port chassis pools, where equipment shortages during peak agricultural export windows create systemic bottlenecks. Distribution runs through Cairo International Airport bonded zones for high-value verticals, with Mediterranean port gateways handling bulk freight at compressed margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's 3PL sector sits at a platform-economics inflection where Egyptian Customs Authority API integration functions as the dominant interoperability layer, filtering contract awards toward pre-integrated providers and marginalizing operators lacking real-time data feeds.
For Market Incumbents: Entrench competitive position by deepening backward integration into Cairo International Airport bonded warehouse infrastructure and accelerating automated guided vehicle deployment across pharmaceutical handling operations. DHL Group and Kuehne + Nagel must defend against DSV's consolidation-oriented posture by securing exclusive customs technology partnerships before the single-window mandate fully filters non-technical operators. Capacity addition in 6th of October City dry port developments represents the critical geographic lever for margin defense. For New Entrants and Emerging Players: Upper Egypt's Sohag-Aswan corridor represents the most penetrable entry point, with underdeveloped logistics infrastructure offering first-mover positioning for Sudan and Libya transit lane establishment. Specialized cold storage operators targeting temperature-sensitive biologics distribution can disaggregate from integrated providers by securing Egyptian Customs Authority API connectivity independent of transportation assets. Direct customs broker certification investment accelerates contract eligibility ahead of licensed broker scarcity constraints. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform-capable operators with pre-integrated compliance architectures over pure-play transportation asset owners. Long-term viability across the projection horizon hinges on predictive clearance service capabilities that command premium pricing through IoT sensor network integration. Acquisition targets should demonstrate Egyptian Customs Authority electronic inventory reconciliation and bonded warehouse license renewal runway. The signal to watch is Suez Canal tariff adjustment announcements, which reshape route economics and trigger fleet reconfiguration requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Customs API Integration Partnership | Egyptian Customs Authority single-window compliance secures port clearance contract eligibility ahead of regulatory filtering. |
| Automated Warehouse Deployment | AGV systems at Cairo International Airport free zones collapse labor cost structures for pharmaceutical handling velocity. |
| Dry Port Capacity Expansion | 6th of October City inland container depot development shifts freight consolidation from congested Mediterranean gates. |
| Cold Chain Certification Investment | Temperature-controlled biologics distribution credentials unlock pharmaceutical vertical premium pricing tiers. |
| Cross-Border Corridor Establishment | Upper Egypt transit lane development captures Sudan and Libya trade flows ahead of infrastructure modernization. |
Research Methodology
Initial hypotheses were tested against primary input from 3PL operations directors, Egyptian Customs Authority licensing officials, pharmaceutical supply chain managers, and fleet procurement leads, then refined through secondary validation against Suez Canal Authority traffic disclosures, Ministry of Transportation regulatory filings, General Authority for Investment and Free Zones bonded warehouse statistics, and customs modernization protocol documentation. Bottom-up service provider capacity modeling and top-down trade flow analysis were triangulated to establish market sizing.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning service type, end-user vertical, technology adoption tier, and delivery mode. Modeled variables included pharmaceutical cold chain expansion rates, e-commerce fulfillment density trajectories, and customs automation penetration curves. CAGRs were derived from weighted scenario analysis across infrastructure investment timelines and regulatory implementation pacing.
Practitioners should monitor diesel subsidy adjustment announcements, Suez Canal tariff revisions, and bonded warehouse licensing rule changes for early signals requiring forecast reassessment. Material shifts in Egyptian Customs Authority single-window enforcement timelines or dry port development completion schedules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
North America Same Day Delivery Market
Logistics and Shipping
India 3PL Market
Logistics and Shipping
United Kingdom Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Morocco Freight and Logistics Market
Logistics and Shipping
Turkey Freight and Logistics Market
Logistics and Shipping
US Retail Logistics Market
Logistics and Shipping
China Project Logistics Market
Logistics and Shipping
Ocean Freight Forwarding Market
Logistics and Shipping
Iraq Air Freight Transport Market
Logistics and Shipping
GCC Trailer Market
Logistics and Shipping
South Korea Parcel Delivery Market
Logistics and Shipping
Mexico Containerized Shipping Market
Logistics and Shipping
Australia Last Mile Delivery Market
Logistics and Shipping
Australia Freight Forwarding Market
Logistics and Shipping
Poland Third Party Logistics (3PL) Market
Logistics and Shipping
Asia-Pacific Container Drayage Market