
 New York Freight and Logistics Market | 2026-2036
New York Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
New York Freight and Logistics Market Insights
Integrated warehousing-plus-transportation bundling is consolidating buyer choice across the New York metro corridor. OEC Group anchors trans-Pacific freight forwarding through its Long Island headquarters and port-adjacent operations. Thompson Logistic specializes in regional drayage and cross-dock coordination, while Cornucopia Logistics extends last-mile coverage into Brooklyn and Queens through localized courier networks.
New York freight and logistics encompasses the physical movement, storage, and information management of goods across road, rail, air, and maritime modes serving the Port of New York and New Jersey, the largest East Coast container gateway by volume. Operations integrate GPS tracking for real-time visibility, RFID systems for inventory authentication, and automated sorting for parcel throughput exceeding manual capacity. Freight forwarding dominates value capture given international trade density through the port complex, while last-mile delivery segments face margin compression from e-commerce volume surges and urban congestion constraints. Warehousing exhibits structural tightness in Meadowlands and Red Hook submarkets where industrial land scarcity elevates per-square-foot costs.
Federal Motor Carrier Safety Administration hours-of-service rules and New York State Department of Transportation weight limits constrain trucking capacity and route flexibility across interstate corridors. New York City Department of Transportation truck route designations and off-peak delivery programs reshape urban distribution patterns and fleet scheduling. Stakeholders must monitor congestion pricing implementation timelines and Hudson Valley rail electrification progress to align capital deployment with infrastructure evolution.
Market Dynamics
Congestion pricing implementation across Manhattan's central business district is forcing fleet operators to restructure route optimization algorithms and delivery window scheduling. This single policy mechanism cascades through drayage economics, warehousing location decisions, and labor shift patterns across the broader metro logistics ecosystem.
Growth Catalysts
- E-commerce fulfillment density:Same-day delivery promises from Queens and Brooklyn distribution nodes are pulling inventory closer to urban consumers. Micro-fulfillment centers in former retail footprints reduce last-mile transit distances.
- Port infrastructure deepening:The Bayonne Bridge clearance project completed by the Port Authority of New York and New Jersey now accommodates ultra-large container vessels. Post-Panamax ship calls concentrate cargo flows through this gateway.
- Local Law 97 compliance pathways:Building emissions caps are accelerating warehouse electrification retrofits. Cold storage facilities in the Meadowlands submarket are installing solar-plus-battery systems to offset carbon penalties.
Market Restraints
- Industrial land scarcity:Red Hook and Hunts Point submarkets face sub-3% vacancy rates. Speculative development is constrained by zoning overlays and community board opposition.
- Diesel price volatility:Fuel represents 28-35% of trucking operating costs. Small fleet operators lack hedging instruments available to asset-heavy carriers.
- Intermodal terminal throughput limits:Staten Island and Bronx rail yards operate near design capacity during peak import seasons. Container dwell times extend when vessel bunching occurs.
Strategic Opportunities
- Upstate corridor electrification:The Empire Corridor rail line from Albany to Buffalo offers freight bypass capacity. Battery-electric locomotive pilots could capture modal shift from I-87 trucking.
- Reverse logistics specialization:Apparel and electronics returns processing requires distinct sortation infrastructure. Dedicated facilities in New Jersey's Route 287 belt address this gap.
- Off-peak delivery incentives:NYC DOT's truck safety and emissions program waives certain restrictions for nighttime operations. Fleet operators rebalancing driver schedules capture productivity gains.
Industry Challenges
- Commercial driver shortage:Class A CDL holders are aging out faster than training programs replace them. Vocational schools in the Hudson Valley report waitlists exceeding six months.
- Legacy warehouse management system integration:Mid-sized 3PLs operate on platforms installed during the 2000s. API connectivity to modern transportation management systems requires custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New York Freight and Logistics Market |
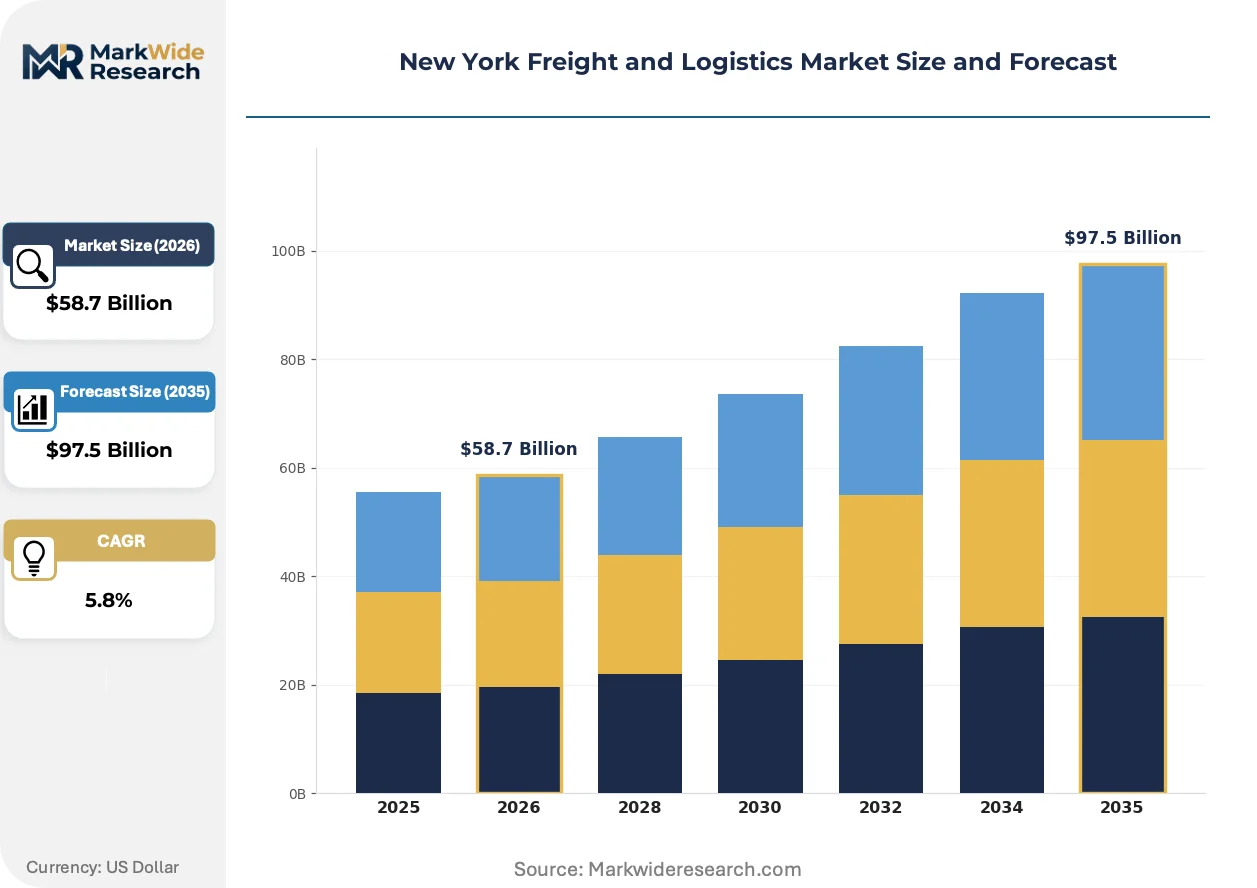
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $97.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Freight Forwarding, Last Mile Delivery, Warehousing, Supply Chain Management Technology: GPS Tracking, RFID Systems, Freight Management Software, Automated Sorting End User: E-commerce, Retailers, Manufacturers, Distributors Distribution Channel: Direct Shipping, Third-party Logistics, Courier Services, Freight Brokers |
| Companies Covered | Trammo, Motivate, CNW - Courier NetWork, Thompson Logistic, Masterpiece International, Select Express & Logistics, Cornucopia Logistics, FlatRate Moving Ltd, OEC Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New York Freight and Logistics Market Trends and Innovations
Freight matching platforms are compressing broker margins by algorithmically connecting shippers directly with available carrier capacity. This technological intermediation is redistributing value capture across the transportation execution layer.
Autonomous yard tractors are modularizing terminal operations at Port Newark and Elizabeth marine terminals. Terminal operators are piloting sensor-guided vehicles for container repositioning within gated facilities. This automation is compressing labor requirements for repetitive horizontal transport while maintaining human oversight for complex exception handling.
New York City Local Law 97 carbon intensity limits are tightening compliance timelines for commercial buildings exceeding 25,000 square feet. Warehouse operators in the five boroughs are installing building energy management systems and procuring renewable energy credits. Cold chain facilities face the steepest abatement obligations given refrigeration energy loads.
Consolidated purchasing cooperatives are emerging among mid-sized retail chains sharing distribution infrastructure. These buying alliances aggregate volume to secure dedicated fleet capacity and warehouse slots. Food and beverage distributors in the Bronx and Queens are most active in forming these procurement collectives.
New York Freight and Logistics Market Segmentation
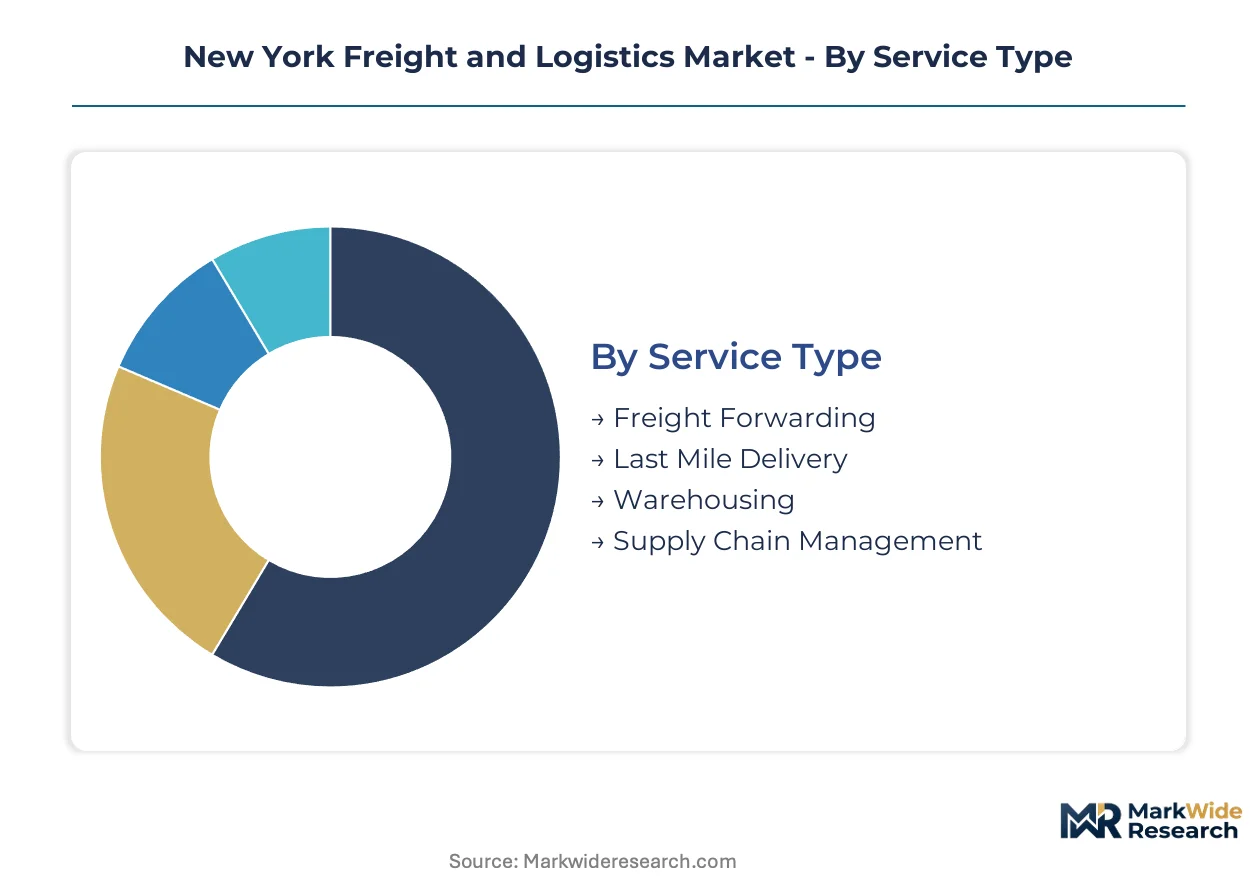
New York's freight and logistics market fragments across service delivery models, technology stacks, and customer verticals. Understanding these segment boundaries clarifies where capital deployment concentrates and where margin structures diverge across the metro corridor.
Service Type:
Technology integration depth separates high-value orchestration from commodity execution across service tiers.
- Freight Forwarding:International trade documentation and carrier procurement coordination anchor revenue capture. Port of New York and New Jersey gateway volumes concentrate demand in trans-Pacific and trans-Atlantic corridors, though customs brokerage complexity constrains new entrant scale.
- Last Mile Delivery:Urban density in Brooklyn and Queens creates route optimization challenges distinct from suburban distribution. E-commerce volume surges compress per-stop margins while Same-day delivery promises from Queens and Brooklyn distribution nodes are pulling inventory closer to urban consumers.
- Warehousing:Meadowlands and Red Hook submarkets exhibit structural tightness where industrial land scarcity elevates per-square-foot costs.
- Supply Chain Management:End-to-end visibility platforms integrate upstream supplier coordination with downstream retail replenishment.
Freight forwarding leads on scale; last mile delivery leads on momentum.
Technology:
Adoption velocity correlates with shipment volume throughput and labor cost pressure.
- GPS Tracking:Real-time vehicle location feeds dynamic route recalculation algorithms. Fleet operators across I-87 and I-95 corridors leverage satellite positioning to optimize driver hours-of-service compliance.
- RFID Systems:Passive tag authentication enables inventory authentication without line-of-sight scanning. Apparel distributors in the Bronx and Queens deploy pallet-level tracking to accelerate cross-dock velocity.
- Freight Management Software:Cloud-based transportation management systems consolidate carrier selection and load tendering.
- Automated Sorting:Parcel throughput exceeding manual capacity drives capital investment in sensor-guided diverters.
Freight management software leads on scale; automated sorting leads on momentum.
End User:
Demand volatility and service level requirements shape logistics procurement specifications.
- E-commerce:Order frequency spikes during promotional windows strain capacity planning. Micro-fulfillment centers in former retail footprints reduce last-mile transit distances for same-day delivery promises.
- Retailers:Store replenishment cadences require predictable delivery windows. Consolidated purchasing cooperatives are emerging among mid-sized retail chains sharing distribution infrastructure.
- Manufacturers:Just-in-time production schedules mandate precise inbound material coordination.
- Distributors:Multi-brand aggregation creates complexity in inventory segmentation and order batching.
E-commerce leads on scale; retailers lead on momentum.
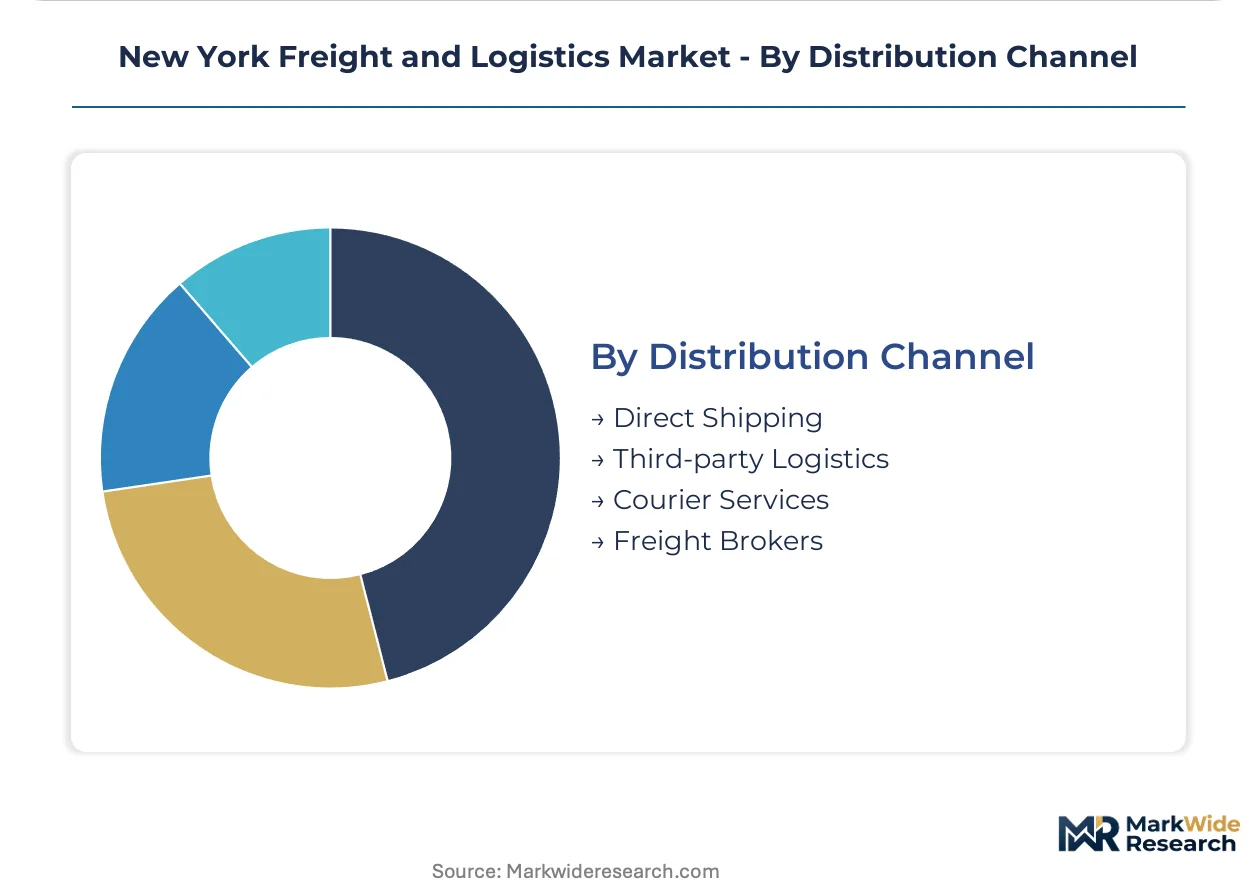
Distribution Channel:
Asset ownership models determine risk allocation and pricing transparency.
- Direct Shipping:Shipper-controlled fleets bypass intermediary markups for high-volume lanes. Large retailers with dedicated private fleets operate across the Hudson Valley to maintain schedule control.
- Third-party Logistics:Integrated warehousing-plus-transportation bundling consolidates buyer choice across the New York metro corridor.
- Courier Services:Localized courier networks extend coverage into Brooklyn and Queens through parcel-level handoff protocols.
- Freight Brokers:Freight matching platforms compress margins by algorithmically connecting shippers directly with available carrier capacity.
Third-party logistics leads on scale; freight brokers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New York freight and logistics traces its commercial lineage to the Erie Canal era, when Buffalo and Albany emerged as transshipment hubs connecting Atlantic ports to Midwestern agricultural markets. The contemporary market distributes activity across five distinct sub-regional clusters shaped by infrastructure endowments and regulatory boundaries.
New York City Metro
E-commerce fulfillment density concentrates in Queens and Brooklyn distribution nodes, where same-day delivery promises pull inventory closer to urban consumers. New York City Local Law 97 carbon intensity limits are accelerating warehouse electrification retrofits across the five boroughs. The Red Hook and Hunts Point submarkets exhibit sub-3% industrial vacancy rates, constraining speculative development despite sustained demand from food and beverage distributors.
Long Island
Port-adjacent freight forwarding operations anchor trans-Pacific trade documentation and carrier procurement coordination through Nassau and Suffolk county headquarters. The Port Authority of New York and New Jersey maintains intermodal connectivity through rail yards serving the marine terminals. Garden City and Melville logistics parks concentrate customs brokerage capacity given proximity to JFK International Airport's air cargo facilities.
Hudson Valley
Class A CDL training programs in the Hudson Valley report waitlists exceeding six months as commercial driver aging-out outpaces vocational school capacity. New York State Department of Transportation weight limits constrain trucking route flexibility across I-87 and I-84 interstate corridors. The Albany-Troy-Schenectady metropolitan area functions as a north-south distribution pivot between New England manufacturing and Pennsylvania distribution centers.
Capital Region
The Empire Corridor rail line from Albany to Buffalo offers freight bypass capacity for modal shift away from I-87 trucking congestion. Battery-electric locomotive pilots could capture volume from shippers facing diesel price volatility and hours-of-service constraints. Schenectady and Rensselaer county industrial parks are attracting cold storage developers seeking lower per-square-foot costs than Meadowlands alternatives.
Western New York
Buffalo-Niagara logistics activity leverages cross-border connectivity to Ontario manufacturing and Toronto distribution markets. The Peace Bridge and Lewiston-Queenston Bridge corridors handle substantial truck freight subject to Canadian and U.S. customs coordination. Former industrial footprints in Erie County are converting to micro-fulfillment centers serving Rochester and Syracuse consumer markets.
New York Freight and Logistics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across service integration depth, with freight forwarders and bundled 3PLs commanding pricing power over single-service truck brokers and courier networks. The vendor base organizes into three tiers: international trade orchestrators with customs brokerage depth, regional drayage and cross-dock specialists, and last-mile courier networks with localized density. Consolidation pressure operates through warehousing-plus-transportation bundling, while technology differentiation separates algorithmic freight matchers from legacy phone-and-fax operators.
Among the forwarding and logistics tier, OEC Group anchors trans-Pacific coordination through its Long Island headquarters and port-adjacent operations. Thompson Logistic occupies a position within the regional drayage specialist archetype, while Cornucopia Logistics exemplifies the last-mile courier model extending coverage into Brooklyn and Queens through localized network density.
| Leading Market Players |
|---|
| Trammo |
| Motivate |
| CNW - Courier NetWork |
| Thompson Logistic |
| Masterpiece International |
| Select Express & Logistics |
| Cornucopia Logistics |
| FlatRate Moving Ltd |
| OEC Group |
| Others |
Pricing and Supply Chain Analysis
Freight matching platforms are compressing broker margins by algorithmically connecting shippers directly with available carrier capacity. This technological intermediation redistributes value capture across the transportation execution layer while simultaneously reshaping cost economics for small fleet operators and concentrating procurement power among asset-heavy carriers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the New York metro corridor. Premium tiers attach to guaranteed capacity contracts with real-time visibility, while economy tiers trade price for flexibility in delivery windows. Price differentiation hinges on service reliability and carbon compliance certification under Local Law 97. Cost compression in the standard tier is intensifying because freight matching platforms erode traditional broker markups. E-commerce retailers exhibit the highest price sensitivity due to margin-thin fulfillment economics, whereas pharmaceutical distributors accept premium pricing for cold chain integrity.
Supply Chain Analysis
Domestic-content mandates under the Buy American Act are reshaping sourcing patterns for port infrastructure components and rail equipment. The New York freight ecosystem draws from manufacturing clusters in China, South Korea, and Germany for container handling equipment and locomotive components. Supply chains rest on diesel engine parts, battery-electric drivetrains, and automated sorting machinery. Single-source vulnerability concentrates in Chinese-manufactured gantry crane systems. Distribution runs through the Port of New York and New Jersey gateway, with final-mile handoffs to localized courier networks across the five boroughs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
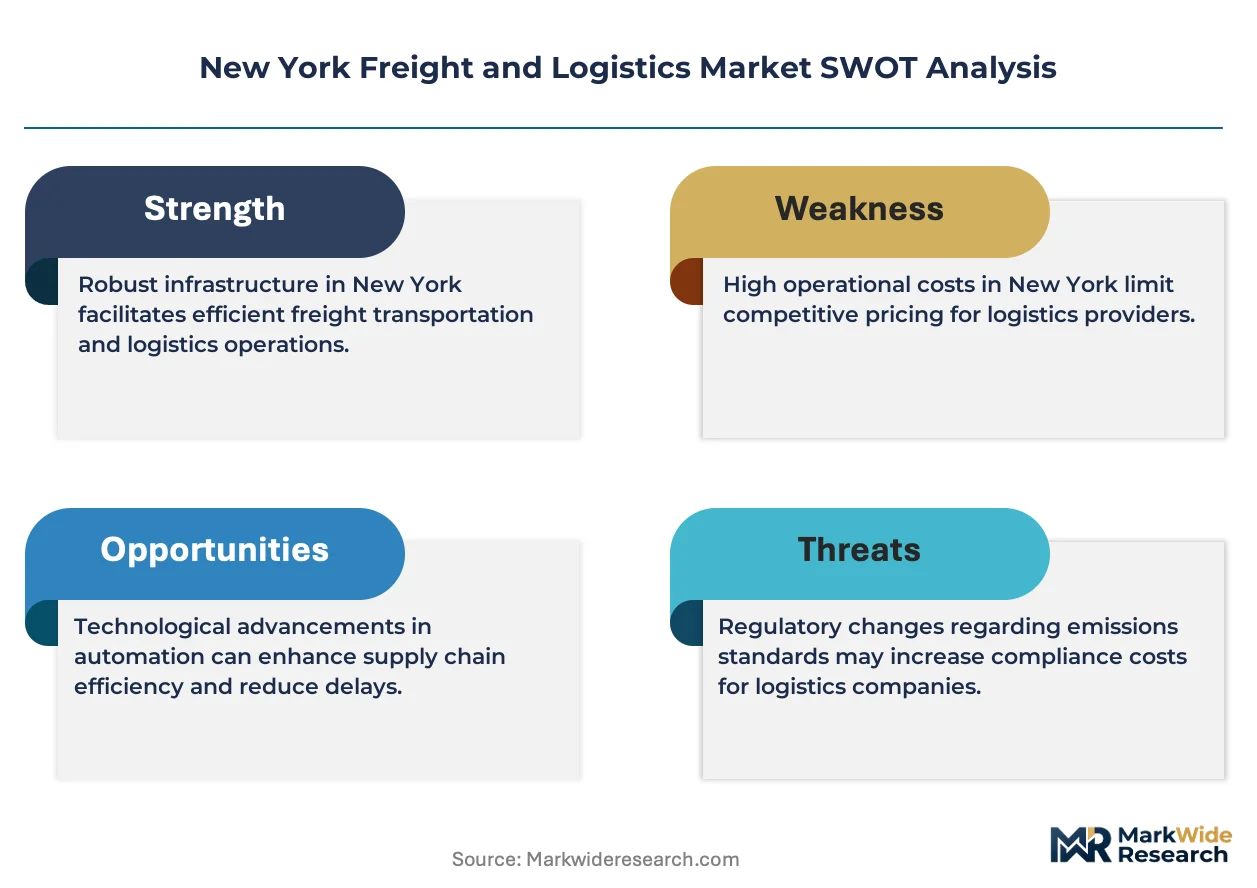
New York freight and logistics functions as a regulatory compounder where Local Law 97 carbon intensity limits are accelerating warehouse electrification retrofits and reshaping fleet procurement economics across the metro corridor.
For Market Incumbents: Hedge against margin erosion by securing long-term renewable energy contracts for Meadowlands and Red Hook warehouse portfolios before carbon penalty escalation. Acquire Class A CDL training pipeline capacity in the Hudson Valley to lock in driver supply as vocational school waitlists extend. Diversify drayage operations across Staten Island and Bronx rail yards to mitigate container dwell time risk during peak import seasons.
For New Entrants and Emerging Players: Local Law 97 in New York City opens a window for specialized cold storage electrification services targeting food and beverage distributors facing steep abatement obligations. Target reverse logistics processing for apparel and electronics returns in New Jersey's Route 287 belt, where dedicated sortation infrastructure remains underdeveloped. Pursue off-peak delivery contracts with NYC DOT incentive alignment to capture nighttime route productivity gains without congestion pricing exposure.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized 3PLs operating on legacy warehouse management systems requiring API middleware investment. Long-term viability centers on bundled warehousing-plus-transportation providers with established port-adjacent real estate positions. Monitor Empire Corridor rail electrification pilot progress as the inflection signal for battery-electric locomotive adoption and modal shift capture from I-87 trucking.
| Strategic Initiative | Industry Significance |
|---|---|
| Warehouse Electrification Retrofit | Local Law 97 compliance pathways drive solar-plus-battery installation in Meadowlands cold storage facilities. |
| Freight Matching Platform Integration | Algorithmic capacity matching compresses traditional broker margins while capturing shipper-direct relationships. |
| Last-Mile Courier Network Density | Localized parcel handoff protocols in Brooklyn and Queens enable same-day delivery promise fulfillment. |
| Reverse Logistics Facility Development | Dedicated returns processing infrastructure addresses apparel and electronics sortation gaps in Route 287 belt. |
| Off-Peak Delivery Schedule Rebalancing | NYC DOT truck safety program incentives capture nighttime productivity gains and congestion pricing avoidance. |
Research Methodology
Bottom-up e-commerce fulfillment modeling reconciled against top-down port throughput tracking forms the analytical core of this study. Primary interviews with fleet operators, warehouse facility managers, customs brokerage executives, and NYC DOT planning officers were cross-validated against secondary sources including Port Authority of New York and New Jersey cargo statistics, EPA emissions compliance filings, and New York State Department of Transportation corridor weight limit documentation. Trade flow data from the U.S. Census Bureau and customs brokerage volume indices provided additional triangulation anchors.
Historical trendline analysis of container vessel calls and intermodal rail movements established baseline growth patterns across the analysis window. Segmentation modeling incorporated service type, technology adoption tier, end-use vertical, and distribution channel ownership structure. CAGRs were derived from shipment volume trajectories, warehouse absorption rates, and fleet electrification procurement pipelines. Forecast inputs included congestion pricing implementation timelines, Hudson Valley rail electrification progress, and vocational school CDL training capacity expansion.
Revisions become necessary when EPA emissions standard amendments, congestion pricing policy suspensions, or port labor contract disruptions materialize outside baseline assumptions. Forecasts reflect documented parameters around infrastructure investment schedules and regulatory compliance deadlines. Supply chain chokepoints, diesel price volatility spikes, and intermodal terminal capacity constraints represent specific risk factors that could alter trajectory projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Italy Cold Chain Logistics Market
Logistics and Shipping
Slovakia Freight and Logistics Market
Logistics and Shipping
Singapore Shipping Agency Services Market
Logistics and Shipping
Nigeria Freight and Logistics Market
Logistics and Shipping
Contract Logistics Market
Logistics and Shipping
Digital Freight Brokerage Market
Logistics and Shipping
High-Tech Logistics Market
Logistics and Shipping
Logistics Data Quality and Normalization Services Market
Logistics and Shipping
Nigeria Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Czech Republic Freight and Logistics Market
Logistics and Shipping
Germany Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Iraq Freight and Logistics Market
Logistics and Shipping
Military Logistics Market
Logistics and Shipping
India 3PL Market
Logistics and Shipping
United States Freight and Logistics Market
Logistics and Shipping
Singapore Freight and Logistics Market