

Big Data in Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Big Data in Logistics Market Insights
Market Context
Multi-source analytics procurement is recalibrating how logistics operators balance cloud agility against data sovereignty requirements. IBM leverages its hybrid cloud architecture to anchor enterprise clients with complex cross-border freight flows. SAP competes through deep ERP integration that sustains demand-planning workflows for distribution centers. Amazon Web Services dominates hyperscale infrastructure for real-time fleet telematics ingestion.
Technical Definition and Segments
Big Data in Logistics denotes the capture, storage, and algorithmic processing of structured and unstructured datasets exceeding terabyte scale from transport records, warehouse sensors, and fleet telematics to generate predictive operational intelligence. Its primary commercial purpose is the reduction of empty-mile incidence and inventory carrying costs through machine-learned demand signals. Cloud-Based deployment now leads in new implementations because elasticity matches seasonal freight volatility, while Edge Computing represents the fastest-growing architecture as autonomous yard vehicles require sub-50-millisecond inference latency. Route Optimization commands the largest application-level margin pool due to fuel cost sensitivity, whereas Risk Management is accelerating as climate-related supply disruption models mature.
Regulatory Outlook
The EU AI Act imposes conformity requirements on automated freight-routing decisions, while HIPAA governs health-care logistics data flows in the United States and the F-Gas Regulation indirectly shapes cold-chain sensor compliance across Europe. These frameworks elevate auditability standards for algorithmic traceability and data residency, effectively filtering vendor eligibility by certification depth. Stakeholders must monitor emerging algorithmic accountability rules in multiple jurisdictions to preempt procurement lock-in.
Market Dynamics
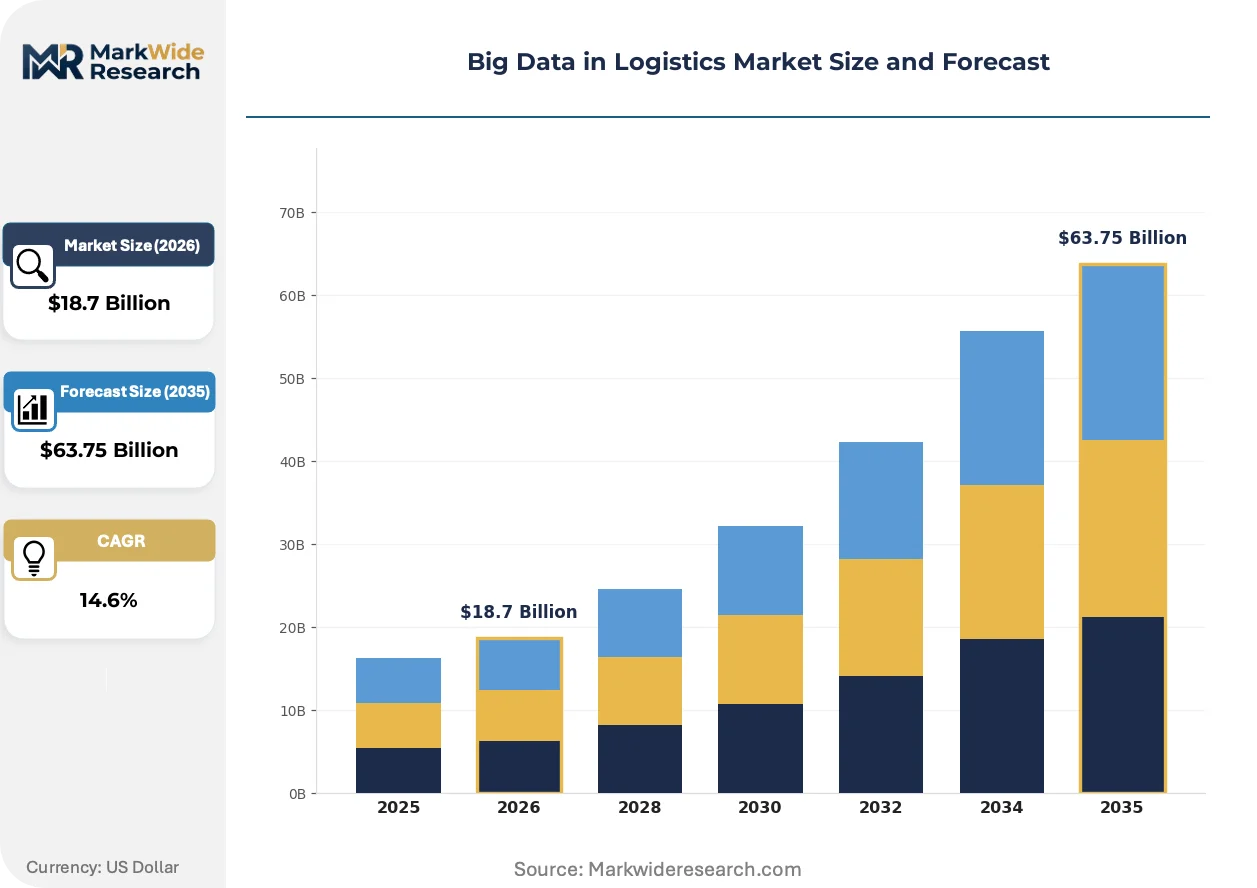
EU AI Act cloud-migration mandates and freight corridor digitization investments across the United States are compressing deployment timelines for algorithmic logistics platforms. The collision between data sovereignty requirements and real-time analytics demand is forcing architecture trade-offs that favor hybrid infrastructure.
Growth Catalysts
- EU AI Act Conformity Pressure:Automated freight-routing auditability requirements in Europe are accelerating procurement of certified algorithmic traceability systems. Logistics operators must demonstrate decision explainability to maintain cross-border operational licenses.
- E-commerce Last-Mile Complexity:Parcel volume volatility from online retail is driving demand for elastic cloud infrastructure that scales with seasonal freight surges. Distribution centers require predictive capacity planning to manage same-day delivery windows.
- Port Automation Investment Waves:Container terminal digitization in the United States is generating terabyte-scale sensor data streams. Automated yard equipment and vessel scheduling systems depend on sub-second inference latency for collision avoidance.
Market Restraints
- Cloud Infrastructure Cost Volatility:Hyperscale compute pricing fluctuations compress margins for mid-sized 3PL operators running continuous fleet optimization workloads. Energy-intensive machine learning training cycles amplify exposure to electricity rate spikes.
- Data Residency Fragmentation:Divergent national data localization laws fragment unified analytics architectures. Cross-border freight flows face compliance friction when telemetry crosses jurisdictions with conflicting sovereignty requirements.
- Edge Hardware Supply Concentration:GPU and specialized inference chip fabrication concentrates in Taiwan and South Korea. Logistics autonomy projects face procurement delays when semiconductor foundry capacity tightens.
Strategic Opportunities
- Cold-Chain Risk Analytics:Climate-related supply disruption models for pharmaceutical and perishable cargo remain underdeveloped. F-Gas Regulation sensor compliance requirements in Europe create entry points for predictive spoilage detection platforms.
- India Logistics Digitization:National highway corridor sensorization and GST invoice-matching data lakes offer greenfield deployment potential. Domestic e-commerce fulfillment networks lack mature demand-forecasting infrastructure.
- Digital Twin Convergence:Integration of warehouse simulation models with live telematics feeds enables prescriptive rather than predictive optimization. 3D spatial analytics fused with inventory velocity data compresses dock-to-stock cycle times.
Industry Challenges
- Algorithmic Accountability Talent Scarcity:Supply of data engineers capable of building auditable machine learning pipelines for freight routing lags demand. Regulatory conformity documentation requires specialized expertise at the intersection of logistics operations and computational law.
- Legacy WMS Integration Friction:Decades-old warehouse management systems resist API-based connectivity to modern analytics platforms. Custom middleware development for ERP synchronization consumes implementation budgets and extends deployment timelines.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Big Data in Logistics Market Trends and Innovations
Algorithmic freight management is migrating from descriptive dashboards toward autonomous decision systems that execute routing and inventory moves without human intervention. This shift demands new infrastructure architectures and compliance frameworks.
Edge computing for autonomous yard vehicles is consolidating control over yard operations previously distributed between human dispatchers and centralized cloud platforms. Terminal operators at the Port of Los Angeles and Port of Long Beach are deploying sub-50-millisecond inference clusters to coordinate automated guided vehicles. This consolidation compresses response latency for collision avoidance while reducing bandwidth costs for continuous cloud telemetry upload.
The EU AI Act's risk-based classification system imposes conformity assessment burdens on automated freight-routing algorithms deemed high-risk. Logistics software vendors must maintain technical documentation and human oversight protocols to satisfy notified body requirements. European 3PLs are responding by segregating decision systems into explainable rule-based modules and black-box optimization engines.
Shippers are unbundling transportation management from freight audit and payment functions, creating openings for specialized analytics providers. Large retail consolidators now source route optimization as a standalone service rather than embedded within full-service logistics contracts. This disintermediation is most visible in United States consumer goods distribution, where direct procurement of algorithmic dispatching from software vendors bypasses traditional 3PL technology stacks.
Big Data in Logistics Market Segmentation
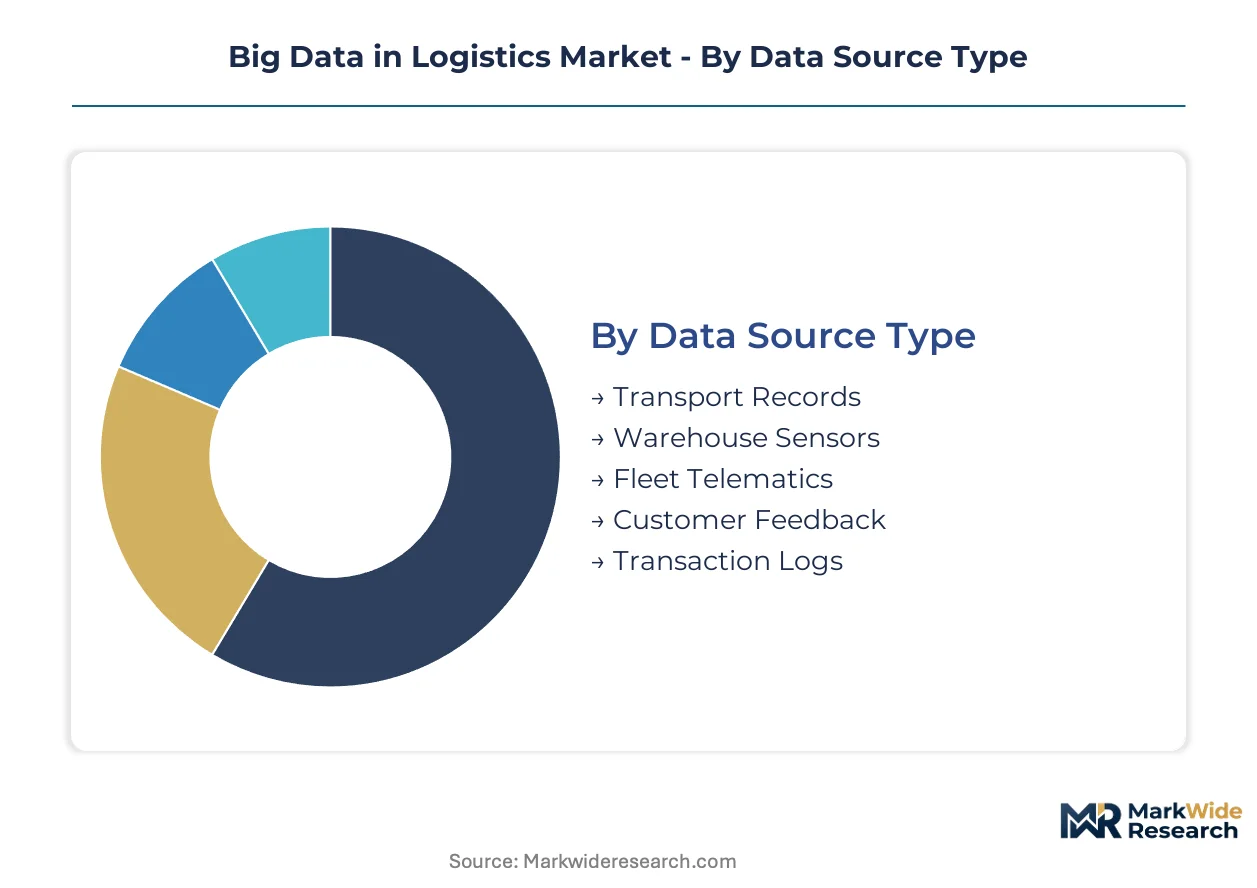
Logistics operators select big data architectures based on latency requirements, sovereignty constraints, and integration depth with legacy warehouse systems. Segmentation reveals where cloud elasticity competes against edge inference and which application layers command implementation priority.
Data Source Type:
Fleet telematics and warehouse sensors dominate data volume, while customer feedback and transaction logs concentrate premium analytics spend.
- Fleet Telematics:GPS, engine diagnostics, and driver behavior streams from commercial vehicles generate continuous location and performance data. Demand concentrates among long-haul trucking operators in the United States seeking fuel efficiency gains through predictive maintenance alerts.
- Warehouse Sensors:RFID, temperature, and motion detection devices capture inventory velocity and environmental conditions. Cold-chain pharmaceutical distributors in Europe drive implementation under F-Gas Regulation compliance mandates for spoilage prevention.
- Transport Records:Bill of lading, customs documentation, and carrier manifests provide structured shipment histories.
- Customer Feedback:Delivery satisfaction scores and complaint logs supply unstructured sentiment data for service optimization.
- Transaction Logs:Payment and invoice records enable freight audit automation and revenue leakage detection.
Mature deployment sits with Fleet Telematics. Newer deployment is concentrated in Customer Feedback.
Deployment Model:
Cloud-based implementations lead new procurement, though edge computing gains share fastest among autonomous yard operations.
- Cloud-Based:Hyperscale infrastructure delivers elastic compute for seasonal freight volatility without capital expenditure. E-commerce fulfillment networks in the United States scale warehouse management systems during peak holiday periods through auto-provisioned analytics clusters.
- Edge Computing:Localized inference clusters process sensor data with sub-50-millisecond latency for real-time decision execution. Container terminals at the Port of Los Angeles deploy edge nodes to coordinate automated guided vehicle collision avoidance without cloud round-trip delays.
- Hybrid:Split architectures route sensitive data on-premises while bursting non-critical workloads to public cloud.
- On-Premises:Dedicated data centers serve defense and government logistics with strict air-gapped requirements.
- Managed Services:Third-party operators maintain infrastructure and model training for mid-sized 3PLs lacking internal data engineering capacity.
Volume leadership belongs to Cloud-Based. Steepest expansion trajectory is concentrated in Edge Computing.
Application:
Route optimization commands the largest margin pool, while risk management applications accelerate as climate disruption models mature.
- Route Optimization:Algorithmic dispatching minimizes empty miles and fuel consumption through dynamic traffic and demand integration. National trucking fleets in the United States prioritize this capability as diesel price volatility compresses per-mile profitability.
- Risk Management:Predictive models assess weather, geopolitical, and supplier failure probabilities for supply continuity planning. European pharmaceutical shippers invest here under EU AI Act requirements for auditable disruption contingency protocols.
- Inventory Forecasting:Machine-learned demand signals reduce safety stock requirements and obsolescence write-offs.
- Demand Planning:Multi-echelon optimization aligns procurement, production, and distribution schedules across supply networks.
- Freight Tracking:Real-time visibility platforms consolidate carrier EDI feeds and IoT sensor locations for shipment status monitoring.
Established adoption centers on Route Optimization. Emerging investment flows into Risk Management.
End User:
E-commerce businesses expand their analytics spend fastest, while third-party logistics providers concentrate vendor bargaining power.
- E-commerce Businesses:Direct-to-consumer retailers require predictive last-mile capacity planning for same-day and next-day delivery windows. Domestic fulfillment networks in India lack mature demand-forecasting infrastructure and represent greenfield deployment opportunities.
- Third-Party Logistics:Asset-light operators differentiate through algorithmic freight matching and dynamic pricing engines. Large retail consolidators in the United States now unbundle route optimization from full-service contracts, pressuring 3PL technology stack margins.
- Shipping Companies:Ocean and air carriers optimize vessel scheduling and container utilization through predictive port congestion models.
- Distribution Centers:Warehouse operators deploy spatial analytics and robotic orchestration systems for dock-to-stock cycle compression.
- Freight Forwarders:Intermediaries leverage customs data and trade lane analytics to optimize multimodal routing and documentation workflows.
Scale concentration rests with Third-Party Logistics. Fastest-growing demand originates from E-commerce Businesses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for algorithmic logistics platforms concentrates most acutely in the United States, where freight corridor digitization and port automation investments outpace other national markets. European operators face EU AI Act conformity deadlines that compress procurement timelines. Asian markets present greenfield deployment opportunities where fulfillment infrastructure remains underdeveloped.
United States
Freight corridor sensorization along Interstate highways generates continuous telematics streams for predictive maintenance algorithms. The Federal Motor Carrier Safety Administration mandates electronic logging device compliance that standardizes data capture across commercial fleets. Port automation investments at Los Angeles and Long Beach container terminals deploy edge computing clusters for automated guided vehicle coordination.
Germany
Automotive supply chains demand real-time inventory visibility across multi-tier supplier networks. The EU AI Act imposes conformity assessment requirements on automated freight-routing algorithms classified as high-risk. Industrial logistics clusters in Baden-Württemberg integrate warehouse management systems with predictive demand-planning platforms.
China
E-commerce fulfillment networks generate parcel volume volatility that strains last-mile capacity planning. National data localization laws under the Cybersecurity Law fragment cross-border analytics architectures. Yangtze River Delta distribution centers deploy digital twin simulations to compress dock-to-stock cycle times.
India
National highway corridor sensorization and GST invoice-matching data lakes create greenfield deployment potential for demand-forecasting infrastructure. The Bureau of Indian Standards issues technical specifications for cold-chain monitoring equipment. Domestic e-commerce fulfillment networks in Maharashtra and Karnataka lack mature predictive capacity planning systems.
United Kingdom
Post-Brexit customs documentation complexity drives demand for automated trade lane analytics. The UK Information Commissioner's Office enforces data residency requirements that shape cloud procurement decisions. London-based freight forwarders unbundle transportation management from freight audit functions to source specialized algorithmic dispatching.
Big Data in Logistics Market Competitive Landscape
Strategic partnerships dominate the current landscape as hyperscale cloud providers align with specialized logistics software vendors to deliver integrated analytics stacks. The vendor base organizes into three tiers: full-service enterprise platforms, cloud-native specialists, and legacy warehouse management system incumbents. Two archetypes define competitive positioning: hybrid cloud architects serving cross-border freight operators, and edge computing specialists targeting port automation projects. Geographic expansion and technology licensing represent the dominant competitive moves as vendors seek certification depth across multiple regulatory jurisdictions.
Within the enterprise platform tier, IBM leverages hybrid cloud architecture to anchor clients with complex freight flows, while SAP competes through ERP integration sustaining demand-planning workflows. Amazon Web Services occupies a position at the hyperscale infrastructure end, dominating real-time fleet telematics ingestion. These three exemplify how competitive positioning stratifies across cloud agility, integration depth, and sovereignty compliance capabilities.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| Oracle |
| SAP |
| Amazon Web Services |
| Blue Yonder |
| Teradata |
| Kinaxis |
| Manhattan Associates |
| Others |
Pricing and Supply Chain Analysis
Captive cloud infrastructure ownership among hyperscale providers anchors both supply security and pricing power in algorithmic logistics platforms. AWS, Microsoft Azure, and Google Cloud Platform control the compute layer that underpins fleet telematics ingestion and warehouse sensor analytics, creating asymmetric bargaining positions against mid-sized 3PL operators seeking elastic capacity.
Pricing Analysis
Warranty and service bundling separates premium-tier deployments from economy implementations in logistics analytics procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth under EU AI Act conformity requirements and integration complexity with legacy warehouse management systems. Price differentiation hinges on algorithmic auditability documentation and human-in-the-loop oversight protocols. Pricing pressure stems from hyperscale compute rate volatility compressing margins for continuous fleet optimization workloads. Mid-sized 3PL operators exhibit highest price sensitivity due to energy-intensive machine learning training cycles amplifying electricity cost exposure.
Supply Chain Analysis
Warehouse-distribution layer consolidation concentrates GPU and specialized inference chip procurement through regional distribution centers in Taiwan, South Korea, and the United States. Semiconductor foundry capacity feeds from NVIDIA, AMD, and Intel fabrication networks for edge computing clusters deployed at container terminals. Raw material dependencies span silicon wafers, advanced packaging substrates, and rare earth elements for magnet-based sensors. Single-source vulnerability in Taiwan Semiconductor Manufacturing Company production creates chokepoint risk for autonomous yard vehicle projects. Distribution runs through hub-and-spoke patterns anchored by hyperscale cloud regions in Northern Virginia, Frankfurt, and Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algorithmic freight management is displacing descriptive dashboard systems with autonomous decision architectures. Edge computing inference clusters replace centralized cloud platforms for sub-50-millisecond latency requirements in port automation.
For Market Incumbents: Deepen hybrid cloud certification depth across multiple regulatory jurisdictions to preempt procurement lock-in from EU AI Act conformity deadlines. Incumbent enterprise platforms face margin compression from disintermediation as large retail consolidators unbundle route optimization from full-service logistics contracts. Vertical integration into edge hardware distribution secures supply position against semiconductor foundry capacity constraints. For New Entrants and Emerging Players: Direct-to-software procurement channels bypass entrenched 3PL technology stacks in United States consumer goods distribution. Cold-chain risk analytics for pharmaceutical and perishable cargo remains underdeveloped relative to route optimization maturity. India logistics digitization offers greenfield deployment potential where national highway corridor sensorization and GST invoice-matching data lakes lack mature demand-forecasting infrastructure. API-native platforms targeting mid-market 3PLs without internal data engineering capacity capture managed services substitution demand. For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscale cloud provider acquisition of specialized logistics software vendors for integrated analytics stack delivery. Long-term viability favors vendors with certification depth spanning EU AI Act, HIPAA, and emerging algorithmic accountability frameworks across multiple jurisdictions. Acquisition target archetype: edge computing specialists with port automation deployment track records and sub-50-millisecond inference latency capabilities. Signal to watch: notified body conformity assessment backlog duration as indicator of vendor compliance velocity advantage.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Certification | Notified body assessment unlocks cross-border operational licenses for automated freight-routing algorithms in Europe. |
| Edge Computing Cluster Deployment | Sub-50-millisecond inference latency enables autonomous guided vehicle coordination at Port of Los Angeles terminals. |
| Hybrid Cloud Architecture Expansion | Split processing satisfies data residency requirements while bursting non-critical workloads to public hyperscale infrastructure. |
| Legacy WMS API Integration | Middleware development connects decades-old warehouse systems to modern analytics platforms for ERP synchronization. |
| India Market Entry Partnership | Domestic e-commerce fulfillment networks in Maharashtra lack predictive capacity planning infrastructure for same-day delivery. |
Research Methodology
Independent corroboration across logistics technology procurement officers, data engineering leads at 3PL operators, regulatory compliance specialists, and cloud solution architects underwrites the qualitative findings. Primary interviews with fleet telematics managers, warehouse automation directors, and port terminal operators supplied operational implementation data. Secondary validation drew from SEC filings of publicly traded logistics software vendors, hyperscaler capex disclosures, EU AI Act implementing guidance, and customs data on semiconductor import flows. Bottom-up triangulation across deployment model adoption rates and top-down reconciliation against aggregate cloud infrastructure spend produced convergent estimates.
Rate-of-change decomposition separates baseline logistics digitization trends from EU AI Act conformity acceleration effects and e-commerce last-mile complexity inflections across the analysis window. Segmentation dimensions modeled include deployment architecture elasticity, data source type volume concentration, application layer margin pool distribution, and end-user vertical adoption velocity. CAGRs derived from logistic curve fitting to technology diffusion patterns in comparable enterprise software categories. Industry-specific forecast inputs incorporate electronic logging device mandate compliance saturation and F-Gas Regulation cold-chain sensor replacement cycles.
The model holds under stable regulatory enforcement intensity and continued hyperscale cloud capacity expansion; deviation in semiconductor foundry output or algorithmic accountability rule expansion would shift deployment timeline assumptions. Forecasts reflect documented assumptions regarding freight corridor sensorization investment continuity and port automation capital allocation priorities. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.