
 Smart Shipping Containers Market | 2026-2036
Smart Shipping Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Shipping Containers Market Outlook
Aftermarket service revenue from predictive maintenance platforms is reshaping profit pools across the container fleet management value chain. ORBCOMM leverages satellite connectivity infrastructure to sustain recurring data-service margins. Traxens anchors European rail and maritime corridors with proprietary mesh-network hardware. Globe Tracker competes on open-architecture APIs that integrate with third-party logistics software ecosystems.
Smart shipping containers are steel freight enclosures retrofitted with GPS transponders, IoT environmental sensors, and telemetry gateways transmitting location, shock, humidity, and temperature data at configurable intervals to centralized fleet dashboards. Their primary commercial purpose is eliminating cargo loss, customs delay, and spoilage through real-time supply chain visibility. Temperature-controlled units command premium positioning as pharmaceutical cold-chain integrity requirements tighten across international lanes. GPS and IoT sensor deployments are expanding fastest where multimodal handoffs create accountability gaps between ocean carriers and last-mile distributors.
The International Maritime Organization's mandatory container weighing verification rules and the EU's CSRD emissions disclosure mandates are compelling fleet operators to document cargo conditions and carbon footprints through automated sensor logs. The US Coast Guard and FDA jointly scrutinize temperature excursion records for food and pharmaceutical imports at American ports. Stakeholders must decide whether to build captive IoT platforms or subscribe to neutral data aggregators before interoperability standards consolidate around dominant protocols.
Market Dynamics
Pharmaceutical cold-chain integrity mandates are compressing replacement cycles for reefer fleets as regulators tighten documentation requirements for temperature-sensitive cargo. Fleet operators face simultaneous pressure to retrofit existing boxes and deploy new sensor-native containers across multimodal corridors.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant emission limits are compelling Hamburg-Bremerhaven operators to upgrade temperature-control systems, accelerating IoT-enabled reefer deployments.
- Pharmaceutical logistics:Cold-chain biologics shipments require continuous temperature logging, driving sensor density in temperature-controlled units.
- IMO container weighing rules:Automated weight verification mandates are forcing adoption of integrated telemetry gateways across ocean carrier fleets.
Market Restraints
- Steel price volatility:Container manufacturing costs swing with raw material inputs, compressing margins for box lessors considering sensor retrofits.
- Satellite connectivity dependency:Maritime routes rely on narrowband satellite coverage gaps in southern ocean corridors, limiting real-time data reliability.
- Legacy fleet inertia:Twenty-year container depreciation schedules delay replacement economics despite sensor retrofit payback periods.
Strategic Opportunities
- India pharmaceutical exports:CDSCO cold-chain documentation requirements are creating first-mover advantage for sensor-integrated reefer deployments at Mumbai-JNPT port.
- Rail-maritime convergence:Mesh-network hardware enabling seamless handoffs between European rail corridors and deep-sea terminals reduces data fragmentation.
- EU CSRD emissions disclosure:Automated carbon footprint logging creates subscription revenue streams from compliance reporting services.
Industry Challenges
- Interoperability fragmentation:Competing telemetry protocols between carrier-owned platforms and neutral data aggregators complicate fleet-wide dashboard integration.
- Cyber-physical certification timelines:IEC 62443 security standard compliance for connected containers extends product validation cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Shipping Containers Market |
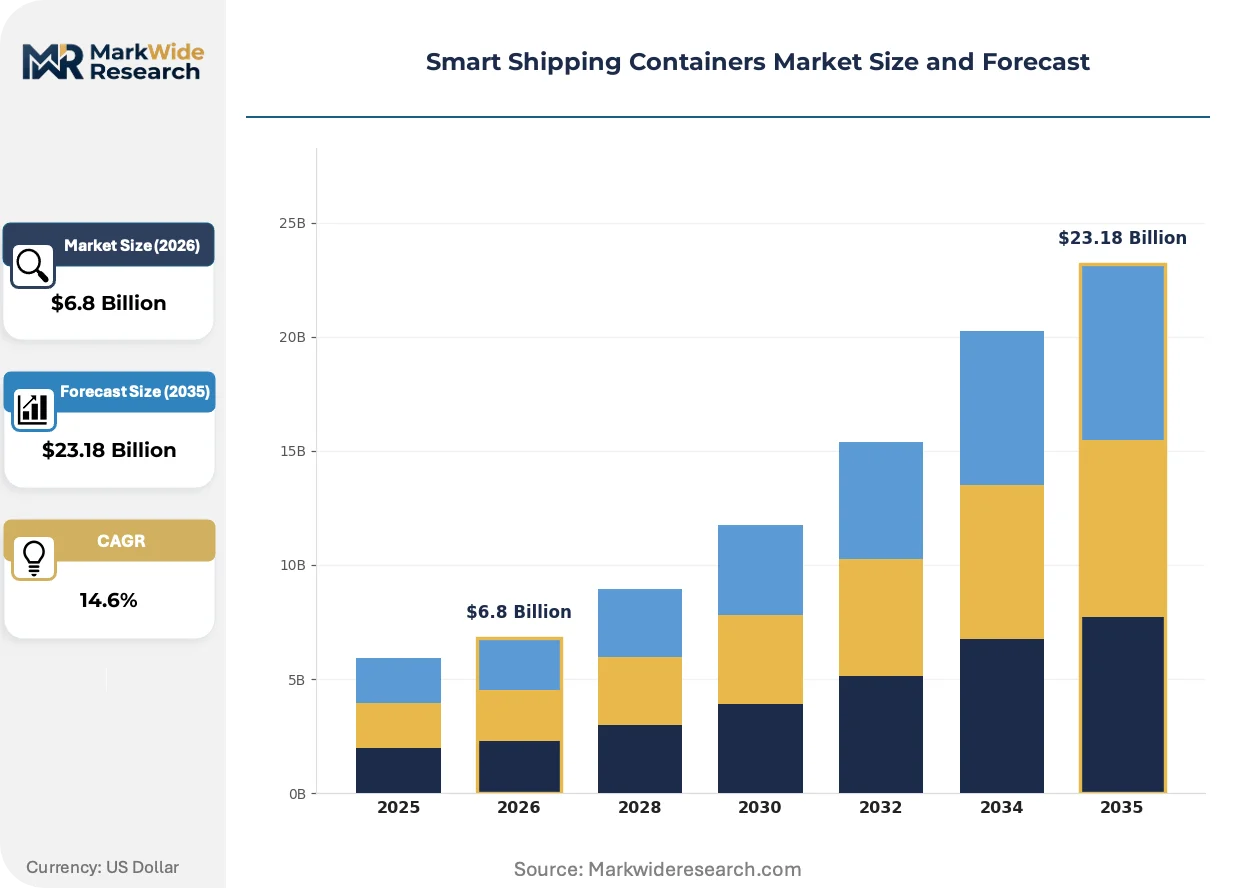
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $23.18 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature-Controlled, Hazardous Material, Standard, Customizable Technology: RFID, GPS, IoT Sensors, Telemetry End User: Logistics Providers, Retailers, Manufacturers, Food Distributors Deployment: On-Premises, Cloud-Based, Hybrid, Mobile |
| Companies Covered | ORBCOMM, Traxens, Globe Tracker, MSC, Sealand-A Maersk Company, Nexxiot AG, Smart Containers Group, CMA CGM Group, CIMC Smart Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Shipping Containers Market Strategic Shifts
Sensor fusion architectures are redefining how container fleets generate actionable intelligence, moving beyond location tracking toward predictive cargo-state modeling. This evolution is compressing the value chain between hardware deployment and software monetization.
Edge computing is migrating from centralized cloud processing to container-mounted gateways capable of local anomaly detection and bandwidth-efficient data triage. Pharmaceutical shippers are adopting these gateways fastest, requiring sub-minute latency for temperature excursion alerts. The structural consequence is collapsing reliance on continuous satellite uplinks, reducing connectivity costs for high-frequency monitoring routes.
The EU F-Gas Regulation is banning hydrofluorocarbon refrigerants in new reefer equipment, forcing compressor redesigns and alternative cooling chemistry validation. Equipment manufacturers must recalibrate sensor calibration algorithms for ammonia and CO2-based systems. German port operators are piloting these compliant units most aggressively, creating regulatory arbitrage pressure on Baltic and Mediterranean terminals.
Freight procurement is consolidating around performance-guarantee contracts that penalize temperature deviations rather than equipment rental fees alone. Large pharmaceutical distributors are unbundling sensor data ownership from ocean carrier agreements, demanding API access to raw telemetry streams. This shift is most pronounced in trans-Atlantic lanes where FDA import scrutiny at US ports creates liability asymmetry.
Smart Shipping Containers Market Segmentation
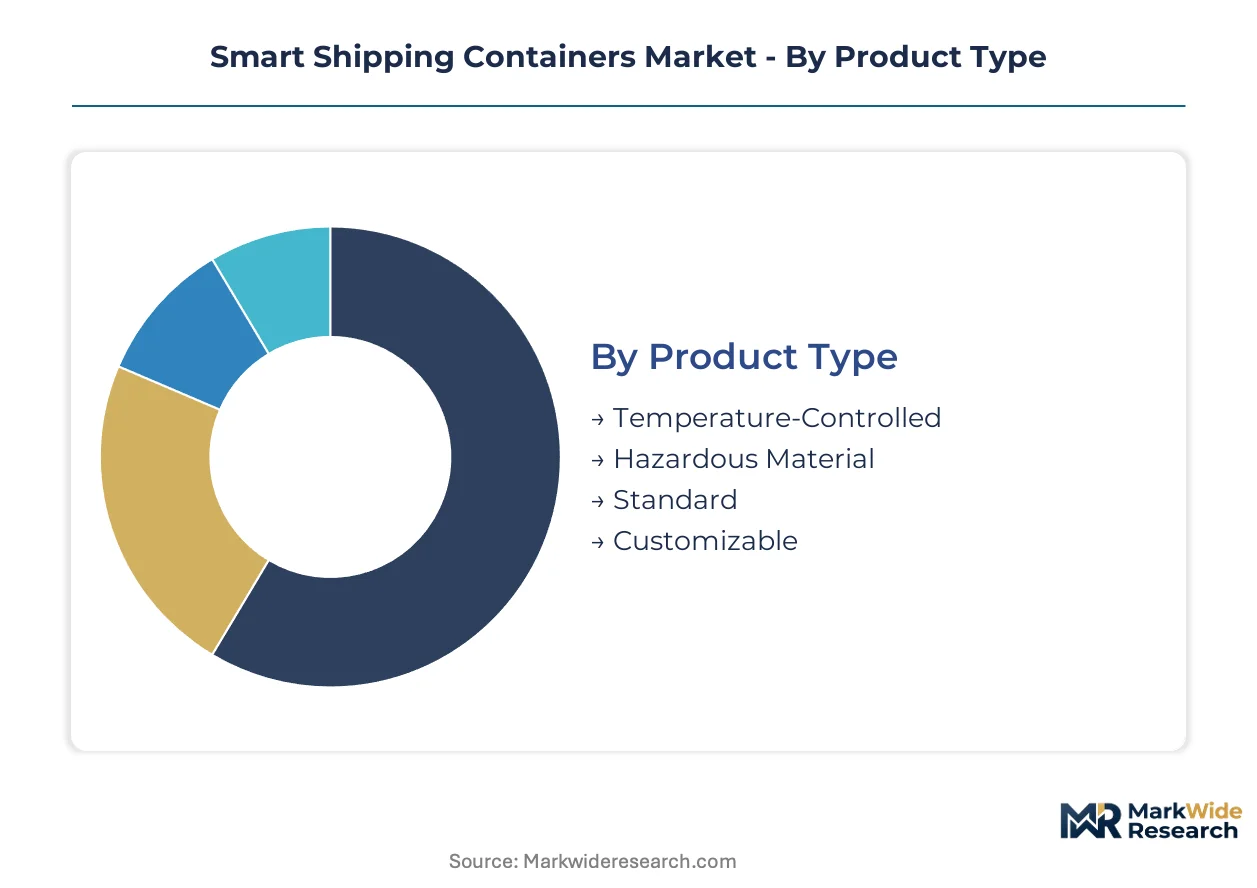
Segmentation in smart shipping containers reveals how hardware specifications, connectivity architectures, and operational deployment models align with distinct cargo risk profiles and regulatory compliance burdens across multimodal supply chains.
Product Type:
Use-case spectrum spans from precision cold-chain pharmaceuticals to bulk commodity freight, with sensor density and environmental control sophistication scaling directly with cargo value density and spoilage risk.
- Temperature-Controlled:Refrigerated units integrate multi-point thermal sensors, compressor telemetry, and automated defrost logging to maintain 2-8°C or -20°C setpoints for biologics and vaccines. Demand concentrates at Germany's Hamburg-Bremerhaven cluster where EU F-Gas Regulation mandates refrigerant emission compliance upgrades.
- Hazardous Material:Explosion-proof sensor housings and intrinsically safe telemetry gateways monitor pressure, vapor concentration, and container integrity for chemical and flammable cargo. German chemical shippers along the Rhine corridor deploy these units under ECHA REACH documentation requirements.
- Standard:Basic GPS location and shock detection for dry cargo with minimal environmental sensitivity.
- Customizable:Modular sensor arrays configurable for project cargo, oversized equipment, or specialized agricultural products.
Established volume favors Standard; emerging adoption favors Temperature-Controlled.
Technology:
Cost tier determines whether fleets deploy legacy identification tags or full telemetry stacks with edge computing and satellite backhaul.
- RFID:Passive and active radio-frequency tags provide gate-level identification and yard inventory management without continuous connectivity. European rail terminals use these for cost-efficient handoff verification between maritime and inland corridors.
- GPS:Satellite positioning transponders enable real-time location tracking across ocean and land routes. Maritime carriers favor these for vessel stow planning and customs pre-clearance at US ports under Coast Guard scrutiny.
- IoT Sensors:Multi-parameter environmental monitoring for temperature, humidity, shock, and light intrusion. Pharmaceutical distributors demand these for FDA-import documentation at American entry points.
- Telemetry:Integrated gateways combining sensor fusion, edge processing, and cellular/satellite transmission. These command premium positioning where continuous data streams support outcome-based freight contracts.
RFID and GPS anchor fleet-wide deployment economics; IoT Sensors and Telemetry capture steepest expansion trajectory as pharmaceutical documentation requirements tighten.
End User:
Customer type dictates data ownership models and integration complexity with existing enterprise resource planning systems.
- Logistics Providers:Third-party freight forwarders and ocean carriers deploying fleet-wide visibility platforms across multiple shipper accounts. These stakeholders face the sharpest pressure from IMO container weighing mandates and multimodal handoff accountability gaps.
- Retailers:Large apparel and electronics distributors tracking high-value inventory from Asian manufacturing clusters to European distribution centers.
- Manufacturers:Industrial shippers monitoring inbound component supply chains and outbound finished goods with just-in-time delivery constraints.
- Food Distributors:Perishable supply chain operators requiring temperature logging for FDA and EU food safety compliance.
Logistics Providers dominate installed base; Food Distributors are climbing the fastest as fresh produce traceability regulations harden.
Deployment:
Infrastructure maturity separates captive data centers from flexible cloud architectures and field-mobile access models.
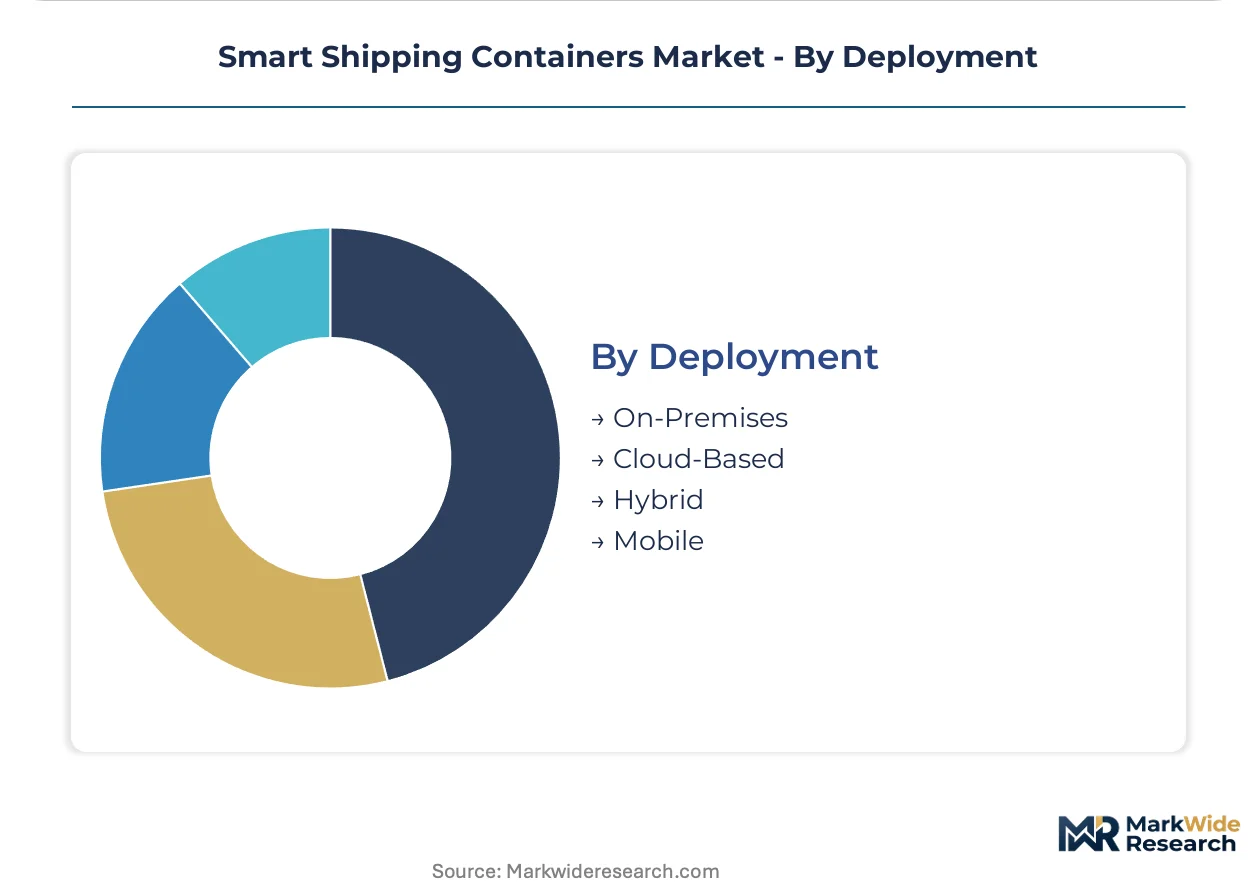
- On-Premises:Dedicated server installations within carrier or shipper facilities for maximum data sovereignty and latency control. Large German container lessors prefer these for Hamburg-Bremerhaven fleet operations under strict EU data residency requirements.
- Cloud-Based:Scalable SaaS platforms aggregating telemetry from dispersed container fleets. These reduce capital burden for mid-size logistics providers seeking rapid deployment.
- Hybrid:Split architectures processing sensitive cargo data locally while pushing non-critical analytics to public cloud infrastructure.
- Mobile:Smartphone and tablet applications enabling field personnel to access container status during port inspections and last-mile handoffs.
Cloud-Based deployment gains share fastest among new entrants; On-Premises retains preference at major European port operators with legacy systems integration requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive dry-cargo operators in Southeast Asia resist sensor premiums, while pharmaceutical shippers in Germany and the United States absorb hardware costs without volume elasticity. This demand bifurcation shapes regional deployment patterns.
United States
FDA import scrutiny at major entry ports drives pharmaceutical distributors to mandate continuous temperature logging. The US Coast Guard enforces container weighing verification through automated telemetry systems. Los Angeles-Long Beach port complex sees fastest IoT reefer adoption for biologics inbound from Asian manufacturing clusters.
Germany
EU F-Gas Regulation refrigerant emission limits force Hamburg-Bremerhaven operators into compliant temperature-control upgrades. ECHA REACH documentation requirements govern chemical cargo sensor deployments along Rhine corridor routes. Bavarian pharmaceutical exporters anchor premium reefer demand for trans-Atlantic cold-chain lanes.
China
NMPA cold-chain integrity rules for vaccine exports accelerate sensor-native container orders at Shanghai-Ningbo port cluster. MIIT IoT standards push domestic telemetry gateway adoption across state-owned carrier fleets. Pearl River Delta electronics manufacturers deploy shock-monitoring units for high-value component shipments to European distribution centers.
India
CDSCO pharmaceutical export documentation mandates create first-mover incentive for reefer sensor integration at Mumbai-JNPT port. DGFT traceability requirements extend to perishable agricultural shipments from Gujarat processing zones. Telangana-based vaccine manufacturers contract dedicated cold-chain container pools for Middle East and African lane expansion.
Singapore
Strategic transshipment hub status drives neutral data aggregator platforms serving multi-carrier fleets. Maritime and Port Authority certification requirements shape telemetry hardware specifications for vessels calling Southeast Asian lanes. Jurong Port pharmaceutical logistics zone concentrates regional cold-chain container maintenance and calibration services.
Smart Shipping Containers Market Competitive Environment
Capability concentration sits with telemetry platform specialists; scale advantage sits with ocean carrier captive fleets. The market structures around three tiers: neutral data service providers, carrier-integrated hardware deployers, and equipment manufacturer technology divisions. Strategic moves center on API ecosystem partnerships and predictive maintenance subscription models.
Within the satellite-connectivity tier, ORBCOMM exemplifies recurring-service margin architecture. Traxens anchors European rail-maritime corridor integration through proprietary mesh-network positioning. Globe Tracker occupies the open-architecture vector, enabling third-party logistics software integration through standardized API frameworks.
| Leading Market Players |
|---|
| ORBCOMM |
| Traxens |
| Globe Tracker |
| MSC |
| Sealand-A Maersk Company |
| Nexxiot AG |
| Smart Containers Group |
| CMA CGM Group |
| CIMC Smart Technologies |
| Others |
Value Chain & Pricing Dynamics
The Hamburg-Bremerhaven corridor's reefer modernization surge concentrates pricing power among German port operators facing EU F-Gas Regulation compliance deadlines, while downstream pharmaceutical distributors absorb sensor premiums without volume elasticity and dry-cargo operators in Southeast Asia resist hardware costs entirely.
Pricing Analysis
Long-term offtake contracts dominate temperature-controlled fleet deployments, with pharmaceutical shippers locking multi-year telemetry subscriptions to secure FDA-import documentation compliance. Price differentiation rests on IEC 62443 cybersecurity certification tiers and satellite connectivity redundancy levels. Cost compression in standard dry-cargo segments is intensifying because steel price volatility squeezes retrofit margins for box lessors. Food distributors exhibit highest price sensitivity, while cold-chain biologics shippers show minimal elasticity.
Supply Chain Analysis
Export-control regimes on dual-use GPS and satellite communication components limit telemetry gateway flows from US and EU suppliers to Chinese equipment manufacturers. Hardware assembly concentrates in China, South Korea, and Germany. Raw material dependencies include steel enclosures, lithium battery cells, and narrowband satellite transceiver modules. Single-source vulnerability in southern ocean satellite coverage creates data blackouts on key maritime routes. Distribution runs through ocean carrier captive fleets and neutral data aggregator platforms serving multi-shipper accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of IEC 62443-certified cybersecurity engineering talent constrains product validation timelines, compressing competitive windows for container telemetry platform launches and favoring incumbents with established certification pathways.
For Market Incumbents: Pre-empt emerging API standardization by anchoring open-architecture partnerships with third-party logistics software ecosystems before interoperability protocols consolidate. Backward integration into edge-computing gateway manufacturing reduces exposure to semiconductor supply shocks. Lock long-term satellite bandwidth contracts to defend recurring-service margins against connectivity cost volatility. For New Entrants and Emerging Players: India's Mumbai-JNPT pharmaceutical export corridor offers underpenetrated sensor-native reefer deployment potential ahead of CDSCO documentation mandate enforcement. Target mesh-network hardware for European rail-maritime convergence corridors where seamless handoff data fragments incumbent platforms. Pursue white-label telemetry partnerships with regional container lessors lacking captive IoT development capabilities. For Investors and Strategic Acquirers: Carve-out targets emerge from ocean carrier technology divisions with stranded IoT assets outside core shipping operations. Five-to-ten year viability hinges on subscription revenue durability from predictive maintenance platforms rather than hardware shipment cyclicality. Monitor FDA enforcement intensity at US entry ports as inflection indicator for pharmaceutical cold-chain hardware demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Partnership | Open-architecture integration with SAP and Oracle logistics platforms accelerates third-party software adoption. |
| Predictive Maintenance Platform Launch | Recurring SaaS revenue from compressor telemetry analytics reshapes container lessor profit pools. |
| Edge Computing Gateway Deployment | Container-mounted anomaly detection reduces satellite bandwidth costs for high-frequency monitoring routes. |
| IEC 62443 Certification Investment | Cyber-physical security compliance extends product validation cycles but creates regulatory moats. |
| Mesh-Network Rail Integration | Seamless data handoffs between European inland corridors and deep-sea terminals reduce fragmentation. |
Study Parameters
Cross-validation between primary interviews with fleet operations directors and secondary customs trade data anchors the qualitative findings on reefer deployment patterns. Stakeholder consultations included container lessor procurement heads, maritime carrier technology officers, pharmaceutical supply chain managers, and port authority logistics planners. Secondary sources encompassed IMO regulatory filings, EU F-Gas Regulation implementation reports, FDA import alert databases, and SEC disclosures from listed equipment manufacturers. Bottom-up sensor deployment counts triangulate against top-down fleet modernization expenditure estimates.
Calibration against historical reefer replacement cycles and pharmaceutical cold-chain investment trajectories shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, connectivity technology tier, end-user vertical, and deployment architecture. CAGRs derive from fitted growth curves on sensor penetration rates within temperature-controlled fleet segments. Industry-specific inputs incorporate EU refrigerant phase-out schedules and NMPA vaccine export documentation timelines.
Practitioners should monitor IEC 62443 certification backlog durations and satellite constellation expansion announcements for early signals of supply constraint easing. Forecasts reflect assumptions on regulatory enforcement consistency and steel price stabilization. Material shifts in FDA import scrutiny intensity or EU F-Gas Regulation compliance deadline extensions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Middle East and Africa Freight & Logistics Market
Logistics and Shipping
Sustainable Logistics Market
Logistics and Shipping
Kazakhstan Freight and Logistics Market
Logistics and Shipping
Renewable Resources Logistics Market
Logistics and Shipping
Mexico Freight and Logistics Market
Logistics and Shipping
Latin America Cold Chain Logistics Market
Logistics and Shipping
India less than Truckload Road Freight Transport Market
Logistics and Shipping
Jordan Freight and Logistics Market
Logistics and Shipping
Cambodia Freight and Logistics Market
Logistics and Shipping
ISO Shipping Container Market
Logistics and Shipping
Mexico Logistics Market
Logistics and Shipping
North America Pharmaceutical Logistics Market
Logistics and Shipping
Total Logistics Market
Logistics and Shipping
Europe Refrigerated Container Shipping Market
Logistics and Shipping
United Arab Emirates (UAE) Third-Party Logistics (3PL) Market
Logistics and Shipping
Japan Cross-Border E-Commerce Logistics Market