
 North America Electric Vehicle Thermal Management System Market | 2026-2036
North America Electric Vehicle Thermal Management System Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electric Vehicle Thermal Management System Market Analytics
OEM-direct supply contracts is rewriting how thermal system vendors reach vehicle programs in North America. BorgWarner Inc. leverages its power electronics heritage to bundle inverter-cooling modules with battery thermal hardware. Dana Limited anchors its position through in-house production of cooling plates and gaskets for electric axle programs. Valeo competes by extending its European heat pump designs into North American climate extremes.
An electric vehicle thermal management system regulates battery, motor, and power electronics temperatures through liquid coolant loops, refrigerant circuits, and phase change materials operating between negative forty and one hundred twenty degrees Celsius. Its primary purpose is preventing thermal runaway in lithium-ion packs while maintaining optimal discharge rates across ambient conditions. Liquid cooling technology dominates OEM factory-installed programs due to its heat flux capacity, while phase change materials represent the fastest-growing technology segment as solid-state battery architectures demand passive stabilization. Active systems capture the largest value pool, though modular retrofitted installations for aftermarket fleet conversions are gaining traction among commercial operators seeking to extend vehicle service life.
The EPA tailpipe emissions standards and NHTSA fuel economy rules compel OEMs to optimize every kilowatt-hour of battery capacity, directly expanding thermal system content per vehicle. The Inflation Reduction Act's domestic content requirements further shape sourcing decisions, pushing suppliers to localize coolant pump and heat exchanger manufacturing within the United States, Canada, or Mexico. Stakeholders must monitor how state-level zero-emission vehicle mandates in California and its Section 177 allies cascade into thermal system specification changes before federal rules tighten.
Market Dynamics
The EPA tailpipe emissions standards and Inflation Reduction Act domestic content rules are forcing OEMs to redesign thermal architectures around localized supply chains and higher heat-flux battery chemistries.
Growth Catalysts
- IRA Clean Vehicle Tax Credits:Domestic assembly requirements push automakers to source coolant pumps and heat exchangers from U.S., Canadian, or Mexican facilities, expanding regional manufacturing capacity.
- Fleet electrification mandates:California's Advanced Clean Trucks regulation and its Section 177 allies in New York, New Jersey, and Oregon compel commercial operators to adopt liquid-cooled battery packs for medium- and heavy-duty vehicles.
- Solid-state battery prototyping:Next-generation cell architectures demand passive thermal stabilization through phase change materials, opening new specification categories for thermal system vendors.
Market Restraints
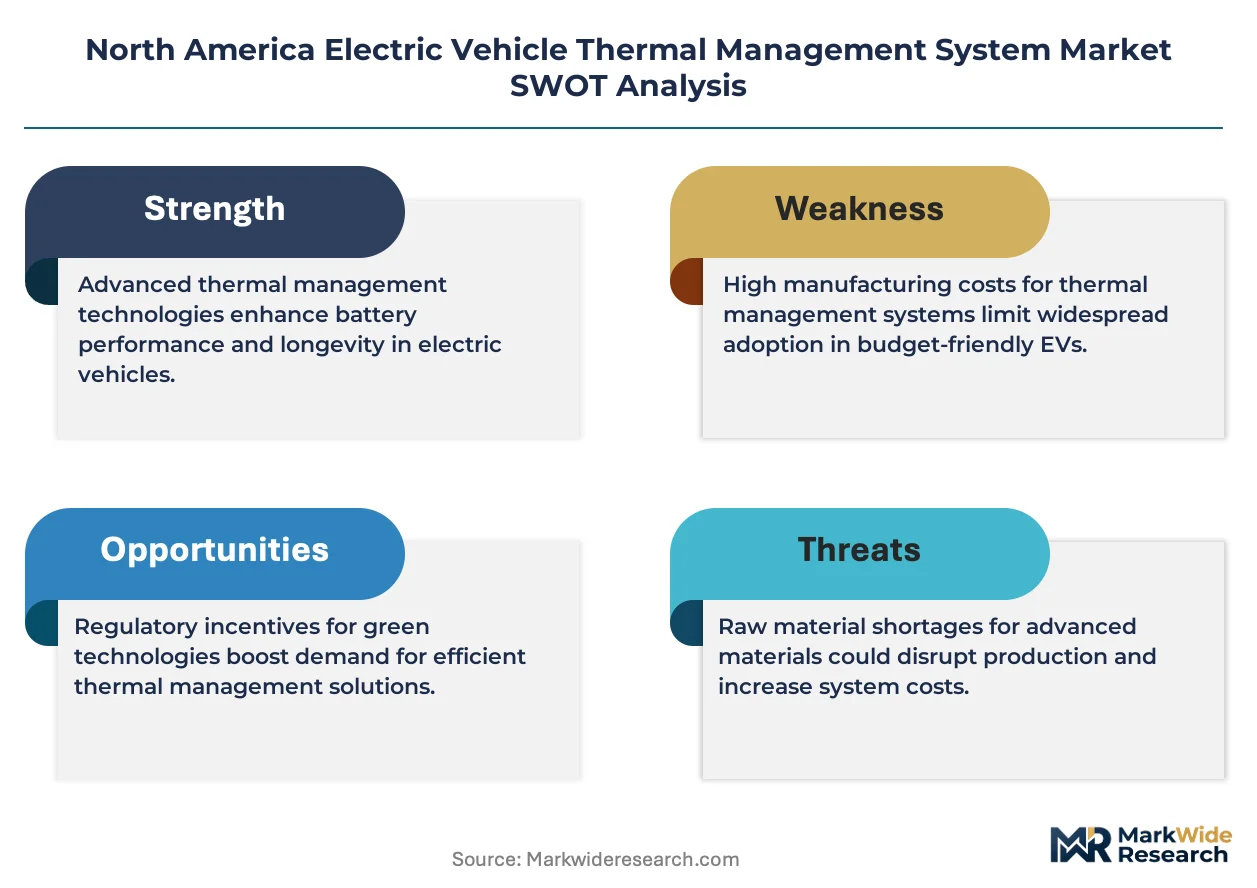
- Copper and aluminum price volatility:Heat exchanger and cooling plate production faces margin compression from commodity input swings, squeezing tier-two suppliers without long-term hedging contracts.
- Single-source pump motor dependencies:Rare earth magnet supply concentrates in processing facilities outside North America, creating vulnerability in high-efficiency coolant circulation systems.
- Refrigerant capacity constraints:The EPA Significant New Alternatives Policy limits high-global-warming-potential working fluids, forcing costly retooling of refrigerant circuit designs before low-GWP alternatives scale.
Strategic Opportunities
- Aftermarket fleet retrofits:Commercial operators in Texas and Florida seek modular thermal upgrades to extend service life of first-generation electric delivery vans, creating a channel outside OEM-direct contracts.
- Heat pump convergence with cabin HVAC:Integrated thermal circuits that combine battery conditioning with passenger comfort reduce component count and assembly complexity for crossover and SUV platforms.
- Canadian critical minerals processing:Ontario and Quebec battery material refining investments position suppliers to meet IRA domestic content thresholds for thermal management hardware.
Industry Challenges
- Thermal-fluid engineering talent scarcity:OEMs and tier-one suppliers compete for specialists in two-phase heat transfer and battery cell-level simulation, slowing product development cycles.
- UL 2580 certification timelines:Battery pack thermal runaway propagation testing creates bottlenecks as third-party labs face backlog for abuse testing and documentation review.
- Legacy vehicle platform integration:Thermal system suppliers must adapt designs to existing stamping and assembly fixtures originally engineered for internal combustion architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electric Vehicle Thermal Management System Market |
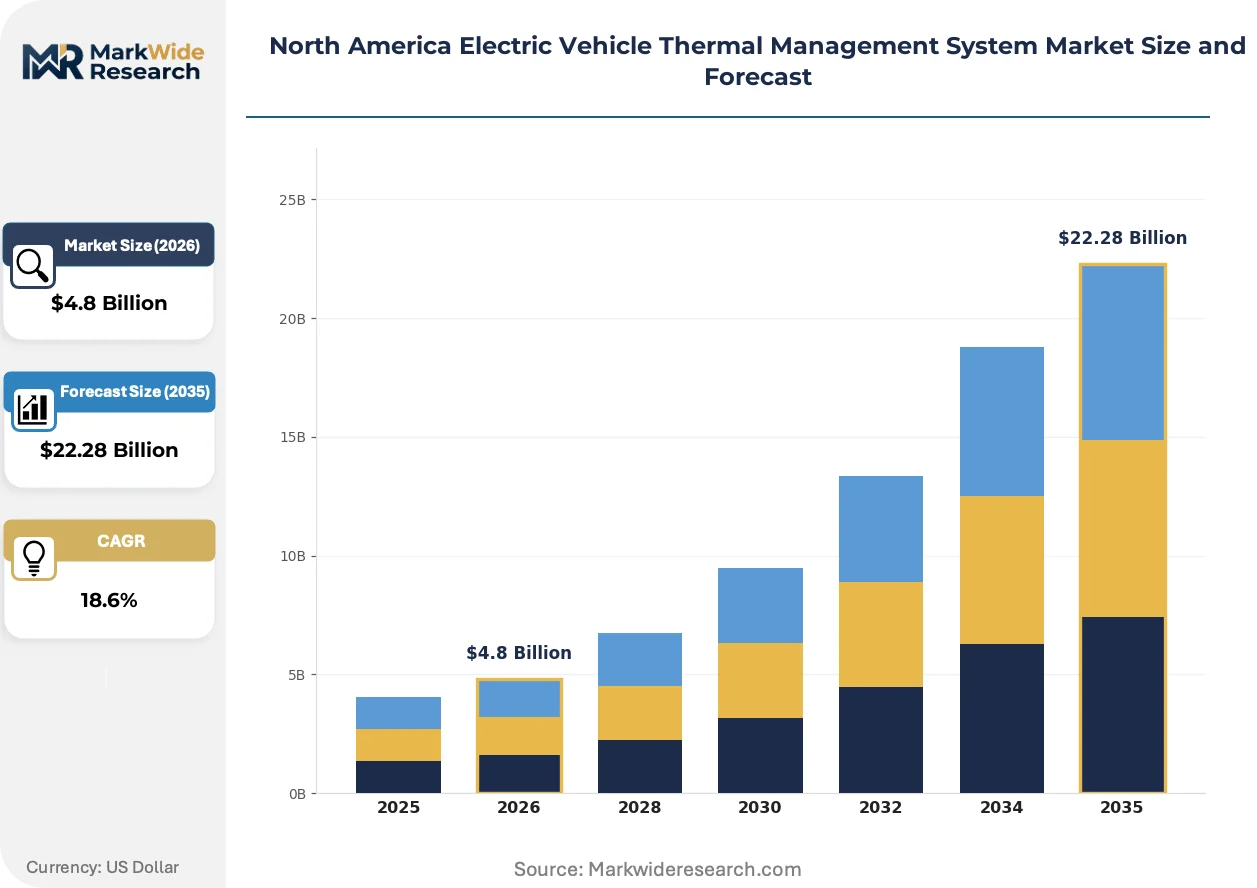
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Systems, Passive Systems, Coolant Pumps, Heat Exchangers Technology: Liquid Cooling, Air Cooling, Refrigeration, Phase Change Materials End User: OEMs, Aftermarket Providers, Fleet Operators, Research Institutions Installation: Integrated, Retrofitted, Factory-installed, Modular |
| Companies Covered | MAHLE GmbH, Valeo, Dana Limited, Hanon Systems, Robert Bosch GmbH, BorgWarner Inc., Continental AG, DENSO Corporation, GENTHERM, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electric Vehicle Thermal Management System Market Evolving Landscape
Heat pump architectures and refrigerant circuit integration are compressing the traditional separation between powertrain thermal management and passenger climate control into unified system designs.
Immersion cooling using dielectric fluids is collapsing the distinction between cell-level and pack-level thermal control. Battery startups in Michigan and California are piloting direct-contact cooling for high-nickel cathode formulations. This approach is collapsing the need for separate cold plates and complex coolant routing, reducing part count and assembly labor in gigafactory lines.
The EPA Significant New Alternatives Policy and parallel Environment and Climate Change Canada regulations are accelerating refrigerant transitions. OEMs must qualify low-global-warming-potential alternatives like R-1234yf and CO2-based systems for heat pump duty cycles. The commercial vehicle segment faces the steepest compliance curve, as existing service infrastructure must adapt to handling and recovery protocols for new working fluids.
Fleet operators are consolidating procurement decisions at the holding-company level rather than individual depot authority. Large logistics networks in Illinois and Pennsylvania now specify thermal system performance warranties across multi-year vehicle supply agreements. This concentration is visible most acutely in last-mile delivery, where Amazon, UPS, and FedEx vehicle programs drive standardization of cooling capacity ratings and service interval protocols.
North America Electric Vehicle Thermal Management System Market Segmentation
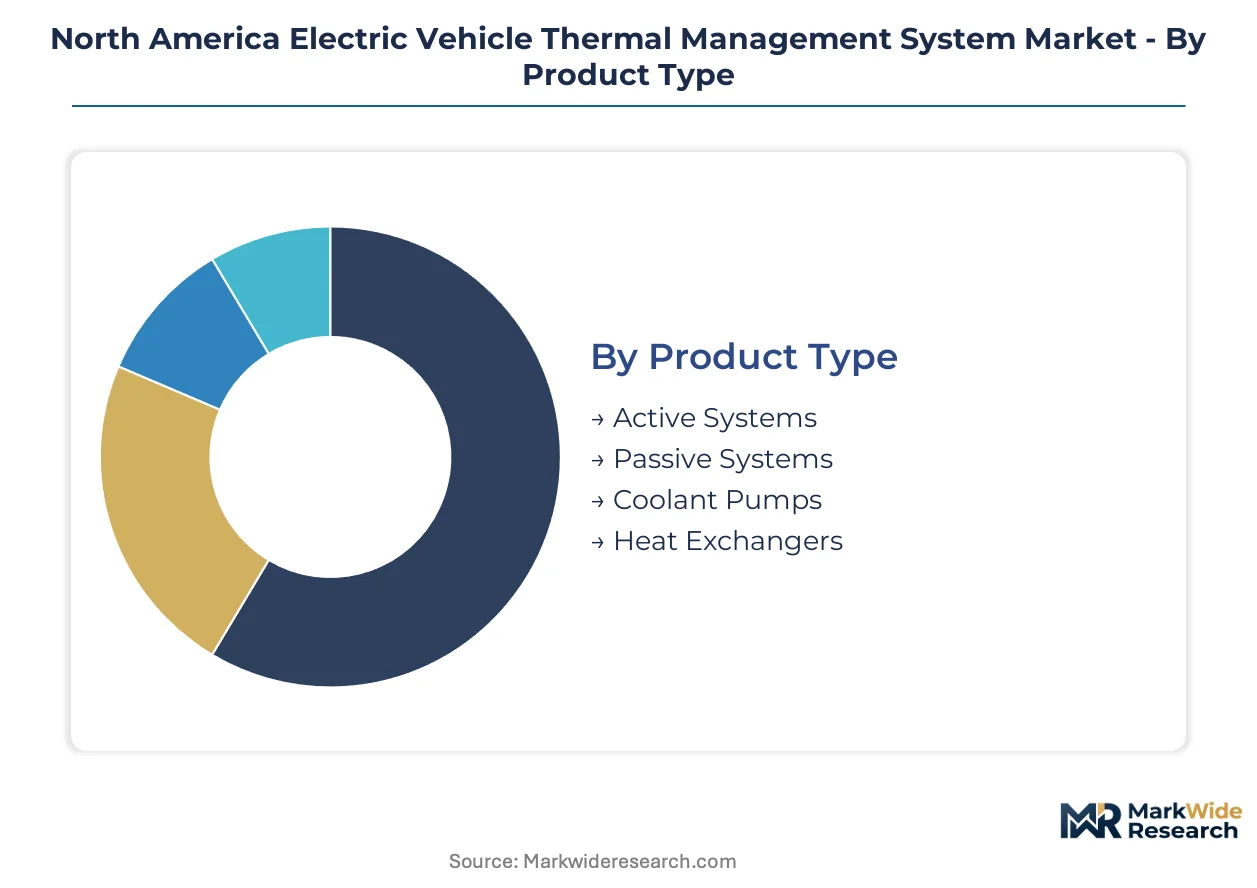
Thermal management architectures diverge sharply across vehicle programs based on cooling load requirements, battery chemistry, and integration depth with powertrain platforms. Segment boundaries reflect how OEMs balance factory-installed precision against aftermarket flexibility for fleet conversions.
Product Type:
Cost tier determines supplier margin structure and contract duration across the hardware spectrum.
- Active Systems:Pump-driven coolant loops and compressor-based refrigeration circuits manage high heat-flux battery packs and power electronics. Michigan and California OEM programs specify these for premium electric trucks and performance sedans facing extreme ambient temperature cycles.
- Passive Systems:Conductive cooling plates and natural convection heat sinks operate without parasitic energy draw. Texas and Florida fleet operators retrofit these into first-generation delivery vans to extend thermal stability without electrical system upgrades.
- Coolant Pumps:Brushless DC circulation units with rare-earth magnet motors dominate factory specifications.
- Heat Exchangers:Aluminum-brazed plate-and-fin designs anchor liquid-to-liquid thermal transfer.
Active systems command the established base. The steepest expansion runs through modular retrofit configurations for commercial vehicle life extension.
Technology:
Application heat flux density and operating temperature range dictate technology selection across passenger and commercial platforms.
- Liquid Cooling:Ethylene-glycol or dielectric fluid circuits extract heat from cell surfaces through cold plate contact or direct immersion. High-nickel cathode formulations in Michigan-assembled battery packs require this approach to prevent thermal runaway propagation during fast-charging events.
- Phase Change Materials:Paraffin or salt-hydrate compounds absorb latent heat at constant temperature during transient thermal spikes. Solid-state battery prototyping programs in California and Ontario specify these for passive stabilization where active circulation adds complexity.
- Air Cooling:Forced convection through finned heat sinks serves low-power auxiliary systems.
- Refrigeration:Vapor-compression circuits handle cabin HVAC and battery conditioning convergence.
Liquid cooling dominates installed capacity. Phase change materials are climbing the fastest as next-generation cell architectures enter validation.
End User:
Customer procurement authority shapes warranty terms, service interval specifications, and channel economics.
- OEMs:Vehicle manufacturers integrate thermal hardware at the platform engineering stage, specifying coolant flow rates and refrigerant charge capacities across model generations. Ford, General Motors, and Stellantis programs in Michigan and Ontario source direct from tier-one suppliers under multi-year blanket orders with IRA domestic content compliance.
- Fleet Operators:Consolidated holding-company procurement in Illinois and Pennsylvania now drives standardization of cooling capacity ratings and thermal performance warranties across multi-vehicle supply agreements.
- Aftermarket Providers:Independent installers serve vehicle life extension and accident repair demand.
- Research Institutions:National laboratories and university programs validate emerging thermal architectures.
OEMs anchor volume commitments. Fleet operators are gaining share fastest as electrification mandates concentrate procurement authority.
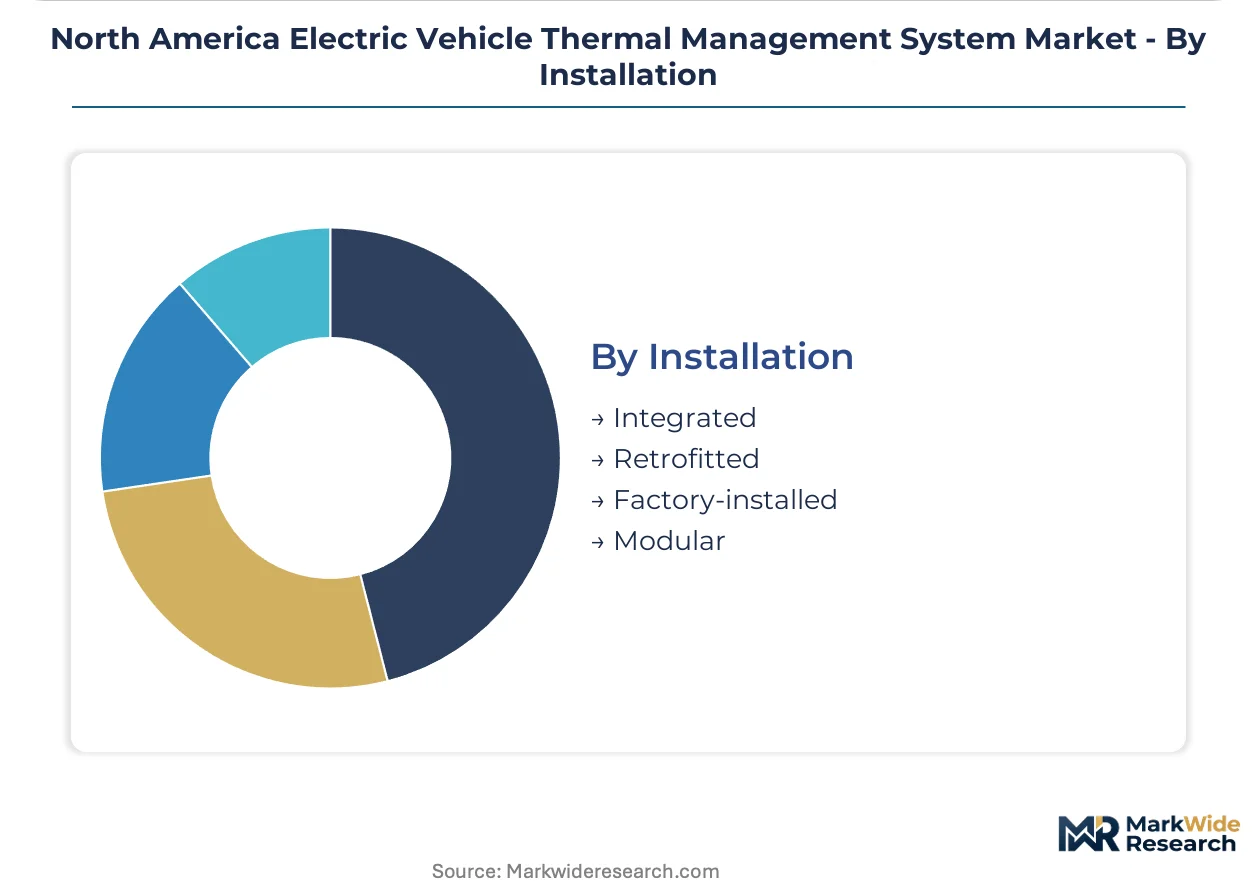
Installation:
Integration depth with vehicle architecture determines assembly labor, part count, and field serviceability.
- Factory-installed:Thermal systems engineered into original platform designs achieve optimal packaging density and refrigerant circuit integration. Crossover and SUV programs from Detroit and Ontario manufacturers specify unified battery-cabin HVAC circuits to reduce component count and assembly complexity.
- Modular:Self-contained thermal units with standardized plumbing interfaces enable rapid field installation. Texas and Florida commercial operators deploy these for electric delivery van conversions where OEM thermal specifications prove inadequate for regional climate loads.
- Integrated:Deep architectural fusion with powertrain and chassis systems.
- Retrofitted:Post-manufacture addition to existing vehicle platforms.
Factory-installed configurations hold the revenue base. Modular formats are expanding most quickly through aftermarket fleet electrification channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Michigan-based OEM programs command premium pricing for liquid-cooled battery packs, while Mexican manufacturing clusters undercut component costs by fifteen to twenty percent. This asymmetry is reshaping procurement patterns across the continent.
United States
Fleet electrification mandates in California and New York drive demand for medium-duty truck thermal systems. EPA tailpipe emissions standards compel OEMs to optimize battery thermal efficiency. Michigan and California battery assembly clusters concentrate coolant pump and heat exchanger sourcing decisions.
Canada
Ontario and Quebec critical minerals refining investments position suppliers to meet IRA domestic content thresholds. Environment and Climate Change Canada refrigerant regulations accelerate low-GWP working fluid transitions. Windsor-Toronto corridor battery material processing facilities anchor thermal hardware manufacturing.
Mexico
Nearshoring of heat exchanger and cooling plate production expands capacity for U.S. OEM programs. Mexican federal manufacturing incentives attract tier-two suppliers seeking cost advantages. Nuevo León and Bajío Region automotive clusters integrate thermal component assembly into existing powertrain supply chains.
North America Electric Vehicle Thermal Management System Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in cooling plates and circulation hardware. The vendor base splits between diversified automotive suppliers with powertrain heritage and dedicated thermal engineering houses. Two strategic archetypes dominate: bundlers leveraging inverter-cooling synergies, and modular retrofit specialists serving fleet conversion demand. Competitive moves concentrate on capacity localization for IRA compliance and refrigerant circuit retooling for EPA SNAP alignment.
Within the diversified automotive tier, MAHLE GmbH, Dana Limited, and BorgWarner Inc. exemplify contrasting positioning strategies. MAHLE represents the European-heritage system integrator archetype. Dana Limited anchors North American axle-thermal convergence. BorgWarner occupies the power electronics bundling position. These three illustrate how thermal management capability now merges with adjacent powertrain domains rather than standing as isolated component categories.
| Leading Market Players |
|---|
| MAHLE GmbH |
| Valeo |
| Dana Limited |
| Hanon Systems |
| Robert Bosch GmbH |
| BorgWarner Inc. |
| Continental AG |
| DENSO Corporation |
| GENTHERM |
| Others |
Value Network & Pricing Analysis
Nuevo León manufacturing clusters anchor heat exchanger capacity for U.S. OEM programs, translating fifteen to twenty percent cost advantages into tier-two supplier pricing power downstream. Copper and aluminum commodity swings compress margins for cooling plate producers without long-term hedging, while IRA domestic content rules reshape procurement toward Michigan and Ontario facilities.
Pricing Analysis
Configured-to-order thermal systems command substantial premiums over standard catalog pricing for fleet operators with specialized duty cycles. Three-tier pricing structure across premium, standard, and economy levels separates OEM-direct factory programs from modular retrofit configurations and aftermarket replacement parts. Cost compression in aluminum-brazed heat exchangers is intensifying because Mexican nearshoring expands capacity faster than demand absorption. Fleet procurement teams at consolidated logistics networks exhibit highest price sensitivity, while OEM platform engineering groups prioritize thermal performance warranties over unit cost.
Supply Chain Analysis
Extended payment terms from tier-one automotive suppliers now stretch sixty to ninety days, forcing tier-two pump motor and cooling plate manufacturers into supply-chain finance facilities. Manufacturing concentrates in Mexico, the United States, and Canada under USMCA alignment. Rare earth magnet processing for brushless DC pumps draws from facilities outside North America, creating single-source vulnerability in high-efficiency circulation systems. Distribution runs through OEM-direct blanket orders, fleet holding-company procurement agreements, and independent aftermarket channels serving accident repair demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized thermal-fluid engineering talent pools have contracted sharply, with OEMs and tier-one suppliers competing for finite specialists in two-phase heat transfer and cell-level simulation. This scarcity slows product development cycles and elevates compensation costs for qualified hires.
For Market Incumbents: Pre-empt emerging modular retrofit specialists by acquiring aftermarket distribution channels in Texas and Florida before fleet electrification mandates concentrate procurement authority further. In-house production of cooling plates and gaskets defends margin position against commodity volatility, while UL 2580 certification investment creates switching costs for OEM platform programs. For New Entrants and Emerging Players: Aftermarket fleet retrofits for first-generation electric delivery vans in high-heat climate zones represent the most penetrable entry point, with commercial operators seeking thermal upgrades without electrical system overhauls. Phase change material integration for solid-state battery prototyping programs in California and Ontario offers a second white-space target. Go-to-market execution should anchor on direct relationships with consolidated fleet holding companies rather than individual depot procurement. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because EPA tailpipe emissions standards and IRA domestic content rules embed thermal system demand into vehicle platform economics regardless of battery chemistry evolution. Acquisition targets should emphasize tier-two suppliers with captive heat exchanger or pump motor capabilities and established OEM-direct relationships. The signal to watch is backlog duration at third-party UL 2580 testing laboratories as a proxy for platform program launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Localization for IRA Compliance | Establishes qualified domestic content status for coolant pumps and heat exchangers sold into Michigan and Ontario OEM programs. |
| Refrigerant Circuit Retooling for EPA SNAP Alignment | Enables qualification of R-1234yf and CO2-based systems ahead of high-GWP working fluid phaseouts. |
| Backward Integration into Cooling Plate Production | Captures margin from aluminum-brazed components while hedging commodity price volatility exposure. |
| Heat Pump Convergence with Cabin HVAC | Reduces component count for crossover and SUV platforms from Detroit and Ontario manufacturers. |
| Aftermarket Fleet Retrofit Channel Development | Creates recurring revenue stream outside OEM-direct contracts as commercial operators extend vehicle service life. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with thermal system engineering directors, OEM platform procurement managers, fleet holding-company sustainability officers, and aftermarket distribution channel heads; and secondary validation through SEC 10-K filings, vehicle production databases, EPA regulatory dockets, and IHS Markit registration data. Bottom-up unit economics triangulated against top-down market sizing across active and passive system categories.
Forecast inputs span vehicle class, propulsion architecture, thermal content per vehicle, OEM tier positioning, and regional production cluster concentration. CAGRs were derived from segment-level growth trajectory modeling throughout the forecast period, incorporating battery chemistry transition timelines and fleet electrification mandate phase-in schedules. Phase change material adoption curves and heat pump penetration rates for crossover platforms anchored technology-specific projections.
Macroeconomic conditions sit as an overlay; deviation in copper and aluminum commodity indices, rare earth magnet supply availability, or federal zero-emission vehicle mandate timing would shift the trajectory. Forecasts reflect documented assumptions regarding IRA domestic content threshold interpretations and EPA SNAP refrigerant phaseout schedules. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Panoramic Sunroof Market
Electric Vehicles
Electric Vehicle Communication Controller Market
Electric Vehicles
Europe Wireless Electric Vehicle Charging Market
Electric Vehicles
Speed Pedelec E-Bike Market
Electric Vehicles
ASEAN EV Battery Pack Market
Electric Vehicles
Oman Electric Vehicle (EV) Market
Electric Vehicles
UK Electric Bus Battery Pack Market
Electric Vehicles
Recreational Vehicle (RV) Batteries Market
Electric Vehicles
Automotive Battery Powered Propulsion System Market
Electric Vehicles
Asia-Pacific Lithium-Ion Battery for Electric Vehicle Market
Electric Vehicles
Construction Electric Vehicle Market
Electric Vehicles
Automotive Battery Packs Market
Electric Vehicles
Solar Powered Electric Vehicle Market
Electric Vehicles
Electric Passenger Cars Market
Electric Vehicles
Electric Vehicle Electronic Expansion Valve (EXV) Market
Electric Vehicles
Global Electric Scooters Market