
 Romania Freight and Logistics Market | 2026-2036
Romania Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Romania Freight and Logistics Market Insights
The shift from single-source carrier contracts to multi-source logistics networks is repositioning how Romanian manufacturers secure freight capacity. FAN Courier leverages its domestic parcel density to control last-mile routes in urban centers. DB Schenker anchors cross-border rail and road corridors linking Romania to Central European hubs. DSV competes through integrated forwarding and contract logistics services serving automotive and industrial clients.
Romania freight and logistics encompasses the planning, execution, and management of goods movement via road, rail, air, and sea modalities, with road freight dominating tonnage throughput due to the country's extensive European route corridor connections and Black Sea port access. The primary commercial purpose centers on enabling trade flows between EU member states, Balkan markets, and Asian origins through the Constanta port gateway. Road freight leads service type revenue due to fragmented shipper demand and flexible routing, while e-commerce end users generate the fastest growth segment as domestic online retail penetration deepens. Third-party logistics channels capture expanding margin pools as manufacturers outsource fleet ownership and warehouse operations to specialized providers.
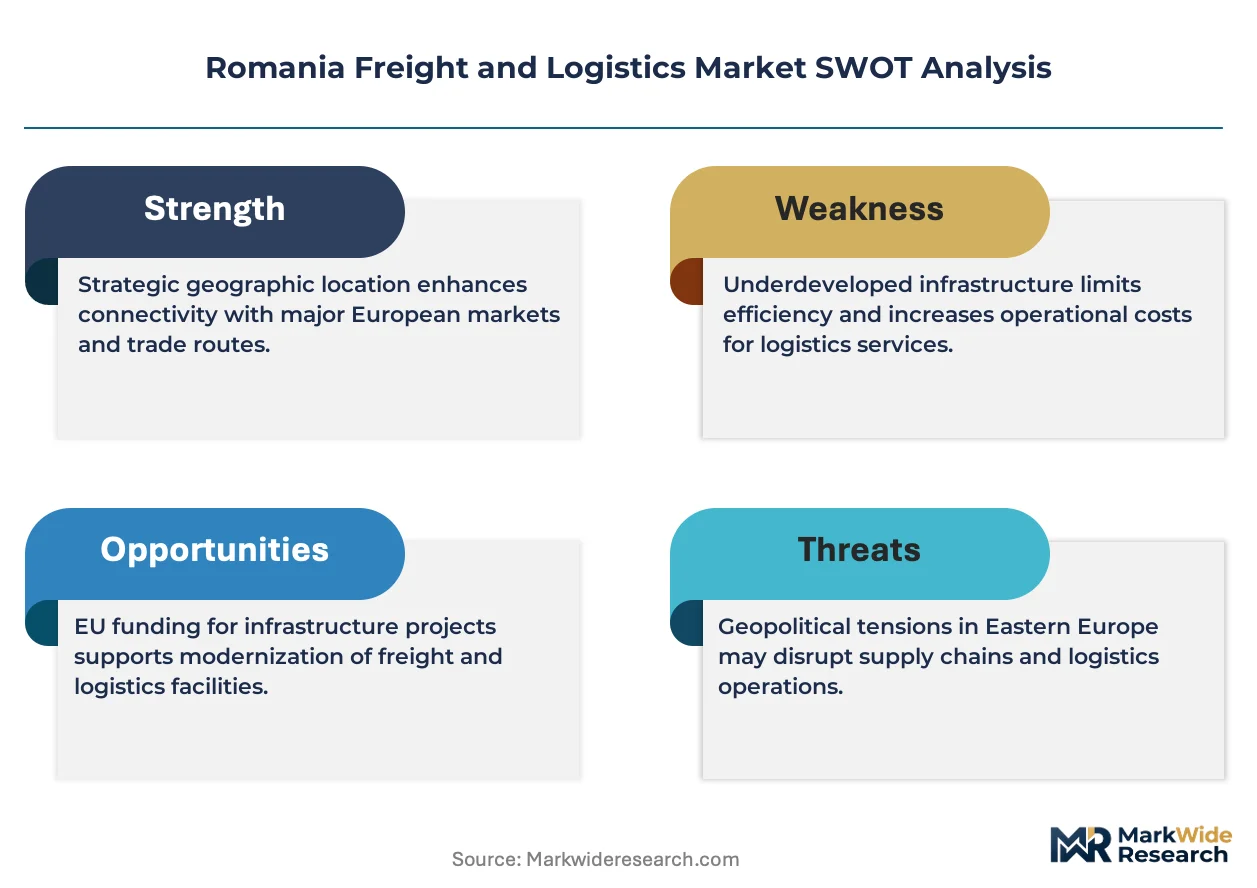
Romania's integration into EU regulatory frameworks subjects operators to EASA air cargo standards, EU Mobility Package driving and rest-time rules, and national road transport authority enforcement of cabotage limits. These regulations reshape fleet investment cycles, driver recruitment costs, and cross-border permit allocations for Romanian carriers. Stakeholders must monitor EU Green Deal freight decarbonization timelines and alternative fuel infrastructure commitments to anticipate compliance-driven asset replacement schedules.
Market Dynamics
Romania's freight sector is restructuring around EU Mobility Package compliance costs and the electrification of fleet assets, with operators recalibrating route economics and driver deployment models to absorb regulatory-driven cost step-ups.
Growth Catalysts
- EU Green Deal freight decarbonization timelines:The national road transport authority is accelerating alternative fuel infrastructure commitments, forcing fleet renewal toward electric and hydrogen-powered trucks.
- E-commerce fulfillment density:Domestic online retail penetration is deepening parcel volume throughput, pulling investment into automated sortation hubs and urban micro-fulfillment centers.
- Constanta port gateway expansion:Black Sea container terminal capacity upgrades are capturing Asian-origin trade flows, anchoring multimodal corridors toward Central European manufacturing belts.
Market Restraints
- Driver recruitment cost inflation:EU Mobility Package rest-time rules and cabotage limit enforcement have compressed available driving hours, escalating wage pressure for compliant operators.
- Diesel price volatility:Road freight's dependence on petroleum-based fuel exposes margins to energy market swings without hedging infrastructure among mid-sized carriers.
- Cross-border permit allocation scarcity:Bilateral road transport agreements limit Romanian carrier access to Western European markets, constraining revenue diversification.
Strategic Opportunities
- Transylvania manufacturing belt underpenetration:Cluj-Napoca and Timisoara industrial zones lack sufficient contract logistics capacity, creating white space for temperature-controlled and automotive parts warehousing.
- Rail-sea intermodal convergence:Integration of Constanta port feeder rail with inland terminal networks offers modal shift incentives for bulk commodity shippers.
- EU alternative fuel infrastructure deployment mandates:AFIR regulation funding streams support charging and hydrogen refueling station buildout along TEN-T corridor segments.
Industry Challenges
- Telematics and fleet management platform integration:Legacy dispatch systems require costly retrofitting to interface with EU-mandated digital tachograph and real-time tracking protocols.
- Certified hazardous goods handling capacity:ADR-licensed driver scarcity and specialized tanker equipment availability constrain chemical and fuel logistics expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Romania Freight and Logistics Market |
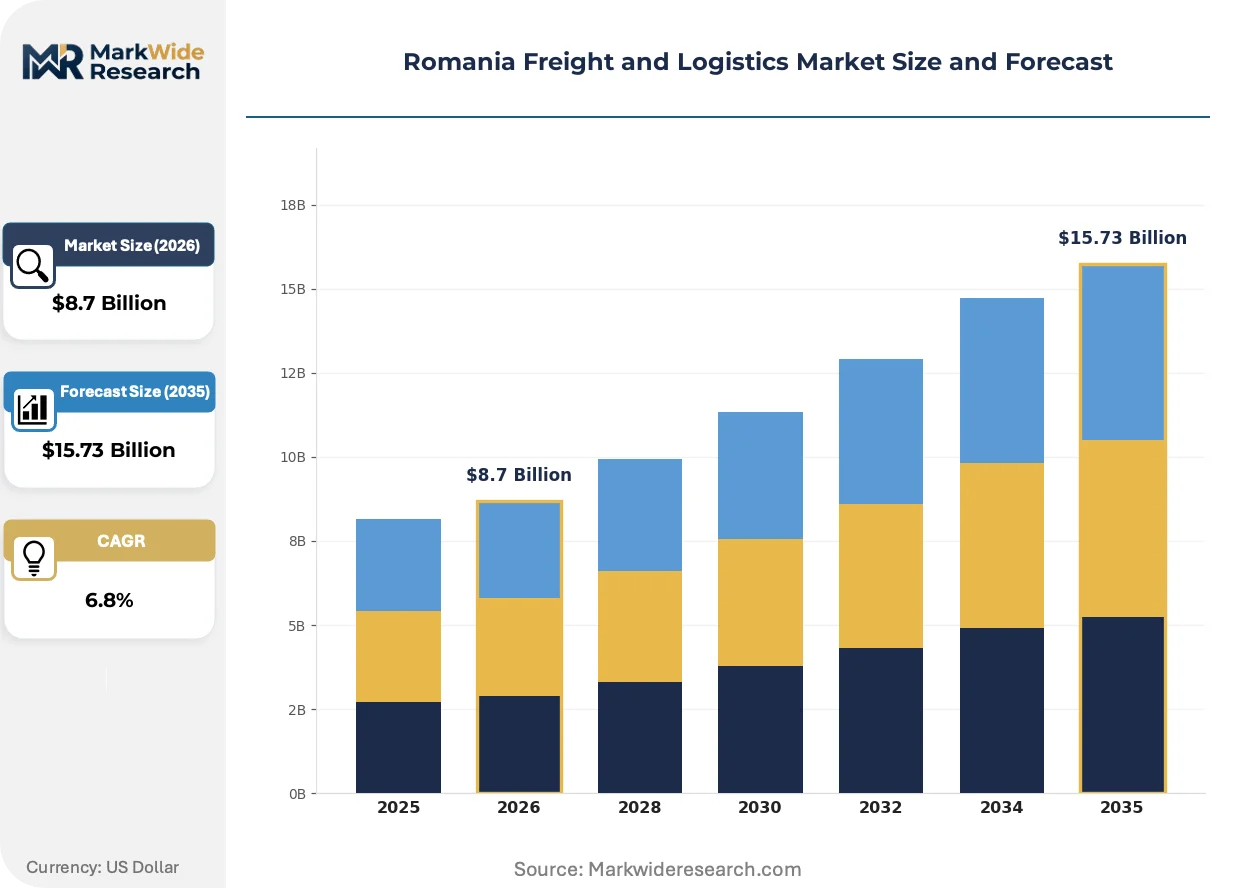
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Road Freight, Rail Freight, Air Cargo, Sea Freight End User: E-commerce, Manufacturing, Retail, Agriculture Technology: GPS Tracking, RFID, IoT Solutions, Warehouse Management Distribution Channel: Direct Shipping, Third-Party Logistics, Freight Forwarders, Warehousing |
| Companies Covered | Posta Romana, Urgent Cargus, The Maurice Ward Group, FAN Courier, Aquila Part Prod, Yusen Logistics, Sameday, DSV, DB Schenker, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Romania Freight and Logistics Market Trends and Innovations
Digital freight matching platforms and predictive cargo visibility tools are compressing information asymmetries between shippers and carriers, while alternative drivetrain adoption accelerates asset replacement cycles.
Telematics-enabled dynamic route optimization is overtaking static dispatch scheduling in long-haul operations. Major retail distributors are deploying AI-driven load consolidation algorithms across their Romanian networks. This compression of empty kilometers is enabling same-day delivery promises for urban consignments previously constrained by driver hour regulations.
The EU Mobility Package driving and rest-time rules are restructuring crew deployment economics. Fleet operators must now factor in mandatory return-to-home provisions and cabotage sequence restrictions when pricing cross-border lanes. Bucharest-based carriers are responding by establishing satellite driver pools in Hungary and Bulgaria to maintain lane utilization.
Shippers are consolidating vendor relationships around integrated 4PL contracts that bundle freight forwarding with customs brokerage and warehousing. Automotive component manufacturers in the Timisoara cluster are replacing fragmented spot-market purchasing with multi-year capacity commitments. This concentration of procurement authority is most visible among German-owned production facilities seeking supply chain audit uniformity.
Romania Freight and Logistics Market Segmentation
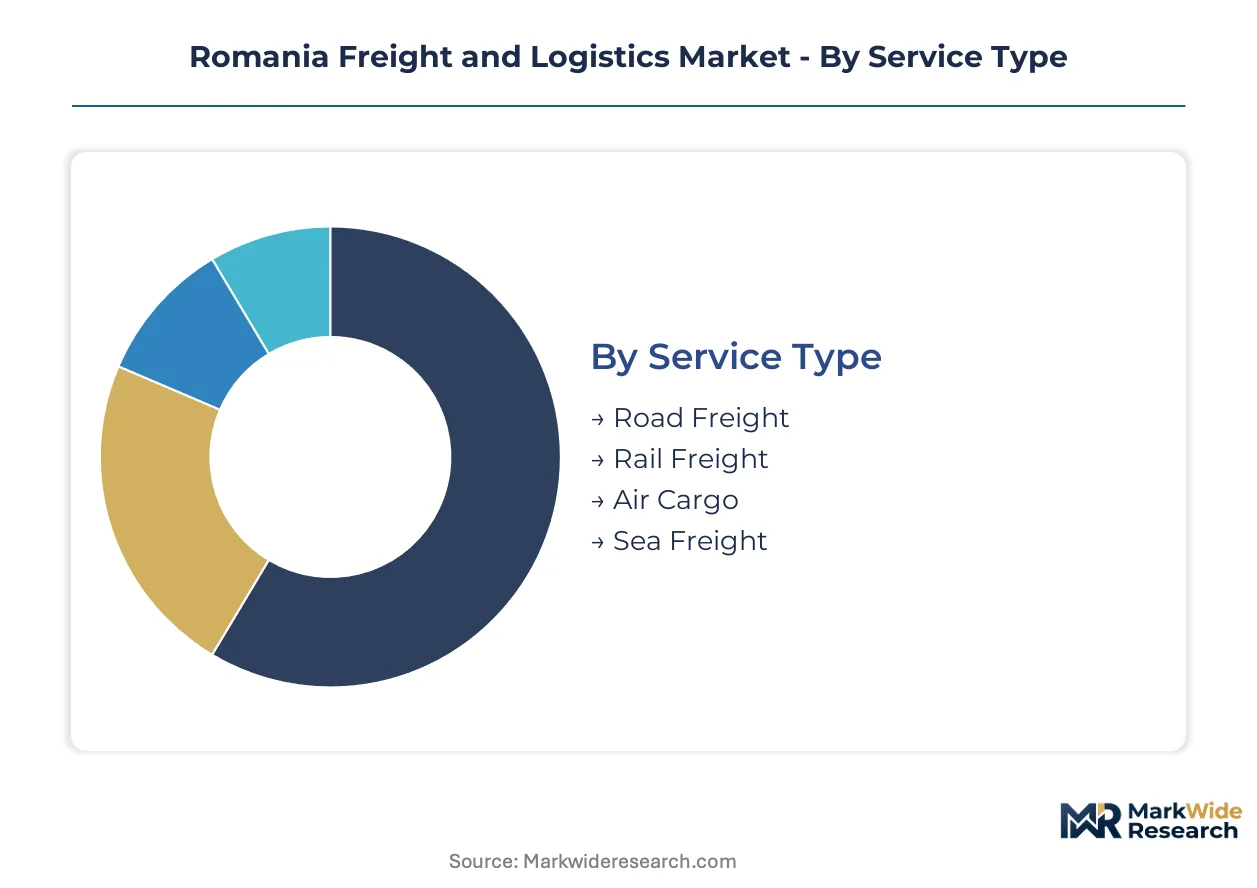
Romanian freight and logistics segmentation reveals how modal specialization and technology deployment create distinct margin pools. Shippers match service tiers to cargo value density and delivery velocity requirements.
Service Type:
Fleet replacement cycles differ sharply across modalities as EU Green Deal deadlines force asset turnover decisions.
- Road Freight:Flexible routing across TEN-T corridors enables just-in-time delivery for automotive and retail supply chains. Bucharest-Ilfov corridor carriers absorb the highest tonnage volumes, though driver hour restrictions under Mobility Package rules compress lane economics.
- Rail Freight:Bulk commodity movement and containerized intermodal flows dominate Constanta port feeder lines. Cluj-Napoca industrial shippers are shifting steel and chemical loads from road to rail to hedge diesel volatility.
- Air Cargo:High-value electronics and pharmaceutical cold chain shipments utilize Henri Coanda International Airport connections.
- Sea Freight:Black Sea container terminal capacity anchors Asian-origin import corridors toward Central European manufacturing belts.
Volume placements concentrate in Road Freight; the faster expansion belongs to Rail Freight.
End User:
Customer procurement sophistication separates cost-plus contract logistics from spot-market freight purchasing.
- E-commerce:Parcel density in urban centers drives automated sortation hub investment. FAN Courier and domestic operators are deploying micro-fulfillment centers in Timisoara and Cluj-Napoca to compress last-mile delivery windows.
- Manufacturing:Automotive component plants in Transylvania belt require sequenced parts delivery synchronized to production lines. German-owned facilities are consolidating vendor relationships around multi-year 4PL contracts bundling freight forwarding with customs brokerage.
- Retail:Grocery and general merchandise distributors utilize temperature-controlled warehousing for perishable inventory.
- Agriculture:Grain and oilseed exporters depend on Constanta port rail-sea intermodal convergence for Black Sea shipment.
Manufacturing commands the largest contract value commitments; E-commerce is climbing the fastest.
Technology:
Compliance mandates and operational efficiency gains determine technology adoption sequencing.
- GPS Tracking:Real-time vehicle location data enables dynamic route optimization and customer visibility portals. EU-mandated digital tachograph integration requires telematics platform retrofitting for legacy fleets.
- RFID:Automated cargo identification at warehouse gates and port terminals reduces manual scanning labor. Retail distribution centers in Bucharest-Ilfov corridor are deploying item-level tracking for high-value electronics.
- IoT Solutions:Sensor-enabled cargo monitoring provides temperature and shock alerts for pharmaceutical cold chain.
- Warehouse Management:Automated inventory allocation and pick-path optimization systems integrate with e-commerce order management platforms.
GPS Tracking retains the deepest installed base; Warehouse Management systems are gaining share fastest.
Distribution Channel:
Channel selection reflects shipper preferences for asset control versus operational outsourcing.
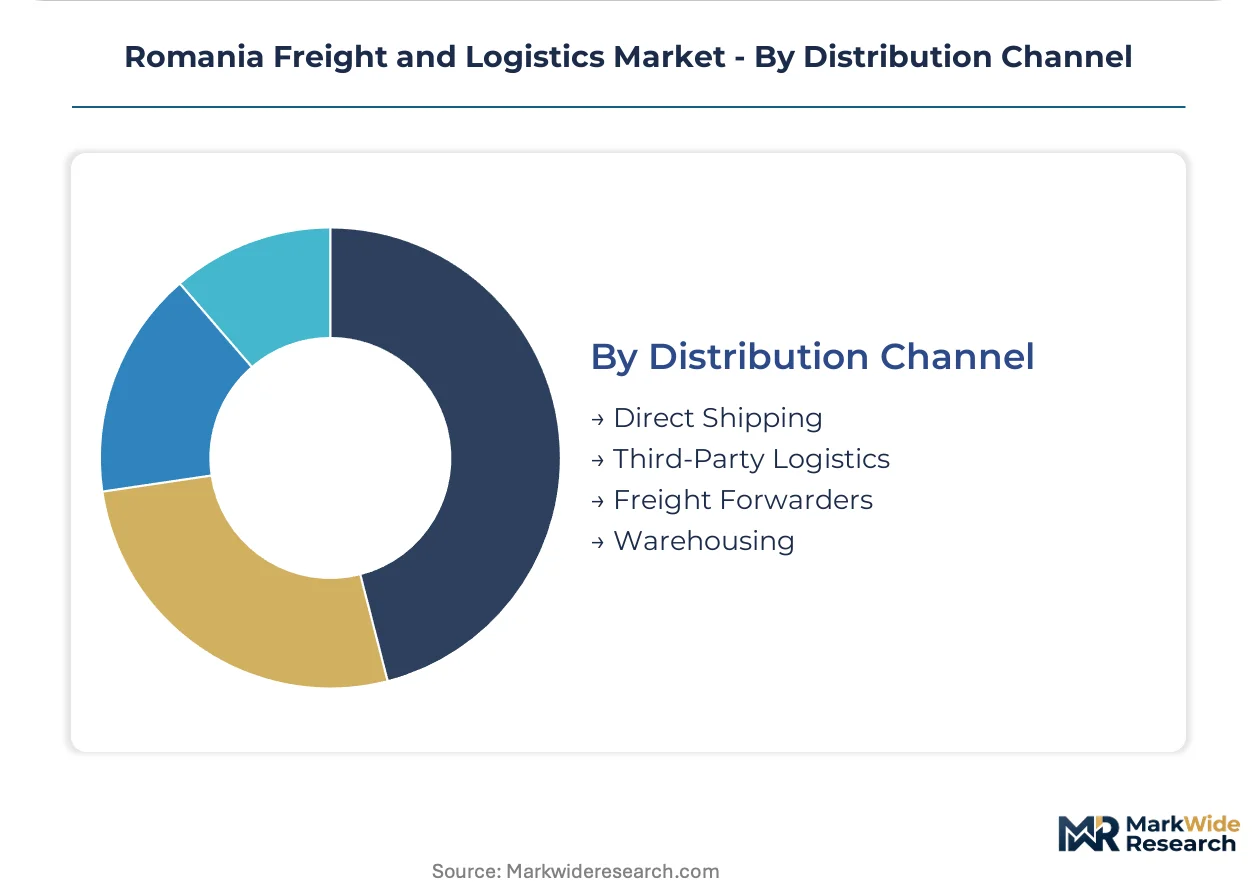
- Direct Shipping:Large manufacturers retain captive fleets for core lanes between production facilities and major customers. Automotive assemblers in Timisoara cluster operate dedicated truck pools to protect sequenced delivery reliability.
- Third-Party Logistics:Outsourced warehousing and transportation management captures expanding margin pools as manufacturers divest non-core fleet assets. Temperature-controlled capacity scarcity in Transylvania belt creates white space for specialized providers.
- Freight Forwarders:Cross-border customs brokerage and multimodal coordination services consolidate fragmented international shipments.
- Warehousing:Contract logistics operators provide bonded storage and value-added services including kitting and labeling.
Third-Party Logistics handles the highest shipment volumes; Direct Shipping is expanding most quickly among large manufacturers reclaiming lane control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Romanian freight demand concentrates along the Bucharest-Ilfov logistics corridor and the Transylvania manufacturing belt, with cross-border flows toward Central European markets absorbing the highest tonnage volumes.
Bucharest-Ilfov Corridor
E-commerce fulfillment density and automotive parts distribution dominate freight flows through Romania's capital region. EU Mobility Package driving and rest-time rules enforce compliance costs on fleet operators serving this corridor. The Otopeni logistics zone anchors automated sortation hubs for parcel operators compressing last-mile delivery windows.
Transylvania Belt
Cluj-Napoca and Timisoara industrial zones generate sequenced parts delivery demand for automotive assemblers. EU Green Deal freight decarbonization timelines accelerate alternative fuel infrastructure commitments along TEN-T corridor segments. German-owned production facilities in Timisoara cluster are consolidating vendor relationships around multi-year 4PL contracts.
Constanta Port Gateway
Black Sea container terminal capacity upgrades capture Asian-origin trade flows toward Central European manufacturing belts. National road transport authority enforcement of cabotage limits constrains Romanian carrier access to Western European markets. The port's rail-sea intermodal convergence anchors bulk commodity export corridors for grain and oilseed shippers.
Western Border Zones
Oradea and Arad logistics nodes facilitate cross-border road and rail corridors into Hungary and beyond. Bilateral road transport agreements limit permit allocations for Romanian carriers entering Austrian and German markets. Temperature-controlled warehousing scarcity in this zone creates white space for specialized contract logistics providers.
Moldova Interface
Eastern Romanian counties handle transshipment flows toward Moldovan and Ukrainian markets via road and rail corridors. EU alignment with transport regulations reshapes fleet operations for operators serving this peripheral zone. Iasi logistics clusters are developing bonded storage capacity for customs-intensive cross-border shipments.
Romania Freight and Logistics Market Competitive Landscape
Capacity expansion dominates the current landscape as operators deploy automated sortation hubs and alternative-fuel fleets to capture e-commerce volume growth. The market structures around three tiers: domestic parcel specialists with urban last-mile density, integrated global forwarders anchoring cross-border corridors, and regional contract logistics providers serving manufacturing clusters. Strategic archetypes include asset-heavy fleet operators absorbing EU Mobility Package compliance costs, technology-enabled platforms matching freight capacity to shipper demand, and vertically integrated warehouse-fleet combinations serving automotive just-in-time requirements. M&A activity and strategic partnerships concentrate among mid-sized carriers seeking scale to justify telematics platform investments.
Among domestic parcel specialists, FAN Courier and Sameday exemplify the asset-heavy archetype with established urban route networks. Posta Romana occupies a position bridging universal service obligations with commercial logistics diversification. Within the integrated forwarding tier, DB Schenker and DSV represent global operators leveraging cross-border rail and road corridor control. These named entities anchor competitive dynamics without exhaustively mapping the vendor landscape.
| Leading Market Players |
|---|
| Posta Romana |
| Urgent Cargus |
| The Maurice Ward Group |
| FAN Courier |
| Aquila Part Prod |
| Yusen Logistics |
| Sameday |
| DSV |
| DB Schenker |
| Others |
Pricing and Supply Chain Analysis
Certified carrier tiers versus non-compliant operators create a sharp bifurcation in Romania's freight market, with EU Mobility Package adherence separating premium-priced capacity from commoditized spot trucking. This certification ladder manifests in both rate structures and fleet procurement decisions, as compliant operators command sustained margin premiums while non-compliant carriers face exclusion from cross-border lanes and major shipper contracts.
Pricing Analysis
Volume concentration in road freight competes against margin compression from regulatory compliance costs. Three-tier pricing structure across certified premium, standard compliant, and spot-market economy levels reflects driver qualification depth and telematics integration. Pricing pressure stems from diesel volatility and EU Mobility Package wage inflation, with e-commerce shippers exhibiting highest price sensitivity due to thin parcel economics, while automotive manufacturers accept premium rates for sequenced delivery reliability.
Supply Chain Analysis
Driver pool constraints in Cluj-Napoca and Timisoara industrial zones force carriers to recruit from Hungary and Bulgaria satellite pools. Equipment sourcing draws from German and Polish manufacturing for EU-compliant tractor units, while diesel fuel supply rests on Black Sea refinery throughput and import corridors. Single-source vulnerability concentrates in ADR-certified tanker capacity for chemical logistics. Distribution runs through Bucharest-Ilfov consolidation hubs feeding Transylvania manufacturing belts and Constanta port multimodal terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Romania's freight market operates under acute supply constraints, with ADR-certified driver scarcity and EU-compliant fleet shortages propping pricing power for qualified operators. Capacity bottlenecks in specialized segments create defendable margin pools.
For Market Incumbents: Anchor cross-border corridor control through satellite driver pool establishment in Hungary and Bulgaria, insulating lane utilization from EU Mobility Package return-to-home provisions. Prioritize telematics platform retrofitting to capture 4PL contract consolidation among German-owned automotive facilities. Defend against technology-enabled freight matching platforms by deepening embedded relationships with sequenced parts delivery contracts. For New Entrants and Emerging Players: Temperature-controlled warehousing scarcity in the Transylvania belt offers immediate white-space capture for specialized contract logistics providers. Target underpenetrated Cluj-Napoca industrial zones with automotive parts consolidation services, leveraging EU alternative fuel infrastructure funding for electric fleet deployment. Go-to-market angle centers on bundled customs brokerage and warehousing for cross-border shippers facing permit allocation constraints. For Investors and Strategic Acquirers: Re-rating potential sits with mid-sized carriers possessing EU-compliant fleet bases and established Transylvania manufacturing relationships, given EU Green Deal freight decarbonization timelines accelerating asset replacement demand. Long-term viability favors operators with backward integration into driver training academies and alternative fuel infrastructure access. Signal to watch: AFIR regulation funding disbursement velocity for charging station buildout along TEN-T corridors.| Strategic Initiative | Industry Significance |
|---|---|
| EU-Compliant Fleet Renewal | Electric and hydrogen tractor deployment captures premium pricing from ESG-mandated shippers. |
| Transylvania Warehouse Buildout | Temperature-controlled capacity addresses automotive and pharmaceutical cold chain gaps. |
| Cross-Border Driver Pool Expansion | Hungary and Bulgaria satellite bases circumvent EU Mobility Package return-to-home restrictions. |
| Telematics Platform Integration | Digital tachograph compliance enables 4PL contract eligibility with German OEM procurement. |
| Rail-Sea Intermodal Investment | Constanta port feeder rail integration captures bulk commodity modal shift from road. |
Research Methodology
Multi-period observation of fleet utilization rates, driver wage inflation, and EU permit allocation volumes anchored the trend analysis, supplemented by interviews with fleet operations directors, automotive procurement managers at Timisoara manufacturing facilities, customs brokerage heads, and national road transport authority officials. Secondary validation drew from EU Mobility Package implementation trackers, national alternative fuel infrastructure registries, Constanta port throughput statistics, and automotive production databases. Bottom-up carrier capacity modeling and top-down trade flow analysis provided cross-verification.
Input-output matrix framing connected macro trade corridor volumes to micro fleet deployment economics across the projection horizon. Segmentation dimensions modeled include service modality, end-user industry vertical, technology adoption tier, and distribution channel structure. CAGRs were derived from fitted trend extrapolation against regulatory deadline constraints. Industry-specific forecast inputs incorporated EU Green Deal freight decarbonization timelines and e-commerce parcel density growth curves.
Revisions become necessary when EU Mobility Package enforcement intensity shifts, alternative fuel infrastructure deployment lags regulatory deadlines, or cross-border permit allocation agreements undergo renegotiation. Forecasts reflect documented assumptions about regulatory compliance cost pass-through rates and shipper outsourcing propensity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
China Same Day Delivery Market
Logistics and Shipping
Nigeria Third-Party Logistics (3PL) Market
Logistics and Shipping
Global 5PL Solutions Market
Logistics and Shipping
United States Apparel Logistics Market
Logistics and Shipping
WAN Connected Returnable Transport Asset Tracking Market
Logistics and Shipping
Nigeria Freight and Logistics Market
Logistics and Shipping
Nigeria Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Third-Party Logistics (3PL) Market
Logistics and Shipping
Mexico Containerized Shipping Market
Logistics and Shipping
Last-Mile Delivery Market
Logistics and Shipping
Saudi Arabia Secure Logistics Market
Logistics and Shipping
Chile Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
GCC Finished Vehicle Logistics Market
Logistics and Shipping
Nordics Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Myanmar Freight and Logistics Market
Logistics and Shipping
Argentina Freight and Logistics Market