
 Automotive Door Handles Market | 2026-2036
Automotive Door Handles Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Door Handles Market Analysis
Software-defined access features bundled through subscription tiers is realigning how door handle systems generate lifetime revenue beyond hardware sales. Huf Group leverages its mechatronics heritage to anchor smart-handle production across European OEM programs. Sandhar Technologies sustains cost-competitive manufacturing scale from its India base while competing for share in automated handle assemblies.
Automotive door handles are mechanical or electromechanical interface components, typically injection-molded from engineering plastics or die-cast from zinc alloy and aluminum, designed to enable occupant entry and egress while integrating antenna coils for passive entry systems. Their primary purpose spans functional actuation, vehicle security signaling, and aerodynamic surface continuity in modern body design. Exterior handles and smart handles command the strongest margin pools as flush designs proliferate across premium segments, while plastic and aluminum material categories split volume leadership between cost-driven mass-market platforms and lightweighting-focused architectures. OEM and Tier-1 supplier channels dominate installation flows, with automated assembly lines displacing manual fitment at original build.
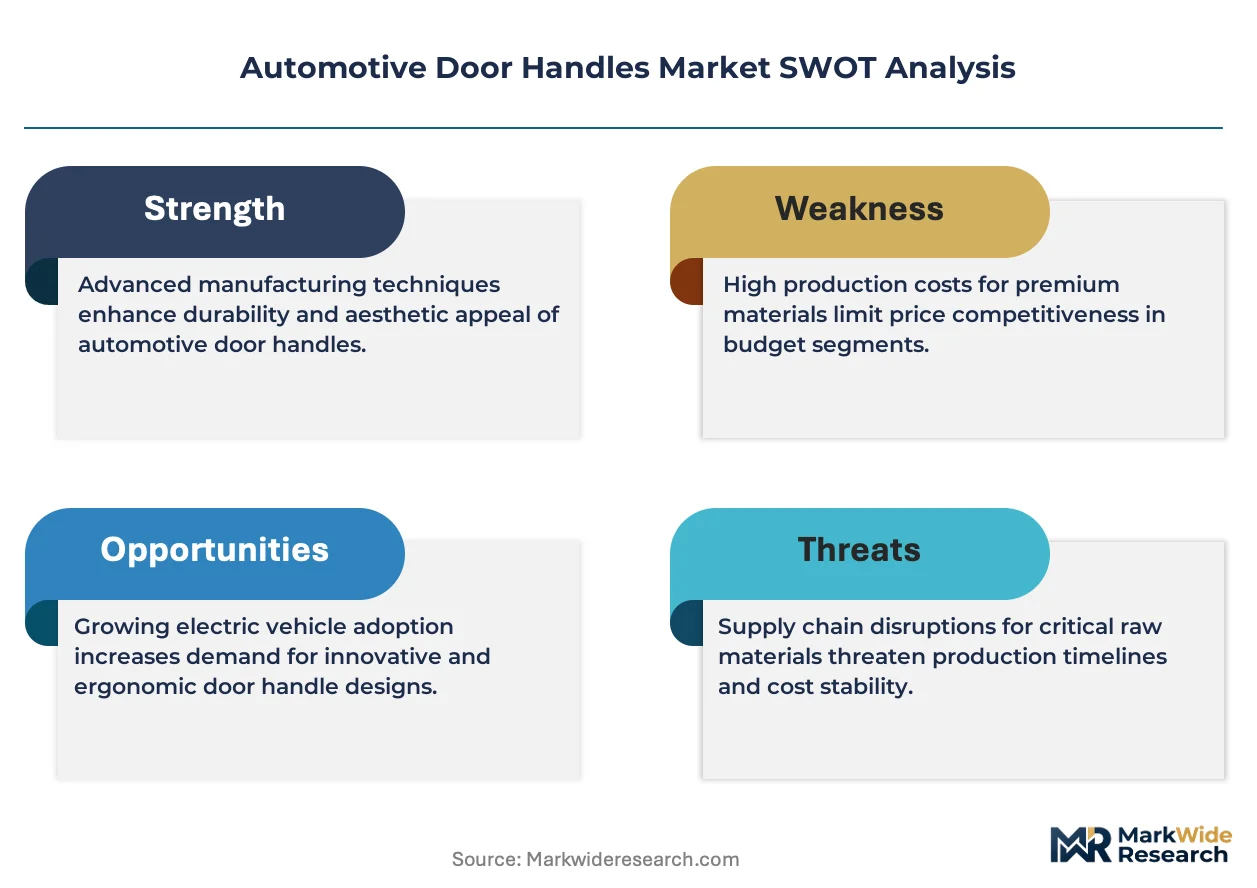
NHTSA FMVSS 206 door retention standards, ECE R21 interior impact regulations, and China's GB 11552 occupant protection rules collectively dictate latch durability, projection limits, and emergency-release accessibility that shape handle geometry and material selection. REACH substance restrictions and RoHS compliance further constrain plating chemistries and polymer formulations across export-bound supply chains. Stakeholders must monitor how cybersecurity mandates for connected entry systems reshape certification burdens and supplier qualification timelines.
Market Dynamics
The transition from mechanical to electromechanical entry systems is compressing development cycles and forcing parallel investments in cybersecurity validation alongside traditional crash-safety testing. Flush-mounted smart handles now require simultaneous compliance with aerodynamic targets, passive entry antenna integration, and emergency-release accessibility mandates.
Growth Catalysts
- UN R79 Steering Standards:European safety mandates for pedestrian protection and interior impact are accelerating aluminum and zinc alloy adoption over legacy plastic constructions in premium vehicle programs.
- Electric Vehicle Proliferation:EV platforms prioritize aerodynamic efficiency, creating demand for flush-mounted handles that eliminate surface discontinuities and reduce drag coefficients.
- Passive Entry System Integration:Antenna coil embedding within handle housings is standardizing across mid-tier and luxury segments as keyless access becomes a baseline consumer expectation.
Market Restraints
- Zinc Alloy Price Volatility:Die-cast metal feedstock costs fluctuate with London Metal Exchange pricing, squeezing margin predictability for suppliers serving cost-sensitive mass-market OEMs.
- REACH Substance Restrictions:European chemical regulations constrain plating chemistries and polymer formulations, forcing reformulation investments across export-bound supply chains.
- Legacy Mechanical Redundancy:Smart handle architectures must maintain failsafe mechanical release mechanisms, adding component count and assembly complexity that pure electronic solutions would eliminate.
Strategic Opportunities
- Software-Defined Access Subscriptions:Feature bundling through tiered service plans creates recurring revenue streams beyond hardware sales, with personalization and temporary access credentialing as anchor services.
- India Manufacturing Scale:Cost-competitive automated assembly capacity in Pune and Chennai offers export competitiveness for suppliers serving European and North American aftermarket channels.
- Cybersecurity Certification Mandates:UN ECE WP.29 regulations for connected vehicle systems are creating qualification barriers that favor established mechatronics suppliers with embedded security engineering capabilities.
Industry Challenges
- Cross-Functional Talent Scarcity:Mechatronics engineers capable of integrating mechanical latching, RF antenna design, and embedded cybersecurity are concentrated among a handful of Tier-1 suppliers.
- Dual Certification Timelines:Simultaneous NHTSA FMVSS 206 door retention validation and ECE R21 interior impact testing extends program development schedules by 8-14 months.
- Legacy Platform Integration:Retrofitting smart handles onto existing vehicle architectures requires reconciling 12V electrical systems with low-power antenna requirements and CAN bus protocol variations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Door Handles Market |
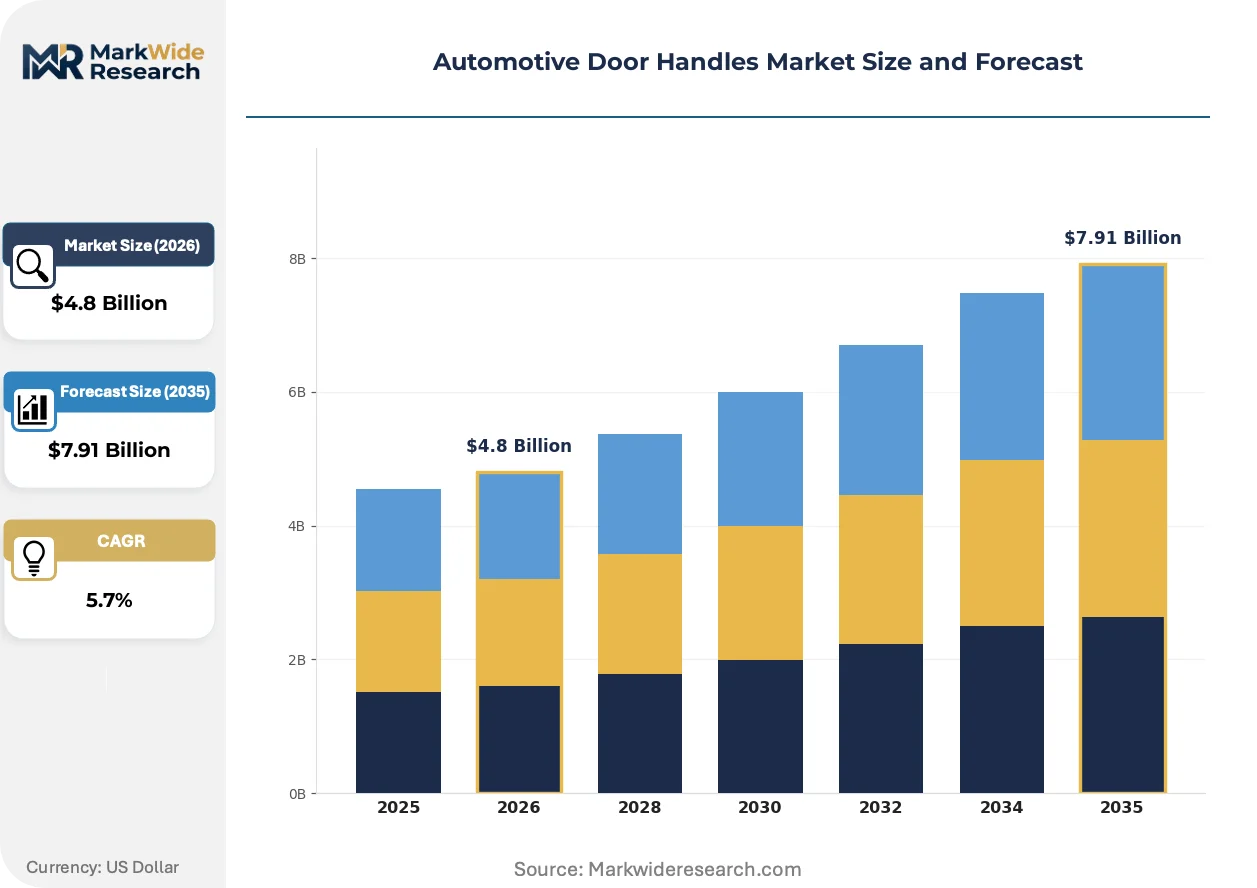
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interior Handles, Exterior Handles, Smart Handles, Child Safety Handles Material: Plastic, Aluminum, Steel, Zinc Alloy End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Installation: Manual Installation, Automated Installation, Replacement, Custom Installation |
| Companies Covered | Minda VAST Access Systems, Sandhar Technologies, Huf Group, CI Car International, MinebeaMitsumi, ALPHA Corporation, U-Shin, HuaDe Holding Group, Illinois Tool Works, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Door Handles Market Emerging Trajectories
Capacitive sensing and haptic feedback mechanisms are replacing physical button actuation, while material science advances enable thinner-wall aluminum castings that maintain structural integrity under crash loading. These shifts are compressing the boundary between exterior styling and functional safety hardware.
Capacitive touch surfaces embedded in flush handle housings are integrating proximity detection, force sensing, and haptic response into single-module assemblies. Luxury and electric vehicle OEMs in Germany and California are specifying these architectures for 2026-2028 model year launches. This convergence is integrating previously separate sensor, actuator, and antenna supply chains into consolidated mechatronics procurement packages.
REACH Annex XVII restrictions on nickel release and hexavalent chromium plating are forcing migration to trivalent chrome and PVD coating alternatives for decorative handle finishes. Suppliers serving European OEM programs face reformulation deadlines that compress qualification windows. Die-cast zinc suppliers with in-house surface treatment capabilities are capturing specification authority that plating subcontractors previously held.
Fleet operators and mobility service providers are unbundling after-sales handle maintenance from traditional dealer service networks. Third-party certified repair channels in Texas and Guangdong are capturing warranty and post-warranty volume through specialized trim removal and recalibration equipment. This channel fragmentation is most visible in commercial vehicle segments where uptime metrics override brand-loyal service preferences.
Automotive Door Handles Market Segmentation
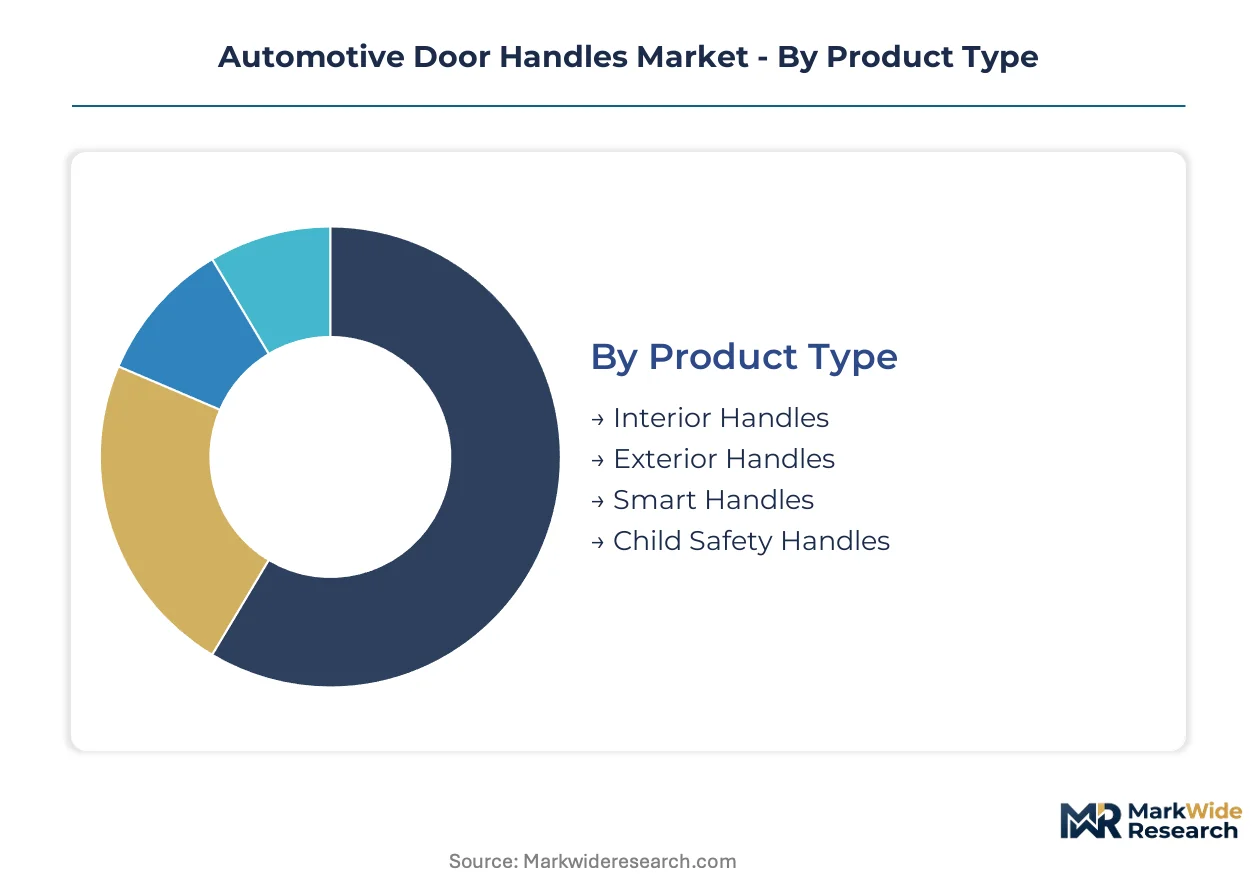
Automotive door handle segmentation reveals how supply chain configuration and regulatory pressure distribute value across material grades, product architectures, and installation modalities. Understanding these splits enables suppliers to align capacity investments with margin concentration points.
Product Type:
Supply concentration in smart handle mechatronics has shifted procurement authority toward Tier-1 suppliers with embedded antenna and sensor integration capabilities.
- Exterior Handles:Die-cast zinc alloy and aluminum housings with integrated passive entry antenna coils dominate premium vehicle specifications. Demand concentrates in Germany and the United States where flush-mounted designs reduce drag coefficients on electric vehicle platforms.
- Smart Handles:Capacitive sensing modules with haptic feedback and proximity detection consolidate previously separate sensor, actuator, and RF subsystems. German and California-based OEMs specify these for upcoming model year launches, creating qualification barriers for suppliers lacking mechatronics heritage.
- Interior Handles:Injection-molded engineering plastics with mechanical latching mechanisms serve cost-driven mass-market platforms where ECE R21 interior impact compliance dictates material selection.
- Child Safety Handles:Specialized release mechanisms with force-limiting features address NHTSA FMVSS 206 emergency accessibility mandates for rear passenger compartments.
Today's leader: Exterior Handles. Tomorrow's challenger: Smart Handles.
Material:
Cost tier differentiation separates mass-market plastic specifications from lightweighting-driven aluminum and zinc alloy programs serving premium architectures.
- Aluminum:Thin-wall die-castings with structural integrity under crash loading enable aerodynamic flush-handle designs. European ECE R21 pedestrian protection standards accelerate substitution over legacy plastic in Germany and premium export programs.
- Zinc Alloy:High-pressure die-casting delivers complex geometries with decorative surface finishes, though London Metal Exchange price volatility squeezes margin predictability for suppliers serving volume OEMs.
- Plastic:Glass-reinforced polyamide and ABS formulations dominate interior applications and cost-sensitive exterior programs where REACH substance restrictions constrain plating chemistries.
- Steel:Stamped and formed constructions persist in commercial vehicle and heavy-duty applications where mechanical durability overrides weight considerations.
Volume leadership splits: Plastic in mass-market platforms. Aluminum in lightweighting-focused architectures.
End User:
Procurement patterns diverge between captive OEM supply chains and fragmented aftermarket channels with distinct certification and service requirements.
- OEMs:Direct specification authority for smart handle architectures with software-defined access features bundled through subscription tiers, generating lifetime revenue beyond hardware sales.
- Tier-1 Suppliers:Consolidated mechatronics procurement packages integrate sensor, actuator, and antenna supply chains into single-source contracts for flush-mounted handle assemblies.
- Vehicle Assemblers:Automated installation lines displace manual fitment at original build, with Pune and Chennai manufacturing bases offering export competitiveness.
- Aftermarket Providers:Third-party certified repair channels in Texas and Guangdong capture warranty and post-warranty volume through specialized trim removal and recalibration equipment.
Channel control: OEMs and Tier-1 suppliers dominate specification. Aftermarket fragmentation accelerates in commercial vehicle segments.
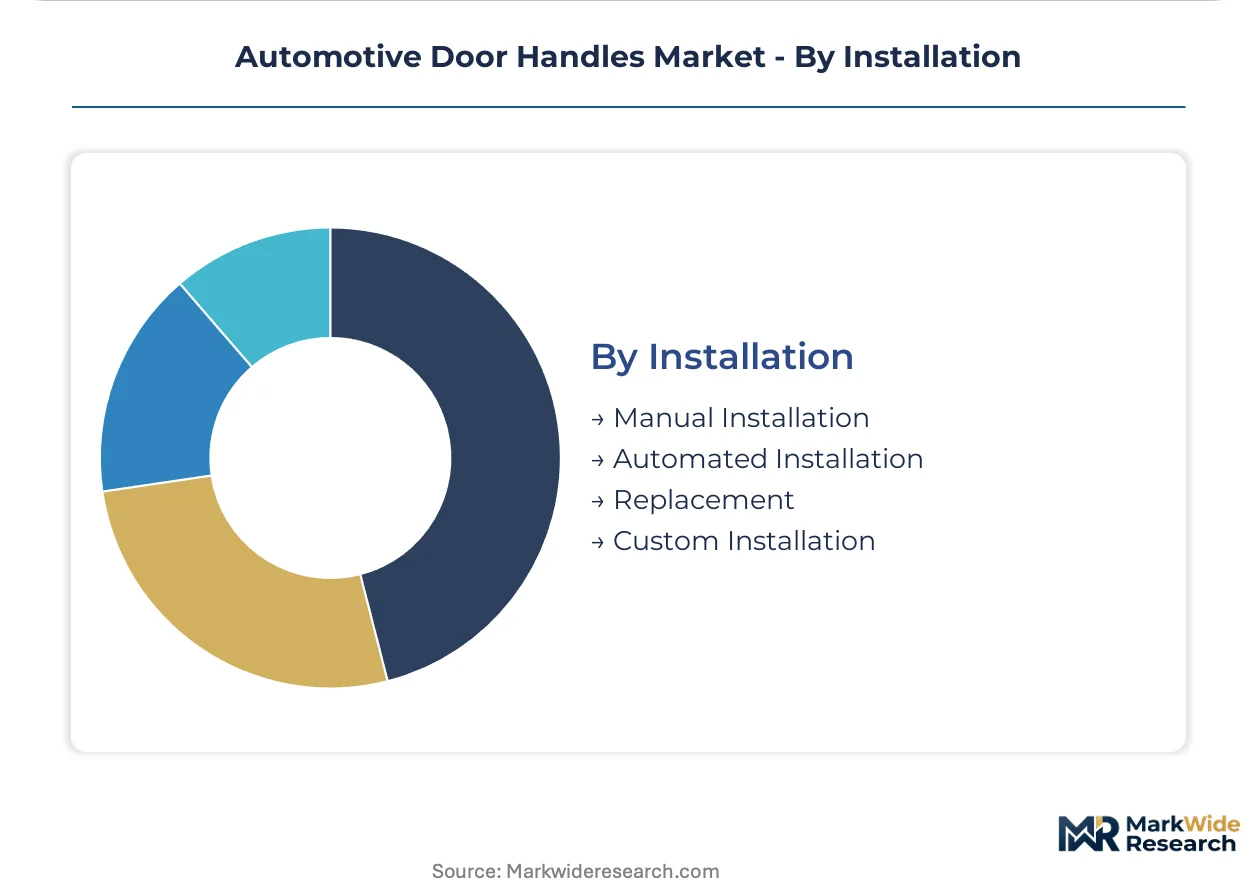
Installation:
Maturity gradients separate established automated assembly from emerging custom installation services targeting personalization and fleet retrofit markets.
- Automated Installation:Robotic fitment systems with torque-controlled fastening and inline quality verification displace manual assembly at high-volume vehicle plants.
- Manual Installation:Remains prevalent in low-volume specialty builds and legacy platform maintenance where production economics resist automation investment.
- Replacement:Standardized service procedures for collision repair and warranty claims, with diagnostic recalibration requirements expanding for smart handle architectures.
- Custom Installation:Bespoke handle finishes and access credentialing systems serve luxury personalization programs and mobility fleet operators requiring temporary access provisioning.
Deployment trajectory: Automated Installation scales fastest. Custom Installation gains share in premium personalization segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and China pursue divergent pathways toward smart handle adoption, with European safety mandates accelerating aluminum substitution while Chinese OEMs prioritize cost-competitive mechatronics integration at scale.
Germany
Premium vehicle assembly volumes in Bavaria and Baden-Württemberg drive specification authority for flush-mounted aluminum handles. KBA enforces ECE R21 pedestrian protection standards that mandate structural integrity testing for exterior components. Stuttgart's supplier corridor hosts Huf Group's mechatronics development centers, where antenna-integrated assemblies undergo parallel cybersecurity and crash-safety validation.
China
Electric vehicle platforms from BYD and NIO prioritize aerodynamic efficiency through flush handle architectures. MIIT's GB standards for occupant protection align with NHTSA-equivalent door retention requirements for export-bound vehicles. Yangtze River Delta manufacturing clusters in Shanghai and Suzhou concentrate die-casting capacity serving both domestic OEMs and European Tier-1 supply chains.
United States
Detroit Three OEMs and Tesla anchor demand for smart handles with software-defined access features. NHTSA FMVSS 206 door retention standards dictate latch durability testing protocols that extend development timelines. Michigan's automated assembly infrastructure supports robotic fitment systems with inline quality verification for high-volume truck and SUV programs.
India
Cost-competitive manufacturing scale in Pune and Chennai attracts export-oriented handle assembly contracts. BIS certification requirements for automotive components constrain plating chemistries and polymer formulations. Tamil Nadu's supplier parks host Sandhar Technologies' automated production lines serving European aftermarket channels.
Japan
Keiretsu supply relationships concentrate procurement authority among integrated Tier-1 suppliers. METI's alignment with UN ECE WP.29 cybersecurity regulations shapes connected entry system certification timelines. Aichi Prefecture's Nagoya industrial corridor maintains die-cast zinc and aluminum capacity for hybrid vehicle programs requiring mechanical-electronic redundancy.
Automotive Door Handles Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with mechatronics-integrated smart handles consolidating procurement toward Tier-1 suppliers while commodity exterior hardware fragments across regional fabricators. The vendor base separates into three strategic archetypes: European heritage suppliers with embedded RF engineering capabilities, India-based scale manufacturers serving aftermarket channels, and Japanese integrated component specialists. Competitive positioning hinges on M&A activity targeting antenna design firms and capacity expansion into automated assembly corridors.
Within the European heritage tier, Huf Group and U-Shin occupy positions anchored by mechatronics development heritage and keiretsu supply relationships respectively. Sandhar Technologies represents the India-based scale archetype, leveraging Pune and Chennai manufacturing bases for export competitiveness. Minda VAST Access Systems exemplifies regional specialists consolidating specification authority through proximity to German and Indian OEM programs.
| Leading Market Players |
|---|
| Minda VAST Access Systems |
| Sandhar Technologies |
| Huf Group |
| CI Car International |
| MinebeaMitsumi |
| ALPHA Corporation |
| U-Shin |
| HuaDe Holding Group |
| Illinois Tool Works |
| Others |
Supply Flow & Price Mechanics
Family-owned die-casting specialists in Germany's supplier corridor anchor pricing discipline through captive surface treatment capabilities, while sovereign-backed Chinese producers in the Yangtze River Delta compress cost floors through integrated antenna coil manufacturing. This ownership bifurcation creates divergent margin structures across European premium programs and Chinese volume exports.
Pricing Analysis
Capacity additions in India's Pune and Chennai manufacturing clusters are reshaping price floors for aftermarket and export-bound handle assemblies. Three-tier pricing structure across premium flush-mounted smart handles, standard exterior die-cast units, and economy plastic interior mechanisms stratifies the market. Price differentiation centers on ECE R21 certification grade and embedded mechatronics complexity. Margins are tightening in zinc alloy die-casting tiers due to London Metal Exchange feedstock volatility. Mass-market OEM procurement teams exhibit highest price sensitivity, while luxury electric vehicle programs prioritize antenna integration performance over unit cost.
Supply Chain Analysis
ECE R21 pedestrian protection certification and UN ECE WP.29 cybersecurity mandates gate supplier qualification, concentrating Tier-1 procurement authority among mechatronics-integrated specialists. Manufacturing gravity draws from Germany, China, and India, with die-cast aluminum and zinc alloy feedstock sourcing from European and Asian smelters. Supply chain risk rests on single-source antenna coil vendors for smart handle architectures. Distribution runs through captive OEM supply chains for original build, with fragmented third-party certified repair channels capturing aftermarket volume in Texas and Guangdong.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where UN ECE WP.29 cybersecurity mandates for connected entry systems are accelerating supplier consolidation toward qualified mechatronics specialists.
For Market Incumbents: To counter margin erosion from zinc alloy price volatility and Chinese cost competition, backward integration into antenna design capabilities and die-casting capacity expansion in India's automated assembly corridors represent priority defensive moves. ECE R21 certification maintenance and embedded cybersecurity engineering investment sustain specification authority against emerging contract manufacturers. For New Entrants and Emerging Players: Capture aftermarket service channel fragmentation in commercial vehicle segments where uptime metrics override brand-loyal dealer networks. White-space concentration sits in third-party certified repair infrastructure for smart handle recalibration and temporary access credentialing systems serving mobility fleet operators. Go-to-market positioning through specialized trim removal equipment leasing differentiates against incumbent parts distribution. For Investors and Strategic Acquirers: Valuations sit cheapest among India-based automated assembly scale players with export competitiveness and European heritage suppliers lacking embedded RF engineering capabilities. Five-to-ten year viability favors mechatronics-integrated specialists with software-defined access subscription revenue streams. Watch cybersecurity certification backlog timelines at KBA and NHTSA as inflection indicators for supplier qualification bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| Mechatronics Integration Investment | Consolidates antenna, sensor, and actuator supply chains into single-source procurement packages for flush-mounted smart handles. |
| India Manufacturing Footprint Expansion | Pune and Chennai automated assembly lines offer cost-competitive export capacity serving European and North American aftermarket channels. |
| Cybersecurity Certification Pathway | UN ECE WP.29 compliance creates qualification barriers favoring established suppliers with embedded security engineering capabilities. |
| Software-Defined Access Platform | Subscription-tiered personalization and temporary credentialing services generate recurring revenue beyond hardware sales cycles. |
| Surface Treatment Capability Acquisition | In-house trivalent chrome and PVD coating alternatives capture specification authority from plating subcontractors facing REACH deadlines. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers with secondary validation against vehicle production databases, IHS Markit registration data, NHTSA FMVSS 206 filings, and ECE R21 test protocols. Bottom-up segment sizing and top-down market triangulation cross-verified volume and value estimates.
Segment-weighted modeling distributed value across product type, material grade, installation modality, and regional production cluster dimensions throughout the forecast period. CAGRs derived from production volume trajectories, content-per-vehicle assumptions for smart handle penetration, and pricing elasticity by OEM tier. Forecast inputs incorporated electric vehicle platform launch schedules and regulatory compliance deadline clustering.
Raw material price volatility, cybersecurity certification delays, and electric vehicle platform ramp timing are the dominant revision risks to modeled assumptions. Deviation in UN ECE WP.29 implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
India Automotive Door Seals Market
Automotive Interior & Exterior
Truck Parking Air Conditioner Market
Automotive Interior & Exterior
Power Sunroof Market
Automotive Interior & Exterior
Automotive OEM Interior Coatings Market
Automotive Interior & Exterior
Automotive Fascia Market
Automotive Interior & Exterior
Automotive Seating Systems Market
Automotive Interior & Exterior
Ventilated Seats Market
Automotive Interior & Exterior
Automotive Exterior Trim Parts Market
Automotive Interior & Exterior
Automotive Heat Shield Market
Automotive Interior & Exterior
Automotive Roof Liners Market
Automotive Interior & Exterior
Automotive Door Check Market
Automotive Interior & Exterior
Automotive Door Impact Bars Market
Automotive Interior & Exterior
Automotive Drawer Slides Market
Automotive Interior & Exterior
Automotive Seat Covers Market
Automotive Interior & Exterior
Automotive Reconfigurable Body Panel Market
Automotive Interior & Exterior
Automotive Outside Rearview Mirrors (ORVM) Market