
 Middle East Pipeline Construction Market | 2026-2036
Middle East Pipeline Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Pipeline Construction Market Analytics
API 5L X80 grade specification is unwinding across major trunkline awards, pushing contractors toward higher-yield metallurgy and automated welding protocols. NMDC Energy leverages its Abu Dhabi marine fabrication yards to dominate shallow-water pipeline installation. Bechtel sustains engineering dominance through its Qatar LNG expansion backlog. Saipem differentiates with reel-lay vessel deployment in Saudi deepwater fields.
Middle East pipeline construction encompasses the engineering, procurement, and installation of conduits for hydrocarbon and fluid transport, typically employing carbon steel with specified minimum yield strength of 52,000 to 80,000 psi, coated with fusion-bonded epoxy or three-layer polyethylene for corrosion protection in desert and subsea environments. Carbon steel pipelines occupy the majority of awarded tonnage due to established welding procedures and cost efficiency in high-pressure hydrocarbon service. Horizontal directional drilling is gaining share for urban crossings and environmentally sensitive corridors where open trenching faces permitting constraints. Oil and gas end-use leads contract value, though water supply infrastructure is expanding fastest in the UAE and Oman desalination networks.
Saudi Standards, Metrology and Quality Organization (SASO) and the Emirates Authority for Standardization and Metrology (ESMA) enforce pipeline material certification and welding qualification protocols that gate market access for foreign contractors. The Gulf Cooperation Council's unified technical regulation for pressure equipment is forcing alignment across national approval systems. Stakeholders must monitor sour service qualification requirements as hydrogen sulfide content in new gas fields escalates metallurgical complexity and inspection scope.
Market Dynamics
API 5L X80 grade specification is displacing X65 across Saudi Aramco and ADNOC trunkline awards, forcing contractors to retool welding protocols and metallurgical sourcing. This specification upgrade concentrates procurement power among mills capable of high-yield alloy production.
Growth Catalysts
- Master Gas System expansion:Saudi Aramco's domestic gas distribution backbone requires 48-inch diameter trunklines across the Eastern Province, sustaining fabrication yard utilization through 2030.
- Sour service qualification mandates:The Gulf Cooperation Council's unified technical regulation for pressure equipment is tightening material certification requirements, advantaging pre-qualified contractors.
- Horizontal directional drilling:Urban corridor permitting in Dubai and Riyadh is accelerating trenchless crossing adoption for distribution networks.
Market Restraints
- Alloy supply concentration:High-yield plate mills cluster in South Korea and Japan, exposing contractors to freight cost volatility and extended lead times.
- SASO welding protocol friction:The Saudi Standards, Metrology and Quality Organization's qualification timeline adds 8-12 weeks to contractor mobilization.
- Corrosion-resistant alloy substitution:Thermoplastic composite pipelines from TechnipFMC and Airborne Oil & Gas threaten carbon steel share in low-pressure gathering systems.
Strategic Opportunities
- Oman desalination conveyance:The Sharqiyah and Dhofar governorates are tendering 200km+ raw water transmission mains with polymer-concrete coating specifications.
- Abu Dhabi sour gas development:ADNOC's Hail and Ghasha fields require 22% chromium duplex stainless for high-H2S service, opening premium metallurgy contracts.
- Reel-lay vessel deployment:Deepwater tiebacks in Saudi Arabia's Red Sea blocks favor single-vessel installation over traditional S-lay spreads.
Industry Challenges
- Automated welding technician scarcity:X80-grade pipeline construction requires qualified operators for mechanized GMAW processes, with certification backlogs at ESMA-approved facilities.
- Fusion-bonded epoxy certification timelines:Coating applicators face extended qualification periods under the Emirates Authority for Standardization and Metrology's revised adhesion testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Pipeline Construction Market |
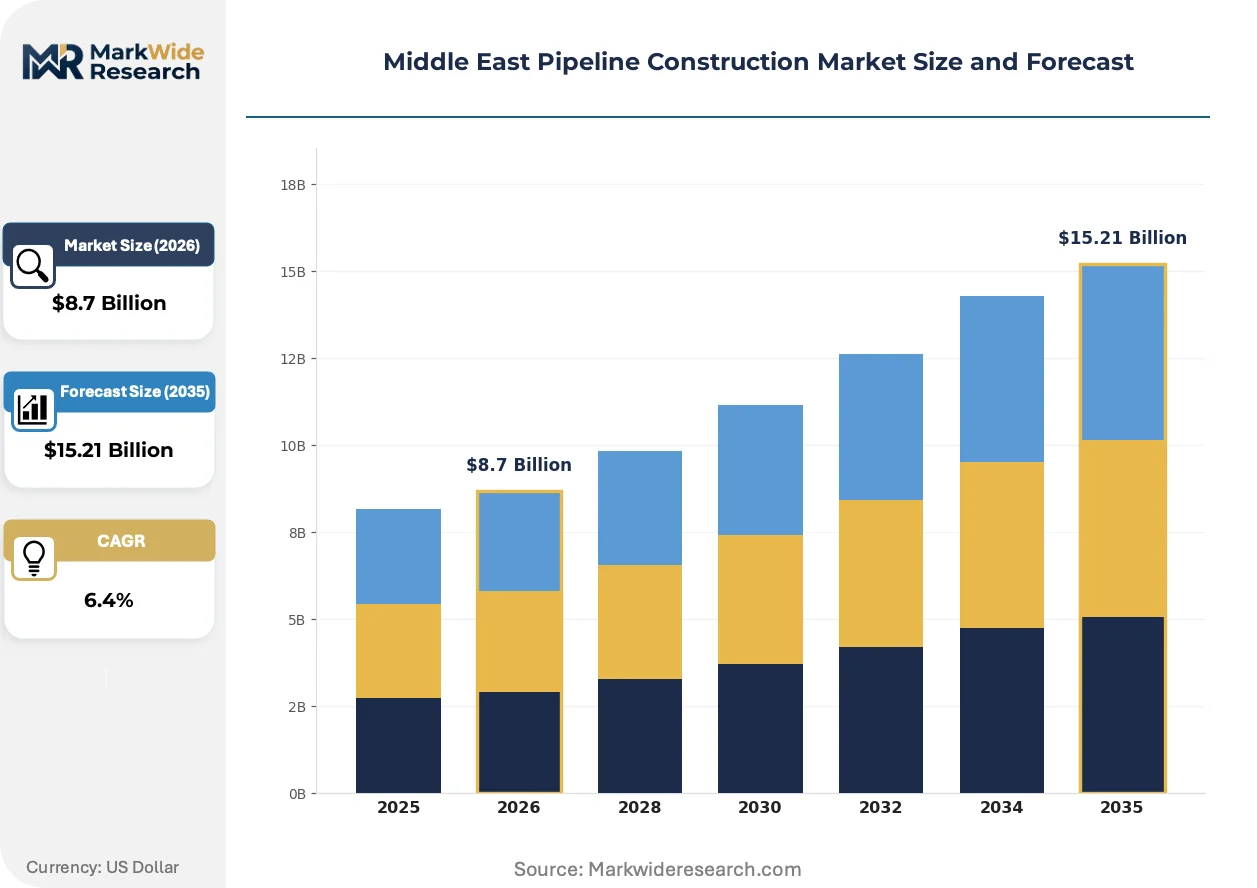
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Steel, PVC, HDPE, Fiberglass Installation Method: Trenching, Horizontal Directional Drilling, Excavation, Microtunneling End Use Industry: Oil & Gas, Water Supply, Wastewater Management, Chemical Processing Technology: Welding, Coatings, Inspection, Valve Technology |
| Companies Covered | NMDC Energy, Tecnimont, China Petroleum Pipeline Engineering Company, Technip Energies, Bechtel, Petrofac Emirates LLC, Saipem, JGC Corporation, Target Engineering Construction Company, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Pipeline Construction Market Evolving Landscape
Digital twin integration and automated inspection protocols are compressing project handover timelines while expanding predictive maintenance scope across Gulf Cooperation Council pipeline networks.
Corrosion-resistant alloy cladding is displacing solid CRA pipe in moderate-sour service applications. ADNOC and Saudi Aramco are specifying metallurgically bonded 625 overlays for manifolds and risers. This hybrid approach is displacing full-duplex procurement, reducing material costs by 30-40% while maintaining NACE MR0175 compliance.
The Gulf Cooperation Council's unified technical regulation for pressure equipment is harmonizing national approval systems across Saudi Arabia, UAE, Qatar, Kuwait, Bahrain, and Oman. ESMA and SASO are converging welding qualification protocols, reducing contractor re-certification burden. Pipeline fabricators with dual Saudi-Emirati accreditation are capturing cross-border awards previously fragmented by jurisdictional silos.
Performance-based contracting is restructuring EPC relationships in Qatar's North Field expansion. Contractors now assume corrosion-risk liability for 15-20 year operational periods, shifting inspection technology selection from lowest-first-cost to life-cycle reliability. This model is concentrating awards among integrators with in-house integrity management capabilities.
Middle East Pipeline Construction Market Segmentation
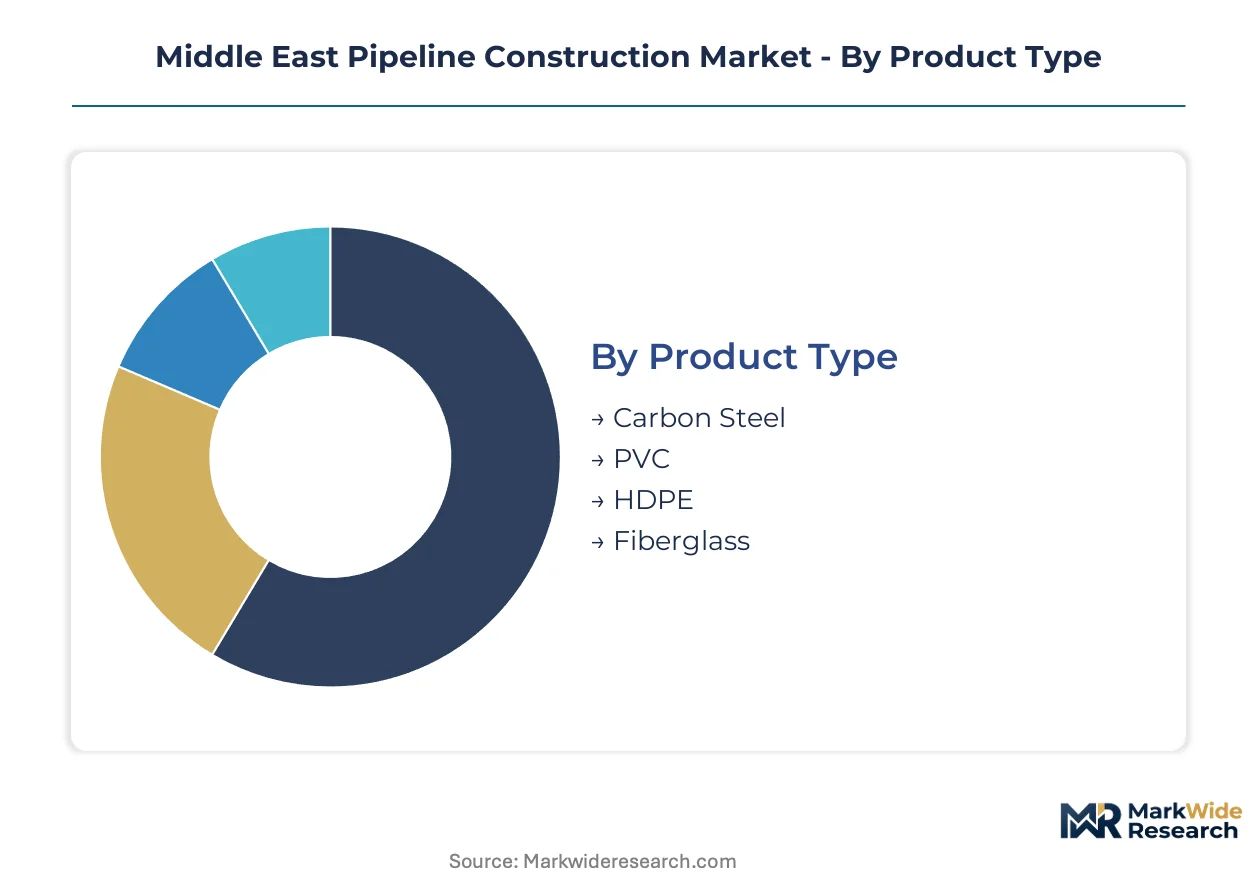
Pipeline construction segmentation in the Middle East reflects divergent material economics and installation constraints across desert terrain, subsea fields, and urban corridors. Specification choices cascade through procurement, welding protocols, and regulatory compliance pathways.
Product Type:
Carbon steel dominates trunkline awards across Saudi Arabia and the UAE, while polymer alternatives penetrate distribution networks and water infrastructure where pressure ratings permit.
- Carbon Steel:API 5L X65 and X80 grades handle high-pressure hydrocarbon transmission across Aramco and ADNOC master gas systems. Eastern Province fabrication yards and Abu Dhabi marine facilities concentrate tonnage procurement for domestic trunkline programs.
- HDPE:Flexible polyethylene pipe serves UAE and Oman desalination conveyance networks with fusion-joint installation protocols. Sharqiyah governorate water tenders specify HDPE for corrosion immunity in saline groundwater conditions.
- PVC:Rigid thermoplastic dominates low-pressure municipal distribution in Riyadh and Dubai urban corridors.
- Fiberglass:Glass-reinforced epoxy systems penetrate chemical processing and moderate-sour gathering lines where weight reduction matters.
Carbon steel holds the largest share; momentum sits with HDPE as water infrastructure accelerates.
Installation Method:
Method selection hinges on terrain constraints, with open-cut trenching yielding to trenchless alternatives where urban density or environmental sensitivity triggers permitting friction.
- Trenching:Conventional open-cut excavation remains default for rural Saudi trunklines and Qatar LNG corridor development. Lower unit costs sustain dominance in uninhabited desert terrain where right-of-way access faces minimal constraint.
- Horizontal Directional Drilling:Steerable trenchless crossing technology penetrates Dubai Marina districts and Riyadh metropolitan zones where surface disruption triggers municipal rejection. HDD rig counts are climbing fastest in UAE urban distribution awards.
- Excavation:Cut-and-fill earthworks support pump station tie-ins and valve assembly pads across Omani interior fields.
- Microtunneling:Slurry-supported boring machines handle deep gravity sewer crossings beneath Abu Dhabi road and rail infrastructure.
Trenching commands volume leadership; horizontal directional drilling is climbing the fastest as urban permitting tightens.
End Use Industry:
Hydrocarbon transmission anchors contract value, though water and wastewater segments expand on desalination investment and sanitation infrastructure gaps.
- Oil & Gas:Crude oil trunklines, gas gathering systems, and LNG export corridors absorb the majority of Saudi and Qatari EPC capacity. Saudi Aramco's Master Gas System expansion and Qatar North Field development concentrate award flow.
- Water Supply:Raw water transmission and desalinated product distribution networks are expanding across UAE and Oman. Dhofar governorate conveyance tenders specify polymer-concrete coating for coastal corrosion resistance.
- Wastewater Management:Sanitation infrastructure in Jeddah and Doha metropolitan zones drives gravity sewer and force main installation.
- Chemical Processing:Sour service pipelines for high-H2S fields and petrochemical feedstock lines require specialized metallurgy and inspection protocols.
Oil and gas holds the largest share; water supply is gaining share fastest on desalination network buildout.
Technology:
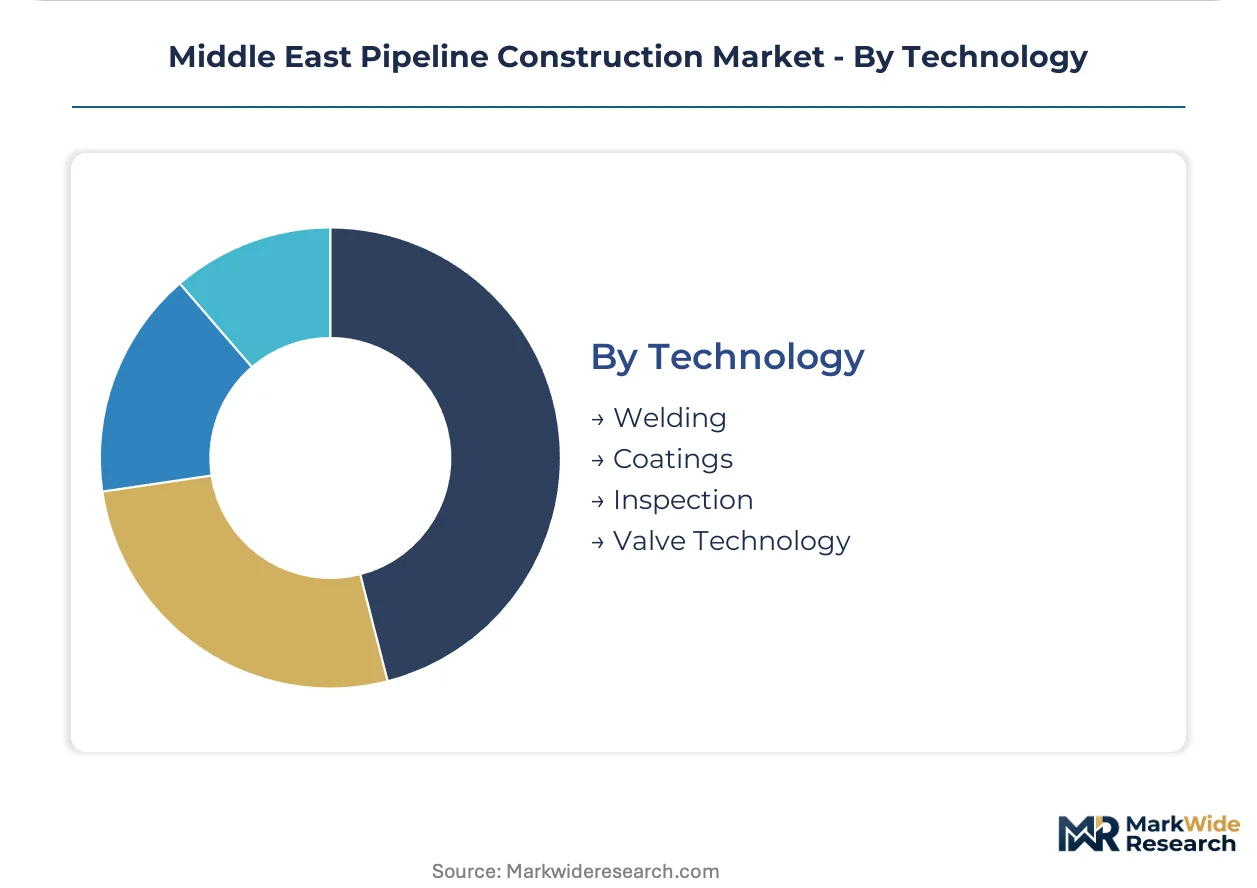
Technology segmentation tracks the fabrication-to-commissioning value chain, with automated welding and inspection protocols reshaping contractor capability requirements.
- Welding:Mechanized GMAW processes for X80-grade pipe demand certified technician pools that concentrate at ESMA and SASO-approved facilities. Automated orbital welding systems are displacing manual stick welding in Saudi trunkline awards.
- Coatings:Fusion-bonded epoxy and three-layer polyethylene systems protect carbon steel in desert and subsea environments. Coating applicators face extended adhesion testing timelines under revised ESMA protocols.
- Inspection:Automated ultrasonic testing and radiographic examination verify weld integrity per Gulf Cooperation Council unified technical regulation requirements.
- Valve Technology:Actuated isolation and control valve systems integrate with SCADA for remote pipeline operation across Saudi and Emirati transmission networks.
Welding commands the largest technology spend; coatings is expanding most quickly as specification upgrades extend qualification burdens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Middle East pipeline construction market operates on a net-import basis for high-yield steel plate and specialized welding equipment, while exporting engineering services and installation expertise across the Gulf Cooperation Council. Domestic fabrication capacity concentrates in coastal zones with deepwater access, creating geographic asymmetry between material inflows and project execution hubs.
Saudi Arabia
Saudi Aramco's Master Gas System expansion and Red Sea deepwater development anchor regional demand for large-diameter trunklines. SASO welding qualification protocols govern contractor mobilization timelines for Eastern Province fabrication yards. Dhahran and Jubail industrial cities host concentrated pipe coating and joint venture facilities serving domestic trunkline programs.
United Arab Emirates
ADNOC's sour gas development at Hail and Ghasha fields drives premium metallurgy procurement for high-H2S service lines. ESMA certification requirements for fusion-bonded epoxy applicators filter market access for coating specialists. Abu Dhabi marine fabrication yards and Dubai's Jebel Ali corridor dominate installation equipment staging and reel-lay vessel support.
Qatar
North Field LNG expansion sustains contract flow for cryogenic pipeline systems and carbon capture tie-in infrastructure. Performance-based contracting models transfer corrosion-risk liability to EPC integrators over 15-20 year operational periods. Ras Laffan Industrial City clusters fabrication capacity for offshore gathering systems and export corridor development.
Oman
Desalination network expansion in Sharqiyah and Dhofar governorates accelerates raw water transmission main construction with polymer-concrete coating specifications. Ministry of Regional Municipalities and Water Resources tenders specify HDPE for saline groundwater immunity. Sohar and Duqm port zones concentrate import logistics for water infrastructure materials.
Kuwait
Heavy oil production enhancement projects require steam distribution pipeline networks across northern oil fields. Kuwait Authority for Partnership Projects governs private sector participation frameworks for energy infrastructure delivery. Al-Zour refinery integration and petrochemical feedstock lines sustain fabrication demand through domestic engineering alliances.
Middle East Pipeline Construction Market Competitive Landscape
Concentration sits with national oil company-affiliated fabricators and international EPC majors holding dual SASO-ESMA accreditation. The vendor base stratifies across three tiers: integrated engineering-procurement-construction firms with proprietary vessel fleets, regional fabrication specialists leveraging marine yard assets, and niche contractors focused on trenchless urban installation. Capacity expansion through Abu Dhabi marine yard upgrades and strategic partnerships for X80-grade steel sourcing represent dominant competitive vectors.
Within the integrated EPC tier, NMDC Energy and Saipem exemplify contrasting installation philosophies—yard-based fabrication versus reel-lay vessel deployment—while Bechtel occupies a position anchored in Qatar LNG engineering dominance. Among Asian entrants, China Petroleum Pipeline Engineering Company and JGC Corporation represent state-linked and privately structured approaches to Gulf market participation. Petrofac Emirates LLC and Target Engineering Construction Company sit within the regional specialist archetype, leveraging proximity accreditation and local workforce integration.
| Leading Market Players |
|---|
| NMDC Energy |
| Tecnimont |
| China Petroleum Pipeline Engineering Company |
| Technip Energies |
| Bechtel |
| Petrofac Emirates LLC |
| Saipem |
| JGC Corporation |
| Target Engineering Construction Company |
| Others |
Value Network & Pricing Analysis
API 5L X80 grade steel substitution for legacy X65 specifications simultaneously relocates procurement gravity toward South Korean and Japanese plate mills and compresses contractor margins through alloy premiums and extended lead-time pricing. This metallurgical upgrade forces Saudi Aramco and ADNOC trunkline awards into long-term offtake structures that transfer freight volatility risk to EPC integrators.
Pricing Analysis
Industrial OEM buyers anchor project-based contract pricing across Saudi Aramco's Master Gas System expansion and ADNOC sour gas programs. Three-tier pricing structure across premium metallurgy, standard carbon steel, and economy-grade water infrastructure segments differentiates on SASO welding certification tier and corrosion-resistance specification. Cost compression in standard-grade carbon steel is intensifying because Chinese mill overcapacity feeds spot-market discounting. National oil companies exhibit lowest price sensitivity due to strategic energy security mandates, while municipal water authorities in Oman and UAE demonstrate highest sensitivity on desalination conveyance tenders.
Supply Chain Analysis
Strategic stockpile preferences dominate among Saudi Aramco and ADNOC procurement teams managing X80-grade plate exposure to maritime freight volatility. High-yield alloy supply concentrates in South Korea, Japan, and select German specialty mills, with coating applicators clustering in Abu Dhabi marine yards and Jubail industrial corridors. Raw material dependencies span iron ore pellets, nickel-chromium alloys for sour service, and fusion-bonded epoxy resin systems. Single-source vulnerability runs through the limited qualified mill base for 22% chromium duplex stainless specified in Hail and Ghasha field awards. Distribution runs through national oil company tender platforms with pre-qualification gating.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoplastic composite pipeline substitution from TechnipFMC and Airborne Oil & Gas threatens carbon steel incumbents in low-pressure gathering systems, demanding defensive capability investments.
For Market Incumbents: Shield trunkline market share through captive X80-grade plate sourcing partnerships with POSCO or Nippon Steel, eliminating freight-exposed spot procurement. Accelerate ESMA and SASO dual-accreditation for automated welding facilities to capture cross-border awards as GCC technical regulations harmonize. Composite pipeline entrants threaten gathering-system margins; defend through performance-based contracting that assumes 15-20 year corrosion liability.
For New Entrants and Emerging Players: ESMA fast-track certification for fusion-bonded epoxy applicators opens Abu Dhabi marine yard access ahead of competitors facing extended adhesion-testing timelines. Target Oman desalination conveyance tenders in Sharqiyah and Dhofar governorates where polymer-concrete coating specifications favor specialized entrants over integrated EPCs. Lead with HDPE fusion-joint installation expertise for saline groundwater immunity positioning.
For Investors and Strategic Acquirers: The market sits at a specification-upgrade phase that favors metallurgy-capable fabricators over pure installation contractors. Long-term viability centers on sour-service qualification depth as hydrogen sulfide content escalates across new gas fields. Acquisition focus: reel-lay vessel operators or automated welding specialists with ESMA-approved technician pools. Watch ADNOC's Hail and Ghasha field award timelines as inflection signal for premium alloy demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Yield Plate Supply | Captive sourcing from South Korean mills insulates Saudi Aramco contractors from freight cost volatility. |
| Dual SASO-ESMA Accreditation Investment | Cross-border fabrication awards concentrate among pre-qualified contractors as GCC regulations harmonize. |
| Reel-Lay Vessel Deployment | Deepwater Red Sea tiebacks favor single-vessel installation economics over traditional S-lay spreads. |
| Automated Welding Technician Certification | Mechanized GMAW operator scarcity at approved facilities creates bottleneck for X80-grade trunkline awards. |
| Performance-Based Contracting Adoption | Qatar North Field expansion transfers 15-20 year corrosion liability to EPC integrators with integrity capabilities. |
Research Methodology
A standing panel of EPC project directors, national oil company procurement officers, coating applicator technical leads, and marine fabrication yard managers provided ongoing calibration across primary interview cycles. Secondary validation drew from Saudi Aramco and ADNOC tender disclosures, SASO and ESMA certification registries, GCC customs trade data for high-yield steel plate imports, and Lloyd's Register offshore installation tracking. Bottom-up project pipeline aggregation triangulated against top-down national infrastructure budget allocations.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning material grade tier, installation method complexity, end-use industry regulatory cluster, and sour service qualification level. CAGRs derived from project award flow analysis, fabrication yard utilization rates, and metallurgical specification upgrade trajectories. Key inputs included Saudi Master Gas System expansion phasing, ADNOC sour gas field development timelines, and Oman desalination network tender progressions.
Decision-makers should treat outputs as directional under sustained oil prices supporting national oil company capital deployment and GCC regulatory harmonization proceeding; material deviation would warrant model refresh. Revision becomes warranted when thermoplastic composite pipeline substitution rates or X80-grade mill capacity expansion crosses thresholds that reshape supply-demand balance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
South America Data Center Construction Market
Infrastructure Construction
Thailand Data Center Construction Market
Infrastructure Construction
United States Transportation Infrastructure Construction Market
Infrastructure Construction
Pipeline Construction Market
Infrastructure Construction
Denmark Data Center Construction Market
Infrastructure Construction
France Transportation Infrastructure Construction Market
Infrastructure Construction
Japan Transportation Infrastructure Construction Market
Infrastructure Construction
Docks Market
Infrastructure Construction
Poland Transportation Infrastructure Construction Market
Infrastructure Construction
South Korea Infrastructure Market
Infrastructure Construction
Switzerland Transportation Infrastructure Construction Market
Infrastructure Construction
Brazil Data Center Construction Market
Infrastructure Construction
New Zealand Data Center Construction Market
Infrastructure Construction
Infrastructure Sector in Asia Pacific Market
Infrastructure Construction
Taiwan Data Center Construction Market
Infrastructure Construction
Gas Pipeline Infrastructure Market