
 Saudi Arabia Roofing Market | 2026-2036
Saudi Arabia Roofing Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Roofing Market Insights
Preventive maintenance contracts and extended warranty service layers is consolidating value capture away from pure product sales in the Saudi Arabia roofing sector. SABIC leverages its petrochemical feedstock position to dominate polymer-based membrane supply. Saudi Ceramic Company anchors traditional clay tile production with established kiln infrastructure across the Kingdom. Saint-Gobain competes through technical insulation integration with roofing system specifications.
Roofing encompasses the external weatherproof envelope installed atop building structures, typically comprising bituminous membranes, metal panels, clay or concrete tiles, or synthetic polymers engineered to achieve specified U-values and wind uplift resistance. Its primary function is structural protection combined with thermal regulation of interior conditioned spaces. Metal roofing and PVC membrane segments are capturing disproportionate share in commercial giga-projects where lifecycle cost metrics outweigh first-cost considerations. Clay tiles retain entrenched position in premium residential developments across Riyadh and Jeddah where aesthetic conformity to regional architectural idioms governs selection. Flat roof system demand tracks institutional and healthcare construction where mechanical equipment mounting requirements predominate.
Saudi Building Code enforcement through the Saudi Standards, Metrology and Quality Organization (SASO) mandates minimum thermal performance ratings that disqualify legacy material specifications. The Ministry of Municipal and Rural Affairs and Housing (MOMRAH) coordinates municipal permitting that increasingly requires green building compliance for projects above threshold scales. SFDA oversight of construction chemical imports affects adhesive and sealant availability for membrane system installation. Stakeholders must monitor evolving SASO energy efficiency tier upgrades and their downstream specification impacts on approved product lists.
Market Dynamics
Vision 2030 giga-projects are compressing procurement cycles and consolidating buyer power around lifecycle-cost specifications rather than first-cost bidding. This structural shift favors integrated system suppliers capable of delivering thermal performance guarantees backed by extended warranty structures.
Growth Catalysts
- Vision 2030 hospitality construction:Commercial giga-projects along the Red Sea coast specify high-performance roofing systems with 25-year service life guarantees. Mega-developers bundle roofing into design-build contracts that accelerate material qualification timelines.
- SASO energy efficiency tiers:Upgraded Saudi Building Code thermal performance mandates disqualify legacy bituminous specifications. Compliance deadlines force asset owners into accelerated re-roofing cycles on existing commercial stock.
- Polymer membrane technology:TPO and PVC single-ply systems capture specification share in flat roof applications where mechanical equipment density requires seamless waterproofing integrity. Material suppliers integrate technical support into project delivery.
Market Restraints
- Petrochemical feedstock volatility:Polymer membrane production depends on ethylene and propylene derivatives whose prices track crude oil fluctuations. Margin compression hits specialty membrane converters without backward integration into base resin supply.
- Clay tile kiln concentration:Traditional ceramic roofing production clusters around Riyadh and limited coastal facilities. Transportation cost penalties constrain tile competitiveness in remote giga-project sites.
- Technical labor scarcity:Certified membrane welding and hot-work installation requires skilled crews in short supply across the Kingdom. Training pipeline gaps extend project mobilization timelines.
Strategic Opportunities
- Neom and Red Sea Project corridors:Unprecedented construction velocity in northwestern giga-developments creates demand for roofing systems with accelerated installation protocols. Prefabricated panel solutions reduce on-site labor dependency.
- Preventive maintenance service layers:Extended warranty and inspection contracts capture recurring revenue streams detached from product-only sales. Facilities management integrators seek roofing partners with predictive analytics capabilities.
- Cool roof incentive alignment:SASO solar reflectance index requirements for commercial buildings above threshold scales create specification pull for high-albedo membrane and coating systems. Material suppliers bundle thermal performance modeling into pre-sale engineering.
Industry Challenges
- Certification timeline compression:SASO product conformity assessment procedures for imported membrane systems extend lead times. Distributors face working capital pressure from inventory builds awaiting approval.
- Integration complexity with MEP systems:Flat roof specifications must coordinate waterproofing integrity with HVAC, solar, and drainage penetrations. Design-assist contracting models shift liability exposure to roofing contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Roofing Market |
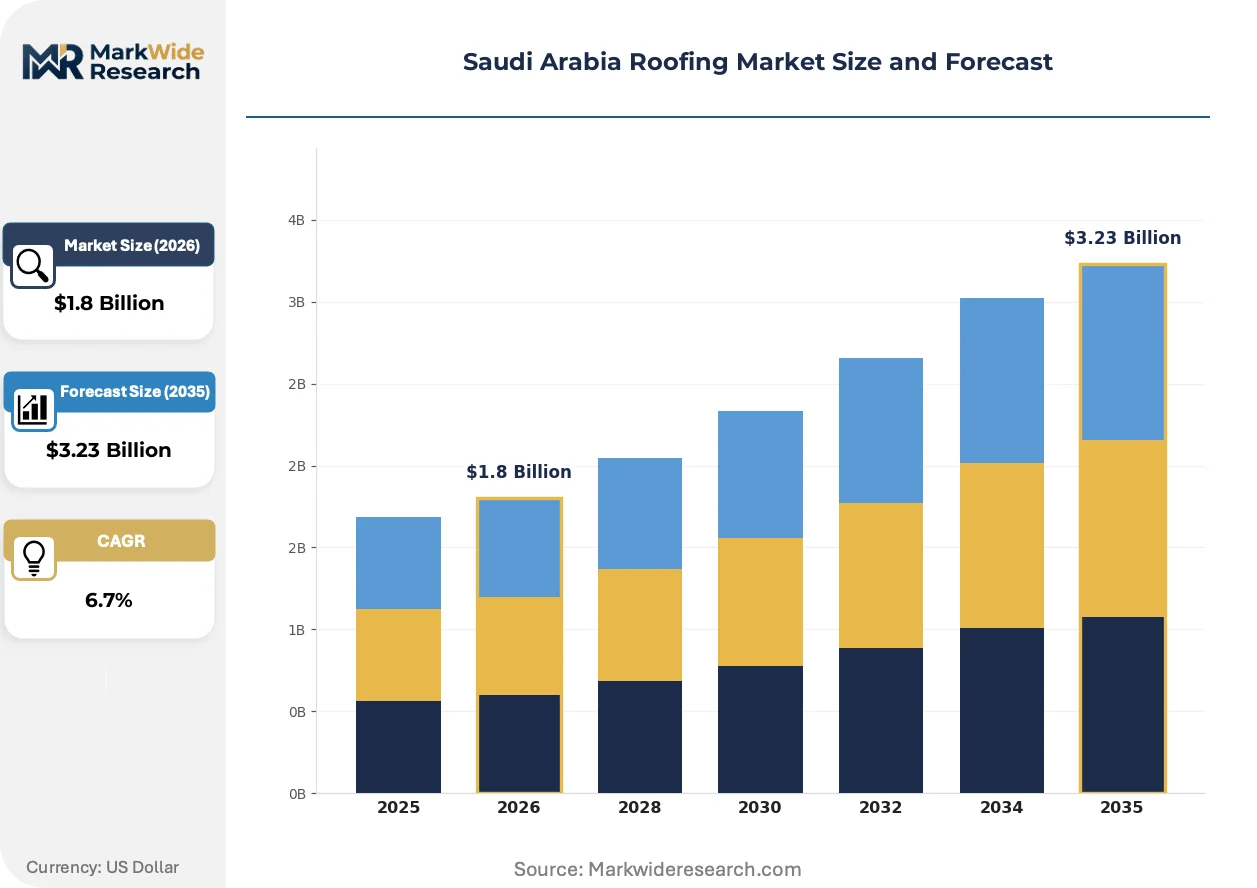
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Asphalt Shingles, Clay Tiles, Metal Roofing, PVC Membrane Application: Residential, Commercial, Industrial, Institutional Roofing System: Flat Roofs, Pitched Roofs, Green Roofs, Membrane Systems End User: Homeowners, Contractors, Architects, Developers |
| Companies Covered | Saudi Basic Industries Corporation (SABIC), Saudi Ceramic Company, Saudi Bitumen Industries Co. Ltd (SABIT), Saint-Gobain, Owens Corning, Al Watania for Industries (AWI), Al Rajhi Building Solution Group, Arabian Fiberglass Insulation Company (AFICO), Alupco, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Roofing Market Trends and Innovations
Material science convergence with digital specification tools is reconfiguring how roofing systems are engineered, procured, and warranted across Saudi commercial construction.
Building-integrated photovoltaics (BIPV) is decentralizing the traditional separation between weatherproofing and energy generation functions. Hospitality and institutional developers in Neom and the Red Sea Project specify BIPV roof assemblies that consolidate structural, thermal, and electrical performance into single-source procurement. This convergence compresses subcontractor coordination costs while extending system warranty obligations to 20-year horizons.
SASO's progressive enforcement of Saudi Building Code thermal performance tiers is disqualifying conventional low-R-value assemblies from permitted commercial projects above threshold scales. The regulation forces importers and domestic converters to requalify product lines through accelerated testing protocols. Healthcare and educational construction segments respond fastest due to MOMRAH's stricter green building compliance thresholds for public institutional buildings.
Asset owners now unbundle roofing procurement from general contracting packages to engage directly with system manufacturers for design-assist and extended warranty coverage. This disintermediation shifts specification authority from cost-driven contractors to lifecycle-cost-focused facilities managers. Riyadh-based commercial property portfolios and Red Sea hospitality operators lead this behavioral transition, demanding predictive maintenance telemetry integrated into roof monitoring systems.
Saudi Arabia Roofing Market Segmentation
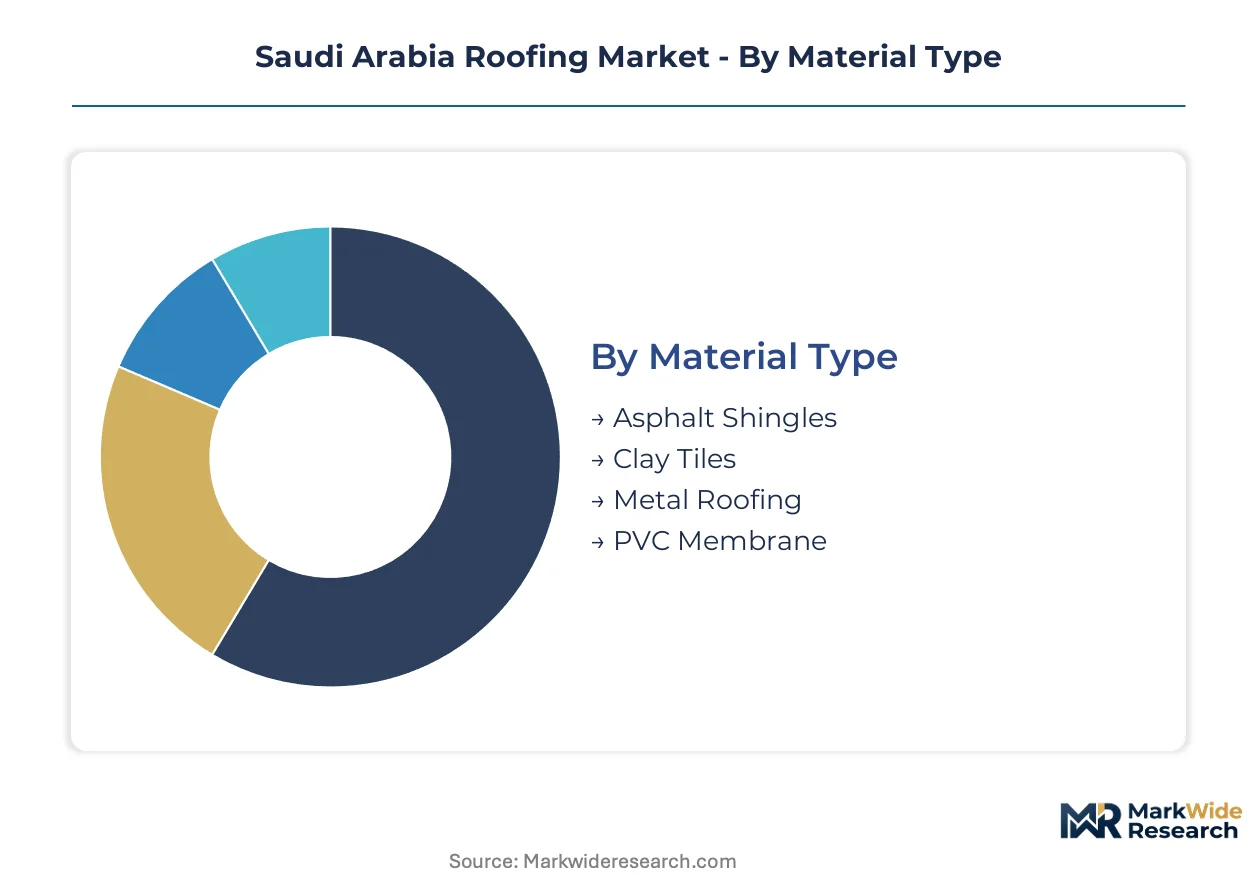
Saudi Arabia's roofing market fragments across four critical dimensions that determine procurement behavior and margin capture. Material selection governs thermal compliance under SASO mandates. Application type drives specification authority between cost-driven contractors and lifecycle-focused asset owners.
Material Type:
Buyer decisions hinge on thermal performance ratings required for Saudi Building Code compliance and lifecycle cost justification in giga-project procurement.
- Metal Roofing:Pre-painted galvanized steel and aluminum standing-seam panels deliver specified U-values for commercial hospitality developments. Red Sea Project contractors specify metal systems for 25-year warranty alignment with resort asset depreciation schedules.
- Clay Tiles:Traditional ceramic roofing fired in natural gas kilns retains entrenched specification across Riyadh and Jeddah premium residential. Aesthetic conformity to regional architectural idioms overrides first-cost disadvantages in upscale villa developments.
- PVC Membrane:Single-ply thermoplastic systems achieve seamless waterproofing for flat roof mechanical equipment density. Neom healthcare and data center specifications favor PVC for chemical resistance and weld integrity.
- Asphalt Shingles:Bituminous composite roofing dominates entry-level residential in secondary cities where SASO thermal tiers remain less stringently enforced. Import dependency creates working capital pressure for distributors awaiting SASO conformity assessment.
Metal roofing leads on scale; PVC membrane leads on momentum.
Application:
Construction velocity and specification authority diverge sharply between Vision 2030 giga-projects and legacy commercial stock.
- Commercial:Hospitality, retail, and office developments concentrate procurement power in design-build contracts. Red Sea Project and Neom developers bundle roofing into single-source packages with thermal performance guarantees.
- Residential:Villa and apartment construction splits between Riyadh-Jeddah premium clay tile specifications and Dammam-Khobar metal roofing adoption. MOMRAH municipal permitting increasingly mandates green building compliance for projects above threshold scales.
- Institutional:Healthcare and educational construction faces strictest SASO energy efficiency enforcement. Public procurement requires extended warranty structures and predictive maintenance telemetry integration.
- Industrial:Warehousing and manufacturing facilities prioritize rapid installation protocols over thermal optimization. Prefabricated panel solutions reduce on-site labor dependency in remote giga-project corridors.
Commercial applications command specification authority; institutional segments face tightest regulatory compliance timelines.
Roofing System:
Structural geometry determines waterproofing methodology and integration complexity with building mechanical systems.
- Membrane Systems:TPO and PVC single-ply assemblies dominate flat roof specifications where HVAC, solar, and drainage penetrations require seamless integrity. Design-assist contracting shifts liability exposure to specialized contractors.
- Pitched Roofs:Sloped geometries accommodate clay tile and metal panel runoff management for residential and hospitality aesthetics. Riyadh premium developments specify steep pitches for regional architectural authenticity.
- Flat Roofs:Horizontal assemblies concentrate in institutional and healthcare construction where equipment mounting density predominates. Waterproofing coordination with MEP systems extends design timelines.
- Green Roofs:Vegetated assemblies gain specification in Neom sustainability showcases and Riyadh commercial portfolios seeking SASO cool roof incentive alignment. Substrate weight and irrigation infrastructure constrain adoption.
Membrane systems lead on commercial penetration; green roofs expand most quickly from negligible base.
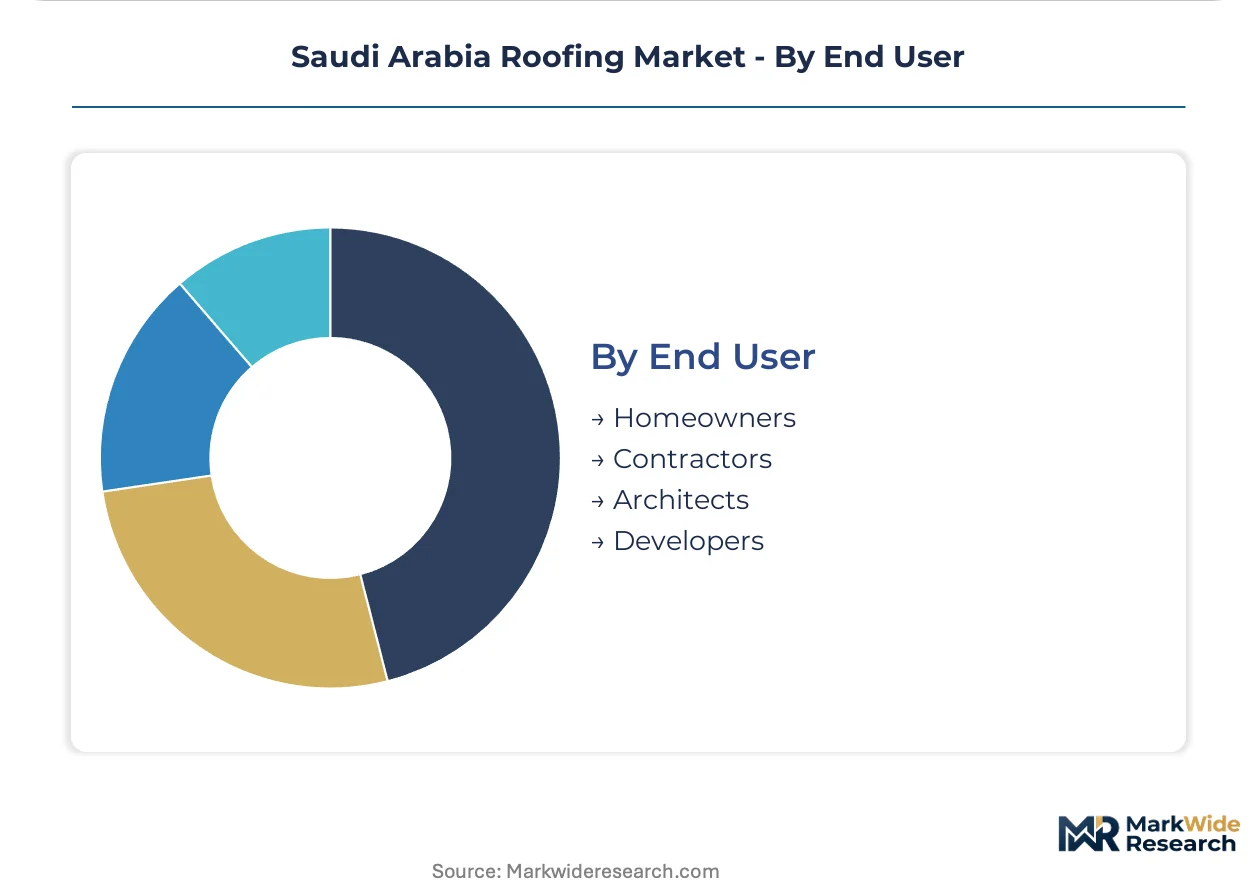
End User:
Procurement authority is shifting from general contractors to facilities managers demanding lifecycle-cost accountability.
- Developers:Vision 2030 giga-project sponsors unbundle roofing from construction packages to engage manufacturers directly. Extended warranty and predictive maintenance contracts capture recurring revenue streams.
- Contractors:Traditional general contracting retains influence in secondary city residential and industrial construction. Cost-driven bidding disadvantages integrated system suppliers without design-assist capabilities.
- Architects:Specification authority concentrates in hospitality and institutional segments where aesthetic and thermal performance requirements converge. Digital specification tools accelerate material qualification timelines.
- Homeowners:Individual purchasers dominate villa construction in Riyadh and Jeddah residential clusters. Clay tile selection prioritizes neighborhood conformity over thermal optimization.
Developers lead on procurement innovation; homeowners lag in specification sophistication.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward Riyadh and the Eastern Province where SASO certification infrastructure reduces compliance cost penalties against Red Sea coastal imports. This regulatory-arbitrage dynamic concentrates membrane system conversion capacity near petrochemical feedstock sources while giga-project demand pulls distribution westward.
Riyadh
The capital anchors clay tile kiln infrastructure and premium residential construction where aesthetic conformity governs material selection. MOMRAH municipal permitting enforces green building compliance thresholds for commercial projects above specified scales. Riyadh's commercial property portfolios lead procurement disintermediation toward direct manufacturer engagement for lifecycle-cost accountability.
Eastern Province
Dammam-Khobar metal roofing adoption accelerates in residential clusters where first-cost sensitivity outweighs thermal optimization preferences. SABIC's petrochemical complex proximity enables backward-integrated membrane production with reduced resin transportation penalties. The region's industrial warehousing construction prioritizes rapid installation protocols over energy efficiency tier compliance.
Western Region
Jeddah retains entrenched clay tile specification in upscale villa developments along the Red Sea coastal corridor. SFDA oversight of construction chemical imports affects adhesive availability for membrane system contractors mobilizing from Riyadh. The city's hospitality construction faces compressed procurement cycles under Vision 2030 timelines.
NEOM Northwest
The giga-development corridor generates unprecedented demand for prefabricated panel solutions reducing on-site labor dependency. BIPV roof assemblies consolidate weatherproofing and energy generation into single-source procurement with 20-year warranty horizons. Remote location transportation cost penalties disadvantage clay tile suppliers concentrated around Riyadh kilns.
Saudi Arabia Roofing Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with petrochemical-integrated membrane converters capturing value from SASO thermal tier upgrades while traditional clay tile fabricators defend regional aesthetic preferences. The market structure concentrates polymer supply around feedstock-advantaged producers, fragmenting across specialized membrane welders and ceramic kiln operators. Three archetypes dominate: petrochemical-integrated system suppliers, traditional building materials conglomerates with kiln assets, and international technical insulation integrators. Competitive moves center on design-assist contracting capabilities and extended warranty service layer expansion.
Among domestic petrochemical-integrated players, Saudi Basic Industries Corporation anchors polymer-based membrane supply through captive ethylene derivative access. Saudi Ceramic Company exemplifies traditional kiln infrastructure consolidation with established production across the Kingdom. Saint-Gobain occupies a position among international technical insulation specialists competing through system integration rather than component supply.
| Leading Market Players |
|---|
| Saudi Basic Industries Corporation (SABIC) |
| Saudi Ceramic Company |
| Saudi Bitumen Industries Co. Ltd (SABIT) |
| Saint-Gobain |
| Owens Corning |
| Al Watania for Industries (AWI) |
| Al Rajhi Building Solution Group |
| Arabian Fiberglass Insulation Company (AFICO) |
| Alupco |
| Others |
Pricing and Supply Chain Analysis
Petrochemical-integrated sovereign-backed producers anchor supply discipline through captive ethylene derivative access, compressing margin capture for non-integrated membrane converters while SASO thermal tier enforcement hardens price floors for compliant specifications. This ownership structure concentrates pricing power among feedstock-advantaged players and fragments negotiation leverage across import-dependent distributors awaiting conformity assessment timelines.
Pricing Analysis
Capacity additions in the Eastern Province are reshaping price floors for polymer membrane systems as SABIC's backward-integrated production eliminates resin transportation penalties. Project-based contracting dominates commercial giga-procurement, with price differentiation driven by SASO certification tier and extended warranty bundling. Cost compression in entry-level asphalt shingle segments intensifies because import dependency extends working capital cycles. Secondary city residential contractors exhibit highest price sensitivity, while Red Sea hospitality developers prioritize lifecycle-cost metrics over first-cost bidding.
Supply Chain Analysis
Ethylene and propylene derivative supply rests on Saudi petrochemical complex output concentrated in Jubail and Yanbu, with specialty polymer additives drawing from German and Japanese specialty chemical producers. Membrane system installation depends on certified welding equipment and hot-work tooling predominantly sourced from European manufacturers. Single-source vulnerability concentrates in SFDA-regulated construction chemical adhesives where import approval timelines create stockout risk. Distribution runs through Riyadh-based distributors with SASO certification infrastructure, extending last-mile reach into Neom and Red Sea corridors through project-dedicated logistics partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's roofing market represents a late-cycle quality story where procurement disintermediation favors system suppliers capable of thermal performance guarantees. Demand is shifting decisively toward premium specifications under Vision 2030 giga-project procurement, compressing share for pure product vendors without design-assist capabilities.
For Market Incumbents: To counter margin erosion from petrochemical feedstock volatility, SABIC-integrated players should deepen captive resin conversion into TPO and PVC membrane systems with embedded technical support. Certification investment in accelerated SASO testing protocols preserves specification access as compliance timelines compress. Channel control through direct developer engagement in Riyadh commercial portfolios captures lifecycle-cost accountability away from general contracting intermediaries. For New Entrants and Emerging Players: The premium-economy price-point gap in institutional healthcare construction creates white-space opportunity for membrane specialists with predictive maintenance telemetry integration. Neom's remote location penalties disadvantage traditional clay tile suppliers, opening prefabricated panel solutions to challengers with modular manufacturing footprints. A design-assist contracting model targeting MOMRAH green building compliance thresholds offers the most penetrable go-to-market angle against established distributors. For Investors and Strategic Acquirers: Valuations sit cheapest among non-integrated membrane converters facing resin cost pressure without feedstock capture. Long-term viability over the next decade hinges on preventive maintenance service layer expansion detaching revenue from construction cyclicality. The signal to watch is SASO energy efficiency tier upgrade announcements forcing accelerated re-roofing cycles on existing commercial stock.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Resin Supply | Captive ethylene derivative access eliminates margin compression from crude-linked feedstock volatility for SABIC-anchored producers. |
| Extended Warranty Service Layer Expansion | Predictive maintenance contracts with Riyadh commercial portfolios generate recurring revenue detached from product-only sales cycles. |
| SASO Certification Fast-Track Investment | Accelerated conformity assessment protocols reduce inventory holding periods for distributors awaiting membrane system approval. |
| Prefabricated Panel Manufacturing Scale-Up | Modular production addresses Neom labor scarcity while compressing installation timelines for remote giga-project corridors. |
| Building-Integrated Photovoltaics Partnership | BIPV roof assemblies consolidate weatherproofing and energy generation into single-source procurement with 20-year warranty alignment. |
Research Methodology
Bottom-up construction activity modeling reconciled against top-down petrochemical feedstock tracking forms the analytical core of this study. Primary interviews with membrane system contractors, facilities management directors at Red Sea hospitality operators, SASO certification specialists, and MOMRAH municipal permitting officers combined with secondary validation from customs import records, Saudi Building Code enforcement bulletins, and Vision 2030 project development databases. Triangulation between procurement volume estimates and resin consumption patterns cross-checks segment-level assumptions.
Historical trendline analysis of material specification shifts across the analysis window informs projection frameworks. Segmentation dimensions modeled include material type, application category, roofing system geometry, and end-user procurement authority. CAGRs derive from elasticity-adjusted demand curves incorporating SASO regulatory phase-in schedules and giga-project construction velocity assumptions. Forecast inputs incorporate petrochemical price correlation coefficients and certified installer pipeline constraints.
Caveats apply where SFDA import approval timeline extensions or MOMRAH green building threshold adjustments could materially shift the outlook. Forecasts reflect assumptions regarding Vision 2030 project commissioning schedules and SASO energy efficiency tier enforcement cadence. A small set of named triggers—SASO tier upgrade announcements, Neom construction velocity revisions, and feedstock price volatility spikes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Construction
Vietnam Structural Steel Fabrication Market
Structural Construction
Prefabricated Steel Bridge Market
Structural Construction
UAE Prefabricated Building and Structural Steel Market
Structural Construction
South Korea Construction Market
Structural Construction
GCC Prefabricated Building and Structural Steel Market
Structural Construction
Timber Frame Construction Market
Structural Construction
North America Structural Steel Fabrication Market
Structural Construction
Italy Concrete Railway Sleepers Market
Structural Construction
GCC Structural Steel Fabrication Market
Structural Construction
Bridge Bearings Market
Structural Construction
H Beam Market
Structural Construction
Saudi Arabia Structural Steel Fabrication Market
Structural Construction
Sandwich Plate System Market
Structural Construction
Canada Composite Repair Market
Structural Construction
Bridge Construction Market
Structural Construction
Saudi Arabia Prefabricated Building and Structural Steel Market