
 GCC Structural Steel Fabrication Market | 2026-2036
GCC Structural Steel Fabrication Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Structural Steel Fabrication Market Analysis
Saudi Arabia's giga-project pipeline is rewriting capacity assumptions across the GCC structural steel value chain. Zamil Steel's Structural Steel Division dominates the kingdom's heavy-truss segment through captive rolling and in-house coating capabilities. Al Yamamah Steel Industries Co. anchors the central region with fabrication yards positioned within two hours of Riyadh's mega-project sites. Hidada Ltd Co. differentiates through specialized industrial module assembly serving Jubail's petrochemical corridor.
Structural steel fabrication encompasses the cutting, welding, coating, and assembly of hot-rolled sections into engineered frameworks for buildings and infrastructure, typically using carbon steel grades with yield strengths between 250 and 355 MPa and protective zinc or intumescent coatings for corrosion and fire resistance. The process transforms raw I-beams, channels, plates, and angles into project-specific assemblies that bear vertical and lateral loads in commercial, industrial, and infrastructure applications. Commercial construction commands the largest application share as Saudi giga-projects and UAE mixed-use towers sustain heavy order books, while infrastructure development represents the fastest-expanding segment driven by rail, bridge, and utility investments across the six GCC states. Welding technology leads the process hierarchy, though coating is gaining margin traction as fire-rating specifications tighten under updated national building codes.
Saudi Arabia's Saudi Building Code and the UAE's Fire and Life Safety Code, alongside the Gulf Standardization Organization's steel quality protocols, are mandating enhanced material certification and traceability that filter market access toward fabricators with integrated testing laboratories. These regulatory layers elevate compliance costs for smaller operators while rewarding scale investments in automated cutting and robotic welding systems. Stakeholders must monitor how Bahrain, Oman, and Kuwait adapt their national construction codes to align with Saudi-Emirati standards, as regulatory convergence will determine which fabrication networks capture cross-border project flows.
Market Dynamics
Saudi Arabia's sovereign wealth-backed giga-developments are compressing traditional steel delivery timelines, forcing fabricators to automate cutting and welding workflows while expanding in-house coating capacity to meet compressed procurement calendars.
Growth Catalysts
- Saudi Building Code traceability mandates:Material certification requirements are filtering market access toward fabricators with integrated testing laboratories, rewarding scale investments in automated quality systems.
- Qatar's post-World Cup infrastructure transition:Stadium and transport assets are converting to commercial and hospitality use, sustaining structural steel demand through adaptive reuse projects.
- Robotic welding adoption:Fabricators deploying automated arc systems are reducing rework rates and accelerating throughput for complex truss assemblies in Riyadh's commercial towers.
Market Restraints
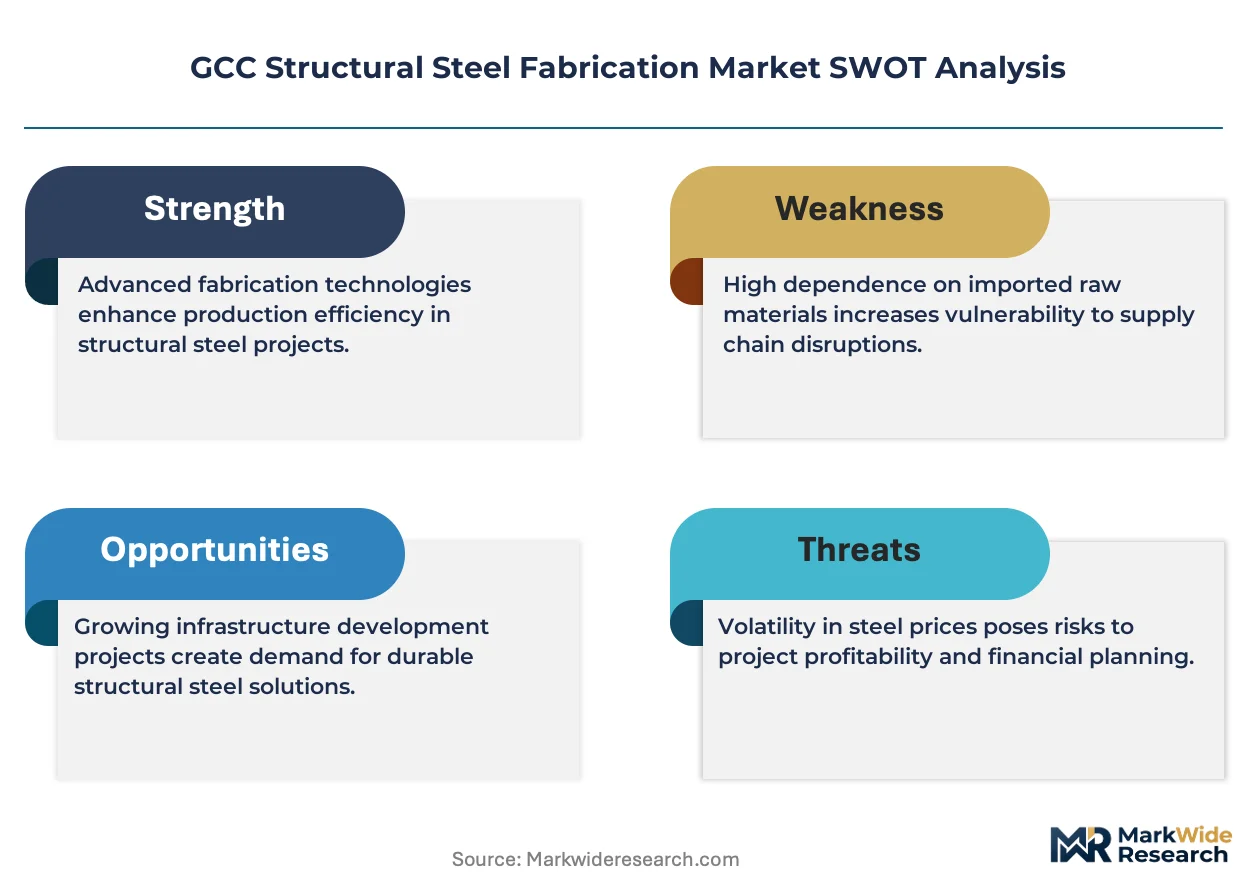
- Hot-rolled coil import dependency:GCC fabricators rely on imported feedstock from East Asian mills, exposing margins to freight volatility and currency fluctuation.
- Saudi-Emirati regulatory divergence:Misaligned fire-rating specifications between the Saudi Building Code and UAE Fire and Life Safety Code complicate cross-border project execution.
- Skilled welder scarcity:Certified structural welders command premium wages, constraining output expansion for mid-scale fabrication yards.
Strategic Opportunities
- Oman's industrial corridor development:Duqm Special Economic Zone petrochemical investments are creating demand for modular structural assemblies with limited local fabrication capacity.
- Intumescent coating convergence with digital application:Automated spray systems paired with real-time thickness monitoring are opening premium-margin fire-protection service lines.
- Bahrain's national construction code alignment:Anticipated harmonization with Saudi-Emirati standards positions compliant fabricators to capture cross-border project flows.
Industry Challenges
- Multi-code certification timelines:Fabricators serving both Saudi and UAE markets must maintain parallel testing protocols, extending project qualification periods.
- Legacy ERP integration with shop-floor automation:Mid-scale yards face data architecture gaps when connecting robotic welding cells to existing production scheduling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Structural Steel Fabrication Market |
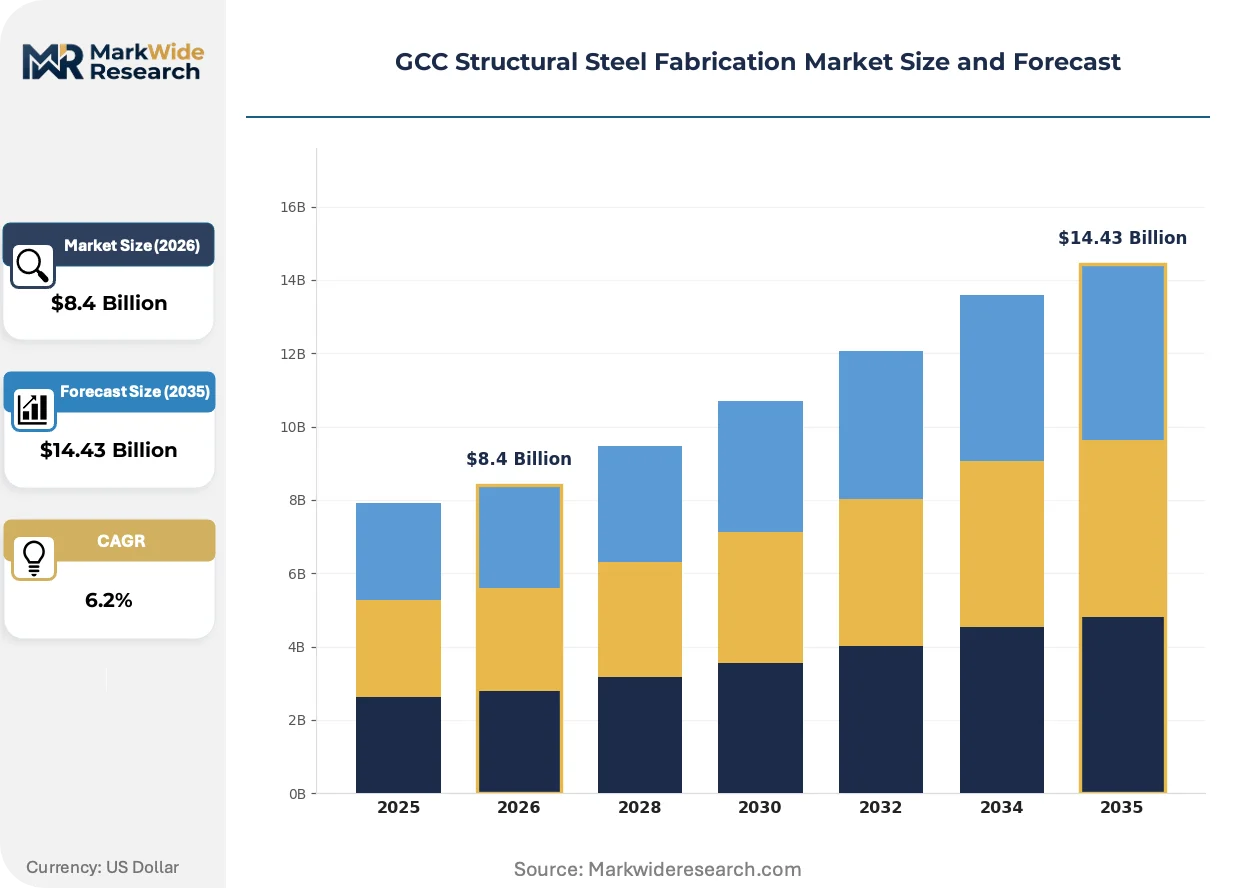
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: I-Beams, Channels, Plates, Angles Application: Commercial Construction, Industrial Projects, Residential Buildings, Infrastructure Development End User: Contractors, Architects, Engineers, Fabricators Technology: Welding, Cutting, Coating, Assembly |
| Companies Covered | Al Shahin Company for Metal Industries, IMCC, Arabian International Company for Steel Structures, Techno Steel, Standard Steel Fabrication Co. LLC, Al Yamamah Steel Industries Co., Hidada Ltd Co., Zamil Steel's Structural Steel Division, Mabani Steel LLC, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Structural Steel Fabrication Market Emerging Trajectories
Digital coating systems and automated quality verification are reshaping how structural steel moves from raw sections to site-ready assemblies across GCC fabrication networks.
Robotic gas metal arc welding is migrating from high-volume commercial tower production into mid-scale infrastructure fabrication. Saudi giga-project contractors are mandating automated weld traceability for primary structural connections. The technology is migrating from premium commercial applications toward standardized bridge and utility structures as equipment costs decline.
The UAE Fire and Life Safety Code's updated intumescent coating thickness specifications are forcing recalibration of spray booth configurations. Third-party inspection intervals have tightened from annual to semi-annual cycles. Industrial module fabricators serving Jubail's petrochemical corridor are investing in real-time dry-film thickness monitoring to pre-empt compliance failures.
Consolidated procurement desks at sovereign wealth-backed developers are unbundling fabrication from erection contracts. Single-source accountability for design-build structural packages is displacing fragmented subcontractor networks. This concentration is most visible in Riyadh's Diriyah and Qiddiya developments, where master contractors now pre-qualify fabricators on integrated coating and logistics capability.
GCC Structural Steel Fabrication Market Segmentation
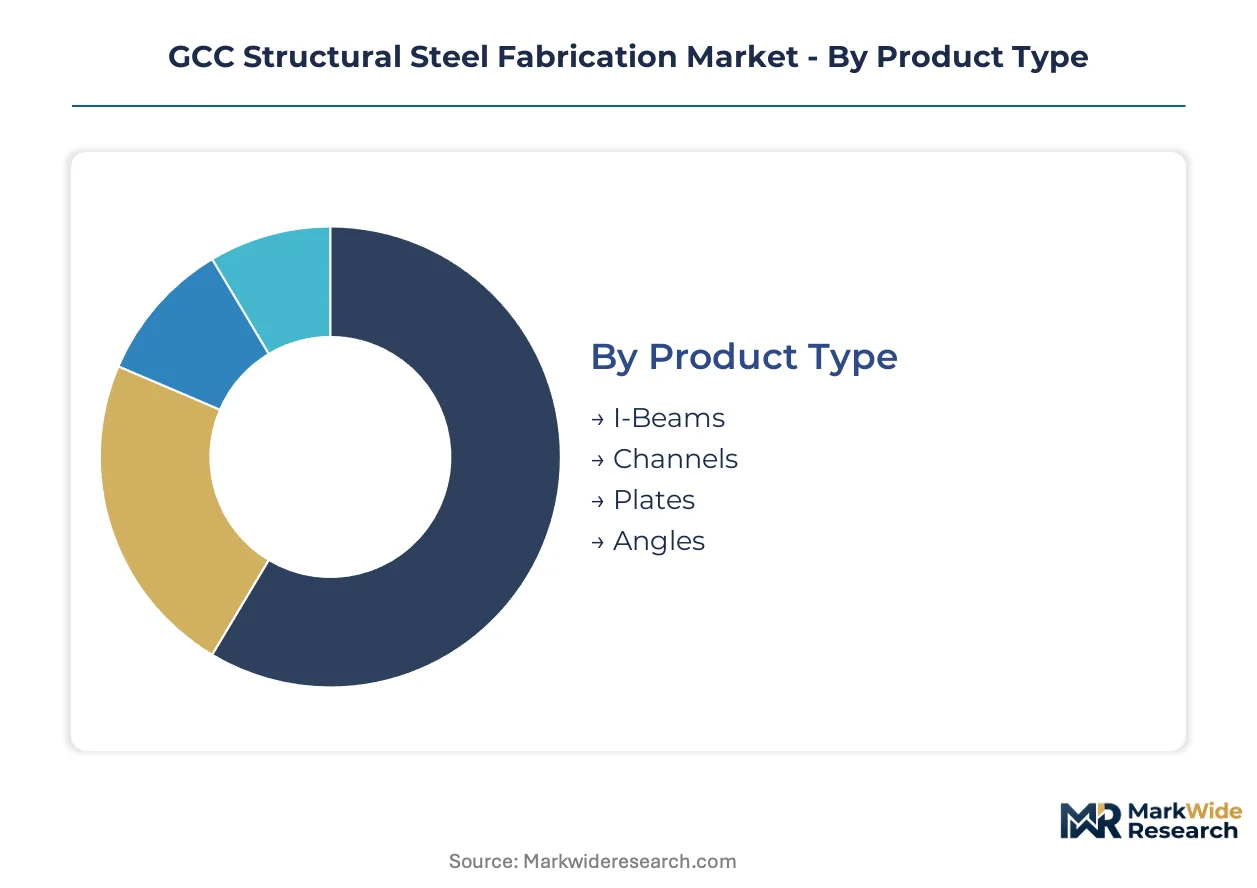
Structural steel fabrication in the GCC divides across product geometries, construction applications, and process technologies that each carry distinct procurement protocols. Saudi giga-projects and UAE commercial towers are compressing traditional specification cycles, forcing fabricators to align segment-specific capabilities with sovereign wealth-backed delivery timelines.
Product Type:
Hot-rolled sections span a use-case spectrum from heavy vertical columns to lightweight bracing elements, with specification grades tied directly to load-bearing requirements in Riyadh's commercial towers and Jeddah's infrastructure corridors.
- I-Beams:Wide-flange and standard sections with yield strengths of 250-355 MPa form the primary vertical and horizontal framing in commercial high-rises. Demand concentrates in Riyadh's Diriyah and Qiddiya developments where sovereign wealth-backed contractors mandate mill certificates and automated weld traceability for primary connections.
- Plates:Flat-rolled carbon steel in thicknesses from 6mm to 100mm enable custom connection plates, gussets, and built-up beam assemblies. Procurement calendars in Jubail's petrochemical corridor favor fabricators with in-house plasma cutting and integrated coating booths for corrosion-resistant module fabrication.
- Channels:C-shaped sections serve secondary framing, purlins, and bracing applications with lighter load requirements.
- Angles:L-shaped sections function as lintels, bracing members, and connection cleats in standardized truss assemblies.
Established volume favors I-Beams; emerging adoption favors Plates in modular industrial applications.
Application:
Construction end-uses stratify by project scale, code complexity, and coating specification intensity across the six GCC states.
- Commercial Construction:Mixed-use towers, retail complexes, and hospitality structures absorb the heaviest tonnage with demanding fire-rating specifications. Saudi Arabia's giga-developments in Riyadh and Jeddah sustain record order books while compressing traditional steel delivery timelines through consolidated procurement desks.
- Infrastructure Development:Rail viaducts, bridge structures, and utility frameworks are expanding most quickly as Qatar transitions post-World Cup assets and Oman develops the Duqm corridor. The segment demands certified weld procedures and third-party inspection protocols that filter market access toward fabricators with integrated testing laboratories.
- Industrial Projects:Petrochemical modules, power plant structures, and manufacturing facilities require specialized corrosion protection and seismic detailing.
- Residential Buildings:Mid-rise housing and villa developments utilize standardized light-gauge and structural steel framing with simpler coating requirements.
Commercial Construction commands current procurement volume; Infrastructure Development is climbing the fastest on rail and bridge investments.
End User:
Stakeholder influence over specification and procurement varies by project delivery model and contracting structure.
- Contractors:Design-build and EPC firms control fabrication procurement for Saudi giga-projects and UAE mixed-use towers, increasingly mandating single-source accountability for structural packages that unbundle fabrication from erection.
- Engineers:Structural design consultants specify grade, coating thickness, and weld quality levels that determine fabricator qualification for primary structural connections in commercial high-rises.
- Architects:Design visionaries influence exposed steel aesthetics and fire-rating integration in signature developments.
- Fabricators:Direct end-users of raw sections and processing equipment face compressed margins from hot-rolled coil import dependency and skilled welder scarcity.
Contractors dominate procurement decision-making; Engineers control technical compliance gates.
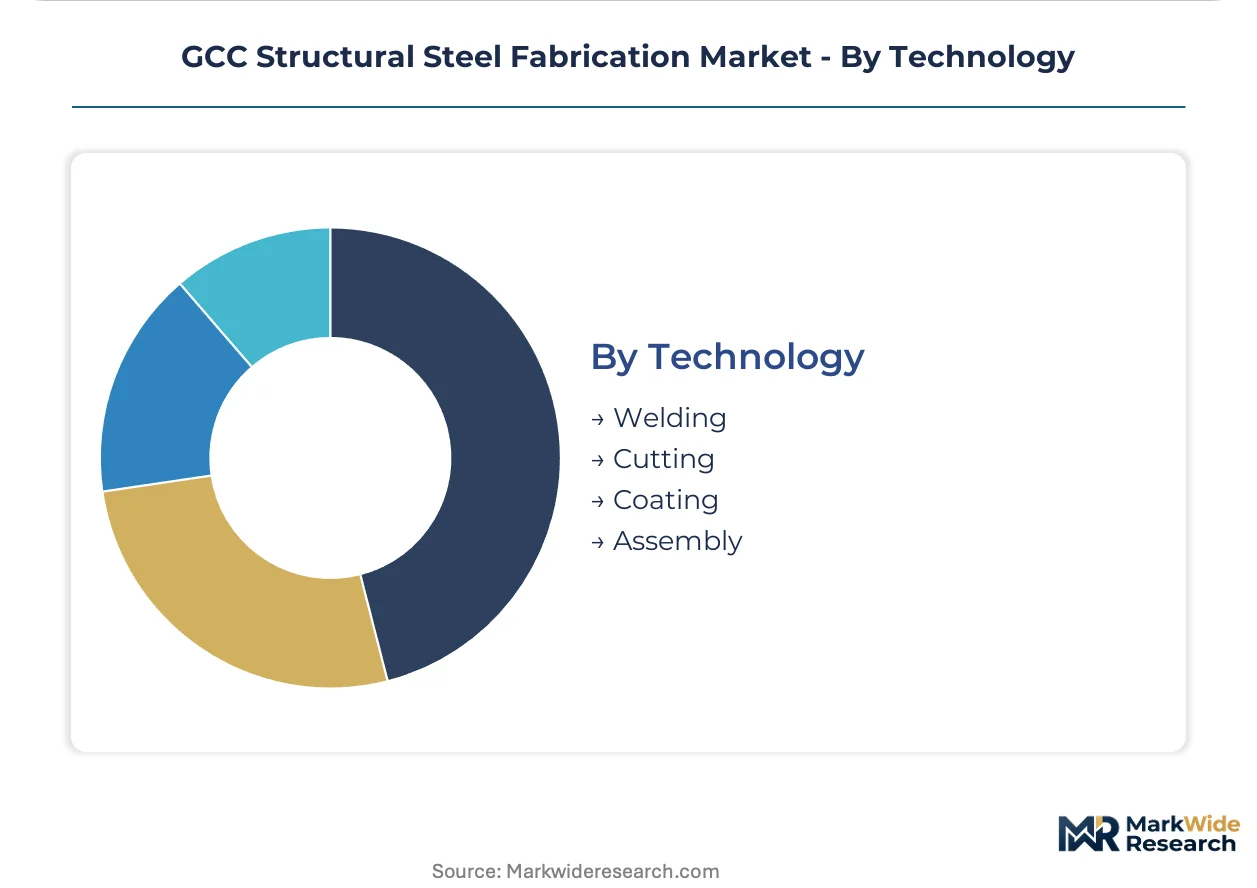
Technology:
Process capabilities determine margin structure and market access under tightening Saudi Building Code and UAE Fire and Life Safety Code requirements.
- Welding:Gas metal arc and flux-cored processes transform raw sections into engineered assemblies, with robotic systems reducing rework rates in Riyadh's commercial tower production. Zamil Steel and Al Yamamah Steel Industries Co. anchor capacity for heavy-truss and central region demand respectively.
- Coating:Zinc-rich primers and intumescent fire-protection systems are gaining margin traction as automated spray systems with real-time thickness monitoring open premium service lines under updated code specifications.
- Cutting:Plasma and oxy-fuel processes prepare sections for fit-up, with automated nesting software optimizing material yield.
- Assembly:Jig-based fit-up and trial erection procedures verify dimensional accuracy before site delivery.
Welding anchors process revenue; Coating is gaining share fastest on fire-rating specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Saudi Building Code anchors the dominant geography, with SFDA-aligned material traceability requirements filtering market access toward fabricators with integrated testing laboratories across the six GCC states.
Saudi Arabia
Sovereign wealth-backed giga-developments in Riyadh and Jeddah are compressing steel delivery timelines through consolidated procurement desks. The Saudi Building Code mandates enhanced material certification that rewards scale investments in automated quality systems. Zamil Steel's Structural Steel Division anchors heavy-truss capacity from its Eastern Province fabrication yards.
United Arab Emirates
Mixed-use towers in Dubai and Abu Dhabi sustain heavy order books with demanding fire-rating specifications under the UAE Fire and Life Safety Code. MOHAP-aligned inspection protocols filter fabricator qualification toward operators with in-house coating booths. Mabani Steel LLC occupies a central position serving the emirates' commercial construction pipeline.
Qatar
Post-World Cup infrastructure transition is converting stadium and transport assets to commercial and hospitality use through adaptive reuse projects. The country's national construction regulator maintains weld procedure certification requirements that sustain demand for qualified fabrication networks. Doha-based yards are repositioning capacity toward modular structural assemblies.
Oman
Duqm Special Economic Zone petrochemical investments are creating demand for industrial module fabrication with limited local capacity. The sultanate's national standardization body is anticipated to align construction codes with Saudi-Emirati frameworks. Fabricators serving the central corridor face compressed margins from skilled welder scarcity and feedstock import dependency.
Kuwait
Public infrastructure renewal and residential expansion are sustaining structural steel demand through EPC-contracted projects. The national quality authority maintains steel import inspection protocols that elevate compliance costs for smaller operators. Kuwait City-based contractors are consolidating procurement toward single-source structural packages with integrated coating capability.
GCC Structural Steel Fabrication Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market structures around vertically integrated heavy-truss specialists, regional-scale commercial fabricators, and mid-scale industrial module assemblers. Three archetypes dominate: sovereign wealth-aligned giga-project suppliers, code-compliant premium coating operators, and petrochemical corridor specialists. Competitive moves center on automated welding cell deployment and in-house coating capacity expansion to meet compressed delivery timelines.
Among Saudi-based fabricators, Zamil Steel's Structural Steel Division and Al Yamamah Steel Industries Co. exemplify the scale-driven tier with captive rolling and central-region positioning. Hidada Ltd Co. occupies the industrial specialization vector serving Jubail's petrochemical corridor. These three anchors represent distinct strategic postures: integrated heavy-truss supply, regional commercial proximity, and modular assembly for corrosion-critical applications.
| Leading Market Players |
|---|
| Al Shahin Company for Metal Industries |
| IMCC |
| Arabian International Company for Steel Structures |
| Techno Steel |
| Standard Steel Fabrication Co. LLC |
| Al Yamamah Steel Industries Co. |
| Hidada Ltd Co. |
| Zamil Steel's Structural Steel Division |
| Mabani Steel LLC |
| Others |
Supply Flow & Price Mechanics
Hot-rolled coil import dependency from East Asian mills determines both the spread between premium certified and standard-grade fabrication tiers and the geographic clustering of GCC supply networks around Jeddah and Jebel Ali port corridors.
Pricing Analysis
Saudi Arabia commands 15-20% price premiums over UAE fabrication yards due to compressed delivery timelines at Riyadh giga-project sites and SFDA-aligned certification overhead. Three-tier pricing structure across premium certified, standard commercial, and economy-grade levels reflects differentiation by weld traceability depth and coating specification intensity. Cost compression in economy-grade segments is intensifying because mid-scale yards compete for fragmented residential and light commercial work. Contractors serving sovereign wealth-backed developments show least price sensitivity; mid-scale fabricators chasing spot infrastructure contracts face acute margin pressure.
Supply Chain Analysis
Upstream feedstock for GCC structural steel fabrication draws from South Korea, Japan, and China as dominant hot-rolled coil sources, with Indian mills gaining share in lower-grade commercial segments. Raw material dependencies center on carbon steel slabs, zinc ingots for galvanizing, and intumescent chemical formulations for fire-protection systems. Single-source vulnerability concentrates in East Asian mill relationships where freight volatility and currency fluctuation transmit directly to fabrication margins. Distribution runs through port-advanced stocking yards in Jeddah, Jebel Ali, and Dammam before final cutting and welding at project-proximate facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidated procurement desks at sovereign wealth-backed developers are transforming structural steel fabrication into a platform-economy inflection, where single-source accountability for design-build packages displaces fragmented subcontractor networks and rewards interoperable digital coating and logistics capability.
For Market Incumbents: Build regulatory moats through SFDA and MOHAP-aligned integrated testing laboratories that filter competitor access to Saudi giga-project and UAE commercial tower pipelines. Deepen upstream control over hot-rolled coil supply through long-term offtake agreements with East Asian mills to buffer freight volatility. Expand robotic welding cell deployment to compress rework rates and defend margin position against emerging automated entrants from Bahrain and Oman. For New Entrants and Emerging Players: Establish a beachhead in Oman's Duqm Special Economic Zone where petrochemical module demand outstrips local fabrication capacity and regulatory alignment with Saudi-Emirati standards remains incomplete. Target adaptive reuse projects in Qatar's post-World Cup infrastructure transition where weld procedure certification requirements sustain demand but incumbent capacity is repositioning. Lead with automated coating booth investments paired with real-time thickness monitoring to differentiate on MOHAP inspection protocol compliance. For Investors and Strategic Acquirers: Saudi Building Code traceability mandates reshapes the acquisition landscape toward fabricators with captive rolling, in-house coating, and integrated logistics capability that can absorb compressed delivery timelines without margin erosion. Long-term viability centers on scale-advantaged operators with sovereign wealth project relationships and technology-forward welding automation. The signal to watch is Bahrain's national construction code alignment timing, which will determine cross-border project flow capture and justify premium multiples for early-compliant regional networks.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Welding Cell Deployment | Reduces rework rates for complex truss assemblies in Riyadh's Diriyah and Qiddiya developments. |
| In-House Coating Capacity Expansion | Captures premium-margin fire-protection service lines under tightened UAE Fire and Life Safety Code specifications. |
| Long-Term Hot-Rolled Coil Supply Agreement | Buffers margin volatility from East Asian mill import dependency and freight cost fluctuation. |
| Integrated Testing Laboratory Investment | Qualifies fabricators for SFDA-aligned material traceability mandates filtering Saudi giga-project access. |
| Duqm Special Economic Zone Facility Establishment | Positions for petrochemical module demand with limited incumbent fabrication capacity in Oman's central corridor. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs and trade data, Gulf Standardization Organization steel quality protocols, and SEC filings from publicly listed fabrication equipment suppliers. Primary interviews engaged fabrication yard operations directors, EPC contractor procurement leads, structural engineering consultants specifying weld quality levels, and coating system technical sales managers. Secondary validation drew from Saudi Building Code implementation guidance, UAE Fire and Life Safety Code update circulars, and port authority throughput statistics. Bottom-up tonnage estimates from individual project pipelines triangulate against top-down GDP-infrastructure elasticity models.
Forecast inputs span product geometry segmentation across I-beams, plates, channels, and angles; application intensity across commercial construction, infrastructure development, industrial projects, and residential buildings; and technology adoption curves for robotic welding, automated coating, and digital quality verification. CAGRs derive from segment-specific volume buildups normalized against historical procurement calendar patterns and sovereign wealth capital deployment schedules. Industry-specific forecast inputs include Saudi giga-project steel delivery timeline compression and Qatar post-World Cup asset conversion trajectories.
Sensitivities concentrate around East Asian hot-rolled coil supply disruption, Saudi-Emirati regulatory divergence on fire-rating specifications, and skilled welder wage inflation across the GCC. Forecasts embed assumptions regarding sovereign wealth capital commitment continuity and national construction code harmonization timing. Cross-checking against GCC customs import statistics and EPC contractor order backlog disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Construction
United Arab Emirates Structural Steel Fabrication Market
Structural Construction
Canada Composite Repair Market
Structural Construction
Saudi Arabia Prefabricated Building and Structural Steel Market
Structural Construction
Glue Laminated Beams Market
Structural Construction
US Heavy Movable Bridges Market
Structural Construction
Vietnam Structural Steel Fabrication Market
Structural Construction
Girder Market
Structural Construction
UAE Prefabricated Building and Structural Steel Market
Structural Construction
Timber Frame Construction Market
Structural Construction
Saudi Arabia Structural Steel Fabrication Market
Structural Construction
Prefabricated Steel Bridge Market
Structural Construction
Bridge Bearings Market
Structural Construction
Steel Beam Market
Structural Construction
Bridge Construction Market
Structural Construction
Self-Consolidating Concrete (SCC) Market
Structural Construction
North America Structural Steel Fabrication Market