
 Ceiling Expansion Joint Market | 2026-2036
Ceiling Expansion Joint Market Size, Share, and Industry Trends Forecast 2026-2036
Ceiling Expansion Joint Market Insights
REACH compliance in Europe is consolidating material sourcing requirements for ceiling expansion joint manufacturers. Balco leverages its fire-resistant technology portfolio to sustain specification rates across North American healthcare and transit infrastructure. EMSEAL Joint Systems anchors its competitive position through deep integration with seismic movement engineering standards. Witzenmann differentiates via metallic expansion joint specialization for high-temperature commercial HVAC ceiling penetrations.
Ceiling expansion joints are engineered gap-management assemblies installed at structural discontinuities in suspended ceiling systems, typically fabricated from aluminum extrusions, stainless steel covers, or elastomeric membranes with fire-retardant infill rated to ASTM E119 or EN 1363 temperature exposure criteria. These devices accommodate differential building movement from thermal cycling, seismic activity, or moisture-induced substrate deformation while preserving acoustic isolation and smoke barrier integrity. Metallic product types dominate current specification volumes due to durability and load-bearing capacity, yet hybrid configurations combining elastomeric seals with metal carriers represent the fastest-growing segment as architects seek multi-performance solutions for complex ceiling geometries. Application demand concentrates in commercial buildings and sports complexes where large clear spans generate substantial movement joints, with educational institutions emerging as a volume growth vector driven by modernized campus construction codes.
The National Fire Protection Association (NFPA) and International Building Code (IBC) in the United States, alongside the European Committee for Standardization (CEN) and EN 1399 fire resistance testing protocols, shape product certification requirements and market access conditions for ceiling expansion joint suppliers. China's Ministry of Housing and Urban-Rural Development (MOHURD) enforces GB 50016 fire prevention standards that mandate expansion joint fire ratings in public assembly occupancies above specified thresholds. Stakeholders must monitor evolving seismic design category reclassifications and green building material disclosure mandates that will determine specification eligibility and supplier qualification criteria across priority construction markets.
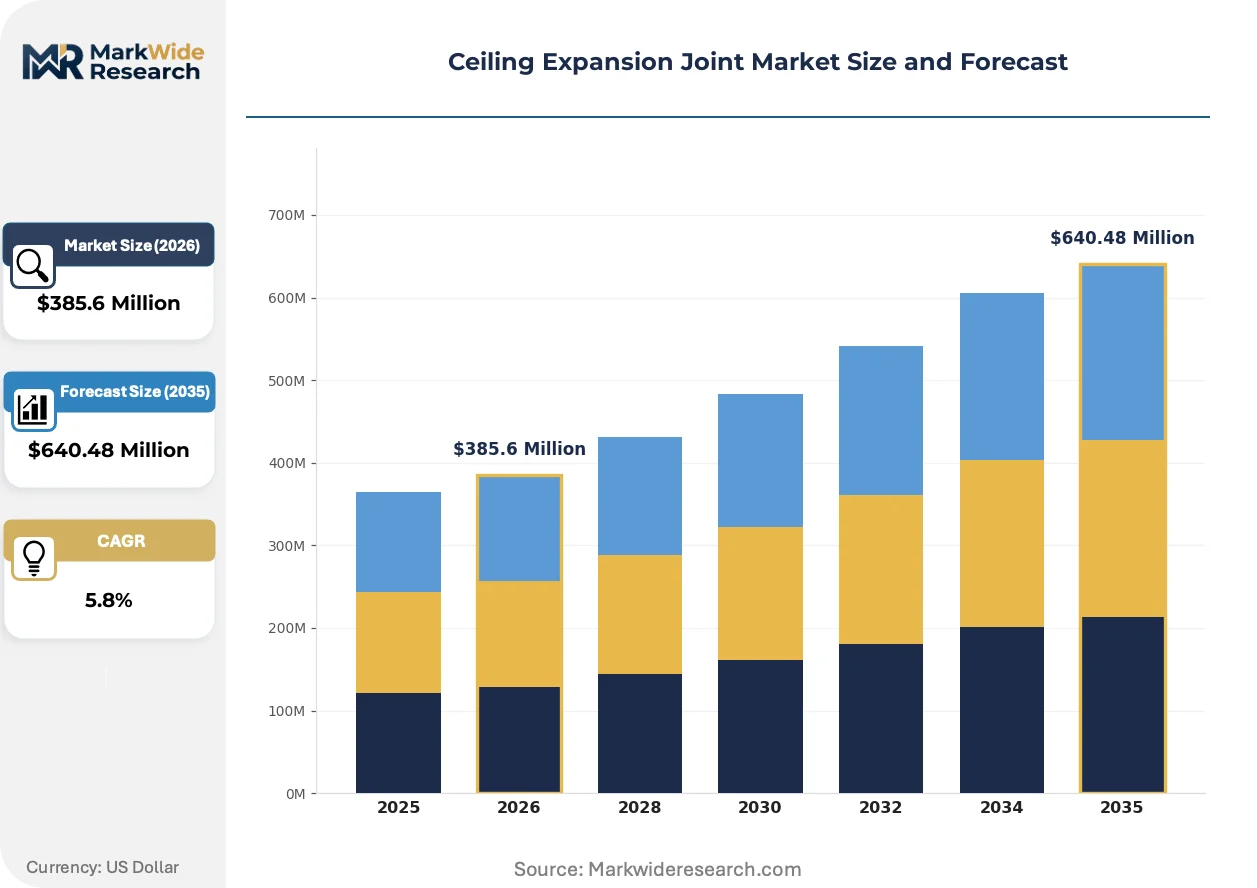
Market Dynamics
The ceiling expansion joint market is restructuring around seismic compliance mandates that now require fire-rated assemblies in high-occupancy commercial buildings, forcing specification upgrades across North American healthcare and transit infrastructure projects.
Growth Catalysts
- IBC Seismic Category Reclassification:Updated International Building Code provisions in the United States now mandate expansion joint fire ratings in assembly occupancies above 300 persons, driving specification volume in stadiums and convention centers.
- Hybrid Material Convergence:Architects are specifying elastomeric-metal composite assemblies for complex ceiling geometries that demand simultaneous acoustic isolation, smoke barrier integrity, and multi-directional movement accommodation.
- Campus Modernization Cycles:Educational institutions across Germany and China are replacing aging ceiling systems under accelerated building code renewal programs, creating concentrated demand for seismic-rated joint assemblies.
Market Restraints
- Aluminum Input Volatility:Extrusion-grade aluminum pricing fluctuations compress margin stability for metallic product manufacturers who cannot pass through material cost swings to locked public project contracts.
- REACH Compliance Consolidation:European Chemicals Agency restrictions on halogenated flame retardants are forcing reformulation of fire-rated infill materials, extending product recertification timelines by 12-18 months.
- Prefabricated Modular Substitutes:Integrated ceiling systems with factory-installed movement accommodation are capturing specification share in standardized commercial office builds, bypassing discrete expansion joint procurement.
Strategic Opportunities
- GB 50016 Public Assembly Mandates:China's Ministry of Housing and Urban-Rural Development enforcement of fire prevention standards in theaters and exhibition halls creates specification entry points for fire-rated metallic assemblies in tier-two cities.
- Digital Specification Platforms:Building information modeling-integrated product libraries are compressing the architect-to-contractor specification pathway, rewarding suppliers with parametrically configurable joint system databases.
- Acoustic-Seismic Convergence:Hybrid assemblies combining elastomeric seals with seismic-rated metal carriers address emerging multi-performance requirements in airport terminals and performing arts venues.
Industry Challenges
- ASTM E119 Certification Bottlenecks:Fire resistance testing facility capacity constraints are extending time-to-market for new product variants, particularly for hybrid configurations requiring multiple test protocols.
- Seismic Engineering Talent Scarcity:Specialized expertise in movement engineering calculations for complex ceiling geometries remains concentrated among a limited pool of consulting engineers, constraining project execution velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceiling Expansion Joint Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metallic, Elastomeric, Hybrid, Fiberglass, PVC Technology: Acoustic Isolation, Fire Resistant, Seismic Movement, Thermal Insulation, Water Tightness Application: Commercial Buildings, Educational Institutions, Entertainment Venues, Sports Complexes, Government Facilities End User: Construction Contractors, Interior Designers, Facility Management, Structural Engineers, Renovation Experts |
| Companies Covered | Balco, EMSEAL Joint Systems, Witzenmann, BOA Group, Trelleborg Sealing Solutions, U.S. Bellows, Senior Flexonics Pathway, Unaflex, Flexider, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceiling Expansion Joint Market Trends and Innovations
Product development in ceiling expansion joints is pivoting toward multi-performance integration, with manufacturers engineering assemblies that simultaneously address seismic movement, fire containment, and acoustic attenuation without discrete component layering.
Intumescent coating technologies are absorbing fire-protection functionality directly into metallic cover extrusions, eliminating separate fire-barrier infill components. Healthcare facility designers in the United States are specifying these integrated assemblies for surgical suite ceilings where maintenance access constraints favor simplified joint geometries. The technology is absorbing specification share from traditional three-layer systems by reducing installed depth and simplifying contractor training requirements.
REACH authorization procedures for alternative flame-retardant chemistries are accelerating material substitution timelines across European supply chains. Manufacturers serving German and French commercial building markets are reformulating elastomeric seals to meet ECHA substance restrictions while preserving EN 1363 fire resistance ratings. The regulatory pressure is compressing product development cycles and favoring suppliers with in-house polymer compounding capabilities over assembly-only competitors.
Specification authority is migrating from general contractors to specialized seismic engineering consultants who control movement joint placement in complex commercial structures. Large-span sports complex projects in China and the United States now route ceiling expansion joint selection through independent engineering peer review, displacing traditional distributor-led specification. This authority shift is visible most acutely in transit infrastructure projects where design-build contracts consolidate technical decision-making under single engineering entities.
Ceiling Expansion Joint Market Segmentation
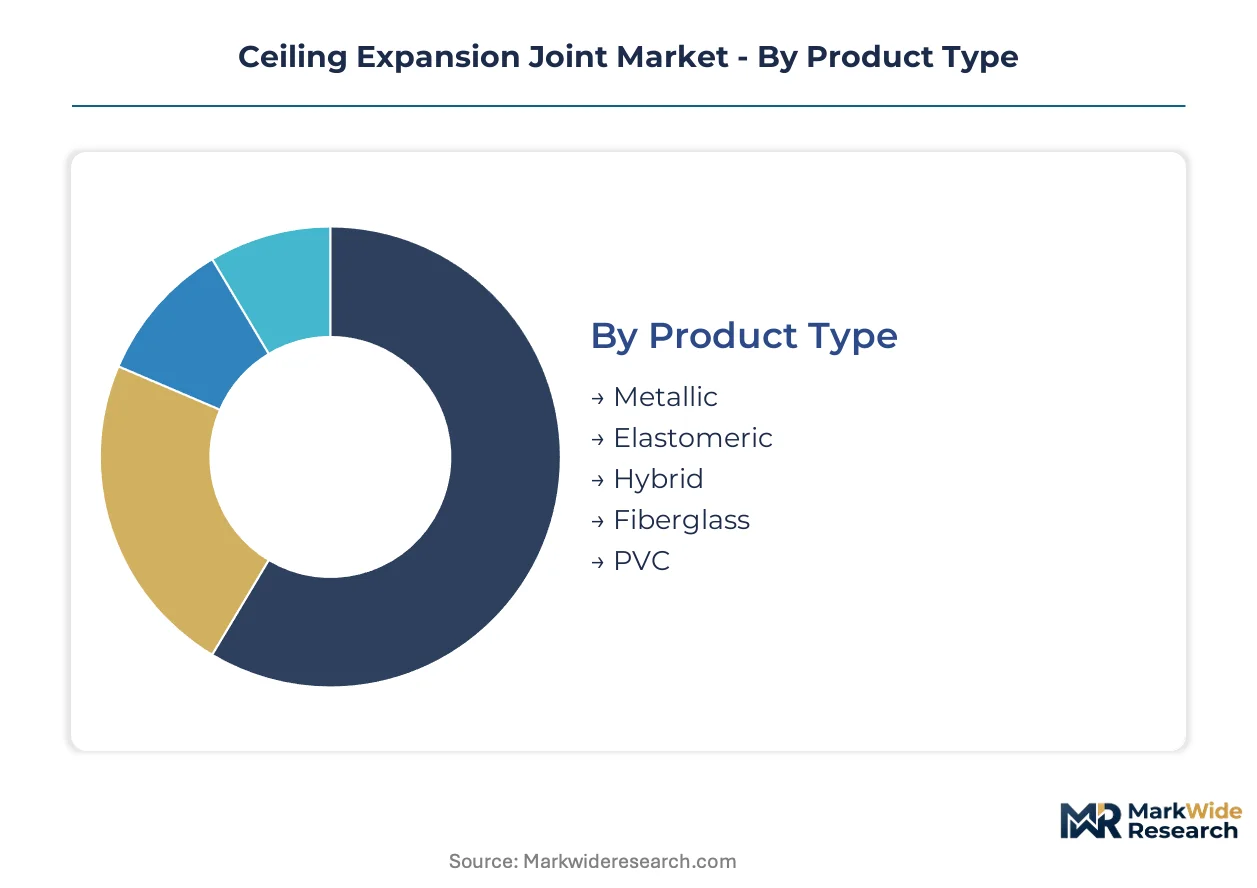
Ceiling expansion joint procurement diverges sharply across performance tiers, with certification requirements dictating specification pathways in high-occupancy infrastructure. Architects and contractors segment demand by movement capacity, fire rating, and acoustic attenuation needs rather than material cost alone.
Product Type:
ASTM E119 and EN 1363 fire resistance certifications impose divergent testing burdens across material categories, with metallic assemblies requiring sustained load-bearing validation under thermal exposure while elastomeric variants face additional smoke toxicity protocols.
- Metallic:Aluminum extrusions and stainless steel covers dominate procurement in United States healthcare and transit infrastructure where IBC seismic mandates require documented load-bearing capacity. Contractors prioritize these assemblies for high-occupancy commercial buildings despite aluminum input price volatility compressing manufacturer margins on locked public contracts.
- Hybrid:Elastomeric-metal composite configurations are gaining specification share fastest among airport terminals and performing arts venues demanding simultaneous acoustic isolation, smoke barrier integrity, and multi-directional movement accommodation. These assemblies command premium positioning by addressing complex ceiling geometries that discrete single-material solutions cannot satisfy.
- Elastomeric:Flexible membrane systems serve standardized commercial office builds with moderate movement requirements and constrained maintenance access.
- Fiberglass:Lightweight composite covers address corrosive environment applications in aquatic centers and industrial food processing facilities.
- PVC:Cost-driven specifications in budget-constrained educational renovation projects favor these entry-tier assemblies where fire ratings fall below threshold mandates.
Leading the category by volume: Metallic. Expanding most quickly: Hybrid.
Technology:
Specification authority migrates toward integrated performance bundles rather than discrete functional layers, with seismic movement engineering now routinely combined with fire containment and acoustic attenuation in single assemblies.
- Fire Resistant:Intumescent coating technologies absorb fire-protection functionality directly into metallic cover extrusions, eliminating separate barrier infill components. United States surgical suite designers specify these integrated assemblies where maintenance access constraints favor simplified joint geometries and reduced installed depth.
- Seismic Movement:Multi-directional accommodation systems anchor specification in China and United States sports complexes where large clear spans generate substantial differential building movement from thermal cycling and substrate deformation.
- Acoustic Isolation:Elastomeric dampening layers address STC rating requirements in performing arts venues and conference facilities.
- Thermal Insulation:Cold bridge interruption capabilities serve climate-controlled pharmaceutical manufacturing and data center ceiling penetrations.
- Water Tightness:Moisture barrier integration protects against condensation damage in aquatic center and greenhouse applications.
Dominant by specification frequency: Fire Resistant. Steepest adoption trajectory: Seismic Movement.
Application:
Building code renewal cycles concentrate demand in specific verticals, with educational institutions and entertainment venues undergoing accelerated modernization programs across Germany and China.
- Commercial Buildings:Office towers and retail complexes in United States urban cores drive metallic assembly procurement following updated IBC seismic compliance mandates. Specification volume concentrates in assembly occupancies above 300 persons where fire-rated joint systems are now compulsory.
- Educational Institutions:Campus modernization cycles across Germany and China are replacing aging ceiling systems under accelerated building code renewal programs. These projects create concentrated demand for seismic-rated joint assemblies in lecture halls and library atriums.
- Sports Complexes:Large-span arenas require engineered gap-management at structural discontinuities accommodating substantial thermal and seismic movement.
- Entertainment Venues:Theaters and exhibition halls in China's tier-two cities face GB 50016 enforcement creating specification entry points for fire-rated metallic assemblies.
- Government Facilities:Secure infrastructure projects route procurement through specialized seismic engineering consultants controlling technical decision-making.
Highest procurement volume: Commercial Buildings. Fastest specification growth: Educational Institutions.
End User:
Authority over ceiling expansion joint selection is consolidating under technical specialists rather than general contractors, with seismic engineering consultants and facility managers gaining procurement influence.
- Structural Engineers:Independent engineering peer review now controls movement joint placement in complex commercial structures across China and United States large-span projects. Design-build contracts consolidate technical decision-making under single engineering entities, displacing traditional distributor-led specification.
- Construction Contractors:Metallic product procurement volumes dominate across United States, Germany, and China as contractors prioritize structural integrity in high-occupancy infrastructure despite locked public project contracts limiting margin recovery from material cost swings.
- Interior Designers:Aesthetic integration requirements drive hybrid assembly specification for visible ceiling geometries in premium commercial and hospitality spaces.
- Facility Management:Maintenance access constraints and lifecycle cost calculations influence renovation project material selection.
- Renovation Experts:Aging building system replacements concentrate demand in educational and government facility upgrade cycles.
Controlling largest specification share: Construction Contractors. Gaining authority fastest: Structural Engineers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China and enterprise zones in the United States concentrate ceiling expansion joint procurement through accelerated infrastructure depreciation allowances and streamlined permitting for high-occupancy commercial developments.
United States
Seismic compliance mandates from the International Building Code drive specification volume in assembly occupancies above 300 persons. The NFPA coordinates fire resistance testing protocols that manufacturers must satisfy for healthcare and transit infrastructure eligibility. Texas and California metropolitan corridors concentrate procurement for stadium and convention center projects requiring multi-directional movement accommodation.
Germany
Campus modernization cycles across federal states generate concentrated demand for seismic-rated joint assemblies in lecture halls and library atriums. ECHA restrictions on halogenated flame retardants force reformulation of fire-rated infill materials, extending recertification timelines. Bavaria and North Rhine-Westphalia host the densest clusters of commercial building renovation contractors specifying hybrid elastomeric-metal configurations.
China
GB 50016 enforcement in theaters and exhibition halls creates specification entry points for fire-rated metallic assemblies in tier-two cities. MOHURD mandates expansion joint fire ratings in public assembly occupancies above specified thresholds. Yangtze River Delta and Pearl River Delta manufacturing corridors supply extrusion-grade aluminum and stainless steel components to domestic and export markets.
United Arab Emirates
Transit infrastructure and airport terminal expansions route procurement through specialized seismic engineering consultants controlling technical decision-making. Dubai Building Code provisions align with international fire resistance standards while permitting accelerated project timelines. Dubai and Abu Dhabi construction authorities specify hybrid assemblies for complex ceiling geometries in performing arts venues and hospitality complexes.
India
Educational institution building code renewal programs accelerate ceiling system replacement in metropolitan campus developments. BIS fire safety standards for public assembly occupancies increasingly reference ASTM E119 and EN 1363 testing protocols for imported assemblies. Maharashtra and Karnataka urban development authorities specify metallic expansion joints for high-occupancy commercial and healthcare infrastructure in Mumbai and Bangalore metropolitan regions.
Ceiling Expansion Joint Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct specification tiers in the ceiling expansion joint market. The vendor base organizes around three strategic archetypes: metallic fabrication specialists with in-house extrusion capabilities, hybrid assembly integrators combining elastomeric and metal technologies, and fire-protection technology licensors supplying intumescent coating formulations. Competitive dynamics center on ASTM E119 certification velocity and seismic engineering consultant relationships rather than price alone. Capacity expansion in aluminum extrusion and strategic partnerships with building information modeling platform providers represent the dominant competitive moves.
Among metallic fabrication specialists, Balco and EMSEAL Joint Systems exemplify archetypes positioned around fire-resistant technology portfolios and seismic movement engineering integration respectively. Witzenmann occupies a position within the high-temperature commercial HVAC specialization tier. These three anchors demonstrate how geographic origin and corporate structure suffixes map to distinct strategic postures: Balco operates as a corporation focused on North American healthcare and transit infrastructure, EMSEAL functions as a joint systems limited liability entity with engineering standard integration, and Witzenmann represents GmbH-structured metallic specialization for European industrial applications.
| Leading Market Players |
|---|
| Balco |
| EMSEAL Joint Systems |
| Witzenmann |
| BOA Group |
| Trelleborg Sealing Solutions |
| U.S. Bellows |
| Senior Flexonics Pathway |
| Unaflex |
| Flexider |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap extrusion specialists across Germany and China anchor supply-side discipline, translating captive aluminum sourcing into pricing stability that public-project contractors cannot replicate when locked into fixed-bid contracts. Their ownership structure insulates procurement from short-term margin compression while enabling selective premium positioning for ASTM E119-certified assemblies.
Pricing Analysis
Short lead-time premiums of 15-25% apply to fire-rated metallic assemblies required for urgent healthcare and transit infrastructure retrofits under IBC seismic deadlines. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with hybrid elastomeric-metal configurations commanding the highest positioning due to multi-performance integration. Cost compression in entry-tier PVC segments is intensifying because Chinese manufacturers are absorbing aluminum volatility to maintain export share. Public-project contractors exhibit the greatest price sensitivity, while seismic engineering consultants driving specification authority prioritize performance over unit cost.
Supply Chain Analysis
Direct-to-contractor channels handle standardized metallic assembly demand in United States commercial construction, while specification-through-consultant pathways dominate complex hybrid procurement for airport terminals and performing arts venues. Extrusion-grade aluminum supply concentrates in China, Germany, and the United States, with stainless steel cover sourcing tethered to Yangtze River Delta and North Rhine-Westphalia manufacturing corridors. Raw material dependencies include aluminum billets, intumescent coating formulations, and elastomeric polymer compounds. Single-source vulnerability in ASTM E119 fire resistance testing capacity extends time-to-market for new product variants. Distribution runs through specialized seismic engineering consultants who consolidated specification authority in design-build contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ceiling expansion joint market is transitioning from discrete functional layers to integrated multi-performance assemblies, with intumescent-coated metallic extrusions displacing traditional three-layer fire-barrier systems in surgical suite and transit infrastructure specifications.
For Market Incumbents: Acquire in-house polymer compounding capabilities to accelerate REACH-compliant elastomeric seal reformulation ahead of ECHA authorization timelines. Defend specification share by embedding parametric product libraries in building information modeling platforms that compress architect-to-contractor pathways. Prefabricated modular ceiling systems with factory-installed movement accommodation threaten discrete joint procurement in standardized commercial office builds. For New Entrants and Emerging Players: Digital specification platforms offering BIM-integrated joint system databases provide the fastest route to specification authority bypassing traditional distributor relationships. Target China's tier-two cities where GB 50016 enforcement in theaters and exhibition halls creates entry points for fire-rated metallic assemblies before incumbent relationships solidify. White-space exists in acoustic-seismic convergence for airport terminal applications where hybrid assembly demand outpaces specialized supplier capacity. For Investors and Strategic Acquirers: Distressed-cycle entries favor metallic fabrication specialists with captive aluminum extrusion capacity in Germany and the United States, where public-project contract locks have compressed margins below sustainable levels for thinly capitalized competitors. Long-term viability hinges on certification velocity and seismic engineering consultant relationships rather than scale alone. Monitor ECHA substance restriction timelines and ASTM E119 testing facility expansion announcements as inflection indicators for product development cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive billet sourcing insulates margin stability from LME volatility in locked public contracts. |
| BIM Platform Partnership | Parametric product libraries compress specification pathways and displace distributor-led procurement. |
| REACH-Compliant Polymer Reformulation | In-house compounding capabilities accelerate ECHA authorization timelines versus assembly-only competitors. |
| Fire Testing Facility Expansion | Added ASTM E119 capacity reduces time-to-market bottlenecks for hybrid configuration variants. |
| Seismic Engineering Consultant Engagement | Design-build contract consolidation under single engineering entities elevates technical influence over price. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with seismic engineering consultants, construction contractor procurement leads, and facility management directors across United States, German, and Chinese metropolitan corridors. Secondary sources included IBC and NFPA code documentation, ECHA substance restriction databases, MOHURD GB 50016 enforcement notices, and SEC filings from publicly traded building products conglomerates. Bottom-up project pipeline analysis triangulated against top-down construction spending forecasts to validate volume assumptions.
Data-stream reconciliation across product type, technology bundle, application vertical, and end-user authority dimensions enabled segmentation-level forecasting over the projection horizon. Modeled dimensions included metallic versus hybrid material configuration, fire-resistant versus seismic-movement technology priority, commercial building versus educational institution application concentration, and contractor-led versus engineering-consultant specification control. CAGRs were derived from fitted growth curves applied to verified installation volumes, with cross-checks against aluminum extrusion output and fire resistance testing facility throughput data.
The model holds under steady regulatory enforcement of IBC seismic categories and GB 50016 public assembly mandates; deviation in ECHA authorization timelines or ASTM E119 testing capacity expansion would shift hybrid segment penetration trajectories. Practitioners should monitor halogenated flame retardant substitution progress and seismic design category reclassification announcements for early signals of specification eligibility shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Construction
Saudi Arabia Prefabricated Building and Structural Steel Market
Structural Construction
Elastomeric Bearings Market
Structural Construction
United Arab Emirates Structural Steel Fabrication Market
Structural Construction
GCC Structural Steel Fabrication Market
Structural Construction
South Korea Construction Market
Structural Construction
Global Concrete Contractor Market
Structural Construction
Bridge Bearings Market
Structural Construction
Girder Market
Structural Construction
UAE Prefabricated Building and Structural Steel Market
Structural Construction
US Heavy Movable Bridges Market
Structural Construction
GCC Prefabricated Building and Structural Steel Market
Structural Construction
Vietnam Structural Steel Fabrication Market
Structural Construction
China Structural Steel Fabrication Market
Structural Construction
Self-Consolidating Concrete (SCC) Market
Structural Construction
North America Structural Steel Fabrication Market
Structural Construction
Saudi Arabia Structural Steel Fabrication Market