
 Bridge Bearings Market | 2026-2036
Bridge Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
Bridge Bearings Market Analysis
The EU Green Deal's embodied carbon thresholds for construction materials is consolidating procurement standards across European bridge programs. Trelleborg AB leverages its polymer compounding expertise to supply high-performance elastomeric bearing pads certified under EN 1337. Mageba SA anchors its position through specialized seismic isolation bearings for Alpine corridor projects. Schreiber Brücken-Dehntechnik GmbH competes on precision-machined steel pot bearings tailored to German Federal Highway Research Institute specifications.
Bridge bearings are structural interface devices engineered to transmit vertical loads while accommodating horizontal movements, rotations, and thermal expansion in bridge superstructures. Elastomeric bearings incorporate laminated steel reinforcement plates within chloroprene or natural rubber matrices to achieve shear stiffness values between 0.8 and 1.2 MPa under EN 1337-3 test protocols. Pot bearings dominate heavy-duty roadway applications where rotational capacities exceed 0.02 radians and vertical loads surpass 30 MN. Composite material bearings represent the fastest-growing segment as fiber-reinforced polymer laminates displace conventional steel in coastal and chemically aggressive environments.
AASHTO LRFD Bridge Design Specifications and EN 1337 harmonization through CEN/TC 167 shape product development cycles and cross-border certification costs for manufacturers. The US Federal Highway Administration's Long-Term Bridge Performance Program generates performance data that feeds into updated AASHTO calibration factors for bearing design life. Stakeholders must monitor evolving seismic design maps from USGS and Eurocode 8 Annex E revisions that redefine displacement capacity requirements for isolation bearings in moderate seismic zones.
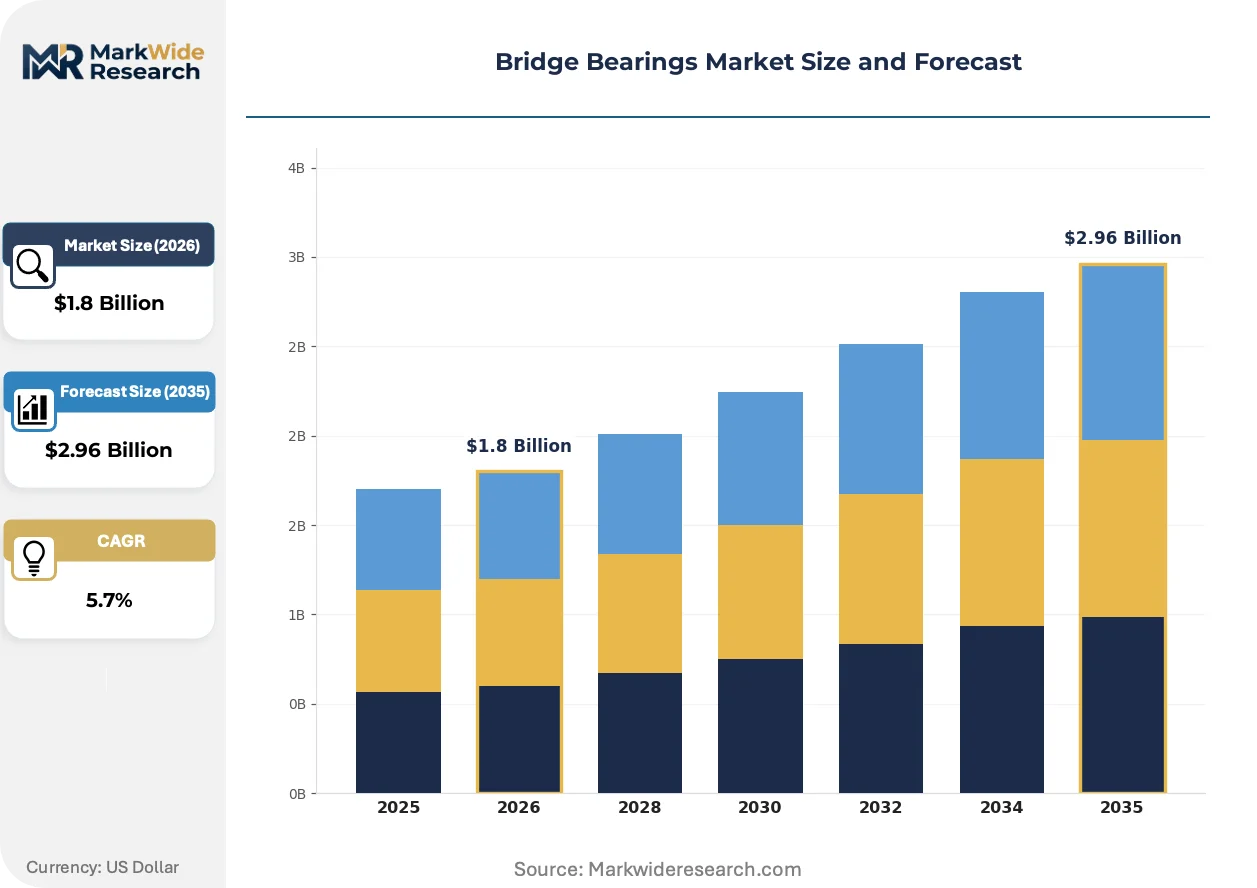
Market Dynamics
Bridge rehabilitation mandates across aging highway networks are accelerating specification updates for high-durability bearing systems, while EU embodied carbon thresholds force material substitutions in public procurement.
Growth Catalysts
- EN 1337 harmonization:CEN/TC 167 standards alignment reduces cross-border certification costs for manufacturers supplying multiple European highway authorities.
- Alpine corridor seismic upgrades:Switzerland and Austria are retrofitting critical transport links with displacement-capable isolation bearings under Eurocode 8 Annex E revisions.
- Fiber-reinforced polymer adoption:Coastal bridge programs in Florida and the Netherlands specify FRP-composite bearings to replace corrosion-susceptible steel assemblies.
Market Restraints
- Chloroprene rubber supply concentration:Specialty elastomer feedstock depends on limited polymer compounding capacity in Germany and Japan.
- AASHTO LRFD calibration lag:Updated bearing design life factors from US Federal Highway Administration performance data create temporary specification uncertainty.
- Steel pot bearing substitution:Spherical bearings capture share in heavy-rotational applications above 0.03 radians.
Strategic Opportunities
- India National Highway expansion:Ministry of Road Transport and Highways specifications for 50-year design life create demand for laminated elastomeric systems.
- EU Green Deal procurement incentives:Embodied carbon scoring favors suppliers with verified EPDs for rubber-steel composite bearings.
- Digital twin integration:Sensor-embedded smart bearings enable predictive maintenance contracts with state DOTs.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise for high-shear-stiffness elastomers concentrates among retiring specialists at European compounders.
- Seismic test facility bottlenecks:USGS displacement capacity validation requires extended queue times at specialized US and Japanese laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bridge Bearings Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Elastomeric, Pot Bearings, Sliding Bearings, Rocker Bearings Material: Steel, Concrete, Rubber, Composite Application: Roadways, Railways, Pedestrian Bridges, Overpasses Load Rating: Light Duty, Medium Duty, Heavy Duty, Ultra Heavy Duty |
| Companies Covered | Granor Rubber & Engineering Pty. Limited, Ekspan Ltd., Trelleborg AB, RJ Watson, Schreiber Brücken-Dehntechnik GmbH, Canam Group Inc., Freyssinet Limited, Gumba GmbH & Co. KG, Mageba SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bridge Bearings Market Emerging Trajectories
Material science advances and digitalization are compressing product development cycles while regulatory carbon accounting restructures supplier qualification pathways across public infrastructure programs.
Smart bearing systems with embedded strain gauges and accelerometers are converging with cloud-based structural health monitoring platforms. State transportation departments in California and Texas are piloting these instrumented assemblies on critical span replacements. Real-time load and movement data is converging with predictive analytics to extend inspection intervals and reduce lifecycle maintenance costs.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons in rubber compounding are forcing reformulation of traditional chloroprene bearing pads. German Federal Highway Research Institute specifications now require PAH-compliant elastomers for autobahn projects. Manufacturers with in-house polymer laboratories are accelerating alternative curing agent validation to maintain EN 1337-3 certification scope.
Consolidated procurement through national framework agreements is displacing project-specific tendering for standard bearing types. UK National Highways and Transport Scotland now mandate pre-approved supplier lists for elastomeric pad categories. This channel concentration rewards compounders with established highway authority relationships and compresses margins for spot-market participants.
Bridge Bearings Market Segmentation
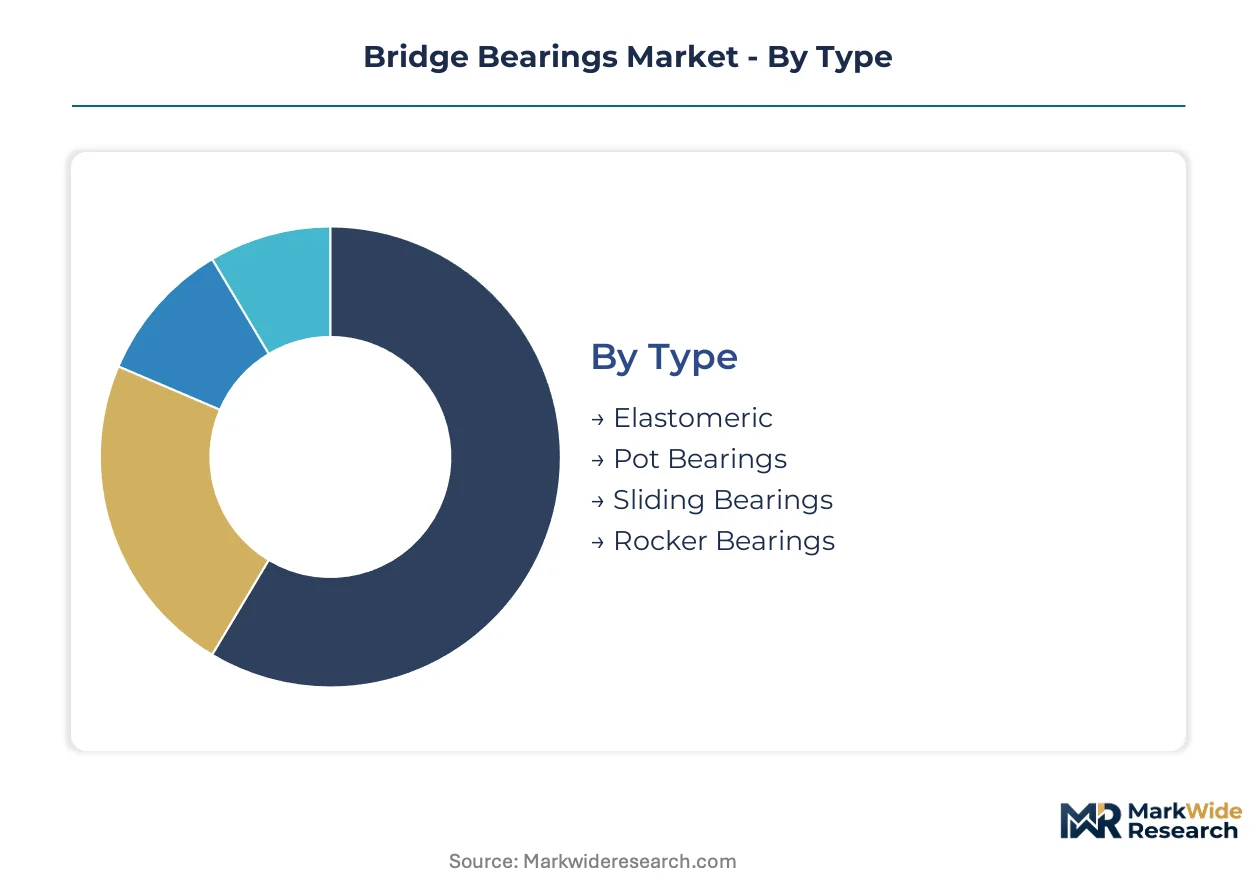
Bridge bearings segment by structural function, material durability, and load regime — each axis reshaping supplier R&D priorities and procurement qualification pathways. Specification divergence between highway authorities and rail operators forces manufacturers to maintain parallel certification portfolios.
Type:
Buyers differentiate by rotational capacity requirements and movement accommodation range rather than initial unit cost.
- Elastomeric:Laminated steel-reinforced chloroprene or natural rubber matrices deliver shear stiffness between 0.8 and 1.2 MPa under EN 1337-3 protocols. German autobahn expansion corridors specify these for moderate-load applications where horizontal displacement stays below 50mm.
- Pot Bearings:Precision-machined steel cylinders with PTFE sliding surfaces accommodate rotational demands exceeding 0.02 radians and vertical loads surpassing 30 MN. Swiss and Austrian Alpine corridor retrofits under Eurocode 8 Annex E revisions are accelerating procurement of displacement-capable variants.
- Sliding Bearings:PTFE-stainless steel interfaces permit multi-directional movement in long-span continuous girder bridges.
- Rocker Bearings:Curved steel bearing surfaces accommodate rotation through rocking motion, now largely superseded by pot and elastomeric systems in new construction.
Elastomeric bearings lead volumes today; pot bearings are gaining share fastest in seismic retrofit programs.
Material:
Material selection tracks environmental exposure severity and regulatory carbon accounting thresholds.
- Steel:Forged and cast steel assemblies dominate heavy-rotational applications. Florida coastal bridge programs are substituting FRP alternatives where salt spray accelerates section loss.
- Rubber:Chloroprene and natural rubber compounds with carbon black reinforcement provide elastomeric flexibility. REACH Annex XVII PAH restrictions are forcing compound reformulation at European manufacturers.
- Composite:Fiber-reinforced polymer laminates displace steel in chemically aggressive environments. Netherlands delta program specifications now mandate FRP bearings for marine exposure zones.
- Concrete:Plain or reinforced concrete bearing pads serve low-cost, low-movement applications in developing highway networks.
Steel leads volumes today; composite materials are expanding most quickly in coastal procurement specifications.
Application:
End-use verticals impose divergent fatigue cycles, load spectra, and maintenance access constraints.
- Roadways:Heavy truck traffic and thermal expansion cycles demand 50-year design life under AASHTO LRFD specifications. India National Highway expansion mandates laminated elastomeric systems for new construction.
- Railways:High-frequency axle loading and vibration isolation requirements favor specialized elastomeric pads with enhanced damping coefficients.
- Pedestrian Bridges:Lower load ratings permit lighter bearing assemblies with aesthetic integration requirements.
- Overpasses:Urban constraint geometries and seismic isolation needs drive specification complexity in moderate seismic zones.
Roadway applications lead volumes today; railway retrofits are climbing the fastest as European corridor upgrades accelerate.
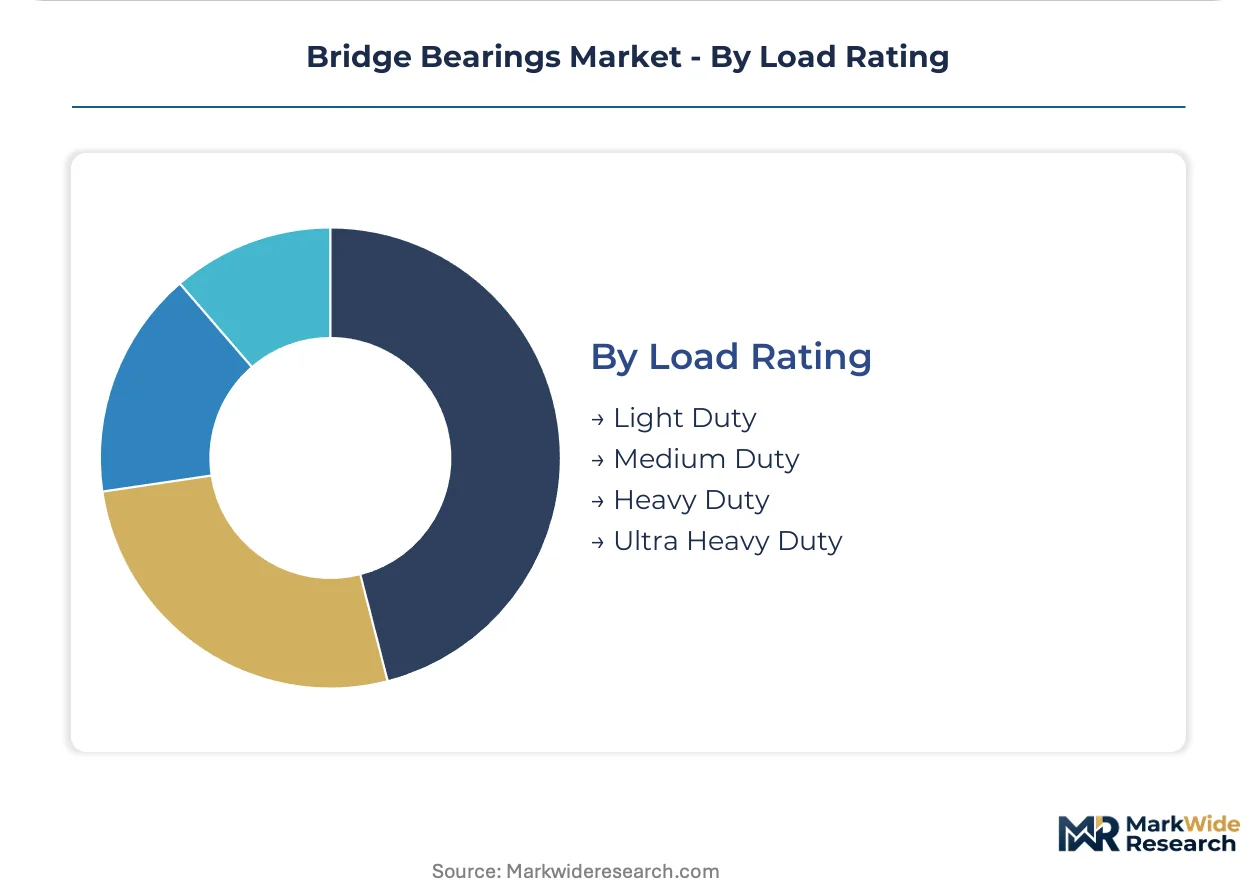
Load Rating:
Procurement tiering follows superstructure weight and traffic intensity rather than bridge span length.
- Heavy Duty:Vertical load capacities between 10 MN and 30 MN serve primary highway corridors and freight rail lines. German Federal Highway Research Institute specifications favor high-durability assemblies for autobahn segments.
- Ultra Heavy Duty:Capacities exceeding 30 MN accommodate cable-stayed and suspension bridge anchorages. Seismic isolation bearings in this class require extended queue times at USGS validation facilities.
- Medium Duty:2 MN to 10 MN range covers secondary roadways and light rail systems.
- Light Duty:Below 2 MN capacity serves pedestrian bridges and minor span structures.
Heavy duty bearings lead volumes today; ultra heavy duty assemblies show steepest expansion trajectory in long-span bridge programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bridge bearing manufacturing originated in German industrial centers during post-war autobahn reconstruction, establishing quality benchmarks that persist in today's EN 1337 certification framework. Modern demand distributes across aging infrastructure networks in North America, Alpine Europe, and Asia-Pacific highway expansion corridors.
United States
State transportation departments in California and Texas are piloting sensor-embedded smart bearings on critical span replacements. AASHTO LRFD calibration updates from Federal Highway Administration performance data create temporary specification uncertainty. Pittsburgh-based steel fabricators supply pot bearing assemblies for Appalachian corridor rehabilitation programs.
Germany
Federal highway authority specifications favor high-durability bearing assemblies for autobahn expansion corridors. EU Green Deal embodied carbon thresholds reshape supplier qualification criteria through verified EPD requirements. Stuttgart and Munich industrial clusters host precision-machining operations for pot bearing production serving Alpine transit links.
Switzerland
Alpine corridor seismic upgrades accelerate procurement of displacement-capable isolation bearings under Eurocode 8 Annex E revisions. Federal Office for the Environment enforces REACH Annex XVII PAH restrictions on rubber compounding for infrastructure materials. Basel chemical industry proximity supports polymer laboratory capacity for elastomer formulation.
India
Ministry of Road Transport and Highways specifications for 50-year design life create demand for laminated elastomeric systems in National Highway expansion. Central Public Works Department procurement guidelines increasingly reference international certification standards. Mumbai and Delhi industrial zones concentrate domestic bearing fabrication capacity for subcontinent projects.
Netherlands
Delta program specifications mandate FRP-composite bearings for marine exposure zones in coastal bridge construction. Rijkswaterstaat procurement frameworks prioritize embodied carbon scoring in material selection. Rotterdam port logistics infrastructure supports composite material supply chains for North Sea protection works.
Bridge Bearings Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the bearing supply landscape. The vendor base clusters around three tiers: integrated polymer compounders with in-house rubber laboratories, precision steel fabricators serving heavy-rotational applications, and regional installation specialists capturing maintenance contract value. Strategic moves concentrate on framework agreement positioning with national highway authorities and polymer formulation patent filings for PAH-compliant elastomers.
Within the integrated compounder tier, Trelleborg AB exemplifies polymer laboratory ownership that secures EN 1337-3 certification scope. Mageba SA occupies a position among seismic isolation specialists serving Alpine corridor retrofits. Schreiber Brücken-Dehntechnik GmbH anchors the precision-machining segment with German Federal Highway Research Institute specification alignment.
| Leading Market Players |
|---|
| Granor Rubber & Engineering Pty. Limited |
| Ekspan Ltd. |
| Trelleborg AB |
| RJ Watson |
| Schreiber Brücken-Dehntechnik GmbH |
| Canam Group Inc. |
| Freyssinet Limited |
| Gumba GmbH & Co. KG |
| Mageba SA |
| Others |
Supply Flow & Price Mechanics
EU Green Deal embodied carbon thresholds gate qualified supply and premium-tier pricing access for bridge bearing manufacturers, forcing procurement officers to pay certification premiums for verified EPD rubber-steel composite systems while excluding uncertified compounders from autobahn and delta program frameworks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by EN 1337-3 certification scope and polymer laboratory ownership. Price differentiation centers on shear stiffness validation protocols and German Federal Highway Research Institute specification alignment. Cost compression in economy-tier chloroprene pads is intensifying because REACH Annex XVII PAH reformulation expenses concentrate among smaller compounders without captive rubber laboratories. State DOT procurement teams show highest price sensitivity, while Alpine corridor seismic retrofit programs prioritize displacement capacity over unit cost.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Munich, and Basel anchor hub-and-spoke patterns serving German autobahn and Swiss Alpine corridor projects. Geographic supply concentration centers on Germany, Switzerland, and Japan for precision-machined steel pot bearings and specialty elastomer compounding. Raw material feeds draw from chloroprene rubber polymerization in German industrial clusters, PTFE sliding surface imports, and carbon black reinforcement from European petrochemical networks. Single-source vulnerability runs through limited seismic test facility capacity at USGS and Japanese laboratories. Distribution runs through national framework agreements with pre-approved supplier lists displacing spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bridge bearings constitute a late-cycle quality story as federal rehabilitation programs shift procurement toward 50-year design life specifications and sensor-embedded smart bearing systems.
For Market Incumbents: To counter spherical bearing substitution in heavy-rotational applications above 0.03 radians, Trelleborg AB and Mageba SA should deepen backward integration into captive polymer laboratories for PAH-compliant elastomer formulation while securing extended framework agreement positioning with UK National Highways and Transport Scotland pre-approved supplier lists. For New Entrants and Emerging Players: State transportation department pilot programs for predictive maintenance contracts present the most penetrable entry point. California and Texas DOT smart bearing trials offer white-space access through sensor-embedded assembly partnerships with cloud-based structural health monitoring platforms. Digital twin integration capabilities provide the critical go-to-market angle against established compounders. For Investors and Strategic Acquirers: Valuations sit cheapest among regional installation specialists capturing maintenance contract value rather than capital-heavy integrated manufacturers. Long-term viability over the next decade favors precision steel fabricators with German Federal Highway Research Institute specification alignment and demonstrated seismic isolation bearing production. The signal to watch is queue time compression at USGS displacement capacity validation facilities indicating demand inflection for ultra heavy duty isolation systems.| Strategic Initiative | Industry Significance |
|---|---|
| Polymer Laboratory Backward Integration | Captive PAH-compliant elastomer formulation secures EN 1337-3 certification scope against REACH restrictions. |
| Smart Bearing Sensor Embedding | Strain gauge and accelerometer integration enables predictive maintenance contracts with California and Texas DOTs. |
| National Framework Agreement Positioning | UK National Highways pre-approved supplier list placement displaces spot-market competitors from standard elastomeric pad procurement. |
| Alpine Corridor Seismic Retrofit Specialization | Eurocode 8 Annex E displacement-capable isolation bearing production captures Swiss and Austrian federal upgrade budgets. |
| FRP-Composite Material Transition | Fiber-reinforced polymer laminate manufacturing addresses Netherlands delta program marine exposure zone mandates. |
Methodological Framework
Coverage spans Germany, Switzerland, United States, India, and Netherlands, with primary inputs from each market combining interviews with highway authority procurement officers, bridge design engineers at state DOTs, polymer laboratory directors at integrated compounders, and seismic test facility managers. Secondary validation draws from EN 1337-3 certification databases, AASHTO LRFD specification updates, EU Green Deal procurement guideline releases, and US Federal Highway Administration Long-Term Bridge Performance Program datasets. Bottom-up bearing unit demand modeling triangulates against top-down infrastructure spending allocation analysis.
Granularity-level modeling disaggregates volume and value across the projection horizon by bearing type (elastomeric, pot, sliding, rocker), material composition (steel, rubber, composite, concrete), application vertical (roadways, railways, pedestrian, overpass), and load rating tier (light through ultra heavy duty). CAGRs derive from bridge rehabilitation program pipeline analysis, federal highway authority specification update schedules, and embodied carbon threshold implementation timelines. Industry-specific forecast inputs include USGS seismic design map revisions and Eurocode 8 Annex E displacement capacity requirement changes.
Underlying measurement precision varies by segment; elastomeric bearing volumes carry tighter precision than emerging FRP-composite categories where procurement specification adoption remains uneven. Forecasts reflect assumptions around EN 1337 and AASHTO LRFD harmonization progress, polymer compounding capacity expansion rates, and seismic test facility throughput constraints. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Construction
Self-Consolidating Concrete (SCC) Market
Structural Construction
Ceiling Expansion Joint Market
Structural Construction
US Heavy Movable Bridges Market
Structural Construction
Canada Composite Repair Market
Structural Construction
Sandwich Plate System Market
Structural Construction
North America Structural Steel Fabrication Market
Structural Construction
Supported Scaffolding Market
Structural Construction
Girder Market
Structural Construction
Saudi Arabia Roofing Market
Structural Construction
Saudi Arabia Structural Steel Fabrication Market
Structural Construction
Italy Concrete Railway Sleepers Market
Structural Construction
Bridge Construction Market
Structural Construction
Prefabricated Steel Bridge Market
Structural Construction
H Beam Market
Structural Construction
Global Rebar Splice Market
Structural Construction
Saudi Arabia Prefabricated Building and Structural Steel Market