
 North America Structural Steel Fabrication Market | 2026-2036
North America Structural Steel Fabrication Market Size, Share, and Industry Trends Forecast 2026-2036
North America Structural Steel Fabrication Market Analytics
Aftermarket service revenue is reshaping margin pools across the North America structural steel fabrication value chain, pulling returns away from pure production volume. Valmont Industries leverages its coast-to-coast manufacturing footprint to dominate utility and infrastructure segments. DBM Global anchors its position through integrated engineering-fabrication-installation capabilities on complex commercial projects. Cornerstone Building Brands competes via specialized building envelope systems that reduce field labor dependency.
Structural steel fabrication encompasses the cutting, welding, bending, and assembly of hot-rolled and built-up steel sections into load-bearing frameworks for buildings, bridges, and industrial structures, typically using ASTM A992 or A572 Grade 50 material with yield strengths of 50 ksi. The process transforms raw mill products into engineered components ready for field erection, serving as the skeletal system for modern construction. Beams and columns command the largest share of product output, reflecting their ubiquity in multi-story framing. Infrastructure Projects represent the fastest-expanding application category, driven by federal transportation and energy investments. Welding technology sustains the deepest margin pools, as certified procedures and skilled labor create defensible competitive barriers.
The American Institute of Steel Construction (AISC) certification program governs quality standards and shop capabilities, while OSHA workplace safety regulations shape labor costs and operational protocols across US fabrication facilities. Canadian standards through the Canadian Standards Association (CSA) create dual-compliance requirements for cross-border suppliers. Mexico's construction norms under its national building code add a third regulatory layer for integrated North American supply chains. Stakeholders must monitor evolving Buy America domestic content thresholds, as these provisions increasingly determine eligibility for federally funded projects across all three countries.
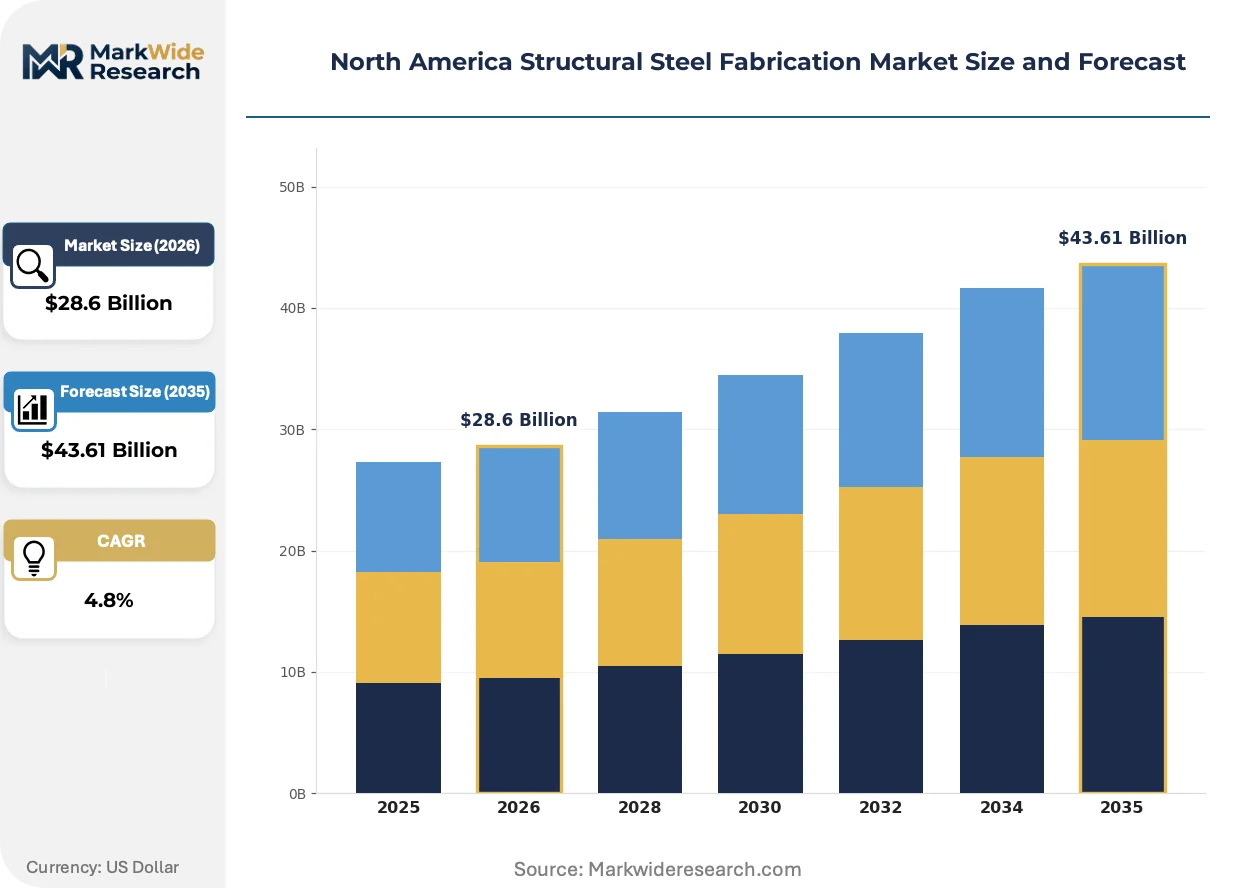
Market Dynamics
Federal infrastructure spending under the Infrastructure Investment and Jobs Act is redirecting fabrication capacity toward bridge and highway components, tightening availability for commercial building projects across the continent.
Growth Catalysts
- Data Center Construction Boom:Hyperscale cloud providers are procuring steel framing at unprecedented scale across Texas, Virginia, and Arizona to support AI-driven computing infrastructure.
- Buy America Provisions:Domestic content thresholds under US federal procurement rules are mandating North American-sourced steel for transportation and energy projects, insulating regional producers from import competition.
- Advanced Welding Automation:Robotic welding cells with machine vision are expanding shop throughput while reducing dependency on scarce certified welders.
Market Restraints
- Scrap Price Volatility:Electric arc furnace operators face margin compression when ferrous scrap costs spike, as this input constitutes the majority of raw material expense for domestic mills.
- Canadian Import Dependency:Specialty wide-flange sections and plate products rely heavily on integrated mill capacity concentrated in Hamilton, Ontario, creating single-source vulnerability.
- Labor Substitution Limits:Prefabricated concrete and mass timber are capturing mid-rise commercial framing where developers prioritize speed-to-enclosure over steel's structural flexibility.
Strategic Opportunities
- Mexico Manufacturing Expansion:Fabricators establishing operations in Monterrey and Querétaro can serve US Southwest markets with lower logistics costs while leveraging USMCA trade benefits.
- Offshore Wind Fabrication:Monopile and jacket foundation contracts for Atlantic Coast wind farms require specialized thick-plate rolling and coating capabilities that few shops currently possess.
- Carbon Accounting Integration:Environmental Product Declarations and embodied carbon scoring are becoming bid requirements, rewarding early adopters of mill-specific emissions data and low-carbon steel sourcing.
Industry Challenges
- Certified Welder Shortage:AWS D1.1 structural welding certification programs cannot replenish retiring craftworkers at the pace required by project backlogs.
- AISC Certification Timelines:New shop qualification audits face 6-12 month queues, delaying market entry for emerging fabricators.
- Legacy ERP Integration:Steel management information systems must interface with modern BIM platforms, forcing costly middleware development or full system replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Structural Steel Fabrication Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beams, Columns, Plates, Angles Application: Commercial Buildings, Industrial Facilities, Infrastructure Projects, Residential Structures Technology: Welding, Cutting, Bending, Coating End User: Contractors, Engineers, Architects, Manufacturers |
| Companies Covered | Valmont Industries Inc., DBM Global Inc., Cornerstone Building Brands Inc., Groupe Canam Inc., High Industries Inc., O’Neal Manufacturing Services, BTD Manufacturing Inc., Mayville Engineering Company Inc., Kloeckner Metals Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Structural Steel Fabrication Market Evolving Landscape
Digital fabrication workflows and sustainability accounting are compressing traditional project timelines while elevating material traceability from competitive advantage to baseline requirement.
Building Information Modeling with direct-to-fabrication data transfer is rendering obsolete manual takeoff and paper-based shop drawings. General contractors on complex commercial projects now mandate model-based steel procurement, compressing detailing cycles from weeks to days. This shift is consolidating detailing work among specialists with in-house BIM capabilities and API integrations with fabrication equipment.
The EPA's strengthened industrial emissions standards under the Clean Air Act are compelling fabrication facilities to upgrade particulate capture systems and welding fume extraction. Shops in heavy-industry corridors face the steepest compliance costs, accelerating consolidation among smaller operators. Canadian fabricators serving cross-border projects must now maintain dual certification under evolving US EPA and provincial environmental regulations.
Modular construction procurement is fragmenting traditional general contractor-fabricator relationships. Developers of multifamily housing and healthcare facilities now contract directly with steel module producers, bypassing conventional bidding channels. Texas and Florida markets exhibit the most pronounced shift, as speed-constrained projects prioritize factory-controlled quality over field-erection flexibility.
North America Structural Steel Fabrication Market Segmentation
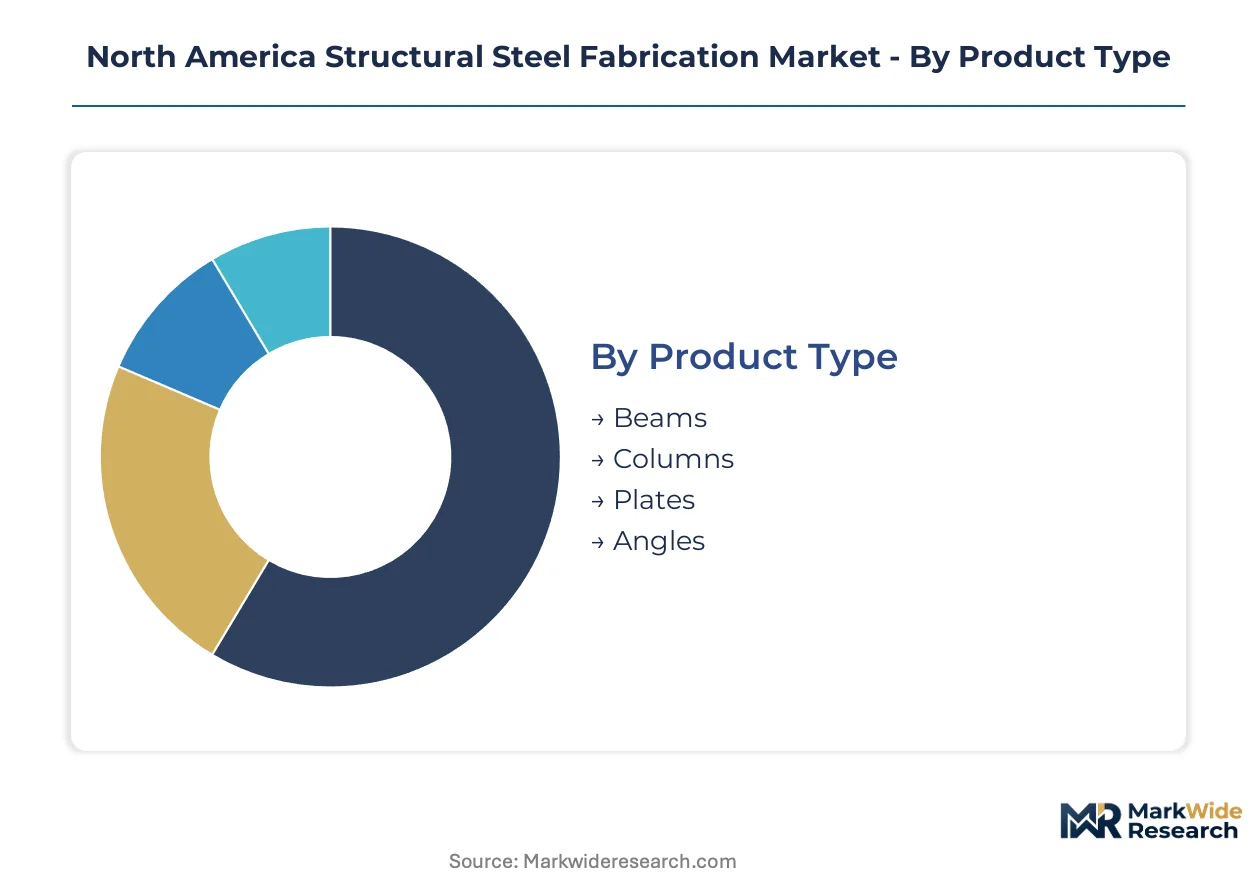
Segmentation in structural steel fabrication reveals how capital intensity, project duration, and technical certification requirements create distinct competitive arenas. Cycle times vary dramatically across product categories and end-use applications, directly influencing inventory strategy and margin realization for fabrication shops.
Product Type:
Beams and columns turn on predictable commercial construction cycles with standardized mill rolling schedules, while plates and angles serve longer-lead industrial and infrastructure projects with more volatile demand patterns.
- Beams:Wide-flange and built-up I-sections fabricated from ASTM A992 material with 50 ksi yield strength form the primary horizontal framing members in multi-story construction. Demand clusters in Texas data center corridors and Arizona logistics hubs where warehouse clear-span requirements drive heavy W24 and W30 sections.
- Columns:Vertical compression members ranging from HSS tube sections to welded box columns support gravity and lateral loads in high-rise framing. Expansion concentrates in Nashville and Austin commercial cores where 30-plus-story mixed-use towers are accelerating steel tonnage procurement.
- Plates:Quenched-and-tempered or normalized plate products serve bridge gussets, connection plates, and heavy industrial foundations with thicknesses from 3/16 inch to 6 inches. Fabricators in Hamilton, Ontario and Gary, Indiana maintain specialized thermal cutting and beveling capacity for infrastructure-grade material.
- Angles:L-shaped structural sections provide bracing, shelf supports, and secondary framing in lighter commercial and residential applications. Mexican fabricators in Monterrey exploit angle production for cost-competitive Southwest US distribution under USMCA rules of origin.
Beams dominate installed base across commercial building stock. Infrastructure-grade plates are where expansion concentrates.
Application:
Cost tier stratification separates speculative commercial work with thin margins from federally funded infrastructure with compliance premiums and captive domestic content requirements.
- Commercial Buildings:Office towers, retail centers, and mixed-use developments represent the volume foundation of North American fabrication demand. Procurement cycles compress to 12-16 weeks in Texas and Florida markets where developer speed-to-market priorities override pure material cost optimization.
- Industrial Facilities:Manufacturing plants, process facilities, and energy infrastructure require heavy wide-flange and built-up sections with specialized connection detailing. Gulf Coast petrochemical expansions and Ohio Valley battery plant construction are concentrating demand for crane-supported framing with 100-plus-year design lives.
- Infrastructure Projects:Highway bridges, rail terminals, and airport structures governed by AASHTO and AREMA specifications demand enhanced material traceability and Charpy V-notch toughness certification. Federal IIJA disbursements are redirecting shop capacity toward DOT-funded components with Buy America domestic melt and pour requirements.
- Residential Structures:Mid-rise multifamily and single-family light-gauge steel framing occupies a distinct tier from structural heavy shapes, though cold-formed sections increasingly encroach on traditional wood platforms in fire-code-constrained California and Florida coastal zones.
Commercial buildings anchor fabrication revenue tonnage. Infrastructure projects are climbing the fastest as federal transportation disbursements accelerate.
Technology:
Process maturity and automation potential separate high-throughput operations from craft-dependent specialty work, with margin structure inversely correlated to labor substitution feasibility.
- Welding:Flux-cored arc and submerged arc processes with AWS D1.1 certification sustain the deepest margin pools in fabrication, as qualified welders and procedure qualifications create defensible competitive barriers. Robotic cells with machine vision are expanding throughput in high-volume beam-line operations while manual processes persist on complex connection geometries.
- Cutting:Plasma and oxy-fuel thermal cutting of plate and structural sections has achieved near-complete CNC automation, compressing cycle times and material nesting efficiency. Texas and Louisiana shops serving offshore wind monopile fabrication are investing in multi-torch beveling systems for thick-plate joint preparation.
- Bending:Roll-forming and press-brake operations shape angles, channels, and custom curved sections for architectural and bridge applications. Curved steel for stadium roofs and pedestrian bridges requires specialized three-roll and induction heating equipment concentrated among fewer than two dozen North American specialists.
- Coating:Shop-applied intumescent fireproofing and corrosion-resistant paint systems extend field erection windows and reduce weather dependency. EPA VOC regulations and SSPC surface preparation standards govern application protocols, with automated blast-and-paint lines achieving throughput rates manual operations cannot match.
Welding commands premium pricing through certification scarcity. Coating is gaining share fastest as project specifications tighten fire-resistance and durability requirements.
End User:
Customer sophistication and procurement leverage separate price-takers from specification-shapers, with direct relationships increasingly displacing traditional distributor intermediaries.
- Contractors:General and steel erection contractors dominate procurement volume, with ENR Top 400 firms consolidating supply relationships around AISC-certified fabricators with BIM-to-fabrication data transfer capability. Design-build delivery is compressing traditional bidding cycles and favoring early contractor involvement.
- Engineers:Structural engineering consultants specify material grades, connection types, and fabrication tolerances that constrain shop sourcing options. Firms with in-house detailing capabilities are increasingly contracting directly with fabricators, disintermediating traditional general contractor procurement channels.
- Architects:Exposed structural steel and long-span systems in civic and cultural buildings drive aesthetic performance requirements beyond standard commercial specifications. Architect-led design competitions for signature projects often predetermine fabricator selection through qualification-based rather than price-based criteria.
- Manufacturers:OEMs and industrial equipment producers procure custom structural frames for machinery bases, material handling systems, and process skids with tighter dimensional tolerances than building construction. Automotive and battery manufacturing facility expansions are accelerating demand for precision-fabricated support structures.
Contractors control procurement volume through consolidated supply agreements. Engineers are expanding influence fastest as model-based design erodes traditional procurement boundaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the three North American markets. The United States prioritizes data center and energy infrastructure steel tonnage. Canada concentrates on transportation-grade material with enhanced toughness certification. Mexico serves cost-sensitive Southwest US distribution through integrated manufacturing corridors.
United States
Data center construction in Northern Virginia, Phoenix, and Dallas-Fort Worth is absorbing unprecedented wide-flange beam volumes for AI computing facilities. OSHA welding fume regulations are compelling Texas and Arizona shops to upgrade extraction systems ahead of EPA enforcement timelines. Houston-Gulf Coast fabricators are retooling for offshore wind monopile contracts requiring thick-plate rolling capacity absent from most existing facilities.
Canada
Bridge and highway rehabilitation under federal infrastructure programs is redirecting Hamilton and Quebec shop capacity toward AASHTO-certified components with Charpy V-notch requirements. CSA S16 steel design standards create dual-compliance burdens for Ontario fabricators bidding on US transportation projects. Edmonton and Calgary shops are capturing oil sands module fabrication with integrated engineering capabilities that bypass traditional procurement channels.
Mexico
USMCA rules of origin are attracting Monterrey and Querétaro investments to serve Texas and Arizona construction markets with reduced logistics friction. Mexican construction norms under NOM standards add certification layers for cross-border suppliers integrating into North American supply chains. Nuevo León fabricators are scaling angle and light structural production for Southwest US residential and commercial framing where cost competition with domestic mills intensifies.
North America Structural Steel Fabrication Market Competitive Landscape
Capability concentration sits with integrated engineering-fabrication-installation specialists; scale advantage sits with coast-to-coast manufacturing networks serving repetitive infrastructure programs. The vendor base separates into three functional tiers: utility-focused national networks, complex commercial project integrators, and regional specialists in building envelope systems. Consolidation pressures are mounting as AISC certification backlogs and EPA compliance costs accelerate smaller shop exits. Dominant competitive moves include geographic expansion into Mexico manufacturing corridors and backward integration into detailing and BIM services.
Among North American fabricators, Valmont Industries Inc. anchors the utility and infrastructure segment with coast-to-coast manufacturing coverage. DBM Global Inc. occupies a position exemplifying integrated engineering-fabrication-installation capabilities on complex commercial developments. Cornerstone Building Brands Inc. represents the building envelope specialization tier with systems reducing field labor dependency. These three entities collectively illustrate how certification depth, geographic footprint, and service integration separate sustainable positions from commodity pressure.
| Leading Market Players |
|---|
| Valmont Industries Inc. |
| DBM Global Inc. |
| Cornerstone Building Brands Inc. |
| Groupe Canam Inc. |
| High Industries Inc. |
| O'Neal Manufacturing Services |
| BTD Manufacturing Inc. |
| Mayville Engineering Company Inc. |
| Kloeckner Metals Corporation |
| Others |
Value Network & Pricing Analysis
Undercapacity in Canadian wide-flange rolling mills is compressing regional supply elasticity and amplifying price volatility for US Gulf Coast infrastructure contractors bidding on IIJA-funded bridge components. This utilization squeeze forces buyers into longer-dated procurement commitments while rewarding fabricators with captive mill relationships.
Pricing Analysis
Long-term offtake agreements dominate procurement for federally funded transportation projects, insulating qualified AISC-certified fabricators from spot market scrap volatility. Price differentiation hinges on Charpy V-notch certification tier and BIM-to-fabrication data integration capability. Cost compression in commercial building segments is intensifying because mass timber substitutes are capturing mid-rise framing share. General contractors on speculative office towers exhibit highest price sensitivity, while DOT program managers prioritize compliance traceability over unit cost.
Supply Chain Analysis
Buy America domestic content thresholds function as de facto export controls limiting non-qualifying steel flows into federally funded project pipelines. Raw material supply concentrates in US electric arc furnace corridors, Canadian integrated mill capacity in Hamilton, and Mexican semi-finished feedstock from Monterrey. Ferrous scrap, graphite electrodes, and alloy additives constitute critical input dependencies. Single-source vulnerability runs through Ontario's specialized plate rolling capacity. Distribution runs through AISC-certified fabricator networks with direct-to-jobsite logistics coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive boundaries as BIM-to-fabrication data interoperability becomes the gateway to general contractor procurement systems, consolidating influence among API-integrated specialists.
For Market Incumbents: Build certification moats through accelerated AISC endorsement expansion into Mexican manufacturing corridors before audit queues lengthen. Deepen backward integration into detailing services to capture model-based procurement premiums. Mass timber encroachment and emerging robotic welding competitors threaten traditional beam-line margins. Prioritize captive supply relationships with Hamilton plate mills to secure infrastructure-grade material allocation. For New Entrants and Emerging Players: Build out offshore wind foundation fabrication capabilities in Texas and Louisiana, where thick-plate rolling demand outstrips qualified shop supply. Target Atlantic Coast monopile contracts as the most penetrable application tier. Pursue direct engineering firm relationships to bypass entrenched general contractor procurement channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated welding cell deployments, favoring scaled operators with deployment capital. Long-term viability centers on fabrication shops with integrated BIM capabilities and USMCA-qualifying Mexican footprints. Acquisition targets should exhibit AISC certification depth paired with coastal logistics positioning. Monitor EPA enforcement timelines for welding fume extraction upgrades as margin compression inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Mexico Manufacturing Expansion | USMCA rules of origin enable tariff-advantaged supply to Texas and Arizona data center corridors. |
| Offshore Wind Fabrication Capability | Atlantic Coast lease auctions are concentrating demand for thick-plate monopile and jacket foundation production. |
| BIM-to-Fabrication Integration | Direct model data transfer is becoming mandatory for ENR Top 400 contractor procurement qualification. |
| Carbon Accounting Certification | Environmental Product Declarations are emerging as bid requirements for federal and institutional projects. |
| Robotic Welding Automation | Machine vision cells address certified welder scarcity while expanding throughput in high-volume beam operations. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with steel erection contractors, structural engineering consultants, AISC certification auditors, and EPC procurement managers. Secondary validation drew from US DOT IIJA disbursement records, EPA Clean Air Act enforcement schedules, USMCA customs documentation, and AISC shop certification databases. Bottom-up tonnage estimates from individual fabrication facilities were triangulated against top-down steel consumption data from regional mill shipments.
Calibration against historical capacity utilization and project backlog trends informed volume projections across the analysis window. Segmentation modeling incorporated product type, application category, technology process, and end-user procurement channel dimensions. CAGRs were derived from regression analysis of disclosed contract values and mill shipment volumes. Forecast inputs included data center construction pipeline disclosures, federal infrastructure appropriation schedules, and offshore wind lease development timelines.
Practitioners should monitor scrap price volatility, EPA enforcement acceleration, and AISC certification audit queue lengths for early signals of supply constraint or margin compression. Forecasts reflect assumptions regarding sustained IIJA disbursement velocity and USMCA rule stability. Material shifts in Buy America domestic content thresholds or Canadian mill capacity rationalization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Construction
Timber Frame Construction Market
Structural Construction
Girder Market
Structural Construction
Global Structural Steel Fabrication Market
Structural Construction
H Beam Market
Structural Construction
Saudi Arabia Structural Steel Fabrication Market
Structural Construction
Bridge Bearings Market
Structural Construction
GCC Prefabricated Building and Structural Steel Market
Structural Construction
Global Rebar Splice Market
Structural Construction
US Heavy Movable Bridges Market
Structural Construction
Sandwich Plate System Market
Structural Construction
Ceiling Expansion Joint Market
Structural Construction
Saudi Arabia Roofing Market
Structural Construction
GCC Structural Steel Fabrication Market
Structural Construction
Canada Composite Repair Market
Structural Construction
UAE Prefabricated Building and Structural Steel Market
Structural Construction
Italy Concrete Railway Sleepers Market