
 Elastomeric Bearings Market | 2026-2036
Elastomeric Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
Elastomeric Bearings Market Insights
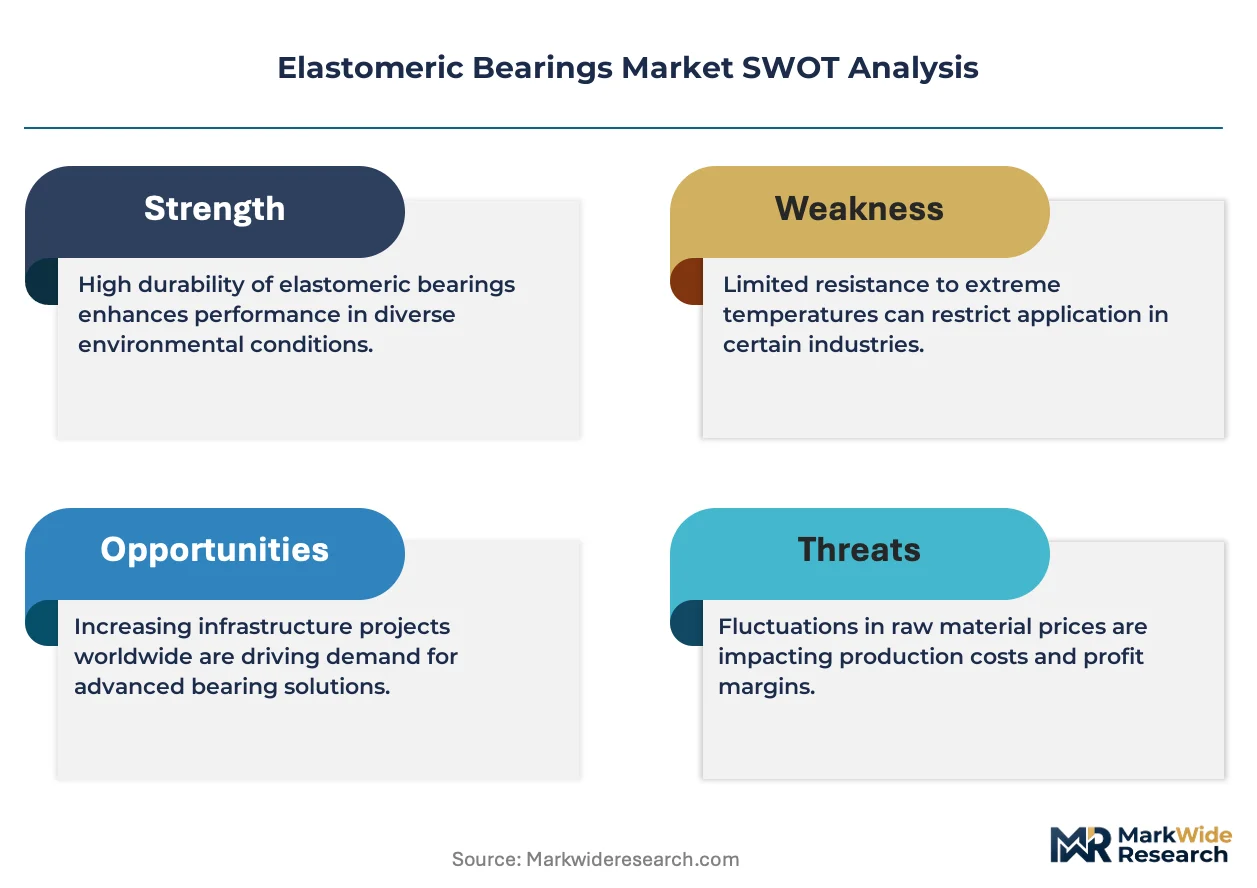
Project finance tied to availability-based road concessions is narrowing the supplier pool for elastomeric bearing contracts. Trelleborg AB leverages its polymer compounding expertise to secure multi-year supply agreements with European infrastructure funds. Freyssinet Limited anchors its competitiveness through vertical integration from elastomer formulation to structural installation services. Mageba Group specializes in seismic isolation systems, positioning itself for bridge retrofit mandates in earthquake-prone zones.
Elastomeric bearings are multilayer structural devices comprising alternating steel plates and vulcanized rubber compounds, engineered to accommodate rotational, translational, and vertical loads while isolating superstructures from substructure movements. They typically achieve shear moduli between 0.4 and 1.2 MPa and operate across temperature ranges from minus 40 to plus 70 degrees Celsius, serving primarily to extend service life and reduce maintenance frequency in civil infrastructure. Steel laminated products dominate procurement volumes for heavy-load bridge applications due to their superior load distribution and fatigue resistance. Neoprene compounds represent the fastest-growing material category as contractors seek ozone-resistant alternatives for coastal and industrial environments. The retrofit installation segment carries elevated margin pools relative to new-build contracts, reflecting specialized jacking requirements and shorter project timelines.
EMA material compliance standards, EU Green Deal procurement guidelines, and F-Gas Regulation restrictions on synthetic elastomer feedstocks are reshaping compound formulation requirements and supplier qualification protocols across European infrastructure markets. The US Federal Highway Administration and state DOTs enforce AASHTO LRFD specifications that mandate proof-load testing and long-term durability certifications for bridge bearing acceptance. Stakeholders must monitor evolving low-carbon material mandates and seismic code upgrades to align R&D priorities with emerging specification thresholds.
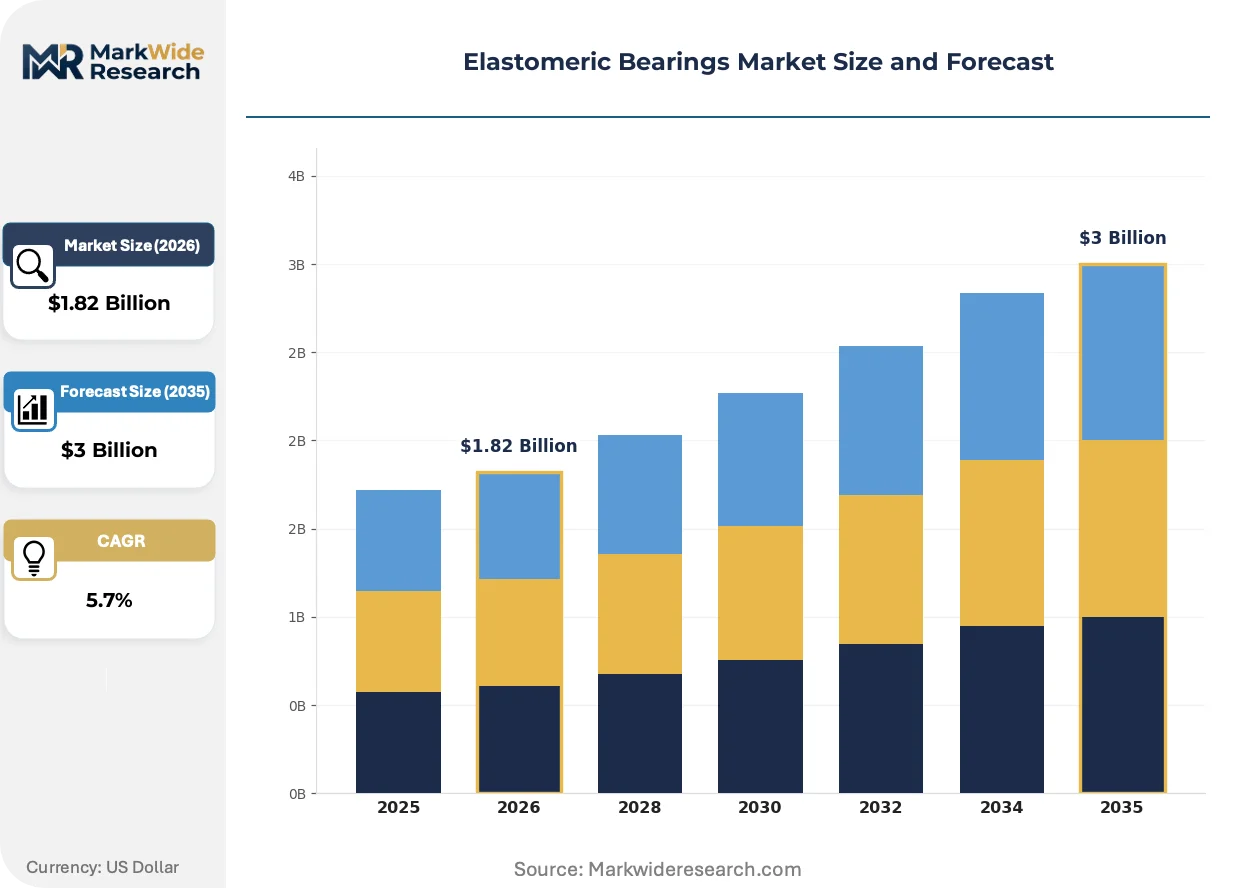
Market Dynamics
Bridge rehabilitation mandates across aging infrastructure networks are compressing procurement cycles and elevating specification thresholds for seismic isolation systems. Federal highway authorities in Germany and state DOTs in the US are accelerating retrofit timelines, forcing compound suppliers to certify low-emission elastomer formulations under tightened environmental protocols.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on synthetic elastomer feedstocks are accelerating R&D investment in bio-based neoprene alternatives for coastal bridge applications.
- Seismic retrofit mandates:Earthquake-prone zones in Japan and the western US are mandating base isolation upgrades for pre-1980s highway infrastructure.
- Steel-laminated bearing systems:Heavy-load bridge engineers specify these for superior fatigue resistance under autobahn traffic volumes.
Market Restraints
- Petrochemical input volatility:Crude oil price swings directly compress margins on chloroprene and natural rubber compounds.
- Supplier concentration in East Asia:Vulcanized steel plate fabrication clusters in China create single-source vulnerability for European contractors.
- AASHTO LRFD certification timelines:Proof-load testing requirements extend qualification periods to 18-24 months for new entrants.
Strategic Opportunities
- India highway expansion:National infrastructure corridors under the Bharatmala program lack domestic seismic bearing capacity, opening import substitution potential.
- Digital twin integration:IoT sensor embedding in bearing pads enables predictive maintenance contracts for toll-road operators.
- EU Green Deal procurement:Public infrastructure tenders now weight embodied carbon scores, favoring low-emission compound suppliers.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise for high-damping rubber compounds concentrates among retiring specialists in Germany and Japan.
- Legacy bridge documentation gaps:As-built drawings from 1960s-70s construction lack load-bearing specifications, complicating retrofit engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elastomeric Bearings Market |
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Laminated, Neoprene, Natural Rubber, Silicone, Fluoroelastomer Application: Bridges, Railways, Tunnels, Flyovers, Elevated Highways End User: Construction Firms, Infrastructure Developers, Road Contractors, Civil Engineering Consultants Installation Type: New Installation, Retrofit, Replacement, Maintenance, Testing |
| Companies Covered | Trelleborg AB, Freyssinet Limited, Mageba Group, Canam Group Inc., BRP Manufacturing, D.S. Brown, MAURER SE, Granor Rubber & Engineering Pty. Limited, Ekspan Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elastomeric Bearings Market Trends and Innovations
Material science advances and digital instrumentation are converging to transform static bearing components into intelligent structural health monitors. Compound suppliers must now integrate sensor compatibility into vulcanization processes.
High-damping natural rubber formulations with added carbon black are rendering obsolete conventional neoprene bearings in moderate seismic zones. Japanese bridge engineers at METI-funded projects specify these for 30% greater energy dissipation. The technology is compressing specification windows for standard chloroprene products in Pacific Rim markets.
The EU F-Gas Regulation is banning hydrofluorocarbon blowing agents in elastomer production from 2027. Compounders are reformulating with water-based foaming systems that increase manufacturing cycle times by 15%. German federal procurement offices now require Environmental Product Declarations for all bridge bearing contracts.
Availability-based road concessions are unbundling bearing supply from installation services. European infrastructure funds now contract separately for material provision and structural jacking, fragmenting vendor relationships. This pattern is most visible in France and Spain, where Vinci and Ferrovial operate toll-road portfolios exceeding 2,000 kilometers.
Elastomeric Bearings Market Segmentation
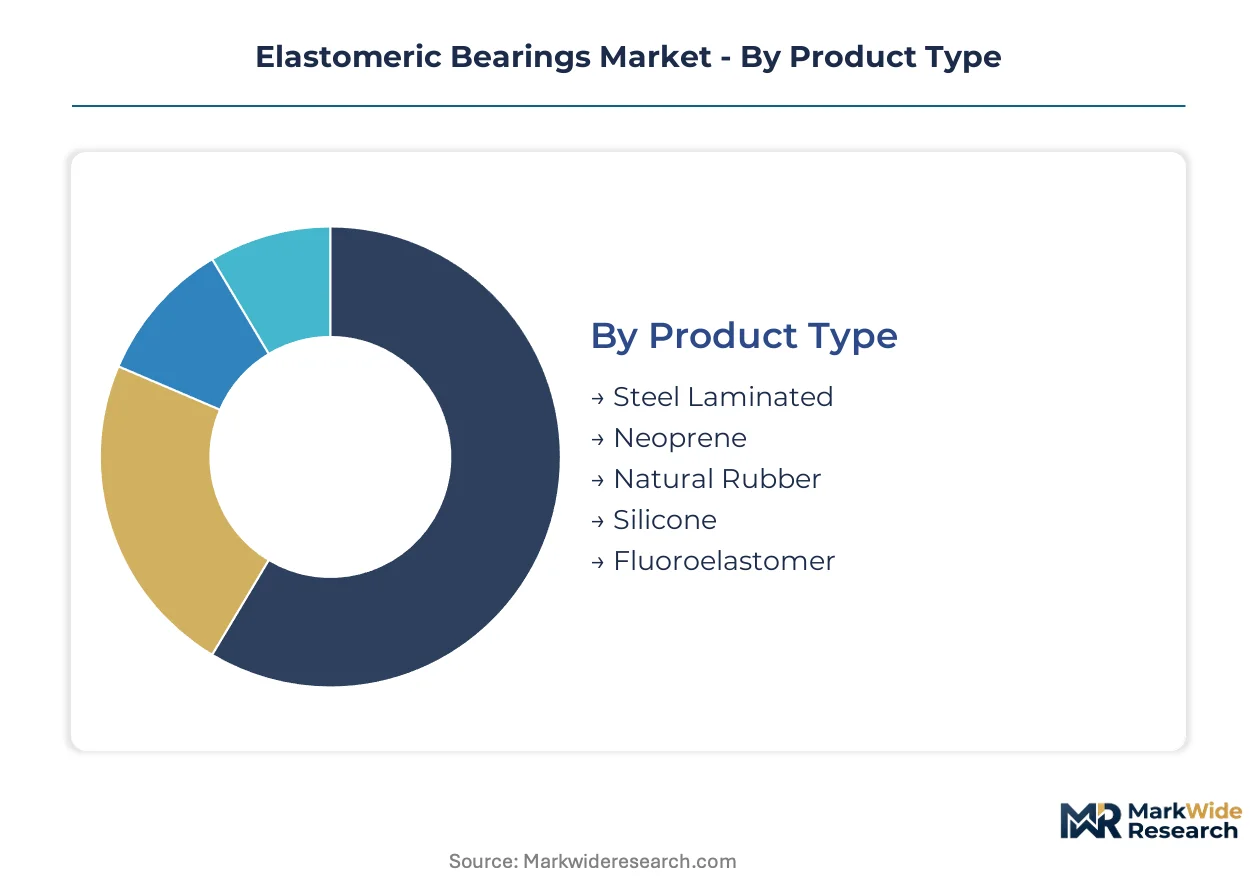
Elastomeric bearing procurement splits across material chemistry, structural application, and project lifecycle stage. Specification thresholds diverge sharply between new-build contracts and retrofit mandates, forcing suppliers to maintain parallel certification portfolios.
Product Type:
After-sales service intensity varies dramatically across elastomer compounds, with steel-laminated systems demanding predictive maintenance contracts and fluoroelastomer grades requiring specialized inspection protocols.
- Steel Laminated:Alternating vulcanized rubber layers bonded to steel plates deliver shear moduli of 0.4-1.2 MPa for heavy-load bridge applications. German autobahn authorities specify these for fatigue resistance under continuous traffic loading, with federal procurement offices mandating 50-year design life certifications.
- Neoprene:Polychloroprene compounds resist ozone degradation and coastal salt exposure, expanding service intervals in maritime environments. Contractors in France and Spain favor these for toll-road portfolios where maintenance access is restricted.
- Natural Rubber:High-damping formulations with carbon black additives dissipate seismic energy in base isolation systems.
- Silicone:Extreme temperature stability from minus 60 to plus 200 degrees Celsius suits cryogenic and high-heat infrastructure.
- Fluoroelastomer:Chemical resistance against petroleum derivatives and industrial solvents protects bearings in refinery-adjacent bridges.
By volume, steel-laminated bearings lead procurement. By growth pace, neoprene compounds are expanding most quickly as coastal retrofit programs accelerate.
Application:
Structural load characteristics and movement tolerances dictate material selection across transportation infrastructure categories.
- Bridges:Multi-span highway structures require bearings accommodating longitudinal thermal expansion and rotational deck movements. Seismic retrofit mandates in Japan and the western US are compressing installation timelines for pre-1980s infrastructure.
- Railways:High-speed track systems demand vertical stiffness control to maintain gauge stability under dynamic wheel loads.
- Tunnels:Confined installation spaces restrict bearing dimensions and favor segmented replacement strategies.
- Flyovers:Urban interchanges with constrained maintenance windows specify quick-install bearing systems.
- Elevated Highways:Curved alignments introduce complex multi-axis movement requirements.
Bridges dominate procurement volume. Railways show the steepest expansion trajectory as high-speed corridor investments multiply.
End User:
Contractor technical capabilities and project financing structures shape specification authority across the value chain.
- Construction Firms:General contractors with in-house structural teams influence bearing selection during design-build procurement.
- Infrastructure Developers:Availability-based concession holders prioritize lifecycle cost optimization over initial capital expenditure.
- Road Contractors:Specialized paving and bridge firms execute installation under subcontract to asset owners.
- Civil Engineering Consultants:Design authorities specify bearing performance criteria and approve supplier qualifications.
Infrastructure developers control the largest contract value. Civil engineering consultants are gaining specification influence as performance-based design spreads.
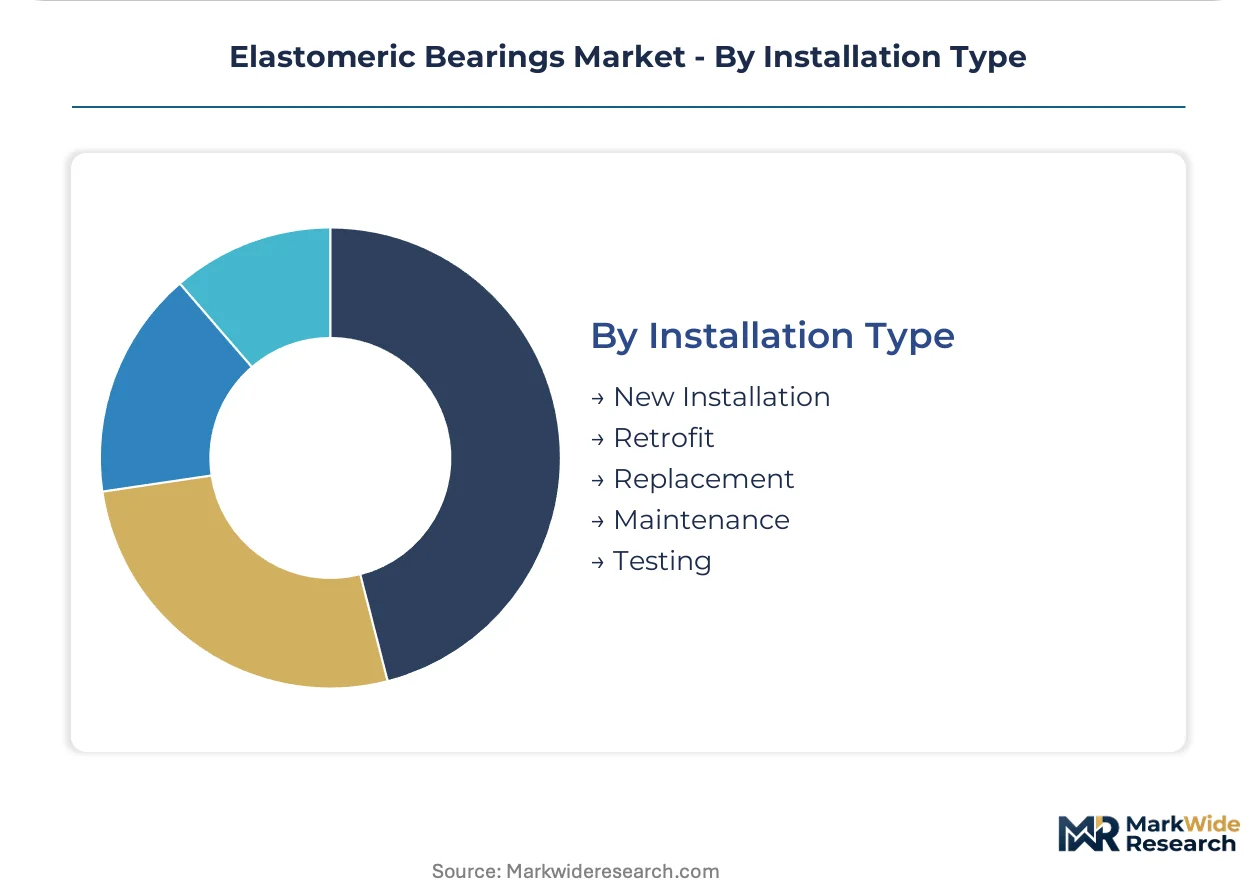
Installation Type:
Project lifecycle positioning determines margin structure and technical risk allocation for bearing suppliers.
- New Installation:Greenfield bridge construction allows integrated bearing design with substructure elements, reducing interface engineering.
- Retrofit:Seismic upgrade projects require hydraulic jacking and temporary structural support, elevating labor intensity and contract margins.
- Replacement:End-of-life bearing swaps demand compatibility with existing anchorages and load paths.
- Maintenance:Scheduled inspection and elastomer surface treatment extends service intervals.
- Testing:Proof-load validation and displacement monitoring verify performance under AASHTO LRFD protocols.
New installation generates the highest absolute volume. Retrofit contracts command premium pricing and fastest backlog growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal infrastructure stimulus programs and seismic safety mandates are redirecting procurement volumes toward bridge rehabilitation markets. National highway authorities in industrialized economies are compressing supplier qualification timelines while tightening environmental compliance thresholds for elastomer compounds.
Germany
Autobahn bridge retrofit mandates are accelerating demand for steel-laminated bearing systems. The EU Green Deal procurement guidelines require Environmental Product Declarations for all federal infrastructure contracts. Industrial clusters in Bavaria and North Rhine-Westphalia host specialized vulcanization facilities serving Central European highway programs.
United States
State DOT seismic upgrade programs for pre-1980s highway infrastructure are expanding specification volumes. The Federal Highway Administration enforces AASHTO LRFD proof-load testing protocols that extend supplier certification periods. Fabrication capacity concentrates in the Midwest and Gulf Coast regions where petrochemical feedstock access supports chloroprene compound production.
Japan
METI-funded base isolation projects specify high-damping natural rubber formulations for energy dissipation. National seismic codes mandate bearing replacements for aging highway structures in earthquake-prone zones. Engineering expertise clusters in the Kanto and Kansai regions where polymer chemist specialization supports advanced compound development.
India
Bharatmala national highway corridors lack domestic seismic bearing manufacturing capacity, creating import dependency. The Bureau of Indian Standards is developing localized certification protocols for bridge bearing acceptance. Infrastructure development concentrates in Maharashtra and Gujarat where toll-road concessions are expanding procurement pipelines.
France
Availability-based road concessions operated by infrastructure funds are unbundling bearing supply from installation services. EU F-Gas Regulation restrictions are accelerating compound reformulation toward water-based foaming systems. Lyon and Paris metropolitan zones host engineering consultancies specifying performance-based bearing criteria for urban interchange projects.
Elastomeric Bearings Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement environments. The vendor base organizes into three tiers: polymer compounders with captive vulcanization capacity, structural installation contractors with backward integration into bearing supply, and regional fabrication shops serving discrete geographic markets. Dominant competitive moves include strategic partnerships with infrastructure funds and portfolio diversification into predictive maintenance services.
Within the polymer-compounder archetype, Trelleborg AB anchors Nordic supply relationships through multi-year infrastructure fund agreements. Freyssinet Limited exemplifies the vertically integrated installation contractor model, controlling elastomer formulation through structural jacking service delivery. Mageba Group occupies the seismic-specialist position, concentrating specification authority in earthquake-prone retrofit markets. These three entities represent distinct competitive vectors: compound expertise, installation integration, and application specialization.
| Leading Market Players |
|---|
| Trelleborg AB |
| Freyssinet Limited |
| Mageba Group |
| Canam Group Inc. |
| BRP Manufacturing |
| D.S. Brown |
| MAURER SE |
| Granor Rubber & Engineering Pty. Limited |
| Ekspan Limited |
| Others |
Pricing and Supply Chain Analysis
Vulcanized steel plate fabrication clusters in China concentrate upstream capacity for elastomeric bearing laminates, anchoring margin pools with compounders who command AASHTO LRFD certification and captive polymer formulation expertise. European contractors face cost compression when sourcing from these single-source regions, while retrofit installation specialists capture premium pricing through hydraulic jacking capabilities that commodity fabricators cannot replicate.
Pricing Analysis
Certification level creates the primary spread across elastomeric bearing tiers, with AASHTO LRFD proof-load validation and EU Environmental Product Declarations commanding 15-25% premiums over uncertified alternatives. Pricing stratifies across seismic-grade high-damping compounds, standard neoprene formulations, and economy natural rubber grades, with coastal salt-resistance specifications widening the gap between ozone-resistant neoprene and baseline chloroprene. Cost compression in economy tiers is intensifying because Indian and Southeast Asian contractors are qualifying lower-grade suppliers for Bharatmala highway corridors. State DOT procurement officers show the highest price sensitivity, while availability-based infrastructure funds prioritize lifecycle cost optimization over unit pricing.
Supply Chain Analysis
Contract vulcanization capacity concentrates with Trelleborg AB's Nordic facilities, Freyssinet Limited's European plants, and specialized fabrication shops in China's Yangtze River Delta region. Raw material flows draw from Malaysian natural rubber plantations, German petrochemical chloroprene streams, and Japanese carbon black additives for high-damping formulations. Single-source vulnerability runs through Chinese steel plate lamination clusters, where export licensing delays can disrupt European retrofit timelines. Distribution feeds from compounder-direct relationships with infrastructure funds, bypassing traditional construction distributor networks for large highway concession contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation expertise for high-damping rubber compounds is retiring faster than knowledge transfer systems can replace it, compressing the window for capability acquisition across Germany and Japan's specialist clusters.
For Market Incumbents: Pre-empt compound specialist retirements by acquiring polymer chemistry teams from defunct Japanese METI-funded research programs before competitors lock in talent. Defend margin position through captive supply of water-based foaming systems that comply with EU F-Gas Regulation bans on hydrofluorocarbon blowing agents, while adding predictive maintenance sensor integration to bearing pads for toll-road operator contracts. For New Entrants and Emerging Players: Pursue seismic retrofit mandates in India's Bharatmala corridors where domestic bearing manufacturing capacity is absent and import substitution incentives are expanding. Target state DOT procurement offices in the US western states where pre-1980s bridge seismic upgrade timelines are compressing and AASHTO LRFD certification backlogs create qualification gaps. Lead with digital twin integration capabilities that incumbent compounders lack, embedding IoT displacement sensors during vulcanization. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed infrastructure installation contractors who acquired bearing supply capabilities during 2015-2020 concession privatization waves. Five-to-ten year viability hinges on compound reformulation R&D pipelines aligned with EU Green Deal embodied carbon scoring mandates. Monitor German federal highway authority procurement bulletins for seismic retrofit program acceleration as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive neoprene formulation secures EU F-Gas compliance for German autobahn contracts. |
| Seismic Isolation System Certification | METI-funded base isolation specifications in Japan open premium retrofit pricing tiers. |
| Digital Twin Sensor Embedding | IoT displacement monitoring enables predictive maintenance contracts with Vinci and Ferrovial toll-road portfolios. |
| Water-Based Foaming System Transition | Environmental Product Declaration compliance meets EU Green Deal procurement weighting for federal infrastructure tenders. |
| Regional Fabrication Capacity Expansion | Maharashtra and Gujarat facilities reduce import dependency for India's Bharatmala highway corridors. |
Research Methodology
A standing panel of bridge design engineers, state DOT procurement officers, polymer compound R&D directors, and infrastructure fund asset managers provided ongoing calibration against primary fieldwork conducted across German autobahn authorities, Japanese METI project offices, and Indian National Highways Authority of India planning divisions. Secondary validation drew from AASHTO LRFD specification updates, EU F-Gas Regulation implementation bulletins, Bureau of Indian Standards draft protocols, and customs trade data on vulcanized rubber product flows. Bottom-up project pipeline analysis triangulated with top-down infrastructure stimulus allocation tracking.
Scenario bracketing around EU Green Deal procurement acceleration, seismic code upgrade timing, and petrochemical feedstock price volatility shaped volume and value outputs across the projection horizon. Segmentation dimensions modeled include material chemistry tier, structural application category, project lifecycle stage, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves fitted to historic retrofit installation backlogs and new-build highway concession awards, with carbon black additive cost curves and steel plate laminate fabrication capacity utilization serving as industry-specific forecast inputs.
Sensitivities concentrate around EU F-Gas Regulation enforcement timing, Japanese seismic code revision cycles, and Indian domestic certification protocol finalization. Forecasts reflect assumptions on infrastructure fund concession award velocity and polymer chemist labor market tightness. Quarterly review of German federal procurement office Environmental Product Declaration requirements and US state DOT seismic retrofit program announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Construction
North America Structural Steel Fabrication Market
Structural Construction
South Korea Construction Market
Structural Construction
Saudi Arabia Structural Steel Fabrication Market
Structural Construction
Sandwich Plate System Market
Structural Construction
Steel Beam Market
Structural Construction
Girder Market
Structural Construction
GCC Prefabricated Building and Structural Steel Market
Structural Construction
Italy Concrete Railway Sleepers Market
Structural Construction
Supported Scaffolding Market
Structural Construction
GCC Structural Steel Fabrication Market
Structural Construction
Vietnam Structural Steel Fabrication Market
Structural Construction
Global Concrete Contractor Market
Structural Construction
H Beam Market
Structural Construction
Glue Laminated Beams Market
Structural Construction
Saudi Arabia Prefabricated Building and Structural Steel Market
Structural Construction
US Heavy Movable Bridges Market