
 Global Structural Steel Fabrication Market | 2026-2036
Global Structural Steel Fabrication Market Size, Share, and Industry Trends Forecast 2026-2036
Global Structural Steel Fabrication Market Foresight
The direct-to-fabricator procurement channel is narrowing as tier-one contractors consolidate vendor lists and push volume commitments onto fewer approved suppliers. Thyssenkrupp leverages its integrated steel-to-fabrication workflow to secure long-term infrastructure contracts across European rail and bridge projects. Schuff Steel anchors North American demand through its specialized heavy-plate and seismic-resistant fabrication capabilities for high-rise commercial cores.
Structural steel fabrication transforms hot-rolled sections, plates, and hollow structural sections into engineered assemblies through cutting, welding, drilling, and thermal-mechanical processing, with yield strengths typically ranging from 250 MPa to 690 MPa depending on grade specification. These fabricated elements serve as the primary load-bearing skeleton for commercial buildings, bridges, industrial facilities, and transportation infrastructure. Beams and columns dominate current fabrication tonnage due to their ubiquity in multi-story commercial construction, while plates and pipes capture expanding share in bridge cable-stay anchorages and industrial process structures where thicker sections and specialized welding protocols command premium positioning. The welding technology segment leads capital investment intensity as automated submerged-arc and robotic gas-metal-arc systems displace manual processes in high-volume shops.
The American Institute of Steel Construction certification, EN 1090 execution-class standards in Europe, and ISO 3834 welding quality requirements collectively govern market access and project eligibility across major economies. China's GB standards and MEE emissions enforcement are tightening shop-floor environmental compliance, reshaping cost structures for export-oriented fabricators. Stakeholders must monitor evolving carbon-border adjustment mechanisms and building-code seismic upgrades as these forces will redistribute competitive advantage between domestic and cross-border fabrication sources.
Market Dynamics
The global structural steel fabrication market is experiencing a fundamental reconfiguration as embodied-carbon mandates compress supplier margins and concentrate procurement authority among tier-one contractors with certified green supply chains. This regulatory pressure is colliding with automation investments that are widening the capability gap between capital-rich fabricators and smaller regional shops.
Growth Catalysts
- EU Green Deal embodied-carbon thresholds:Germany, France, and Italy are tightening building-code requirements for structural steel, forcing asset owners to source low-carbon fabricated elements and creating premium positioning for mills with electric-arc furnace capacity.
- Bridge megaprojects across North America:Procurement volumes for welded plate girders and box sections are expanding as state transportation departments accelerate deferred infrastructure replacement programs.
- Automated welding systems:Robotic gas-metal-arc and submerged-arc technologies are displacing manual processes in high-volume shops, reducing labor cost volatility and improving repeatability for seismic-grade connections.
Market Restraints
- Scrap and electricity cost volatility:Electric-arc furnace operators face input cost instability that compresses fabrication margins when long-term infrastructure contracts lock in fixed pricing.
- Supply concentration in Chinese heavy-plate:Export-oriented fabricators in Southeast Asia remain dependent on Chinese mill supply for thick sections, exposing them to carbon-border adjustment mechanism risks and trade policy friction.
- Technical limitation in hydrogen-ready steel:Commercial-scale production of near-zero-emission structural grades remains below volume thresholds needed for mainstream bridge and high-rise specifications.
Strategic Opportunities
- India's industrial corridor buildout:The country's Dedicated Freight Corridor and smart city programs are generating demand for fabricated trusses and portal frames that domestic capacity cannot fully supply.
- Modular offsite construction convergence:Fabricators integrating building information modeling with automated cutting and drilling are capturing design-phase value previously held by engineering consultancies.
- US Inflation Reduction Act domestic content bonuses:Tax incentives for domestically sourced structural steel are redirecting procurement toward US-based fabrication shops with AISC certification.
Industry Challenges
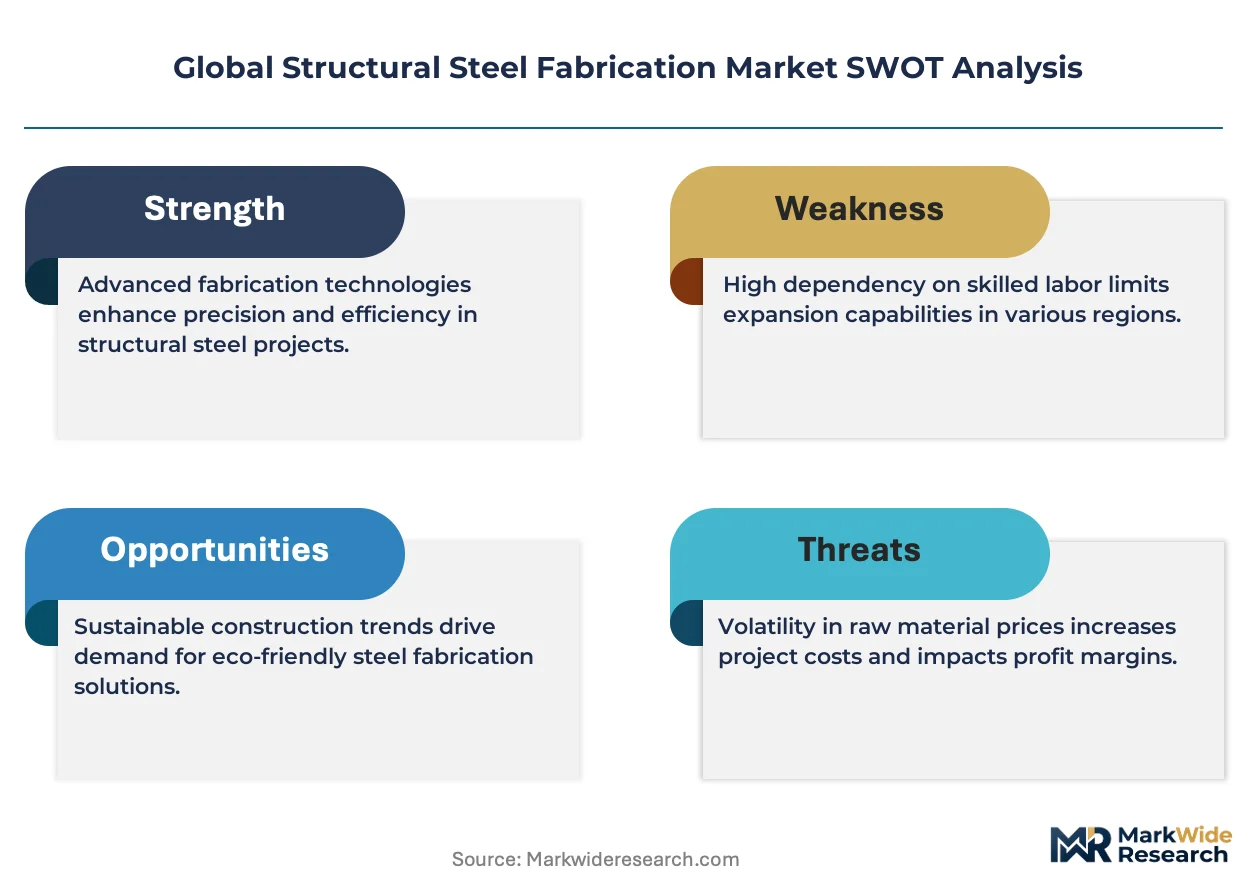
- Certified welder scarcity:Shops struggle to recruit operators qualified for EN 1090 execution-class welding and seismic connection protocols, extending project timelines.
- Multi-standard compliance complexity:Fabricators serving cross-border projects must simultaneously maintain AISC, EN 1090, and ISO 3834 quality systems, inflating audit and documentation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Structural Steel Fabrication Market |
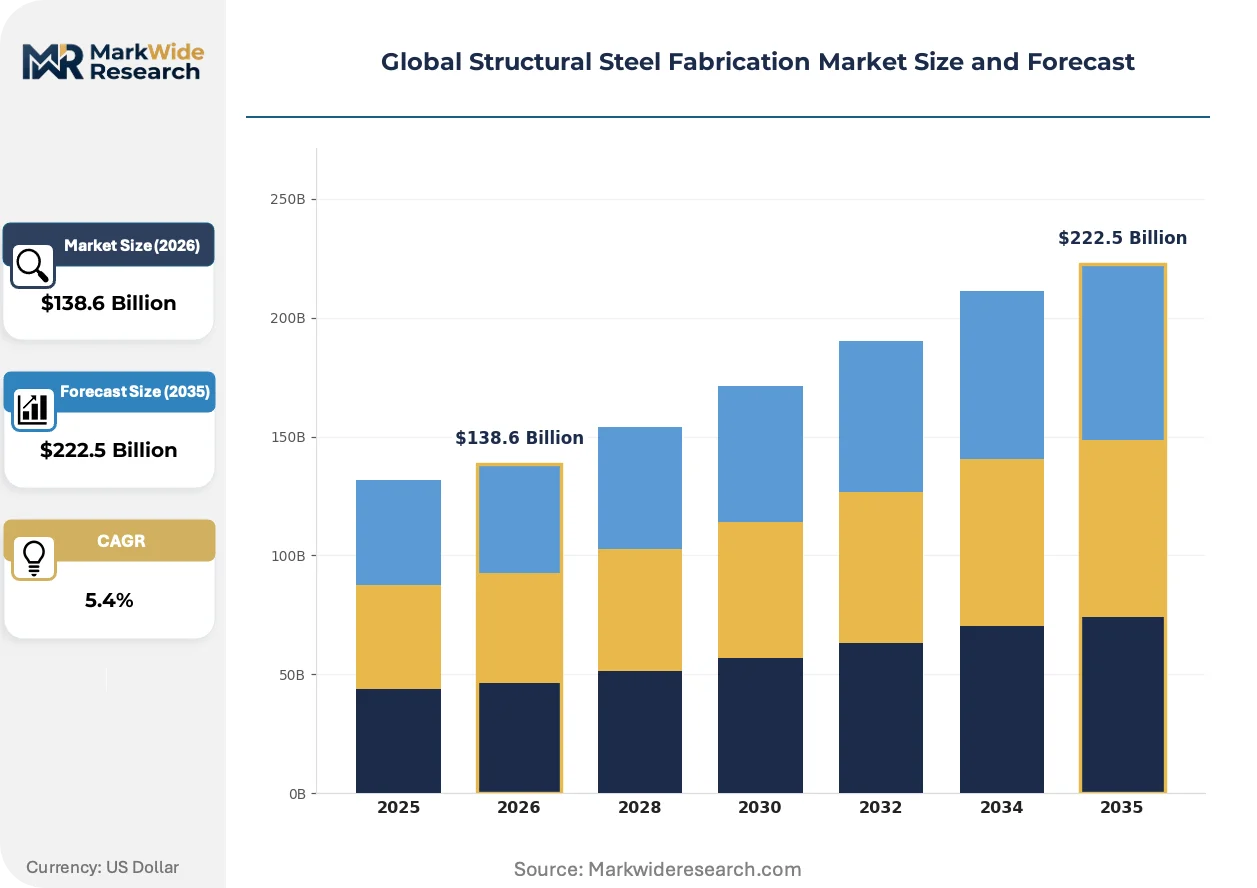
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $222.5 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beams, Columns, Trusses, Plates, Pipes, Channels Technology: Cutting, Welding, Drilling, Bending, Rolling, Shearing Application: Commercial Buildings, Bridges, Industrial Facilities, Warehouses, Stadiums, Transportation Infrastructure End User: Construction Companies, Engineering Firms, Fabricators, Infrastructure Developers, Fabrication Workshops |
| Companies Covered | Schuff Steel, Thyssenkrupp, Mayville Engineering Company, BlueScope Steel, Voestalpine, BTD Manufacturing, Lexicon, Anchor Fabrication, O’Neal Manufacturing Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Structural Steel Fabrication Market Shifts & Advancements
Digital thread technologies are collapsing the traditional sequence between engineering design, fabrication planning, and field erection. This integration is compressing project timelines and shifting competitive advantage toward shops with in-house engineering capabilities.
Robotic thermal cutting and drilling systems paired with real-time dimensional feedback loops are rendering obsolete manual layout and fit-up processes in high-volume structural shops. Bridge fabricators in the United States are adopting these systems fastest, driven by Federal Highway Administration quality assurance requirements that reward repeatable precision with reduced inspection sampling rates.
The EU Green Deal's carbon-border adjustment mechanism is forcing non-European fabricators to document embodied emissions through third-party verification. Mills in Turkey and South Korea are responding by securing renewable electricity supply contracts and installing scrap-based electric-arc furnace capacity to maintain access to German and French infrastructure tenders.
Consolidation of approved vendor lists by tier-one contractors is concentrating procurement authority among a shrinking pool of pre-qualified fabricators. This pattern is most visible in United States commercial high-rise construction, where general contractors now require AISC certification, past-performance bonding, and million-ton annual capacity as minimum entry thresholds, displacing mid-size regional shops from core urban projects.
Global Structural Steel Fabrication Market Segmentation
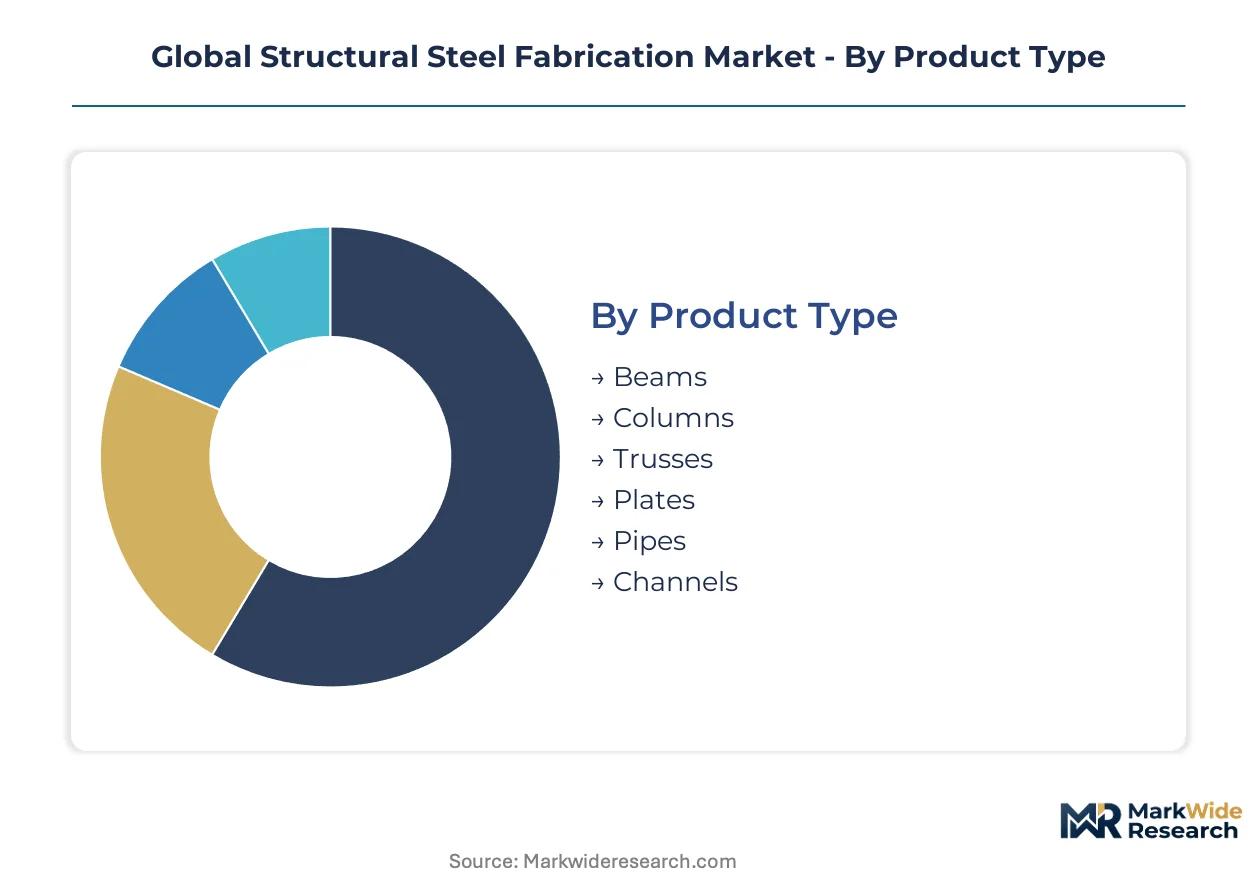
Segmentation in structural steel fabrication reveals how specification complexity, automation intensity, and project scale reshape procurement patterns. Each dimension exposes distinct margin profiles and capability requirements that separate capital-intensive leaders from regional competitors.
Product Type:
Product choice tracks directly to load-bearing function and connection complexity across building and infrastructure types.
- Beams:Hot-rolled I-sections and welded plate girders constitute the foundational horizontal elements for floor and roof systems. Procurement volumes concentrate in commercial high-rise cores across China, India, and the United States as urban density intensifies.
- Columns:Vertical compression members fabricated from wide-flange sections or built-up plates carry gravity loads through multi-story structures. Seismic-resistant moment-frame specifications in California and Japan drive demand for high-strength grades with stringent ductility requirements.
- Trusses:Triangulated assemblies of hollow structural sections or angles optimize span-to-weight ratios for long-roof applications.
- Plates:Flat-rolled steel processed into gussets, base plates, and box-section components for bridge and industrial structures.
- Pipes:Circular hollow sections serve as columns, bracing, and architectural exposed elements with superior torsional resistance.
- Channels:C-shaped sections provide secondary framing, bracing, and miscellaneous support in industrial construction.
The dominant share belongs to beams, while plates are closing the gap fastest on bridge megaproject demand.
Technology:
Process selection determines labor cost exposure, repeatability, and certification eligibility for seismic and pressure-vessel applications.
- Welding:Automated submerged-arc and robotic gas-metal-arc systems displace manual processes in high-volume shops serving bridge and high-rise specifications. Federal Highway Administration quality assurance protocols reward robotic precision with reduced inspection sampling rates.
- Cutting:Thermal plasma and laser systems with real-time dimensional feedback collapse layout-to-fabrication timelines. European fabricators adopting these systems fastest under EN 1090 execution-class tolerances for rail infrastructure.
- Drilling:CNC beam lines automate hole patterns for bolted connections in commercial building frames.
- Bending:Roll-forming and press-brake operations shape plates and sections into curved architectural and bridge elements.
- Rolling:Section straightening and camber adjustment correct residual stresses from hot-rolling or welding heat input.
- Shearing:Mechanical and hydraulic cutting prepares plate stock for subsequent welding and machining operations.
Welding commands the highest capital investment intensity, with cutting gaining share fastest through digital integration with building information modeling.
Application:
End-use segmentation separates commodity fabrication from premium positioning through specification grade and certification burden.
- Commercial Buildings:Multi-story office and residential towers drive repetitive beam-and-column fabrication with AISC certification requirements. US Inflation Reduction Act domestic content bonuses redirect procurement toward certified US shops.
- Bridges:Welded plate girders and box sections for cable-stay and truss systems command premium margins through fracture-critical specifications. State transportation departments across Texas, California, and New York accelerate deferred replacement programs.
- Industrial Facilities:Process structures and heavy equipment supports utilize thicker plates and specialized welding protocols.
- Warehouses:Single-story portal frames and rack-supported buildings prioritize speed and economy over architectural finish.
- Stadiums:Long-span roof trusses and exposed architectural steel require tight dimensional tolerances and aesthetic surface quality.
- Transportation Infrastructure:Rail stations, airport terminals, and port facilities combine heavy structural loads with high-visibility architectural requirements.
Commercial buildings retain the largest fabrication tonnage, with bridges expanding most quickly on infrastructure stimulus deployment.
End User:
Customer type determines contract structure, from spot purchasing to multi-year framework agreements with engineering integration.
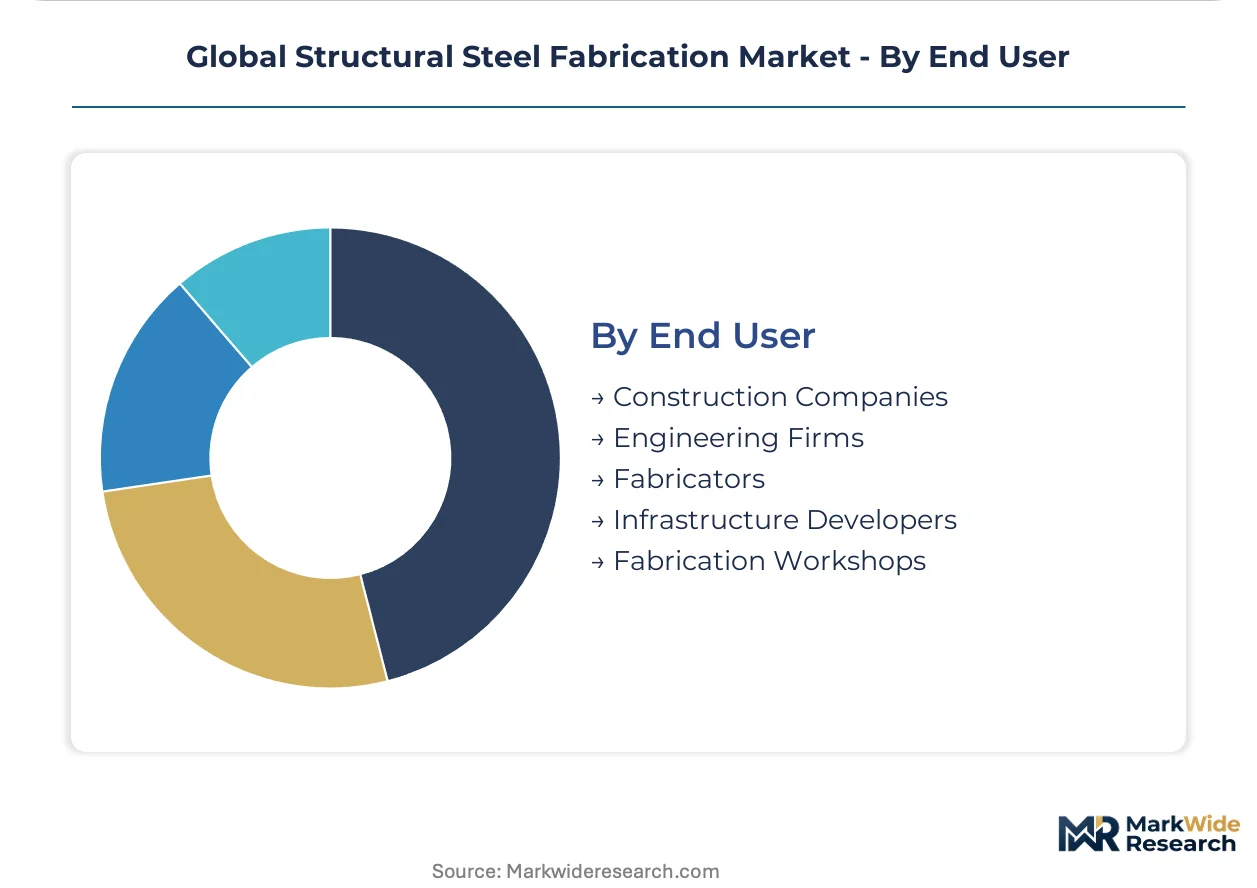
- Construction Companies:General contractors and tier-one builders consolidate vendor lists and push volume commitments onto fewer approved suppliers with million-ton annual capacity thresholds.
- Engineering Firms:Design-phase procurement of specialty connections and complex assemblies rewards fabricators with in-house detailing capabilities.
- Fabricators:Subcontracted component supply for shops lacking specific equipment or certification scope.
- Infrastructure Developers:Public-private partnership sponsors and concession holders source fabricated elements through design-build contracts.
- Fabrication Workshops:Smaller regional shops serving local commercial and industrial projects with limited certification scope.
Construction companies control the dominant procurement volume, while engineering firms are gaining influence fastest through early-stage design integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in German fabrication shops runs 15-20% above Southeast Asian export rates, reflecting EN 1090 certification premiums and carbon-border adjustment exposure. Chinese fabricators absorb margin compression from MEE emissions enforcement. Indian domestic capacity strains against Dedicated Freight Corridor demand.
United States
State transportation departments in Texas, California, and New York accelerate bridge replacement programs, expanding procurement for welded plate girders. The Federal Highway Administration rewards robotic welding precision with reduced inspection sampling rates. Schuff Steel anchors Gulf Coast and West Coast demand through heavy-plate capabilities for seismic-resistant high-rise cores.
Germany
Rail infrastructure across Bavaria and North Rhine-Westphalia drives demand for EN 1090 execution-class fabricated elements. The EU Green Deal's embodied-carbon thresholds force asset owners toward electric-arc furnace supply chains. Thyssenkrupp leverages integrated steel-to-fabrication workflows to secure long-term contracts for European bridge and rail projects.
China
Megaproject pipelines in the Yangtze River Delta and Pearl River Delta concentrate demand for fabricated beams and columns. MEE emissions enforcement tightens shop-floor environmental compliance, reshaping cost structures for export-oriented fabricators. GB standards governing welding quality and carbon intensity reshape competitive positioning between coastal and inland fabrication clusters.
India
The Dedicated Freight Corridor and smart city programs generate demand for fabricated trusses and portal frames that domestic capacity cannot fully supply. BIS certification requirements and PLI scheme incentives redirect procurement toward domestic mills with expanded fabrication capabilities. Maharashtra and Gujarat industrial corridors attract foreign fabrication joint ventures to bridge supply gaps.
United Arab Emirates
NEOM and Red Sea tourism infrastructure projects source fabricated elements for long-span roof systems and transportation terminals. MOHAP and municipal building codes tighten structural steel specifications for seismic resilience. Dubai and Abu Dhabi fabrication clusters specialize in architectural exposed steel with tight dimensional tolerances for high-visibility developments.
Global Structural Steel Fabrication Market Competitive Landscape
Integrated steel-to-fabrication conglomerates and specialized heavy-plate contractors split the market along capital-intensity lines. Consolidation pressure from tier-one contractor vendor-list narrowing favors shops with million-ton annual capacity and multi-standard certification portfolios. Three archetypes dominate: mill-integrated fabricators with captive steel supply, independent heavy-plate specialists with seismic-grade capabilities, and regional job shops serving local commercial construction. Competitive dynamics center on automation investment cycles and cross-border carbon-compliance documentation.
Within the mill-integrated tier, Thyssenkrupp exemplifies European vertical control over steel production and fabrication execution. Among North American heavy-plate specialists, Schuff Steel occupies a position defined by seismic-resistant fabrication capabilities for high-rise commercial cores. Voestalpine represents the Austrian-German fabrication complex serving rail and bridge infrastructure with EN 1090-certified execution. These three anchors illustrate how certification scope and geographic concentration determine project eligibility in an increasingly consolidated procurement environment.
| Leading Market Players |
|---|
| Schuff Steel |
| Thyssenkrupp |
| Mayville Engineering Company |
| BlueScope Steel |
| Voestalpine |
| BTD Manufacturing |
| Lexicon |
| Anchor Fabrication |
| O'Neal Manufacturing Services |
| Others |
Supply & Pricing Matrix
Carbon-border adjustment exposure determines both pricing tier spreads and supply chain shape across the structural steel fabrication landscape. Fabricators serving German and French infrastructure tenders absorb compliance documentation costs that widen spreads between EN 1090-certified premium supply and uncertified economy-grade alternatives.
Pricing Analysis
Configured-to-order pricing for fracture-critical bridge girders commands substantial premiums over standard beam-and-column fabrication for commercial buildings. Three-tier pricing structure across premium, standard, and economy levels separates seismic-grade moment-frame connections from warehouse portal frames and uncertified miscellaneous steel. Cost compression in standard commercial tonnage intensifies as Chinese export capacity absorbs regional demand. Warehouse developers exhibit highest price sensitivity, while bridge authorities prioritize certification reliability over unit cost.
Supply Chain Analysis
Heavy-plate rolling capacity concentrates in China, Japan, and South Korea, with Turkish mills gaining share under EU carbon-border adjustment compliance. Fabrication draws from scrap-based electric-arc furnace feedstock, imported heavy plate, and domestic hollow structural sections. Single-source vulnerability runs through Chinese thick-plate supply for Southeast Asian export fabricators. Distribution runs through tier-one contractor approved-vendor lists that consolidate procurement authority among pre-qualified suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Structural steel fabrication operates as a substitution defense against mass timber and engineered composites in mid-rise construction. Incumbents must navigate cross-laminated timber code approvals that threaten traditional beam-and-column specifications.
For Market Incumbents: Pre-empt mass timber encroachment by securing early-stage engineering integration through building information modeling partnerships. Capture design-phase value previously held by consultancies. Deepen captive steel supply through electric-arc furnace investments that satisfy EU Green Deal thresholds. Defend against emerging modular offsite construction entrants by embedding fabrication data into digital thread workflows.
For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, as domestic capacity strains against urbanization demand. India's Dedicated Freight Corridor and smart city programs offer white-space traction where foreign joint ventures bridge supply gaps. Target engineering firm procurement channels with specialized connection detailing capabilities rather than competing for tier-one contractor vendor-list slots.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mill-integrated fabricators with multi-standard certification portfolios. Long-term viability hinges on automation capital intensity and carbon-compliance documentation capabilities. Acquisition candidates should demonstrate EN 1090, AISC, and ISO 3834 quality systems alongside robotic welding deployment. Monitor carbon-border adjustment mechanism expansion as the primary inflection signal for competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electric-Arc Furnace Steel | Captive low-carbon supply secures eligibility for German and French infrastructure tenders under EU Green Deal thresholds. |
| Robotic Welding System Deployment | Automated submerged-arc and gas-metal-arc systems reduce Federal Highway Administration inspection sampling rates for bridge fabricators. |
| Multi-Standard Certification Investment | Simultaneous AISC, EN 1090, and ISO 3834 quality systems unlock cross-border project eligibility and tier-one contractor vendor-list inclusion. |
| Building Information Modeling Integration | Design-phase data capture shifts value from engineering consultancies toward fabrication shops with in-house detailing capabilities. |
| Renewable Electricity Supply Contracting | Third-party verified embodied-carbon documentation maintains access to European markets under carbon-border adjustment mechanisms. |
Research Methodology
A spread of perspectives from fabrication plant managers, tier-one contractor procurement directors, bridge authority engineers, and electric-arc furnace operators converged on the working assumptions. Primary interviews combined with secondary validation against customs trade data, American Institute of Steel Construction certification records, SEC filings from publicly traded steel producers, and European Committee for Standardization documentation. Bottom-up project pipeline assessments triangulated against top-down steel consumption forecasts.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, welding technology tier, application specification grade, and regional regulatory cluster. CAGRs derived from historical tonnage trajectories adjusted for megaproject acceleration and embodied-carbon policy implementation. Forecast inputs incorporated electric-arc furnace capacity expansion timelines and carbon-border adjustment mechanism coverage expansion.
Practitioners should monitor scrap and electricity cost volatility, hydrogen-ready steel commercialization thresholds, and seismic code upgrade schedules for early signals of forecast revision. Quarterly review of tier-one contractor vendor-list consolidation patterns and EN 1090 certification issuance rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Construction
China Structural Steel Fabrication Market
Structural Construction
Bridge Construction Market
Structural Construction
Italy Concrete Railway Sleepers Market
Structural Construction
Global Rebar Splice Market
Structural Construction
Ceiling Expansion Joint Market
Structural Construction
H Beam Market
Structural Construction
North America Structural Steel Fabrication Market
Structural Construction
Steel Beam Market
Structural Construction
United Arab Emirates Structural Steel Fabrication Market
Structural Construction
Vietnam Structural Steel Fabrication Market
Structural Construction
UAE Prefabricated Building and Structural Steel Market
Structural Construction
Glue Laminated Beams Market
Structural Construction
Global Concrete Contractor Market
Structural Construction
Girder Market
Structural Construction
Supported Scaffolding Market
Structural Construction
Bridge Bearings Market