
 Europe Sandwich Panels Market | 2026-2036
Europe Sandwich Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sandwich Panels Market Insights
Modular prefabrication of complete wall-roof systems is consolidating buyer choice around factory-integrated thermal and fire-performance packages rather than site-assembled components. Kingspan Group leverages its vertically integrated insulation-core manufacturing to sustain margin control across Northern European projects. ArcelorMittal anchors supply of coated steel facings through dedicated rolling capacity near Benelux construction hubs. Metecno competes on project-specific engineering for cold-chain clients requiring validated thermal-bridge calculations.
Europe sandwich panels are composite building elements comprising rigid insulating cores bonded between metal or composite facing sheets, typically achieving U-values below 0.20 W/m²K for envelope applications. Their primary purpose is to deliver structural load-bearing capacity combined with thermal, fire, or acoustic performance in a single lightweight factory-manufactured component. Thermal insulated panels dominate volume across warehouse and logistics construction where energy-code compliance drives specification, while fire resistant variants command premium positioning in multi-storey commercial and public buildings where Euroclass A2 or B-s1,d0 ratings are mandatory. Acoustic panels remain a specialized margin pool for transport infrastructure and industrial facilities near residential zones, with mineral wool cores preferred where sound attenuation exceeds thermal priority.
The EU Green Deal's renovation-wave targets and the Energy Performance of Buildings Directive reshape product standards across member states, with CE marking under EN 14509 governing structural and thermal declarations. ECHA's evolving restrictions on flame-retardant additives in polystyrene cores are prompting reformulation toward mineral wool and pentane-blown polyurethane alternatives. National building regulators in France and Germany enforce divergent fire-test protocols that fragment certification requirements for cross-border suppliers. Stakeholders must monitor pending revisions to the Construction Products Regulation and assess core-material transition costs before capacity commitments crystallize.
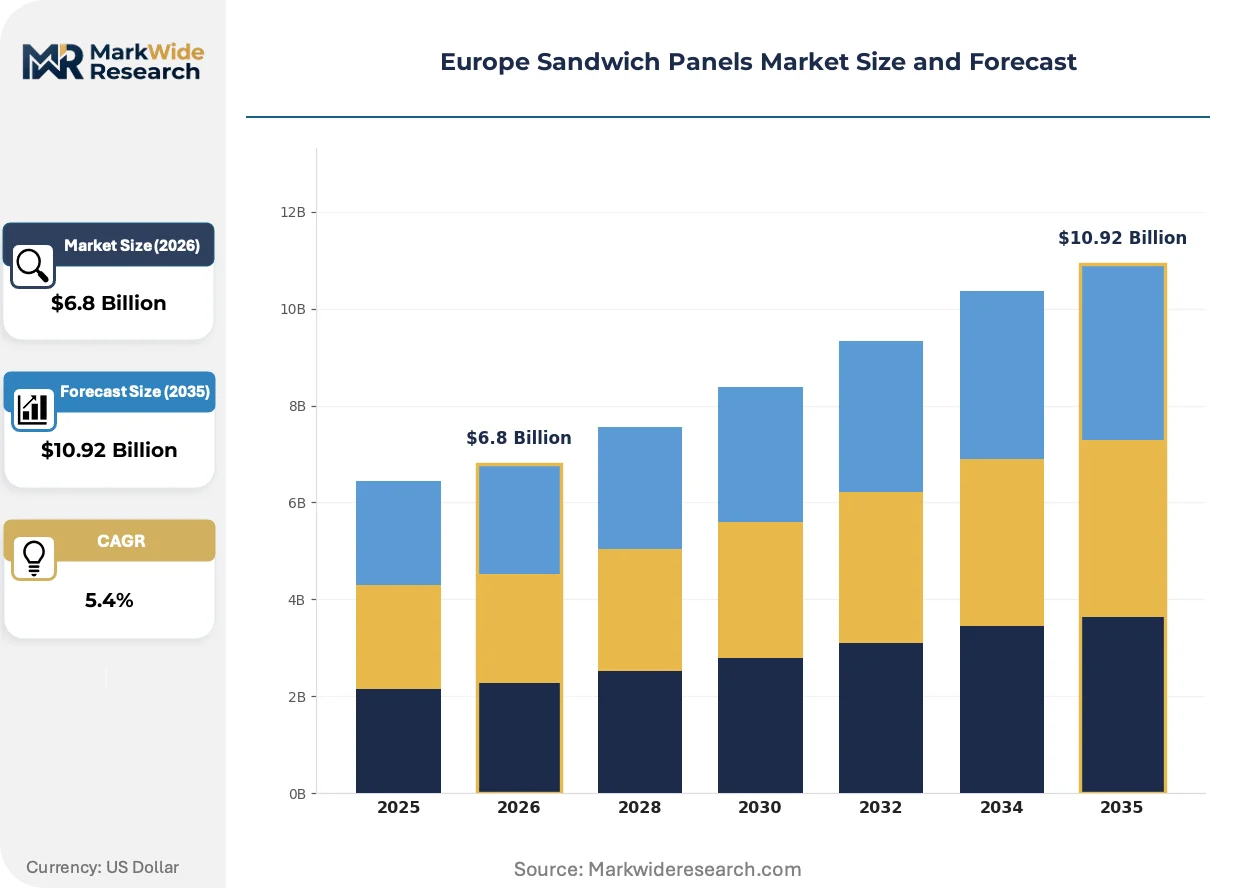
Market Dynamics
Modular prefabrication of complete wall-roof systems is consolidating buyer choice around factory-integrated thermal and fire-performance packages rather than site-assembled components, compressing lead times and reshaping supplier relationships across Northern European construction corridors.
Growth Catalysts
- EU Green Deal renovation targets:The Energy Performance of Buildings Directive mandates deep energy retrofits across existing stock, accelerating specification of high-performance insulated envelopes in public and commercial buildings.
- Cold-chain logistics expansion:Warehouse operators in Germany and the Netherlands are expanding footprints with thermally efficient cladding systems to meet pharmaceutical and food-grade storage requirements.
- Mineral wool core substitution:ECHA restrictions on flame-retardant additives in polystyrene are prompting rapid reformulation toward pentane-blown polyurethane and mineral wool alternatives that satisfy Euroclass A2 ratings.
Market Restraints
- Raw material cost volatility:Coated steel facing prices fluctuate with ArcelorMittal's rolling capacity utilization near Benelux hubs, compressing margins for non-integrated fabricators.
- Regulatory fragmentation:France and Germany enforce divergent fire-test protocols that fragment certification requirements, forcing cross-border suppliers to maintain multiple compliance dossiers.
- Technical substitution risk:Cross-laminated timber and structural insulated panels compete for low-rise commercial envelopes where aesthetic flexibility outweighs thermal performance priorities.
Strategic Opportunities
- Poland's industrial corridors:Rapidly manufacturingizing regions favor modular wall and roof assemblies for new production facilities, creating first-mover advantage for panel suppliers with local fabrication.
- Acoustic specialization:Transport infrastructure and industrial facilities near residential zones in the Netherlands generate premium demand for mineral wool cored panels where sound attenuation exceeds thermal priority.
- CSRD-aligned carbon disclosure:Corporate Sustainability Reporting Directive requirements are elevating embodied carbon transparency as a procurement criterion, rewarding suppliers with verified Environmental Product Declarations.
Industry Challenges
- Thermal bridge engineering capacity:Cold-chain clients demand validated calculations that exceed standard EN 14509 declarations, constraining project execution for firms without dedicated simulation teams.
- Core material transition capex:Reconfiguring production lines from polystyrene to mineral wool or pentane-blown polyurethane requires substantial equipment investment before capacity commitments crystallize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sandwich Panels Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Insulated, Fire Resistant, Acoustic Panels, Structural Panels End User: Construction, Cold Storage, Industrial, Retail Material: Polyurethane, Polystyrene, Mineral Wool, Steel Application: Walls, Roofs, Ceilings, Partitions |
| Companies Covered | Kingspan Group, Metecno, ArcelorMittal, Tata Steel, Assan Panel, Isopan, Balex Metal, FischerSIPS, Lattonedil, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sandwich Panels Market Trends and Innovations
Factory-integrated performance packages are displacing site-assembled component sourcing across European envelope construction, compressing project timelines and elevating engineering accountability upstream to panel manufacturers.
Biobased polyurethane cores derived from agricultural feedstocks are expanding into warehouse and logistics specifications where end-users prioritize Scope 3 emissions reduction. German cold-storage operators are piloting these materials at scale. This substitution is expanding into premium positioning as carbon accounting tightens under CSRD disclosure requirements.
REACH restrictions on halogenated flame retardants are forcing rapid core-material transitions before 2026 enforcement windows. Reformulation costs concentrate among mid-scale fabricators lacking captive insulation production. Poland and Spain are experiencing the steepest compliance ramps due to legacy polystyrene dependence in their installed production bases.
Buyers are consolidating vendor relationships around single-source envelope responsibility rather than fragmented component procurement. Logistics developers in the Netherlands now specify complete wall-roof systems with guaranteed thermal-bridge performance. This consolidation is most visible in Benelux markets where project delivery speed determines lease commencement timelines.
Europe Sandwich Panels Market Segmentation
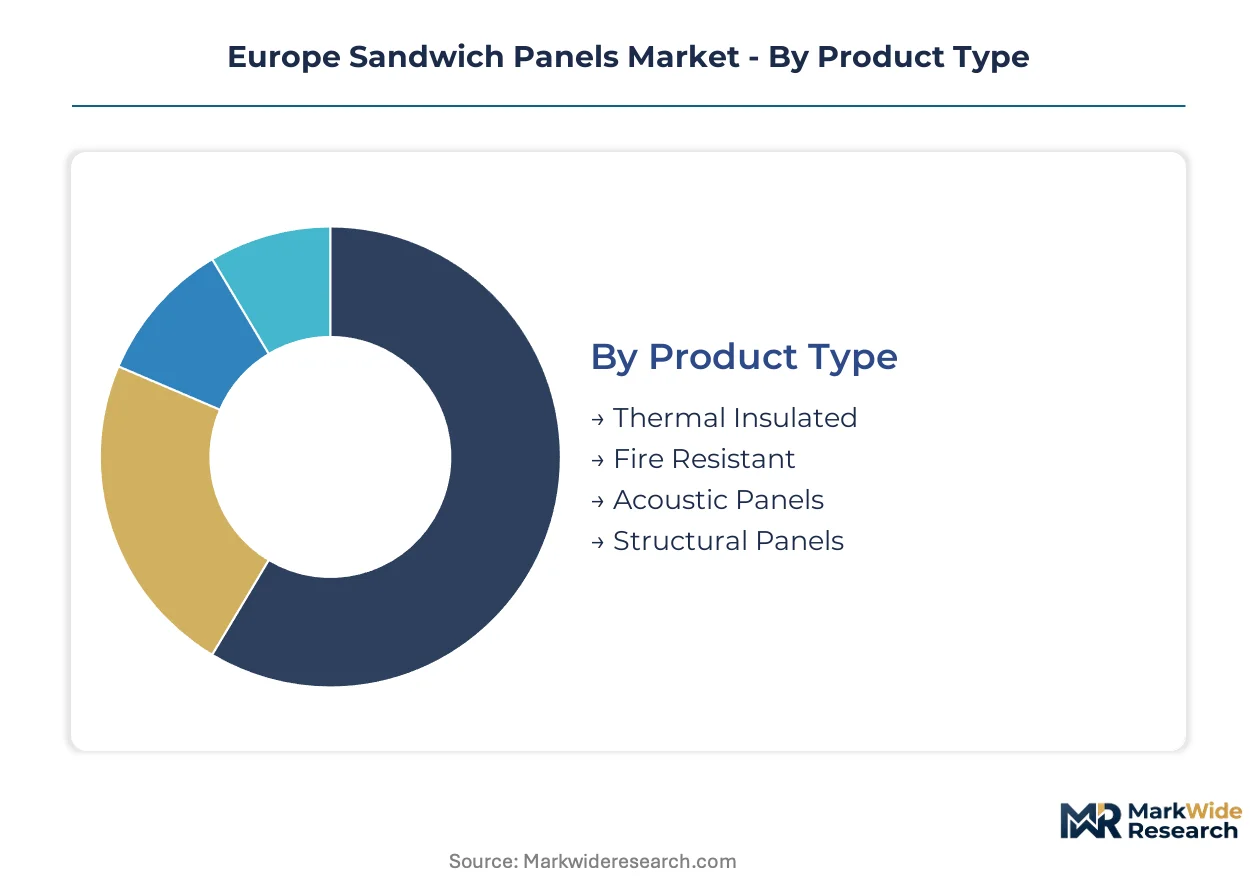
Sandwich panel specification varies sharply across thermal, fire, and acoustic performance tiers, with material core selection determining compliance pathways under divergent national building codes. Understanding segment boundaries reveals where procurement consolidates around integrated envelope systems versus component sourcing.
Product Type:
Thermal insulated panels dominate volume across warehouse construction, while fire-resistant variants capture premium positioning in multi-storey commercial envelopes where Euroclass ratings are mandatory.
- Thermal Insulated:Polyurethane or polystyrene cores bonded between metal facings achieve U-values below 0.20 W/m²K. Demand concentrates in German and Dutch cold-chain logistics facilities where energy-code compliance drives specification of factory-integrated wall-roof systems.
- Fire Resistant:Mineral wool cores deliver Euroclass A2 or B-s1,d0 ratings required in French and German multi-storey commercial buildings. Premium positioning reflects mandatory fire-test protocols that fragment certification requirements for cross-border suppliers.
- Acoustic Panels:Specialized mineral wool cored variants serve transport infrastructure and industrial facilities near residential zones in the Netherlands.
- Structural Panels:Load-bearing configurations support roof spans without secondary steel in Poland's rapidly industrializing manufacturing corridors.
Mature deployment sits with thermal insulated panels across established logistics markets. Newer deployment is concentrated in fire-resistant variants as the EU Green Deal's renovation-wave targets deepen energy retrofits in existing commercial stock.
End User:
Construction sector procurement favors complete envelope systems, while cold storage operators prioritize validated thermal-bridge calculations exceeding standard declarations.
- Construction:General commercial and public building envelopes specify CE-marked panels under EN 14509, with French and German regulators enforcing divergent fire-test protocols that complicate cross-border supply.
- Cold Storage:Pharmaceutical and food-grade warehouse operators in Germany and the Netherlands demand thermally efficient cladding systems with guaranteed thermal-bridge performance to meet stringent storage requirements.
- Industrial:Manufacturing facilities in Poland favor modular wall and roof assemblies for rapid facility commissioning.
- Retail:Big-box and distribution centers specify lightweight factory-manufactured components to compress project timelines and accelerate lease commencement.
Procurement consolidation is most visible in cold storage, where single-source envelope responsibility displaces fragmented component sourcing. Construction maintains more fragmented vendor relationships across public tender processes.
Material:
Core material selection is reshaping around REACH restrictions on halogenated flame retardants, with reformulation costs concentrating among mid-scale fabricators lacking captive insulation production.
- Polyurethane:Pentane-blown formulations satisfy Euroclass B ratings while maintaining thermal performance. German cold-storage operators are piloting biobased variants derived from agricultural feedstocks under tightening CSRD disclosure requirements.
- Polystyrene:Legacy dependence persists in Poland and Spain where installed production bases face steepest compliance ramps ahead of 2026 enforcement windows for ECHA flame-retardant restrictions.
- Mineral Wool:Non-combustible cores preferred where Euroclass A2 ratings are mandatory and sound attenuation exceeds thermal priority.
- Steel:Coated facing supply anchors through dedicated rolling capacity near Benelux construction hubs, with price volatility tracking ArcelorMittal's utilization rates.
Polyurethane cores are climbing the fastest as reformulation accelerates, while polystyrene faces structural decline under regulatory pressure.
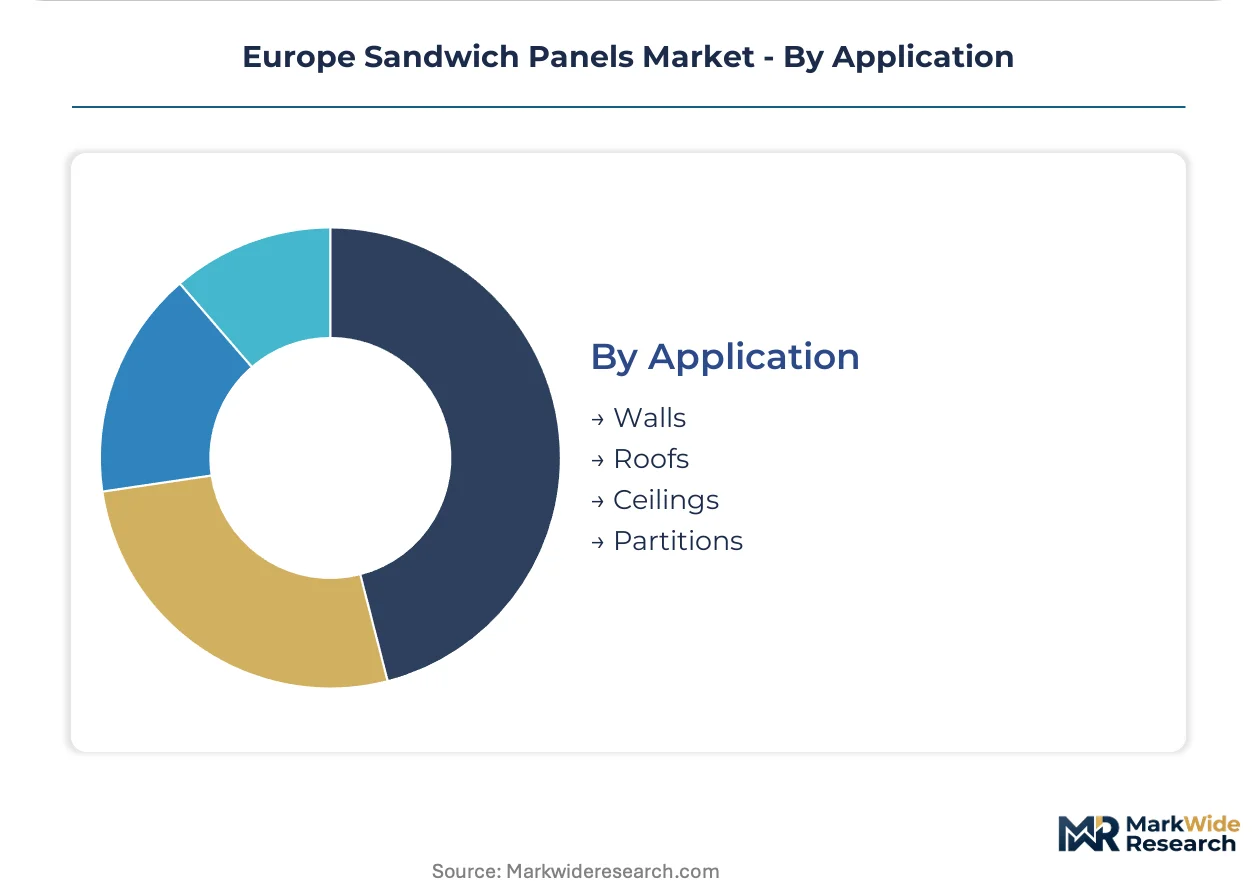
Application:
Wall and roof specifications are consolidating around factory-integrated performance packages, compressing lead times and elevating engineering accountability upstream to panel manufacturers.
- Walls:Vertical envelope applications dominate warehouse and logistics construction across Northern European corridors, with modular prefabrication displacing site-assembled components.
- Roofs:Structural load-bearing configurations support wide spans without purlins in industrial facilities, reducing steel tonnage and accelerating installation.
- Ceilings:Interior applications concentrate in cold-chain facilities where thermal continuity between wall and roof assemblies is critical.
- Partitions:Demountable interior systems serve retail fit-outs requiring rapid reconfiguration.
Wall and roof applications command integrated specification, while ceiling and partition segments remain more fragmented in procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Western European steel-rolling corridors while consumption accelerates faster in Central European industrializing zones. Germany and the Netherlands anchor supply of coated steel facings through integrated rolling mills near port logistics hubs. Poland and Spain absorb expanding volumes as manufacturing investment outpaces local fabrication capacity.
Germany
Pharmaceutical cold-chain operators in Frankfurt-Rhine-Main and Hamburg are commissioning thermally efficient warehouse envelopes with validated thermal-bridge calculations. The national building regulator enforces divergent fire-test protocols that exceed baseline EN 14509 requirements. Bavarian manufacturing clusters near Munich favor structural roof panels that eliminate secondary steel purlins in new production facilities.
Netherlands
Logistics developers in Rotterdam port zones and Amsterdam Schiphol corridors specify complete wall-roof systems to compress lease commencement timelines. The EU Green Deal's renovation-wave targets accelerate deep energy retrofits in existing commercial stock around Randstad cities. Eindhoven's industrial belt generates premium demand for acoustic mineral wool panels where transport infrastructure abuts residential zones.
Poland
Rapidly industrializing manufacturing corridors near Łódź and Wrocław favor modular prefabricated assemblies for rapid facility commissioning. ECHA restrictions on halogenated flame retardants force steepest compliance ramps among legacy polystyrene-dependent fabricators. Silesian steel-processing zones are attracting panel fabrication investment to serve Central European demand growth.
France
Multi-storey commercial developments in Île-de-France mandate Euroclass A2 fire ratings that fragment cross-border supplier certification dossiers. The Energy Performance of Buildings Directive reshapes public procurement criteria for high-performance insulated envelopes in Parisian retrofit projects. Lyon-Auvergne-Rhône-Alpes clusters concentrate fire-resistant panel specification for mixed-use commercial buildings.
Spain
Legacy polystyrene core dependence in Madrid and Barcelona installed bases faces 2026 REACH enforcement windows for flame-retardant additive restrictions. Andalusian logistics operators are expanding cold-storage footprints to serve pharmaceutical distribution networks. Basque Country industrial zones retain specialized acoustic panel demand for manufacturing facilities near dense residential areas.
Europe Sandwich Panels Market Competitive Landscape
The competitive structure tilts toward vertically integrated insulation-core manufacturers who control margin exposure across Northern European project pipelines. Three archetypes dominate: steel-rolling conglomerates with dedicated coated facing capacity, captive-core fabricators with in-house polyurethane or mineral wool production, and project-engineering specialists serving validated thermal-performance requirements. Capacity expansion and backward integration into core-material supply represent the dominant competitive vectors as reformulation costs concentrate among non-integrated mid-scale players.
Among Ireland-based building envelope conglomerates, Kingspan Group occupies a position exemplifying captive-core vertical integration. Italian project-engineering specialists Metecno and Luxembourg-anchored steel giant ArcelorMittal represent contrasting archetypes—one serving cold-chain clients through validated thermal-bridge calculation capabilities, the other anchoring coated steel facing supply through dedicated rolling capacity near Benelux construction hubs. These three entities illustrate how competitive positioning stratifies across core-material control, metallurgical supply security, and specialized engineering services.
| Leading Market Players |
|---|
| Kingspan Group |
| Metecno |
| ArcelorMittal |
| Tata Steel |
| Assan Panel |
| Isopan |
| Balex Metal |
| FischerSIPS |
| Lattonedil |
| Others |
Pricing and Supply Chain Analysis
Hot-rolled coil steel prices at ArcelorMittal's Benelux facilities cascade through coated facing production into three-tier pricing stratification across premium fire-rated, standard thermal, and economy-grade polystyrene-dependent panels. This commodity anchor compresses margins for fabricators lacking captive steel supply or backward integration into core-material production.
Pricing Analysis
Margin tightening in standard thermal panels reflects coated steel facing volatility tracking ArcelorMittal's rolling utilization near Rotterdam and Ghent hubs. Pricing stratifies across Euroclass A2-certified fire-resistant tiers, CE-marked standard thermal grades, and legacy polystyrene economy segments. Cost-down pressure accelerates on non-integrated mid-scale fabricators as REACH reformulation deadlines approach. Cold-chain logistics buyers exhibit lowest price sensitivity due to validated thermal-bridge requirements, while retail distribution centers prioritize procurement speed over unit cost optimization.
Supply Chain Analysis
Inland freight differentials between Silesian steel-processing zones and Polish manufacturing corridors compress landed costs for regional fabricators serving Central European demand. Supply concentrates in Germany, the Netherlands, and Poland where coated facing mills and panel fabrication align. Raw material flows draw from ArcelorMittal's Benelux rolling capacity, pentane-blown polyurethane feedstock from German chemical producers, and mineral wool from French and Belgian insulation manufacturers. Single-source vulnerability sits with halogenated flame-retardant additives facing ECHA restriction enforcement. Distribution runs through direct project contracting for large logistics developers and regional distributor networks for smaller construction contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Core-material transition costs and regulatory compliance burdens are forcing consolidation among mid-scale fabricators lacking captive insulation production or metallurgical supply security.
For Market Incumbents: Extend backward integration into pentane-blown polyurethane or mineral wool core production to defend margin position against raw material volatility and REACH reformulation mandates. Secure dedicated coated steel facing offtake from Benelux rolling mills to lock in supply priority as capacity utilization tightens. Target acquisition of distressed polystyrene-dependent fabricators in Poland and Spain to consolidate regional market share ahead of 2026 enforcement windows. For New Entrants and Emerging Players: Digital direct-to-contractor platforms offer route-to-market bypassing established distributor relationships in fragmented retail and light industrial segments. Poland's rapidly industrializing manufacturing corridors present the most penetrable geography where local fabrication capacity lags demand growth. Pursue project-specific engineering partnerships with cold-chain developers requiring validated thermal-bridge calculations as differentiated entry wedge. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale fabricators with installed production lines in Poland and Spain where legacy polystyrene dependence creates forced-seller dynamics under ECHA compliance ramps. Long-term viability centers on captive core-material supply and CSRD-aligned Environmental Product Declaration capabilities. Watch mineral wool core substitution velocity as inflection indicator for premium positioning capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Core-Material Production | Captive polyurethane or mineral wool supply insulates margin from ECHA reformulation cost spikes. |
| Benelux Steel Facing Supply Agreement | Dedicated ArcelorMittal rolling capacity locks in coated facing priority for Northern European project pipelines. |
| CSRD-Aligned Environmental Product Declaration | Verified embodied carbon transparency elevates procurement scoring under Corporate Sustainability Reporting Directive criteria. |
| Acoustic Specialization Capacity Addition | Mineral wool cored panel production serves Netherlands transport infrastructure premium demand near residential zones. |
| Poland Manufacturing Corridor Expansion | Local fabrication footprint captures rapidly industrializing demand in Łódź and Wrocław production clusters. |
Research Methodology
Independent corroboration across plant managers at panel fabrication facilities, procurement leads at German and Dutch cold-chain logistics operators, distribution channel partners serving Benelux construction corridors, and technical R&D directors at insulation-core manufacturers underwrites the qualitative findings. Secondary validation draws from customs and trade data tracking coated steel and core-material flows, SEC filings of publicly traded building envelope conglomerates, Cefic chemical industry reports, and EN 14509 certification registries. Bottom-up project pipeline tracking and top-down construction spend forecasts triangulate volume estimates.
Rate-of-change decomposition across product type segments, end-user verticals, core-material categories, and national regulatory clusters structures the analytical framework. CAGRs derive from fitted trend projections calibrated against historical construction output elasticities and energy-code adoption trajectories. Modeled inputs include EU Green Deal renovation-wave implementation pace, ECHA flame-retardant restriction compliance timelines, and cold-chain logistics capacity expansion announcements across the analysis window.
The model holds under steady regulatory enforcement schedules and commodity price bands; deviation in ECHA restriction timing or coated steel facing supply disruptions would shift core-material substitution velocity and regional competitive positioning. Stakeholders should weight assumptions against their own operating context and supply contract structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Corrugated Polycarbonate Panels Market
Building & Construction Materials
Global Shotcrete/Sprayed Concrete Market
Building & Construction Materials
Roofing Underlayment Market
Building & Construction Materials
Granite Flooring Market
Building & Construction Materials
Construction Sealants Market
Building & Construction Materials
Asia-Pacific Ceramic Sanitary Ware Market
Building & Construction Materials
Saudi Arabia Sanitaryware Market
Building & Construction Materials
Central & South America Iron Casting Market
Building & Construction Materials
Plumbing Components Market
Building & Construction Materials
Steel Roofing Market
Building & Construction Materials
United Kingdom Prefab Wood Buildings Market
Building & Construction Materials
Prefabricated Building System Market
Building & Construction Materials
Egypt Prefab Wood Buildings Market
Building & Construction Materials
Asia-Pacific Oriented Strand Board Market
Building & Construction Materials
Foldable Houses Market
Building & Construction Materials
Manufactured Sand Market