
 Poland Transportation Infrastructure Construction Market | 2026-2036
Poland Transportation Infrastructure Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Transportation Infrastructure Construction Market Analytics
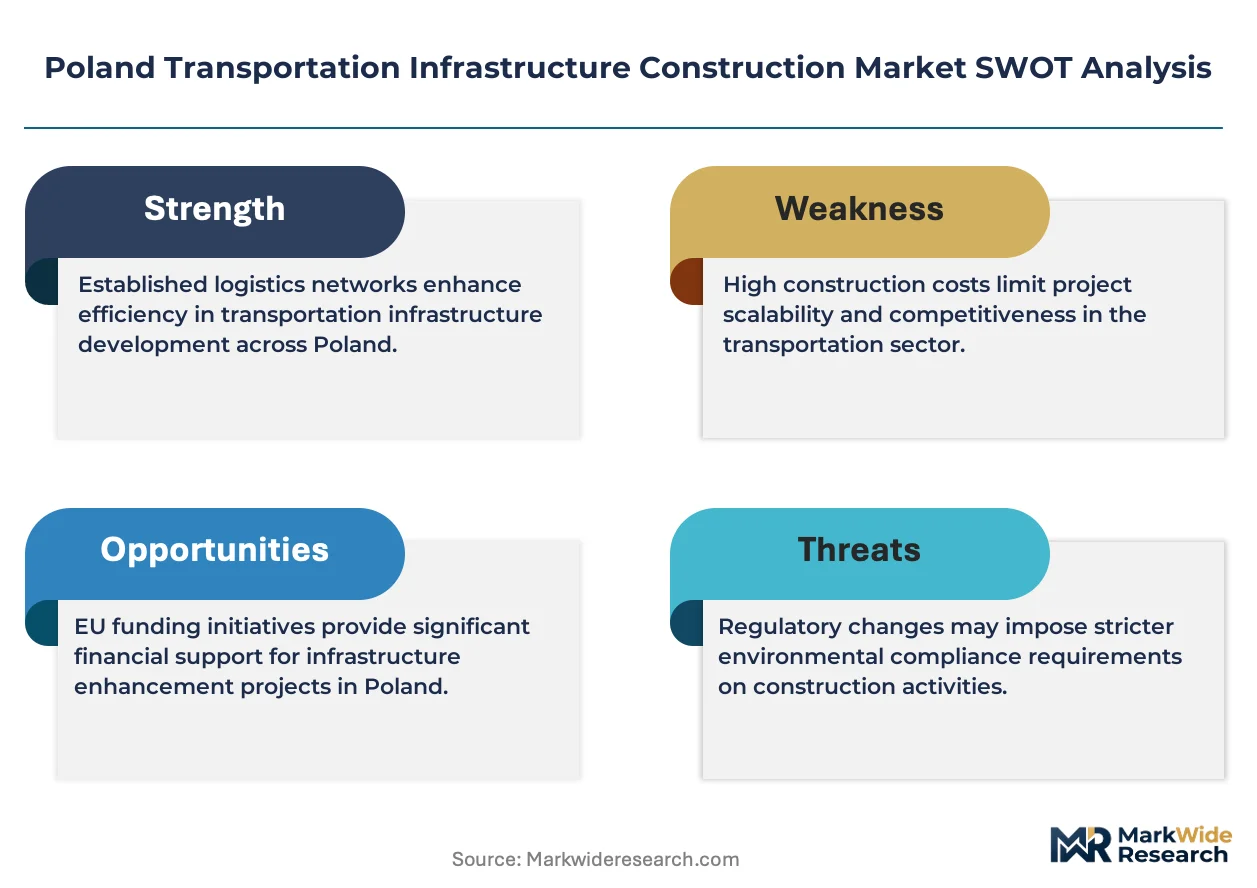
EU TEN-T corridor mandates are pivoting the cost-of-entry calculus for contractors bidding on cross-border rail and highway links. Budimex leverages its vertically integrated concrete and aggregates network to lock in material costs across Silesian and Mazovian project clusters. Strabag sustains competitive tension through Austrian-captive engineering standards that it exports into Polish design-build tenders. Skanska dominates urban rail and bridge segments where Swedish environmental protocols differentiate bid scoring.
Poland transportation infrastructure construction encompasses the civil engineering, earthworks, structural assembly, and systems integration required to build roadways, railways, bridges, and tunnels for public and commercial mobility. Projects typically specify C30/37 to C50/60 concrete grades for bridge superstructures, hot-mix asphalt with polymer modification for motorway surfaces, and EN 1090-certified steel for long-span crossings. Railways and roadways absorb the dominant share of public capex, with rail corridors expanding fastest as EU cohesion funds prioritize intermodal freight and high-speed passenger links. Bridge construction concentrates margin pools in specialty steel and composite segments where technical complexity limits bidder pools, while tunnel work remains nascent outside Tatra bypass studies and urban metro extensions.
Polish construction law, EU EIA Directive transpositions, and BUDIMEX-aligned General Directorate for National Roads and Motorways technical specifications jointly determine contractor eligibility, environmental clearance timelines, and material certification requirements. The Polish National Recovery Plan's green transition conditionalities are tightening embodied-carbon thresholds for asphalt and concrete in public tenders. Stakeholders must monitor how EU fund disbursement rhythms interact with domestic capacity constraints in steel reinforcement and specialized tunneling labor.
Market Dynamics
EU cohesion fund absorption deadlines are compressing project timelines and forcing Polish state agencies to front-load motorway and rail corridor awards before programming windows close.
Growth Catalysts
- EU TEN-T Corridor Mandates:Cross-border rail and highway interoperability standards are mandating uniform gauge electrification and signaling upgrades across Polish trunk routes.
- Łódź-Warsaw-Kraków Freight Triangle:Central Poland's logistics density is generating dedicated bypass and intermodal terminal construction pipelines.
- Lower-Carbon Asphalt Blends:Warm-mix technologies with reclaimed asphalt pavement integration are qualifying projects for green procurement preference scoring.
Market Restraints
- Steel Reinforcement Supply Concentration:Domestic rebar capacity bottlenecks force reliance on Ukrainian and Turkish mill imports subject to tariff volatility.
- Specialized Tunneling Labor Scarcity:Poland trains fewer than forty TBM operators annually, constraining urban metro and mountain bypass feasibility.
- Environmental Impact Assessment Delays:EU EIA Directive transpositions into Polish administrative procedure extend clearance timelines by fourteen to twenty-two months for greenfield corridors.
Strategic Opportunities
- Silesian Brownfield Industrial Conversion:Decommissioned mining infrastructure offers ready-made rights-of-way for freight rail spurs serving battery and EV component plants.
- Performance-Based Maintenance Contracts:Twenty-five-year availability agreements for motorway segments are transferring pavement lifecycle risk from public budgets to contractor balance sheets.
- Digital Twin Integration:BIM-to-asset-management handoffs are creating recurring revenue streams for contractors retaining operational data rights.
Industry Challenges
- EN 1090 Execution Class 4 Certification:Bridge steel fabrication for long-span crossings requires welder qualification records that Polish workshops struggle to document at scale.
- C30/37 to C50/60 Concrete Grade Transition:Higher-performance mix designs demand quality-assured aggregate sources that exceed existing certified quarry reserves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Transportation Infrastructure Construction Market |
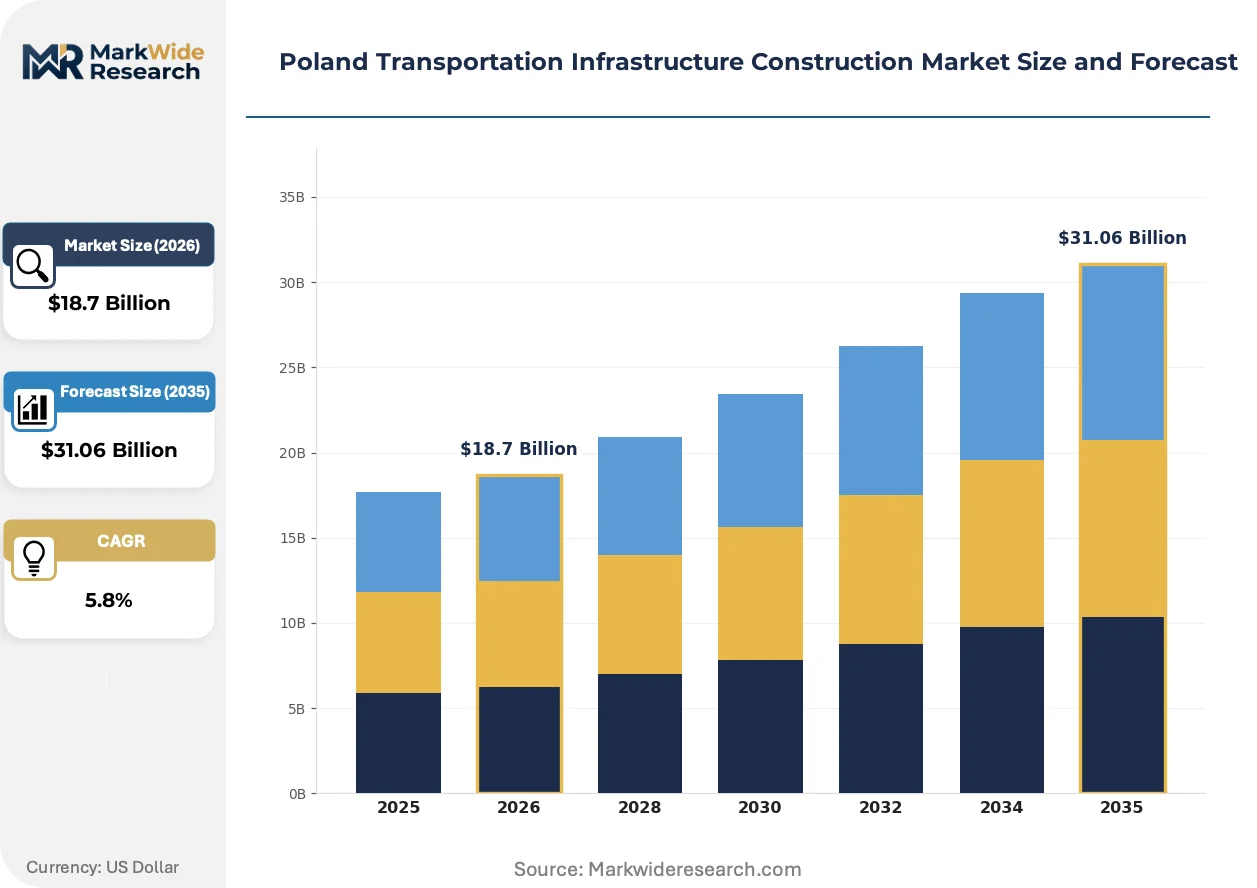
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Roadways, Railways, Bridges, Tunnels Material Type: Concrete, Asphalt, Steel, Composites End User: Public Sector, Private Contractors, NGOs, Investors Construction Method: Conventional, Modular, Design-Build, Green |
| Companies Covered | Budimex, Strabag, Porr, Skanska, Mostostal Warszawa, Torpol, Unibep, Acciona, Hochtief, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Transportation Infrastructure Construction Market Evolving Landscape
Railway electrification and sustainable material specifications are converging to redefine contractor capability requirements and bid evaluation criteria across Polish public procurement.
Catenary-free tram and battery-electric locomotive traction is electrifying depot and last-mile segments where traditional 3kV DC infrastructure proves cost-prohibitive. Regional operators in Lower Silesia and Pomerania are piloting fast-charging systems at terminal stations. This distributed power architecture is compressing the capital intensity gap between light rail and bus rapid transit modes.
Polish transpositions of the EU Green Deal sustainable mobility framework are mandating embodied-carbon declarations for asphalt and concrete in tenders exceeding fifty million złoty. The General Directorate for National Roads and Motorways is embedding these thresholds into technical specifications from 2026. Contractors with verified environmental product declarations are securing bid price advantages of four to seven percent in scoring algorithms.
Public clients are unbundling design-build-maintain contracts into separate design competitions and construction frameworks. The shift fragments risk allocation and exposes contractors to scope-gap disputes during handover. Mazowieckie Voivodeship rail projects exhibit this procurement evolution most visibly, with design contests now preceding contractor prequalification by eight to twelve months.
Poland Transportation Infrastructure Construction Market Segmentation
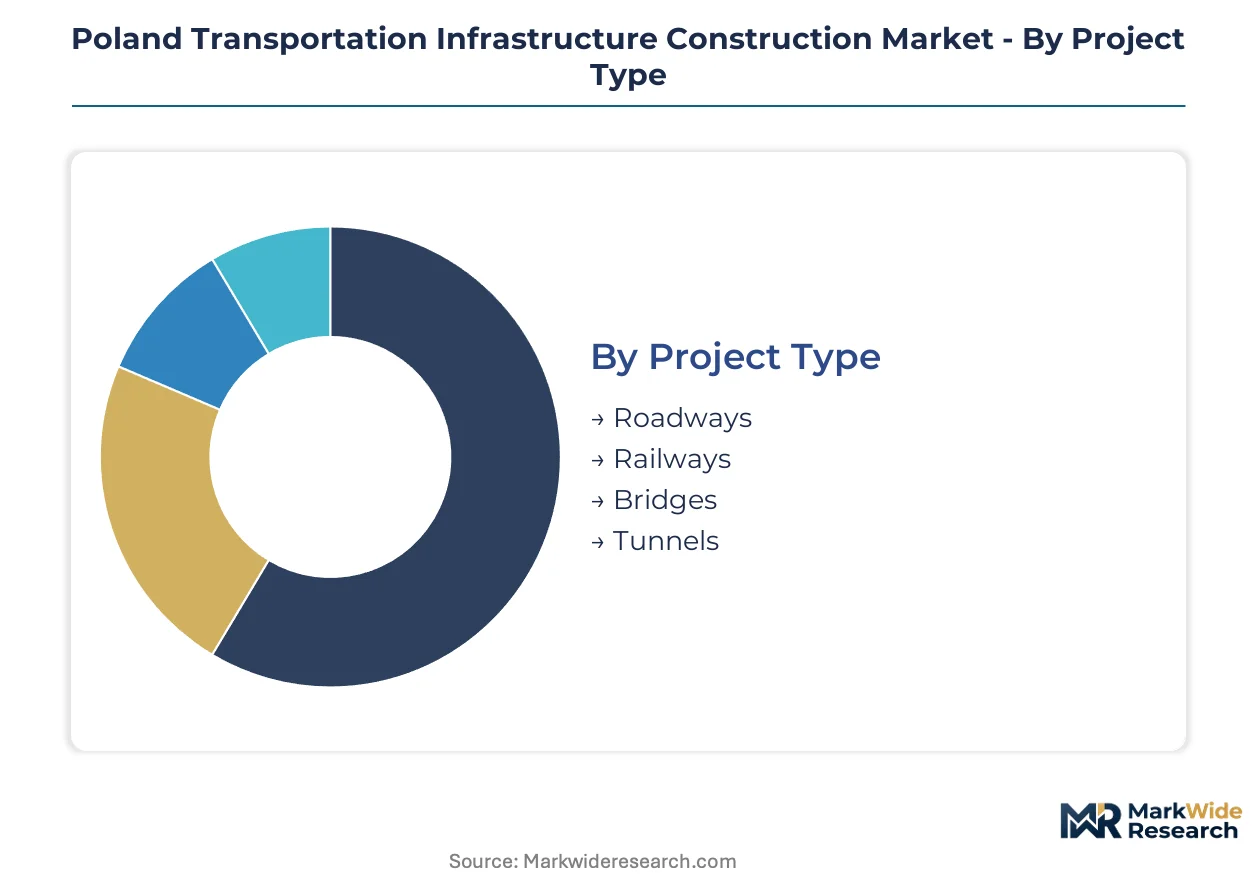
Segmentation in Poland's transportation infrastructure construction reveals how procurement priorities, material specifications, and delivery methodologies shape contractor positioning. Each dimension carries distinct technical requirements and regulatory compliance burdens that determine market access and margin capture.
Project Type:
Public procurement volume and EU fund eligibility criteria drive contractor specialization decisions across project categories.
- Roadways:Motorway and expressway construction specifies hot-mix asphalt with polymer modification for surface courses, absorbing the largest share of General Directorate for National Roads and Motorways capex. Demand clusters in central Poland's Łódź-Warsaw-Kraków corridor where freight density justifies multi-lane expansion.
- Railways:TEN-T corridor mandates require uniform gauge electrification and ETCS signaling upgrades, with intermodal freight terminals generating dedicated construction pipelines. EU cohesion fund deadlines are compressing award timelines for cross-border trunk routes.
- Bridges:Long-span crossings demand EN 1090 Execution Class 4 steel fabrication and C50/60 concrete superstructures, concentrating margin pools where technical complexity limits bidder pools.
- Tunnels:Mountain bypass studies and urban metro extensions remain nascent, constrained by annual training output of fewer than forty TBM operators.
Roadways lead on scale; railways lead on momentum.
Material Type:
Embodied-carbon thresholds in Polish National Recovery Plan tenders are restructuring supplier qualification requirements.
- Concrete:Bridge superstructures specify C30/37 to C50/60 grades demanding quality-assured aggregate sources. Certified quarry reserves in Mazovia and Silesia face exhaustion as higher-performance mix designs proliferate.
- Asphalt:Warm-mix technologies with reclaimed asphalt pavement integration qualify for green procurement preference scoring. General Directorate for National Roads and Motorways embedded these thresholds into technical specifications from 2026.
- Steel:Domestic rebar capacity bottlenecks force reliance on Ukrainian and Turkish mill imports subject to tariff volatility.
- Composites:Fiber-reinforced polymer applications in bridge decks and noise barriers remain specialty segments with limited domestic fabrication capacity.
Concrete dominates current volume; asphalt is climbing the fastest on sustainability-linked procurement.
End User:
Risk allocation preferences and contract tenure length differentiate buyer segments.
- Public Sector:State agencies and voivodeship authorities control motorway, rail, and bridge awards through EU-funded frameworks, unbundling design-build-maintain contracts into separate competitions.
- Private Contractors:Design-build specialists and consortium partners absorb construction risk while pursuing twenty-five-year availability agreements that transfer pavement lifecycle responsibility.
- NGOs:Environmental advocacy groups influence corridor routing through EIA challenge procedures, extending clearance timelines.
- Investors:Pension funds and infrastructure funds deploy capital into operational road and rail assets, rarely originating greenfield construction.
Public sector commands award volume; private contractors capture expanding risk-transfer scope.
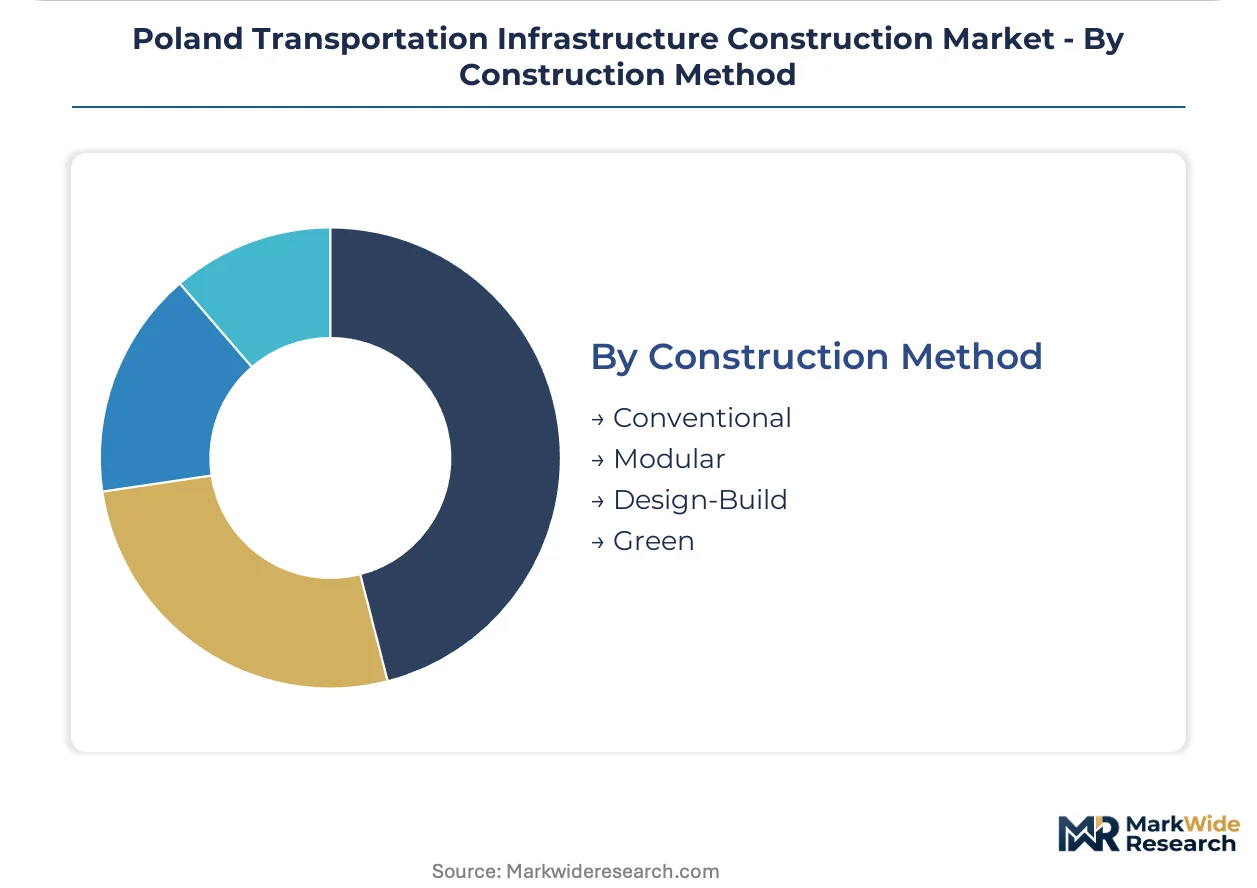
Construction Method:
Procurement evolution is fragmenting traditional design-build integration.
- Conventional:Sequential design-bid-build delivery persists in smaller municipal road contracts where public sector retains full design responsibility.
- Modular:Prefabricated bridge elements and precast concrete segments compress on-site construction duration for constrained urban corridors.
- Design-Build:Single-point responsibility contracts face unbundling pressure as Mazowieckie Voivodeship rail projects separate design contests from contractor prequalification.
- Green:Sustainable construction protocols mandate BIM-to-asset-management handoffs and environmental product declarations for tenders exceeding fifty million złoty.
Design-build holds established share; green methods are gaining share fastest on conditional funding requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polish engineering talent concentrates in the Silesian and Mazovian basins, where technical universities feed specialized construction labor into trunk corridor projects. This workforce distribution shapes regional award patterns and contractor mobilization strategies across the national territory.
Mazowieckie Voivodeship
Warsaw's radial motorway network and urban rail extensions absorb the largest share of General Directorate for National Roads and Motorways capex. The voivodeship unbundles design contests from contractor prequalification, extending procurement timelines by eight to twelve months. The Warsaw-Łódź corridor anchors intermodal freight terminal construction.
Śląskie Voivodeship
Silesian brownfield mining infrastructure offers ready-made rights-of-way for battery supply chain logistics spurs. EU cohesion fund deadlines compress award timelines for cross-border TEN-T links into the Czech Republic. Katowice-Gliwice-Zabrze forms the densest construction labor market outside Warsaw.
Małopolskie Voivodeship
Kraków's ring road completion and Tatra mountain bypass studies drive bridge and tunnel feasibility work. Environmental Impact Assessment procedures extend clearance timelines by fourteen to twenty-two months for greenfield corridors. The Kraków-Łódź freight axis concentrates polymer-modified asphalt demand.
Dolnośląskie Voivodeship
Wrocław's position on the Berlin-Warsaw-Moscow rail corridor mandates ETCS signaling and gauge standardization upgrades. Regional operators pilot catenary-free tram traction with fast-charging terminal infrastructure. The Legnica-Głogów copper belt generates heavy-haul rail rehabilitation contracts.
Pomorskie Voivodeship
Gdańsk-Gdynia port rail connections and Baltic Rail integration absorb maritime-intermodal construction investment. Warm-mix asphalt with reclaimed pavement integration qualifies projects for green procurement preference scoring. The Tricity urban rail extension pipeline competes for specialized tunneling labor with Warsaw metro projects.
Poland Transportation Infrastructure Construction Market Competitive Landscape
The competitive structure tilts toward vertically integrated domestic specialists with captive concrete and aggregates networks. Three archetypes dominate: state-aligned Polish conglomerates with design-build-maintain capabilities, Austrian and Swedish multinationals exporting engineering standards, and mid-tier regional contractors capturing municipal road maintenance. Consolidation pressure operates through twenty-five-year availability agreements that transfer lifecycle risk, while unbundled procurement fragments traditional design-build integration.
Among the integrated domestic tier, Budimex anchors material cost control through Silesian and Mazovian quarry networks. Strabag and Skanska occupy positions as standards-exporting multinationals, with the former representing Austrian-captive engineering protocols and the latter exemplifying Swedish environmental scoring differentiation in urban rail segments. Torpol and Mostostal Warszawa sit within the specialized rail and bridge fabrication tier where EN 1090 certification requirements limit bidder pools.
| Leading Market Players |
|---|
| Budimex |
| Strabag |
| Porr |
| Skanska |
| Mostostal Warszawa |
| Torpol |
| Unibep |
| Acciona |
| Hochtief |
| Others |
Value Network & Pricing Analysis
Captive concrete and aggregates networks anchor both supply security and bid pricing power for vertically integrated contractors across Silesian and Mazovian project clusters. This backward integration into certified quarry reserves insulates material cost volatility while compressing competitor margins on fixed-price motorway tenders.
Pricing Analysis
Bundled design-build-maintain contracts command premium pricing against fragmented design-then-build procurement. Price differentiation rests on EN 1090 Execution Class 4 certification and verified environmental product declarations for green scoring preference. Cost compression in standard roadwork segments intensifies as unbundled procurement exposes contractors to scope-gap disputes. Municipal authorities exhibit highest price sensitivity; long-availability motorway concessionaires absorb lifecycle risk at lower upfront cost tolerance.
Supply Chain Analysis
Direct-to-project quarry networks handle bulk material demand for central Poland's Łódź-Warsaw-Kraków corridor. Raw material sourcing draws from domestic Mazovian and Silesian aggregate basins, Ukrainian and Turkish rebar mills, and specialized German steel fabricators. Tariff exposure on reinforcement steel imports creates margin volatility for bridge contractors. Distribution runs through captive logistics fleets and third-party heavy-haul operators serving GDDKIA-managed sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland's transportation infrastructure construction market functions as a stable compounder underpinned by EU cohesion fund absorption deadlines that compress award pipelines into predictable annual rhythms.
For Market Incumbents: To counter unbundled procurement fragmentation, lock design capability through early-stage engineering partnerships with voivodeship authorities. Deepen captive quarry reserves in Mazovia before certified aggregate exhaustion accelerates. Secure twenty-five-year availability contract templates that transfer pavement lifecycle risk to balance sheets. For New Entrants and Emerging Players: Launch via modular precast bridge element fabrication for constrained urban corridors where on-site duration compression commands bid premiums. Target Silesian brownfield rail spur conversions serving battery supply chain logistics. Pursue fast-track EN 1090 welder qualification partnerships with German technical institutes. For Investors and Strategic Acquirers: Roll-up economics work for specialized rail-electrification contractors because TEN-T corridor standardization mandates create scalable capability replication across Polish trunk routes. Five-to-ten-year viability hinges on EU fund disbursement continuity. Monitor GDDKIA tender unbundling velocity as inflection signal for design-build margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Quarries | Captive aggregate supply locks material cost control for C50/60 concrete grade transitions. |
| EN 1090 Execution Class 4 Certification Investment | Welder qualification documentation opens long-span bridge segments where bidder pools narrow. |
| Warm-Mix Asphalt Technology Adoption | Reclaimed pavement integration qualifies contractors for green procurement preference scoring. |
| Twenty-Five-Year Availability Contract Structuring | Lifecycle risk transfer mechanisms align contractor incentives with GDDKIA pavement durability targets. |
| BIM-to-Asset-Management Data Rights Retention | Digital twin handoffs create recurring revenue streams beyond construction completion. |
Research Methodology
Multiple input streams — primary interviews with GDDKIA procurement officers, EPC contractor project directors, and quarry operations managers; secondary validation against EU cohesion fund disbursement records, Polish National Recovery Plan technical specifications, and TEN-T corridor investment pipelines; plus customs data on steel reinforcement imports — were reconciled through bottom-up project pipeline aggregation and top-down fund allocation verification.
Data-stream reconciliation across the projection horizon applied segment-specific growth drivers: project type differentiation between roadways, railways, bridges and tunnels; material type tiering across concrete grade, asphalt specification and steel certification; end-user risk allocation preferences; and construction method evolution from design-build toward unbundled green procurement. CAGRs were derived from fund absorption deadline modeling and capacity constraint elasticity estimates for specialized tunneling labor and certified aggregate reserves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU fund disbursement delays or Ukrainian steel import disruption. Forecasts reflect assumptions on cohesion fund programming continuity, TBM operator training pipeline expansion, and EIA clearance timeline stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Qatar Transportation Infrastructure Construction Market
Infrastructure Construction
Offshore Pipeline Infrastructure Market
Infrastructure Construction
North America Transportation Infrastructure Construction Market
Infrastructure Construction
US Pipeline Construction Market
Infrastructure Construction
Road & Highway Infrastructure Market
Infrastructure Construction
Composite Railroad Tie Market
Infrastructure Construction
Heavy Movable Bridges Market
Infrastructure Construction
Qatar Infrastructure Sector Market
Infrastructure Construction
New Zealand Infrastructure Market
Infrastructure Construction
APAC Data Center Construction Market
Infrastructure Construction
Mexico Data Center Construction Market
Infrastructure Construction
India Transportation Infrastructure Construction Market
Infrastructure Construction
Thailand Data Center Construction Market
Infrastructure Construction
Sweden Transportation Infrastructure Construction Market
Infrastructure Construction
Philippines Data Center Construction Market
Infrastructure Construction
New Zealand Data Center Construction Market