
 Saudi Arabia Structural Steel Fabrication Market | 2026-2036
Saudi Arabia Structural Steel Fabrication Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Structural Steel Fabrication Market Insights
Buyer concentration among mega-project developers is repositioning procurement leverage toward a handful of state-backed master developers. Zamil Steel leverages its integrated coastal manufacturing footprint to serve Jubail and Yanbu industrial clients. Attieh Steel sustains competitive intensity through specialized plate fabrication for energy sector contractors. Al Rajhi Steel anchors downstream demand via captive rebar and structural sections supply to its affiliated construction network.
Structural steel fabrication encompasses the cutting, welding, drilling, and surface treatment of hot-rolled sections and plates to produce engineered building frames and industrial supports, typically conforming to ASTM A992 or equivalent yield strength specifications of 345-450 MPa. The process transforms raw mill products into connection-ready assemblies for rapid site erection. Beams and columns dominate volume throughput given their ubiquity in commercial building skeletons, while plates command premium margins in oil and gas module fabrication. Infrastructure applications represent the fastest-expanding demand pool as giga-project transport corridors multiply. Welding technology differentiates fabricators capable of delivering complex moment-resisting connections versus commodity bolted-only suppliers.
The Saudi Building Code and SFDA-aligned material certification protocols shape product standards for fire resistance and seismic performance in high-rise construction. MOHAP construction permits and municipal building departments in Riyadh, Jeddah, and Dammam enforce structural steel inspection regimes that filter out non-compliant fabricators. Contractors must monitor how SABIC's hot-rolled coil pricing and the PLI scheme for domestic steel downstreaming reshape fabrication cost structures and local content requirements.
Market Dynamics
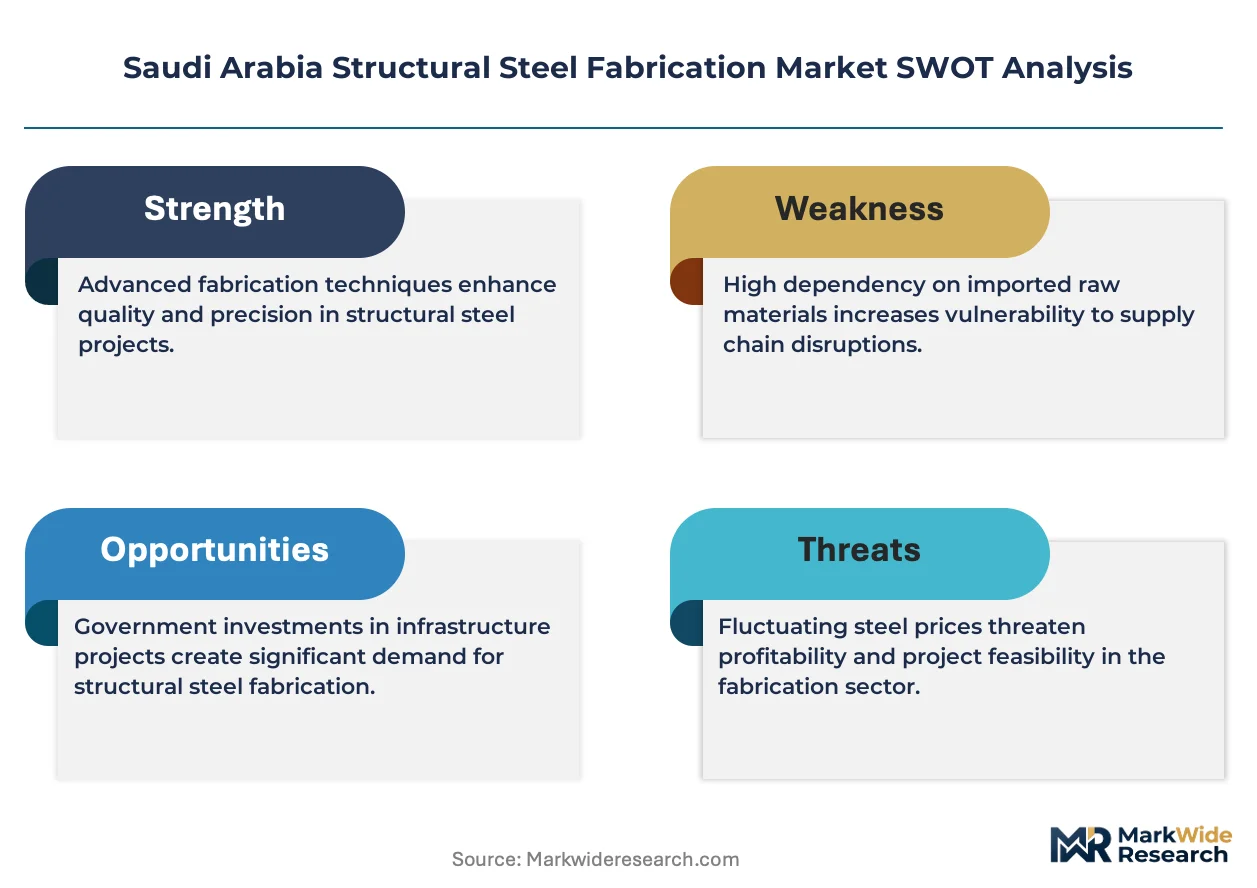
Master developer procurement consolidation at NEOM and the Red Sea Project is compressing supplier margins while demanding certified fabrication capacity that smaller operators cannot scale to meet.
Growth Catalysts
- Saudi Building Code enforcement:Mandatory seismic and fire-resistance standards for high-rise construction in Riyadh and Jeddah are filtering out uncertified fabricators and concentrating contracts with accredited suppliers.
- Giga-project transport corridors:Infrastructure applications across the Kingdom's giga-developments are expanding throughput for heavy-girder fabrication and modular bridge components.
- SABIC domestic capacity expansion:Downstream hot-rolled coil supply integration is shortening lead times for Jubail and Yanbu industrial zone fabricators serving petrochemical clients.
Market Restraints
- Scrap steel price volatility:Input cost swings for electric-arc furnace feedstock are compressing margin predictability for mid-tier fabricators without long-term SABIC supply agreements.
- Coastal manufacturing concentration:Fabrication capacity clusters along the Arabian Gulf, exposing project schedules to Red Sea shipping congestion and port capacity constraints at Jeddah.
- Welding certification bottlenecks:SFDA-aligned material protocols and MOHAP inspection regimes are extending pre-qualification timelines for new market entrants.
Strategic Opportunities
- NEOM modular construction demand:The linear city's factory-built assembly model favors fabricators capable of precision-cut, connection-ready steel packages delivered on just-in-sequence schedules.
- PLI scheme downstreaming incentives:Domestic value-add requirements for government-contracted projects are creating captive demand for locally fabricated structural sections over imported mill products.
- Digital twin integration:Convergence of BIM modeling with automated beam-line cutting is enabling fabricators to bid on complex moment-resisting frame contracts previously reserved to European suppliers.
Industry Challenges
- Certified welder scarcity:Specialized SMAW and FCAW qualifications for seismic-grade connections are in short supply, constraining capacity expansion for fabricators serving Riyadh's commercial tower pipeline.
- MOHAP inspection timeline compression:Municipal building departments in Dammam and Jeddah are extending structural steel approval cycles, delaying site erection and inflating contractor carrying costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Structural Steel Fabrication Market |
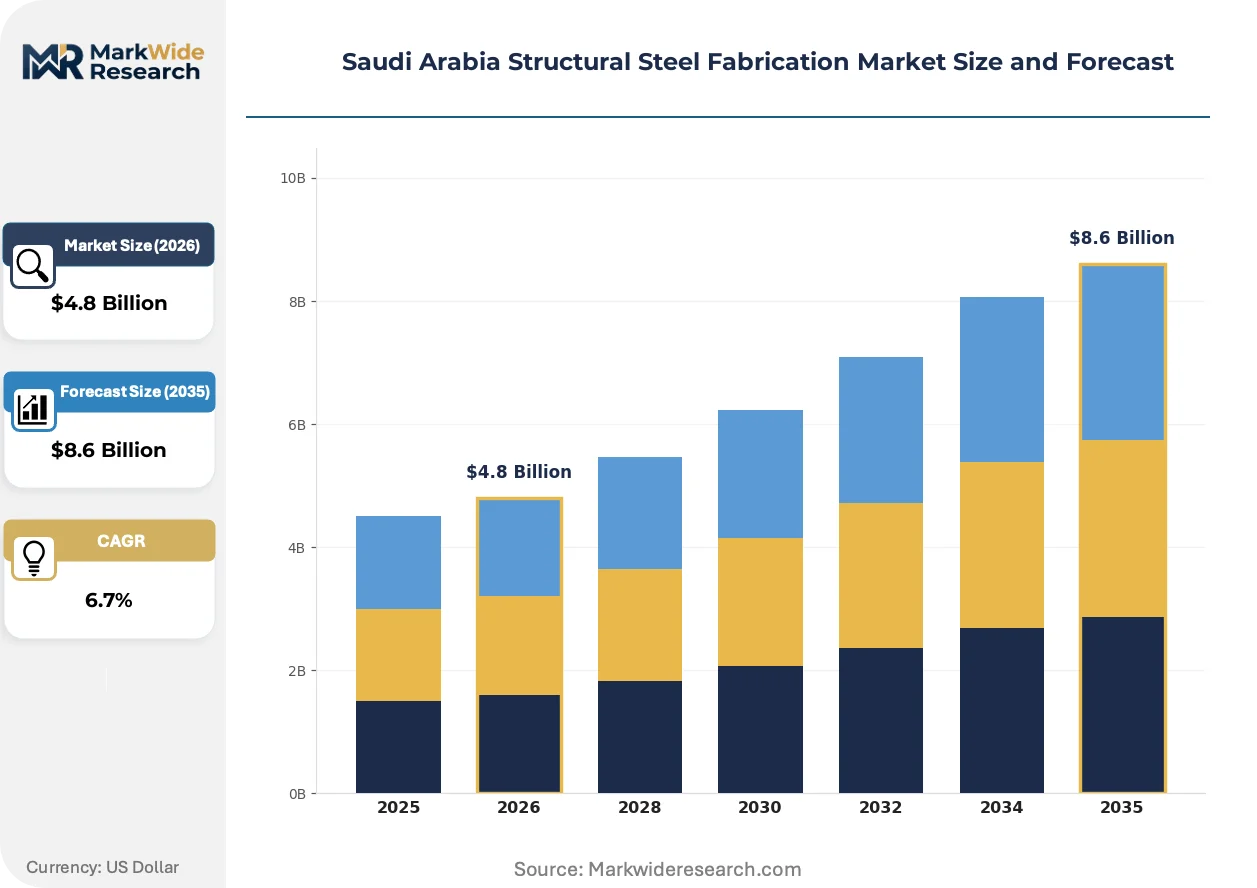
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beams, Columns, Plates, Angles Application: Commercial Buildings, Industrial Structures, Infrastructure, Oil & Gas End User: Contractors, Fabricators, OEMs, Construction Companies Technology: Welding, Cutting, Finishing, Coating |
| Companies Covered | Zamil Steel, Attieh Steel, Gulf Specialized Works Co., Al Rajhi Steel, Arabian International Company for Steel Structures, Alfanar Steel, Age Steel, Absal Steel, Al Shoula Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Structural Steel Fabrication Market Trends and Innovations
Automation in cutting and welding workflows is compressing fabrication cycles while raising quality consistency thresholds that manual operations struggle to match.
Robotic beam-line processing is overtaking manual plasma cutting in high-throughput shops serving the Kingdom's giga-project pipeline. NEOM master developers are specifying robotic-fabricated connections for their modular building programs. This technology shift is enabling 24-hour production cycles that manual shops cannot replicate, consolidating contract awards toward capital-intensive operators.
The Saudi Building Code's seismic performance mandates are tightening material traceability requirements for structural steel used in Riyadh high-rises above 20 stories. SFDA-aligned certification protocols now require mill test reports for every heat lot delivered to site. Commercial tower contractors are responding by pre-qualifying only fabricators with in-house metallurgical testing capability, excluding smaller job shops from premium segments.
Direct sourcing from fabricators is displacing traditional distributor intermediaries for Jubail industrial zone expansions. Petrochemical EPC contractors are establishing frame agreements with certified shops for repetitive structural packages. This channel compression is most visible in Yanbu's refinery upgrade programs, where project owners now contract fabrication capacity 18-24 months ahead of site mobilization rather than spot-buying through steel traders.
Saudi Arabia Structural Steel Fabrication Market Segmentation
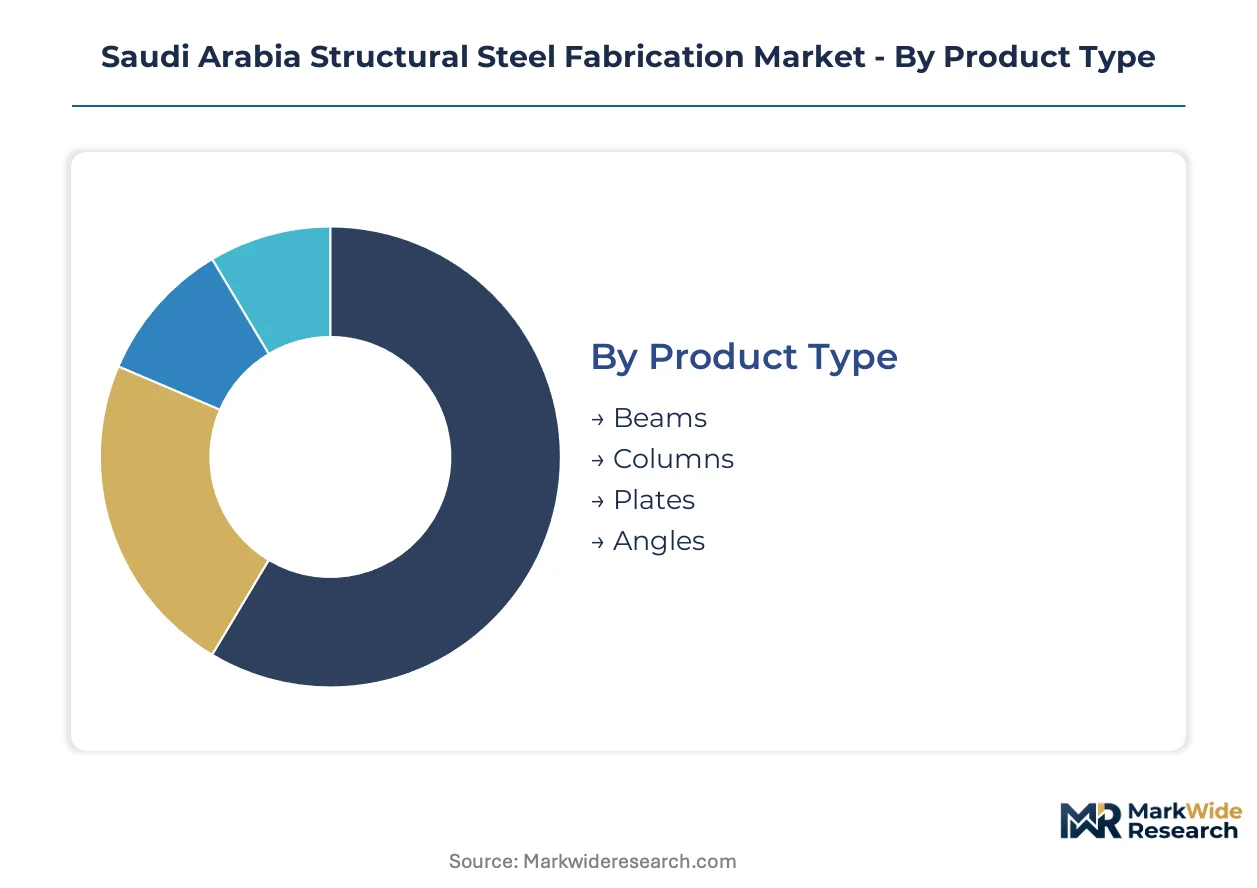
Structural steel fabrication in Saudi Arabia fragments across product geometries, end-use intensity, and processing sophistication. Understanding these divides reveals where certified capacity concentrates and where margin premiums accrue.
Product Type:
Standalone structural members dominate procurement volumes, while integrated plate-and-section assemblies command premium positioning in industrial modules.
- Beams:Hot-rolled I-sections and wide-flange profiles conforming to ASTM A992 specifications form the skeletal framework for commercial towers. Riyadh's high-rise pipeline consumes the bulk of fabricated beam tonnage, with NEOM modular programs specifying pre-drilled, connection-ready packages.
- Plates:Heavy-gauge carbon steel sheets undergo plasma cutting and edge preparation for oil and gas module fabrication. Jubail and Yanbu petrochemical EPC contractors source flame-cut plate assemblies under 18-24 month frame agreements, bypassing traditional steel traders.
- Columns:Box and H-section vertical supports anchor building gravity and lateral load systems. Demand clusters in Dammam municipal building permits requiring seismic-grade moment-resisting connections.
- Angles:L-shaped sections serve bracing and secondary framing applications with lower certification thresholds. Smaller job shops compete here without SFDA-aligned metallurgical testing capability.
Volume placements concentrate in Beams; the faster expansion belongs to Plates.
Application:
Cost tier separation runs from commodity building frames through precision-engineered energy infrastructure, with infrastructure corridors carving out distinct procurement channels.
- Infrastructure:Bridge girders, transport corridor supports, and utility structures across giga-developments multiply heavy-girder demand. NEOM linear city transport spines and Red Sea Project access roads specify weathering-grade fabrication with 100-year design life.
- Oil & Gas:Offshore platforms, refinery structures, and petrochemical module skids require sour-service material grades and full traceability documentation. SABIC's Jubail hot-rolled coil supply integration shortens lead times for Yanbu fabricators serving Saudi Aramco contractors.
- Commercial Buildings:Office towers, retail complexes, and hospitality structures in Riyadh and Jeddah drive standardized beam-and-column packages. Saudi Building Code seismic mandates filter contracts toward accredited shops with in-house welding certification.
- Industrial Structures:Manufacturing facilities, warehouses, and logistics centers in Dammam's industrial zones absorb medium-gauge framing with lower connection complexity.
Commercial Buildings anchor present volume; Infrastructure claims the steepest expansion trajectory.
End User:
Customer type determines procurement leverage, with master developer direct sourcing displacing traditional distributor intermediaries for large-scale programs.
- Contractors:Commercial tower and infrastructure general contractors specify fabricated steel packages in lump-sum bids, carrying MOHAP inspection timeline risk. Riyadh-based contractors pre-qualify fabricators 12-18 months ahead of mobilization.
- Construction Companies:Affiliated builders like Al Rajhi Steel's captive network source structural sections from integrated group supply, compressing procurement cycles for repetitive building typologies.
- Fabricators:Tier-2 shops purchase raw sections for re-processing into specialized assemblies, concentrating in Yanbu's marine fabrication cluster.
- OEMs:Original equipment manufacturers for material handling and process systems embed fabricated frames into packaged plant deliveries, requiring ISO 3834 welding quality certification.
Contractors command the dominant share; Construction Companies are gaining procurement velocity through vertical integration.
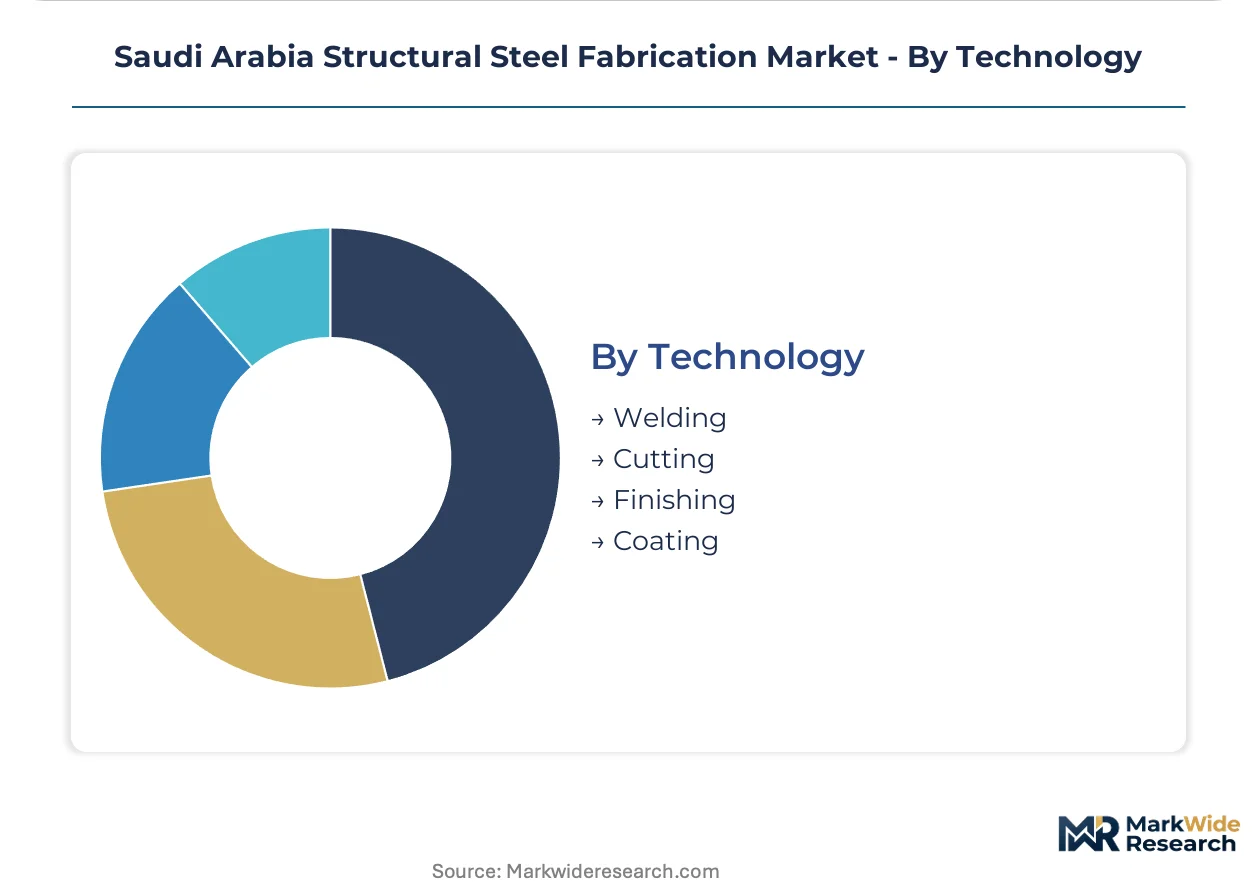
Technology:
Process maturity separates capital-intensive automated workflows from manual operations, with coating and finishing emerging as margin differentiation layers.
- Welding:SMAW, FCAW, and robotic MIG processes produce moment-resisting connections for seismic-grade structures. Certified welder scarcity constrains Riyadh fabricators expanding into high-rise commercial segments.
- Cutting:CNC beam-line processing and plasma systems enable 24-hour production cycles that manual shops cannot match. NEOM modular programs specify robotic-fabricated connections exclusively.
- Coating:Hot-dip galvanizing and intumescent fireproofing applications add value beyond raw fabrication, with Saudi Building Code fire-resistance mandates driving specification.
- Finishing:Surface preparation, hole drilling, and connection detailing complete fabrication-to-erection handoff. Just-in-sequence delivery requirements from NEOM developers compress finishing turnaround windows.
Cutting absorbs the greatest capital deployment; Coating delivers the widest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SABIC's Jubail hot-rolled coil supply anchors fabrication capacity along the Arabian Gulf coast. Master developer procurement at NEOM and the Red Sea Project is redistributing demand toward northwestern clusters.
Riyadh
The capital's commercial tower pipeline consumes fabricated beam-and-column packages for high-rise construction. Saudi Building Code seismic mandates enforced by municipal building departments filter contracts toward accredited shops with in-house welding certification. Riyadh-based contractors pre-qualify fabricators 12-18 months ahead of mobilization.
Eastern Province
Jubail and Yanbu industrial zones drive heavy-gauge plate fabrication for petrochemical EPC contractors. SABIC's domestic hot-rolled coil capacity expansion shortens lead times for fabricators serving Saudi Aramco contractors. Direct sourcing agreements now span 18-24 months, displacing spot purchases through steel traders.
Western Region
Jeddah's port infrastructure exposes fabrication schedules to Red Sea shipping congestion and capacity constraints. MOHAP inspection regimes at municipal building departments extend structural steel approval cycles, delaying site erection. Coastal manufacturing concentration here creates vulnerability to maritime logistics bottlenecks.
NEOM Northwest
The linear city's factory-built assembly model favors precision-cut, connection-ready steel packages delivered on just-in-sequence schedules. Robotic-fabricated connections are specified exclusively for modular building programs. This technology shift consolidates contract awards toward capital-intensive operators capable of 24-hour production cycles.
Saudi Arabia Structural Steel Fabrication Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized plate fabrication and modular construction capabilities. The market exhibits tiered concentration around integrated coastal manufacturers, mid-scale regional specialists, and captive construction-affiliated networks. Three archetypes dominate: Gulf-based integrated fabricators with SABIC supply agreements, Riyadh-focused commercial tower specialists, and industrial zone plate fabricators serving petrochemical clients. Capacity expansion and welding certification acquisition represent the dominant competitive moves.
Among Saudi-based fabricators, Zamil Steel, Attieh Steel, and Al Rajhi Steel occupy distinct positioning within this structure. Zamil Steel exemplifies the integrated coastal archetype with its manufacturing footprint aligned to Jubail and Yanbu industrial demand. Attieh Steel represents specialized plate fabrication capability serving energy sector contractors. Al Rajhi Steel anchors downstream demand through captive supply to its affiliated construction network, compressing procurement cycles for repetitive building typologies.
| Leading Market Players |
|---|
| Zamil Steel |
| Attieh Steel |
| Gulf Specialized Works Co. |
| Al Rajhi Steel |
| Arabian International Company for Steel Structures |
| Alfanar Steel |
| Age Steel |
| Absal Steel |
| Al Shoula Group |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed master developers at NEOM and the Red Sea Project concentrate procurement leverage, compressing supplier margins while enforcing certified fabrication standards that reshape pricing discipline across tiered supplier categories.
Pricing Analysis
High-volume beam-and-column packages for Riyadh commercial towers trade on thin margins, while precision-engineered plate assemblies for Jubail petrochemical modules capture premium returns. Three-tier pricing structure across premium seismic-grade, standard commercial, and economy industrial levels separates fabricators by welding certification and metallurgical testing capability. Cost compression in commodity segments is intensifying because SABIC's domestic hot-rolled coil supply shortens lead times and eliminates import premiums for integrated coastal manufacturers. Mid-tier fabricators without long-term SABIC agreements face the greatest price sensitivity as scrap steel volatility erodes margin predictability.
Supply Chain Analysis
Single-source vulnerability sits with SABIC's Jubail hot-rolled coil capacity as the dominant domestic feedstock for Eastern Province fabricators. Raw material flows draw from Saudi Arabia's domestic steel downstreaming, UAE re-export channels, and Indian plate shipments for specialized sour-service grades. Supply chain risk centers on Red Sea shipping congestion at Jeddah port, which exposes Western Region fabrication schedules to maritime logistics bottlenecks. Distribution runs through direct frame agreements between petrochemical EPC contractors and certified shops, displacing traditional steel trader intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified welder scarcity for seismic-grade SMAW and FCAW qualifications constrains fabrication capacity expansion, propping pricing power for accredited suppliers serving Riyadh's commercial tower pipeline.
For Market Incumbents: Anticipate margin compression from robotic-fabricated competitors by securing SABIC supply agreements and expanding in-house metallurgical testing capability. Defensive moves should prioritize welding certification acquisition for moment-resisting connections and backward integration into hot-rolled coil sourcing through PLI scheme partnerships. For New Entrants and Emerging Players: Capture white-space opportunity in NEOM modular construction by developing just-in-sequence delivery capability and robotic beam-line processing. The most penetrable segment lies in precision-cut connection-ready packages for linear city transport corridors, with entry via technology licensing from European automation specialists. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale regional specialists with SFDA-aligned certification and established MOHAP inspection relationships in Dammam and Jeddah. Long-term viability over the coming decade hinges on digital twin integration and BIM convergence capabilities. The signal to watch is master developer procurement consolidation accelerating toward direct sourcing models.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Fabrication Deployment | NEOM modular programs specify robotic-fabricated connections exclusively, consolidating contract awards. |
| Welding Certification Investment | SFDA-aligned SMAW and FCAW qualifications unlock seismic-grade commercial tower contracts in Riyadh. |
| Backward Integration into Coil Supply | SABIC long-term agreements shorten lead times and eliminate import premium exposure for Jubail fabricators. |
| Digital Twin Integration | BIM convergence enables bidding on complex moment-resisting frames previously reserved to European suppliers. |
| Direct Frame Agreement Expansion | Petrochemical EPC contractors now contract fabrication capacity 18-24 months ahead, bypassing steel traders. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with fabrication plant managers, petrochemical EPC procurement leads, MOHAP inspection officials, and master developer supply chain directors. Bottom-up volume modeling triangulated against SABIC production disclosures and Saudi Building Code enforcement timelines, cross-referenced with top-down market sizing from construction permit databases and giga-project procurement announcements.
Segment-level granularity modeled product type, application intensity, and technology sophistication across the projection horizon, with regional splits calibrated to municipal building permit flows in Riyadh, Dammam, and Jeddah. CAGRs derived from trend extrapolation of master developer procurement consolidation and PLI scheme downstreaming incentives, incorporating SABIC capacity expansion trajectories and welding certification pipeline constraints as industry-specific forecast inputs.
The model holds under sustained giga-project execution and Saudi Building Code enforcement continuity; deviation in scrap steel price volatility or Red Sea shipping disruption would shift fabrication cost structures and regional capacity utilization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Construction
Prefabricated Steel Bridge Market
Structural Construction
Self-Consolidating Concrete (SCC) Market
Structural Construction
Global Rebar Splice Market
Structural Construction
GCC Prefabricated Building and Structural Steel Market
Structural Construction
H Beam Market
Structural Construction
Sandwich Plate System Market
Structural Construction
China Structural Steel Fabrication Market
Structural Construction
South Korea Construction Market
Structural Construction
United Arab Emirates Structural Steel Fabrication Market
Structural Construction
Ceiling Expansion Joint Market
Structural Construction
Timber Frame Construction Market
Structural Construction
Elastomeric Bearings Market
Structural Construction
Bridge Bearings Market
Structural Construction
Saudi Arabia Roofing Market
Structural Construction
Girder Market
Structural Construction
Steel Beam Market