
 Solar Cooling Market | 2026-2036
Solar Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Cooling Market Analytics
Middle Eastern engineering consortiums is decoupling solar cooling project development from conventional HVAC procurement models. Synhelion leverages concentrated solar thermal expertise to anchor high-temperature process cooling contracts in arid climates. SOLHO BV competes through modular off-grid refrigeration units designed for agricultural cold chains. Icarus RT, Inc. differentiates by hybridizing photovoltaic arrays with thermal collection for dual-output commercial installations.
Solar cooling encompasses thermally driven refrigeration and air-conditioning systems that use solar collectors to power absorption, adsorption, or desiccant cycles, typically operating with lithium bromide-water or silica gel-water working pairs at generator temperatures of 75°C to 200°C. Flat-plate collectors dominate residential and small-commercial deployments due to lower capital thresholds, while evacuated tube collectors capture premium margins in industrial process cooling where higher operating temperatures improve coefficient of performance. Absorption chillers occupy the largest installed base among product types, though hybrid systems integrating photovoltaic-driven heat pumps are gaining traction in institutional buildings seeking dispatchable cooling independent of thermal storage sizing.
EPA SNAP program restrictions on high-GWP refrigerants and the EU F-Gas Regulation are reshaping product standards by disqualifying conventional vapor-compression equipment from public procurement in multiple jurisdictions. Saudi Arabia's national regulator and the UAE's MOHAP-aligned building codes are mandating renewable thermal fractions in new district cooling capacity, directly expanding addressable market boundaries. Stakeholders must monitor how refrigerant phase-down schedules synchronize with solar thermal collector certification timelines to avoid stranded equipment configurations.
Market Dynamics
Refrigerant phase-down mandates are compressing the competitive set for conventional vapor-compression equipment, redirecting capital toward thermally driven cooling architectures that bypass synthetic working fluids entirely.
Growth Catalysts
- EU F-Gas Regulation:The synthetic refrigerant phase-down disqualifies high-GWP equipment from public procurement in Germany, France, and Italy, forcing district cooling authorities to specify absorption chiller compatibility.
- Hot-arid building stock:Commercial operators in Saudi Arabia and the UAE face cooling-degree-day loads exceeding 4,000 annually, making solar thermal yield predictability a decisive procurement factor.
- Lithium bromide-water pairs:These working fluids operate at generator temperatures achievable with flat-plate and evacuated tube collectors, eliminating the need for concentrating solar thermal in sub-megawatt installations.
Market Restraints
- Copper and lithium volatility:Absorption chiller heat exchangers and battery-backed photovoltaic hybrids face input cost swings that erode project IRRs during the construction window.
- Chinese collector manufacturing concentration:Evacuated tube supply chains cluster in Shandong and Jiangsu provinces, exposing EPCs to single-point logistics failures and tariff uncertainty.
- Thermal storage sizing:Absorption systems require double-effect chillers or substantial hot water storage to match the dispatchability of electric compression, adding footprint and civil works costs.
Strategic Opportunities
- Agricultural cold chains:Modular off-grid refrigeration units address post-harvest losses in India's horticulture belt, where grid reliability undermines conventional mechanical cooling.
- Hybrid photovoltaic-thermal convergence:Dual-output collectors simultaneously generate electricity and 75-90°C process heat, enabling institutional buyers to consolidate rooftop infrastructure.
- Saudi renewable thermal mandates:The national regulator's renewable fraction requirements for new district cooling capacity create guaranteed offtake for solar thermal field developers.
Industry Challenges
- Absorption chiller technician scarcity:The workforce pipeline for lithium bromide system maintenance lags behind vapor-compression certification programs, extending commissioning timelines.
- ISO 9806 collector certification lag:Test laboratory bottlenecks delay market entry for novel evacuated tube designs, misaligning product availability with refrigerant phase-down deadlines.
- Legacy building envelope retrofits:Existing commercial stock in hot-arid zones requires simultaneous insulation upgrades to right-size solar cooling capacity, complicating single-system procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Cooling Market |
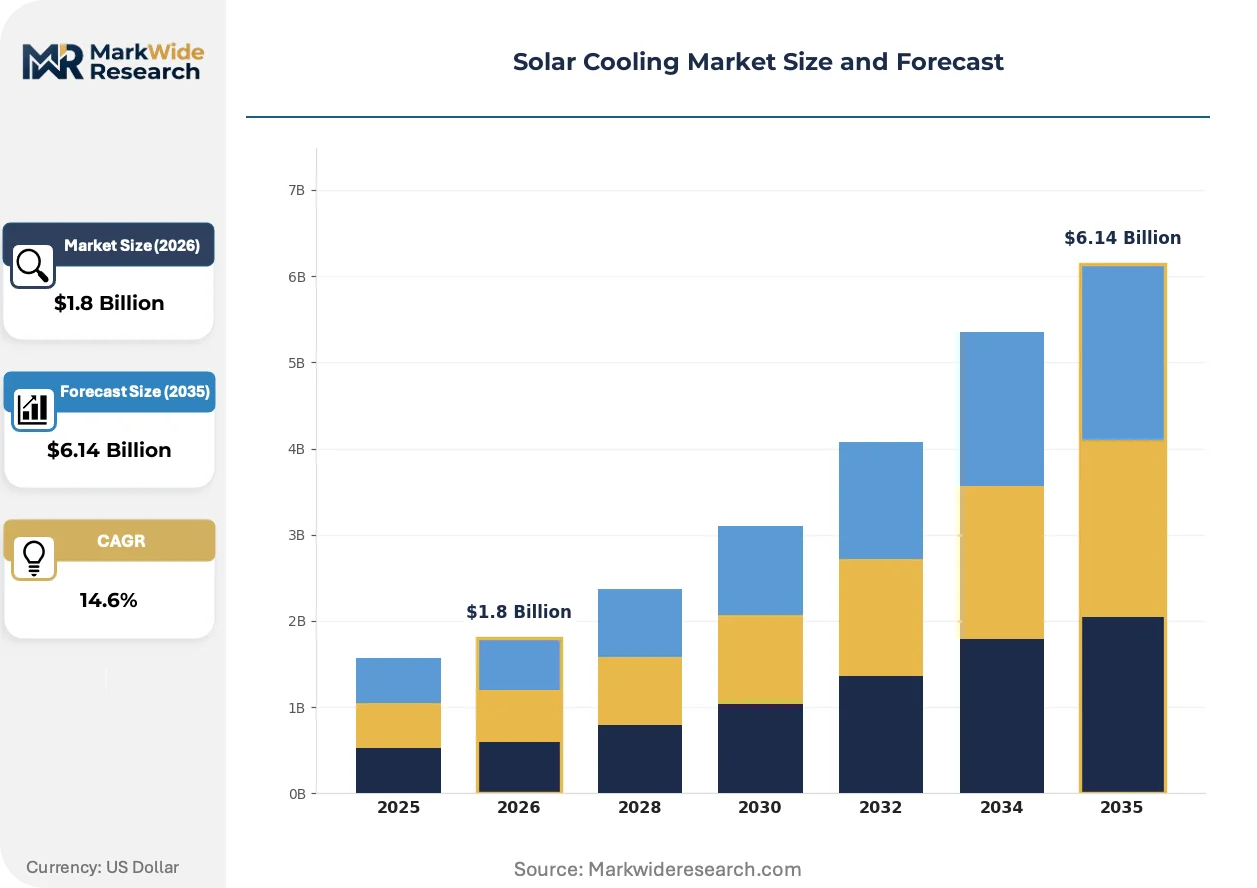
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Thermal, Absorption Chillers, Desiccant Cooling, Hybrid Systems Technology: Flat-Plate Collectors, Evacuated Tube Collectors, Thermoelectric Cooling, Heat Pumps End User: Residential, Commercial, Industrial, Institutional Application: Space Cooling, Process Cooling, Refrigeration, Water Heating |
| Companies Covered | Icarus RT, Inc., Synhelion, Soitec, SunOyster, MGA Thermal, SOLHO BV, GlassPoint, PlexiSun, Heliac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Cooling Market Evolving Landscape
Equipment architectures are converging around dispatchability and refrigerant-free operation, compressing the traditional separation between thermal and electric cooling pathways.
Hybrid photovoltaic-thermal collectors are integrating electricity generation with low-to-medium temperature heat harvesting. Universities and hospital complexes in Spain and Australia are piloting these dual-output systems to maximize rooftop utilization density. The technology is integrating formerly separate procurement categories—solar PV and solar thermal—into unified EPC contracts with single-point performance guarantees.
REACH and the EU F-Gas Regulation are tightening the allowable global warming potential threshold for stationary cooling equipment. Manufacturers serving the European public sector must now certify thermally driven cycles or switch to hydrocarbon refrigerants with flammability constraints. District cooling authorities in Denmark and the Netherlands are responding by mandating absorption chiller compatibility in new build specifications.
Performance contracting is displacing capital purchase models for institutional cooling infrastructure. Saudi universities and UAE healthcare facilities are adopting energy-as-a-service agreements where providers retain ownership of solar thermal fields and absorption equipment. This shift transfers thermal storage sizing risk from building operators to specialized developers with portfolio-scale optimization capabilities.
Solar Cooling Market Segmentation
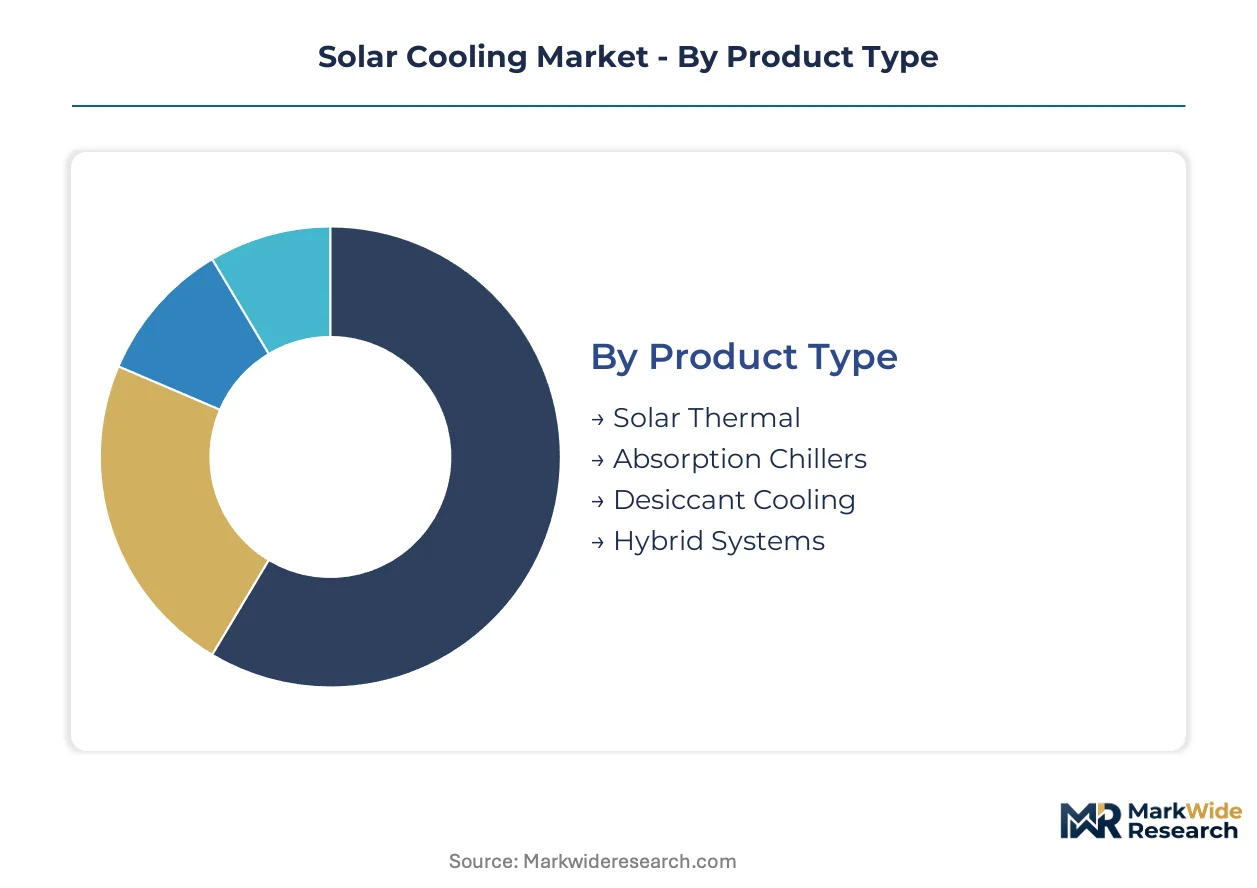
Solar cooling markets fragment across thermal collection architectures and thermodynamic cycles that determine capital intensity, operating temperature ranges, and integration complexity. Procurement patterns diverge sharply between standalone absorption chiller installations and hybrid photovoltaic-thermal systems that consolidate rooftop infrastructure.
Product Type:
Standalone absorption systems dominate utility-scale district cooling contracts, while embedded hybrid configurations penetrate institutional rooftops seeking dispatchable cooling without thermal storage footprints.
- Solar Thermal:Concentrated solar thermal fields generate 150-300°C process heat for double-effect absorption chillers in Saudi Arabian district cooling networks. Saudi Arabia's renewable thermal mandates guarantee offtake for developers constructing parabolic trough installations.
- Absorption Chillers:Lithium bromide-water systems operate at generator temperatures achievable with flat-plate collectors, eliminating refrigerant compliance risks under EU F-Gas Regulation. German and French public procurement specifications now mandate absorption compatibility for projects exceeding 500kW cooling capacity.
- Desiccant Cooling:Silica gel-rotor systems handle latent loads in humid subtropical climates where conventional vapor-compression efficiency collapses.
- Hybrid Systems:Photovoltaic-driven heat pumps with thermal battery backup enable dispatchable cooling independent of solar irradiance timing.
Volume placements concentrate in Absorption Chillers; the faster expansion belongs to Hybrid Systems.
Technology:
Cost tiers separate mature evacuated tube supply chains from emerging thermoelectric alternatives still scaling manufacturing yields.
- Flat-Plate Collectors:Aluminum-copper absorber plates with tempered glass covers dominate residential and small-commercial deployments due to sub-$200/m² installed costs. India's agricultural cold chain subsidies accelerate procurement for modular off-grid refrigeration units.
- Evacuated Tube Collectors:Borosilicate glass vacuum tubes achieve 80-150°C operating temperatures that improve absorption chiller coefficient of performance in industrial process cooling. Chinese manufacturing concentration in Shandong and Jiangsu provinces exposes EPCs to logistics single-point failures.
- Thermoelectric Cooling:Solid-state Peltier modules eliminate moving parts for military and aerospace applications requiring vibration immunity.
- Heat Pumps:Compression-driven cycles with photovoltaic power input bridge thermal and electric cooling pathways for buildings seeking grid independence.
Evacuated Tube Collectors capture the premium pricing tier; Flat-Plate Collectors drive volume penetration in emerging markets.
End User:
Customer type determines performance contracting structures, with institutional buyers adopting energy-as-a-service models while industrial operators retain capital ownership.
- Residential:Single-family installations favor flat-plate collector sizing below 50m² with lithium bromide absorption chillers matched to cooling loads under 20kW. Spanish and Australian subsidy programs target this segment for rooftop density maximization.
- Commercial:Office complexes and retail chains in the UAE face cooling-degree-day loads exceeding 4,000 annually, making solar thermal yield predictability decisive in procurement. Dubai's building codes now require renewable thermal fractions for new commercial permits.
- Industrial:Food processing and pharmaceutical manufacturing demand 24/7 process cooling that forces hybrid system configurations with substantial thermal storage.
- Institutional:Universities and hospital complexes adopt performance contracting where developers retain ownership of solar thermal fields and absorption equipment.
Commercial deployments generate the current revenue base; institutional contracts are climbing the fastest as energy-as-a-service models mature.
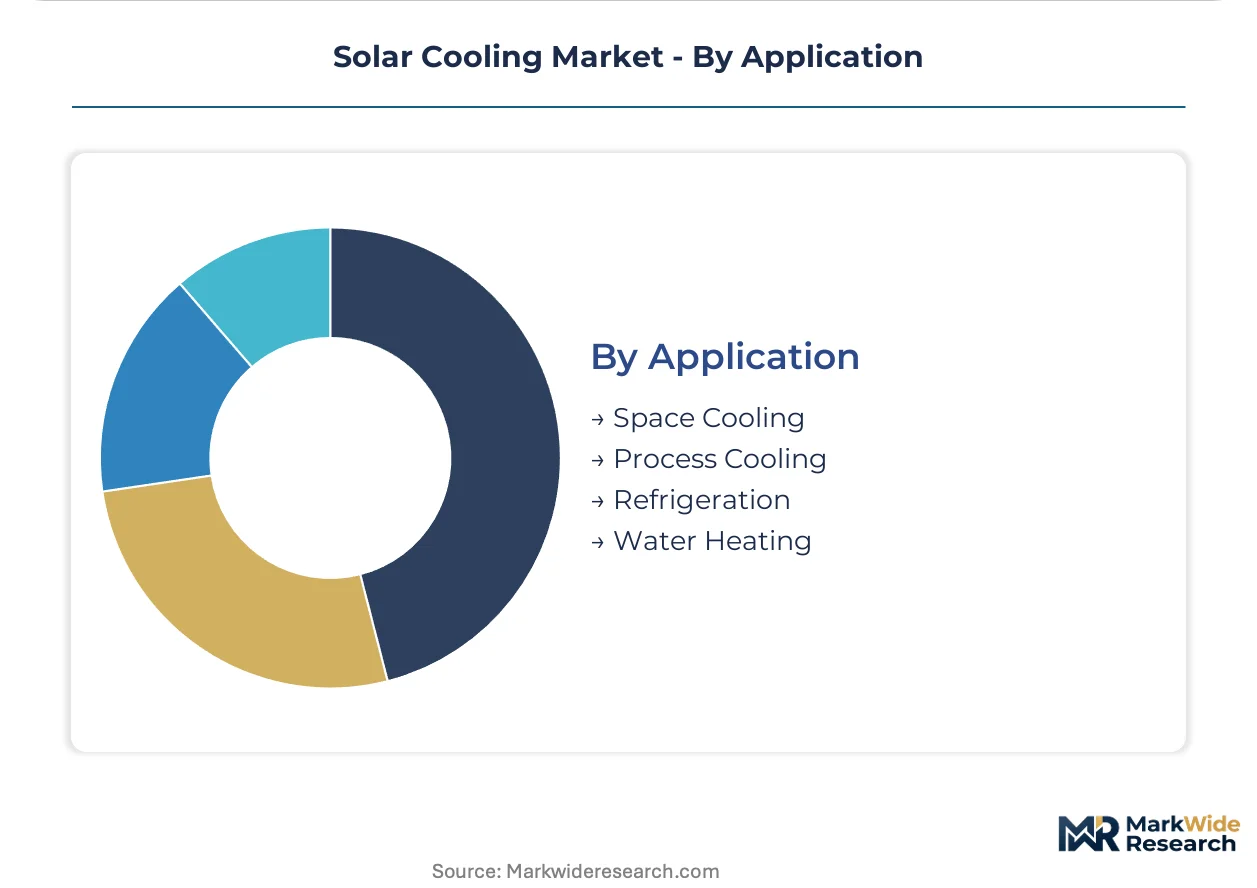
Application:
Application scope spans comfort conditioning through industrial process loads, with refrigeration presenting distinct cold-chain reliability requirements.
- Space Cooling:Air-conditioning loads in hot-arid commercial buildings represent the addressable market anchor, with absorption chillers displacing vapor-compression in Saudi Arabian and UAE district cooling expansions.
- Process Cooling:Manufacturing facilities require 7-12°C chilled water for equipment thermal management, driving evacuated tube collector specifications for higher generator temperatures.
- Refrigeration:Post-harvest cold chains in India's horticulture belt deploy modular off-grid units where grid reliability undermines mechanical compression.
- Water Heating:Combined cooling and heating systems recover absorption chiller waste heat for domestic hot water, improving overall system efficiency in institutional buildings.
Space Cooling dominates current installations; Refrigeration applications are expanding most quickly in agricultural electrification programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium bromide supply chains and evacuated tube manufacturing clusters in Shandong province anchor solar cooling equipment flows into hot-arid deployment zones. Project development concentrates where cooling-degree-day loads exceed 3,500 annually and refrigerant regulations compress conventional equipment viability.
Saudi Arabia
District cooling authorities in Riyadh and the Eastern Province integrate parabolic trough solar thermal fields with double-effect absorption chillers. The national regulator mandates renewable thermal fractions for new district cooling capacity, guaranteeing offtake for developers constructing concentrated solar thermal installations. NEOM Northwest serves as the testbed for next-generation solar cooling architectures at gigawatt-scale district cooling loads.
United Arab Emirates
Commercial building operators in Dubai face cooling-degree-day loads exceeding 4,000 annually, making solar thermal yield predictability decisive in procurement decisions. MOHAP-aligned building codes now require renewable thermal fractions for new commercial permits, directly expanding addressable market boundaries. Dubai's district cooling expansions prioritize absorption chiller compatibility in specifications exceeding 500kW capacity.
Germany
Public procurement specifications in Bavaria and North Rhine-Westphalia now mandate absorption chiller compatibility for cooling projects exceeding 500kW capacity under EU F-Gas Regulation phase-down schedules. Universities in Baden-Württemberg pilot hybrid photovoltaic-thermal collectors to maximize rooftop utilization density. German engineering consortiums anchor performance contracting models where developers retain ownership of solar thermal fields and absorption equipment.
India
Post-harvest cold chain losses in Maharashtra and Gujarat drive procurement of modular off-grid refrigeration units where grid reliability undermines conventional mechanical compression. Agricultural cold chain subsidies accelerate flat-plate collector deployments for sub-50kW cooling loads. The horticulture belt in Karnataka deploys solar thermal-driven absorption systems to replace diesel-powered cold storage.
Australia
Hospital complexes in New South Wales and Victoria adopt energy-as-a-service agreements for hybrid photovoltaic-thermal installations, transferring thermal storage sizing risk to specialized developers. Universities in Queensland pilot dual-output collectors that simultaneously generate electricity and 75-90°C process heat. Australian building codes in arid interior zones increasingly reference solar cooling compatibility for institutional new builds.
Solar Cooling Market Competitive Landscape
Global majors compete with regional champions across technology licensing and project development capabilities, producing a tiered structure where concentrated solar thermal specialists face modular off-grid refrigeration fabricators. The vendor base separates into three strategic archetypes: high-temperature process cooling specialists leveraging parabolic trough expertise, modular system integrators targeting agricultural cold chains, and hybrid technology developers consolidating photovoltaic and thermal collection. Dominant competitive moves include strategic partnerships between solar thermal field developers and district cooling authorities, plus technology licensing agreements that transfer absorption chiller manufacturing know-how across geographies.
Within the high-temperature specialist tier, Synhelion and GlassPoint exemplify concentrated solar thermal expertise applied to industrial process cooling contracts in arid climates. Among modular system integrators, SOLHO BV occupies a position serving agricultural cold chain applications with off-grid refrigeration architectures. Icarus RT, Inc. anchors the hybrid convergence segment, representing dual-output photovoltaic-thermal approaches for institutional rooftop installations. These three archetypes collectively illustrate how competitive positioning fragments across temperature regime, application scale, and grid connectivity requirements rather than consolidating around unified technology platforms.
| Leading Market Players |
|---|
| Icarus RT, Inc. |
| Synhelion |
| Soitec |
| SunOyster |
| MGA Thermal |
| SOLHO BV |
| GlassPoint |
| PlexiSun |
| Heliac |
| Others |
Value Network & Pricing Analysis
District cooling authorities in Saudi Arabia and the UAE anchor procurement volumes, forcing equipment vendors into performance-contracting structures where thermal storage sizing risk transfers to developers. This buyer concentration compresses upfront capital quotes while elongating payback horizons through energy-as-a-service arrangements.
Pricing Analysis
Warranty bundling separates premium-tier absorption chiller offerings from unbundled standard configurations where commissioning and lithium bromide maintenance carry separate line items. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 9806 collector certification status and double-effect versus single-effect chiller architecture. Cost compression in flat-plate collector tiers is intensifying because Chinese manufacturing concentration in Shandong province feeds oversupply into export markets. Commercial building operators in hot-arid zones demonstrate highest price sensitivity, while institutional buyers under performance contracts prioritize dispatchability guarantees over unit economics.
Supply Chain Analysis
Dual-sourcing mandates from European EPCs now require evacuated tube qualification from both Chinese and non-Chinese suppliers to mitigate tariff exposure. Manufacturing gravity centers on China for borosilicate glass vacuum tubes, Germany for precision absorption chiller heat exchangers, and Saudi Arabia for localized parabolic trough assembly. Raw material dependencies encompass lithium bromide from Dead Sea chemical processors, copper for heat exchanger fabrication, and tempered glass for collector covers. Single-source vulnerability concentrates in evacuated tube supply chains clustering in Jiangsu province. Distribution runs through engineering-procurement-construction consortia that consolidate solar thermal field development with chiller installation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation constructs a compliance moat that disqualifies conventional vapor-compression equipment from public procurement, elevating thermally driven cooling specialists with certified absorption chiller portfolios.
For Market Incumbents: Cement market position by securing ISO 9806 certification for novel evacuated tube designs ahead of refrigerant phase-down deadlines, and anchor backward integration into lithium bromide supply agreements to buffer raw material volatility. Emerging hybrid photovoltaic-thermal developers threaten to consolidate rooftop procurement categories previously separated between thermal and electric cooling. For New Entrants and Emerging Players: Capture white-space in India's agricultural cold chain where modular off-grid refrigeration units address post-harvest losses in Maharashtra and Gujarat. Agricultural electrification programs offer the most penetrable entry vector, with flat-plate collector sizing below 50kW presenting minimal capital barriers. Go-to-market execution should leverage state-level horticulture subsidies rather than competing on equipment specifications alone. For Investors and Strategic Acquirers: The window for entry favors developers with portfolio-scale thermal storage optimization capabilities and established relationships with district cooling authorities. Long-term viability hinges on regulatory synchronization between refrigerant phase-down schedules and collector certification timelines. Watch for ISO 9806 test laboratory bottlenecks as an inflection signal—delays there strand equipment configurations and compress compliant player margins.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Agreement | Transfers absorption chiller manufacturing know-how to EPCs in Saudi Arabia's renewable thermal mandate environment. |
| Backward Integration | Captive lithium bromide supply from Dead Sea chemical processors insulates margins against input cost swings. |
| Performance Contracting Expansion | Energy-as-a-service models transfer thermal storage sizing risk from building operators to specialized developers. |
| Hybrid System Development | Dual-output photovoltaic-thermal collectors consolidate rooftop infrastructure for institutional buyers in Spain and Australia. |
| Certification Investment | ISO 9806 collector certification accelerates market entry ahead of EU F-Gas Regulation enforcement deadlines. |
Research Methodology
Independent corroboration across solar thermal EPC contractors, district cooling authority procurement officers, and absorption chiller maintenance technicians underwrites the qualitative findings. Primary fieldwork encompassed interviews with lithium bromide system specialists, flat-plate collector manufacturers, and agricultural cold chain subsidy administrators. Secondary validation drew from EU F-Gas Regulation implementation guidance, Saudi renewable thermal mandate documentation, and customs data on evacuated tube import flows. Bottom-up installation tracking triangulates against top-down regulatory-driven demand modeling.
Rate-of-change decomposition separates volume expansion from value capture across the projection horizon. Segmentation dimensions span thermal collection architecture, thermodynamic cycle type, end-user category, and regional regulatory framework. CAGRs derive from correlating cooling-degree-day loads with refrigerant phase-down enforcement timelines. Forecast inputs incorporate district cooling capacity additions in Riyadh and Dubai, plus agricultural cold chain electrification rates in Maharashtra and Gujarat.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ISO 9806 certification bottlenecks and lithium bromide supply disruptions. Assumptions reflect current EU F-Gas Regulation enforcement schedules and Saudi renewable thermal mandate compliance trajectories. Deviation in Chinese evacuated tube export tariff policy would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Process Chillers Market
Cooling Systems
Industrial Cooling System Market
Cooling Systems
Global Chiller Market
Cooling Systems
United States Heat Pump Market
Cooling Systems
Three Phase Cooling Fans Market
Cooling Systems
Flue Gas Coolers Market
Cooling Systems
Heat Pump Dryer Market
Cooling Systems
Global Secondary Refrigerants Market
Cooling Systems
Temperature Controlled Container Market
Cooling Systems
Industrial Radiators Market
Cooling Systems
Thawing System Market
Cooling Systems
Cold Trap Market
Cooling Systems
Global Air Cooled Condenser Market
Cooling Systems
Middle East and Africa Cooling Systems Market
Cooling Systems
Global Energy Efficient HVAC Systems Market
Cooling Systems
Global Scroll and Absorption Chillers Market