
 Three Phase Cooling Fans Market | 2026-2036
Three Phase Cooling Fans Market Size, Share, and Industry Trends Forecast 2026-2036
Three Phase Cooling Fans Market Analytics
The EU F-Gas Regulation is recalibrating procurement criteria for cooling infrastructure across European data center fleets. Delta Electronics leverages its power electronics heritage to integrate variable frequency drives with three-phase fan motors, capturing efficiency-driven retrofits. Nidec Corporation anchors the high-reliability segment through magnetic bearing technologies that extend mean time between failures in continuous-duty installations. ebm-papst Group differentiates via backward-curved impeller designs optimized for ducted static pressure applications.
Three phase cooling fans are electromechanical air movers driven by three-phase alternating current motors, typically operating at 380-480V with power ratings from 100W to 15kW and rotational speeds governed by VFD control; they serve industrial and commercial thermal management by delivering higher torque density, smoother operation, and superior energy efficiency versus single-phase alternatives. Axial fans dominate volume in computer cooling and outdoor unit applications where low static pressure and high airflow volume are required. Centrifugal fans command premium positioning in industrial equipment and HVAC systems due to their ability to overcome higher system resistance, with margin pools concentrating in custom-impeller configurations for cleanroom and corrosive environments.
REACH compliance in Europe and GB standards enforcement under China's SAMR shape material selection and motor efficiency testing protocols for cross-border suppliers. The US Department of Energy's fan efficiency rating framework and India's BIS certification requirements for three-phase induction motors create layered compliance obligations that filter market access. Stakeholders must monitor evolving efficiency tier thresholds and regional carbon accounting rules to align product roadmaps with procurement specifications before competitive positioning hardens.
Market Dynamics
Data center thermal loads from AI training clusters are forcing infrastructure operators to re-engineer cooling architectures around high-efficiency three-phase fan arrays, compressing upgrade cycles from seven years to under four.
Growth Catalysts
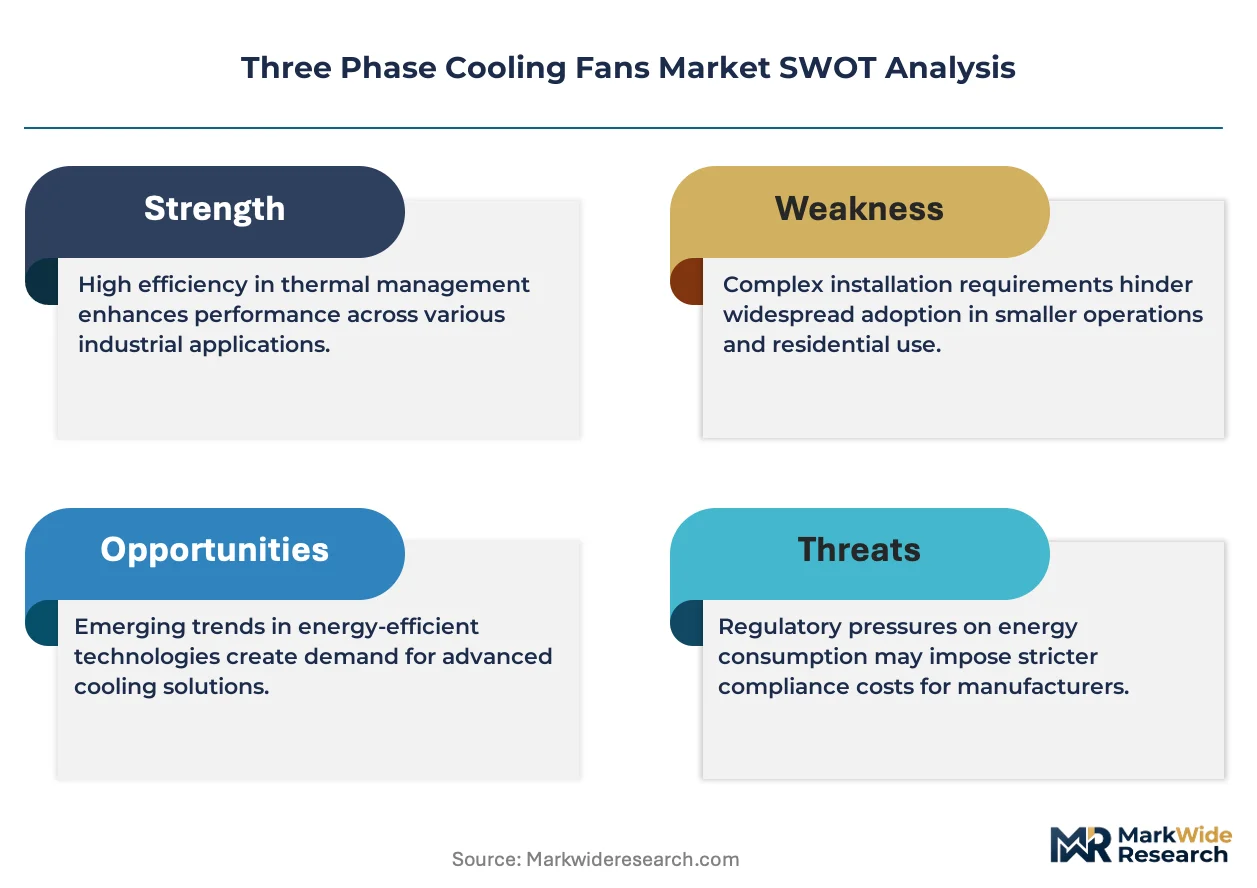
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants is redirecting European facility managers toward direct air cooling systems that rely on dense three-phase fan deployments for thermal management.
- AI training clusters:Hyperscale operators in Northern Virginia and Singapore are scaling three-phase cooling deployments to manage heat densities exceeding 50kW per rack in GPU-intensive environments.
- Guangdong manufacturing corridor:Parallel buildouts of server manufacturing capacity and cloud infrastructure in China's southern province are creating concentrated demand for industrial-grade cooling fans.
Market Restraints
- Copper and rare-earth magnet costs:Three-phase motor production faces input volatility from concentrated mining operations in the Democratic Republic of Congo and China's Inner Mongolia processing facilities.
- Supply concentration in East Asian motor laminations:Over 70% of high-grade electrical steel capacity sits with Japanese and South Korean mill operators, creating chokepoint vulnerability.
- Technical ceiling at extreme static pressure:Axial fan architectures encounter efficiency cliffs above 2,500 Pa system resistance, limiting penetration into deep-drawing industrial exhaust applications.
Strategic Opportunities
- India's BIS certification expansion:The Bureau of Indian Standards is tightening efficiency tiers for three-phase induction motors, creating first-mover advantage for suppliers with pre-certified product lines.
- Magnetic bearing convergence with VFD control:The integration of active magnetic suspension with variable frequency drives enables oil-free operation in cleanroom pharmaceutical environments.
- Retrofit channel development:Direct contracting with facility energy managers is bypassing traditional HVAC distributor networks in European industrial estates.
Industry Challenges
- Electromagnetic compatibility certification:Multi-jurisdiction testing for IEC 61000-3-6 harmonic emissions and FCC Part 15 radiated limits extends product launch timelines by 8-14 months.
- Thermal engineer scarcity:The specialized skill set combining CFD simulation with three-phase motor specification is concentrated among aging cohorts in German and Japanese industrial equipment sectors.
- Legacy building management integration:BACnet and Modbus protocol fragmentation across installed HVAC control systems complicates fan array commissioning in brownfield data centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Three Phase Cooling Fans Market |
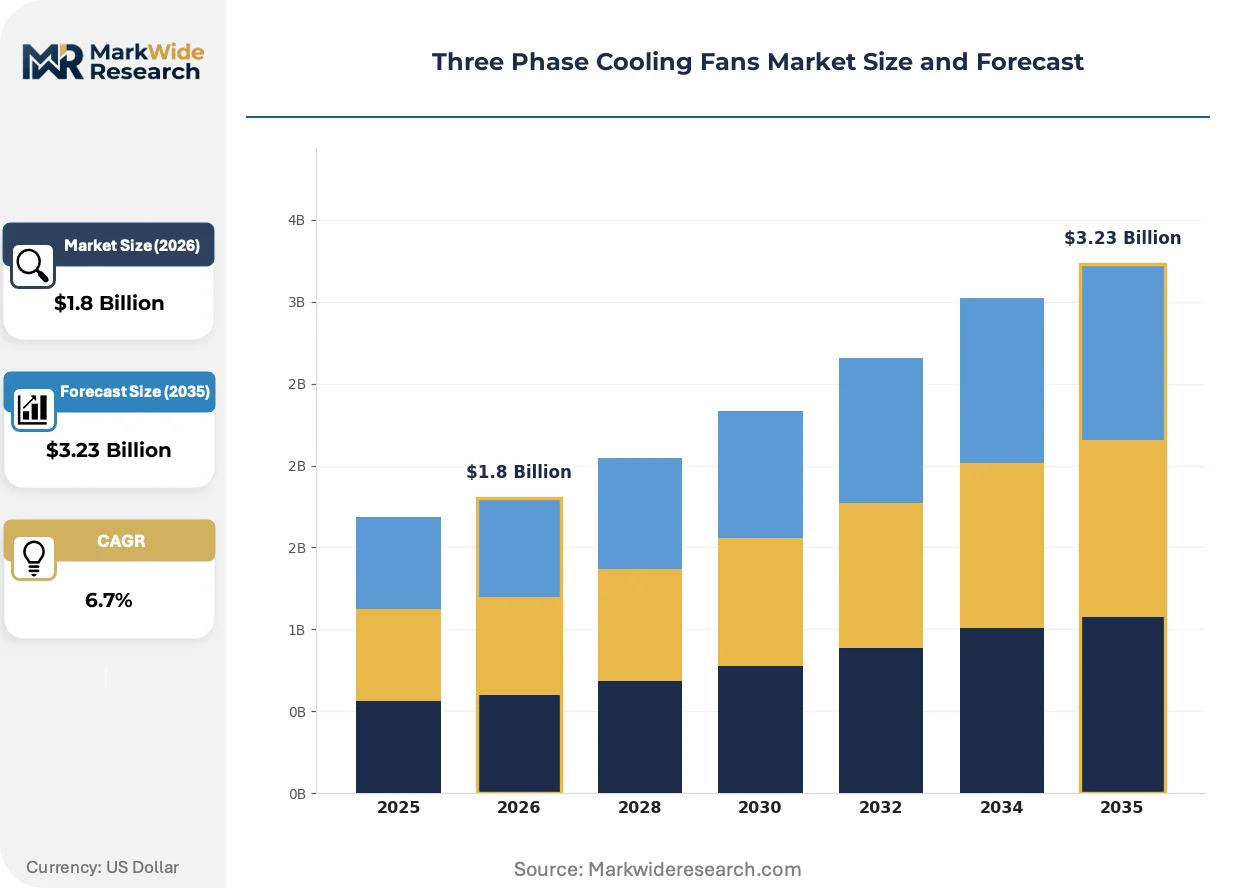
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tangential Fans, Axial Fans, Centrifugal Fans, Blowers Application: Industrial Equipment, HVAC Systems, Computer Cooling, Outdoor Units End User: Manufacturing, Data Centers, Automotive, HVAC Contractors Installation: Wall-Mounted, Ceiling-Mounted, Ducted, Stand-Alone |
| Companies Covered | Delta Electronics, Nidec Corporation, ebm-papst Group, Siemens AG, Sunonwealth Electric Machine Industry, Sanyo Denki, Oriental Motor, MinebeaMitsumi, Rosenberg Ventilatoren, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Three Phase Cooling Fans Market Evolving Landscape
Electrification of industrial thermal management is compressing fan motor efficiency thresholds while regulatory frameworks multiply compliance obligations across export markets.
Permanent magnet synchronous motor technology is consolidating position in premium three-phase fan applications. Hyperscale data center operators in Singapore and Northern Virginia are specifying PM-based arrays for their 96%-plus efficiency at partial load conditions. The technology is consolidating supplier margins toward integrated motor-drive packages and away from standalone component sales.
REACH substance restrictions enforced by ECHA are eliminating certain insulating varnishes and bearing greases from European-bound fan production. Industrial consequence includes accelerated reformulation cycles and supply chain requalification costs. HVAC OEMs serving the German market are responding by consolidating supplier bases to partners with established SVHC compliance documentation systems.
Specification authority is migrating from mechanical contractors to energy procurement teams with carbon accounting mandates. The traditional distributor-specifier channel in US commercial construction is losing influence to direct manufacturer engagement with sustainability officers. This pattern is most visible in Northern Virginia data center developments where power usage effectiveness targets now dominate fan selection criteria.
Three Phase Cooling Fans Market Segmentation
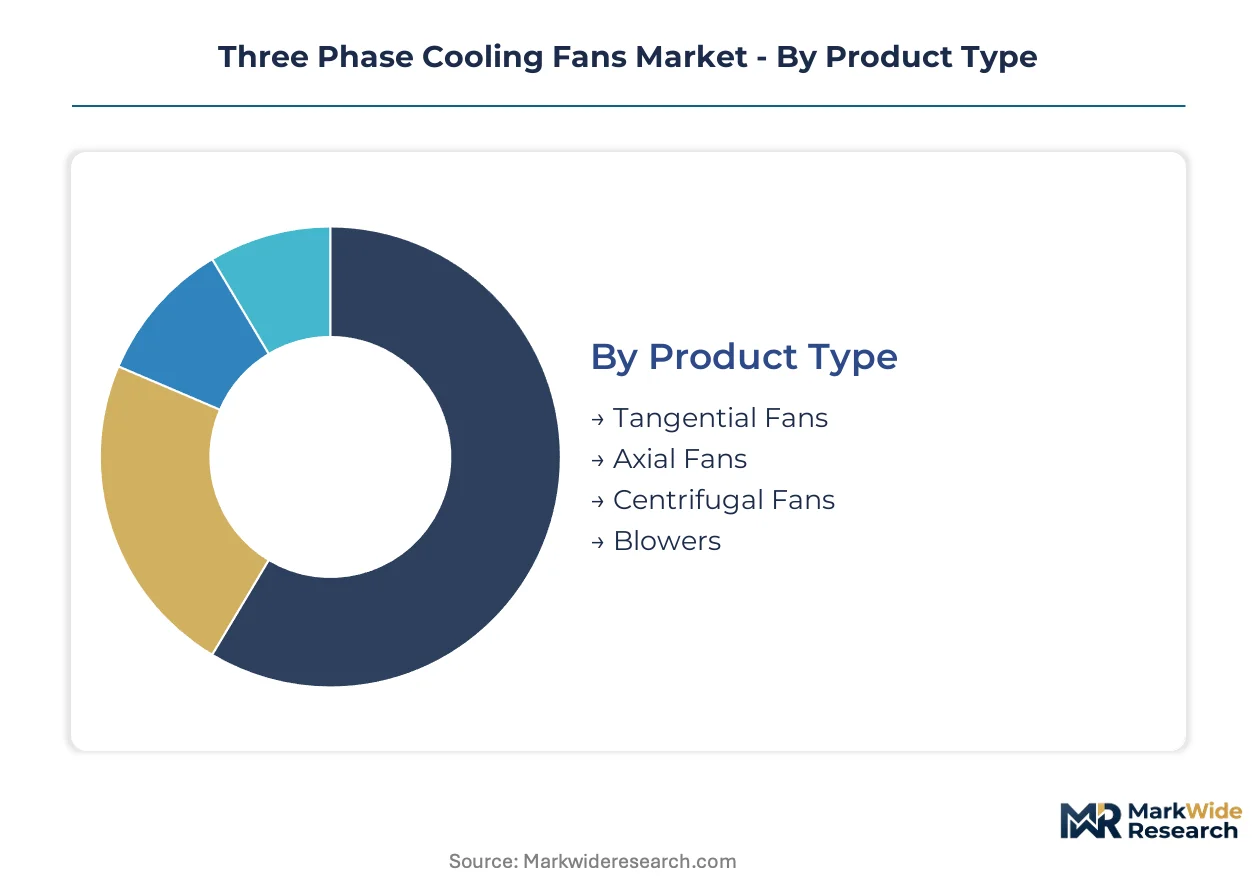
Three-phase cooling fan procurement decisions cascade through multiple technical and commercial filters. Specification authority varies sharply across end-use contexts, from data center energy procurement teams to mechanical contractors bidding on industrial HVAC retrofits.
Product Type:
Static pressure requirements and duty cycle intensity dominate buyer selection criteria across fan architectures.
- Axial Fans:Propeller-style impellers move high air volumes against minimal resistance, typically 50-500 Pa. Data center operators in Northern Virginia specify these for direct air cooling arrays serving AI training clusters where airflow volume trumps pressure head.
- Centrifugal Fans:Backward-curved or forward-curved impellers generate pressure differentials exceeding 2,500 Pa for ducted industrial exhaust. Cleanroom pharmaceutical installations in Singapore specify magnetic-bearing centrifugal units for oil-free operation under continuous duty.
- Tangential Fans:Cross-flow designs deliver uniform air curtains across extended widths for commercial display cases and air handling units.
- Blowers:High-speed impeller configurations concentrate airflow for spot cooling and pneumatic conveying systems in manufacturing environments.
Volume sits with axial configurations; growth tilts toward centrifugal arrays specified for high-density thermal management.
Application:
Regulatory pressure and infrastructure upgrade cycles create divergent demand profiles across installation contexts.
- Data Centers:Hyperscale facilities in Singapore and Northern Virginia deploy three-phase fan arrays to manage rack densities exceeding 50kW from GPU-intensive AI workloads. EU F-Gas Regulation compliance is redirecting European operators from refrigerant-based cooling toward direct air architectures.
- HVAC Systems:Commercial and industrial climate control applications specify centrifugal and axial units for air handling units, chillers, and heat pump outdoor coils. India's BIS efficiency tier tightening is filtering supplier access for new construction projects.
- Industrial Equipment:Machine tool cooling, welding fume extraction, and process ventilation demand corrosion-resistant configurations for aggressive environments.
- Computer Cooling:Server chassis and telecommunications enclosures specify compact axial units with PWM or VFD speed control for thermal load matching.
- Outdoor Units:Condenser and heat pump applications require weatherproof motor enclosures and coated impellers for coastal or industrial atmospheres.
Procurement volume concentrates in HVAC replacement cycles; expansion is steepest in data center thermal infrastructure.
End User:
Buying center composition and specification authority vary systematically across customer categories.
- Data Centers:Energy procurement teams with carbon accounting mandates now override traditional mechanical contractor specifications. Power usage effectiveness targets dominate fan selection in Northern Virginia developments.
- Manufacturing:Plant engineering departments prioritize mean time between failure and spare parts commonality across installed equipment bases.
- HVAC Contractors:Installation firms balance first cost against warranty terms and distributor availability for bid competitiveness.
- Automotive:Battery thermal management and power electronics cooling specify compact, high-reliability units with automotive-grade qualification protocols.
Specification control is migrating from contractors to energy managers in data center and large industrial accounts.
Installation:
Physical mounting constraints and system integration complexity shape product configuration requirements.
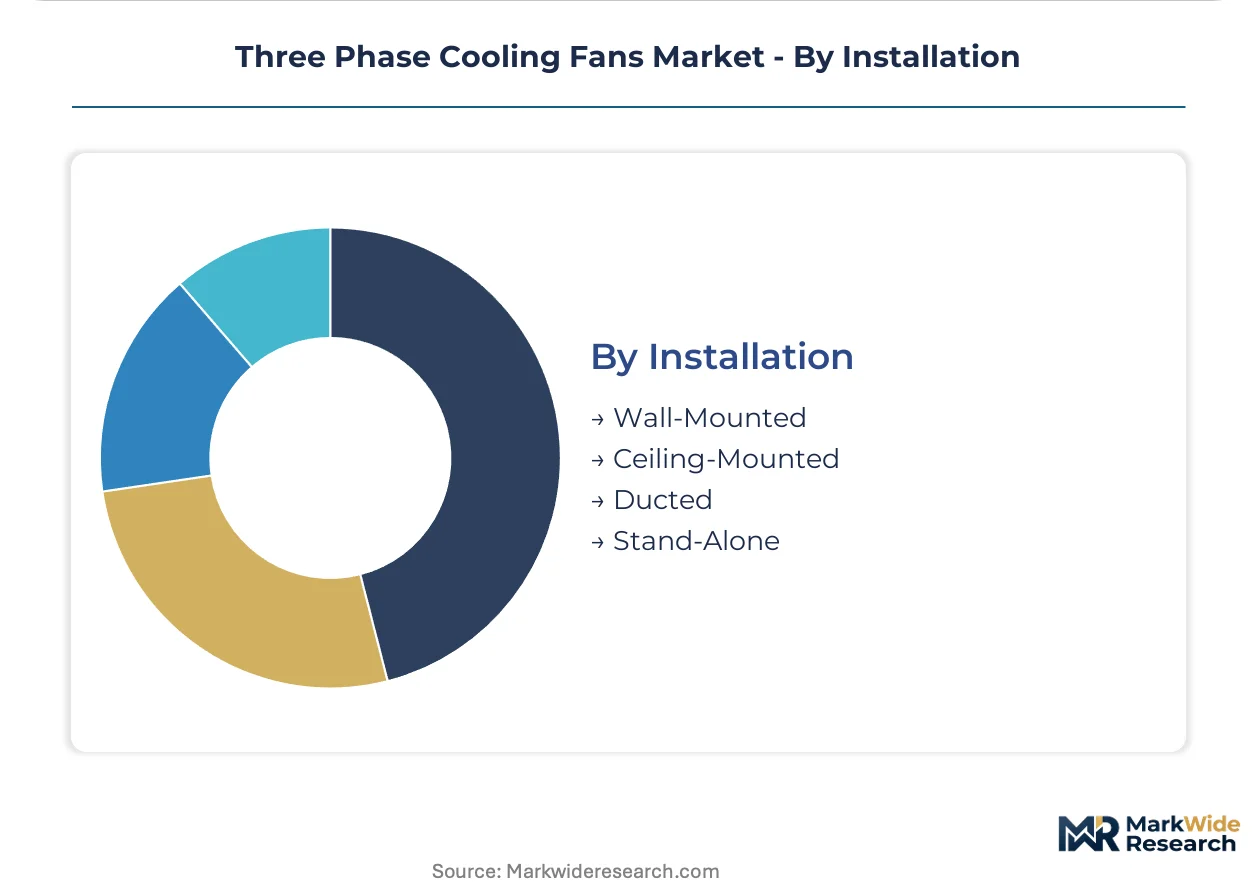
- Ducted:Inline installations for HVAC and industrial exhaust systems demand static pressure-optimized impellers with flanged housing connections.
- Stand-Alone:Portable or fixed pedestal units serve spot cooling and temporary ventilation with minimal installation overhead.
- Wall-Mounted:Through-wall configurations for commercial kitchens, warehouses, and equipment rooms require weather seals and gravity dampers.
- Ceiling-Mounted:Suspended units for distribution warehouses and manufacturing floors optimize floor space utilization.
New construction favors ducted integration; retrofit activity is expanding stand-alone and wall-mounted deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in East Asian electrical steel corridors while consumption concentrates in data center hubs across three continents. The mismatch between motor lamination supply and cooling system deployment creates freight-intensive trade flows. Regional regulatory divergence is fragmenting product specifications faster than component standardization can accommodate.
United States
Hyperscale data center construction in Northern Virginia and Phoenix drives specification authority toward energy procurement teams with power usage effectiveness mandates. The Department of Energy's fan efficiency rating framework filters supplier access for federal facility retrofits. Tax incentives under the Inflation Reduction Act accelerate HVAC modernization in industrial estates across Texas and the Midwest.
China
Guangdong province anchors parallel buildouts of server manufacturing and cloud infrastructure, creating concentrated demand for industrial-grade axial and centrifugal arrays. GB standards enforcement under SAMR shapes motor efficiency testing protocols for domestic and export-bound production. Yangtze River Delta data center clusters in Shanghai and Jiangsu specify high-reliability units for GPU-intensive AI training environments.
Germany
Industrial HVAC retrofit cycles compress as REACH substance restrictions eliminate legacy insulating varnishes from European-bound production. The EU F-Gas Regulation redirects facility managers toward direct air cooling architectures requiring dense three-phase fan deployments. Bavarian automotive battery plants and Baden-Württemberg machine tool manufacturers specify magnetic-bearing centrifugal units for continuous-duty thermal management.
India
BIS certification tightening for three-phase induction motors creates first-mover advantage for suppliers with pre-certified product lines entering new construction projects. Telangana and Karnataka data center developments in Hyderabad and Bangalore specify high-efficiency arrays for tropical climate operation. Maharashtra's industrial corridor around Pune and Mumbai drives replacement demand in automotive and pharmaceutical manufacturing ventilation.
Singapore
Tropical heat density and land scarcity force rack power densities above 50kW in AI training clusters, requiring advanced thermal management architectures. The city-state's carbon neutrality targets for 2050 compress upgrade cycles for existing facility infrastructure. Tuas and Changi data center precincts specify oil-free magnetic-bearing centrifugal units for cleanroom pharmaceutical co-location environments.
Three Phase Cooling Fans Market Competitive Landscape
The competitive structure tilts toward integrated motor-drive specialists with power electronics heritage. Japanese and Taiwanese conglomerates with magnetic materials capabilities occupy premium positioning through bearing technology differentiation. European specialists command specification authority in ducted static pressure applications. Two dominant competitive moves define current positioning: backward integration into variable frequency drive firmware and geographic expansion through direct contracting with facility energy managers bypassing traditional HVAC distribution.
Within the integrated electronics tier, Delta Electronics exemplifies the power electronics-to-thermal management convergence archetype. Nidec Corporation anchors the high-reliability segment through magnetic bearing competencies. Among European specialists, ebm-papst Group occupies a position defined by impeller aerodynamics expertise for ducted industrial applications.
| Leading Market Players |
|---|
| Delta Electronics |
| Nidec Corporation |
| ebm-papst Group |
| Siemens AG |
| Sunonwealth Electric Machine Industry |
| Sanyo Denki |
| Oriental Motor |
| MinebeaMitsumi |
| Rosenberg Ventilatoren |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between magnetic-bearing premium arrays and commodity induction-motor units splits pricing power along supply chain concentration in East Asian electrical steel corridors. Buyers qualifying for EU F-Gas Regulation compliance and India's BIS efficiency tiers face extended lead times from Japanese and South Korean lamination mills, while standard-grade procurement taps fragmented Chinese motor winding capacity.
Pricing Analysis
Margin tightening in standard-grade axial configurations reflects copper and rare-earth magnet cost volatility from Democratic Republic of Congo mining and Inner Mongolia processing bottlenecks. Three-tier pricing structure across premium magnetic-bearing, mid-tier PM synchronous, and economy induction-motor levels separates buyers by mean-time-between-failure requirements and carbon accounting mandates. Cost-down pressure on economy tiers accelerates as Guangdong server manufacturers consolidate supplier bases for volume discounts. Data center energy procurement teams exhibit lowest price sensitivity given power usage effectiveness targets, while HVAC contractors in India's new construction market prioritize first-cost competitiveness.
Supply Chain Analysis
Dual-sourcing requirements from hyperscale operators in Northern Virginia and Singapore mandate qualified alternative suppliers for magnetic-bearing centrifugal arrays beyond Nidec Corporation's primary capacity. High-grade electrical steel production concentrates in Japan and South Korea, with copper winding supply anchored in China and secondary qualification in Vietnam. Supply chain risk centers on single-source vulnerability in rare-earth magnet processing. Distribution runs through direct contracting with facility energy managers bypassing traditional HVAC distributor networks in European industrial estates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrical steel lamination capacity constraints in East Asian mill operations prop pricing premiums for high-efficiency three-phase fan arrays, creating supply-constrained market dynamics favoring incumbents with captive magnetics capabilities.
For Market Incumbents: Lock in long-term offtake agreements with Japanese and South Korean electrical steel producers before efficiency tier tightening in India and Europe hardens qualification requirements. Backward integration into variable frequency drive firmware protects margin pools from standalone component commoditization. Defend against emerging Chinese PM motor specialists by accelerating REACH-compliant varnish reformulation ahead of ECHA enforcement timelines. For New Entrants and Emerging Players: Enter via India's BIS pre-certification channel targeting Telangana and Karnataka data center developments where first-mover advantage remains available. White-space sits with oil-free magnetic-bearing retrofits for Singapore pharmaceutical cleanrooms and German automotive battery plants. Pursue direct contracting relationships with facility energy managers in Northern Virginia bypassing incumbent distributor lock-in. For Investors and Strategic Acquirers: Re-rating potential sits with integrated motor-drive specialists given convergence of VFD control and magnetic-bearing technologies. Five-to-ten year viability favors suppliers with established SVHC compliance documentation and captive rare-earth magnet sourcing. Watch for inflection in EU carbon border adjustment mechanism implementation affecting Chinese motor import competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into VFD Firmware | Captures efficiency-driven retrofit margins in Northern Virginia data center upgrades. |
| Magnetic Bearing Technology Licensing | Enables oil-free operation for Singapore pharmaceutical cleanroom specifications. |
| REACH-Compliant Insulation Reformulation | Preserves European market access under ECHA substance restriction enforcement. |
| Direct Energy Manager Contracting | Bypasses traditional HVAC distribution in European industrial estate retrofits. |
| India BIS Pre-Certification Investment | Secures first-mover positioning in Telangana and Karnataka data center buildouts. |
Research Methodology
Regulatory filings from ECHA, BIS certification databases, and SAMR GB standards documentation formed the secondary backbone for compliance pathway mapping. Primary interviews with data center energy procurement managers, HVAC contractor specification engineers, and electrical steel procurement leads at Japanese mill operators combined with customs trade data and SEC filings from motor-drive specialists. Bottom-up unit economics triangulated against top-down infrastructure capex tracking across Northern Virginia, Singapore, and Guangdong deployment clusters.
Bottom-up modeling segmented volume across axial, centrifugal, tangential, and blower architectures by application intensity and installation configuration. Top-down validation cross-referenced hyperscale operator thermal load projections against fan array density requirements for AI training clusters exceeding 50kW per rack. CAGRs derived from installed base replacement cycle compression and regulatory-driven efficiency tier adoption curves, incorporating rare-earth magnet price indices and electrical steel capacity utilization as sensitivity inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU F-Gas Regulation phase-down or disruption in Democratic Republic of Congo copper concentrate supply. Deviation in Chinese electrical steel export licensing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Horizontal Air Flow Condensers Market
Cooling Systems
United States Heat Pump Market
Cooling Systems
Radiant Cooling Systems Market
Cooling Systems
Solar Air Conditioning Market
Cooling Systems
Evaporative Cooling Tower Market
Cooling Systems
Battery Cooling Plate Market
Cooling Systems
Global Air Cooled Condenser Market
Cooling Systems
Turbine Inlet Cooling Systems Market
Cooling Systems
Chilled Water System Market
Cooling Systems
Fluid Coolers Market
Cooling Systems
Seawater Cooling System Market
Cooling Systems
Cold Climate Air Source Heat Pump Market
Cooling Systems
Industrial Radiators Market
Cooling Systems
North America Evaporative Cooling Market
Cooling Systems
Thermosiphon Cooling System Market
Cooling Systems
Temporary Power and Cooling Solutions Market