
 Refrigeration Valves Market | 2026-2036
Refrigeration Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Refrigeration Valves Market Analytics
Asian component foundries are shifting capacity toward brass and stainless steel valve bodies for transcritical CO2 systems. Danfoss A/S anchors European design standards through its deep catalog of electronic expansion valves. Zhejiang Sanhua Co., Ltd. dominates mass production of solenoid valves for commercial cooling OEMs. Parker Hannifin Corporation leverages aerospace-derived sealing technologies to differentiate in industrial refrigeration.
Refrigeration valves regulate refrigerant flow, pressure, and direction in closed-loop thermodynamic systems, typically machined from brass or stainless steel to withstand pressures exceeding 45 bar in subcritical CO2 applications. Their primary purpose is to maintain system efficiency and safety across vapor compression cycles. Solenoid valves lead unit volume in commercial cooling due to electrification of supermarket rack systems, while stainless steel variants command premium positioning in industrial ammonia installations where corrosion resistance determines replacement cycles. Electric control methods are displacing manual actuation fastest in transport refrigeration, driven by telematics integration and remote diagnostics.
The US EPA SNAP program and the EU F-Gas Regulation are tightening refrigerant eligibility lists, compelling valve manufacturers to certify materials for flammable and high-pressure working fluids. China's NMPA and GB standards enforce pressure equipment safety inspections that delay uncertified imports. Japan's METI energy efficiency benchmarks reward low-leakage valve designs in commercial equipment. Stakeholders must monitor refrigerant-phase transitions and certify products under divergent national pressure-equipment codes before committing to regional production footprints.
Market Dynamics
The Kigali Amendment's refrigerant-phase mandates are compressing valve design cycles, forcing manufacturers to recertify brass and stainless steel architectures for CO2 and ammonia compatibility before legacy R-404A inventories deplete.
Growth Catalysts
- Asia-Pacific cold chain buildout:Warehouse operators in Vietnam and Indonesia are procuring electronic expansion valves for automated rack systems as perishable logistics networks densify.
- F-Gas Regulation phase-down:EU-imposed refrigerant quotas are compelling supermarket chains to retrofit existing installations with low-GWP-compatible valve trains.
- Telematics integration:Fleet operators are specifying solenoid valve arrays with embedded sensors for predictive maintenance in refrigerated transport.
Market Restraints
- Copper and brass input volatility:Foundry energy costs and concentrate supply disruptions from Chilean and Peruvian mines are squeezing margin structures on commodity valve bodies.
- Pressure equipment certification fragmentation:Divergent testing protocols between China's NMPA, the EU's Pressure Equipment Directive, and US ASME standards extend product launch timelines.
- Sealing material obsolescence:Legacy nitrile and neoprene compounds face disqualification under new flammable refrigerant safety standards.
Strategic Opportunities
- Indian cold storage deficit:Post-harvest losses exceeding twenty percent are driving government-backed warehouse construction requiring industrial ammonia valve systems.
- Carbon capture convergence:Transcritical CO2 expertise from refrigeration is transferring to energy storage and industrial process applications.
- Japan's METI efficiency premiums:Low-leakage valve designs qualify for equipment subsidies that accelerate replacement cycles in commercial sectors.
Industry Challenges
- Multiphysics simulation talent scarcity:Valve manufacturers compete for engineers capable of modeling two-phase flow and fatigue in high-pressure CO2 systems.
- Retrofit integration complexity:Existing rack architectures with incompatible piping geometries require custom manifold fabrication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refrigeration Valves Market |
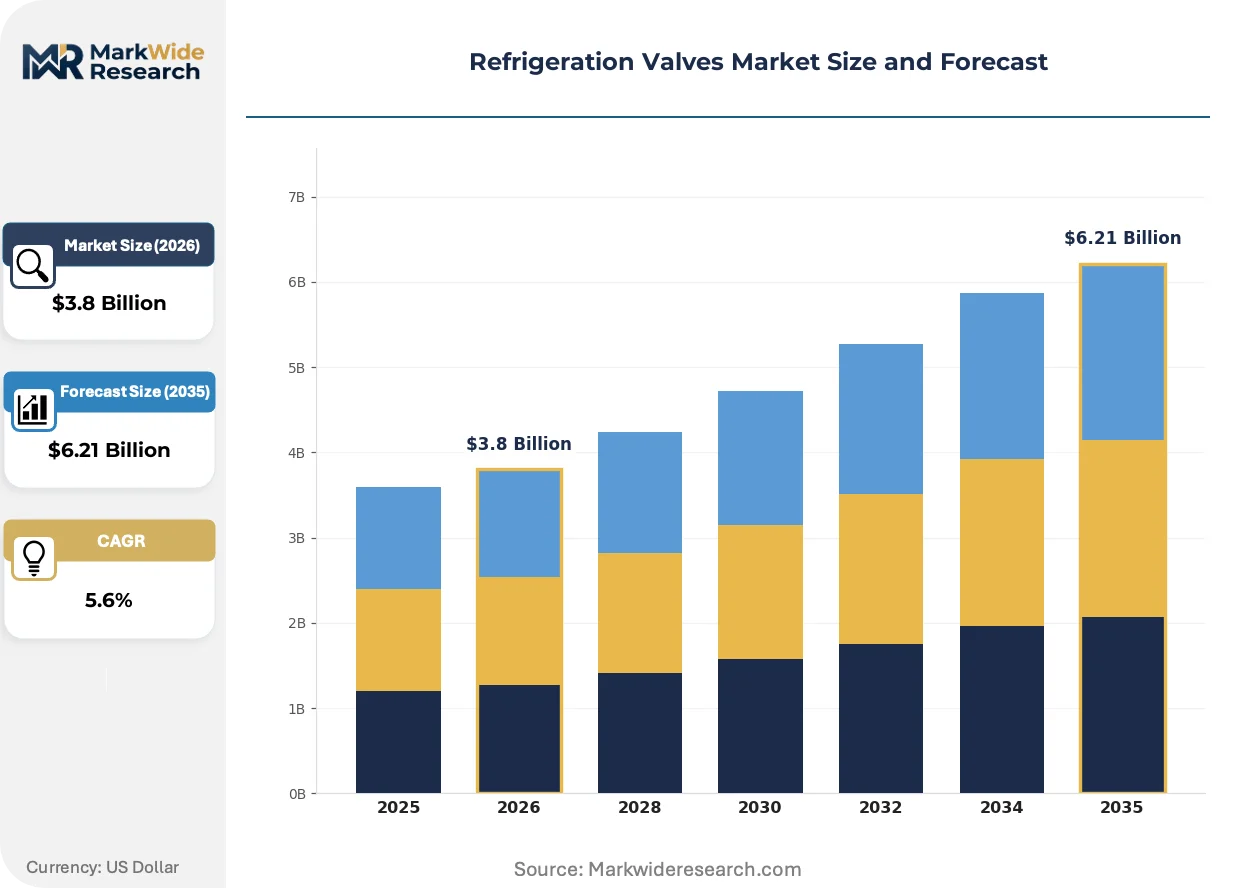
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Solenoid Valves, Check Valves, Ball Valves, Gate Valves Material: Brass, Stainless Steel, Plastic, Copper Application: Commercial Cooling, Industrial Refrigeration, Residential Systems, Transport Refrigeration Control Method: Manual, Electric, Pneumatic, Hydraulic |
| Companies Covered | Parker Hannifin Corporation, CAREL Industries S.p.A, Danfoss A/S, Castel S.p.A, Belimo Holding AG, Emerson Electric Co., Johnson Controls International plc, Honeywell International Inc., Zhejiang Sanhua Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refrigeration Valves Market Evolving Landscape
Actuation architectures are converging with building automation protocols, compressing the distinction between standalone refrigeration components and integrated energy management nodes.
Electronic expansion valve controllers is unifying superheat management with demand-response grid signaling. Supermarket operators in Germany and Denmark are deploying these systems to capture utility incentive payments. The technology is unifying refrigeration control with facility-wide energy arbitrage, elevating valve electronics from passive flow regulation to active grid assets.
REACH substance restrictions are eliminating chromate conversion coatings on brass valve bodies, forcing suppliers to validate trivalent chromium and zirconium-based alternatives. Coating qualification timelines now extend eighteen to twenty-four months. Industrial ammonia installations in the Netherlands and Belgium are experiencing the longest certification delays.
Specifying behavior is pivoting from component procurement to system-level performance contracting. Cold chain logistics providers in California and Texas are sourcing complete rack assemblies with guaranteed leakage rates rather than discrete valves. This pattern is most visible among third-party logistics operators managing multi-temperature distribution centers.
Refrigeration Valves Market Segmentation
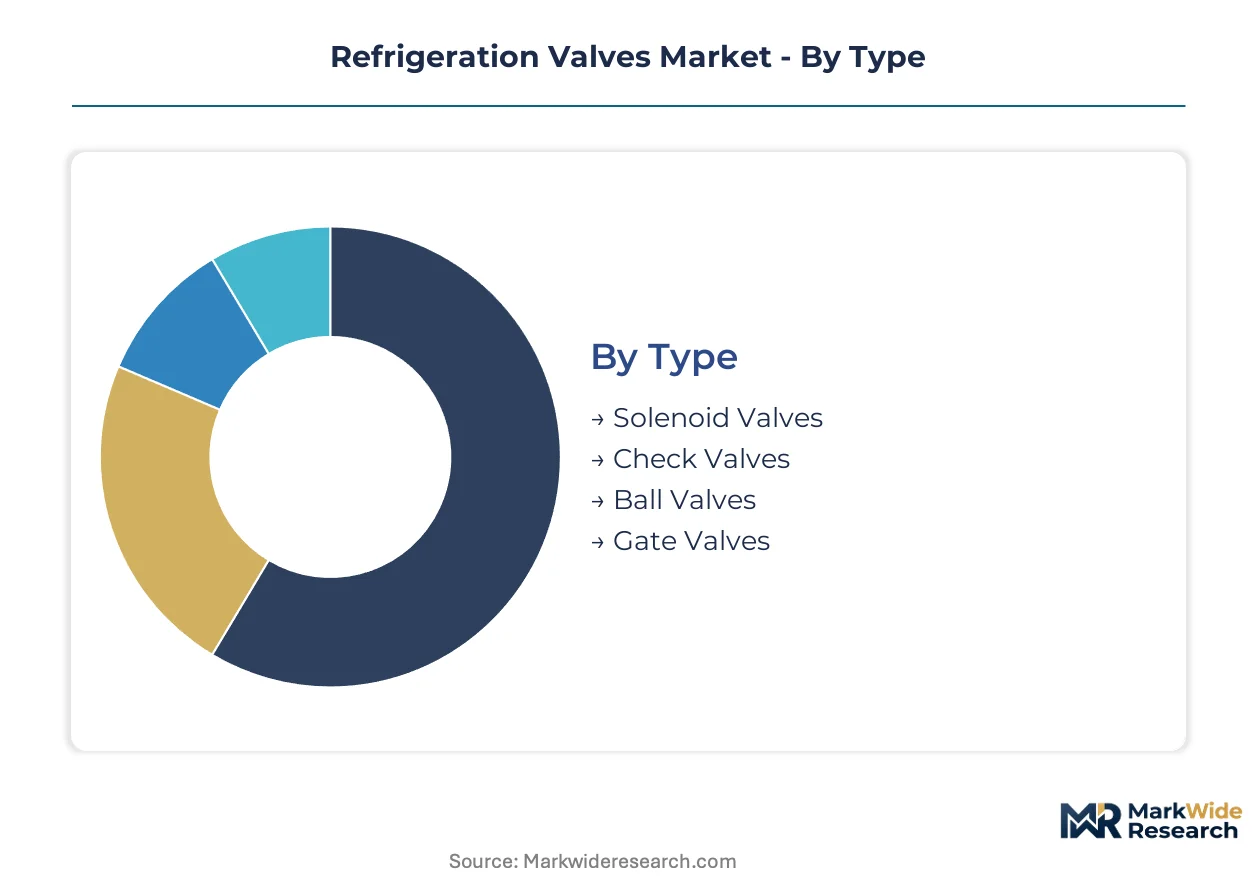
Valve specification diverges sharply across cooling system architectures, with pressure ratings and actuation methods determining compatibility with ammonia, CO2, and synthetic refrigerant chemistries. Procurement patterns cluster around retrofit cycles driven by F-Gas phase-downs and cold chain infrastructure buildouts.
Type:
Standardization dominates high-volume commercial cooling, while industrial ammonia and transcritical CO2 systems demand customized manifold configurations with integrated safety shutoffs.
- Solenoid Valves:Electromagnetic actuation enables rapid cycling for supermarket rack systems and refrigerated transport fleets. China's Zhejiang and Jiangsu provinces concentrate foundry output for Asian OEM supply chains facing Kigali Amendment retrofit deadlines.
- Check Valves:Spring-loaded or gravity-seated designs prevent refrigerant backflow in multi-circuit racks. European supermarket operators specify these for CO2 booster systems where reverse flow risks compressor damage during defrost cycles.
- Ball Valves:Quarter-turn shutoff for service isolation in industrial ammonia distribution. Compact brass variants serve residential heat pump installations.
- Gate Valves:Full-bore linear actuation for large-diameter industrial suction lines. Limited deployment outside heavy-capacity cold storage facilities.
Most installed capacity flows through solenoid architectures. Expansion is steepest in check valve configurations for transcritical CO2 safety circuits.
Material:
Cost tiers separate commodity brass from corrosion-resistant alloys, with premium stainless grades capturing industrial ammonia maintenance contracts.
- Brass:Copper-zinc castings withstand 45 bar pressures in subcritical CO2 applications. Foundries in China's Ningbo region supply volume contracts for commercial cooling OEMs.
- Stainless Steel:Austenitic grades resist ammonia stress corrosion cracking in industrial installations. Dutch and Belgian cold storage operators mandate 316L specifications for replacement cycles exceeding fifteen years.
- Plastic:Polymer bodies reduce weight in residential mini-split systems. Limited pressure ratings exclude industrial deployment.
- Copper:Wrought copper forgings for brazed connections in traditional direct-expansion systems. Facing displacement by brass in cost-sensitive segments.
Brass retains volume leadership across commercial cooling. Stainless steel gains share fastest in ammonia-compliant industrial retrofits.
Application:
End-use concentration shapes specification intensity, with transport refrigeration demanding the most compact actuation packages.
- Commercial Cooling:Supermarket display cases and warehouse rack systems drive electronic expansion valve procurement. German and Danish operators integrate demand-response controllers for grid incentive capture.
- Industrial Refrigeration:Ammonia-based cold storage and food processing plants require pressure-rated stainless architectures. Indian government-backed warehouse construction targets post-harvest loss reduction.
- Residential Systems:Heat pump and air conditioning OEMs specify compact brass solenoids for R32 and R410A circuits.
- Transport Refrigeration:Fleet telematics integration favors electric solenoid arrays with embedded pressure sensors for predictive maintenance.
Commercial cooling channels the largest valve volumes. Transport refrigeration climbs fastest on electrification and connected fleet mandates.
Control Method:
Actuation sophistication separates legacy manual installations from integrated building automation nodes.
- Manual:Handwheel or lever operation for service isolation in small-capacity systems. Retained in developing market cost-sensitive segments.
- Electric:Stepper motor and solenoid drives enable superheat optimization and remote diagnostics. California cold chain operators specify these for multi-temperature distribution centers.
- Pneumatic:Compressed air actuation for explosion-risk environments handling hydrocarbon refrigerants. Niche deployment in specialized industrial settings.
- Hydraulic:Fluid-power actuation for large-bore industrial isolation valves. Limited to heavy-capacity ammonia systems.
Electric methods dominate new specification. Manual configurations persist in replacement parts for installed base maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Valve manufacturers arbitrage compliance costs across jurisdictions, migrating foundry capacity toward regions with streamlined pressure-equipment certification while maintaining design centers near end-use clusters. Production footprints shift where NMPA, ASME, and PED testing protocols diverge most sharply.
China
Ningbo and Jiangsu province foundries supply brass valve bodies for commercial cooling OEMs facing Kigali Amendment retrofit deadlines. The NMPA enforces GB standards pressure equipment inspections that delay uncertified imports. Yangtze River Delta industrial clusters concentrate transcritical CO2 valve prototyping for domestic cold chain buildouts.
Germany
Supermarket operators in Bavaria and North Rhine-Westphalia deploy demand-response-enabled electronic expansion valves to capture utility incentive payments. The EU F-Gas Regulation mandates refrigerant quota compliance that accelerates low-GWP valve train retrofits. Stuttgart-area engineering firms specialize in multiphysics simulation for high-pressure CO2 fatigue modeling.
United States
California and Texas cold chain logistics providers specify electric solenoid arrays with embedded sensors for multi-temperature distribution centers. The EPA SNAP program restricts refrigerant eligibility lists that compel material recertification for flammable working fluids. Pacific Northwest industrial refrigeration contractors source stainless steel ammonia valves for food processing retrofits.
India
Maharashtra and Gujarat warehouse construction targets post-harvest loss reduction exceeding twenty percent through industrial ammonia valve procurement. The BIS pressure equipment code creates certification bottlenecks for imported brass architectures. Delhi-NCR cold storage developers negotiate system-level performance contracts with guaranteed leakage rates.
Japan
Tokyo and Osaka commercial equipment OEMs qualify low-leakage valve designs for METI energy efficiency subsidies that compress replacement cycles. The country's national refrigerant safety standards enforce strict material compatibility testing for CO2 systems. Kanto region supermarket chains integrate valve controllers with building automation protocols for grid arbitrage.
Refrigeration Valves Market Competitive Landscape
European producers anchor the premium tier through deep electronic expansion valve catalogs and aerospace-derived sealing expertise; Chinese fabricators hold volume leadership in solenoid architectures for commercial cooling OEMs. The market structures around three archetypes: integrated building automation suppliers, specialized refrigeration component fabricators, and diversified industrial conglomerates with climate-control divisions. Competitive moves concentrate on capacity expansion in Yangtze River Delta foundries and strategic partnerships between valve manufacturers and cold chain logistics operators.
Among diversified industrial conglomerates, Parker Hannifin Corporation and Emerson Electric Co. exemplify the premium-tier positioning built on aerospace and process control heritage. Zhejiang Sanhua Co., Ltd. occupies the mass-production archetype for Asian OEM supply chains. Danfoss A/S anchors European design standards through its extensive electronic expansion valve portfolio. These three represent the geographic and capability split defining competitive positioning: North American process control depth, Chinese scale manufacturing, and European systems integration expertise.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| CAREL Industries S.p.A |
| Danfoss A/S |
| Castel S.p.A |
| Belimo Holding AG |
| Emerson Electric Co. |
| Johnson Controls International plc |
| Honeywell International Inc. |
| Zhejiang Sanhua Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Transcritical CO2 valve prototyping in China's Yangtze River Delta is simultaneously compressing unit cost curves and concentrating brass foundry capacity around Ningbo-Jiangsu industrial corridors. Cold chain logistics operators in California and Texas now negotiate system-level performance contracts with guaranteed leakage rates rather than discrete component procurement, shifting pricing power toward integrated rack assemblers.
Pricing Analysis
Distributor margins on brass solenoid valves compress as Ningbo foundries ship direct to Asian OEMs under long-term offtake agreements. Three-tier pricing structure across premium stainless ammonia systems, standard brass commercial cooling architectures, and economy plastic residential mini-split valves reflects certification intensity and pressure rating differentiation. Cost compression in commodity brass tiers intensifies because Chilean copper concentrate supply disruptions squeeze input economics. Warehouse operators in Vietnam and Indonesia exhibit highest price sensitivity, while Dutch and Belgian cold storage developers purchasing 316L ammonia systems prioritize fifteen-year replacement cycles over upfront cost.
Supply Chain Analysis
Dual-sourcing mandates from German supermarket chains and Japanese METI-qualified OEMs require valve manufacturers to qualify secondary foundries in China's Jiangsu province and India's Maharashtra industrial belt. Brass and stainless steel architectures draw from copper-zinc concentrate streams anchored in Chile and Peru, with austenitic grades sourcing nickel from Indonesian processing hubs. Single-source vulnerability concentrates in REACH-compliant coating qualification, where trivalent chromium alternatives face eighteen-to-twenty-four-month validation timelines. Distribution runs through refrigeration OEM rack assemblers in Germany, cold storage EPC contractors in India, and direct-to-fleet telematics integrators in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The refrigeration valves market compounds steadily as Kigali Amendment retrofit deadlines force recurring recertification cycles across installed base replacement. Cold chain infrastructure buildouts in Asia-Pacific and ammonia warehouse construction in India provide durable demand anchors.
For Market Incumbents: To counter margin erosion from commodity brass price volatility, anchor position through backward integration into Ningbo-Jiangsu foundry partnerships and captive supply of REACH-compliant coating chemistries. Deepen certification investment under China's NMPA GB standards and EU Pressure Equipment Directive to extend product launch timeline advantages over uncertified imports.
For New Entrants and Emerging Players: Launch via telematics-integrated solenoid valve arrays targeting refrigerated transport fleet operators in California and Texas seeking predictive maintenance capabilities. Penetrate the Indian cold storage deficit through industrial ammonia valve system partnerships with Maharashtra and Gujarat warehouse developers negotiating government-backed performance contracts.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized refrigeration component fabricators lacking electronic expansion valve controller integration. Long-term viability hinges on transcritical CO2 expertise transferability to carbon capture and energy storage applications. Watch for divergence between EU F-Gas Regulation retrofit acceleration and Chinese domestic OEM import substitution as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Yangtze River Delta foundry additions target transcritical CO2 valve volume for Kigali retrofit deadlines. |
| Backward Integration | Captive brass casting capacity insulates margin structures from Chilean concentrate supply disruptions. |
| Long-term Supply Agreement | German supermarket chains lock electronic expansion valve volumes with demand-response controller bundling. |
| Joint Venture | Indian cold storage EPC partnerships secure ammonia valve procurement under government warehouse programs. |
| Technology Licensing | Aerospace-derived sealing expertise from Parker Hannifin transfers to industrial refrigeration corrosion resistance. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with refrigeration OEM procurement directors, cold chain logistics fleet managers, industrial ammonia plant engineers, and pressure equipment certification specialists with secondary validation through customs trade data, EPA SNAP program filings, EU F-Gas Regulation quota disclosures, and NMPA GB standards documentation. Bottom-up valve shipment aggregation and top-down cold chain infrastructure investment triangulation anchored market sizing.
Historical reference periods spanning pre-Kigali Amendment baseline through current retrofit cycle acceleration informed the projection horizon. Segmentation modeling incorporated valve type, material grade, application intensity, and control method sophistication across commercial cooling, industrial refrigeration, residential systems, and transport refrigeration end-uses. CAGRs derived from pressure equipment certification timeline analysis, refrigerant-phase transition velocity, and regional cold chain buildout intensity curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under divergent national pressure-equipment code harmonization scenarios. Deviation in EU-China regulatory alignment on flammable refrigerant safety standards would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Emergency Shut Down Valves (ESDV) Market
Valves
Tank Hydrogen Valve Market
Valves
Valve Remote Control System Market
Valves
Water Draw Off Valves Market
Valves
Mobile Hydraulic Valves Market
Valves
Hybrid Valve Market
Valves
Oil Drain Valves Market
Valves
Pneumatic Positioner Market
Valves
Magnetic Coupler Market
Valves
Industrial Hydraulic Filters Market
Valves
Global Plastic Valves Market
Valves
Global Valves Market
Valves
Global Compression Packing Market
Valves
Pulsation Dampeners Market
Valves
Actuators and Valves Market
Valves
Large Bore Vacuum Insulated Pipe Market