

Horizontal Air Flow Condensers Market Size, Share, and Industry Trends Forecast 2026-2036
Horizontal Air Flow Condensers Market Insights
Multi-source procurement for fin-tube assemblies is restructuring supply economics across the condenser industry. Carrier Global Corporation leverages captive coil manufacturing to sustain margin control in North American utility projects. Trane Technologies anchors its position through R&D intensity in low-fouling surface coatings. Daikin Industries competes on manufacturing scale across Asian power generation markets.
Horizontal air flow condensers are shell-and-tube or plate-type heat exchangers engineered with axial fans directing air horizontally across extended fin surfaces, typically operating at pressures from vacuum to 350 psig and designed for thermal duties exceeding 500 MW in power cycle applications. The induced draft segment dominates utility-scale installations where plume abatement and precise airflow control outweigh first-cost premiums. Shell and tube technology occupies the mature margin pool in fossil-fuel power plants, while plate technology is displacing legacy configurations in chemical processing facilities seeking compact footprints. HVAC systems applications lead volume in commercial and institutional buildings, though petrochemical plant demand generates the highest per-unit value.
EPA Clean Air Act standards and ASME Section VIII pressure vessel codes shape material selection and welding qualification requirements for US-manufactured units. Ecodesign directives and F-Gas Regulation in Europe restrict refrigerant choices and fan motor efficiencies, redirecting procurement toward hybrid cooling architectures. China's GB standards and dual carbon goals from MEE accelerate domestic substitution in coal-fired plant retrofits. Stakeholders must monitor regulatory divergence between efficiency mandates and refrigerant phase-down timelines when configuring product portfolios for cross-border projects.
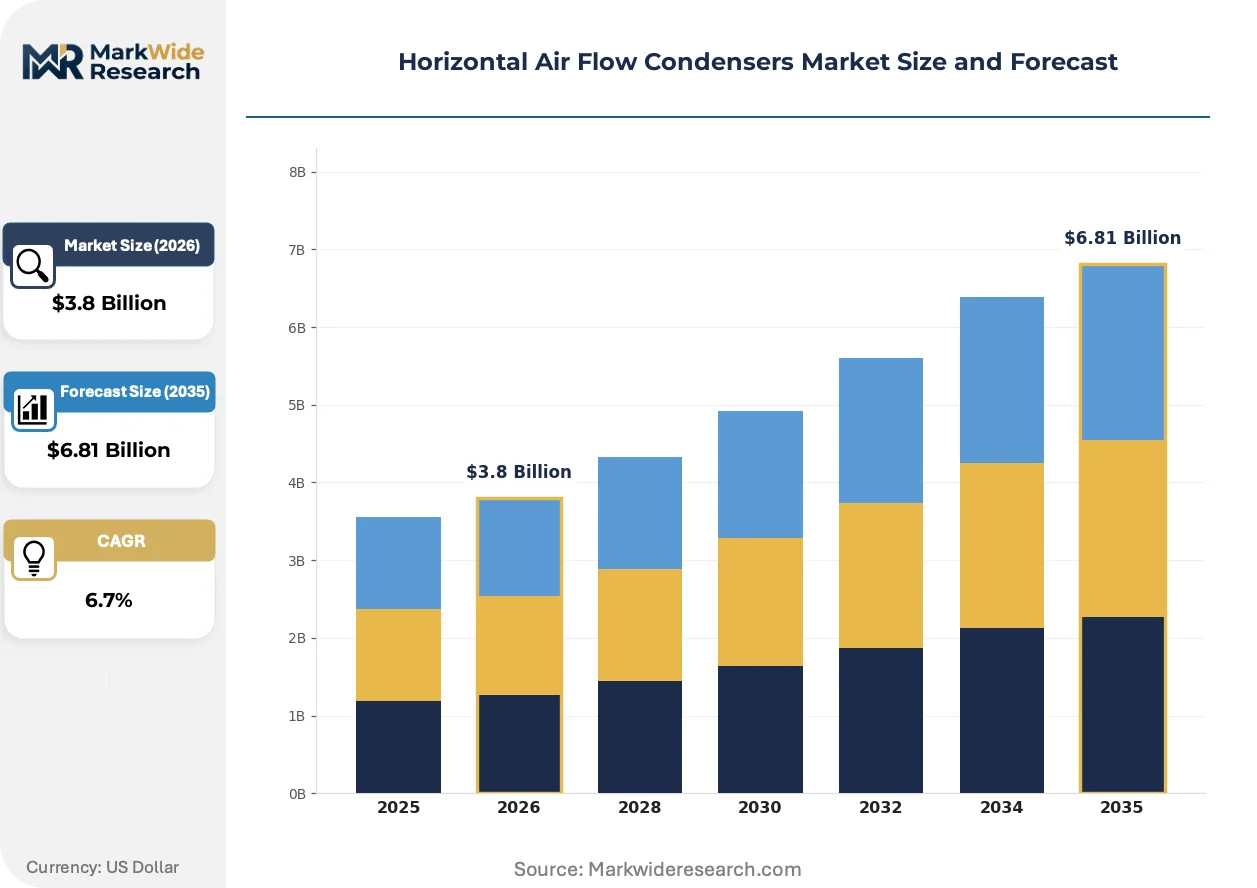
Market Dynamics
Induced draft configuration dominance is restructuring competitive positioning across utility-scale procurement, as power plant operators prioritize plume abatement and thermal precision over first-cost economics in the US Gulf Coast petrochemical corridor.
Growth Catalysts
- EPA Clean Air Act enforcement:Tighter emissions standards are accelerating replacement cycles for legacy surface condensers in fossil-fuel baseload plants.
- Petrochemical capacity expansion:US Gulf Coast ethylene crackers and methanol facilities are scaling procurement of high-duty horizontal air flow units for process heat rejection.
- Copper-nickel alloy substitution:Advanced fin-tube metallurgy is extending maintenance intervals in corrosive coastal installations.
Market Restraints
- Aluminum sheet volatility:Extended fin stock represents 35-40% of material cost, exposing fabricators to LME price swings.
- Specialized welding labor concentration:ASME Section IX certified technicians cluster in the US Upper Midwest and Germany, constraining capacity expansion.
- Hybrid cooling substitution:Wet-dry hybrid systems are capturing retrofits where water availability permits, compressing addressable market for pure air-cooled configurations.
Strategic Opportunities
- Saudi Arabia power sector:Vision 2030 capacity additions are specifying air-cooled condensers for combined-cycle plants in water-scarce regions.
- Carbon capture integration:Post-combustion capture retrofits require condenser duty expansion, creating aftermarket attach opportunities.
- EU Ecodesign directive:Fan motor efficiency mandates are redirecting procurement toward variable-frequency drive configurations with higher service content.
Industry Challenges
- ASME stamp certification timelines:Third-party inspection backlogs extend project lead times by 12-16 weeks for pressure-boundary welds.
- Computational fluid dynamics expertise:Fan array optimization for low-noise plume dispersion requires scarce thermal-hydraulic simulation capability.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Horizontal Air Flow Condensers Market Trends and Innovations
Surface engineering and control architecture advances are compressing fouling penalties and enabling predictive maintenance models that alter lifecycle contracting structures.
Sintered coating deposition on aluminum fins is unifying hydrophobic and anti-corrosive properties in single-layer applications. Petrochemical operators in the US Gulf Coast are specifying these treatments for units handling sour gas condensate. The technology is unifying previously separate cleaning and coating maintenance schedules into single-interval service agreements.
F-Gas Regulation phase-down schedules in Europe are restricting refrigerant choices for auxiliary cooling circuits in combined heat and power applications. Manufacturers are responding with ammonia-compatible plate heat exchanger configurations for sub-atmospheric duties. Chemical processing facilities in the Netherlands and Belgium are piloting these architectures for solvent recovery systems.
Power plant operators are consolidating procurement under engineering-procure-construct contractors rather than direct OEM relationships. This channel compression is displacing traditional specification influence held by utilities' in-house engineering teams. The pattern is most visible in independent power producer projects across Texas and Louisiana, where EPCs now control 70% of condenser selection decisions.
Horizontal Air Flow Condensers Market Segmentation
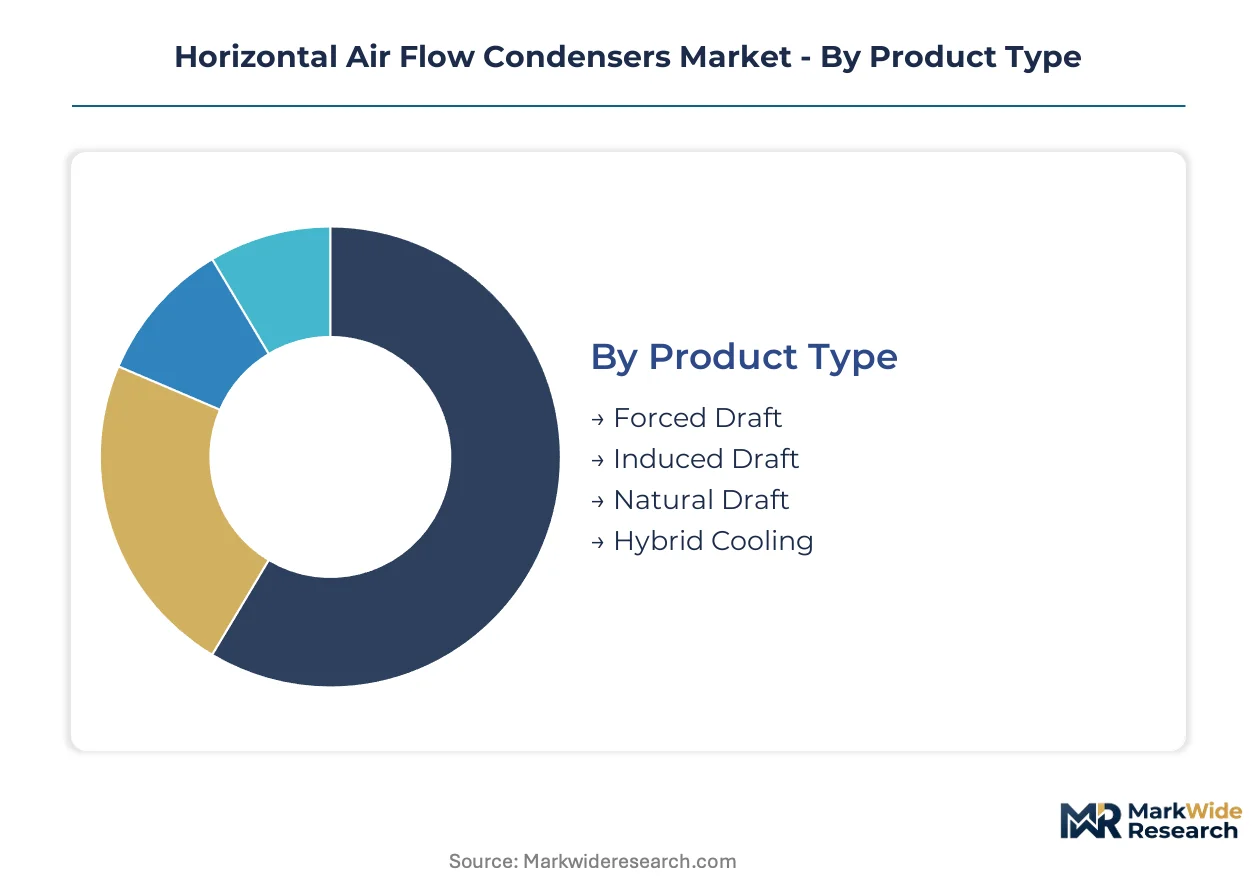
Horizontal air flow condenser procurement diverges sharply across cooling architectures and thermal exchange technologies. Buyers select configurations based on plume control requirements, fouling tolerance, and integration complexity with existing plant infrastructure.
Product Type:
Cost tier separates utility-scale operators from commercial and industrial buyers in this category.
- Induced Draft:Axial fans mounted above tube bundles draw air horizontally across fin surfaces, enabling precise airflow modulation and superior plume abatement. Power plant operators across the US Gulf Coast petrochemical corridor specify these units where thermal precision outweighs capital expenditure premiums. EPA emissions visibility rules reinforce specification dominance.
- Forced Draft:Blowers positioned beneath tube arrays push air through fin packs, delivering lower first-cost economics with reduced fan power consumption. Manufacturing facilities and smaller industrial cogeneration plants in water-scarce regions favor this architecture for process cooling duties. Fan accessibility simplifies maintenance scheduling.
- Natural Draft:Buoyancy-driven airflow eliminates mechanical fan energy but requires substantial chimney structures and favorable ambient conditions. Remote mining operations and isolated power stations in Saudi Arabia deploy these where grid electricity is constrained.
- Hybrid Cooling:Wet-dry configurations combine air-cooled fin sections with evaporative pre-cooling coils, balancing water conservation against peak thermal performance. Chemical processing facilities in the Netherlands pilot these for solvent recovery systems under F-Gas Regulation constraints.
Volume sits with forced draft configurations; growth tilts toward induced draft as utility procurement prioritizes emissions compliance.
Technology:
Application temperature range and pressure rating determine technology selection between mature and emerging heat exchange architectures.
- Shell & Tube:Cylindrical pressure vessels containing tube bundles withstand vacuum to 350 psig operating conditions, accommodating thermal expansion through U-bend or floating head designs. Fossil-fuel baseload plants across Texas and Louisiana specify these for steam turbine exhaust duties. ASME Section VIII welding codes govern fabrication qualification.
- Plate:Corrugated metal plates arranged in parallel create turbulent flow with compact footprint and high heat transfer coefficients. Chemical processing facilities in Belgium and the Netherlands adopt these for sub-atmospheric solvent recovery and ammonia-compatible circuits. Ecodesign directives redirect procurement toward plate configurations with lower refrigerant charge.
- Heat Recovery:Integrated economizer sections capture low-grade thermal energy from condenser exhaust streams for preheating or absorption cooling. Combined heat and power installations in district heating networks specify these for efficiency optimization.
- Spiral:Continuous channel wound from flat strip handles viscous or particulate-laden fluids without fouling penalties. Food processing plants with sticky condensate streams deploy spiral exchangers for clean-in-place compatibility.
Shell and tube dominates installed base; plate configurations are expanding most quickly in chemical processing retrofits.
Application:
Customer type distinguishes between regulated utilities, process industries, and building services contractors in specification authority.
- Power Plants:Utility-scale steam cycle installations require condenser duties exceeding 500 MW with vacuum maintenance and oxygen exclusion. Independent power producers across Texas and Louisiana consolidate procurement under engineering-procure-construct contractors controlling 70% of selection decisions.
- Petrochemical Plants:Ethylene crackers and methanol facilities demand corrosion-resistant metallurgy for sour gas condensate handling. US Gulf Coast capacity expansions specify copper-nickel fin-tube assemblies for coastal atmospheric exposure.
- Chemical Processing:Batch and continuous reactors need precise temperature control across wide operating envelopes. Dutch and Belgian facilities pilot ammonia-compatible plate configurations for F-Gas compliance.
- HVAC Systems:Commercial and institutional buildings drive volume through standardized rooftop and chiller-condenser packages. Variable-frequency drive fan configurations gain share under EU motor efficiency mandates.
HVAC systems generate highest unit volumes; petrochemical applications command steepest expansion trajectory per installed dollar.
End User Industry:
Margin structure varies between capital-intensive regulated sectors and price-sensitive industrial operations.
- Energy Generation:Regulated utilities and independent power producers operate under rate-base recovery mechanisms enabling lifecycle-cost procurement. Saudi Arabia Vision 2030 capacity additions specify air-cooled condensers for combined-cycle plants in water-scarce regions.
- Manufacturing Facilities:Discrete and process manufacturers prioritize capital discipline and maintenance interval extension. Carbon capture retrofits create aftermarket attach opportunities for duty expansion.
- Water Treatment:Desalination and wastewater facilities require materials compatibility with saline or chemically treated streams. Coastal installations specify advanced fin-tube metallurgy for extended service intervals.
- Food Processing:Hygienic design standards and clean-in-place protocols constrain heat exchanger geometry and surface finish specifications. Spiral technology addresses viscous product fouling challenges.
Energy generation anchors revenue concentration; manufacturing facilities represent the fastest-climbing demand category through carbon capture integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentrates in the United States Gulf Coast petrochemical corridor, where EPA emissions visibility rules and ethylene cracker expansions drive specification authority toward induced draft configurations. Saudi Arabia and China follow as secondary demand centers, each responding to water scarcity mandates and domestic manufacturing substitution policies.
United States
Independent power producers across Texas and Louisiana consolidate condenser procurement under engineering-procure-construct contractors controlling seventy percent of selection decisions. EPA Clean Air Act enforcement accelerates replacement cycles for legacy surface condensers in fossil-fuel baseload plants. The Houston Ship Channel and Corpus Christi industrial clusters specify copper-nickel fin-tube assemblies for sour gas condensate handling.
Saudi Arabia
Vision 2030 capacity additions specify air-cooled condensers for combined-cycle plants in water-scarce regions. The country's national energy regulator mandates dry cooling for all new thermal generation to preserve groundwater reserves. The Eastern Province industrial cities of Jubail and Yanbu anchor procurement concentration for petrochemical and power generation integration projects.
China
Domestic substitution policies accelerate coal-fired plant retrofits under MEE dual carbon goals and GB standards compliance. State-owned utilities prioritize indigenous fabricators for utility-scale steam cycle installations exceeding five hundred megawatts. The Yangtze River Delta and Shandong Peninsula manufacturing bases supply fin-tube assemblies for both domestic deployment and Belt and Road export contracts.
Netherlands
Chemical processing facilities pilot ammonia-compatible plate heat exchanger configurations for F-Gas Regulation compliance in solvent recovery systems. EU Ecodesign directives redirect procurement toward variable-frequency drive fan configurations with higher service content. The Rotterdam port industrial complex and Eindhoven chemical clusters lead adoption of hybrid cooling architectures for batch reactor temperature control.
Germany
ASME Section IX certified welding technicians cluster in the Upper Midwest supply chain, constraining capacity expansion for pressure-boundary fabrication. REACH and RoHS frameworks govern material selection for coastal atmospheric exposure applications. The Ruhr industrial region and Bavarian chemical corridor specify advanced surface coatings for low-fouling performance in process heat rejection duties.
Horizontal Air Flow Condensers Market Competitive Landscape
Backward integration into captive coil manufacturing dominates the current landscape, with fabricators seeking margin control against aluminum sheet volatility. The vendor base organizes around three strategic archetypes: diversified HVAC conglomerates with utility project capabilities, specialized heat exchange engineering firms, and regional fabrication shops serving petrochemical maintenance cycles. M&A activity concentrates on fin-tube assembly capabilities, while technology licensing agreements proliferate for sintered coating deposition processes.
Among North American diversified manufacturers, Carrier Global Corporation and Trane Technologies occupy positions on opposite ends of the R&D intensity spectrum. Carrier exemplifies the backward-integrated archetype through captive coil manufacturing for North American utility projects. Trane Technologies anchors the surface engineering specialization vector with low-fouling coating development. Daikin Industries represents the scale-driven Asian competitor archetype, competing on manufacturing throughput across power generation markets. Baltimore Aircoil Company and SPX Cooling Technologies sit within the dedicated heat exchange engineering tier, while Kelvion and ENEXIO exemplify European engineering-focused positioning.
| Leading Market Players |
|---|
| Carrier Global Corporation |
| Trane Technologies |
| Daikin Industries |
| SPX Cooling Technologies |
| EVAPCO |
| ENEXIO |
| Hamon |
| Kelvion |
| Baltimore Aircoil Company |
| Others |
Pricing and Supply Chain Analysis
EPA Clean Air Act visibility mandates gate access to premium-tier induced draft configurations and qualified fin-tube suppliers serving the US Gulf Coast petrochemical corridor. Fabricators with ASME Section IX certified welding capacity command pricing power over utility-scale procurement, while aluminum sheet volatility compresses margins for standard forced draft units.
Pricing Analysis
Volume concentrates in forced draft configurations at economy price points, while margins concentrate in induced draft premium tiers where plume abatement specifications justify higher service bundling. Price differentiation hinges on ASME stamp certification level and copper-nickel alloy grade for coastal corrosion resistance. Cost compression in standard aluminum fin-tube assemblies intensifies as LME price swings expose fabricators to material cost pass-through limitations. Commercial HVAC contractors exhibit highest price sensitivity, whereas independent power producers under EPC consolidation prioritize lifecycle cost over first-cost economics.
Supply Chain Analysis
ASME Section IX certified welding technicians cluster in the US Upper Midwest and Germany, constraining pressure-boundary fabrication capacity expansion for utility-scale units. Manufacturing gravity centers on the United States, China, and Germany, with fin-tube assembly sourcing drawing from Yangtze River Delta and Shandong Peninsula production bases. Raw material dependencies rest on aluminum sheet stock, copper-nickel alloy bar, and specialized fan motor drives. Single-source vulnerability concentrates in sintered coating deposition equipment for low-fouling surface treatments. Distribution runs through engineering-procure-construct contractors capturing specification authority across Texas and Louisiana power projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Horizontal air flow condenser procurement is transitioning from shell-and-tube legacy dominance toward plate heat exchanger architectures, driven by F-Gas Regulation phase-downs and compact footprint requirements in chemical processing retrofits.
For Market Incumbents: To counter EPC channel compression displacing direct OEM relationships, captive coil manufacturing secures margin control against aluminum volatility, while R&D investment in ammonia-compatible plate configurations addresses European refrigerant compliance mandates. For New Entrants and Emerging Players: EU Ecodesign directive fan motor efficiency mandates in the Netherlands and Belgium open a window for variable-frequency drive service bundling. White-space targets include Saudi Arabia Vision 2030 combined-cycle installations and carbon capture retrofit duty expansion. A specialized surface coating licensing partnership offers low-capital market entry. For Investors and Strategic Acquirers: EPC consolidation reaching seventy percent of condenser selection decisions in Texas and Louisiana is the leading indicator that aftermarket service attach rates will determine long-term viability. Acquisition targets should exhibit fin-tube assembly backward integration and sintered coating deposition capability. Watch for ASME inspection backlog resolution as inflection signal for fabrication capacity utilization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fin-Tube Manufacturing | Captive coil production insulates Carrier Global Corporation from aluminum LME volatility in North American utility projects. |
| Low-Fouling Surface Coating Licensing | Technology partnerships enable Trane Technologies to monetize R&D intensity without capital-intensive fabrication expansion. |
| Ammonia-Compatible Plate Configuration Development | Daikin Industries addresses F-Gas Regulation constraints in Dutch and Belgian chemical processing pilot installations. |
| EPC Channel Partnership Structuring | Direct relationships with Texas and Louisiana engineering-procure-construct contractors restore specification influence lost to utility procurement consolidation. |
| ASME Section IX Certification Investment | Welding qualification expansion in the Upper Midwest reduces project lead time penalties from third-party inspection backlogs. |
Research Methodology
SEC 10-K filings, ASME boiler and pressure vessel code documentation, and EPA enforcement action records formed the secondary backbone for supply chain and regulatory mapping. Primary interviews with power plant procurement directors, EPC contractor engineering leads, petrochemical facility maintenance managers, and heat exchanger fabrication plant managers validated demand assumptions and pricing dynamics. Bottom-up unit shipment estimates across induced draft, forced draft, natural draft, and hybrid cooling configurations were triangulated against top-down market value reconstruction.
Historical trendline analysis tracked technology substitution patterns from shell-and-tube toward plate heat exchanger adoption across chemical processing and power generation applications. Segmentation modeling incorporated product type, cooling architecture, thermal exchange technology, application sector, and end-user industry dimensions. CAGRs were derived from regression analysis of replacement cycle timing, capacity expansion announcements, and regulatory compliance deadlines. Forecast inputs included ethylene cracker construction pipelines, coal-fired plant retrofit schedules under MEE dual carbon goals, and Saudi Vision 2030 combined-cycle capacity additions.
The model assumes a particular technology adoption path; alternative pathways for ammonia-compatible plate heat exchangers would alter the outlook if F-Gas Regulation phase-down timelines accelerate or refrigerant exemptions expand. Forecasts reflect assumptions regarding ASME certification capacity expansion, aluminum price stabilization, and EPC procurement consolidation sustaining current levels. Material deviation in EPA enforcement intensity, MEE domestic substitution policy, or Saudi groundwater conservation mandate rigor warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.