
 Battery Cooling Plate Market | 2026-2036
Battery Cooling Plate Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Cooling Plate Market Intelligence
A shift from single-source OEM contracts to a multi-source procurement model for standardized cooling plates is realigning the competitive landscape for automotive manufacturers. Valeo leverages its extensive Tier 1 automotive relationships to offer integrated thermal management systems. Concurrently, MAHLE specializes in advanced liquid cooling plate technologies with optimized internal channel designs. Modine Manufacturing competes on its expertise in brazed aluminum heat exchangers for heavy-duty and commercial vehicle applications.
A battery cooling plate is a thermal management component designed to dissipate heat from battery cells, often constructed from aluminum with internal micro-channels for coolant flow. Its primary purpose is to maintain a battery pack's optimal operating temperature, ensuring performance, safety, and longevity. Within the product landscape, liquid cooling plates dominate due to their efficiency in Electric Vehicles applications. Active cooling technologies represents the fastest-growing technology segment, displacing simpler passive cooling methods in high-performance systems.
Regulatory frameworks such as the US EPA's vehicle emission standards and China's GB standards for battery safety directly influence cooling plate design specifications. Concurrently, material selection is governed by substance regulations like the EU's REACH, restricting the use of certain chemicals in coolants and plate coatings. Navigating the trade-off between thermal performance, component weight, and manufacturing cost remains the central challenge for system integrators and automotive OEMs.
Market Dynamics
The primary dynamic shaping the market is the technical co-dependency between battery cell energy density and thermal management efficacy. As electric vehicle batteries become more powerful, cooling plates must evolve from simple heat sinks to complex, engineered fluid-dynamic systems.
Growth Catalysts
- Regulatory Mandates:The EU Green Deal and its stringent vehicle emission targets accelerate the transition to electric vehicles, directly expanding the addressable market for battery thermal components.
- Battery Chemistry Evolution:The adoption of high-energy chemistries like NMC 811 requires more sophisticated thermal management to mitigate safety risks, boosting demand for high-performance cooling plates.
- Geographic Concentration:China's dominant position in global electric vehicle manufacturing creates a massive, centralized demand center for all battery components, including cooling plates.
Market Restraints
- Material Cost Volatility:The price of high-grade aluminum, the primary material for plates, is subject to global commodity market fluctuations, creating cost pressure for component manufacturers.
- Technical Design Trade-offs:Engineers face a constant compromise between maximizing the internal surface area for heat transfer and minimizing the coolant pressure drop, which impacts system efficiency.
- Manufacturing Bottlenecks:Advanced capabilities like flux-free aluminum brazing and complex stamping are concentrated among a few suppliers, posing a supply chain risk for automotive OEMs.
Strategic Opportunities
- Grid-Scale Energy Storage:The expansion of Battery Energy Storage Systems (BESS) for utility applications opens a new, large-format industrial market for liquid cooling solutions beyond automotive.
- Immersion Cooling Integration:The convergence of dielectric fluids with plate technology offers an opportunity to develop next-generation, fully integrated immersion cooling modules with superior thermal performance. *Heavy-Duty Electrification: Electrification of commercial trucks and buses in markets like India, supported by policies such as the PLI scheme, creates demand for robust, larger-scale cooling plates.
Industry Challenges
- Lack of Standardization:The absence of a standard battery cell or module format across automotive OEMs prevents the mass production of universal cooling plates, increasing design complexity and cost.
- Long-Term Reliability:Ensuring leak-proof performance and preventing corrosion at the interface between the cooling plate and battery module remains a critical engineering challenge over a vehicle's lifespan.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Cooling Plate Market |
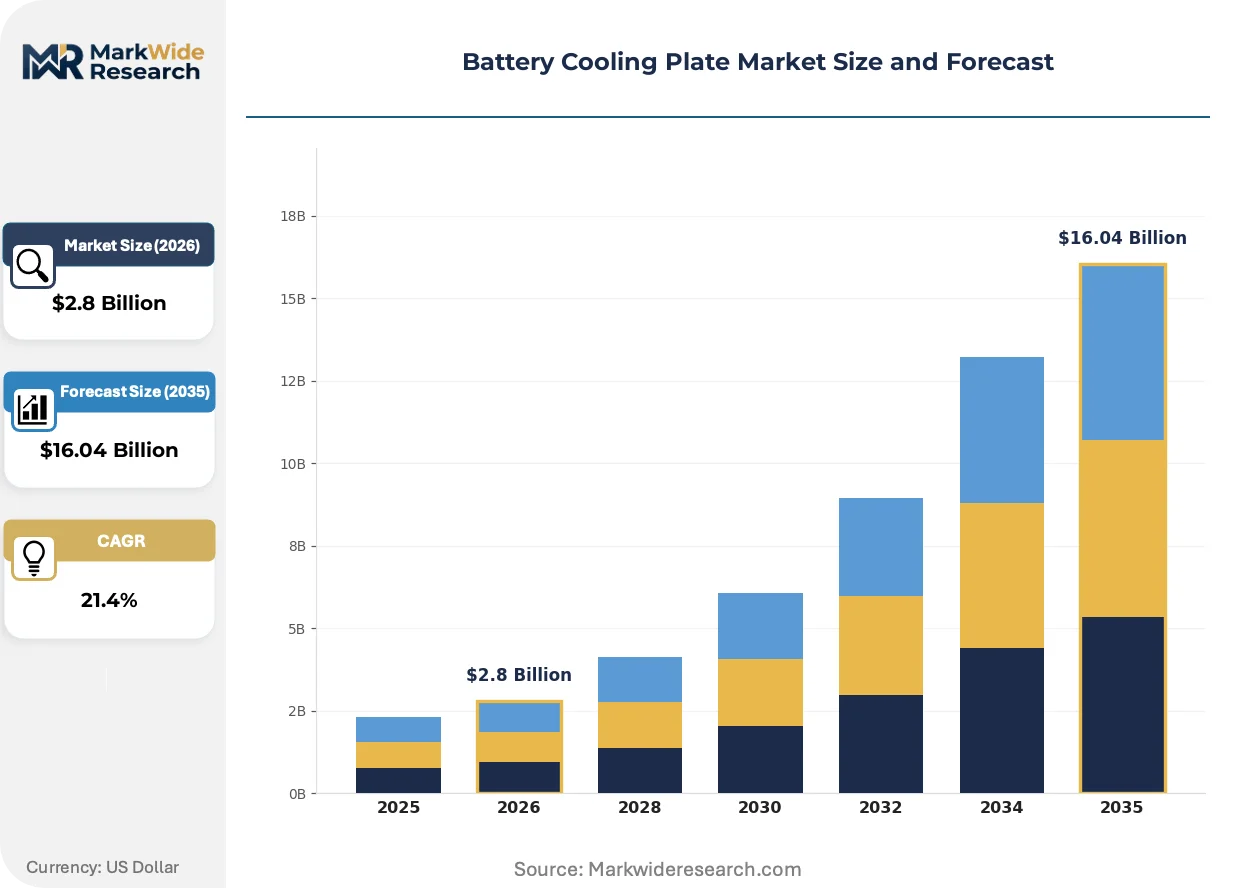
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $16.04 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Cooling Plates, Heat Sink Modules, Air Cooling Plates, Thermal Interface Material Technology: Passive Cooling, Active Cooling, Phase Change Materials, Direct Liquid Cooling Application: Electric Vehicles, Consumer Electronics, Renewable Energy Systems, Industrial Equipment End User: Automotive Manufacturers, Electronics Companies, Energy Providers, Aerospace Sector |
| Companies Covered | Valeo, MAHLE, Modine Manufacturing, Dana, Boyd Corporation, Sanhua Group, Yinlun Holdings, Nippon Light Metal, Sogefi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Cooling Plate Market Strategic Shifts & Innovations
Intensifying performance requirements from electric vehicle manufacturers are driving a parallel evolution in cooling plate materials, design validation, and sourcing strategies. This creates a market where engineering innovation is directly tied to supply chain efficiency and regulatory compliance.
Multi-material cooling plates, combining aluminum with lightweight polymers, function to reduce overall component weight while enabling more complex channel geometries. Electric vehicle OEMs focused on maximizing vehicle range are rapidly adopting these hybrid designs for next-generation battery packs. This integrated material approach is overtaking monolithic aluminum plates in weight-sensitive, high-performance applications.
China’s mandatory GB 38031 standard for electric vehicle safety dictates stringent thermal runaway prevention protocols. This regulation directly impacts cooling plate design, forcing engineers to improve thermal isolation during failure events. The passenger EV segment in China is responding with plates featuring fire-retardant coatings and structural barriers.
A move toward modular battery platforms alters OEM sourcing away from bespoke, single-vehicle components. This change disrupts the model of unique parts for every new car, favoring suppliers with standardized cooling plate architectures. The shift is most visible within high-volume automotive groups in Europe streamlining production across different models.
Battery Cooling Plate Market Segmentation
Understanding the Battery Cooling Plate Market requires dissecting its varied segments, which illuminate distinct technological requirements and end-user demands. This granular analysis reveals how different product types and cooling technologies address specific performance and cost trade-offs. Strategic planning for manufacturers and suppliers depends on identifying these nuanced market pockets.
Product Type:
Buyer decisions within the product type segment are primarily driven by the specific thermal load and packaging constraints of the battery system.
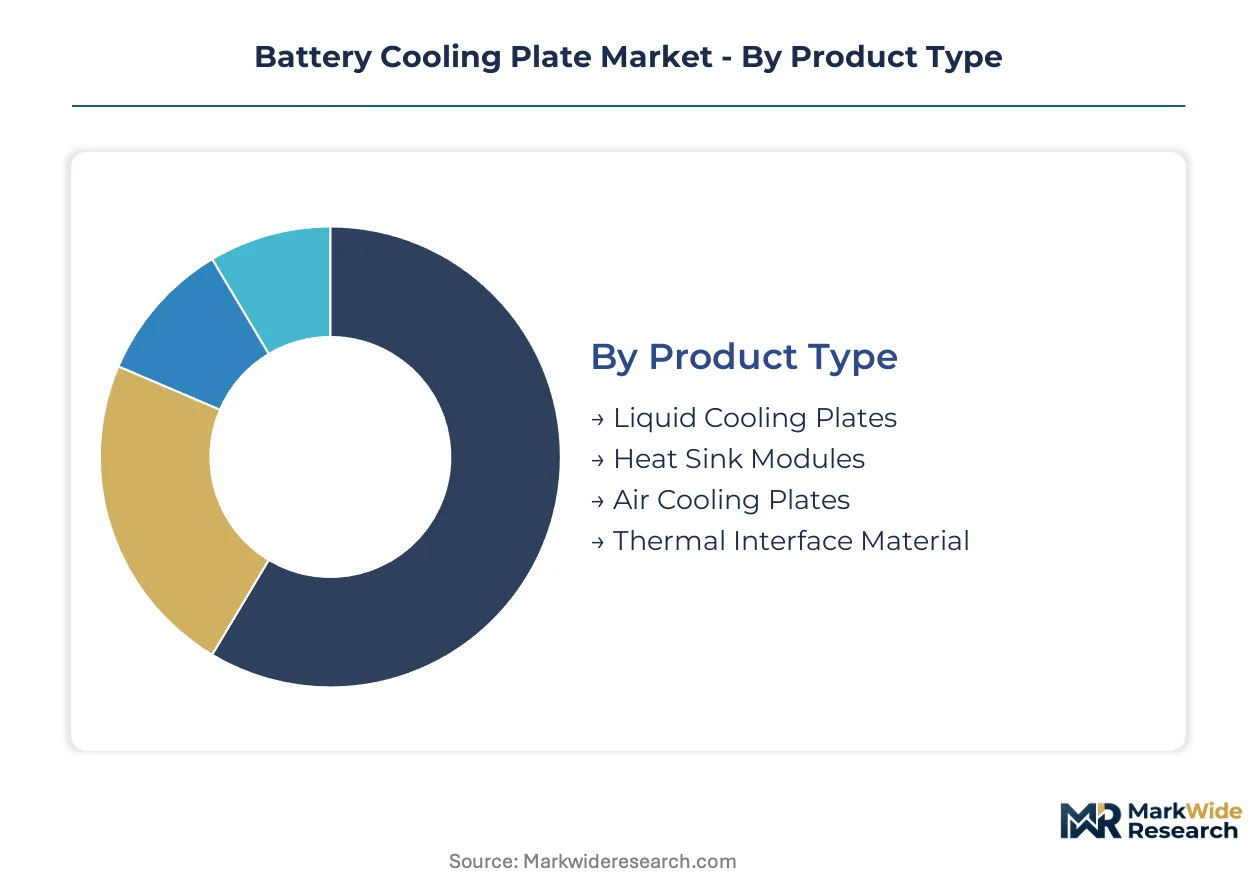
- Liquid Cooling Plates:These components feature internal micro-channels for coolant circulation, offering superior heat dissipation for high-energy density battery packs. Electric vehicle applications in China drive significant demand due to their efficiency in maintaining optimal battery operating temperatures.
- Heat Sink Modules:These simpler metallic structures rely on convection and conduction to dissipate heat from battery cells. Lower power density applications, such as certain consumer electronics, utilize heat sinks for basic thermal management.
- Air Cooling Plates:Utilizing ambient air flow for heat removal, these plates are typically aluminum constructions with finned designs. Cost-sensitive and lower-performance battery systems often employ air cooling due to its simplicity.
- Thermal Interface Material:This material enhances thermal conductivity between the battery cells and cooling plates, minimizing contact resistance. Performance-critical applications, particularly in advanced electric vehicle battery packs, depend on optimized TIM for efficient heat transfer.
Liquid Cooling Plates lead on scale; Thermal Interface Material leads on momentum.
Technology:
The choice of cooling technology directly correlates with the battery's energy density and desired thermal performance in its intended application.
- Passive Cooling:This method relies on natural heat dissipation mechanisms like conduction and convection without external power input. Simpler battery systems in consumer electronics often employ passive cooling due to its low cost and minimal complexity.
- Active Cooling:Utilizing pumps and refrigerants, active cooling systems precisely manage battery temperatures, crucial for high-performance applications. Electric vehicle battery packs, especially those in European markets, increasingly demand active cooling to meet stringent thermal management requirements.
- Phase Change Materials:These materials absorb and release latent heat during phase transitions, providing effective temperature regulation over a narrow range. Emerging applications in compact battery designs are exploring PCM for localized thermal control.
- Direct Liquid Cooling:This advanced technique submerges battery cells directly into dielectric fluids, offering superior thermal management and improved safety. High-power Battery Energy Storage Systems (BESS) and next-generation EV platforms are adopting direct liquid cooling for optimal performance.
Active Cooling technology commands the largest share, while Direct Liquid Cooling is gaining share fastest.
Application:
Application segments are differentiated by the volume of battery packs requiring thermal management and their specific operational environments.
- Electric Vehicles:This segment represents the largest demand for battery cooling plates, driven by the need to manage high thermal loads from powerful battery packs. Regulatory mandates, such as the EU Green Deal, accelerate EV adoption and consequently cooling plate demand in Europe.
- Consumer Electronics:Devices like laptops and smartphones require compact and efficient thermal management solutions for their smaller battery cells. This segment focuses on miniaturization and cost-effective cooling plate designs.
- Renewable Energy Systems:Large-scale Battery Energy Storage Systems (BESS) for grid stabilization and solar/wind integration demand robust liquid cooling solutions. India's PLI scheme for advanced chemistry cell manufacturing supports localized demand for these cooling solutions.
- Industrial Equipment:Heavy-duty machinery and specialized vehicles require durable and high-capacity cooling plates to withstand harsh operating conditions. This segment prioritizes longevity and reliability in thermal management components.
Electric Vehicles dominate the application landscape, with Renewable Energy Systems showing substantial expansion.
End User:
Supply concentration within the end-user segment reflects the specialized procurement processes and technical integration requirements of each industry.
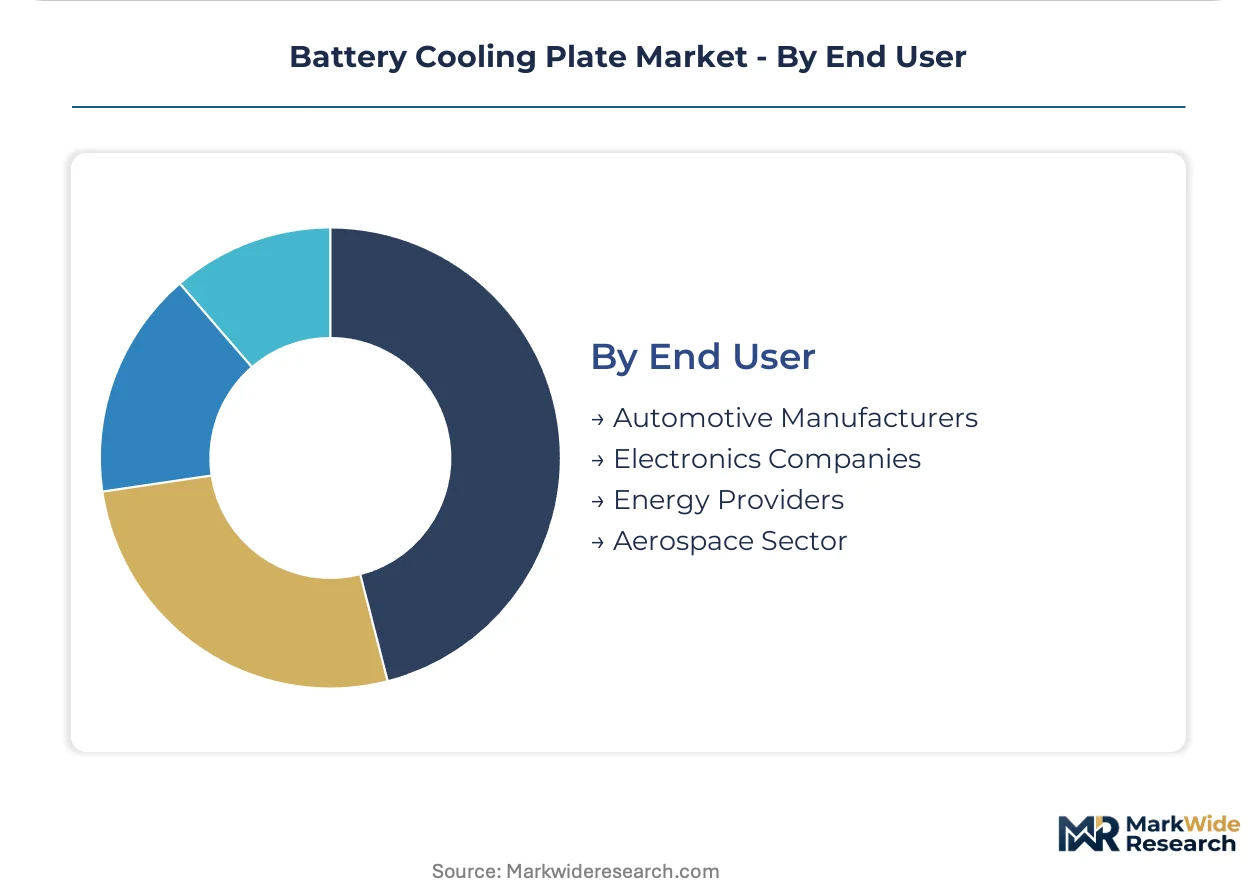
- Automotive Manufacturers:These companies represent the primary end-users, integrating cooling plates directly into electric vehicle battery packs. The shift to multi-source procurement for standardized cooling plates is reshaping supplier relationships for European OEMs.
- Electronics Companies:Manufacturers of consumer electronics incorporate cooling plates into devices to prevent overheating and prolong battery life. This segment often seeks compact and lightweight thermal management solutions.
- Energy Providers:Utilities and independent power producers deploy cooling plates within large-scale Battery Energy Storage Systems. These providers prioritize long-term reliability and efficiency for grid-level energy management solutions.
- Aerospace Sector:This niche segment demands extremely reliable and lightweight cooling plates for specialized aircraft and satellite battery systems. Stringent safety regulations govern material selection and design specifications.
Automotive Manufacturers comprise the largest end-user group, while Energy Providers are emerging as a significant growth area.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global battery cooling plate market exhibits distinct regional dynamics, often influenced by regulatory arbitrage where production gravitates towards regions offering favorable manufacturing costs or less stringent compliance requirements. This strategic realignment of supply chains impacts component sourcing and overall market competitiveness.
China
China's robust electric vehicle manufacturing sector drives substantial demand for advanced battery cooling plates. The nation's GB standards for battery safety directly influence cooling plate design, emphasizing thermal runaway prevention. Manufacturing hubs in the Yangtze River Delta concentrate production capabilities for these essential thermal management components.
Germany
European Union regulations, particularly the EU Green Deal's emission targets, accelerate the transition to electric vehicles, fueling demand in Germany. Automotive manufacturers in this region prioritize high-performance active cooling systems for their advanced battery packs. Bavaria's automotive cluster leads in integrating sophisticated thermal management solutions into next-generation EVs.
United States
Demand for battery cooling plates in the United States stems from the expanding electric vehicle market and regulatory pressures like the US EPA's vehicle emission standards. These standards push for greater battery efficiency and longevity, requiring effective thermal management. California's pioneering role in EV adoption fosters innovation and demand for advanced cooling technologies.
India
India's push for heavy-duty electrification, supported by policies such as the PLI scheme for advanced chemistry cells, generates specific demand for robust, larger-scale cooling plates. This focus on commercial vehicles necessitates durable thermal solutions tailored to demanding operational environments. The state of Maharashtra is emerging as a significant manufacturing and application hub for these components.
Japan
Japanese automotive manufacturers require sophisticated cooling plate solutions for their diverse electric and hybrid vehicle portfolios. Regulations from METI encourage energy efficiency and advanced battery technologies, directly impacting thermal management needs. The Chubu region, particularly around Nagoya, remains a key center for automotive component innovation and production.
Battery Cooling Plate Market Key Industry Players
Established producers occupy the standard tier, while emerging entrants pursue adjacent spaces like immersion cooling integration or specialized heavy-duty applications. The market structure reflects a blend of specialized thermal management providers and broader automotive Tier 1 suppliers. Strategic archetypes include integrated system providers, material specialists, and application-specific solution developers. Dominant competitive moves involve expanding manufacturing capabilities and forging strategic partnerships with battery cell manufacturers.
Within the integrated thermal management system segment, Valeo exemplifies a Tier 1 automotive supplier leveraging extensive OEM relationships to offer comprehensive solutions. MAHLE, a German engineering firm, sits within the advanced liquid cooling plate specialization archetype, focusing on optimized internal channel designs. Modine Manufacturing, an American company, anchors the heavy-duty and commercial vehicle segment, recognized for its expertise in brazed aluminum heat exchangers.
| Leading Market Players |
|---|
| Valeo |
| MAHLE |
| Modine Manufacturing |
| Dana |
| Boyd Corporation |
| Sanhua Group |
| Yinlun Holdings |
| Nippon Light Metal |
| Sogefi Group |
| Others |
Cost & Logistics Intelligence
Multi-source procurement for standardized cooling plates anchors supply positions for automotive manufacturers, shifting pricing power towards suppliers with efficient production and broad OEM relationships.
Pricing Analysis
Direct-to-OEM discounts are common in the battery cooling plate market, reflecting long-term contractual agreements between suppliers and automotive manufacturers. Pricing operates on a contract-based long-term offtake model, driven by customization levels for specific battery pack architectures and stringent safety certifications like China's GB 38031. Pricing pressure stems from material cost volatility, particularly for high-grade aluminum, impacting component manufacturers. Automotive OEMs are highly price-sensitive for high-volume standardized plates, while specialized applications tolerate higher costs for performance.
Supply Chain Analysis
Regional distribution centers support the just-in-time delivery requirements of automotive manufacturing hubs, particularly in China and Germany. Supply concentration for battery cooling plates centers on China, Germany, and Japan, reflecting their advanced automotive and electronics industries. Raw material dependencies include high-grade aluminum and specialized coolants. Manufacturing bottlenecks, specifically in flux-free aluminum brazing and complex stamping, pose a structural risk. The dominant distribution model is direct-to-manufacturer, ensuring seamless integration into OEM assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Battery Cooling Plate Market functions as a stable compounder, driven by the accelerating global transition to electric vehicles. Stringent regulatory mandates for battery safety and performance ensure consistent, long-term demand.
For Market Incumbents: Cement market leadership through sustained investment in advanced manufacturing capabilities, such as flux-free aluminum brazing, to mitigate supply chain risks. Forge strategic partnerships with battery cell manufacturers to co-develop next-generation integrated thermal management systems. This approach counters the threat of material cost volatility and addresses the lack of standardization across battery module formats.
For New Entrants and Emerging Players: Launch via specialized engineering consultancies targeting emerging applications like grid-scale energy storage and heavy-duty electrification. Focus on developing integrated immersion cooling modules for high-power Battery Energy Storage Systems (BESS), a penetrable segment in India supported by the PLI scheme. This go-to-market angle leverages superior thermal performance for niche, high-value industrial applications.
For Investors and Strategic Acquirers: Roll-up economics work for specialized thermal management providers because of the fragmented nature of advanced manufacturing capabilities. This market offers long-term viability, driven by sustained electrification trends across automotive and grid-scale storage over the next decade. Investors should target material specialists with expertise in multi-material cooling plates. The signal to watch is the increasing adoption of direct liquid cooling technologies in next-generation EV platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces design complexity for OEMs, fostering wider cooling plate adoption across vehicle models. |
| Integrated System Development | Enhances thermal management efficiency, crucial for high-energy density battery packs in EVs. |
| Advanced Material R&D | Decreases component weight and improves thermal performance for next-generation battery designs. |
| Manufacturing Capacity Expansion | Addresses supply chain bottlenecks, ensuring consistent availability for high-volume automotive production. |
| Strategic Partnerships | Secures early design-in opportunities with battery cell manufacturers and automotive OEMs. |
Research Approach
Direct dialogue with OEM platform engineers, Tier 1 thermal system suppliers, and battery cell R&D leads formed the primary research foundation. This qualitative grounding was triangulated with extensive secondary validation from regulatory filings, industry association reports, and patent databases. A rigorous bottom-up and top-down approach ensured comprehensive data collection across the value chain.
The quantitative model produced granular volume and value projections across the analysis window, segmented by product type, technology, application, end-user, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical trends, coupled with projected impacts of market drivers and restraints. Key industry-specific forecast inputs included electric vehicle production forecasts and battery energy density roadmaps.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of extreme material cost volatility or unforeseen regulatory shifts. Forecasts reflect core assumptions regarding electric vehicle adoption rates and technological advancements in battery chemistries. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
United States Heat Pump Market
Cooling Systems
Process Chillers Market
Cooling Systems
Absorption Chillers Market
Cooling Systems
Offshore Air Handling Units Market
Cooling Systems
Industrial Water Cooling System Market
Cooling Systems
Global Scroll and Absorption Chillers Market
Cooling Systems
Heat Pump Dryer Market
Cooling Systems
Cryogenic Systems Market
Cooling Systems
Solar Powered Cold Storage Market
Cooling Systems
Solar Cooling Market
Cooling Systems
Evaporative Condensing Unit Market
Cooling Systems
Seawater Cooling System Market
Cooling Systems
Cold Climate Air Source Heat Pump Market
Cooling Systems
Temperature Controlled Container Market
Cooling Systems
Cooling Tower Rental Market
Cooling Systems
Global Energy Efficient HVAC Systems Market