
 Industrial Radiators Market | 2026-2036
Industrial Radiators Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Radiators Market Analytics
EPA emissions standards for industrial cooling systems is shifting the cost-of-entry calculus toward higher-efficiency designs and advanced materials. Modine Manufacturing Company leverages its thermal engineering heritage to dominate North American heavy-duty applications. API Heat Transfer anchors its position through specialized heat exchanger integration that extends into custom radiator configurations. Stelrad Radiators competes on manufacturing scale across European HVAC and industrial plant installations.
Industrial radiators are heat exchange devices engineered to dissipate thermal energy from fluids or gases, typically constructed with finned tube arrays in aluminum or copper-brass composite configurations rated for pressures exceeding 150 psi and operating temperatures up to 350°F. These systems serve critical cooling functions in power generation turbines, manufacturing process loops, and large-scale engine applications where passive or fan-assisted convection maintains thermal equilibrium. Water-cooled radiators retain the largest installed base across power generation and marine end users due to superior heat capacity and established infrastructure compatibility, while air-cooled variants capture fastest growth in remote manufacturing plants and mobile equipment where water scarcity or freezing risk complicates liquid cooling. Aluminum material share expands as OEMs prioritize weight reduction and corrosion resistance, though copper sustains premium positioning in high-pressure process heating applications.
EPA regulations in the United States mandate minimum thermal efficiency thresholds for industrial cooling equipment, while REACH and RoHS frameworks in Europe restrict hazardous substances in radiator coatings and brazing materials. China's MEE enforces dual carbon compliance timelines that force upgrades at steel and cement plants with outdated cooling infrastructure. Stakeholders must monitor evolving efficiency mandates across multiple jurisdictions to time capital replacement cycles and avoid stranded asset risk from premature obsolescence.
Market Dynamics
Thermal efficiency mandates from China's MEE and the US EPA are forcing synchronous replacement cycles across heavy industry, compressing demand into concentrated procurement windows while elevating specification thresholds for new equipment.
Growth Catalysts
- Dual carbon compliance:China's MEE enforcement timelines at steel and cement plants are accelerating cooling infrastructure upgrades as facilities face hard deadlines for emissions reduction.
- Data center thermal loads:Power generation facilities across Asia-Pacific are expanding heat rejection capacity to serve hyperscale computing clusters with sustained high-density cooling requirements.
- Aluminum fin-tube advances:Brazing process improvements and corrosion-resistant coatings are extending service intervals in marine and coastal installations, reducing total lifecycle cost.
Market Restraints
- Copper price volatility:Brass-copper composite radiators face margin compression when London Metal Exchange copper futures spike, forcing OEMs to absorb cost or pass through to capital-constrained buyers.
- Foundry capacity concentration:High-pressure aluminum die-casting for radiator cores concentrates in eastern Chinese manufacturing zones, creating single-source vulnerability for European and North American assemblers.
- Water-cooled infrastructure lock-in:Established power plants with embedded cooling tower investments face high switching costs that slow air-cooled radiator adoption despite water scarcity risks.
Strategic Opportunities
- India manufacturing corridor:Gujarat and Maharashtra states are attracting process industry investment with state-level incentives, creating localized demand for heavy-duty cooling systems.
- Modular retrofit kits:Pre-engineered radiator replacement packages that minimize plant downtime are capturing maintenance budgets from facilities deferring full system overhauls.
- EU F-Gas Regulation:Phase-down schedules for fluorinated greenhouse gases in industrial cooling are redirecting investment toward dry cooling and ambient heat rejection technologies.
Industry Challenges
- Thermal engineering talent scarcity:Finite element analysis and computational fluid dynamics expertise for custom radiator design concentrates at mid-tier specialists, constraining OEM in-house capability expansion.
- Multi-jurisdiction certification stacking:Equipment destined for international projects must sequentially satisfy ASME, PED, and GB standards, extending qualification timelines and engineering overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Radiators Market |
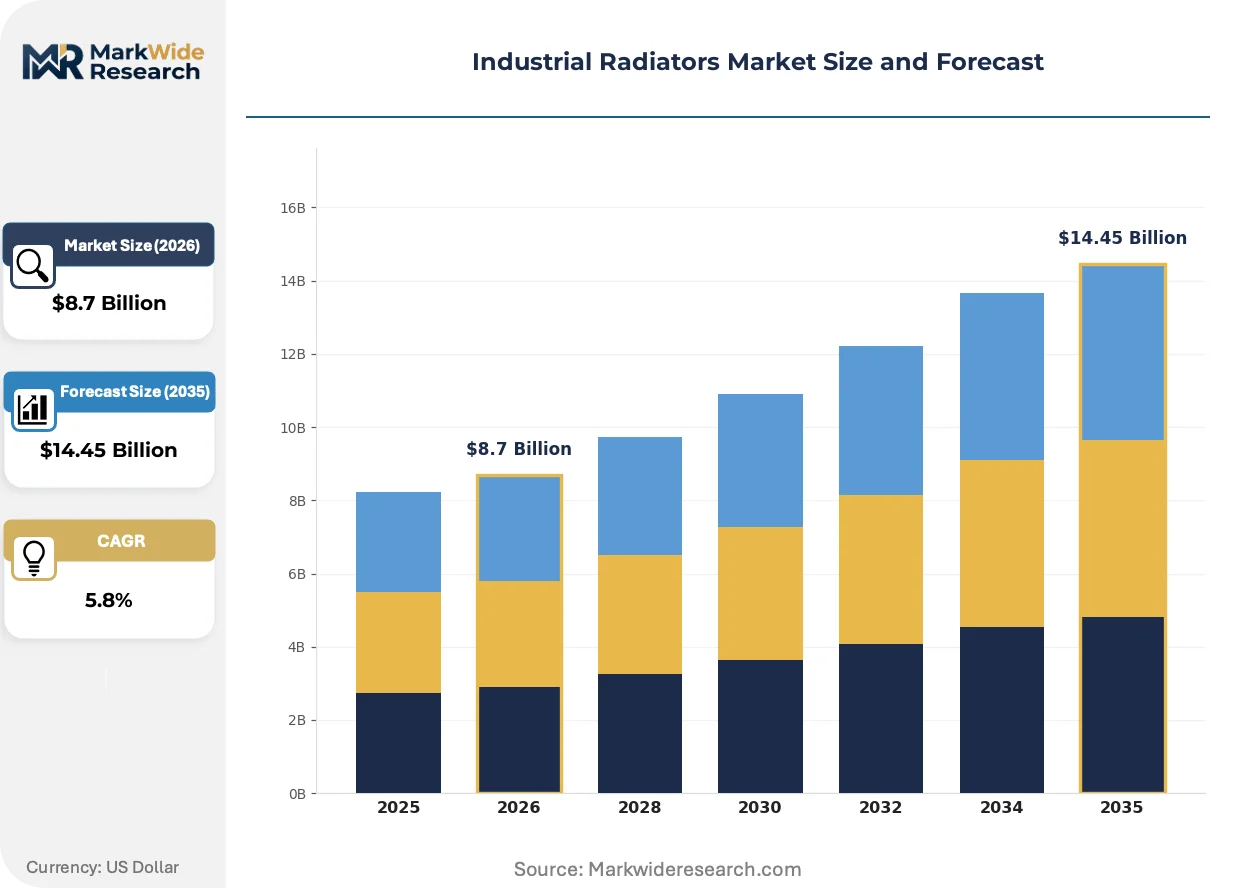
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Cooled Radiators, Oil-Cooled Radiators, Water-Cooled Radiators, Fan Radiators Material: Aluminum, Copper, Steel, Plastic End User: Manufacturing Plants, Power Generation, Automotive, Marine Application: Cooling Systems, HVAC Systems, Engine Cooling, Process Heating |
| Companies Covered | Active Radiator, U.S. Boiler Company, Modine Manufacturing Company, Stelrad Radiators, Runtal Radiators, L&M Radiator, API Heat Transfer, Northern Radiator, Thermal Solutions Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Radiators Market Evolving Landscape
Active thermal management is migrating from passive hardware toward intelligent, condition-monitored systems. Three developments are compressing traditional equipment lifecycles and reshaping supplier-customer relationships.
Additive manufacturing for complex fin geometries is converging with topology-optimized heat transfer surfaces. Aerospace and motorsport suppliers are transferring selective laser melting expertise to industrial radiator production, enabling non-traditional channel configurations that improve air-side heat transfer coefficients. This convergence is compressing the performance gap between custom-engineered and catalog-standard products.
REACH substance restrictions on hexavalent chromium coatings are forcing conversion to trivalent alternatives or ceramic-based surface treatments. European radiator manufacturers face reformulation costs for brazing fluxes and protective finishes, with compliance deadlines cascading through supply contracts. Process heating applications in Germany and France are most affected, with buyers now specifying RoHS-compliant materials in tender documents.
Lifecycle service contracting is displacing transactional equipment sales in power generation and marine segments. Buyers are unbundling capital expenditure from maintenance obligations, awarding ten-to-fifteen-year thermal performance contracts to OEM service arms. This shift is most visible in offshore energy installations where remote monitoring and predictive replacement reduce unplanned outage exposure.
Industrial Radiators Market Segmentation
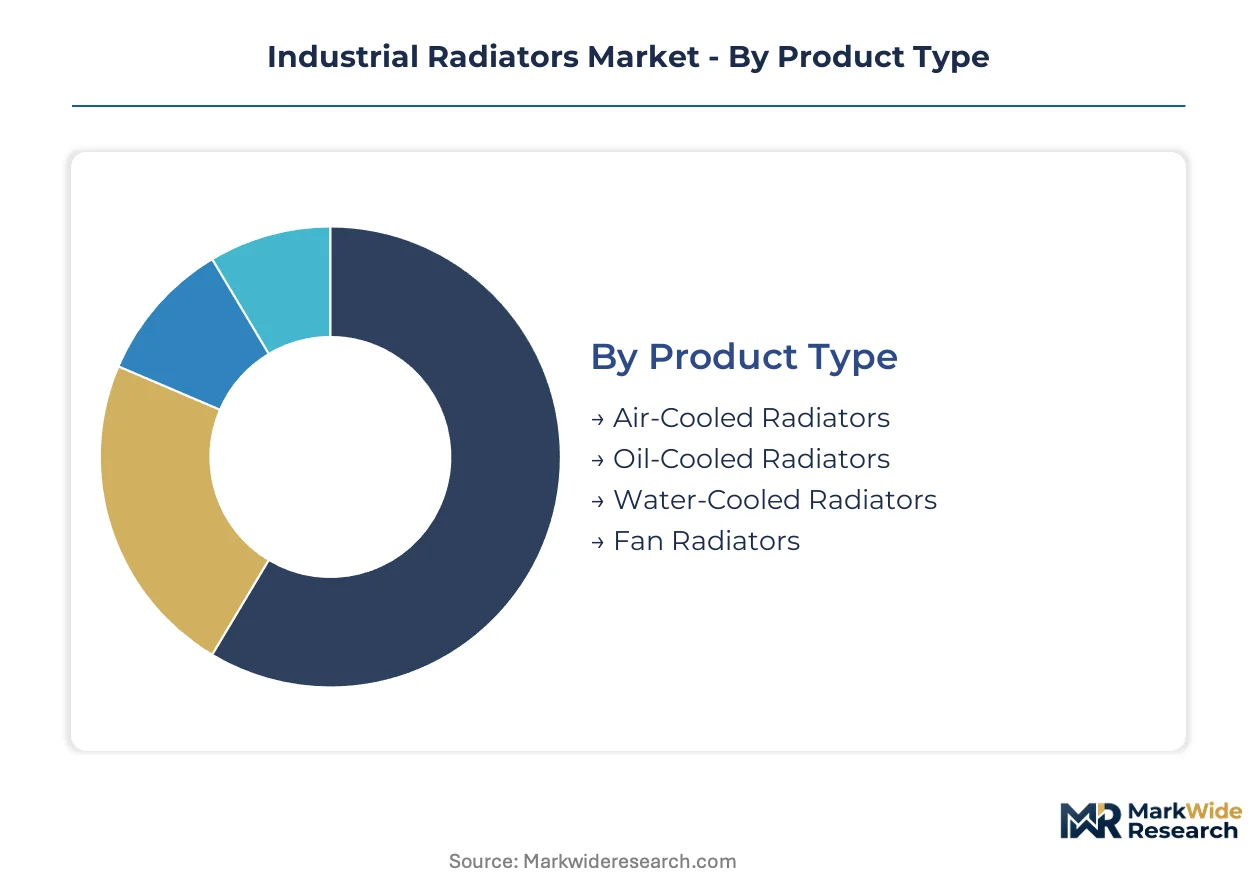
Industrial radiator procurement patterns diverge sharply across cooling media, material specifications, and end-use thermal loads. Buyers prioritize infrastructure compatibility, regulatory compliance timelines, and total lifecycle cost rather than upfront capital expenditure alone.
Product Type:
Cooling medium selection locks facilities into decades of maintenance protocols and fluid management costs.
- Water-Cooled Radiators:Finned tube arrays circulate water-glycol mixtures through aluminum or copper-brass cores, achieving superior heat capacity for sustained high-load operation. Demand concentrates at baseload power generation facilities in India and China where established cooling tower infrastructure reduces switching incentives. Water scarcity risks in Gujarat and Maharashtra manufacturing corridors are beginning to erode this dominance.
- Air-Cooled Radiators:Extended surface fin geometries enable ambient heat rejection without fluid circulation, eliminating freeze protection and water treatment overhead. Remote mining operations in Western Australia and mobile equipment fleets across the US Great Plains are adopting these systems fastest where water access is unreliable or seasonal.
- Oil-Cooled Radiators:Sealed systems dissipate heat from hydraulic fluids and lubricating oils in high-pressure industrial machinery.
- Fan Radiators:Forced convection variants integrate motorized impellers for compact installations with restricted natural airflow.
Volume sits with Water-Cooled Radiators; growth tilts toward Air-Cooled Radiators.
Material:
Material selection trade-offs center on corrosion resistance, weight constraints, and pressure rating requirements.
- Aluminum:Extruded tube and folded fin construction delivers weight reduction and salt spray resistance for marine and coastal applications. China's eastern die-casting zones supply global OEMs, though REACH substance restrictions on hexavalent chromium coatings are forcing European assemblers to qualify alternative surface treatments from domestic suppliers.
- Copper:Brass-copper composite cores sustain premium positioning in process heating above 250 psi where thermal conductivity and fatigue resistance justify raw material cost exposure. German chemical processors and US Gulf Coast refineries specify these alloys for critical loop reliability.
- Steel:Heavy-gauge welded construction serves static installations with minimal corrosion exposure and extreme mechanical durability requirements.
- Plastic:Polymer tank and header components reduce galvanic corrosion in mixed-metal assemblies for light-duty HVAC applications.
Aluminum captures procurement momentum from weight-sensitive segments; copper retains pricing power in high-pressure process environments.
End User:
End-use thermal profiles dictate specification stringency and service contract structures.
- Power Generation:Combined cycle turbines and transformer cooling demand radiators rated for continuous operation at elevated ambient temperatures. China's MEE dual carbon enforcement is compressing replacement cycles at coal and gas facilities facing hard emissions deadlines.
- Manufacturing Plants:Process cooling for metal forming, plastics extrusion, and chemical synthesis requires modular configurations with rapid maintenance access. India's Gujarat and Maharashtra industrial corridors are absorbing capacity from relocated supply chains.
- Automotive:Heavy-duty commercial vehicle and off-highway equipment cooling represents high-volume, specification-driven demand.
- Marine:Salt spray corrosion resistance and compact envelope constraints dominate propulsion and auxiliary system cooling.
Power Generation commands the largest installed base; Manufacturing Plants are expanding most quickly in emerging industrial zones.
Application:
Functional deployment determines whether radiators operate as primary heat rejection or integrated thermal management subsystems.
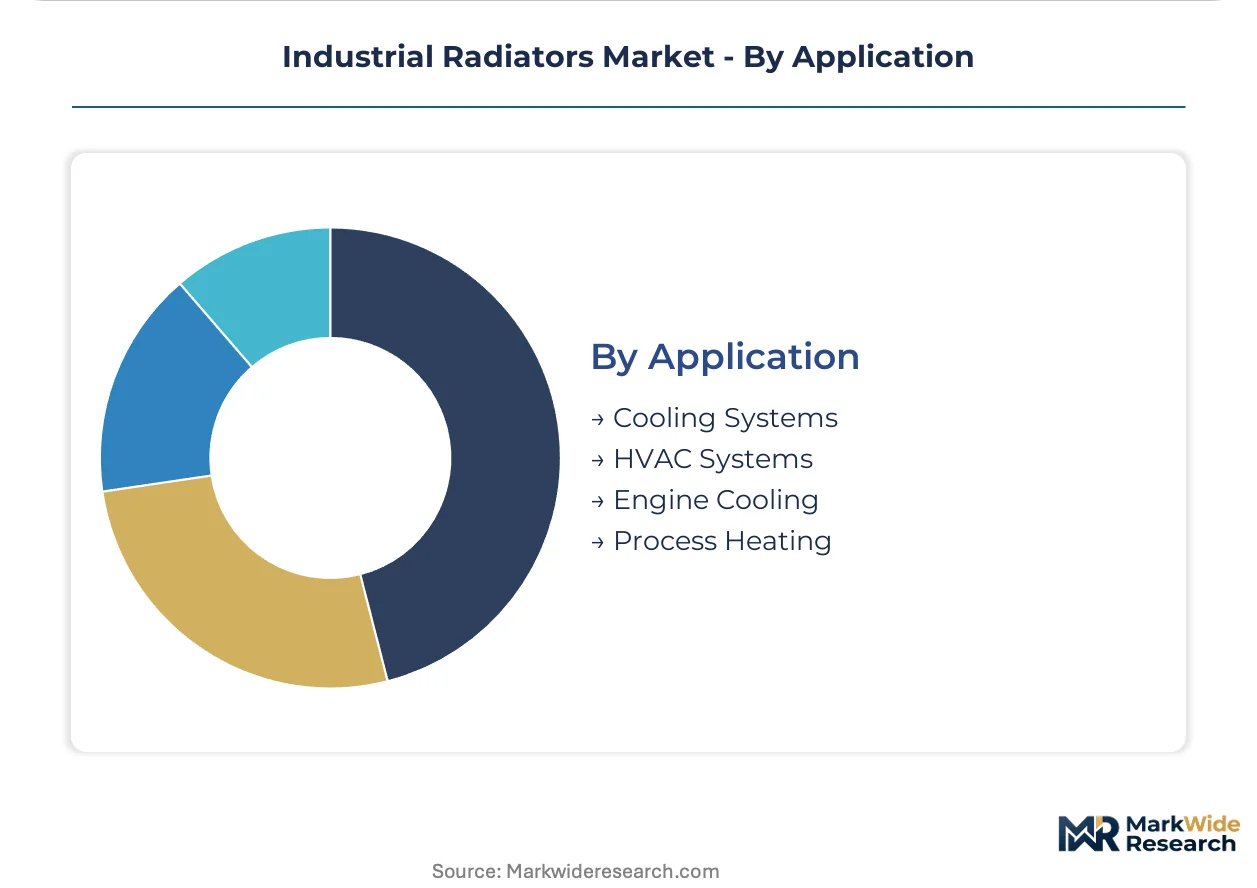
- Cooling Systems:Standalone heat exchangers reject waste thermal energy from closed process loops across power generation and heavy manufacturing. EPA efficiency mandates in the US and China's MEE standards are elevating minimum performance thresholds for new installations.
- HVAC Systems:Building climate control integration prioritizes compact footprints and low acoustic signatures for commercial and industrial facilities. EU F-Gas Regulation phase-down schedules are redirecting investment toward dry cooling alternatives in German and French district heating networks.
- Engine Cooling:Mobile and stationary power unit thermal management requires vibration resistance and transient load response.
- Process Heating:Heat recovery and temperature maintenance applications exploit radiator thermal mass for energy efficiency.
Cooling Systems anchor current procurement volumes; HVAC Systems are gaining share fastest from building efficiency retrofit cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Maharashtra anchor India's manufacturing corridor expansion, while China's eastern die-casting clusters concentrate aluminum radiator core production. Tax incentives and emissions compliance deadlines are synchronizing procurement cycles across heavy industry clusters in multiple jurisdictions.
China
Steel and cement plants in Hebei and Shandong provinces face hard MEE enforcement timelines for dual carbon compliance. The MIIT is tightening industrial cooling equipment efficiency standards through revised GB certification requirements. Yangtze River Delta manufacturing zones supply global OEMs with high-pressure aluminum die-cast radiator cores.
United States
EPA thermal efficiency mandates are compressing replacement cycles at Gulf Coast refineries and Midwest power generation facilities. The agency's emissions thresholds for industrial cooling systems are elevating specification requirements for new installations. Texas and Louisiana petrochemical clusters are absorbing upgraded cooling infrastructure investments.
Germany
REACH substance restrictions on hexavalent chromium coatings are forcing reformulation of brazing fluxes and protective finishes for radiator manufacturers. The EU F-Gas Regulation phase-down is redirecting investment toward dry cooling alternatives in district heating networks. Bavarian and North Rhine-Westphalian chemical processors specify RoHS-compliant materials in tender documents.
India
State-level incentives in Gujarat and Maharashtra are attracting process industry investment with localized demand for heavy-duty cooling systems. The BIS is aligning industrial equipment standards with international pressure vessel codes. Manufacturing corridors around Ahmedabad and Pune are absorbing capacity from relocated supply chains.
Japan
METI efficiency guidelines for industrial thermal management are elevating performance thresholds for power generation and manufacturing applications. JIS standards for heat exchange equipment are undergoing revision to incorporate corrosion-resistant coating specifications. Kansai region heavy industry clusters are upgrading aging cooling infrastructure ahead of regulatory deadlines.
Industrial Radiators Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct specification tiers in the industrial radiators market. The vendor base organizes around thermal engineering heritage, manufacturing scale, and application-specific customization capability. Three strategic archetypes dominate: integrated thermal systems providers, high-volume catalog manufacturers, and custom-engineering boutiques. Competitive moves concentrate on strategic partnerships for foundry capacity access and geographic expansion into state-subsidized industrial corridors.
Among North American fabricators, Modine Manufacturing Company exemplifies the thermal engineering heritage archetype, while API Heat Transfer anchors the integrated systems tier through heat exchanger specialization. Stelrad Radiators occupies a position within the high-volume manufacturing segment serving European HVAC and industrial plant installations. These three companies represent distinct competitive vectors—engineering depth, system integration, and production scale—that structure rivalry across procurement segments.
| Leading Market Players |
|---|
| Active Radiator |
| U.S. Boiler Company |
| Modine Manufacturing Company |
| Stelrad Radiators |
| Runtal Radiators |
| L&M Radiator |
| API Heat Transfer |
| Northern Radiator |
| Thermal Solutions Manufacturing |
| Others |
Value Network & Pricing Analysis
London Metal Exchange copper futures volatility cascades through brass-copper composite radiator production into three-tier pricing structures across premium, standard, and economy levels, with eastern Chinese die-casting concentration amplifying cost pass-through to European and North American assemblers facing REACH coating compliance deadlines.
Pricing Analysis
Short lead-time premiums compress margins for custom-engineered radiator configurations while spot inventory discounts concentrate in catalog-standard aluminum fin-tube products. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and volume scale, with ASME-stamped units commanding sustained premiums. Cost compression in brass-copper tiers is intensifying because LME copper price spikes force OEMs to absorb volatility or surrender orders. Capital-constrained buyers in India's manufacturing corridor exhibit highest price sensitivity; German chemical processors demonstrate lowest.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston anchor hub-and-spoke patterns for finished radiator delivery to power generation and marine end users. High-pressure aluminum die-casting concentrates in China's Yangtze River Delta, with brazing flux and coating inputs drawing from German and Japanese specialty chemical suppliers. Single-source vulnerability concentrates in eastern Chinese foundry zones serving global OEM core production. Distribution runs through authorized service networks for lifecycle contracting in offshore energy installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial radiators market sits in an active technology-transition phase as additive-manufactured fin geometries displace traditional extruded and folded constructions, compressing the performance gap between custom-engineered and catalog-standard products.
For Market Incumbents: Anticipate margin compression from selective laser melting entrants by securing captive foundry capacity in India's Gujarat corridor and accelerating trivalent chromium coating qualification ahead of REACH enforcement cascades. Backward integration into aluminum die-casting insulates against eastern Chinese supply concentration while predictive maintenance service contracts defend installed base relationships against modular retrofit competitors. For New Entrants and Emerging Players: Topology-optimized heat transfer surfaces offer technology-first wedge into aerospace-derived selective laser melting applications for marine and coastal installations where corrosion-resistant coatings command premium positioning. White-space concentrates in India's Maharashtra manufacturing corridor and Western Australian remote mining operations where air-cooled configurations address water scarcity. Go-to-market leverage rests on ten-to-fifteen-year thermal performance contracting unbundling capital from maintenance obligations. For Investors and Strategic Acquirers: Distressed-cycle entries favor custom-engineering boutiques with computational fluid dynamics capability in Germany's North Rhine-Westphalian chemical processing cluster. Long-term viability over a multi-year horizon favors service-integrated OEMs capturing lifecycle value from power generation and marine segments. Watch aluminum price spreads versus copper as inflection indicator for material substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Capacity | Captive aluminum die-casting in India's Gujarat corridor reduces eastern Chinese single-source exposure for European assemblers. |
| Selective Laser Melting Technology Transfer | Aerospace-derived additive manufacturing expertise enables non-traditional fin geometries improving air-side heat transfer coefficients. |
| Trivalent Chromium Coating Qualification | REACH-compliant surface treatments replace hexavalent chromium ahead of cascading supply contract deadlines in German processing. |
| Lifecycle Service Contracting | Ten-to-fifteen-year thermal performance unbundling captures maintenance budgets from offshore energy installations. |
| Modular Retrofit Kit Development | Pre-engineered replacement packages minimize plant downtime for facilities deferring full cooling system overhauls. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews involving plant engineers at power generation facilities, OEM procurement teams, aftermarket service heads, and thermal engineering specialists. EPA enforcement documents, MEE dual carbon compliance timelines, BIS industrial equipment standards, and REACH substance restriction databases provided regulatory validation. Bottom-up unit shipment estimates triangulated against top-down value projections across cooling media, material specifications, and end-use thermal loads.
Granularity-level modeling tracked water-cooled, air-cooled, oil-cooled, and fan radiator configurations separately by aluminum, copper, brass, steel, and plastic material shares across power generation, manufacturing plants, automotive, and marine end users. CAGRs derived from regression analysis of replacement cycle compression under EPA and MEE efficiency mandates, with aluminum price elasticity and foundry capacity utilization as industry-specific demand shapers throughout the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under copper price spike scenarios or sudden REACH coating reformulation accelerations. Periodic stress-testing of base assumptions is recommended, particularly regarding Chinese foundry output disruptions and India manufacturing corridor incentive durability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Global Air Coolers Market
Cooling Systems
Saudi Arabia Desert Air Coolers Market
Cooling Systems
Cold Climate Air Source Heat Pump Market
Cooling Systems
Water Source Heat Pump Market
Cooling Systems
Air to Air Heat Pumps Sales Market
Cooling Systems
Global Evaporative Cooler Market
Cooling Systems
Global Magnetic Refrigeration Market
Cooling Systems
Global Evaporative Cooling Market
Cooling Systems
Heat Pump Dryer Market
Cooling Systems
Process Chillers Market
Cooling Systems
Solar-Assisted Heat Pump Market
Cooling Systems
Solar Fan Market
Cooling Systems
Global Transcritical Co2 Systems Market
Cooling Systems
Three Phase Cooling Fans Market
Cooling Systems
Europe Air Source Heat Pump Market
Cooling Systems
Global Scroll and Absorption Chillers Market