
 Cryosystem Market | 2026-2036
Cryosystem Market Size, Share, and Industry Trends Forecast 2026-2036
Cryosystem Market Analytics
The EU Green Deal is expanding compliance obligations across cryogenic equipment supply chains, compelling manufacturers to redesign refrigeration architectures for lower global warming potential. Linde plc leverages its industrial gas infrastructure to sustain integrated helium logistics across European research corridors. Chart Industries, Inc. anchors its position through specialized cryogenic tank manufacturing for aerospace propulsion systems. Cryomech Inc. differentiates by concentrating on dilution refrigerator technology for quantum computing applications.
A cryosystem comprises engineered equipment designed to generate, maintain, and control temperatures below 123 Kelvin, utilizing vacuum-insulated vessels, specialized compressors, and heat exchangers with aluminum or stainless steel construction to minimize thermal leakage. These systems enable superconductivity research, biological specimen preservation, and industrial gas liquefaction where ambient cooling proves insufficient. Cryogenic freezers command the largest product type position due to entrenched biobanking infrastructure, while helium refrigeration systems represent the fastest-expanding technology segment driven by quantum computing cooling demands. Industrial users generate the highest end-user revenue pool, though research institutions exhibit the steepest adoption trajectory for next-generation superconducting applications.
FDA oversight shapes healthcare cryopreservation standards in the United States, while ECHA's REACH framework governs material compliance for European-manufactured cryogenic vessels, and ISO 20485 establishes international baseline requirements for helium leak detection in vacuum-insulated equipment. Regulatory convergence on fluorinated gas restrictions is forcing equipment redesigns and opening competitive advantage for suppliers with closed-loop recovery capabilities. Stakeholders must monitor emerging quantum computing facility buildouts and evolving superconducting magnet specifications to align R&D roadmaps with downstream cooling requirements.
Market Dynamics
Helium supply concentration and EU F-Gas Regulation compliance deadlines are forcing refrigeration architecture redesigns across cryogenic equipment portfolios. Manufacturers must simultaneously secure rare gas logistics while engineering closed-loop recovery systems.
Growth Catalysts
- Quantum computing facility buildouts:Superconducting qubit arrays require dilution refrigerator infrastructure at scale. Research institutions in Germany, the Netherlands, and France are commissioning specialized cooling capacity.
- EU Green Deal F-Gas Regulation:The 2024-2030 phasedown schedule mandates lower-GWP refrigerants in cryogenic equipment. This accelerates adoption of helium-based and closed-loop systems with recovery capabilities.
- Biobanking infrastructure expansion:Healthcare facilities are scaling cryogenic freezer deployments to support cell therapy manufacturing and precision medicine pipelines. Specimen preservation protocols now demand sub-150 Kelvin storage redundancy.
Market Restraints
- Helium feedstock volatility:Concentrated production in Qatar, Algeria, and the United States creates supply vulnerability. Price spikes disrupt long-term equipment financing and operating cost models.
- Superconducting magnet technical thresholds:NbTi and Nb3Sn conductor performance limits constrain magnetic field density in MRI and NMR applications. Next-generation high-temperature superconductors remain pre-commercial.
- REACH material compliance friction:ECHA substance restrictions on stainless steel alloys and vacuum insulation materials extend European certification timelines by 8-14 months.
Strategic Opportunities
- India biopharma cold chain:CDSCO regulatory harmonization and PLI scheme incentives for biological manufacturing are creating demand for cryogenic logistics infrastructure. Domestic production of liquid nitrogen equipment remains underdeveloped.
- Helium recovery system integration:Closed-loop liquefier technology convergence with IoT monitoring enables predictive maintenance and gas loss minimization. Industrial gas users seek captive recycling to hedge supply risk.
- Space propulsion cryogenic storage:Liquid hydrogen and liquid oxygen tankage for reusable launch vehicles represents an emerging specification segment. Aerospace contractors require flight-qualified insulation systems.
Industry Challenges
- Cryogenic engineer talent scarcity:Specialized expertise in superfluid helium behavior and vacuum system design concentrates at national laboratories and select university programs. Workforce pipeline gaps extend project commissioning schedules.
- ISO 20485 certification complexity:Helium leak detection protocol compliance for vacuum-insulated vessels requires specialized testing facilities. Third-party validation bottlenecks delay product launches.
- Legacy biobank equipment interoperability:Existing freezer fleets use proprietary monitoring protocols. Integration with modern laboratory information management systems demands custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryosystem Market |
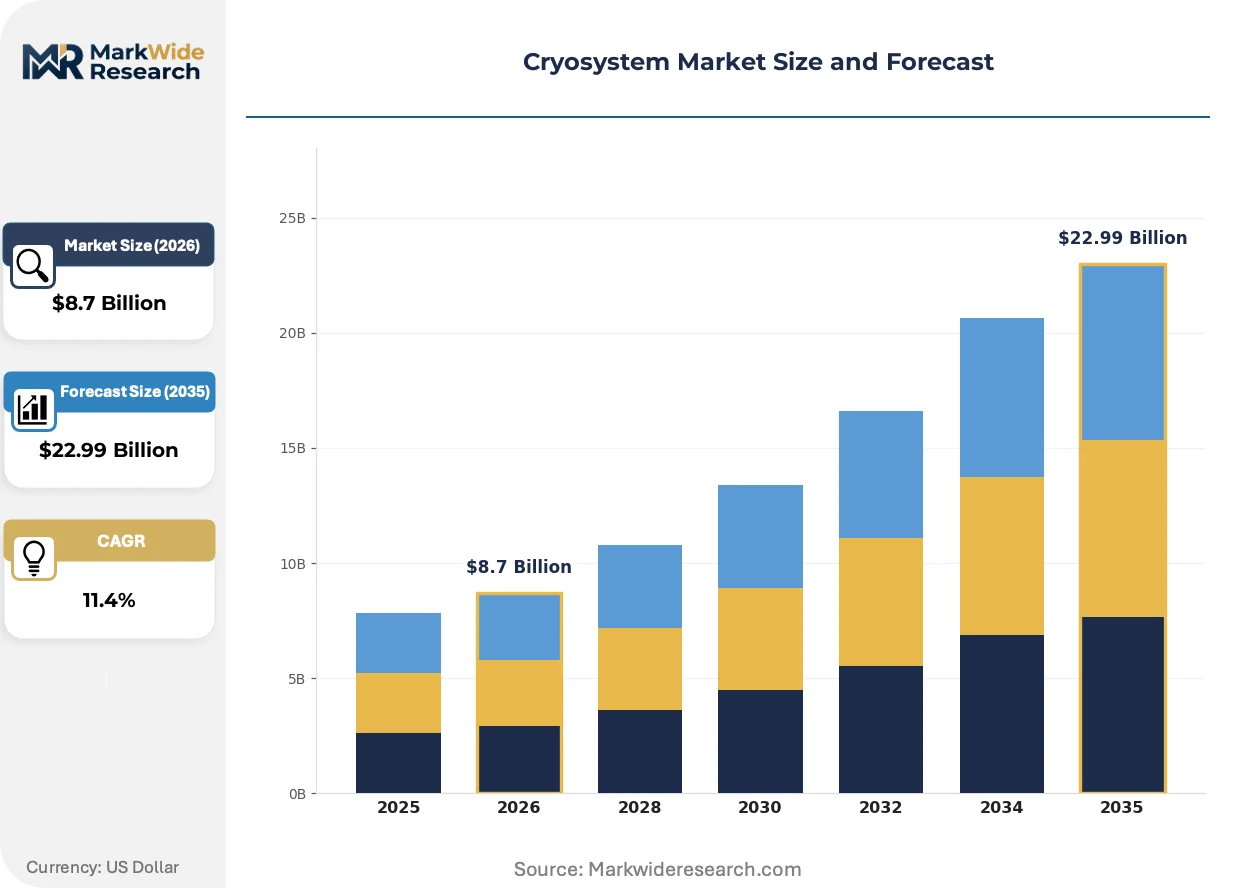
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cryogenic Pumps, Cryogenic Valves, Cryogenic Tanks, Cryogenic Freezers End User: Healthcare Facilities, Research Institutions, Industrial Users, Aerospace Companies Technology: Liquid Nitrogen Systems, Helium Refrigeration, Stirling Coolers, Joule-Thomson Refrigeration Application: Biobanking, Superconductivity Research, Food Preservation, Cryopreservation |
| Companies Covered | Linde plc, Chart Industries, Inc., Air Products and Chemicals, Inc., Cryofab Inc., Air Liquide, Leica Biosystems, Cryomech Inc., Amos Scientific Pty Ltd, Advanced Research Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryosystem Market Evolving Landscape
Active magnetic refrigeration and pulse-tube cryocooler architectures are displacing conventional gas-cycle systems. Equipment manufacturers are reconfiguring product roadmaps around solid-state cooling and vibration-free designs.
Pulse-tube cryocooler technology eliminates moving cold-head components through acoustic resonance heat pumping. Quantum computing laboratories at Delft and Munich are specifying these systems for qubit coherence preservation. The technology is integrating dilution refrigerator pre-cooling stages, compressing mechanical complexity in sub-Kelvin installations.
EU F-Gas Regulation Annex III amendments now classify common cryogenic refrigerants by GWP threshold. Equipment suppliers must redesign heat exchanger architectures to accommodate natural refrigerant alternatives. Medical imaging OEMs in Germany and France face compressed redesign cycles for MRI magnet cooling circuits.
After-sales service unbundling is fragmenting traditional equipment-plus-maintenance bundles. Biobanking facilities now procure cryogenic freezers through capital leases while contracting helium supply and preventive maintenance separately. This pattern concentrates in United States academic medical centers with dedicated procurement functions.
Cryosystem Market Segmentation
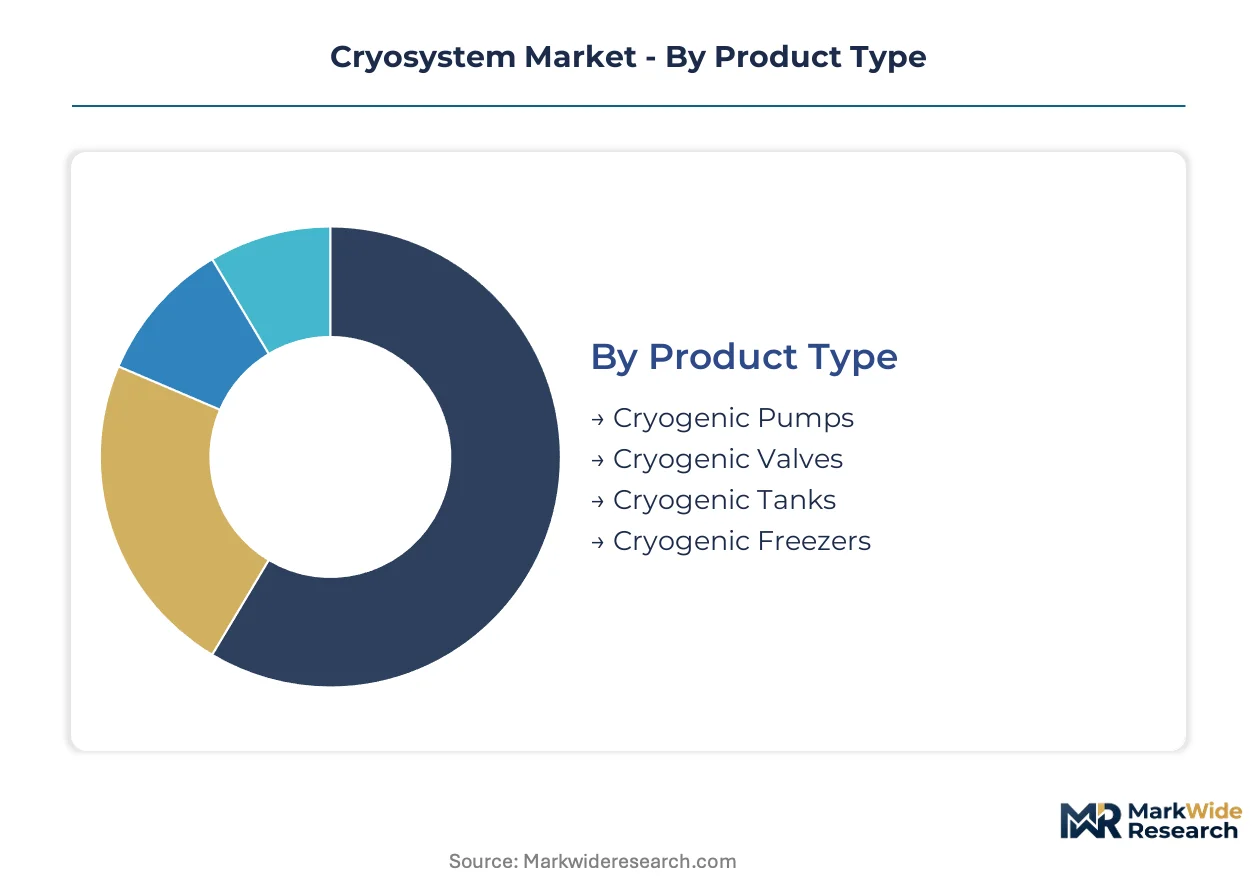
Cryosystem procurement patterns diverge sharply across end-use contexts, with healthcare facilities prioritizing regulatory compliance and uptime guarantees while research institutions optimize for temperature stability at extreme ranges. Equipment specifications, cooling architectures, and service models all pivot on these underlying buyer priorities.
Product Type:
Buyers differentiate primarily by thermal mass requirements and duty cycle intensity, with biobanking operations favoring distributed redundancy and industrial gas users demanding single-point liquefaction capacity.
- Cryogenic Freezers:Vacuum-insulated cabinet systems with aluminum or stainless steel inner chambers maintain temperatures between -150°C and -190°C for biological specimen preservation. Healthcare facilities in Germany and the United States anchor procurement volumes as precision medicine pipelines expand cell therapy storage requirements.
- Cryogenic Tanks:Double-walled vessels with perlite or superinsulation interlayers store liquid nitrogen, liquid helium, or liquid hydrogen at scale. Industrial gas clusters in Germany and aerospace propulsion contractors in France drive specification complexity for higher pressure ratings and extended hold times.
- Cryogenic Pumps:Specialized positive displacement or centrifugal designs handle liquefied gas transfer with minimal heat ingress. LNG terminals and helium liquefaction plants specify these for high-flow, low-NPSH conditions.
- Cryogenic Valves:Extended bonnet designs with vacuum-jacketed bodies isolate cryogenic fluids while preventing stem seal freezing. Distributed across all end-use segments with material grade differentiation by application severity.
Cryogenic freezers lead volumes today; helium-compatible cryogenic tanks are gaining share fastest as quantum computing facility buildouts accelerate.
End User:
Volume concentration and margin structure split across customer types, with industrial users generating the largest revenue pools and research institutions commanding premium pricing for specialized configurations.
- Industrial Users:Air separation plants, LNG facilities, and specialty gas producers operate continuous liquefaction and distribution infrastructure. These buyers in Germany and Qatar prioritize total cost of ownership metrics and captive helium recovery integration.
- Research Institutions:National laboratories and university physics departments require sub-Kelvin cooling for superconducting magnet and quantum computing applications. Facilities in the Netherlands, France, and Germany specify dilution refrigerator pre-cooling stages and vibration-isolated designs.
- Healthcare Facilities:Academic medical centers and cell therapy manufacturers deploy cryogenic freezers for biobanking and cryopreservation protocols. FDA and EMA compliance requirements shape procurement specifications and validation documentation.
- Aerospace Companies:Launch vehicle manufacturers and satellite propulsion developers require flight-qualified liquid hydrogen and liquid oxygen tankage. French and German contractors drive demand for lightweight, high-performance insulation systems.
Industrial users dominate revenue contribution today; research institutions are climbing the fastest as superconductivity research funding expands.
Technology:
Regulatory pressure on fluorinated gas emissions is forcing architecture transitions, with EU F-Gas Regulation compliance deadlines accelerating shifts toward helium-based and natural refrigerant systems.
- Helium Refrigeration:Closed-loop liquefier and recovery systems enable sub-4 Kelvin cooling with gas loss minimization. Quantum computing laboratories in Munich and Delft specify these for qubit coherence preservation, while industrial users seek captive recycling to hedge supply risk.
- Liquid Nitrogen Systems:Open-loop dewar supply or closed-cycle recondensing architectures provide -196°C cooling for biobanking and cryopreservation. Healthcare facilities across Germany and the United States standardize on these for specimen storage redundancy.
- Stirling Coolers:Regenerative thermodynamic cycles with no moving parts at cold temperature enable portable and maintenance-reduced cooling. Emerging applications in distributed sensor cooling and satellite thermal management.
- Joule-Thomson Refrigeration:Expansion-based cooling through porous media or capillary throttling achieves rapid cooldown for infrared detector and sensor applications. Defense and space contractors specify these for tactical system integration.
Liquid nitrogen systems anchor installed base volumes today; helium refrigeration is expanding most quickly as quantum facility commissioning accelerates.
Application:
Specification intensity and service attachment rates vary by use case, with superconductivity research demanding the most complex cooling architectures and food preservation representing the most price-sensitive segment.
- Biobanking:Long-term biological specimen preservation at sub-150 Kelvin with chain-of-custody documentation and redundant monitoring. Healthcare facilities in Germany and the United States scale infrastructure to support cell therapy manufacturing pipelines.
- Superconductivity Research:Sub-Kelvin cooling for quantum computing, NMR spectroscopy, and particle accelerator magnet systems. Research institutions in France, Germany, and the Netherlands commission specialized dilution refrigerator capacity.
- Cryopreservation:Controlled-rate freezing and storage for reproductive cells, tissues, and emerging organ preservation protocols. Fertility clinics and transplant centers drive demand with regulatory-validated equipment specifications.
- Food Preservation:Cryogenic freezing and chilling for processing efficiency and quality retention. Industrial food manufacturers in Germany apply liquid nitrogen tunnel freezers for high-throughput operations with lower capital intensity than mechanical systems.
Biobanking leads application volumes today; superconductivity research shows the steepest expansion trajectory as quantum computing commercialization advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cryogenic engineering originated in European industrial gas laboratories during the early twentieth century, with German chemical conglomerates pioneering commercial helium liquefaction. The industry's geographic footprint now clusters around superconductivity research corridors and biopharma manufacturing zones.
Germany
Industrial gas clusters in North Rhine-Westphalia and Bavaria anchor European helium logistics, with Linde plc operating integrated liquefaction and distribution infrastructure. The EU F-Gas Regulation accelerates equipment redesign timelines for domestic manufacturers. Munich's quantum computing research facilities commission specialized dilution refrigerator capacity from local cryogenic engineering firms.
United States
FDA-validated biobanking infrastructure drives cryogenic freezer procurement across academic medical centers in Boston and the Research Triangle. The EPA oversees fluorinated gas emissions compliance for domestic equipment manufacturers. Houston's energy corridor hosts captive helium recovery installations serving LNG and space propulsion contractors.
France
CEA's superconductivity research programs sustain demand for sub-Kelvin cooling systems at Saclay and Grenoble facilities. ECHA's REACH framework governs material certification for cryogenic vessel construction. Toulouse's aerospace cluster drives specifications for flight-qualified liquid hydrogen tankage in reusable launch vehicle programs.
Netherlands
Quantum computing laboratories at Delft and Eindhoven specify pulse-tube cryocooler architectures for qubit coherence preservation. The EU Green Deal's phasedown schedule compels transition to closed-loop helium recovery systems. ASML's lithography operations create adjacent demand for precision cryogenic components in semiconductor manufacturing.
India
CDSCO regulatory harmonization and PLI scheme incentives for biological manufacturing expand cryogenic logistics requirements across Maharashtra and Telangana. The central bank's infrastructure financing guidelines support cold chain capital investments. Hyderabad's vaccine manufacturing cluster commissions liquid nitrogen distribution networks for cell therapy production.
Cryosystem Market Competitive Landscape
Capital-heavy industrial gas conglomerates compete with specialized cryogenic equipment fabricators across distinct value chain positions. The market structure concentrates around three tiers: integrated gas suppliers with captive helium infrastructure, dedicated cryogenic vessel manufacturers, and niche cooling technology specialists. Strategic moves center on backward integration into rare gas logistics and geographic expansion into quantum computing facility buildouts.
Among integrated gas suppliers, Linde plc and Air Liquide occupy positions spanning helium sourcing through equipment distribution. Chart Industries, Inc. exemplifies the specialized fabricator archetype, while Cryomech Inc. represents the niche technology tier focused on extreme-temperature applications.
| Leading Market Players |
|---|
| Linde plc |
| Chart Industries, Inc. |
| Air Products and Chemicals, Inc. |
| Cryofab Inc. |
| Air Liquide |
| Leica Biosystems |
| Cryomech Inc. |
| Amos Scientific Pty Ltd |
| Advanced Research Systems |
| Others |
Value Network & Pricing Analysis
Industrial gas conglomerates and quantum computing facility developers anchor procurement volumes, concentrating pricing power among suppliers with captive helium logistics and closed-loop recovery capabilities. Their long-term offtake contracts with equipment manufacturers establish reference pricing that filters downstream to healthcare and research segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates equipment transactions, with differentiation driven by ISO 20485 certification grade and after-sales service bundling. Premium tiers command substantial markups for dilution refrigerator systems with sub-Kelvin performance guarantees. Cost compression in standard-tier cryogenic freezers is intensifying because healthcare procurement functions unbundle maintenance contracts from capital leases. Research institutions exhibit the lowest price sensitivity, prioritizing temperature stability specifications over acquisition cost.
Supply Chain Analysis
Helium feedstock supply rests on production concentration in Qatar, Algeria, and the United States, with liquefaction capacity clustering in Germany and the Netherlands. Vacuum-insulated vessel manufacturing draws from specialized aluminum alloy and stainless steel suppliers governed by ECHA REACH material restrictions. Single-source vulnerability in rare gas logistics exposes equipment financing models to commodity price volatility. Distribution runs through industrial gas majors with integrated logistics networks, though specialized fabricators increasingly sell direct to quantum computing facility developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on premium-tier equipment shifts toward quantum computing applications, where sub-Kelvin performance specifications justify substantial pricing premiums over standard biobanking configurations.
For Market Incumbents: Cement market position by deepening backward integration into helium recovery technology and expanding certification capacity for EU F-Gas Regulation compliance. Pulse-tube cryocooler architectures from specialized competitors threaten conventional gas-cycle equipment margins. Priority investment in captive liquefier technology hedges feedstock volatility while locking in long-term service revenue streams. For New Entrants and Emerging Players: The premium-to-economy price gap in cryogenic tanks for aerospace applications creates entry opportunity for flight-qualified insulation specialists. India's biopharma cold chain remains underpenetrated by domestic manufacturers, with CDSCO regulatory harmonization lowering import substitution barriers. Target initial placements through equipment leasing partnerships with Maharashtra-based cell therapy developers. For Investors and Strategic Acquirers: Industrial gas conglomerates are the most active acquirer in this space, seeking dilution refrigerator technology to complete quantum computing cooling portfolios. Five-to-ten year viability favors suppliers with closed-loop recovery capabilities as EU phasedown deadlines harden. Watch helium spot price volatility as inflection indicator for equipment financing model stress.| Strategic Initiative | Industry Significance |
|---|---|
| Helium Recovery System Integration | Captive recycling capabilities hedge supply risk for industrial gas users in Germany and Qatar. |
| Quantum Computing Facility Partnership | Delft and Munich laboratories specify pulse-tube architectures for qubit coherence preservation. |
| EU F-Gas Compliance Redesign | Heat exchanger architectures must accommodate natural refrigerant alternatives by Annex III deadlines. |
| India Biopharma Cold Chain Expansion | Hyderabad vaccine manufacturers commission liquid nitrogen networks for cell therapy production. |
| After-Sales Service Unbundling | US academic medical centers now procure maintenance separately from capital equipment leases. |
Research Methodology
Multiple input streams — cryogenic engineering directors at national laboratories, procurement leads at industrial gas majors, biomedical equipment specialists at academic medical centers, and aftermarket service heads at specialized fabricators — were reconciled against customs trade data, ECHA substance restriction filings, SEC equipment manufacturer disclosures, and quantum computing facility development databases. Bottom-up equipment shipment tallies were cross-validated with top-down industrial gas demand estimates across the analysis window.
Historical capacity deployment patterns were cross-referenced against expert panel input on superconductivity research funding trajectories and biobanking infrastructure buildout timelines. Segmentation modeling spanned product type, end-user category, cooling technology architecture, and application intensity. CAGRs were derived from fitted growth curves incorporating helium supply elasticity parameters and regulatory compliance cost pass-through assumptions.
Caveats apply where EU F-Gas Regulation amendment timing or superconducting magnet technical thresholds could materially shift the outlook. Forecasts embed assumptions about quantum computing commercialization pace and biobank interoperability standards evolution. A small set of triggers — helium spot price spikes, REACH material restriction expansions, and high-temperature superconductor breakthroughs — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Solar Ventilation Systems Market
Cooling Systems
Solar Cold Room Market
Cooling Systems
Solar Air Conditioning Market
Cooling Systems
Air to Air Heat Pumps Sales Market
Cooling Systems
Europe Cooling Systems Market
Cooling Systems
Global Air Coolers Market
Cooling Systems
Global Evaporative Cooler Market
Cooling Systems
Air Source Heat Pump Market
Cooling Systems
Water Cooling Corona Discharge Ozone Generator Market
Cooling Systems
Roll Bond Evaporator Market
Cooling Systems
Evaporative Cooling Tower Market
Cooling Systems
Turbine Inlet Cooling Systems Market
Cooling Systems
Global Air Cooled Condenser Market
Cooling Systems
Thawing System Market
Cooling Systems
Flue Gas Coolers Market
Cooling Systems
United States Heat Pump Market