
 Evaporative Condensing Unit Market | 2026-2036
Evaporative Condensing Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Evaporative Condensing Unit Market Analysis
Data center cooling is realigning demand profiles within the commercial end user segment. Evapco Inc. leverages its specialized coil manufacturing capabilities to dominate niche high-capacity installations. Johnson Controls International PLC anchors its position through integrated building automation platforms that bundle evaporative condensing with energy management systems. Daikin Industries Ltd. competes on variable speed technology leadership across Asian and North American project pipelines.
An evaporative condensing unit combines a refrigerant condenser with a water-cooled heat rejection system that uses evaporative cooling to achieve lower condensing temperatures than air-cooled alternatives, typically operating with wet-bulb approach temperatures of 8–15°F in commercial and industrial refrigeration cycles. Water-cooled product types sustain premium pricing due to superior thermodynamic efficiency in high-ambient conditions, while modular configurations are gaining traction in distributed cold chain infrastructure where scalable capacity expansion matters. Direct expansion technology occupies the largest installed base across food processing applications, though chilled water systems are displacing legacy fixed-speed equipment in HVAC retrofit projects where part-load efficiency regulations tighten.
The EPA refrigerant management rules and ASHRAE 90.1 efficiency standards shape equipment specification timelines and retrofit obligations across the United States. OSHA workplace safety requirements for cooling tower maintenance and the DOE's energy conservation standards for commercial refrigeration equipment add compliance layers that filter vendor qualification. Stakeholders must monitor refrigerant transition pathways and regional water-use restrictions that could pivot technology preference between water-cooled and hybrid product architectures.
Market Dynamics
The EPA's phasedown of hydrofluorocarbon refrigerants under the AIM Act is compressing equipment replacement cycles and forcing cold chain operators to accelerate capital deployment toward lower-GWP alternatives before mandated phaseout deadlines.
Growth Catalysts
- AIM Act Compliance Deadlines:The EPA's refrigerant phasedown mandates are pulling forward replacement demand across warehouse refrigeration infrastructure in Sun Belt states with high cooling-degree-day exposure.
- Data Center Thermal Loads:Hyperscale computing facilities are expanding evaporative condensing adoption to manage rising rack densities and stricter ASHRAE 90.1 efficiency thresholds.
- Variable Speed Compressor Integration:Part-load optimization technology is unlocking efficiency gains in distributed cold chain nodes where modular capacity scaling matters.
Market Restraints
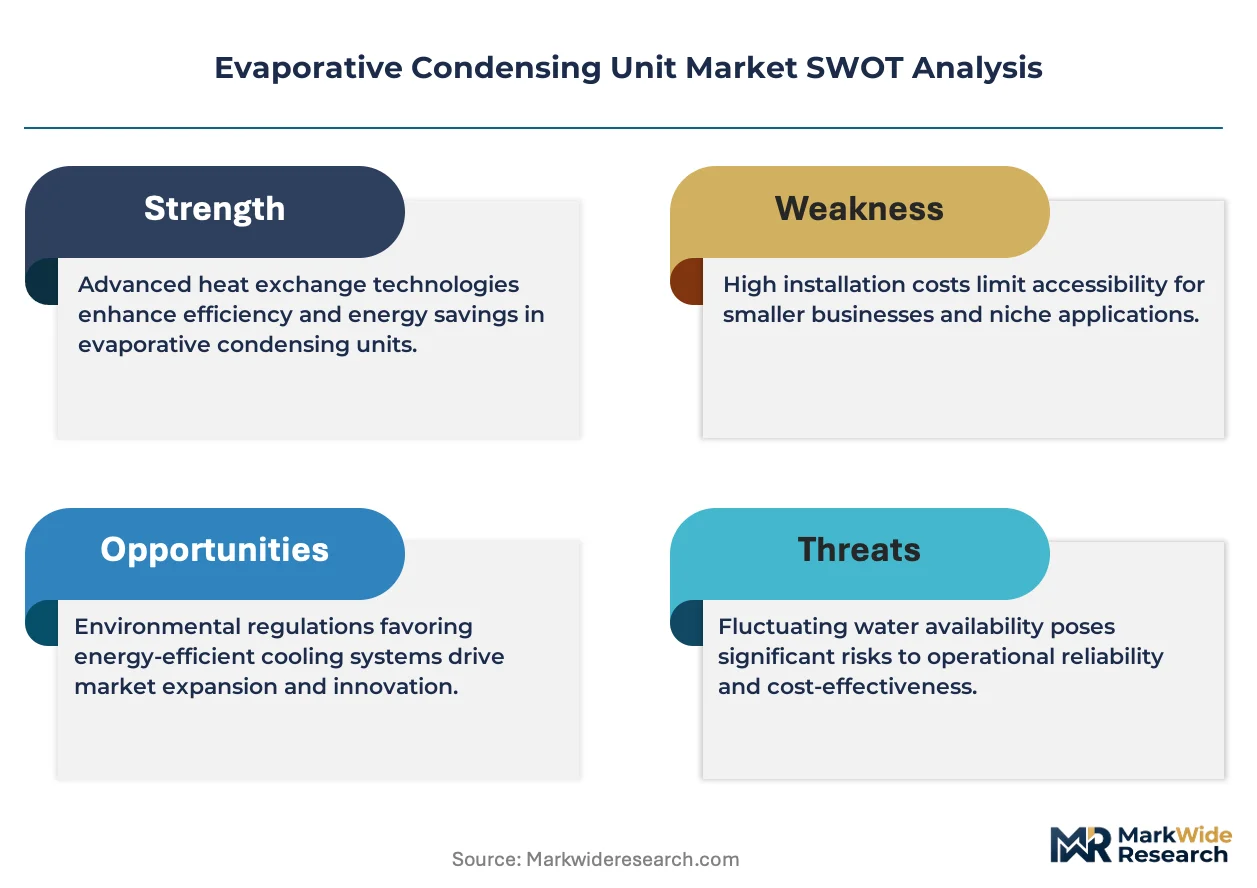
- Copper Coil Input Volatility:Specialized heat exchanger materials face price instability that compresses margins for coil-dependent system configurations.
- Water Scarcity Constraints:Municipal water-use restrictions in drought-prone jurisdictions are limiting deployability of pure water-cooled architectures.
- Legacy DX System Entrenchment:Existing direct expansion installations create switching friction due to embedded piping infrastructure and technician familiarity.
Strategic Opportunities
- Hybrid Evaporative-Dry Cooling Convergence:Water-free backup modes combined with evaporative priming are opening deployment in water-stressed regions previously closed to wet systems.
- Integrated Building Automation Bundling:Energy management platform tie-ins are creating stickier vendor relationships through system-level performance contracting.
- India Cold Chain Modernization:FSSAI-mandated temperature compliance for food logistics is driving first-time evaporative condensing adoption in refrigerated transport and storage infrastructure.
Industry Challenges
- Refrigerant Transition Complexity:Technician certification gaps for A2L mildly flammable alternatives are slowing field deployment and service turnaround.
- OSHA Cooling Tower Maintenance Compliance:Legionella prevention protocols are extending commissioning timelines and raising operational overhead for water-based heat rejection systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Evaporative Condensing Unit Market |
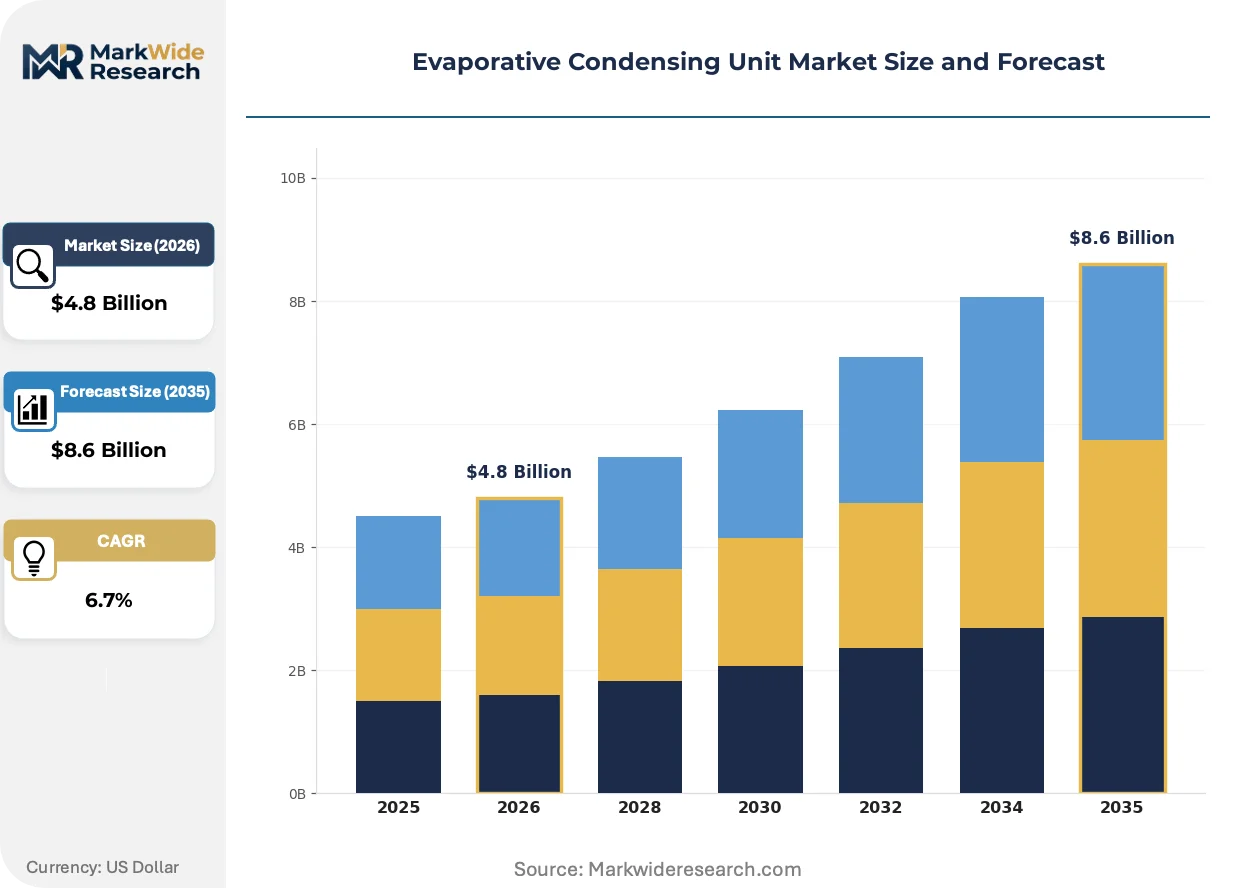
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Cooled, Water-Cooled, Hybrid, Modular End User: Commercial, Industrial, Agricultural, Residential Application: Refrigeration, HVAC, Food Processing, Chemical Processing Technology: Direct Expansion, Chilled Water, Variable Speed, Fixed Speed |
| Companies Covered | Johnson Controls International PLC, Evapco Inc., Baltimore Aircoil Company, SPX Corporation, Daikin Industries Ltd., AAON Inc., DECSA Srl, Mammoth Inc., GEA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Evaporative Condensing Unit Market Emerging Trajectories
Refrigerant chemistry evolution and control system digitization are converging to redefine system architecture priorities, with efficiency optimization and regulatory pre-compliance displacing pure capacity metrics in procurement specifications.
Modular rack-mounted evaporative condensers with embedded variable frequency drives are overtaking centralized plant designs in distributed cold chain applications. Regional logistics operators are specifying scalable 50-200 ton modules that eliminate single points of failure. This configurability is compressing project lead times and enabling phased capital deployment.
The EPA's Significant New Alternatives Policy program is accelerating A2L refrigerant approvals for commercial refrigeration equipment. Equipment manufacturers are redesigning condensing units around lower-flammability thresholds ahead of state-level building code adoptions. Food processing facilities in California and Texas are piloting these systems to secure early-mover compliance positioning.
Performance-based service contracting is displacing traditional break-fix maintenance arrangements in multi-site cold chain operations. Third-party logistics providers are unbundling equipment ownership from thermal outcome guarantees. This shift is most visible among national grocery distributors consolidating vendor relationships under single-source responsibility structures.
Evaporative Condensing Unit Market Segmentation
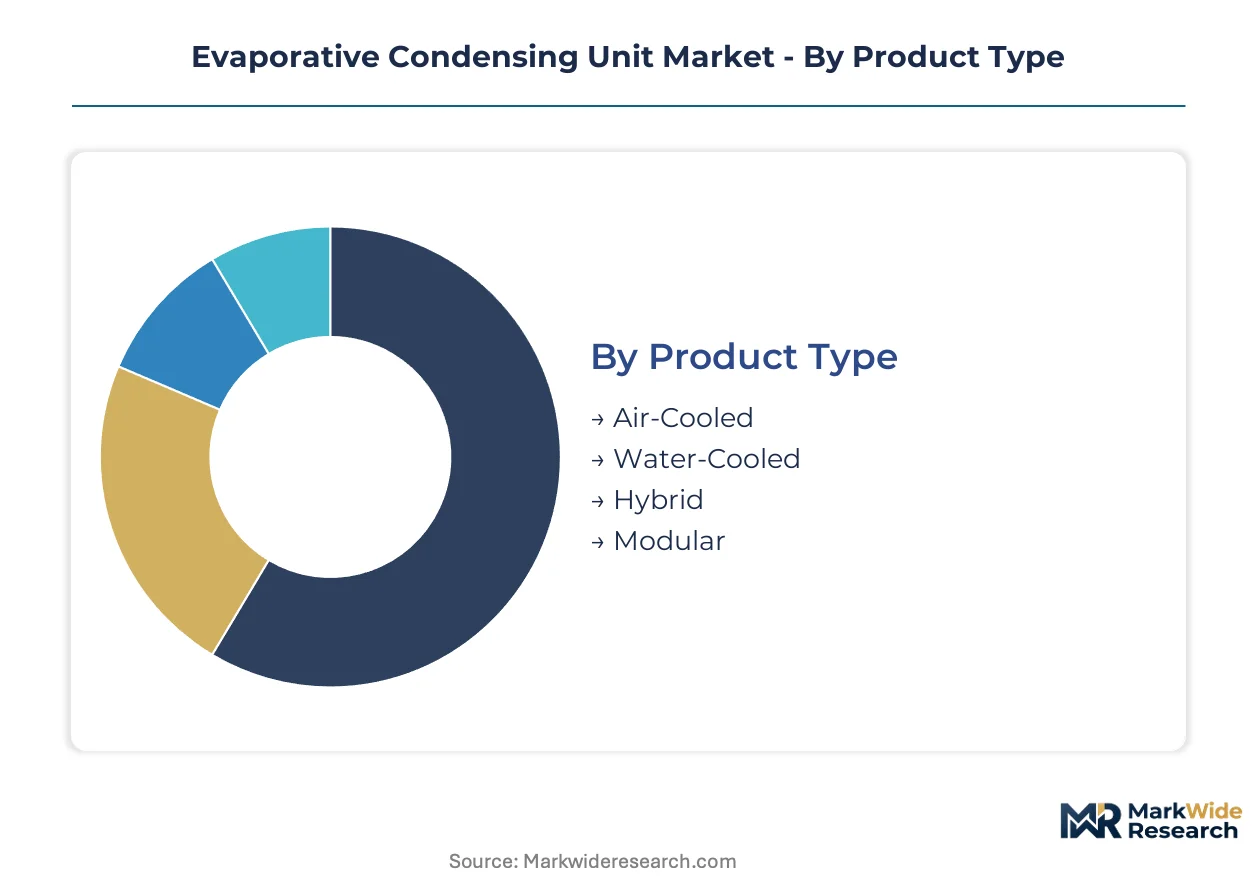
Segmentation in evaporative condensing units reveals how refrigerant phaseout timelines, water scarcity patterns, and building automation integration are fragmenting procurement specifications across end-use verticals. Understanding these divides exposes where vendor specialization creates defensible positioning.
Product Type:
Supply concentration in coil manufacturing and heat exchanger engineering tilts competitive advantage toward vendors with captive metallurgy capabilities or long-term copper sourcing contracts.
- Water-Cooled:These systems achieve lower condensing temperatures through evaporative heat rejection, operating with wet-bulb approach temperatures of 8–15°F. Demand clusters in Sun Belt states with high cooling-degree-day profiles, where thermodynamic efficiency premiums justify higher capital outlay and water treatment infrastructure. EPA AIM Act compliance deadlines are accelerating replacement demand in warehouse refrigeration.
- Hybrid:Combines evaporative priming with water-free backup modes, enabling deployment in drought-prone jurisdictions previously closed to wet systems. Municipal water-use restrictions in California and Texas are pulling adoption forward among hyperscale data center operators seeking ASHRAE 90.1 efficiency thresholds without supply risk.
- Air-Cooled:Eliminates water treatment and Legionella compliance overhead but sacrifices efficiency in high-ambient conditions.
- Modular:Rack-mounted configurations with scalable 50-200 ton modules are gaining traction in distributed cold chain nodes.
Today's leader: Water-Cooled. Tomorrow's challenger: Hybrid.
End User:
Cost tier stratification separates capital-intensive industrial deployments from specification-sensitive commercial retrofits and price-constrained agricultural installations.
- Commercial:Office buildings, retail, and hospitality drive specification complexity through ASHRAE 90.1 efficiency mandates and integrated building automation requirements. Data center thermal loads are realigning demand profiles within this segment, with hyperscale facilities prioritizing variable speed integration and part-load optimization.
- Industrial:Food processing and chemical facilities dominate installed base volume, with legacy direct expansion systems creating switching friction due to embedded piping infrastructure. FSSAI-mandated temperature compliance in India is driving first-time evaporative condensing adoption in refrigerated transport.
- Agricultural:Post-harvest cooling and controlled atmosphere storage prioritize first-cost minimization over lifecycle efficiency.
- Residential:Limited penetration due to scale economics and technician familiarity with conventional split systems.
Industrial installations anchor current revenue. Commercial retrofits are climbing the fastest.
Application:
Volume concentration in cold chain logistics is reshaping how OEMs configure coil geometry and control architectures.
- Refrigeration:Warehouse and transport cooling accounts for the largest installed base, with EPA refrigerant phasedown compressing replacement cycles. Cold chain operators are expanding evaporative condensing adoption ahead of hydrofluorocarbon phaseout deadlines, particularly in Sun Belt distribution hubs.
- HVAC:Part-load efficiency regulations are displacing legacy fixed-speed equipment in retrofit projects. Johnson Controls anchors positioning through energy management system bundling that ties thermal outcomes to building automation platforms.
- Food Processing:Direct expansion technology dominates legacy installations, though chilled water systems are gaining share in greenfield facilities.
- Chemical Processing:Process cooling requirements favor water-cooled architectures with redundant capacity configurations.
Refrigeration commands the largest footprint. HVAC retrofits show the steepest expansion trajectory.
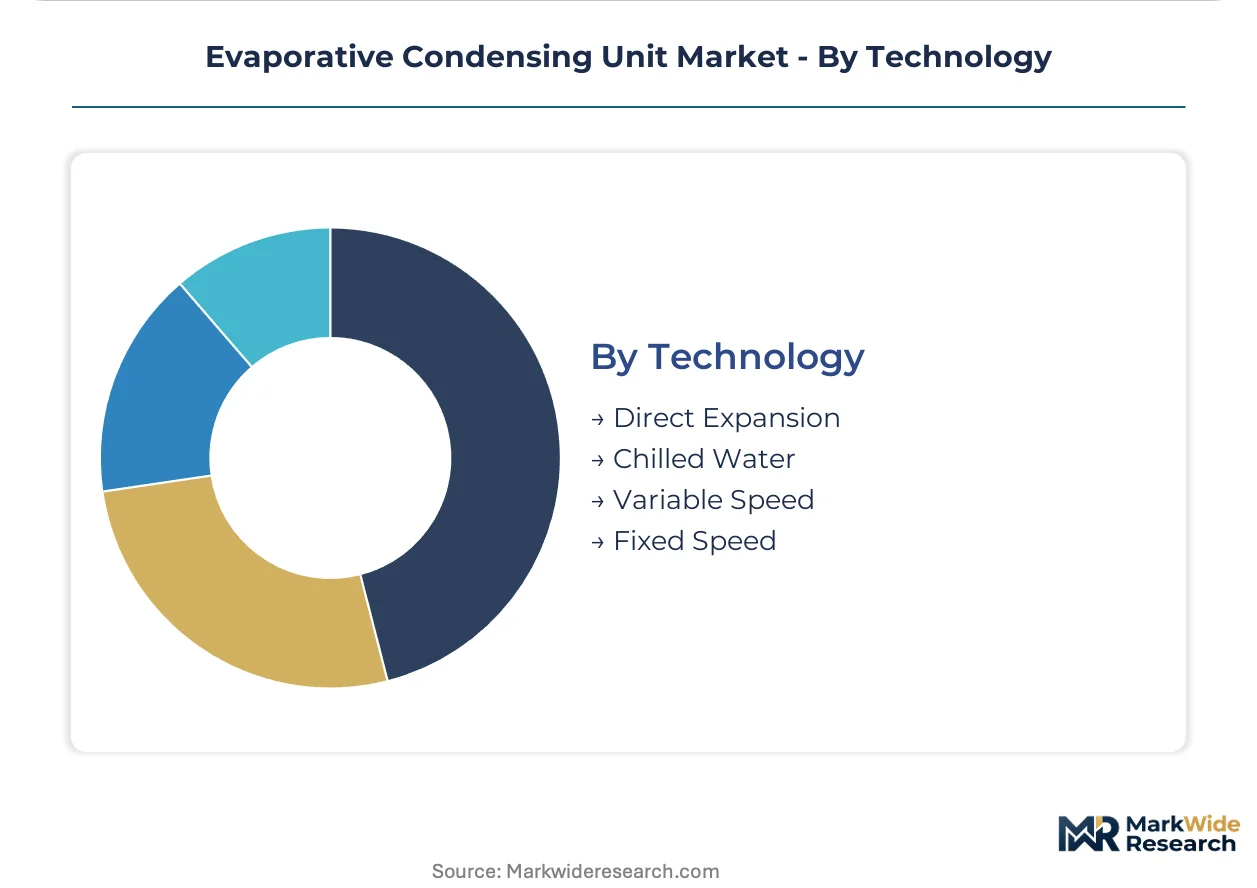
Technology:
Margin structure favors variable speed and digital control integration over commodity fixed-speed configurations.
- Variable Speed:Compressor modulation unlocks efficiency gains in distributed cold chain nodes where load profiles fluctuate seasonally. Daikin Industries competes on technology leadership across Asian and North American project pipelines, with part-load optimization becoming a procurement specification priority.
- Direct Expansion:Legacy installed base across food processing applications creates technician familiarity advantages but faces displacement pressure from efficiency regulations. Embedded piping infrastructure generates switching friction that slows retrofit timelines.
- Chilled Water:Displacing DX in HVAC retrofits where central plant architectures enable thermal storage and load shifting.
- Fixed Speed:Price-sensitive segments in agricultural and emerging market applications sustain residual demand.
Direct Expansion holds the installed base. Variable Speed is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sun Belt warehouse clusters in the United States concentrate the highest density of evaporative condensing installations, with Texas, Arizona, and Florida driving replacement demand ahead of EPA refrigerant phasedown deadlines.
United States
Distribution hubs across Texas and Florida are retrofitting legacy direct expansion systems with water-cooled evaporative condensers to meet ASHRAE 90.1 efficiency thresholds. The EPA's AIM Act refrigerant mandates are compressing equipment replacement cycles in warehouse refrigeration infrastructure. Dallas-Fort Worth logistics corridors are seeing accelerated capital deployment toward lower-GWP alternatives before 2026 compliance deadlines.
India
Cold chain modernization is pulling first-time evaporative condensing adoption into refrigerated transport and storage networks. FSSAI-mandated temperature compliance for food logistics is reshaping procurement specifications across Maharashtra and Gujarat. Mumbai-Pune industrial corridors are deploying modular rack-mounted systems to eliminate single points of failure in distributed logistics nodes.
Germany
Industrial refrigeration in chemical processing and food manufacturing sustains premium water-cooled system demand despite municipal water-use scrutiny. The EU F-Gas Regulation is accelerating equipment turnover toward lower-GWP refrigerant architectures. Bavarian chemical clusters are piloting hybrid evaporative-dry cooling configurations to secure operational continuity under drought contingency protocols.
China
Data center thermal load management is expanding evaporative condensing adoption in hyperscale computing facilities across the Yangtze River Delta. National dual carbon goals are tightening efficiency standards for commercial refrigeration equipment. Shanghai metro area cloud infrastructure operators are specifying variable speed compressor integration to optimize part-load performance under MEE energy conservation guidelines.
Japan
Commercial HVAC retrofits are displacing legacy fixed-speed equipment with chilled water evaporative condensing systems in Tokyo and Osaka metro areas. METI energy efficiency standards are tightening compliance thresholds for building thermal management. Kanto region facility managers are bundling evaporative condensing with building automation platforms to secure performance-based service contracting arrangements.
Evaporative Condensing Unit Market Vendor Landscape
Technology licensing dominates the current landscape as vendors race to secure A2L refrigerant compatibility ahead of building code adoptions. The market structures around three tiers: integrated building automation conglomerates, specialized coil engineering firms, and regional fabrication specialists. Two strategic archetypes have emerged—full-system integrators bundling energy management platforms, and component specialists leveraging captive metallurgy capabilities. M&A activity and portfolio diversification into hybrid cooling architectures represent the dominant competitive vectors.
Within the integrated systems tier, Johnson Controls International PLC and Daikin Industries Ltd. exemplify platform-centric positioning through building automation bundling strategies. Among specialized engineering specialists, Evapco Inc. occupies a position defined by heat exchanger manufacturing depth. Baltimore Aircoil Company and SPX Corporation represent the mid-cap fabrication segment where geographic proximity to Sun Belt demand clusters shapes competitive access. These five entities collectively span the technology-to-scale spectrum without claiming exhaustive market coverage.
| Leading Market Players |
|---|
| Johnson Controls International PLC |
| Evapco Inc. |
| Baltimore Aircoil Company |
| SPX Corporation |
| Daikin Industries Ltd. |
| AAON Inc. |
| DECSA Srl |
| Mammoth Inc. |
| GEA Group |
| Others |
Supply Flow & Price Mechanics
Water-cooled premium positioning against air-cooled commoditization creates a bifurcated cost structure where thermodynamic efficiency premiums coexist with municipal water-use risk premiums, reshaping both procurement specifications and supplier metallurgy investments across coil-dependent system configurations.
Pricing Analysis
Copper coil input volatility passes through to system pricing with lagged adjustments, compressing margins for vendors without long-term metallurgy contracts. Three-tier pricing structure across premium water-cooled, standard hybrid, and economy air-cooled levels differentiates by wet-bulb approach temperature performance and ASHRAE 90.1 compliance certification. Cost compression in modular rack-mounted configurations is intensifying because scalable 50-200 ton units attract multiple fabrication specialists. Agricultural post-harvest cooling buyers exhibit highest price sensitivity, while hyperscale data center operators prioritize part-load efficiency over capital outlay.
Supply Chain Analysis
Freight cost escalation from Asian coil manufacturing hubs to Sun Belt distribution centers is amplifying landed cost differentials for water-cooled system imports. Supply concentrates in China for heat exchanger fabrication, the United States for integrated control systems assembly, and Germany for precision compressor components. Raw material dependencies center on copper tube stock, aluminum fin stock, and specialized refrigerant-grade steel. Single-source vulnerability in A2L-compatible valve sourcing threatens equipment redesign timelines. Distribution runs through national HVAC-R wholesalers with regional cold chain logistics specialists capturing direct retrofit contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The evaporative condensing unit market functions as a stable compounder anchored by EPA refrigerant phasedown mandates that compress replacement cycles regardless of macroeconomic cyclicality.
For Market Incumbents: Hedge against water scarcity constraints by accelerating hybrid evaporative-dry cooling R&D to preserve deployability in drought-prone jurisdictions. Secure captive copper sourcing through backward integration into metallurgy partnerships or long-term offtake agreements with tube mills. Vertical integration into building automation software layers protects margin position against commoditization of standalone condensing hardware.
For New Entrants and Emerging Players: Mid-sized regional cold chain operators in India represent an underserved buyer archetype with first-time evaporative condensing adoption driven by FSSAI temperature compliance mandates. Target modular rack-mounted configurations in Maharashtra and Gujarat logistics corridors where incumbent coverage remains thin. Pursue performance-based service contracting as the go-to-market angle, unbundling equipment ownership from thermal outcome guarantees to displace traditional break-fix arrangements.
For Investors and Strategic Acquirers: Consolidation pressure builds where coil engineering capabilities concentrate among specialized mid-cap fabricators lacking integrated control system expertise. The five-to-ten-year viability window favors vendors with captive heat exchanger manufacturing and A2L refrigerant compatibility certification. Acquisition target archetype: regional fabrication specialists with Sun Belt geographic proximity and untapped building automation bundling potential. Monitor state-level building code adoptions for A2L refrigerants as the inflection signal for technology licensing deal flow acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Cooling Architecture Development | Enables deployment in California and Texas despite municipal water-use restrictions. |
| Variable Speed Compressor Integration | Daikin Industries leverages this technology leadership across Asian and North American pipelines. |
| Building Automation Platform Bundling | Johnson Controls anchors positioning through energy management system tie-ins. |
| A2L Refrigerant Compatibility Certification | EPA Significant New Alternatives Policy approvals accelerate equipment redesign cycles. |
| Modular Rack-Mounted Configuration Scale-Up | Eliminates single points of failure in distributed cold chain nodes for regional logistics operators. |
Methodological Framework
Bottom-up cold chain logistics modeling reconciled against top-down coil manufacturing capacity tracking forms the analytical core of this study. Primary interviews with HVAC-R contractors, cold chain facility maintenance directors, OEM procurement teams, and aftermarket service heads combined with secondary validation against EPA refrigerant phasedown filings, ASHRAE standards documentation, DOE energy conservation rulemakings, and customs trade data for heat exchanger imports. Triangulation between installation volume estimates and supplier shipment disclosures ensures dimensional consistency across water-cooled, hybrid, and air-cooled product architectures.
Input-output matrix framing connects refrigerant transition pathways, regional cooling-degree-day profiles, and water scarcity indices to equipment replacement demand across commercial, industrial, and agricultural end uses. Segmentation dimensions modeled include product type, end user vertical, application category, and technology tier alongside regional regulatory cluster differentiation. CAGRs were derived from slope analysis of replacement cycle compression and greenfield adoption curves. Industry-specific forecast inputs incorporate AIM Act compliance deadline phasing and FSSAI-mandated temperature compliance rollout in India.
Underlying measurement precision varies by segment; water-cooled and hybrid configurations carry tighter precision than legacy air-cooled estimates due to supplier concentration in coil manufacturing. Forecasts reflect assumptions around refrigerant transition timelines, municipal water-use restriction enforcement intensity, and data center thermal load growth trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Air to Air Heat Pumps Sales Market
Cooling Systems
Marine Cooling Systems Market
Cooling Systems
Solar Cooling Market
Cooling Systems
Temporary Power and Cooling Solutions Market
Cooling Systems
Solar Powered Cold Storage Market
Cooling Systems
Portable Chiller Market
Cooling Systems
Evaporative Cooling Tower Market
Cooling Systems
Heat Pump Dryer Market
Cooling Systems
Aftercoolers Market
Cooling Systems
Solar Air Conditioning Market
Cooling Systems
Seawater Condensers Market
Cooling Systems
Flue Gas Coolers Market
Cooling Systems
Global Secondary Refrigerants Market
Cooling Systems
Critical Power and Cooling Market
Cooling Systems
Solar Fan Market
Cooling Systems
Global Chiller Market