
 Solar Ventilation Systems Market | 2026-2036
Solar Ventilation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Ventilation Systems Market Insights
Market Context
Modular bundling of solar panels with ventilation hardware is pivoting buyer choice away from standalone attic fans toward integrated climate kits. Solar Royal leverages its geographic dominance in sunbelt states to control distribution channels for complete rooftop systems. Solatube International differentiates through tubular daylighting-ventilation hybrids that occupy the premium residential segment. Natural Light Energy Systems specializes in DIY-configured product lines that compete on installation simplicity.
Technical Definition and Segment Structure
Solar ventilation systems are active or passive air-exchange devices powered by photovoltaic conversion, typically operating at 10-40 watt panel ratings to drive DC motors or thermosiphon airflow without grid dependency. Their primary commercial purpose is reducing mechanical cooling loads by exhausting hot attic or interior air using freely available solar radiation. Among product types, active systems dominate installed volume while hybrid systems represent the fastest-growing configuration as buyers seek battery-backed operational continuity. By end user, commercial buildings command the deepest margin pools due to scale-driven procurement and corporate sustainability mandates, whereas residential retrofitting lags in penetration but shows the steepest installation growth curve.
Regulatory Framework
The US Department of Energy's appliance efficiency standards, EPA ENERGY STAR certification, and California Title 24 building codes collectively shape product design thresholds and market access requirements for solar ventilation equipment. These frameworks compel manufacturers to publish verified airflow and wattage metrics, effectively filtering uncertified imports from project-specified procurement lists. Stakeholders must monitor evolving state-level net metering reforms that alter the economic calculus of grid-connected versus off-grid solar ventilation configurations.
Market Dynamics
Modular bundling of photovoltaic panels with DC motor assemblies is compressing buyer decision cycles toward integrated rooftop climate kits, displacing standalone attic fan procurement across sunbelt construction markets.
Growth Catalysts
- California Title 24 building codes:Mandatory cool roof and ventilation requirements in new commercial construction are specifying solar-powered exhaust systems as compliance pathways, accelerating specification in municipal permitting offices.
- Attic temperature reduction:Active solar ventilation cuts mechanical cooling loads by exhausting superheated air above insulation layers, delivering measurable HVAC demand reductions for single-story retail and warehouse operators.
- Texas solar irradiance concentration:Dallas-Fort Worth and Houston metro areas combine high cooling-degree-day loads with favorable payback math, concentrating residential retrofit demand in suburban housing stock built before 2010.
Market Restraints
- Polysilicon input volatility:Wafer pricing swings propagate through DC panel cost structures, compressing assembler margins and destabilizing project quoting for multi-unit commercial developments.
- Lead-acid battery substitution:Off-grid hybrid configurations remain dependent on legacy storage chemistry with limited cycle life, constraining operational continuity claims versus lithium-ion alternatives in premium segments.
- Florida wind-load engineering:Hurricane-prone coastal counties impose structural mounting requirements that add material cost and installation complexity, filtering out price-competitive import products.
Strategic Opportunities
- Arizona residential retrofits:Phoenix-Tucson corridor housing stock exhibits low solar ventilation penetration relative to insolation levels, presenting white-space opportunity for contractor channel development.
- Tubular daylighting convergence:Hybrid products integrating natural light transmission with thermosiphon airflow are capturing premium residential segments seeking single-aperture roof penetrations.
- ENERGY STAR certification tailwind:EPA efficiency thresholds for ventilation products are filtering uncertified imports from big-box retail shelves, creating shelf-space advantage for verified domestic assemblers.
Industry Challenges
- Electrical contractor skill gaps:Rooftop DC wiring and grounding requirements exceed standard HVAC technician training, forcing distributors to invest in field certification programs.
- Mounting system integration complexity:Compatibility verification across standing seam, composition shingle, and tile roof types consumes engineering resources and extends pre-sale timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Ventilation Systems Market |
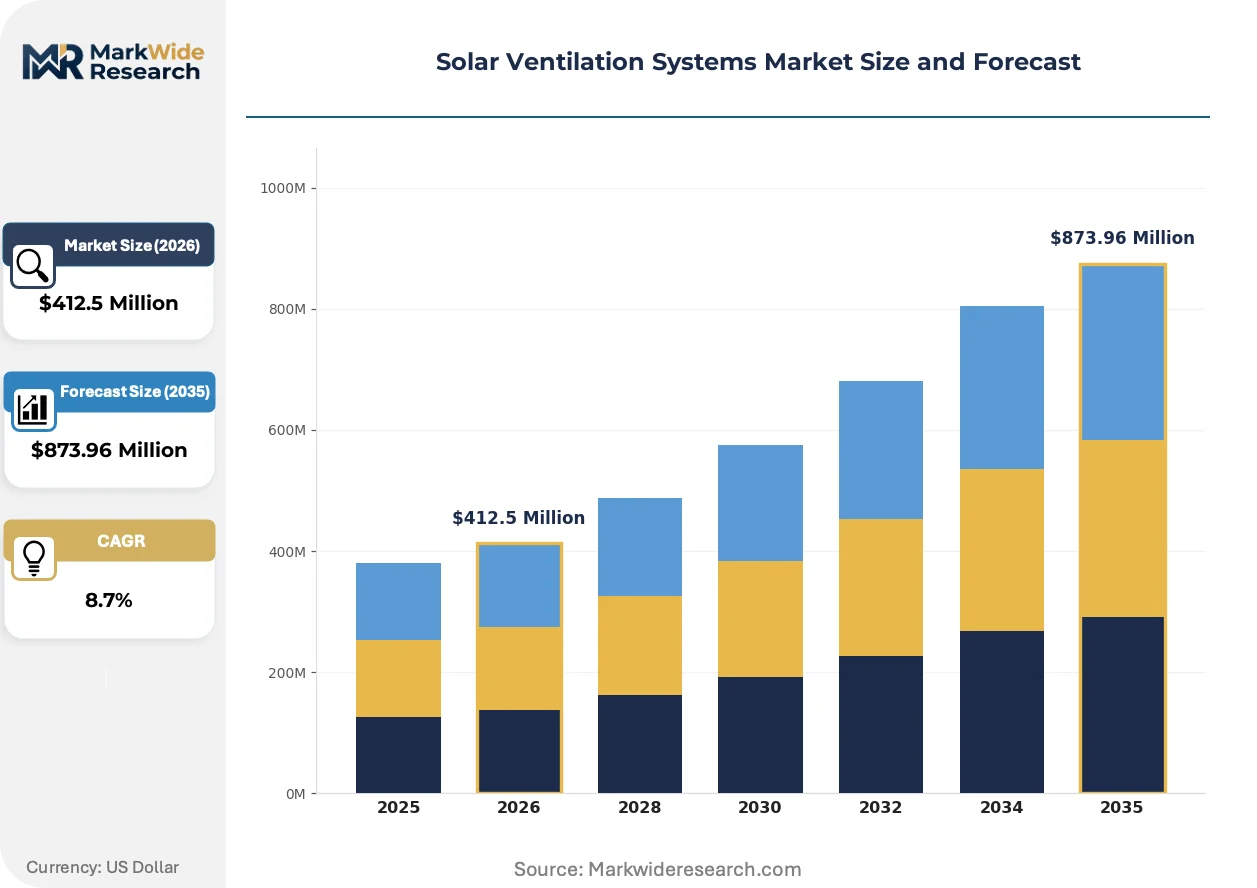
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Systems, Passive Systems, Hybrid Systems, Roof-Mounted Fans End User: Residential Buildings, Commercial Buildings, Industrial Facilities, Agricultural Structures Installation Type: New Construction, Retrofitting, DIY Installations, Professional Installations Energy Source: Photovoltaic Panels, Battery Storage, Grid Connection, Thermodynamic Systems |
| Companies Covered | Solar Royal, Solatube International, SolarVenti, Active Ventilation Products, Solar Star Attic Fans, Natural Light Energy Systems, SunRise Solar, Attic Breeze, Air Vent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Ventilation Systems Market Trends and Innovations
Product architecture is pivoting from discrete component sales toward pre-engineered climate kits, compressing installation labor and collapsing traditional trade boundaries between electrical and roofing contractors.
DC brushless motor technology is converging with rooftop photovoltaic micro-inverters, enabling variable-speed airflow modulation that tracks real-time solar generation rather than binary on-off operation. Large-format retail and cold-storage warehouse operators are specifying these intelligent systems for attic and ridge ventilation. The convergence is compressing energy consumption per cubic foot of air moved and narrowing the performance gap with grid-powered alternatives.
The EPA's ENERGY STAR Most Efficient designation for ventilation products is tightening airflow-per-watt thresholds and mandating third-party verification of published performance metrics. Manufacturers must submit laboratory test data to maintain certification eligibility for federal and utility rebate programs. Commercial building specifiers in California and Texas are filtering procurement lists to exclude non-certified products, accelerating redesign cycles among import-dependent assemblers.
Big-box home improvement retailers are unbundling after-sales service from product margins, shifting installation liability to certified contractor networks rather than in-house service desks. This channel restructuring is compressing price transparency and accelerating SKU rationalization toward private-label and exclusive-brand solar ventilation lines. The behavioral shift is most visible in Florida and Arizona markets where seasonal demand spikes strain legacy distribution infrastructure.
Solar Ventilation Systems Market Segmentation
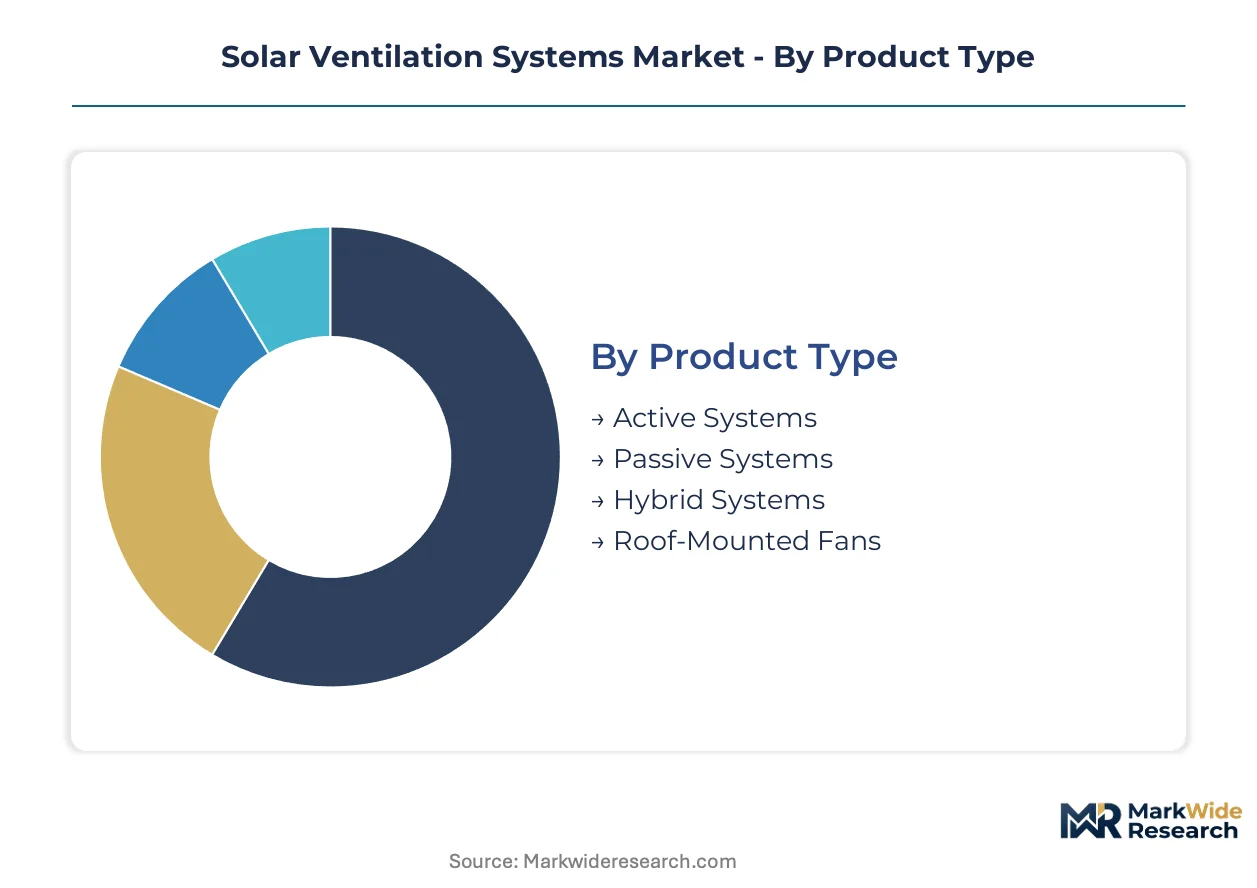
Solar ventilation procurement splits sharply between standardized commodity hardware and engineered climate kits. Specification engineers and retail buyers navigate four distinct taxonomies that reshape margin structures and channel economics across the value chain.
Product Type:
Customization intensity spans from plug-and-play attic fans to architect-specified hybrid arrays with battery integration.
- Active Systems:DC motor assemblies driven by dedicated photovoltaic panels deliver forced airflow at 10-40 watt ratings. Demand concentrates in California commercial retrofits where Title 24 compliance deadlines compress procurement timelines toward proven, code-listed configurations.
- Hybrid Systems:Battery-backed architectures pair rooftop panels with lead-acid or lithium storage to maintain ventilation continuity through cloud cover and evening hours. Texas warehouse operators specify these for temperature-sensitive inventory zones where uninterrupted airflow justifies premium pricing.
- Passive Systems:Thermosiphon designs exploit natural convection without moving parts, appealing to Florida coastal markets where hurricane wind-load requirements complicate mechanical mounting.
- Roof-Mounted Fans:Self-contained units integrate panel, motor, and housing in single-aperture assemblies targeting residential DIY channels in Arizona sunbelt suburbs.
Leading the category by volume: Active Systems. Expanding most quickly: Hybrid Systems.
End User:
Margin capture varies dramatically across customer types with diverging technical sophistication and procurement authority.
- Commercial Buildings:Corporate sustainability mandates and scale-driven procurement generate the deepest margin pools. Facility managers in Dallas-Fort Worth retail and Houston cold-storage warehouses specify ENERGY STAR-certified systems for measurable HVAC load reduction.
- Residential Buildings:Retrofit penetration remains low relative to solar irradiance levels, though Phoenix-Tucson corridor housing stock built before 2010 shows accelerating contractor channel development.
- Industrial Facilities:Process ventilation requirements in manufacturing plants and distribution centers drive demand for high-capacity ridge and attic exhaust configurations.
- Agricultural Structures:Livestock barns and greenhouse operators seek humidity control through solar-powered continuous airflow, particularly in Florida and Texas dairy operations.
Commercial Buildings command the steepest pricing premiums. Residential Buildings climb the fastest installation curve.
Installation Type:
Channel structure fragments between professional trades and consumer-direct fulfillment with diverging liability allocation.
- New Construction:Builder-grade specification at the framing stage enables integrated roof-deck mounting and seamless electrical rough-in, concentrating in California municipal permitting offices with mandatory cool roof requirements.
- Retrofitting:Post-occupancy installation dominates residential volume as homeowners replace failed attic fans or respond to utility rebate programs in Texas and Florida.
- DIY Installations:Pre-configured kits with simplified mounting hardware target big-box retail channels, with Natural Light Energy Systems competing aggressively on installation simplicity.
- Professional Installations:Certified electrical contractors handle DC wiring and grounding requirements that exceed standard HVAC technician training, forcing distributor investment in field certification programs.
Retrofitting generates the largest absolute volume. New Construction gains share fastest as building codes tighten.
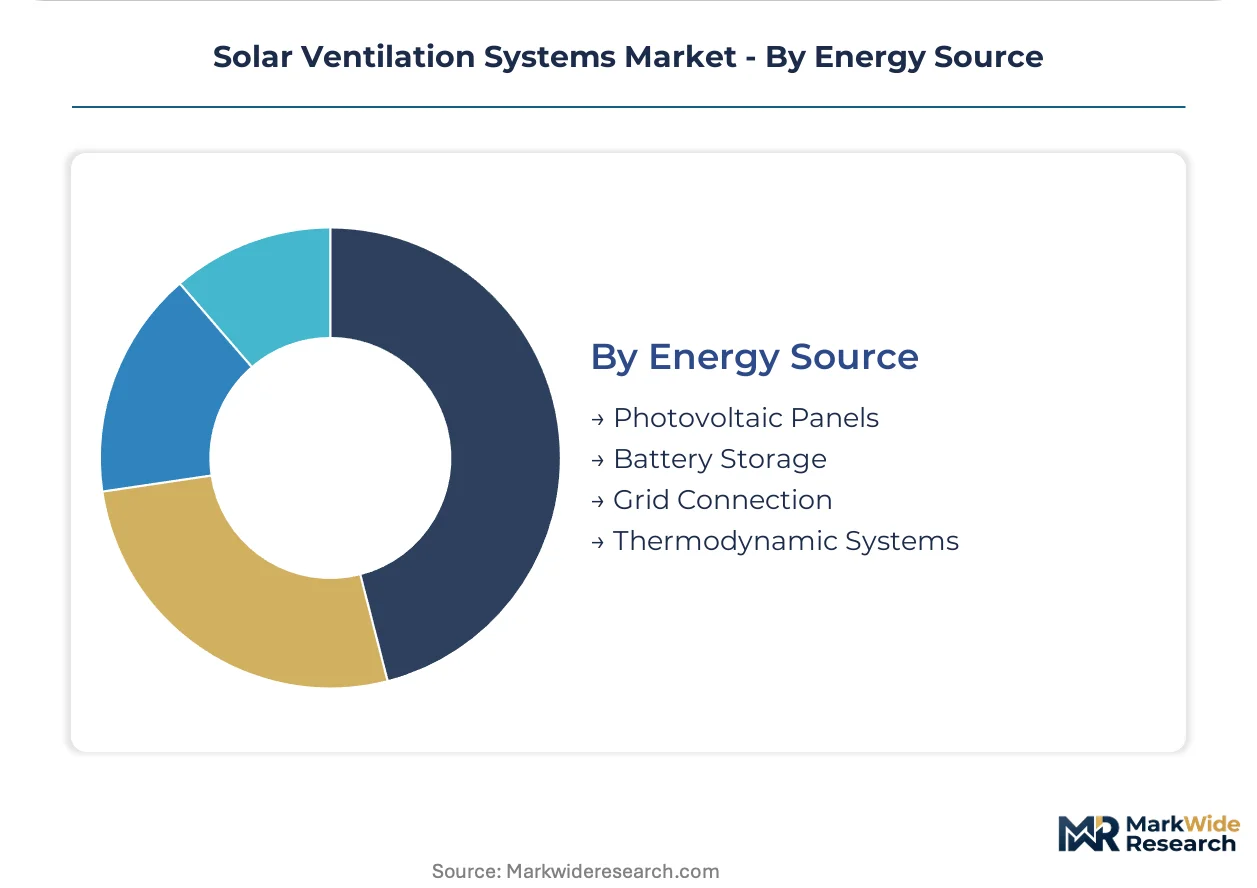
Energy Source:
Architectural flexibility versus operational continuity defines the technology trade-offs in this category.
- Photovoltaic Panels:Dedicated 10-40 watt crystalline or thin-film arrays constitute the baseline configuration for virtually all solar ventilation deployments, with panel efficiency directly determining airflow-per-watt performance metrics.
- Battery Storage:Lead-acid chemistry dominates cost-sensitive hybrid configurations despite limited cycle life, constraining operational continuity claims versus lithium-ion alternatives in premium segments.
- Grid Connection:Grid-tied backup enables dual-mode operation where solar generation supplements utility power during peak cooling loads, prevalent in commercial buildings with existing electrical infrastructure.
- Thermodynamic Systems:Phase-change and adsorption cooling integration represents emerging architectural convergence for zero-energy building targets, currently niche but specified in advanced California Title 24 compliance pathways.
Photovoltaic Panels anchor the category by installed base. Battery Storage shows the steepest technology improvement trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of solar ventilation hardware clusters in China and Taiwan, while consumption concentrates in sunbelt markets across the United States, Australia, and Southern Europe where cooling loads and solar irradiance align.
United States
California Title 24 building codes mandate cool roof and ventilation requirements in new commercial construction, specifying solar-powered exhaust systems as compliance pathways. The EPA's ENERGY STAR certification filters uncertified imports from federal procurement lists. Dallas-Fort Worth and Houston metro areas combine high cooling-degree-day loads with favorable payback math, concentrating residential retrofit demand.
Australia
Queensland and New South Wales housing stock exhibits strong solar penetration that extends to ventilation retrofits. The country's national building regulator enforces energy efficiency standards that favor photovoltaic-powered mechanical systems. Sydney and Melbourne commercial districts specify integrated climate kits for warehouse and retail attic ventilation.
Germany
Passive house construction standards drive demand for thermosiphon ventilation without grid dependency. The EU Green Deal and national building efficiency regulations accelerate specification of solar thermal systems in residential new builds. Bavaria and Baden-Württemberg manufacturing clusters produce DC motor assemblies for export markets.
Spain
Andalusia and Mediterranean coastal provinces combine extreme summer temperatures with abundant solar resource, creating natural demand for attic exhaust systems. National building codes under the EU energy performance directive mandate mechanical ventilation in new construction. Seville and Valencia metropolitan areas show accelerating contractor channel development for residential retrofits.
China
Yangtze River Delta and Pearl River Delta manufacturing centers supply photovoltaic panels and DC motors to global assemblers. The country's dual carbon goals and building efficiency standards stimulate domestic adoption in southern provinces. Guangdong and Jiangsu province industrial zones export complete solar ventilation kits to North American and European distributors.
Solar Ventilation Systems Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the solar ventilation value chain, creating a tiered structure where scale-driven assemblers battle regional installers for margin capture. The vendor base spans photovoltaic panel manufacturers, DC motor specialists, and integrated climate kit assemblers with divergent channel strategies. Three archetypes dominate: sunbelt-focused distributors controlling retail shelf space, tubular daylighting-ventilation hybrid specialists, and DIY-configured product lines competing on installation simplicity. Capacity expansion and ENERGY STAR certification acceleration represent the dominant competitive moves as regulatory barriers reshape procurement lists.
Among sunbelt-focused distributors, Solar Royal exemplifies geographic concentration strategies in high-insolation states. Solatube International occupies the premium residential segment through hybrid architectural solutions. Natural Light Energy Systems anchors the DIY installation archetype with simplified mounting hardware for consumer-direct channels. These three represent contrasting positioning vectors—regional dominance, premium hybridization, and installation accessibility—that define competitive tension in residential retrofit markets.
| Leading Market Players |
|---|
| Solar Royal |
| Solatube International |
| SolarVenti |
| Active Ventilation Products |
| Solar Star Attic Fans |
| Natural Light Energy Systems |
| SunRise Solar |
| Attic Breeze |
| Air Vent |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up specialists in rooftop climate hardware are consolidating distribution channels across sunbelt states, compressing assembler margins while enforcing pricing discipline on uncertified import competitors through ENERGY STAR gatekeeping.
Pricing Analysis
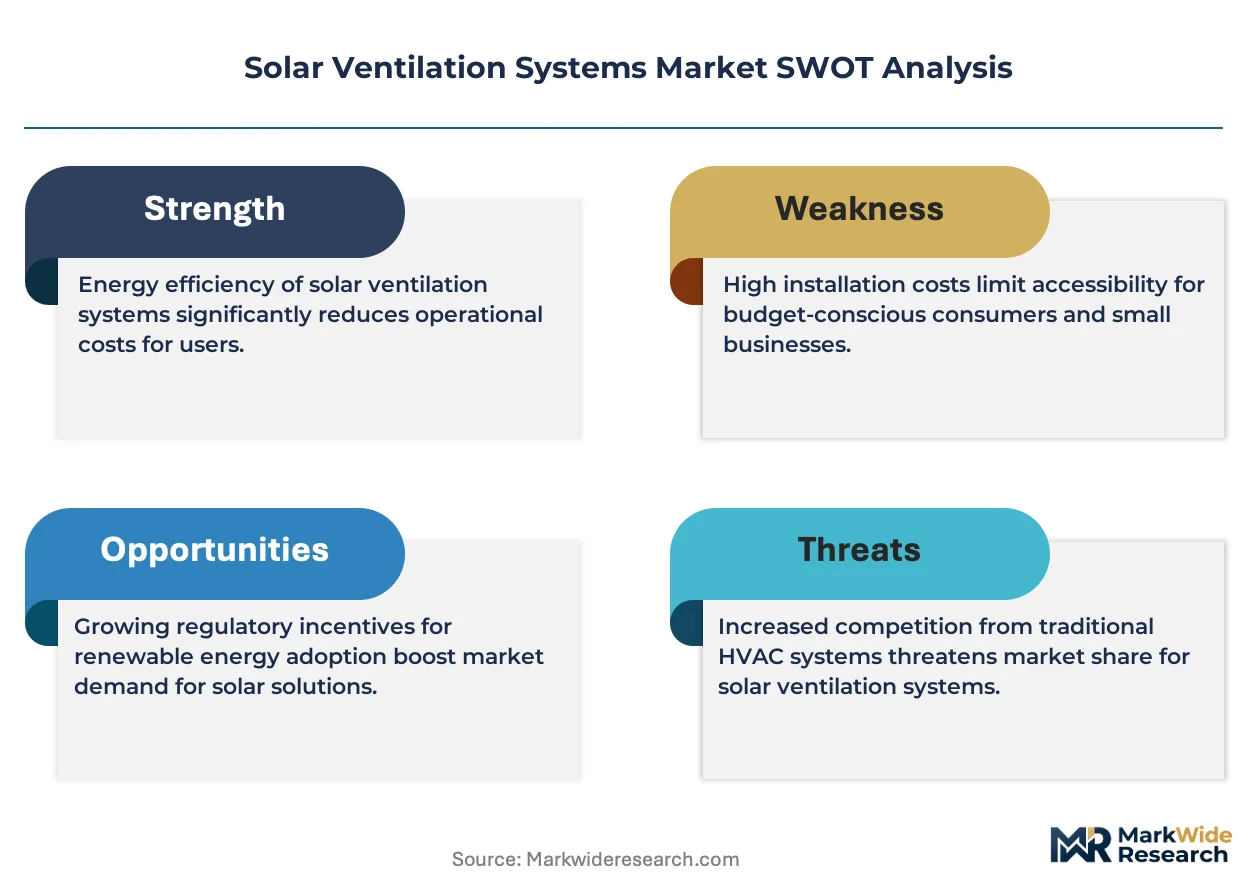
Margin tightening in economy-tier attic fans reflects polysilicon wafer cost volatility propagating through DC panel assemblies. Three-tier pricing structure across ENERGY STAR-certified, code-listed, and uncertified import tiers separates commercial specifiers from residential DIY channels. Cost-down pressure on battery-backed hybrid configurations accelerates as lead-acid substitution limits cycle-life claims against lithium-ion alternatives. Residential retrofit buyers in Texas and Florida exhibit the sharpest price sensitivity, while California commercial facility managers prioritize verified airflow-per-watt metrics over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Dallas-Fort Worth warehouse operators and Phoenix-Tucson contractor networks mandate qualification of both crystalline and thin-film photovoltaic panel suppliers. Manufacturing gravity centers on China, Taiwan, and Vietnam for DC motor assemblies and photovoltaic wafers, with Yangtze River Delta facilities feeding North American distributor inventories. Raw material dependencies span polysilicon ingots, rare-earth permanent magnets, and aluminum extrusion profiles for hurricane-rated mounting hardware. Tariff exposure on Chinese photovoltaic imports creates margin compression for price-competitive assemblers. Distribution runs through big-box retail channels and certified electrical contractor networks with diverging liability allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DC brushless motor convergence with rooftop micro-inverters is displacing binary on-off attic fan architectures, compressing the performance gap with grid-powered alternatives and forcing incumbent assemblers to redesign around variable-speed intelligence.
For Market Incumbents: Anchor ENERGY STAR certification pipelines to defend shelf-space access against uncertified import erosion in California and Texas municipal procurement offices. Deepen backward integration into DC motor assembly production to offset polysilicon input volatility and stabilize project quoting for multi-unit commercial developments. Prioritize tubular daylighting-ventilation hybrid R&D to capture premium residential segments seeking single-aperture roof penetrations. For New Entrants and Emerging Players: Launch via certified electrical contractor networks in the Phoenix-Tucson corridor where solar ventilation penetration lags insolation levels and contractor channel development remains underbuilt. Target Florida coastal counties with passive thermosiphon designs that circumvent hurricane wind-load engineering requirements filtering mechanical competitors. Pursue white-space in agricultural livestock barn applications where humidity control requirements meet solar-powered continuous airflow demand. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap assemblers with captive ENERGY STAR verification and established sunbelt distributor relationships in Arizona and Texas. Long-term viability hinges on lithium-ion battery cost curves enabling hybrid system margin expansion against lead-acid-constrained competitors. Watch state-level net metering reform signals as inflection indicators for grid-connected versus off-grid configuration economics.| Strategic Initiative | Industry Significance |
|---|---|
| ENERGY STAR Certification Acceleration | EPA verification thresholds filter uncertified imports from California and Texas procurement lists. |
| Backward Integration into DC Motor Assembly | Captive production of brushless motor architectures stabilizes margins against polysilicon volatility. |
| Contractor Network Certification Programs | Field training investments address electrical skill gaps exceeding standard HVAC technician capabilities. |
| Tubular Daylighting-Ventilation Hybrid Development | Single-aperture roof penetration designs capture premium residential segments in Florida and Arizona. |
| Lithium-Ion Battery Substitution Pathways | Cycle-life improvements enable operational continuity claims against lead-acid-constrained competitors. |
Research Methodology
SEC filings, EPA ENERGY STAR certification databases, and California Title 24 compliance documentation formed the secondary backbone for market sizing and regulatory mapping. Primary interviews with facility managers at Dallas-Fort Worth retail operators, certified electrical contractors in Phoenix-Tucson corridor markets, and procurement officers at big-box home improvement retailers validated installation trends and channel economics. Bottom-up triangulation across product-type shipment data and top-down cross-check against building permit flows in California, Texas, and Florida anchored volume estimates.
Bottom-up modeling segmented the market across active, hybrid, passive, and roof-mounted fan configurations, with end-user splits between commercial buildings, residential retrofits, industrial facilities, and agricultural structures. The analytical lens weighted cooling-degree-day loads, solar irradiance levels, and state-level net metering policies across the projection horizon. CAGRs derived from regression of historical installation curves against regulatory deadline acceleration and utility rebate program cycles. DC motor efficiency improvements and photovoltaic panel cost curves fed technology adoption assumptions.
Polysilicon price volatility, state-level net metering reform, and hurricane wind-load code amendments are the dominant revision risks to installed base forecasts. Deviation in polysilicon wafer pricing would shift assembler margin outlooks and project quoting stability materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Air to Air Heat Pumps Sales Market
Cooling Systems
Solar-Assisted Heat Pump Market
Cooling Systems
Plate and Frame Heat Exchangers Market
Cooling Systems
North America Evaporative Cooling Market
Cooling Systems
Aftercoolers Market
Cooling Systems
Annular Cooler Market
Cooling Systems
Temporary Power and Cooling Solutions Market
Cooling Systems
Europe Air Source Heat Pump Market
Cooling Systems
Absorption Chillers Market
Cooling Systems
Battery Cooling Plate Market
Cooling Systems
Fluid Coolers Market
Cooling Systems
Air Source Heat Pump Market
Cooling Systems
Industrial Cooling System Market
Cooling Systems
Global Condensing Unit Market
Cooling Systems
Industrial Water Cooling System Market
Cooling Systems
Seawater Condensers Market