
 CNG Compressor Market | 2026-2036
CNG Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
CNG Compressor Market Analysis
Aftermarket service revenue is tilting toward predictive maintenance contracts and extended compressor overhauls as operators prioritize uptime guarantees. Ariel Corporation leverages its deep aftermarket parts network to sustain recurring revenue streams across North American fleet customers. Atlas Copco anchors European demand through its energy-efficient screw compressor platforms designed for high-cycle fuel station duty. Ingersoll Rand competes on integrated system packaging, combining compression, storage, and dispensing into turnkey station builds.
A CNG compressor is a positive-displacement or dynamic machine that raises natural gas pressure from pipeline levels, typically 0.5–5 bar, to 200–250 bar for vehicle fueling or industrial storage, employing multi-stage compression with intercooling to manage adiabatic heating and ensure gas quality compliance. Reciprocating compressors occupy the core of fuel station infrastructure globally, delivering the high-pressure ratios required for fast-fill vehicle dispensing. Screw compressors are displacing smaller reciprocating units in low-pressure booster applications where continuous duty and lower maintenance cycles reduce total cost of ownership. Electric drive technology leads new installations as grid infrastructure improves and carbon accounting intensifies scrutiny of diesel-driven alternatives.
India's Petroleum and Natural Gas Regulatory Board mandates standardized compressor specifications for city gas distribution networks, while the EPA in the United States enforces methane leakage thresholds that shape compressor seal and venting designs. China's National Development and Reform Commission coordinates provincial CNG infrastructure targets that directly determine compressor procurement volumes. Stakeholders must monitor how evolving carbon border mechanisms and zero-emission fleet mandates in major economies redirect investment between CNG compression and alternative fuel pathways.
Market Dynamics
Transit fleet electrification mandates are compressing investment timelines for CNG infrastructure, forcing compressor manufacturers to defend station economics against battery-electric alternatives while securing anchor contracts with municipal bus operators and long-haul trucking networks.
Growth Catalysts
- India's City Gas Distribution Mandate:The Petroleum and Natural Gas Regulatory Board requires standardized compressor specifications across new distribution networks, locking in procurement volumes for reciprocating and screw compressor platforms serving Delhi, Mumbai, and Ahmedabad metropolitan clusters.
- Pipeline Pressure Augmentation:Declining reservoir pressures at mature gas fields require multi-stage booster compression at city gate stations, extending compressor duty cycles and expanding the addressable installed base for overhaul services.
- Carbon Intensity Accounting:Fleet operators under EU Green Deal compliance deadlines are counting CNG against diesel baselines for scope 1 emissions reductions, preserving compressor demand in German and Italian logistics corridors.
Market Restraints
- Steel Alloy Price Volatility:Crankshaft forgings and pressure vessel steels account for substantial compressor bill-of-materials exposure, with Indian and Chinese foundry output fluctuations transmitting directly to manufacturer margins.
- Specialized Maintenance Labor Scarcity:High-pressure reciprocating compressor overhaul requires certified technicians familiar with API 618 alignment protocols, constraining station uptime guarantees in emerging African and Southeast Asian markets.
- Battery-Electric Range Extension:500+ kilometer electric truck platforms from European and Chinese OEMs are capturing fleet procurement budgets previously allocated to CNG vehicle conversion programs.
Strategic Opportunities
- Marine Bunkering Infrastructure:IMO 2020 sulfur regulations and EU FuelEU Maritime standards are opening CNG liquefaction and compression demand at Rotterdam, Singapore, and Houston port clusters for short-sea shipping.
- Biomethane Injection Upgrades:Existing CNG stations in Germany and Sweden are retrofitting compressor skids to handle upgraded biogas with elevated CO2 and moisture content, creating aftermarket hardware attachment revenue.
- Remote Monitoring Integration:Vibration sensing and predictive analytics platforms are collapsing maintenance intervals from scheduled to condition-based, enabling compressor OEMs to capture recurring software and sensor revenue streams.
Industry Challenges
- API 618 Recertification Timelines:Third-party inspection body capacity constraints are extending compressor commissioning cycles by 8-14 weeks at fuel stations requiring operational permits under national pressure equipment directives.
- Legacy SCADA Integration:Brownfield station automation retrofits must bridge proprietary compressor control protocols with modern distributed control systems, multiplying engineering hours and commissioning risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CNG Compressor Market |
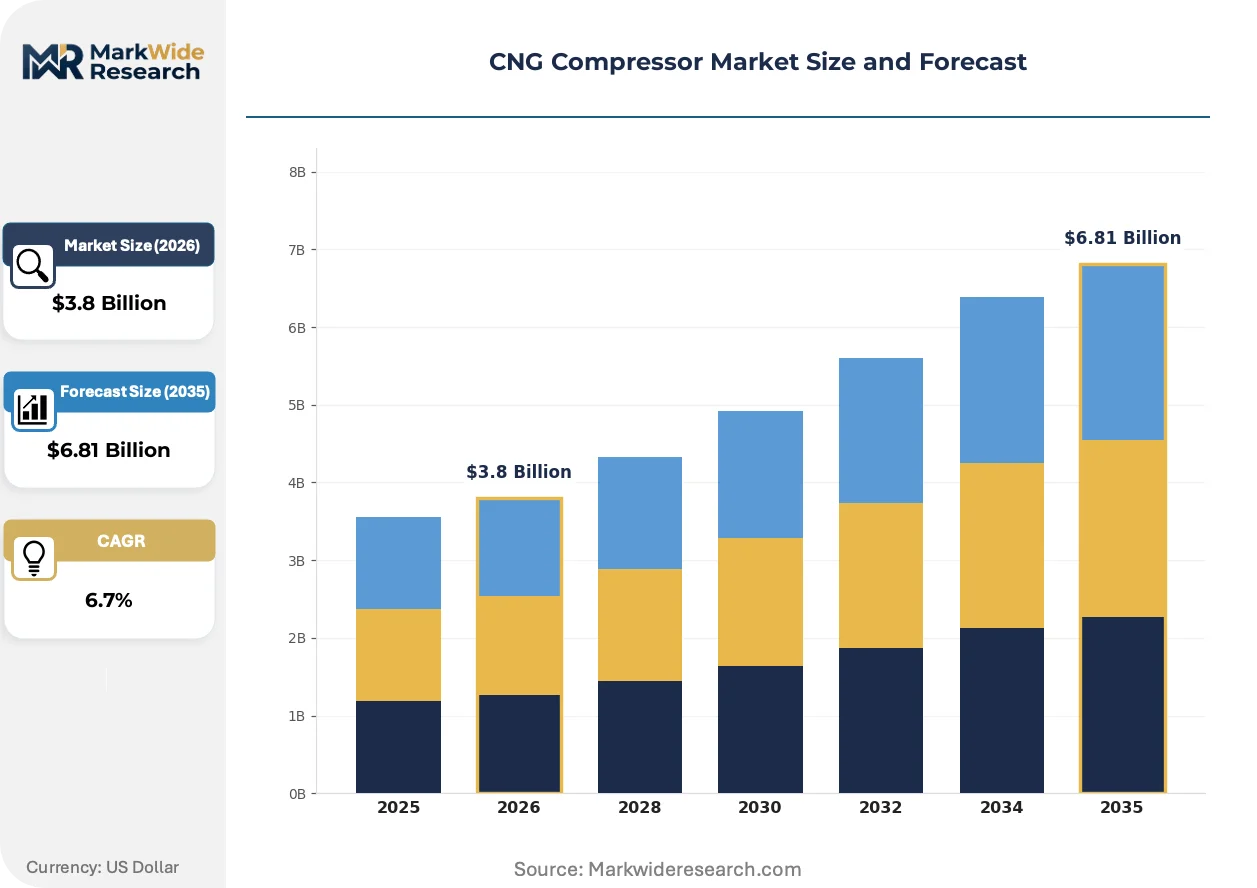
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diaphragm Compressors, Reciprocating Compressors, Screw Compressors, Centrifugal Compressors Technology: Electric Drive, Diesel Drive, Hybrid Drive, Gas Engine Drive End User: Fuel Stations, Industrial Users, Transport Fleets, Power Generation Installation: Stationary, Mobile, Containerized, Pipeline |
| Companies Covered | Ingersoll Rand, PC McKenzie Company, Atlas Copco, Wärtsilä Corporation, J-W Energy Company, Ariel Corporation, Carnot Compression, CIMC Enric, Bauer Compressors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CNG Compressor Market Emerging Trajectories
Digital twin deployment and modular skid architectures are compressing station build schedules while expanding remote diagnostic capabilities across dispersed fueling networks.
Screw compressor technology is collapsing the total cost of ownership gap with reciprocating units in low-pressure booster applications. Transit agencies in California and Texas are specifying oil-free screw packages for 24-hour bus depot operations. The technology is collapsing maintenance intervals from 4,000 to 8,000 operating hours and eliminating crankcase lubricant contamination risks in high-cycle duty.
EPA methane performance standards under the Clean Air Act are forcing seal and packing redesigns for fugitive emissions containment. Compressor manufacturers must now certify venting rates below specified thresholds to maintain eligibility for federal fleet procurement contracts. The regulatory pressure is concentrating R&D investment in dry gas seal alternatives and closed-loop crankcase ventilation systems for North American fuel station deployments.
Fleet operators are unbundling compressor procurement from turnkey station engineering, issuing separate tenders for compression skids, storage vessels, and dispensing equipment. Municipal transit authorities in Canada and Australia are driving this fragmentation to optimize component-level warranty terms and avoid single-source dependency. The behavioral shift is most visible in Australian state government tender documents that now explicitly prohibit packaged station bids exceeding defined compression equipment thresholds.
CNG Compressor Market Segmentation
Compressor procurement patterns diverge sharply across duty cycles, pressure requirements, and grid connectivity profiles. Fleet operators, industrial gas processors, and station developers each prioritize distinct performance envelopes that reshape manufacturer product roadmaps.
Product Type:
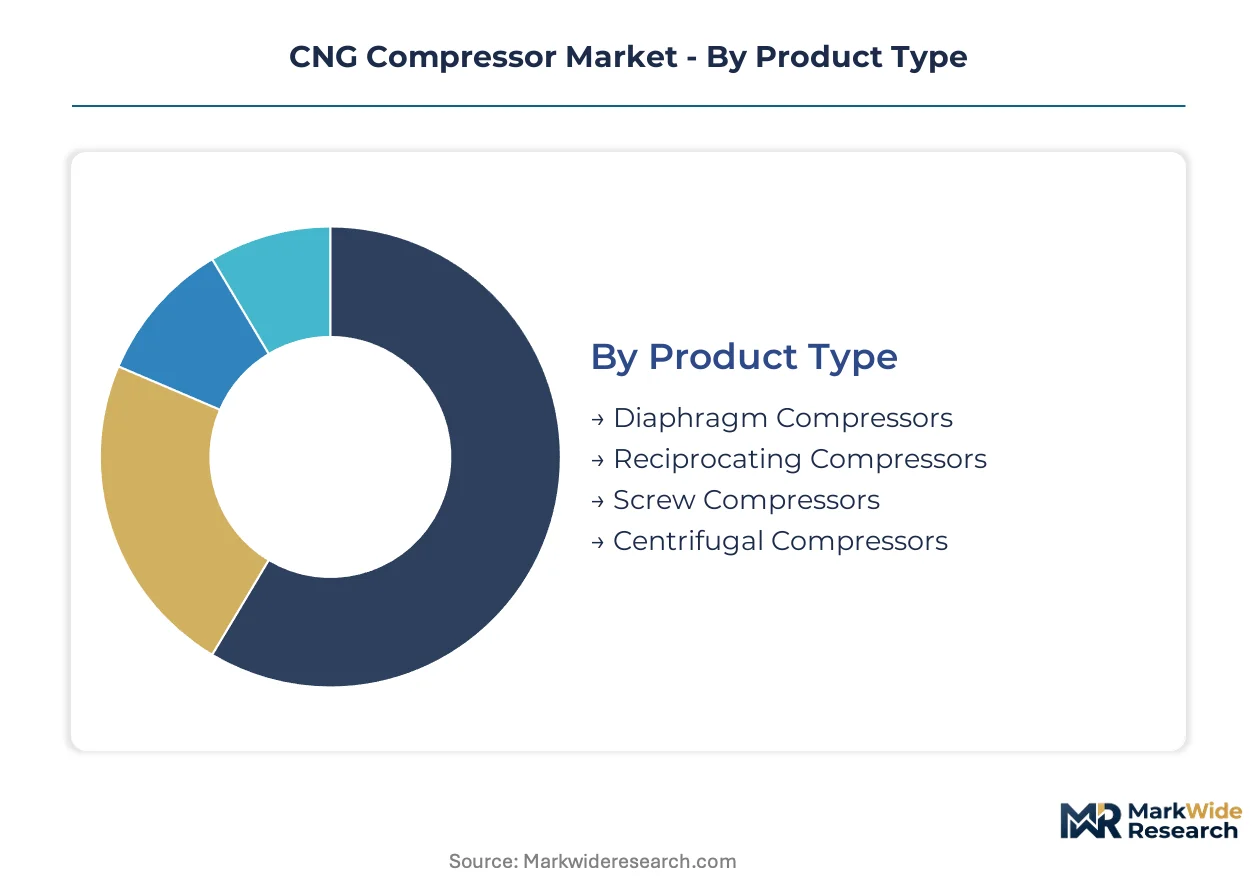
Pressure ratio requirements and maintenance accessibility separate the four compressor architectures competing for fuel station and industrial contracts.
- Reciprocating Compressors:Piston-driven positive-displacement systems achieve discharge pressures exceeding 250 bar through multi-stage compression with intercooling. India's city gas distribution networks in Delhi, Mumbai, and Ahmedabad specify these units for fast-fill vehicle dispensing under Petroleum and Natural Gas Regulatory Board mandates. High-pressure capability anchors demand despite elevated maintenance intervals.
- Screw Compressors:Rotating helical rotors deliver continuous compression without pulsation, collapsing maintenance cycles from 4,000 to 8,000 hours in low-pressure booster applications. California and Texas transit agencies specify oil-free variants for 24-hour bus depot operations where crankcase contamination risks must be eliminated.
- Diaphragm Compressors:Metal or elastomer diaphragms isolate process gas from hydraulic drive fluids, serving laboratory and small-scale industrial applications requiring absolute leak containment.
- Centrifugal Compressors:Dynamic compression through impeller acceleration suits high-volume, low-pressure-ratio pipeline booster duties where continuous operation outweighs capital intensity.
Reciprocating platforms hold installed capacity. Screw compressors are rotating up the share rankings in low-pressure duty cycles.
Technology:
Prime mover selection hinges on grid availability, carbon accounting protocols, and operational continuity requirements at dispersed fueling locations.
- Electric Drive:Grid-synchronous motors dominate new installations as transmission infrastructure improves and fleet operators face intensified carbon disclosure requirements. EU Green Deal compliance deadlines in German and Italian logistics corridors preserve electric compressor demand against diesel alternatives.
- Diesel Drive:Self-contained power units serve remote pipeline booster stations and mobile deployment scenarios beyond grid reach. African and Southeast Asian markets rely on these configurations where certified maintenance labor for high-pressure overhaul remains scarce.
- Hybrid Drive:Dual-mode systems switch between grid and onboard generation, addressing resilience requirements at strategic corridor fueling points.
- Gas Engine Drive:Field gas or pipeline natural gas fuels on-site generation, reducing electrical infrastructure capital at greenfield station developments.
Electric configurations are climbing the fastest. Diesel retains anchoring positions in frontier market deployments.
End User:
Customer type determines pressure specifications, fill rate requirements, and service contract structures that manufacturers must accommodate.
- Fuel Stations:Public and fleet-dedicated dispensing facilities require 200-250 bar discharge for vehicle fast-fill protocols. India's National Capital Region, Maharashtra state, and Gujarat's industrial corridor concentrate procurement as city gas distribution networks proliferate under national clean fuel mandates.
- Transport Fleets:Municipal bus operators and long-haul trucking networks specify integrated compression-dispensing systems with uptime guarantees. Procurement fragmentation is visible in Australian state tender documents that now prohibit packaged station bids exceeding defined compression thresholds.
- Industrial Users:Manufacturing and process industries deploy CNG for on-site power generation and thermal applications at moderate pressure ratios.
- Power Generation:Grid-balancing and distributed generation facilities utilize pipeline-pressure compression for gas turbine fuel delivery.
Fuel stations command the dominant revenue share. Transport fleet specifications are gaining influence over modular skid design priorities.
Installation:
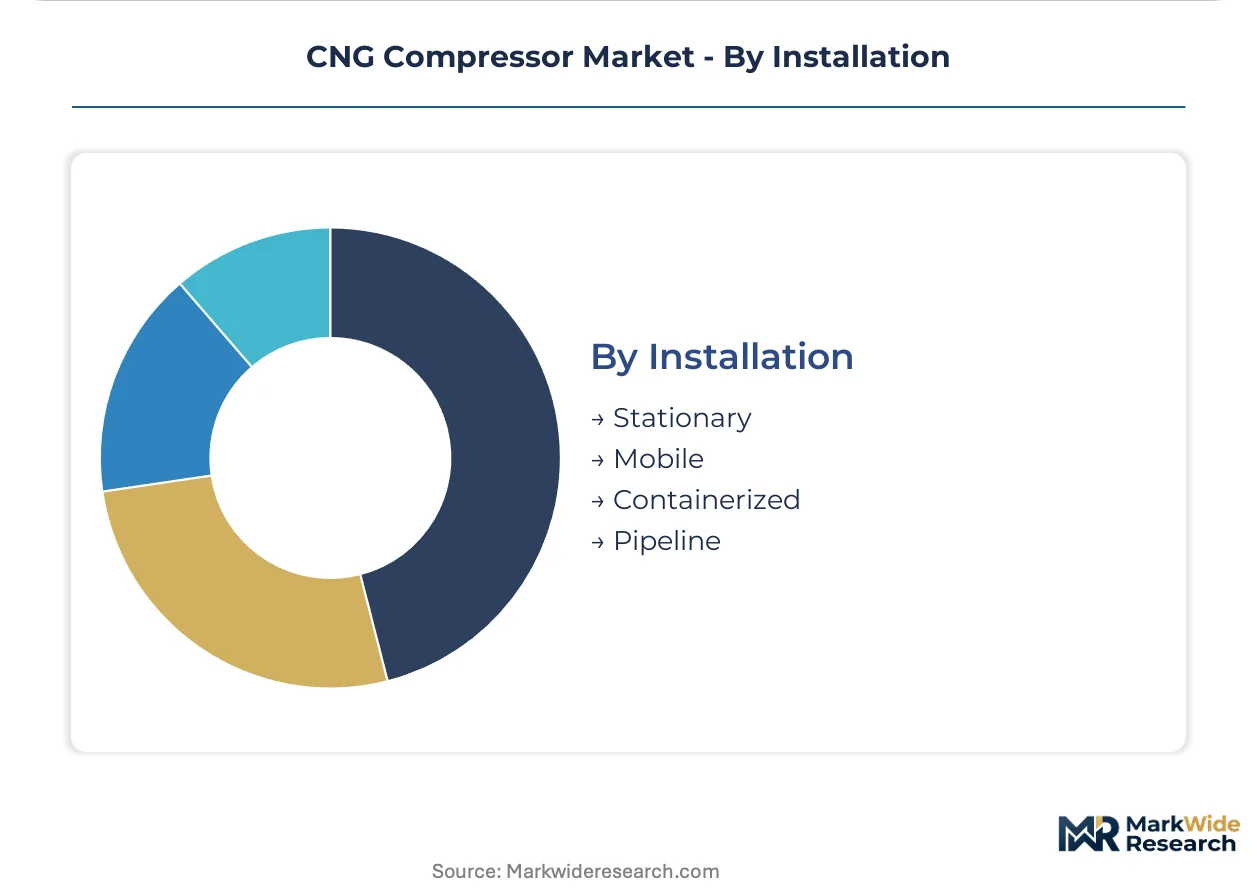
Deployment architecture shapes logistics, permitting timelines, and operational flexibility across stationary infrastructure and mobile applications.
- Stationary:Fixed foundations at fuel stations and industrial sites accommodate the largest compression capacities with permanent utility connections. API 618 recertification timelines extend commissioning cycles by 8-14 weeks at installations requiring operational permits under national pressure equipment directives.
- Containerized:Pre-integrated skids compress station build schedules and enable rapid relocation. Modular architectures expand remote diagnostic capabilities across dispersed fueling networks through standardized control interfaces.
- Mobile:Trailer-mounted units serve temporary construction sites, emergency fueling, and pipeline maintenance campaigns.
- Pipeline:Inline booster installations at city gate stations address declining reservoir pressures at mature gas fields, extending compressor duty cycles and overhaul service demand.
Stationary configurations retain the majority of installed base. Containerized delivery is expanding most quickly in markets prioritizing deployment velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compressor manufacturing clusters in Germany, the United States, India, and China anchor supply-side capacity. Demand concentrates in metropolitan corridors where city gas distribution mandates and transit fleet procurement intersect.
India
India's Petroleum and Natural Gas Regulatory Board mandates standardized compressor specifications across expanding city gas distribution networks. Transit fleet operators in Delhi, Mumbai, and Ahmedabad metropolitan clusters are procuring reciprocating units for fast-fill vehicle dispensing under national clean fuel mandates. The National Capital Region, Maharashtra state, and Gujarat's industrial corridor concentrate procurement volumes as distribution infrastructure proliferates.
United States
The EPA enforces methane leakage thresholds that shape compressor seal and packing designs for North American fuel station deployments. Fleet operators under federal procurement contracts require certified venting rates below specified thresholds to maintain eligibility. California and Texas transit agencies are specifying oil-free screw compressor packages for 24-hour bus depot operations where uptime guarantees dominate vendor selection.
Germany
German logistics corridors under EU Green Deal compliance deadlines are counting CNG against diesel baselines for scope 1 emissions reductions. Existing CNG stations in Germany are retrofitting compressor skids to handle upgraded biogas with elevated CO2 and moisture content. The aftermarket hardware attachment revenue is concentrating in industrial clusters serving short-sea shipping bunkering demand at Rotterdam-adjacent port infrastructure.
China
China's National Development and Reform Commission coordinates provincial CNG infrastructure targets that directly determine compressor procurement volumes. Transit fleet operators are expanding CNG vehicle procurement under national clean fuel mandates in major metropolitan areas. The country's foundry output fluctuations for crankshaft forgings and pressure vessel steels transmit directly to manufacturer margins across the supply chain.
Canada
Municipal transit authorities in Canadian provinces are driving procurement fragmentation to optimize component-level warranty terms. Provincial tender documents now explicitly prohibit packaged station bids exceeding defined compression equipment thresholds. The behavioral shift is visible in state government procurement patterns that unbundle compressor procurement from turnkey station engineering.
CNG Compressor Market Vendor Landscape
Integrated system packagers and specialized compressor fabricators split the market across distinct value-capture models. Tier-1 positions concentrate among manufacturers with deep aftermarket parts networks and energy-efficient platform portfolios. Two strategic archetypes dominate: turnkey station builders combining compression, storage, and dispensing; and component specialists focusing on high-pressure reciprocating or screw compressor skids. Competitive moves center on predictive maintenance contract expansion and modular skid architecture standardization.
Among North American specialists, Ariel Corporation and Ingersoll Rand occupy positions anchoring different competitive vectors. Atlas Copco represents European energy-efficient platform specialization. These named entities exemplify how geographic origin and corporate structure correlate with strategic archetype positioning in fuel station and industrial compression markets.
| Leading Market Players |
|---|
| Ingersoll Rand |
| PC McKenzie Company |
| Atlas Copco |
| Wärtsilä Corporation |
| J-W Energy Company |
| Ariel Corporation |
| Carnot Compression |
| CIMC Enric |
| Bauer Compressors |
| Others |
Supply Flow & Price Mechanics
Steel alloy price volatility determines both pricing tier spreads and supply chain shape across CNG compressor manufacturing. Crankshaft forgings and pressure vessel steels account for substantial bill-of-materials exposure, with Indian and Chinese foundry output fluctuations transmitting directly to manufacturer margins and procurement timelines.
Pricing Analysis
India's Petroleum and Natural Gas Regulatory Board mandates dictate the pricing tier structure across city gas distribution networks. Three-tier pricing structure across premium, standard, and economy levels separates API 618-certified units from general industrial-grade equipment and entry-level booster packages. Cost compression in standard-tier reciprocating compressors is intensifying because municipal transit authorities unbundle procurement to optimize component-level warranty terms. Fleet operators in emerging African and Southeast Asian markets exhibit highest price sensitivity due to scarce certified maintenance labor, while German logistics corridors under EU Green Deal compliance show lowest sensitivity as carbon accounting prioritizes uptime guarantees over capital expenditure.
Supply Chain Analysis
Contract manufacturing concentration rests with Indian and Chinese foundries for crankshaft forgings, German and Italian specialists for high-pressure valves and sealing systems, and North American fabricators for API-certified pressure vessels. Raw material dependencies draw from specialty steel alloys, aluminum castings, and precision-machined compressor valves. Single-source vulnerability concentrates in API 618 recertification capacity, where third-party inspection body constraints extend commissioning cycles. Distribution runs through OEM direct sales for large fleet contracts, regional distributors for aftermarket parts, and integrated system packagers for turnkey station builds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CNG compressor markets approach a platform-economics inflection as predictive maintenance contracts and modular skid architectures reconfigure vendor-customer relationships around uptime guarantees rather than equipment ownership.
For Market Incumbents: Pre-empt battery-electric range extension threats by anchoring municipal bus operator contracts with integrated compression-dispensing systems and 24-hour uptime guarantees. Deepen aftermarket parts networks in India's National Capital Region and Gujarat's industrial corridor to capture recurring revenue from standardized compressor specifications. Invest in oil-free screw compressor R&D to defend against electrification mandates in California and Texas transit agencies.
For New Entrants and Emerging Players: Build out marine bunkering infrastructure specialization at Rotterdam, Singapore, and Houston port clusters where IMO 2020 sulfur regulations and EU FuelEU Maritime standards create unmet CNG liquefaction demand. Target biomethane injection upgrade retrofits in Germany and Sweden as the most penetrable aftermarket segment. Pursue remote monitoring integration partnerships with vibration sensing and predictive analytics platforms to establish recurring software revenue streams.
For Investors and Strategic Acquirers: EPA methane performance standards under the Clean Air Act reshape the acquisition landscape by concentrating R&D investment in dry gas seal alternatives and closed-loop crankcase ventilation systems. Long-term viability favors manufacturers with deep vertical integration into specialty steel forging and certified recertification capacity. Watch for inflection in carbon border mechanism announcements redirecting investment between CNG compression and alternative fuel pathways.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Contract Expansion | Ariel Corporation and Ingersoll Rand capture recurring revenue through uptime guarantees across North American fleet customers. |
| Modular Skid Architecture Standardization | Containerized delivery compresses station build schedules and enables rapid relocation across India's city gas distribution networks. |
| Biomethane Injection Retrofit Programs | German CNG stations handling upgraded biogas with elevated CO2 content create aftermarket hardware attachment revenue. |
| Marine Bunkering Infrastructure Buildout | Rotterdam-adjacent port clusters under EU FuelEU Maritime standards open CNG compression demand for short-sea shipping. |
| Electric Drive Platform Transition | Grid-synchronous motors dominate new installations as EU Green Deal compliance deadlines preserve demand against diesel alternatives. |
Methodological Framework
Operator-level perspectives from fleet maintenance directors, city gas distribution procurement managers, compressor OEM sales engineers, and aftermarket service technicians anchored the qualitative base. Primary interviews combined with secondary validation from Petroleum and Natural Gas Regulatory Board filings, EPA methane performance standard documents, EU Green Deal implementation guidelines, and city gas distribution tender databases. Bottom-up and top-down triangulation cross-referenced equipment installation counts against fuel station permitting records.
Scenario-bracketing framed analytical approaches across the projection horizon, modeling demand trajectories under transit fleet electrification mandates, carbon border mechanism implementations, and marine bunkering regulatory enforcement. Segmentation dimensions included compressor architecture, prime mover technology, end-user category, and installation type. CAGRs were derived from equipment procurement pipelines, infrastructure investment schedules, and fleet conversion program announcements.
Stress conditions across steel alloy price volatility, API 618 recertification timeline extensions, and battery-electric truck platform deployment rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about national clean fuel mandate continuity and methane leakage threshold enforcement. Quarterly review of municipal transit authority tender unbundling patterns and marine bunkering infrastructure investment announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Positive Displacement Gas Compressor Market
Compressors
Liquid Ring Compressors Market
Compressors
Gas Compressors Market
Compressors
Russia Reciprocating Compressor Market
Compressors
Oil-Free Air Compressor Market
Compressors
Reciprocating Hydrogen Compressor Market
Compressors
Stationary Air Compressor Market
Compressors
Turbocompressor Market
Compressors
Integrally Geared Centrifugal Compressor Market
Compressors
Asia-Pacific Compressor Oil Market
Compressors
Chlorine Compressors Market
Compressors
Booster Compressor Market
Compressors
Oil-Injected Screw Compressor Market
Compressors
Portable Air Compressor Market
Compressors
Bus Compressor Market
Compressors
Reciprocating Compressor Market