
 Switzerland Solar Energy Market | 2026-2036
Switzerland Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Switzerland Solar Energy Market Analytics
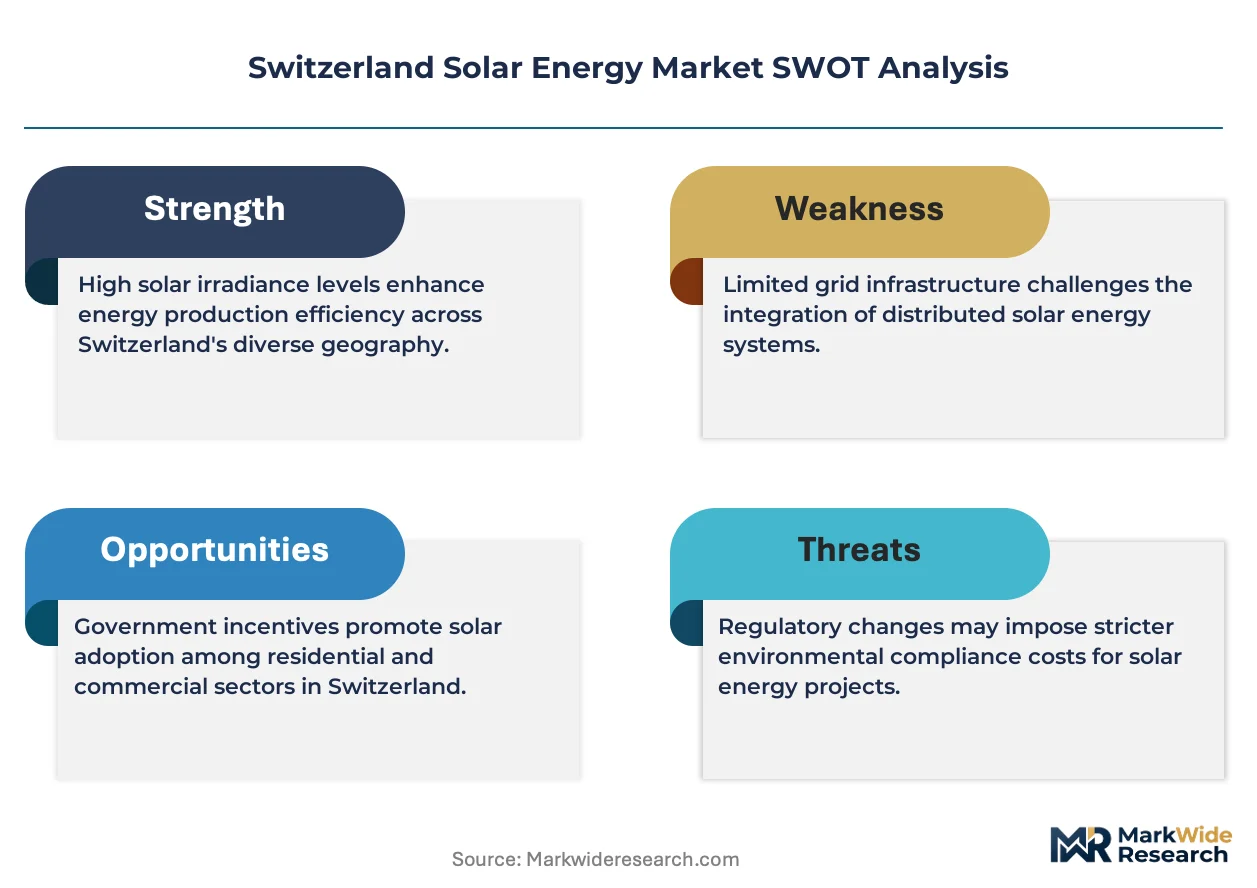
Swiss Federal Office of Energy feed-in tariff recalibration is realigning the cost-of-entry calculus for new market participants. Meyer Burger Technology AG leverages its heterojunction cell manufacturing base in Thun to anchor domestic supply security. ABB competes through industrial automation integration across utility-scale inverter deployments. Solvatec differentiates via specialized alpine installation engineering for high-altitude photovoltaic systems.
Switzerland solar energy encompasses photovoltaic and concentrated solar power systems engineered to convert electromagnetic radiation into electrical current, with crystalline silicon modules typically achieving 20-22% conversion efficiency under standardized test conditions. The technology serves Switzerland's grid decarbonization mandate while addressing mountainous terrain constraints through building-integrated and distributed architectures. Photovoltaic technology dominates installed capacity, while rooftop installation types command premium margins due to Swiss cantonal zoning density and heritage building restrictions. Utility-scale application growth is accelerating fastest as Axpo and Repower AG develop alpine solar parks above snow lines.
Swiss Federal Office of Energy tariff structures, SIA Swiss engineering standards for structural load verification, and cantonal building codes collectively shape equipment certification requirements and interconnection timelines. Swissmedic and SECO coordinate import compliance for inverter electronics under CE marking harmonization with EU Green Deal alignment protocols. Stakeholders must monitor forthcoming revisions to the Federal Act on a Secure Electricity Supply and corresponding storage co-location mandates.
Market Dynamics
Federal Act on a Secure Electricity Supply revision is compressing interconnection timelines while mandating storage co-location, forcing developers to redesign project economics around hybrid system architectures.
Growth Catalysts
- Building-Integrated Photovoltaics Subsidy Tiers:Swiss Federal Office of Energy recalibration reduces upfront capital burden for heritage structure retrofits, unlocking rooftop capacity in dense Zurich and Geneva corridors.
- Alpine Solar Park Deployment:Utility-scale projects above snow lines exploit high-altitude irradiance and reduced temperature coefficients, expanding addressable terrain beyond valley floors.
- Heterojunction Cell Manufacturing:Domestic production of high-efficiency crystalline silicon modules shortens supply lead times and insulates developers from EU import volatility.
Market Restraints
- Structural Load Verification Costs:SIA Swiss engineering standards impose expensive geotechnical and snow-load assessments on alpine installations, inflating soft costs relative to flatter European markets.
- Cantonal Zoning Fragmentation:Twenty-six distinct building codes create permitting heterogeneity, extending development timelines in heritage-protected Ticino and Valais municipalities.
- Grid Interconnection Queues:Swissgrid capacity allocation constraints in central corridor substations delay commercial operation dates for utility-scale projects.
Strategic Opportunities
- Storage Co-Location Mandates:Federal Act revisions create captive demand for lithium-ion and flow battery integration, opening EPC bundling opportunities for hybrid system specialists.
- Agricultural Photovoltaic Convergence:Agrivoltaic pilot programs in Bernese Oberland dairy regions unlock dual-use land economics previously excluded from solar development.
- Municipal Energy Cooperative Models:Canton-level enabling legislation for citizen-owned generation assets is displacing traditional utility PPAs in rural Graubünden communities.
Industry Challenges
- High-Altitude Installation Engineering Talent:Specialized alpine rigging and avalanche-zone mounting expertise remains concentrated among a handful of regional contractors, constraining deployment velocity.
- CE Marking Harmonization Complexity:Swissmedic and SECO coordination delays for inverter electronics create inventory bottlenecks at port of entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Switzerland Solar Energy Market |
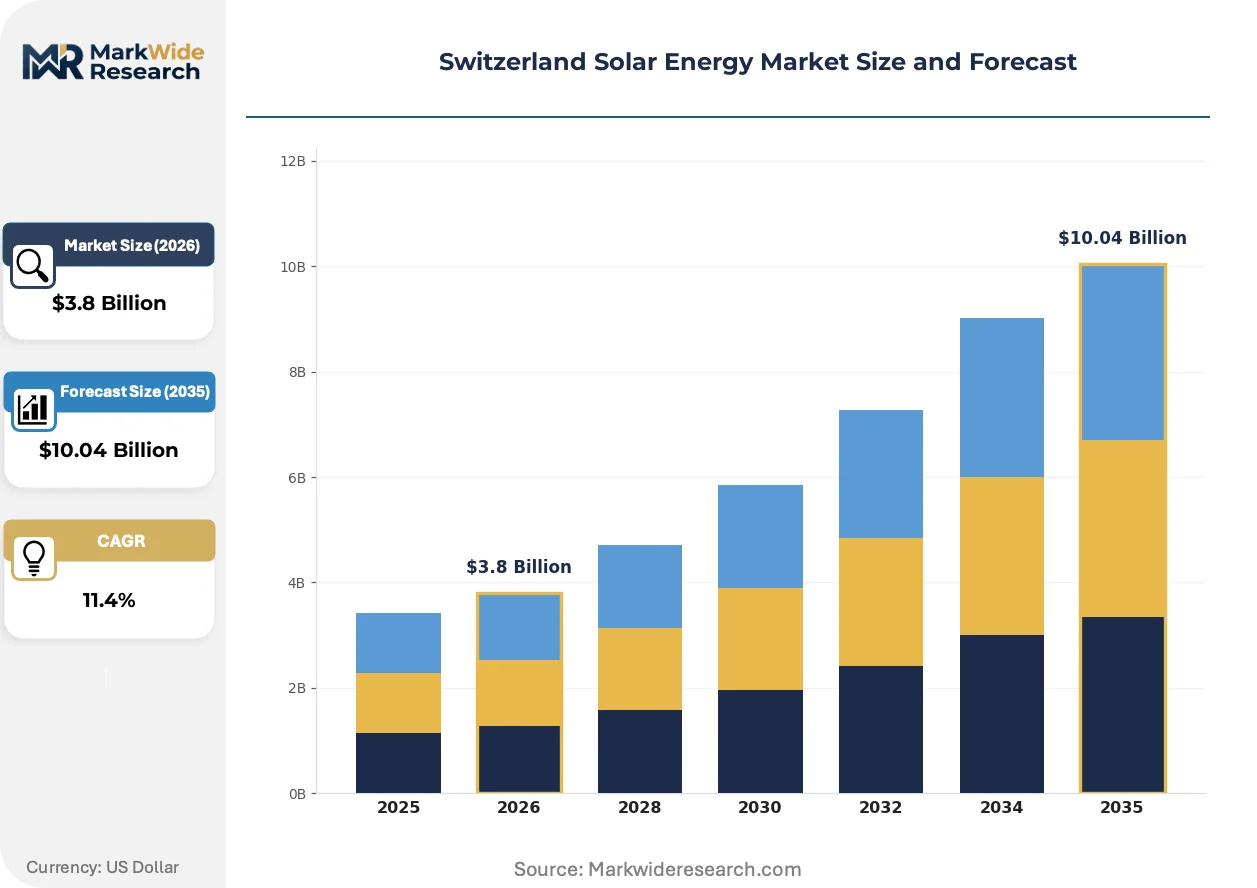
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
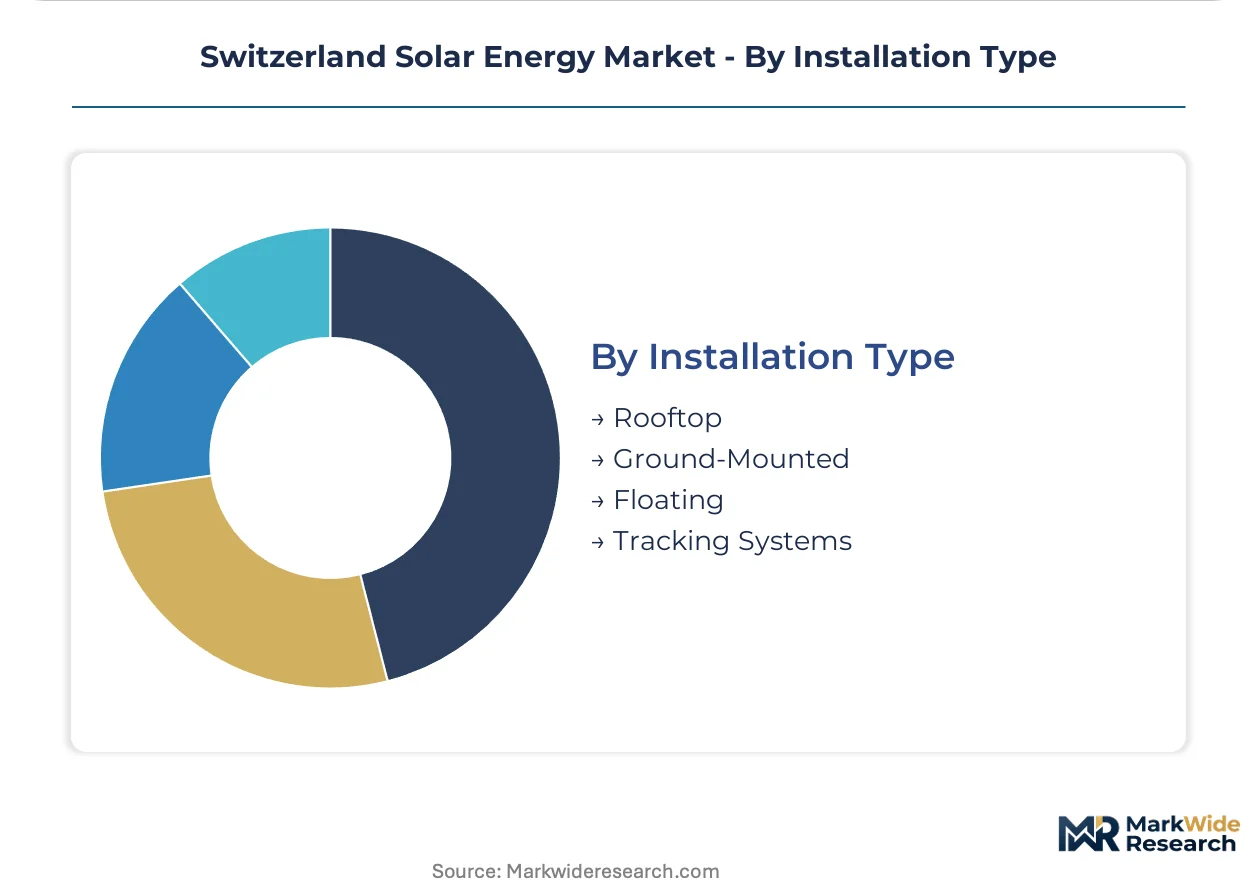
| Segmentation | Technology: Photovoltaic, Concentrated Solar Power, Bifacial Panels, Thin-Film Application: Residential, Commercial, Industrial, Utility-Scale End User: Households, Corporations, Government Facilities, Energy Cooperatives Installation Type: Rooftop, Ground-Mounted, Floating, Tracking Systems |
| Companies Covered | Meyer Burger Technology AG, ABB, SolarMax, Leclanché, Solvatec, Axpo, Repower AG, EKZ, Madrisa Solar AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switzerland Solar Energy Market Evolving Landscape
Technology convergence and regulatory compression are simultaneously expanding addressable applications and compressing development timelines across the Swiss solar value chain.
Heterojunction cell architecture is rewriting efficiency benchmarks for building-integrated systems. Meyer Burger Technology AG's Thun production base supplies modules achieving 22-24% conversion efficiency to Zurich metropolitan retrofit projects. This performance tier is compressing payback periods for heritage building installations previously deemed economically marginal.
Swiss Federal Office of Energy feed-in tariff recalibration is redirecting developer attention toward self-consumption optimization. The policy shift penalizes pure export configurations while rewarding behind-the-meter storage integration. Utility-scale developers are responding with hybrid PPA structures that allocate capacity between grid injection and offtaker direct use.
Energy cooperative procurement models are displacing traditional utility-led development in rural cantons. Bernese Oberland and Graubünden municipalities are aggregating residential demand into collective self-consumption schemes. This channel rotation is fragmenting customer acquisition economics and privileging local EPCs with established cooperative relationships over national installers.
Switzerland Solar Energy Market Segmentation
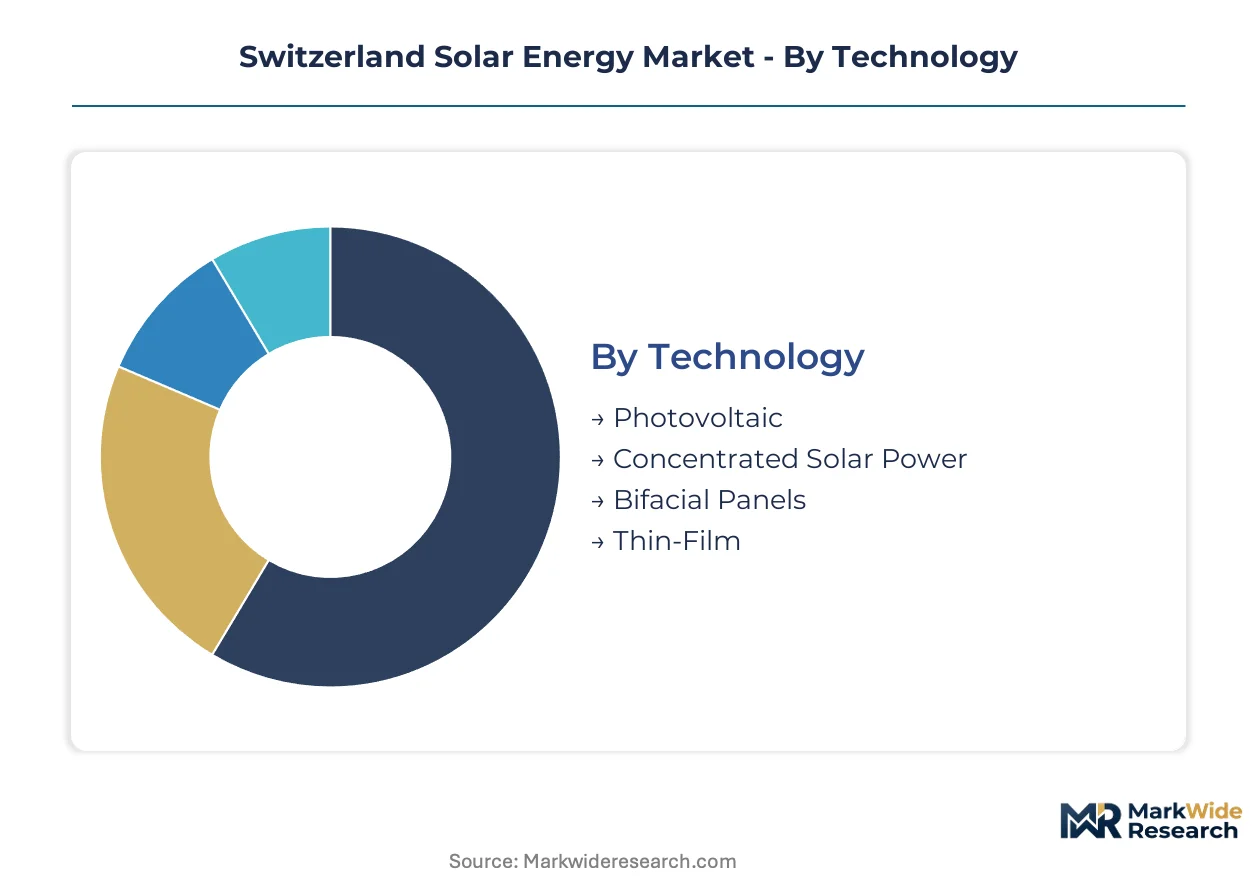
Switzerland's mountainous terrain and cantonal regulatory fragmentation create divergent certification burdens across technology and installation categories. Segmentation reveals where Swiss Federal Office of Energy tariffs and SIA structural standards impose steepest compliance costs.
Technology:
Photovoltaic systems face Swissmedic CE marking harmonization with EU Green Deal protocols, while concentrated solar power encounters additional Federal Office of Energy thermal conversion assessments.
- Photovoltaic:Crystalline silicon modules achieving 20-22% conversion efficiency dominate Swiss installations. Demand clusters around Zurich metropolitan retrofits where Meyer Burger Technology AG's Thun-produced heterojunction cells compress payback periods for building-integrated systems.
- Bifacial Panels:Dual-sided light capture architecture exploits high-albedo snow reflection in alpine deployments above 1,500 meters elevation. Axpo and Repower AG specify these modules for utility-scale parks in Graubünden and Valais cantons where snow-ground reflectance boosts yield 8-12%.
- Concentrated Solar Power:Parabolic trough and tower configurations remain marginal in Swiss deployment due to limited direct normal irradiance availability relative to Southern European markets.
- Thin-Film:Cadmium telluride and copper indium gallium selenide architectures suit lightweight heritage building retrofits where structural load constraints prohibit crystalline silicon mass.
Photovoltaic sits at the top of the volume ranking, with bifacial panels climbing the fastest.
Application:
Cost tier differentiation separates premium building-integrated systems from standardized utility-scale deployments, with interconnection queue depth driving margin compression at the bulk power end.
- Utility-Scale:Alpine solar parks above snow lines exploit reduced temperature coefficients and high-altitude irradiance. Swissgrid capacity allocation constraints in central corridor substations delay commercial operation dates, forcing developers to absorb carrying costs.
- Residential:Behind-the-meter installations leverage Federal Act on a Secure Electricity Supply storage co-location mandates. Canton-level energy cooperative enabling legislation in Bernese Oberland displaces traditional utility PPAs.
- Commercial:Corporate offtakers in Geneva and Basel pharmaceutical clusters pursue self-consumption optimization under revised feed-in tariff structures that penalize pure export configurations.
- Industrial:Manufacturing facilities in Aargau and Zürich industrial zones integrate rooftop arrays with process heat recovery systems.
Utility-scale commands the highest absolute revenue per project, though residential expands most quickly.
End User:
Customer type determines financing structure complexity, with energy cooperatives introducing governance overhead absent from corporate procurement.
- Energy Cooperatives:Citizen-owned generation assets aggregate residential demand into collective self-consumption schemes. Rural Graubünden and Bernese Oberland municipalities favor local EPCs with established cooperative relationships over national installers.
- Corporations:Multinational headquarters in Zurich and Geneva metropolitan corridors execute virtual PPAs for renewable energy certificate arbitrage across European operations.
- Households:Individual prosumers navigate twenty-six distinct cantonal building codes, with heritage-protected Ticino municipalities imposing longest permitting timelines.
- Government Facilities:Federal buildings and cantonal administrative centers face mandatory solar-ready roof requirements under Federal Act revision implementation schedules.
Corporations anchor current procurement volume, while energy cooperatives gain share fastest.
Installation Type:
Geography and terrain dictate engineering specialization, with alpine rigging expertise concentrated among regional contractors constraining deployment velocity for complex mounting configurations.
- Rooftop:Building-integrated and retrofit configurations face SIA Swiss engineering standards for structural load verification and snow-load assessments. Premium margins persist due to cantonal zoning density and heritage building restrictions in dense urban cores.
- Ground-Mounted:Fixed-tilt arrays on valley floors compete with agricultural land use, though agrivoltaic pilot programs in Bernese Oberland dairy regions unlock dual-use economics.
- Tracking Systems:Single-axis and dual-axis trackers optimize yield on south-facing slopes in Valais and Grisons, where avalanche-zone mounting expertise commands contractor premiums.
- Floating:Reservoir-based installations remain experimental in Swiss deployment, with Lake Geneva and Lake Constance pilot projects testing mooring engineering for seasonal water level variation.
Rooftop maintains volume leadership, with tracking systems showing steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized alpine installation engineers and high-altitude rigging technicians concentrate in Graubünden and Valais cantons, anchoring deployment capacity for complex mountain photovoltaic systems.
Zurich Metropolitan Corridor
Corporate headquarters and pharmaceutical clusters drive behind-the-meter demand for building-integrated systems. Swiss Federal Office of Energy feed-in tariff recalibration rewards self-consumption optimization over pure export. Meyer Burger Technology AG supplies heterojunction cells from its Thun production base to retrofit projects across Zurich city center and surrounding cantonal municipalities.
Geneva Metropolitan Corridor
International organizations and banking headquarters execute virtual power purchase agreements for renewable energy certificate arbitrage. Canton-level energy cooperative enabling legislation aggregates residential demand into collective self-consumption schemes. Commercial offtakers in pharmaceutical and precision manufacturing sectors integrate rooftop arrays with process heat recovery systems.
Valais Canton
Alpine solar parks above snow lines exploit reduced temperature coefficients and high-altitude irradiance. SIA Swiss engineering standards impose structural load verification and snow-load assessments on all installations. Axpo and Repower AG develop utility-scale tracking systems on south-facing slopes where avalanche-zone mounting expertise commands contractor premiums.
Graubünden
Rural municipalities favor citizen-owned generation assets through energy cooperative procurement models. Federal Act on a Secure Electricity Supply storage co-location mandates create captive demand for lithium-ion integration. Local EPCs with established cooperative relationships displace national installers in residential and small-commercial segments.
Bernese Oberland
Agrivoltaic pilot programs in dairy regions unlock dual-use land economics previously excluded from solar development. Cantonal building codes in heritage-protected municipalities extend permitting timelines relative to urban cores. Municipal energy cooperatives aggregate agricultural and residential demand into hybrid procurement structures.
Switzerland Solar Energy Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across equipment manufacturing, project development, and installation services. The vendor base clusters around three strategic archetypes: domestic cell manufacturers leveraging proximity to alpine demand, industrial automation integrators serving utility-scale deployments, and regional installation specialists commanding high-altitude engineering premiums. Competitive positioning hardens through backward integration into module production and strategic partnerships for storage co-location bundling.
Among Swiss-headquartered equipment suppliers, Meyer Burger Technology AG and ABB occupy distinct positions within the value chain. Meyer Burger Technology AG exemplifies the domestic manufacturing archetype through its Thun production base. ABB represents the industrial automation integrator model serving utility-scale inverter deployments. Solvatec anchors the specialized installation tier with alpine engineering capabilities. These three entities collectively illustrate how geographic concentration, technology focus, and service specialization segment competitive positioning across the Swiss solar market.
| Leading Market Players |
|---|
| Meyer Burger Technology AG |
| ABB |
| SolarMax |
| Leclanché |
| Solvatec |
| Axpo |
| Repower AG |
| EKZ |
| Madrisa Solar AG |
| Others |
Value Network & Pricing Analysis
Family-owned alpine installation specialists anchor supply-side discipline across Graubünden and Valais cantons, translating scarce high-altitude engineering talent into premium pricing power for complex tracking systems while compressing margins for standardized rooftop configurations.
Pricing Analysis
Bundled EPC-plus-storage offerings command premium positioning against unbundled module-only transactions. Project-based contracting dominates, with price differentiation driven by SIA certification tier and avalanche-zone mounting complexity. Cost compression in utility-scale segments intensifies as Swissgrid interconnection queues extend carrying-cost burdens. Commercial offtakers in Zurich and Geneva pharmaceutical clusters exhibit lowest price sensitivity, while rural energy cooperatives in Bernese Oberland negotiate aggressively on standardized residential packages.
Supply Chain Analysis
Dual-sourcing mandates from Axpo and Repower AG require module qualification across Meyer Burger Technology AG's Thun facility and select EU producers. Crystalline silicon wafers draw from Germany, Norway, and Malaysia; silver paste and aluminum frames hinge on Chinese and South Korean suppliers. Single-source vulnerability concentrates in heterojunction cell metallization equipment. Distribution runs through cantonal EPC networks with direct utility relationships for utility-scale origination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Switzerland's solar market functions as a geographic-arbitrage play between EU import volatility and domestic heterojunction production security, exploiting the Federal Act's storage co-location mandates that impose cost structures absent in neighboring German or Austrian frameworks.
For Market Incumbents: Deploy backward integration into lithium-ion battery assembly to capture hybrid PPA bundling premiums. Meyer Burger Technology AG's Thun production base offers captive supply security against EU import disruption. Incumbents must lock avalanche-zone installation crews through exclusive contractor retainers before seasonal deployment windows compress.
For New Entrants and Emerging Players: Agrivoltaic engineering expertise offers technology-first entry into Bernese Oberland dairy regions where dual-use land economics remain underdeveloped. Target agricultural cooperatives with hybrid procurement structures combining rooftop residential arrays with ground-mounted pasture installations. Partner with established municipal energy cooperatives to bypass national installer channel costs.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional EPCs with specialized alpine rigging capabilities but limited balance-sheet scale. Long-term viability rests on Federal Act implementation pace and storage technology cost curves. Watch Swissgrid interconnection queue clearance rates as the inflection signal for utility-scale deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Assembly | Captures hybrid PPA bundling premiums under Federal Act storage mandates. |
| Alpine Installation Crew Retention Programs | Secures scarce avalanche-zone rigging talent before seasonal deployment peaks. |
| Agrivoltaic Pilot Expansion | Unlocks dual-use land economics in Bernese Oberland dairy regions. |
| Energy Cooperative Partnership Structuring | Displaces traditional utility PPAs in rural Graubünden procurement channels. |
| Heterojunction Cell Capacity Expansion | Insulates developers from EU import volatility through Thun-based supply security. |
Research Methodology
Multiple input streams — structured interviews with utility planning officers and IPP project developers, EPC contractor operational assessments, and grid operator capacity data — were reconciled against secondary validation from Swiss Federal Office of Energy tariff filings, SIA engineering standard documentation, and cantonal building code registries. Bottom-up project pipeline aggregation and top-down federal subsidy allocation analysis provided triangulation across modeling approaches.
Data-stream reconciliation supported segmentation across technology type, installation configuration, end-user archetype, and cantonal regulatory cluster. CAGRs were derived from installed capacity build rates and tariff-adjusted project economics throughout the forecast period. Key inputs included Swissgrid interconnection queue depth, Meyer Burger Technology AG production throughput, and Federal Act implementation schedules.
The model holds under stable Federal Act revision timelines and sustained feed-in tariff structures; deviation in cantonal permitting velocity or EU CE marking harmonization delays would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
PERC Solar Panels Market
Solar Power Systems
United Kingdom Photovoltaic Mounting System Market
Solar Power Systems
United Arab Emirates Solar Energy Market
Solar Power Systems
Indonesia Renewable Energy Market
Solar Power Systems
Off-Grid Solar Energy Market
Solar Power Systems
Asia-Pacific Solar Blanket Market
Solar Power Systems
Thin-Film Photovoltaic Market
Solar Power Systems
US Solar PV Market
Solar Power Systems
Solar Shed Light Market
Solar Power Systems
Solar Photovoltaic Ribbon Market
Solar Power Systems
US Solar Market
Solar Power Systems
Grid Connected PV Systems Market
Solar Power Systems
Egypt Solar Energy Market
Solar Power Systems
Printable Solar Cells Market
Solar Power Systems
Australia Rooftop Solar Market
Solar Power Systems
Solar Panel Glass Market